
 Global EVA Adhesives Market | 2026-2036
Global EVA Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global EVA Adhesives Market Foresight
Specialty chemical distribution is rewriting how EVA adhesives reach polymer processors and building products producers across Asia-Pacific and Europe. Henkel AG & Co. KGaA leverages its direct sales infrastructure to anchor long-term supply contracts with footwear manufacturers in Germany and China. H.B. Fuller Company competes through regional blending facilities that sustain just-in-time delivery for automotive component suppliers in North America. Arkema Group differentiates via captive ethylene-vinyl acetate resin production that controls raw material quality for electronics assembly applications.
Ethylene-vinyl acetate adhesives are thermoplastic bonding systems formulated with 18-40% vinyl acetate content, polymerized through high-pressure bulk processes to deliver flexibility, optical clarity, and moisture resistance for industrial lamination and assembly. Hot melt formulations dominate volume consumption in packaging and woodworking due to instant tack development and solvent-free processing, while reactive systems capture premium positioning in automotive and electronics sectors where thermal cycling durability determines specification. Water-based EVA adhesives are gaining share in footwear and construction materials as factory emission controls tighten, though pressure-sensitive variants remain concentrated in label and tape applications with mature margin profiles.
EPA regulations in the United States limit hazardous air pollutant emissions from adhesive coating operations, compelling reformulation toward lower-VOC EVA systems in solvent-based segments. ECHA's REACH restrictions on substance of very high concern classifications affect crosslinking additives used in reactive EVA adhesives across European manufacturing. China's MEE enforcement of dual carbon goals accelerates water-based and hot-melt substitution in export-oriented polymer processing clusters. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation specialization or unified global product platforms offer superior compliance economics.
Market Dynamics
Solar panel encapsulation demand is compressing formulation cycles as photovoltaic manufacturers in China and Germany mandate faster-curing EVA hot-melt systems to match module throughput targets. This pressure cascades through raw material procurement, forcing resin suppliers to synchronize bulk polymerization capacity with seasonal installation peaks.
Growth Catalysts
- REACH substance restrictions:ECHA's evolving SVHC classifications are accelerating water-based EVA substitution in European woodworking and packaging lines, opening specification windows for compliant formulators.
- Photovoltaic assembly expansion:Domestic module manufacturing targets in India and Germany are pulling EVA encapsulant demand toward localized blending facilities capable of just-in-time delivery.
- Hot-melt processing economics:Solvent-free application systems are capturing share in footwear and automotive trim as factory emission audits intensify across export-oriented manufacturing clusters.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracker output fluctuations in the US Gulf Coast and Northeast Asia transmit directly to EVA resin contract pricing, compressing blender margins during olefin upcycles.
- Vinyl acetate monomer concentration:Three integrated petrochemical complexes supply the majority of VAM feedstock for adhesive-grade EVA, creating geographic supply risk concentrated on the Texas coast and Singapore.
- Moisture barrier limitations:Unmodified EVA formulations exhibit hydrolytic instability above 85°C, excluding the material from under-hood automotive applications where polyamide adhesives dominate thermal cycling performance.
Strategic Opportunities
- India photovoltaic manufacturing:Production-linked incentive schemes for solar module assembly are attracting EVA encapsulant investments toward Gujarat and Tamil Nadu industrial corridors.
- Reactive EVA systems:Crosslinking chemistry advances are opening electronics lamination specifications previously held by epoxy and polyurethane systems, particularly in flexible display bonding.
- Biomass-derived vinyl acetate:Bio-based feedstock pathways from wood pulp processing are nearing commercial scale, offering regulatory positioning under EU Green Deal carbon accounting frameworks.
Industry Challenges
- Formulation chemist scarcity:Expertise in reactive hot-melt rheology and photoinitiator package stability is concentrating among aging technical staff in German and Japanese specialty chemical clusters.
- Dual-carbon compliance timelines:China's MEE enforcement of carbon intensity benchmarks requires retrofitting solvent-based coating lines within compressed windows, straining capital allocation for mid-sized adhesive processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global EVA Adhesives Market |
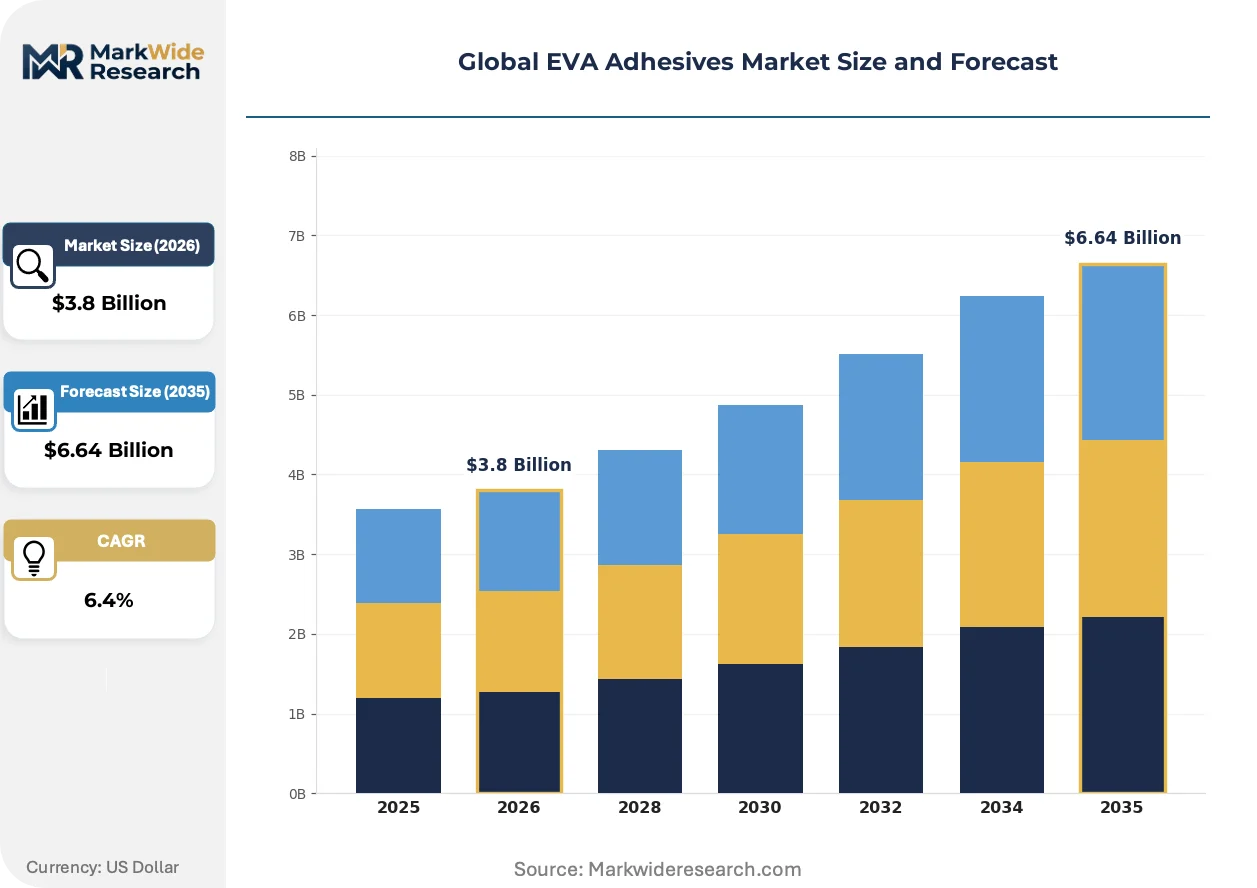
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Melt, Solvent-Based, Water-Based, Reactive, Pressure-Sensitive Application: Packaging, Footwear, Construction Materials, Automotive Components, Electronics Assembly End User: Polymer Processors, Footwear Manufacturers, Building Products Producers, Electrical Equipment Makers Distribution Channel: Direct Sales, Distributors, Online Retailers, Industrial Suppliers, Specialty Stores |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, Arkema Group, Dow, Aica Kogyo Co. Ltd, NANPAO RESINS CHEMICAL GROUP, Jowat SE, Soudal Holding N V, CEMEDINE Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global EVA Adhesives Market Shifts & Advancements
Digital formulation platforms are compressing product development cycles from months to weeks, enabling rapid response to shifting regulatory thresholds and end-use performance specifications. This acceleration is virtualizing traditional R&D hierarchies.
Reactive EVA systems incorporating silane crosslinking chemistry are virtualizing conventional thermal curing protocols in electronics lamination. Display manufacturers in South Korea and Taiwan are adopting these formulations for flexible OLED bonding, eliminating oven curing stages and reducing work-in-process inventory. The technology is virtualizing capital-intensive thermal processing infrastructure, enabling modular production lines with smaller footprints.
ECHA's REACH authorization requirements for boron-based crosslinking additives are forcing reformulation of high-performance EVA grades used in automotive structural bonding. European adhesive blenders are migrating toward peroxide-initiated systems or hybrid epoxy-EVA architectures to maintain specification compliance. The electronics and transportation segments bear the highest compliance burden, with Tier-1 suppliers demanding full substance disclosure through SCIP database entries.
Specification consolidation among photovoltaic module assemblers is compressing supplier qualification timelines and favoring integrated resin-to-adhesive producers capable of certifying full supply chain carbon intensity. Buyers in China and Germany now require ISO 14064-verified greenhouse gas accounting for encapsulant materials, displacing spot-market procurement of unverified EVA grades. This behavioral shift is most pronounced in utility-scale solar projects where lender environmental covenants mandate documented low-carbon sourcing.
Global EVA Adhesives Market Segmentation
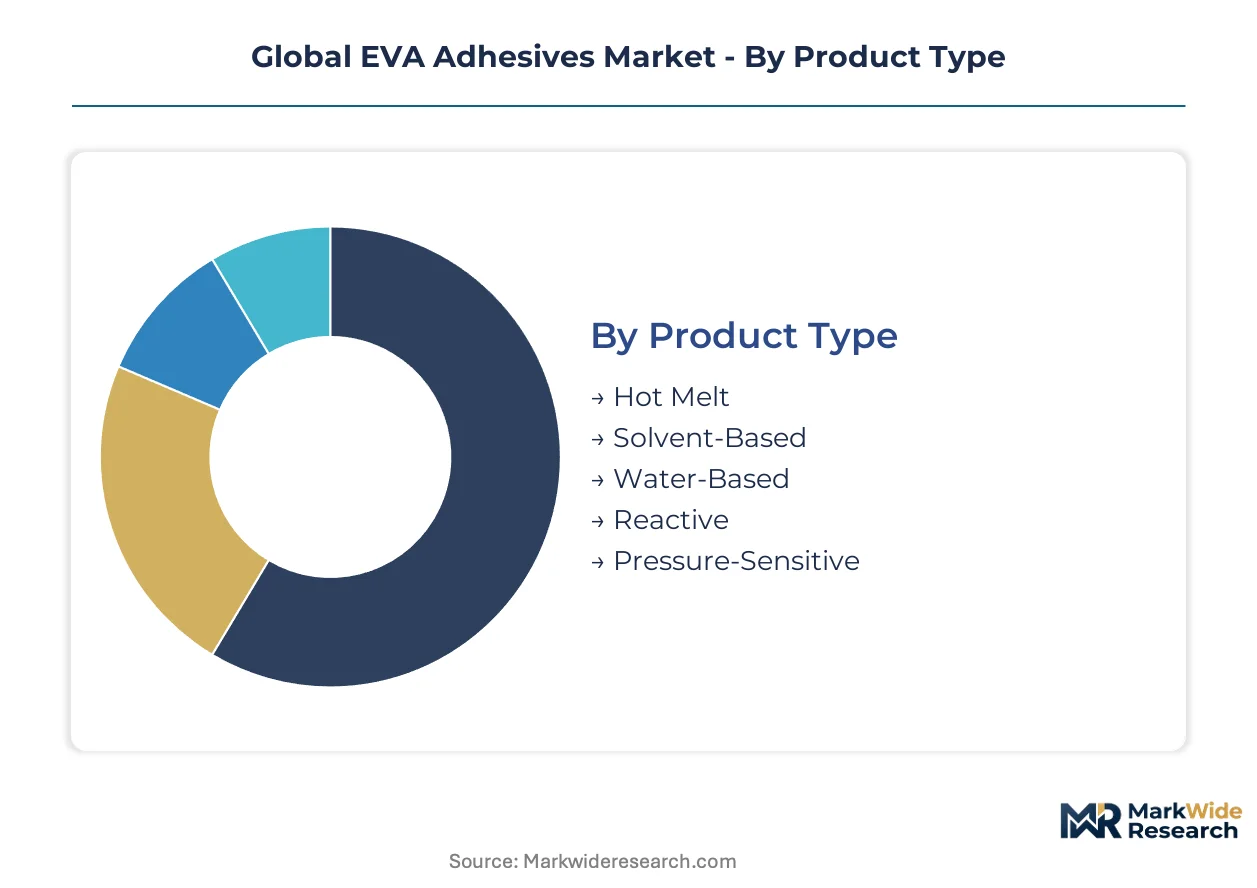
EVA adhesive segmentation reveals divergent growth mechanics across formulation chemistry and end-use specifications. Each category captures distinct margin profiles, regulatory exposure, and supply chain requirements that determine competitive positioning.
Product Type:
Mature hot-melt systems anchor volume consumption while reactive formulations emerge as the technology frontier for specification-intensive applications.
- Hot Melt:Thermoplastic formulations with 18-40% vinyl acetate content deliver instant tack development without solvent emissions. Packaging lines in Germany and China specify these systems to meet EPA and MEE audit requirements for volatile organic compound reduction.
- Reactive:Crosslinking chemistry incorporating silane or peroxide initiators enables thermal cycling durability beyond 85°C thresholds. South Korean display manufacturers specify these grades for flexible OLED bonding where epoxy alternatives previously dominated.
- Solvent-Based:Conventional solution adhesives face reformulation pressure under REACH substance restrictions and China's dual carbon enforcement timelines.
- Water-Based:Emulsion systems capture footwear and construction material specifications as factory emission controls tighten across export-oriented manufacturing clusters.
- Pressure-Sensitive:Mature formulations concentrate in label and tape applications with stable margin profiles and limited technology differentiation.
Hot Melt retains volume leadership; Reactive holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity packaging specifications from premium automotive and electronics bonding requirements.
- Packaging:High-volume carton sealing and flexible lamination consume the majority of commodity EVA hot-melt tonnage. German woodworking facilities specify water-based alternatives as ECHA SVHC classifications restrict conventional crosslinking additives.
- Electronics Assembly:Precision lamination for flexible displays and semiconductor packaging demands optical clarity and moisture resistance. Taiwan and South Korean manufacturers qualify reactive EVA systems to eliminate oven curing stages and compress work-in-process inventory.
- Footwear:Sole bonding and upper assembly applications migrate toward water-based formulations under tightening factory emission audits.
- Construction Materials:Panel lamination and flooring installation specifications favor hot-melt processing economics for on-site application efficiency.
- Automotive Components:Interior trim bonding captures solvent-free hot-melt share while structural applications remain excluded due to hydrolytic instability above 85°C.
Packaging commands the largest volume position; Electronics Assembly is climbing the fastest.
End User:
Customer type determines procurement sophistication, with integrated polymer processors exercising direct resin sourcing leverage versus fragmented building products channels.
- Polymer Processors:Integrated compounders and extruders purchase adhesive-grade EVA resin in bulk for captive formulation. Chinese photovoltaic encapsulant producers qualify suppliers on ISO 14064-verified carbon intensity metrics.
- Electrical Equipment Makers:Solar module assemblers in India and Germany mandate just-in-time delivery from localized blending facilities capable of certifying full supply chain greenhouse gas accounting.
- Footwear Manufacturers:Brand-owners and contract producers in Vietnam and Indonesia specify water-based systems to satisfy EU import compliance on volatile organic compound content.
- Building Products Producers:Fragmented procurement across construction material fabricators favors distributor intermediation over direct supply relationships.
Polymer Processors dominate procurement scale; Electrical Equipment Makers are gaining specification influence fastest.
Distribution Channel:
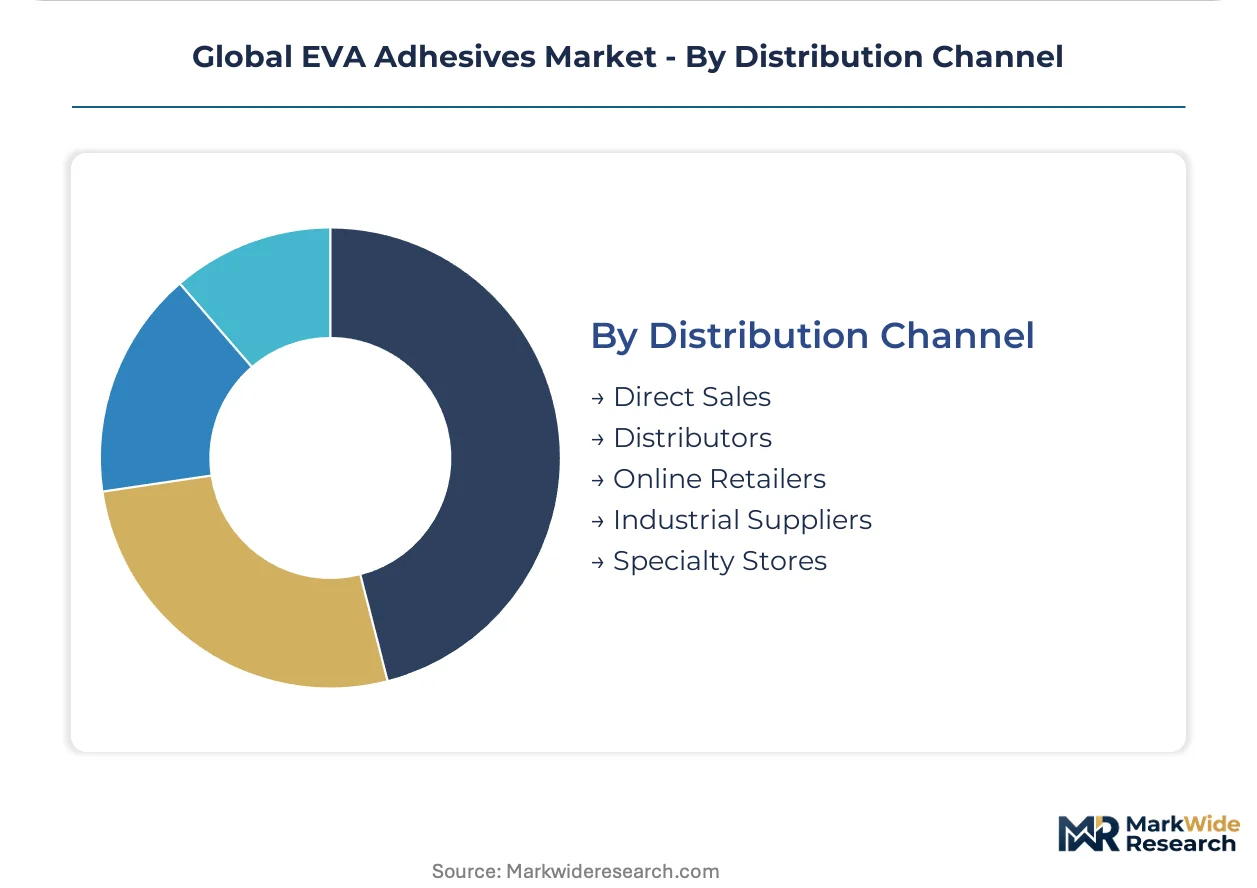
Supply concentration varies dramatically, with direct sales anchoring long-term contracts while specialty stores serve fragmented maintenance requirements.
- Direct Sales:Henkel and H.B. Fuller deploy technical sales infrastructure to secure multi-year supply agreements with footwear and automotive Tier-1 suppliers. These relationships bundle formulation development with volume commitments.
- Distributors:Regional chemical distributors sustain just-in-time inventory for mid-sized polymer processors lacking bulk storage infrastructure. Specialty chemical distribution is rewriting market access across Asia-Pacific and European manufacturing bases.
- Industrial Suppliers:Broad-line distributors capture maintenance and repair operations with standardized hot-melt formulations.
- Online Retailers:E-commerce penetration remains limited to small-volume packaging and woodworking applications.
- Specialty Stores:Localized outlets serve hobbyist and small contractor demand with negligible commercial significance.
Direct Sales commands the highest value concentration; Distributors are expanding geographic coverage most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ningbo-Zhoushan port complex handles the majority of ethylene-vinyl acetate resin imports for Chinese adhesive blenders, anchoring Asia-Pacific supply chain throughput. Germany's Rhine-Main-Danube waterway corridor enables just-in-time resin delivery to Bavarian and Baden-Württemberg manufacturing clusters. The US Gulf Coast petrochemical corridor transmits feedstock pricing volatility directly to North American EVA compounders through integrated pipeline networks.
China
Photovoltaic module assembly expansion in Jiangsu and Zhejiang provinces drives encapsulant-grade EVA consumption at double-digit rates. MEE enforcement of dual carbon goals accelerates water-based and hot-melt substitution in export-oriented polymer processing clusters around Shanghai. The Yangtze River Delta concentration of solar panel manufacturers now mandates ISO 14064-verified carbon intensity metrics for adhesive suppliers.
Germany
Domestic automotive component production and woodworking machinery exports sustain premium hot-melt formulation demand. ECHA's REACH SVHC classifications restrict conventional crosslinking additives, forcing reformulation toward peroxide-initiated reactive systems. The Baden-Württemberg industrial corridor hosts specialized blenders supplying just-in-time encapsulant delivery to local photovoltaic assemblers.
United States
Packaging line automation and footwear manufacturing reshoring expand solvent-free EVA consumption in the Southeast and Midwest. EPA hazardous air pollutant regulations limit emissions from adhesive coating operations, compelling lower-VOC system adoption. The Texas Gulf Coast concentration of ethylene crackers transmits feedstock cost volatility directly to domestic resin contract pricing.
India
Production-linked incentive schemes for solar module assembly attract EVA encapsulant investments toward Gujarat and Tamil Nadu industrial corridors. BIS quality certification requirements for construction materials create specification barriers for unverified imported formulations. The Mundra port infrastructure enables bulk resin import for captive blending at photovoltaic manufacturing parks.
South Korea
Flexible OLED display manufacturing in Gyeonggi Province qualifies reactive EVA systems for bonding applications previously held by epoxy alternatives. MFDS chemical substance registration requirements govern crosslinking additive imports for electronics-grade formulations. The Suwon-Seongnam industrial belt concentrates display panel assemblers demanding silane-crosslinked encapsulant chemistry.
Global EVA Adhesives Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling resin quality and formulation IP. The vendor base organizes around three functional tiers: integrated petrochemical producers with captive EVA resin supply, regional blending specialists with just-in-time logistics infrastructure, and application-focused formulators serving single end-use specifications. Strategic differentiation concentrates on backward integration into ethylene-vinyl acetate polymerization, geographic proximity to photovoltaic assembly clusters, and regulatory pre-certification for REACH and dual-carbon compliance.
Among German-origin chemical conglomerates, Henkel AG & Co. KGaA exemplifies the direct-sales platform archetype bundling technical service with multi-year supply agreements. H.B. Fuller Company represents the regional blending specialist model with distributed manufacturing footprints. Arkema Group occupies a position as an integrated resin-to-adhesive producer controlling upstream polymerization quality. These three anchors illustrate how competitive positioning stratifies across captive supply, logistics density, and formulation expertise vectors.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Arkema Group |
| Dow |
| Aica Kogyo Co. Ltd |
| NANPAO RESINS CHEMICAL GROUP |
| Jowat SE |
| Soudal Holding N V |
| CEMEDINE Co Ltd |
| Others |
Supply & Pricing Matrix
The Ningbo-Zhoushan port complex transmits freight cost volatility directly to EVA resin import pricing, compressing blender margins during container rate spikes while amplifying price differentiation between integrated producers and distributor-dependent compounders sourcing from Singapore and the Texas Gulf Coast.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 14064-certified encapsulant grades from unverified commodity resin and spot-market procurement. Premium tiers command valuation premiums based on carbon intensity verification and REACH pre-certification, while economy segments face acute price sensitivity from photovoltaic assemblers in Gujarat and Tamil Nadu. Cost compression in standard-grade hot-melt formulations is intensifying because of ethylene feedstock volatility transmitted from US Gulf Coast naphtha crackers.
Supply Chain Analysis
Extended payment terms from integrated petrochemical producers in China, South Korea, and Germany are restructuring working capital requirements for mid-sized adhesive blenders lacking bulk storage infrastructure. Raw material procurement draws from vinyl acetate monomer concentrated on the Texas coast and Singapore, ethylene feedstock from integrated crackers, and silane crosslinking additives subject to ECHA authorization delays. Single-source vulnerability around VAM supply creates geographic risk exposure. Distribution runs through regional chemical distributors sustaining just-in-time inventory for polymer processors in the Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, with REACH and dual-carbon compliance timelines creating switching costs that lock in qualified suppliers and exclude unverified competitors from specification-intensive photovoltaic and electronics segments.
For Market Incumbents: Build certification moats by accelerating ISO 14064 verification for encapsulant grades and securing multi-year offtake agreements with module assemblers in Jiangsu and Zhejiang. Threat of biomass-derived vinyl acetate disruption from wood pulp processing pathways demands backward integration into resin polymerization or captive bio-feedstock partnerships. Capacity addition in Tamil Nadu industrial corridors anchors just-in-time delivery commitments for production-linked incentive beneficiaries. For New Entrants and Emerging Players: Establish a beachhead in water-based EVA formulations for Vietnamese and Indonesian footwear manufacturers facing EU import compliance audits. White-space concentrates in reactive systems for South Korean flexible OLED bonding, where silane crosslinking chemistry displaces epoxy alternatives. Go-to-market angle centers on digital formulation platforms compressing product development cycles for mid-sized polymer processors lacking in-house R&D infrastructure. For Investors and Strategic Acquirers: Regional blending specialists with just-in-time logistics density in photovoltaic manufacturing clusters represent the most defensible acquisition archetype for long-term viability across the analysis window. Signal to watch is consolidation among Indian solar module assemblers qualifying localized encapsulant suppliers under BIS quality certification requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVA Resin Polymerization | Captive supply from Texas Gulf Coast and Singapore VAM feedstock secures margin control against olefin volatility. |
| Green Manufacturing Transition | Bio-based vinyl acetate pathways from wood pulp processing align with EU Green Deal carbon accounting frameworks. |
| Long-term Supply Agreement | Multi-year contracts with German and Chinese photovoltaic assemblers lock in volume through REACH compliance windows. |
| Joint Venture | Localized blending partnerships in Gujarat and Tamil Nadu capture production-linked incentive scheme beneficiaries. |
| Capacity Expansion | Regional facilities in Baden-Württemberg enable just-in-time encapsulant delivery to ECHA-regulated automotive suppliers. |
Research Methodology
Operator-level perspectives from plant managers at adhesive blending facilities, procurement leads at photovoltaic module assemblers, distribution channel partners in Asia-Pacific chemical distribution networks, and technical R&D directors specializing in reactive hot-melt rheology anchored the qualitative base. Secondary validation drew from customs and trade data tracking ethylene-vinyl acetate resin flows, Cefic sector reports on adhesive formulation trends, SEC 10-K filings from integrated petrochemical producers, and ECHA substance restriction databases. Bottom-up demand modeling across end-use segments triangulated against top-down macroeconomic indicators to establish market sizing.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation dimensions spanning formulation chemistry tier, end-use industry application, regional production hub concentration, and carbon intensity verification status. CAGRs derived from regression analysis against historical ethylene feedstock pricing cycles, photovoltaic installation capacity buildouts, and regulatory compliance timeline acceleration. Industry-specific forecast inputs incorporated MEE dual-carbon enforcement intensity and REACH SVHC classification expansion schedules.
Sensitivities concentrate around ethylene cracker output fluctuations, ECHA authorization delays for boron-based crosslinking additives, and photovoltaic manufacturing capacity migration patterns. Forecasts reflect documented assumptions on feedstock cost transmission elasticity and regulatory compliance adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Asia-Pacific EVA Adhesives Market
Adhesives & Sealants
Global Tissue Sealants Market
Adhesives & Sealants
Fuel Resistant Sealant Market
Adhesives & Sealants
Silicone Sealants Market
Adhesives & Sealants
Ocular Sealants and Glues Market
Adhesives & Sealants
Automotive Windshield Adhesives Market
Adhesives & Sealants
EMEA Epoxy Adhesives Market
Adhesives & Sealants
Plastic Adhesives Market
Adhesives & Sealants
United States Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Acrylate Oligomer Market
Adhesives & Sealants
Bio-Based Adhesive and Sealant Market
Adhesives & Sealants
Acrylic Flooring Adhesives Market
Adhesives & Sealants
United Kingdom Sealants Market
Adhesives & Sealants
Adhesive Resin Market
Adhesives & Sealants
South America Sealants Market