
 Digital Brain Health Market | 2026-2036
Digital Brain Health Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Brain Health Market Analysis
Cloud infrastructure is restructuring product economics across digital brain health as on-premise deployments give way to scalable SaaS architectures. Akili Interactive leverages its FDA-cleared pediatric ADHD platform to anchor its position in prescription digital therapeutics. IBM sustains competitive relevance through Watson Health's cognitive analytics capabilities for neurological data interpretation. Pear Therapeutics differentiates via its end-to-end platform spanning prescription digital therapeutics and clinician-facing reimbursement infrastructure.
Digital brain health encompasses software-based interventions, biometric monitoring systems, and AI-driven cognitive assessment tools designed to measure, maintain, or improve neurological function through digital interfaces. These platforms typically incorporate real-time data processing algorithms, neuropsychological test batteries, and longitudinal analytics dashboards to enable early detection of cognitive decline and personalized intervention protocols. Mobile Applications currently lead product type revenue pools due to low distribution friction and direct-to-consumer accessibility, while Software Platforms capture the deepest enterprise margins through EMR integration and clinical workflow embedding. Healthcare Providers represent the fastest-growing end user segment as hospital systems and neurology practices integrate reimbursable digital cognitive assessments into standard care pathways.
FDA digital therapeutics enforcement discretion policies and the EU MDR's software-as-medical-device classification collectively shape product development roadmaps and market access timelines for platform developers. HIPAA compliance requirements and GDPR health data provisions impose stringent data governance costs that favor established vendors with dedicated regulatory operations. Stakeholders must monitor evolving reimbursement codes for remote cognitive monitoring as payer acceptance patterns will determine which delivery models achieve sustainable unit economics.
Market Dynamics
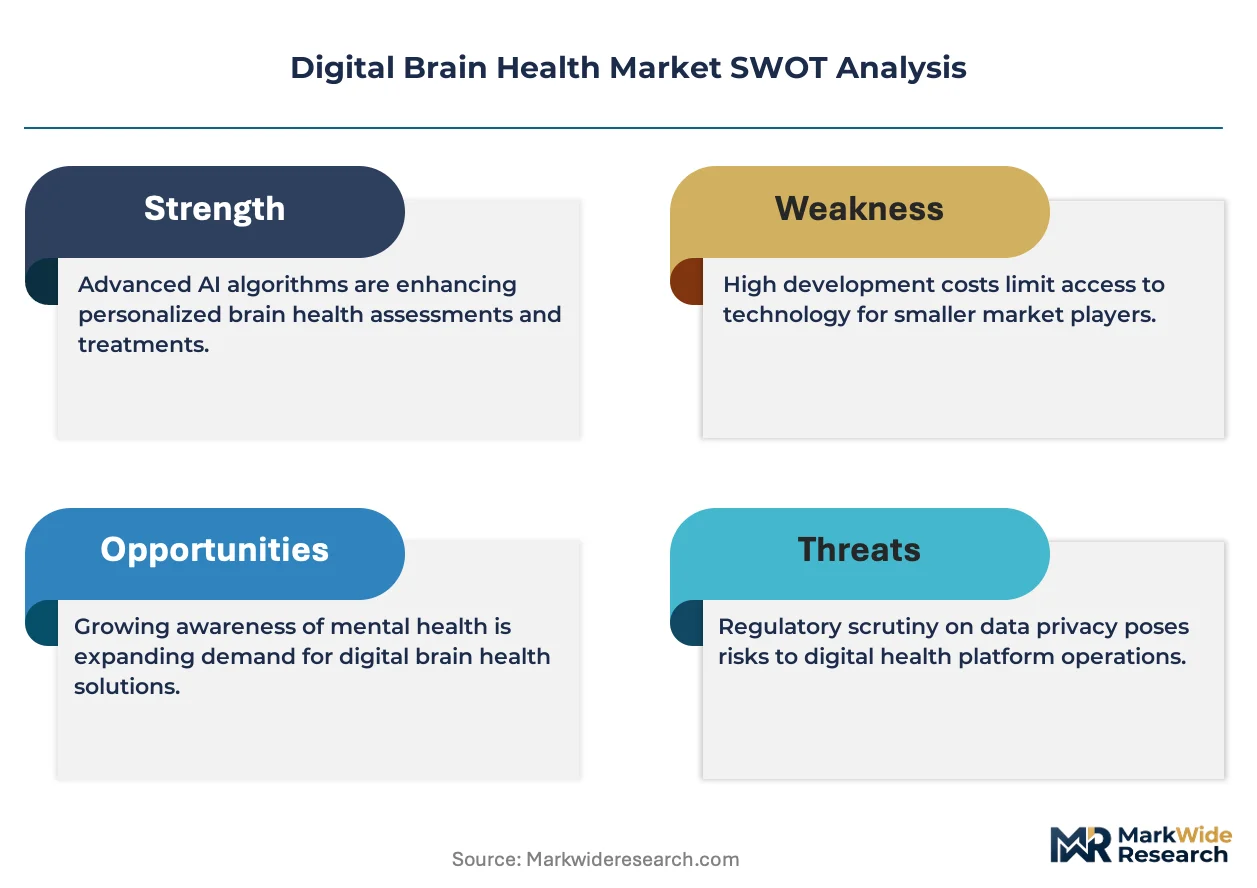
Cloud-native SaaS architectures are restructuring digital brain health economics, compressing deployment timelines from months to weeks while collapsing upfront infrastructure costs that previously locked out mid-tier healthcare systems.
Growth Catalysts
- FDA Enforcement Discretion:The FDA's streamlined digital therapeutics pathway accelerates market entry for prescription-grade cognitive intervention platforms, reducing pre-market validation burdens for qualified software.
- EMR Integration Mandates:Hospital systems in the United States demand seamless cognitive assessment data flows into Epic and Cerner environments, embedding digital brain health tools into routine neurology workflows.
- Passive Biometric Sensing:Smartphone accelerometers and wearable EEG bands enable continuous cognitive monitoring without active patient participation, expanding addressable populations beyond clinic-dependent cohorts.
Market Restraints
- GDPR Health Data Governance:European Union data localization requirements impose infrastructure duplication costs that fragment platform architectures and strain vendor operational margins.
- Reimbursement Code Gaps:CMS and private payers maintain inconsistent coverage policies for remote cognitive monitoring, forcing providers to absorb out-of-pocket costs or limit service availability.
- Clinical Validation Burden:Peer-reviewed efficacy studies for each indicated condition require multi-year, multi-site trials that consume R&D budgets and delay commercialization.
Strategic Opportunities
- India's Digital Health Stack:The country's ABDM interoperability framework creates standardized rails for cognitive assessment integration into primary care, opening access to 1.4 billion screened individuals.
- Convergence of Generative AI and Neuroimaging:Large language models interpreting MRI and fMRI outputs promise automated differential diagnosis support, compressing specialist consultation queues.
- Employer Wellness Channels:Fortune 500 occupational health programs represent an underpenetrated B2B vector for cognitive fitness tools, bypassing clinical reimbursement dependencies entirely.
Industry Challenges
- Neuropsychologist Talent Scarcity:Platform developers compete for limited clinical advisory capacity to design validated assessment batteries and secure FDA clearance.
- Legacy EHR Integration Friction:Proprietary data formats in older hospital systems demand costly custom API development, slowing enterprise sales cycles and inflating implementation quotes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Brain Health Market |
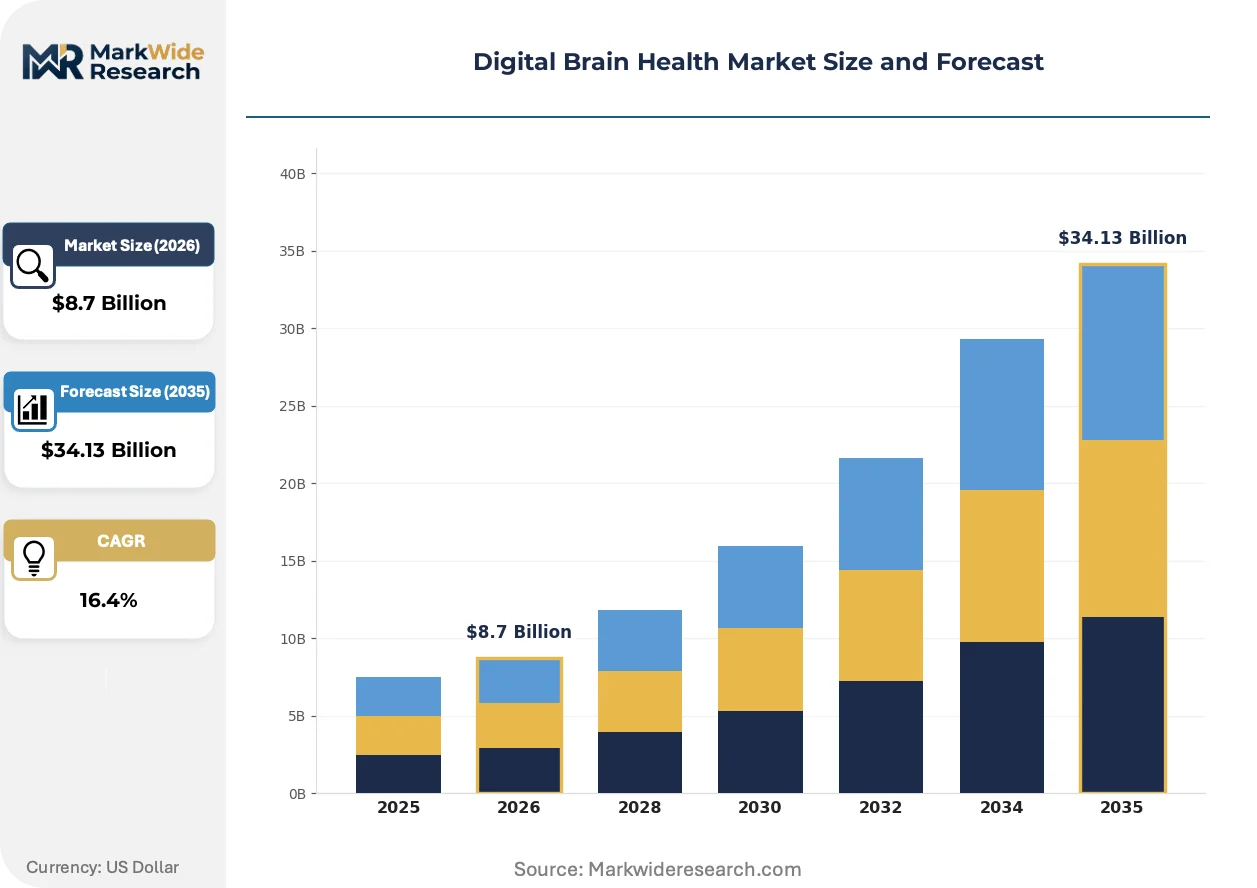
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Applications, Wearable Devices, Software Platforms, Online Programs End User: Individuals, Healthcare Providers, Educational Institutions, Corporate Wellness Programs Delivery Mode: Cloud-Based, On-Premise, Hybrid, Subscription-Based Application: Stress Management, Cognitive Training, Mental Health Monitoring, Mood Tracking |
| Companies Covered | IBM, Linus Health, Holmusk, Medibio, Netsmart Technologies, Cerner Corporation, Akili Interactive, Pear Therapeutics, Cogstate Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Brain Health Market Emerging Trajectories
Digital brain health is experiencing a platformization wave where point solutions give way to integrated ecosystems, compressing vendor count while expanding functional scope per contract.
Edge computing for real-time cognitive assessment is consolidating processing power into localized devices, reducing latency for attention-training games and enabling offline functionality in bandwidth-constrained rural clinics. Neurology practices in the United States are deploying these architectures to maintain service continuity during network outages. The shift is consolidating vendor relationships around hardware-software bundles that lock in multi-year enterprise commitments.
The EU AI Act's risk classification system for medical decision-support software is forcing developers to reengineer algorithmic transparency features and maintain comprehensive training data documentation. Products falling into the high-risk category face notified body conformity assessments that extend time-to-market by 12-18 months. German and French healthcare procurement offices are now requiring AI Act compliance certifications as mandatory bid prerequisites.
Direct-to-consumer subscription models are displacing traditional B2B2C distribution through employer and payer channels, with individuals paying out-of-pocket for cognitive training apps and brain health monitoring services. This bypasses reimbursement friction but intensifies customer acquisition cost pressures and churn risk. The pattern is most visible in United States metropolitan markets where wellness spending penetration exceeds clinical service utilization rates.
Digital Brain Health Market Segmentation
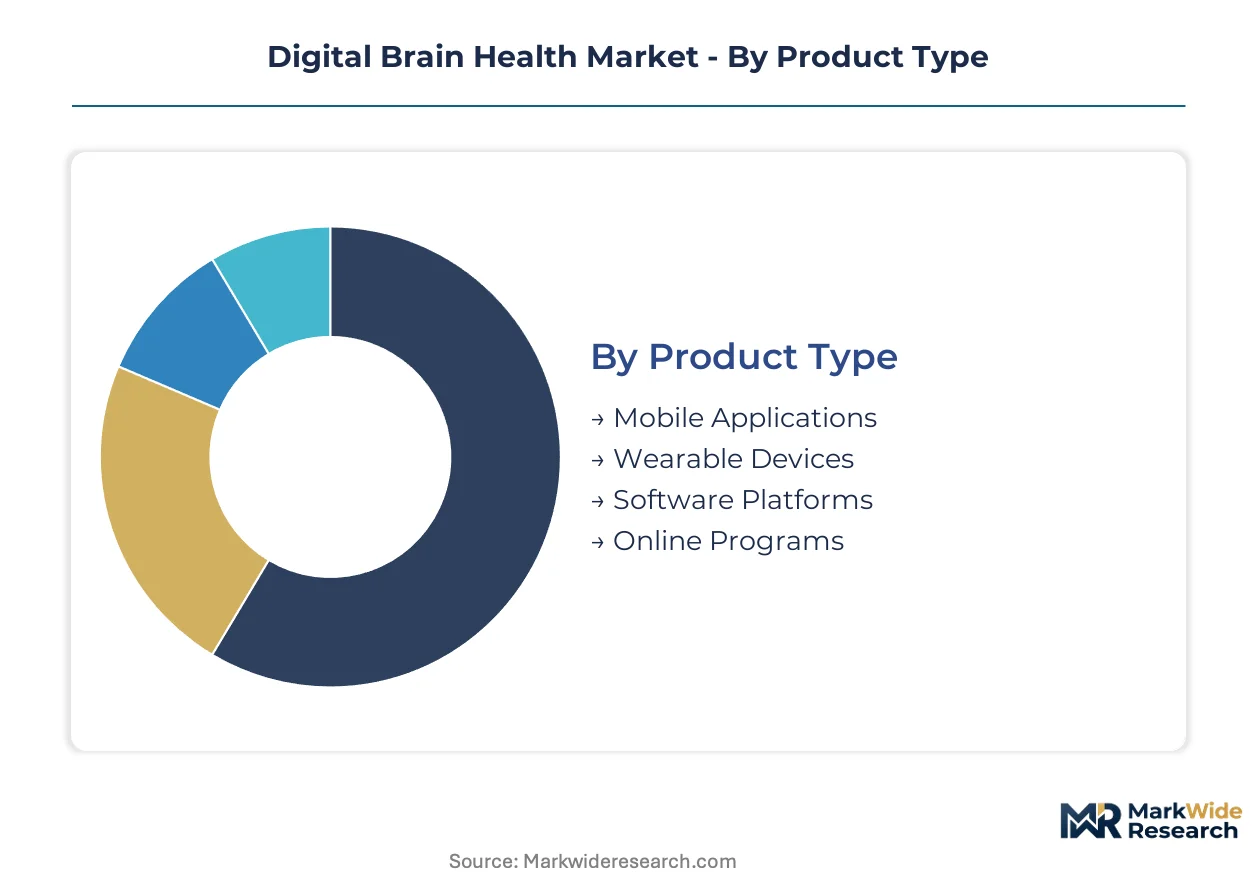
Segmentation in digital brain health determines reimbursement pathways, regulatory classification, and customer acquisition economics. Product architecture choices cascade into delivery mode requirements and end-user pricing power. Application focus shapes clinical validation burdens and partnership strategies with healthcare systems.
Product Type:
Purchase decisions hinge on integration depth with existing clinical infrastructure and data portability requirements.
- Mobile Applications:Consumer-facing interfaces deploy cognitive training protocols through smartphone ecosystems with minimal hardware dependencies. Direct-to-consumer channels in United States metropolitan markets absorb customer acquisition costs through wellness spending budgets, though churn rates pressure lifetime value calculations.
- Software Platforms:Enterprise-grade systems embed neuropsychological test batteries into Epic and Cerner EMR workflows with HL7 FHIR interoperability. Hospital systems in the United States prioritize these deployments for reimbursable cognitive assessments, consolidating vendor relationships around multi-year enterprise agreements.
- Wearable Devices:EEG bands and accelerometer-enabled hardware enable passive biometric monitoring without active patient participation.
- Online Programs:Browser-based cognitive interventions deliver structured curricula through web portals with lower development overhead than native applications.
Volume sits with Mobile Applications; growth tilts toward Software Platforms.
End User:
Revenue concentration follows reimbursement code availability and procurement authorization pathways.
- Healthcare Providers:Neurology practices and hospital systems integrate FDA-cleared platforms into standard care pathways with CMS billing code support. United States health systems demand EMR interoperability and clinical workflow embedding, filtering vendor eligibility to established regulatory operators.
- Corporate Wellness Programs:Fortune 500 occupational health budgets fund cognitive fitness tools outside clinical reimbursement dependencies entirely. Employer channels bypass payer friction but require ROI demonstration through productivity metrics and healthcare cost reduction claims.
- Individuals:Out-of-pocket subscribers access direct-to-consumer cognitive training apps with monthly or annual billing.
- Educational Institutions:University counseling centers and K-12 districts deploy screening tools for student mental health monitoring.
Revenue concentrates with Healthcare Providers; expansion accelerates most quickly in Corporate Wellness Programs.
Delivery Mode:
Margin structure and implementation timeline trade-offs dominate vendor architecture decisions.
- Cloud-Based:SaaS architectures compress deployment timelines from months to weeks while collapsing upfront infrastructure costs. North American clinical settings concentrate demand here as mid-tier healthcare systems previously locked out by on-premise capital requirements gain platform access.
- Subscription-Based:Recurring revenue models align vendor incentives with longitudinal patient engagement and outcome demonstration. This delivery mode spans both clinical and consumer contexts, with annual contracts preferred for enterprise stability and monthly options for individual accessibility.
- Hybrid:Mixed deployments maintain sensitive processing on local infrastructure while leveraging cloud analytics.
- On-Premise:Legacy installations persist in European healthcare systems facing GDPR data localization mandates.
Deployment volume favors Cloud-Based; pricing power accumulates in Subscription-Based structures.
Application:
Clinical validation requirements and regulatory pathway complexity segment addressable market entry.
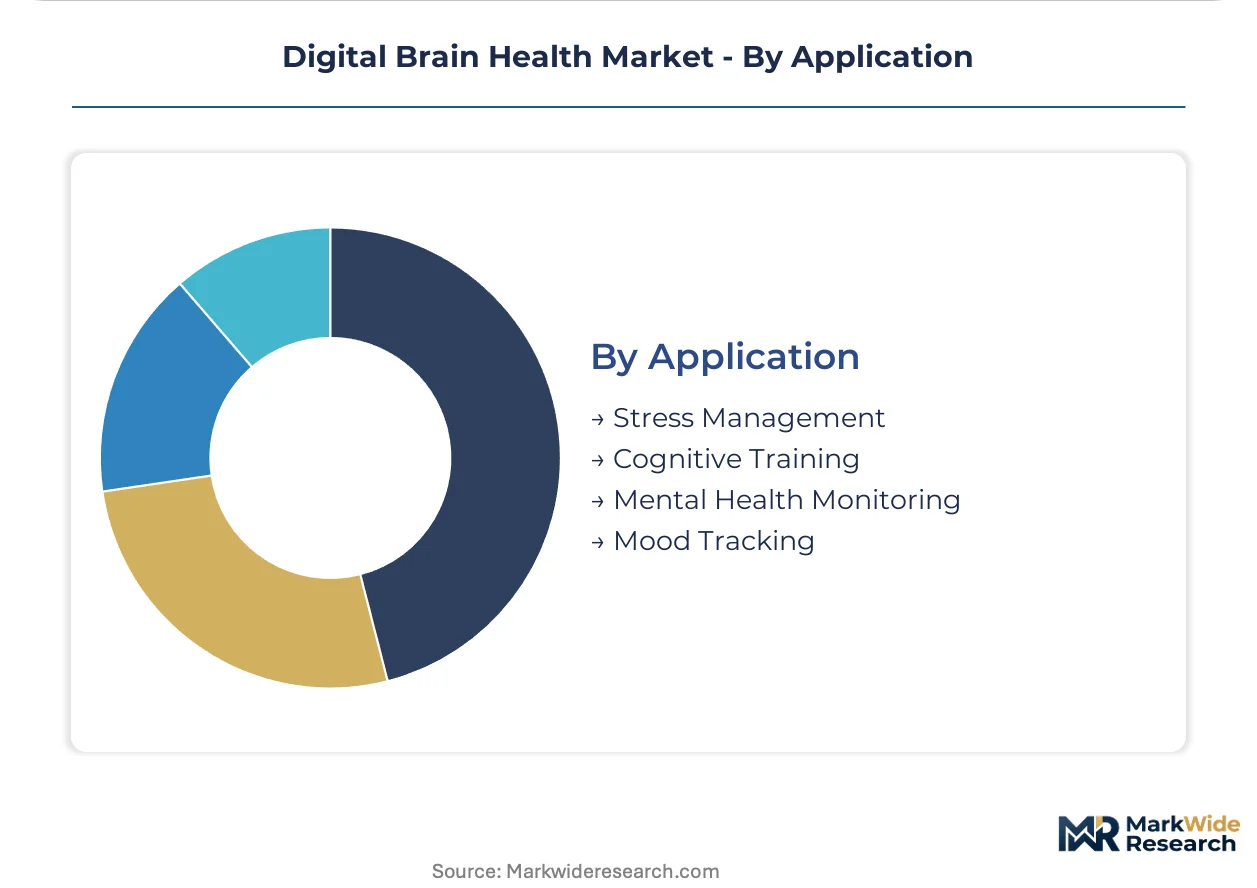
- Cognitive Training:Structured protocols target attention, memory, and executive function through adaptive difficulty algorithms. FDA enforcement discretion policies streamline market entry for prescription-grade platforms, with pediatric ADHD indications already cleared and adult cognitive decline applications advancing through trials.
- Mental Health Monitoring:Continuous assessment of depression, anxiety, and stress biomarkers through passive smartphone sensing and active self-report instruments. European MDR compliance pathways impose software-as-medical-device classification burdens that extend time-to-market for algorithmic diagnostic support features.
- Stress Management:Biofeedback and mindfulness-based interventions delivered through guided exercises and physiological monitoring.
- Mood Tracking:Longitudinal self-report tools and behavioral pattern recognition for affective state documentation.
Regulatory clarity concentrates investment in Cognitive Training; unmet need pulls development toward Mental Health Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare providers in the United States concentrate demand for FDA-cleared cognitive assessment platforms, while European systems under MDR compliance and Asian digital health stacks reshape procurement patterns.
United States
Hospital systems and neurology practices drive demand for reimbursable cognitive assessments embedded in Epic and Cerner workflows. FDA enforcement discretion policies accelerate market entry for prescription digital therapeutics. The Greater Boston cluster anchors development activity for pediatric ADHD platforms.
Germany
Healthcare procurement offices require EU AI Act compliance certifications as mandatory bid prerequisites for algorithmic diagnostic support. GDPR data localization mandates sustain on-premise infrastructure requirements. The Berlin-Brandenburg metro concentrates notified body conformity assessment activity.
United Kingdom
NHS digital transformation programs integrate cognitive screening tools into primary care pathways. MHRA guidance on software-as-medical-device classification shapes product development timelines. London's health tech cluster hosts multiple EMR interoperability specialists.
India
The ABDM interoperability framework creates standardized rails for cognitive assessment integration into primary care networks. CDSCO medical device regulations govern software classification for diagnostic algorithms. Karnataka's Bengaluru tech corridor concentrates health-tech development capacity.
Japan
Aging demographics drive demand for dementia screening and cognitive monitoring platforms. PMDA digital therapeutics guidance establishes regulatory pathways for software-based interventions. Tokyo's Kanto region hosts major hospital system procurement decision centers.
Digital Brain Health Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform developers holding concentrated positions in prescription-grade cognitive interventions while point-solution vendors face margin compression. The vendor base organizes around three archetypes: FDA-cleared prescription digital therapeutic developers, EMR-integrated enterprise software platforms, and direct-to-consumer cognitive training applications. M&A activity concentrates among enterprise software vendors acquiring biometric monitoring capabilities, while strategic partnerships between neuroimaging AI developers and hospital systems accelerate.
Among US-based platform developers, Akili Interactive and Pear Therapeutics exemplify the prescription digital therapeutic archetype, anchoring positions in FDA-cleared cognitive intervention categories. IBM represents the enterprise analytics tier through Watson Health's neurological data interpretation capabilities. These three occupy positions across distinct competitive vectors: pediatric ADHD indications, end-to-end reimbursement infrastructure, and cognitive analytics for clinical decision support.
| Leading Market Players |
|---|
| IBM |
| Linus Health |
| Holmusk |
| Medibio |
| Netsmart Technologies |
| Cerner Corporation |
| Akili Interactive |
| Pear Therapeutics |
| Cogstate Ltd. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up enterprise software platforms discipline pricing through multi-year EMR integration contracts that lock hospital systems into predictable SaaS fee structures while compressing margins for standalone point-solution vendors. This ownership pattern concentrates supply-side bargaining power among vendors with dedicated regulatory operations, forcing price competition downward for undifferentiated cognitive training applications.
Pricing Analysis
Volume concentrates in direct-to-consumer mobile applications with low unit margins, while enterprise software platforms capture premium pricing through EMR workflow embedding and FDA clearance tiers. Price differentiation hinges on certification level—FDA-cleared prescription digital therapeutics command three-to-five-fold premiums over wellness-class applications—and integration depth with Epic or Cerner environments. Pricing pressure stems from reimbursement code gaps that force providers to absorb out-of-pocket costs, intensifying scrutiny on per-seat SaaS fees. Corporate wellness programs exhibit lowest price sensitivity due to productivity-linked ROI frameworks, while individual subscribers churn rapidly when monthly fees exceed wellness budget thresholds.
Supply Chain Analysis
Reverse-logistics flows for wearable EEG bands and accelerometer-enabled hardware concentrate refurbishment operations in Shenzhen and Dongguan, where component recovery rates determine lifetime hardware economics. Core software development anchors in the United States, India, and Israel, with Bengaluru and Tel Aviv hosting specialized cognitive assessment engineering teams. Raw material dependencies include semiconductor chips for edge-computing devices, lithium-ion cells for wearable power systems, and cloud compute credits for AI-driven analytics. Single-source vulnerability runs through Taiwan-based foundries for specialized neuroimaging processing units. Distribution runs through hospital GPO contracts in North America, national health procurement frameworks in Europe, and direct-to-consumer app stores for wellness-tier products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as multi-year clinical validation burdens and FDA clearance timelines force capital-constrained point-solution vendors toward distressed exits or strategic absorption.
For Market Incumbents: Extend platform scope through biometric monitoring acquisitions that harden switching costs for hospital system customers. Acquire EEG hardware specialists or passive sensing algorithm teams to consolidate vendor relationships around hardware-software bundles. FDA enforcement discretion policies favor established regulatory operators with dedicated compliance infrastructure, creating acquisition opportunities among pre-revenue cognitive training startups facing capital exhaustion. For New Entrants and Emerging Players: Generative AI-powered neuroimaging interpretation offers a technology-first wedge into specialist consultation queues currently constrained by neuropsychologist scarcity. Target India's ABDM-integrated primary care networks as the most penetrable geography, where standardized interoperability rails reduce EMR integration friction. Pursue employer wellness channels with productivity-metric ROI demonstrations that bypass clinical reimbursement dependencies entirely. For Investors and Strategic Acquirers: Distressed-cycle entries favor FDA-cleared prescription digital therapeutic developers in the United States with validated pediatric ADHD platforms and dormant adult indication pipelines. Long-term viability hinges on sustainable unit economics under evolving CMS remote monitoring codes. Monitor payer acceptance patterns for cognitive assessment billing codes as the primary inflection indicator for platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Adult Indications | Expands addressable population beyond pediatric ADHD into cognitive decline monitoring. |
| EMR Integration Partnership | Embeds assessment tools into Epic and Cerner workflows for reimbursable clinical use. |
| Reimbursement Strategy Development | Secures CMS billing code support for remote cognitive monitoring services. |
| Acquisition of Biometric Monitoring Firm | Consolidates hardware-software bundles that lock in multi-year enterprise commitments. |
| EU AI Act Compliance Certification | Enables procurement eligibility in German and French healthcare systems. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with digital therapeutics executives, FDA regulatory affairs leads, hospital procurement managers, and neuropsychology practice administrators. Primary fieldwork combined with FDA 510(k) clearance databases, CMS reimbursement code trackers, EU MDR notified body filings, and hospital GPO contract disclosures. Bottom-up unit economics modeling triangulated against top-down market sizing from healthcare IT expenditure surveys.
Data-stream reconciliation across deployment mode, application focus, end-user segment, and regional regulatory cluster produced volume and value estimates throughout the forecast period. CAGRs derived from fitted growth curves against historical adoption patterns in comparable digital health categories. Industry-specific inputs included FDA enforcement discretion policy evolution, EU AI Act implementation timelines, and India's ABDM interoperability rollout pace.
Several conditions sit outside the modeled scope, including hypothetical breakthroughs in non-invasive brain-computer interfaces, radical shifts in pharmaceutical cognitive enhancement regulation, and sovereign healthcare system collapses. Practitioners should monitor FDA digital therapeutics guidance updates, CMS remote monitoring code expansions, and EU AI Act high-risk classification rulings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Pharmacovigilance (PV) and Drug Safety Software Market
Digital Health Solutions
Mixed Reality in Healthcare Market
Digital Health Solutions
Teleradiology Software Market
Digital Health Solutions
Artificial Intelligence in Precision Medicine Market
Digital Health Solutions
Augmented and Virtual Reality in Healthcare Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
Surgical Planning Software Market
Digital Health Solutions
Global Health Kiosk Market
Digital Health Solutions
Long Term Post-Acute Care Software Market
Digital Health Solutions
Mhealth Applications Market
Digital Health Solutions
Asia-Pacific Digital Therapeutic (Dtx) Market
Digital Health Solutions
Patient Engagement Platforms Market
Digital Health Solutions
Global Patient Centric Healthcare App Market
Digital Health Solutions
Global Preventive Healthcare Technologies and Services Market
Digital Health Solutions
Care Management Solutions Market