
 Biometrics Banking Market | 2026-2036
Biometrics Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Biometrics Banking Market Insights
Platform licensing revenue is reconfiguring competitive economics as hardware commoditizes across the biometrics banking stack. NEC Corporation leverages its algorithm portfolio to dominate large-scale government-linked banking deployments across Asia. IDEMIA sustains market presence through end-to-end credential management systems that integrate physical and digital identity layers. Thales Group anchors European banking security infrastructure with hardware security modules and biometric authentication middleware.
Biometrics banking encompasses the deployment of physiological and behavioral recognition systems for identity verification in financial services, typically operating with false acceptance rates below 0.001% and liveness detection protocols to prevent spoofing. These systems authenticate customers through fingerprint, facial, iris, or behavioral pattern analysis to secure transactions and streamline account access. Fingerprint recognition occupies the largest installed base among authentication types due to mature sensor costs and consumer familiarity, while behavioral biometrics represents the fastest-expanding segment as continuous authentication gains traction for fraud detection. Cloud-based deployment models are capturing margin pools from on-premises installations as banks seek operational flexibility and faster integration cycles.
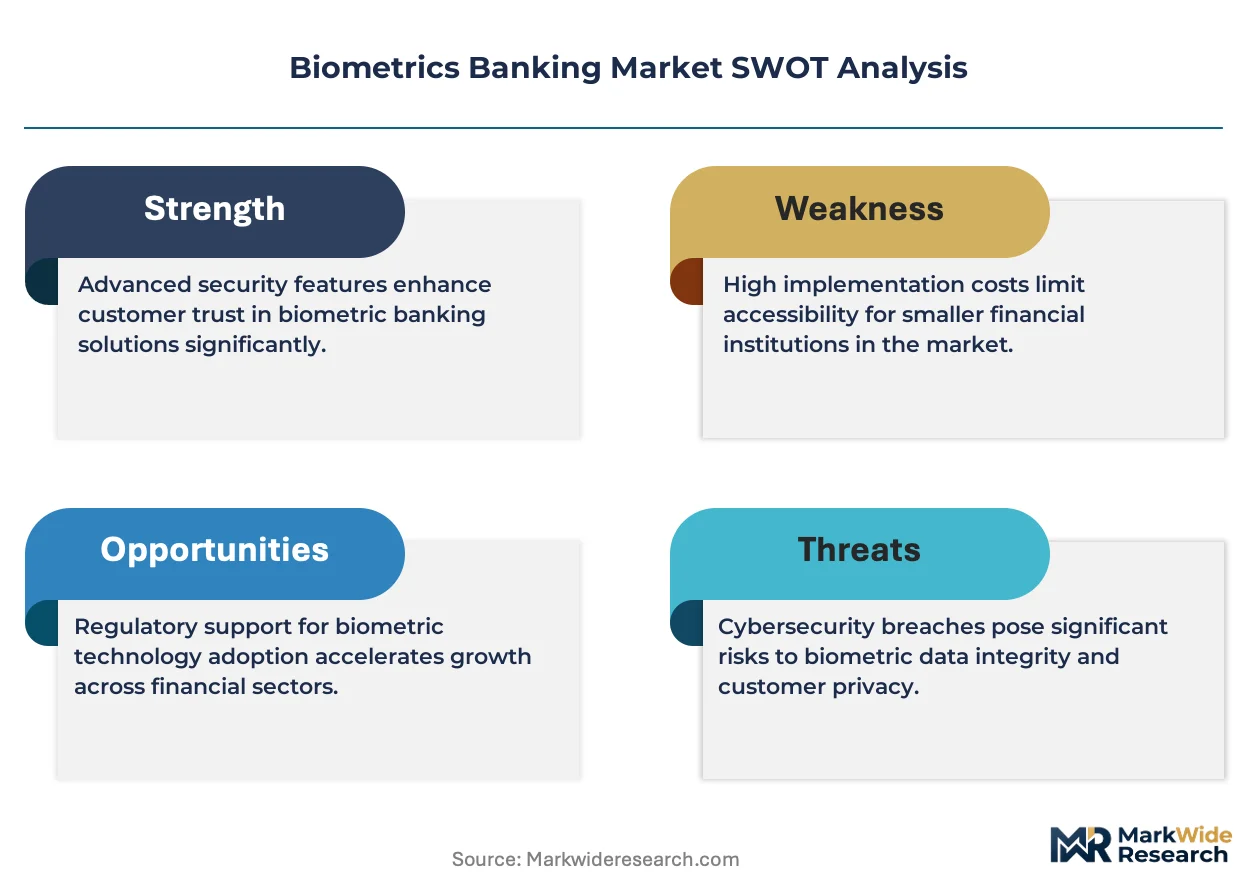
The EU AI Act imposes strict conformity requirements on biometric identification systems deployed by European banks, while GDPR mandates explicit consent frameworks for facial and voice data processing that shape product architecture decisions. In the United States, the FFIEC authentication guidance and state-level biometric privacy laws in Illinois and Texas create a fragmented compliance landscape that vendors must navigate. Stakeholders should monitor evolving regulatory divergence between privacy-centric European frameworks and security-driven U.S. federal banking standards to align R&D investment and market entry sequencing.
Market Dynamics
Platform licensing economics are compressing hardware margins across the biometrics banking stack, forcing vendors to capture value through algorithm subscriptions and cloud-native authentication services rather than sensor sales.
Growth Catalysts
- EU AI Act Conformity Mandates:European banks must deploy privacy-preserving biometric architectures by 2026, creating immediate demand for liveness detection and on-device processing systems that eliminate centralized biometric storage.
- Continuous Authentication Protocols:Behavioral biometrics analyzing keystroke dynamics and mouse movements enable real-time fraud detection without interrupting customer workflows, driving replacement cycles for static password systems.
- United States:Major financial institutions including JPMorgan Chase and Bank of America are deploying multimodal systems combining facial recognition with voice biometrics for high-value wire transfers.
Market Restraints
- Silicon Supply Concentration:Advanced fingerprint sensor fabrication depends on TSMC's 28nm capacity in Taiwan, exposing biometric hardware vendors to geopolitical supply disruptions and foundry allocation constraints.
- GDPR Consent Friction:Explicit opt-in requirements for facial and voice data processing in European retail banking increase customer abandonment rates during digital onboarding sequences.
- Presentation Attack Vulnerability:Deepfake-synthesized voice prints and hyper-realistic masks threaten voice and facial recognition systems, forcing continuous R&D investment in anti-spoofing algorithms.
Strategic Opportunities
- India:The RBI's digital payment push and Aadhaar-linked financial inclusion programs create demand for low-cost biometric POS terminals and voice-authenticated rural banking services.
- Embedded Finance Convergence:Biometric authentication modules integrated directly into automotive infotainment and smart home devices enable contextual banking transactions outside traditional app environments.
- PSD2 Strong Customer Authentication:European open banking regulations mandate two-factor authentication for electronic payments, expanding addressable market for behavioral biometrics as a possession-independent factor.
Industry Challenges
- Algorithm Bias Mitigation:Training datasets skewed toward lighter skin tones and specific age demographics produce elevated false rejection rates for underrepresented populations, requiring expensive dataset curation and fairness auditing.
- Core Banking Integration Complexity:Decades-old COBOL-based legacy systems at major financial institutions resist API-native biometric middleware, extending deployment timelines and inflating professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometrics Banking Market |
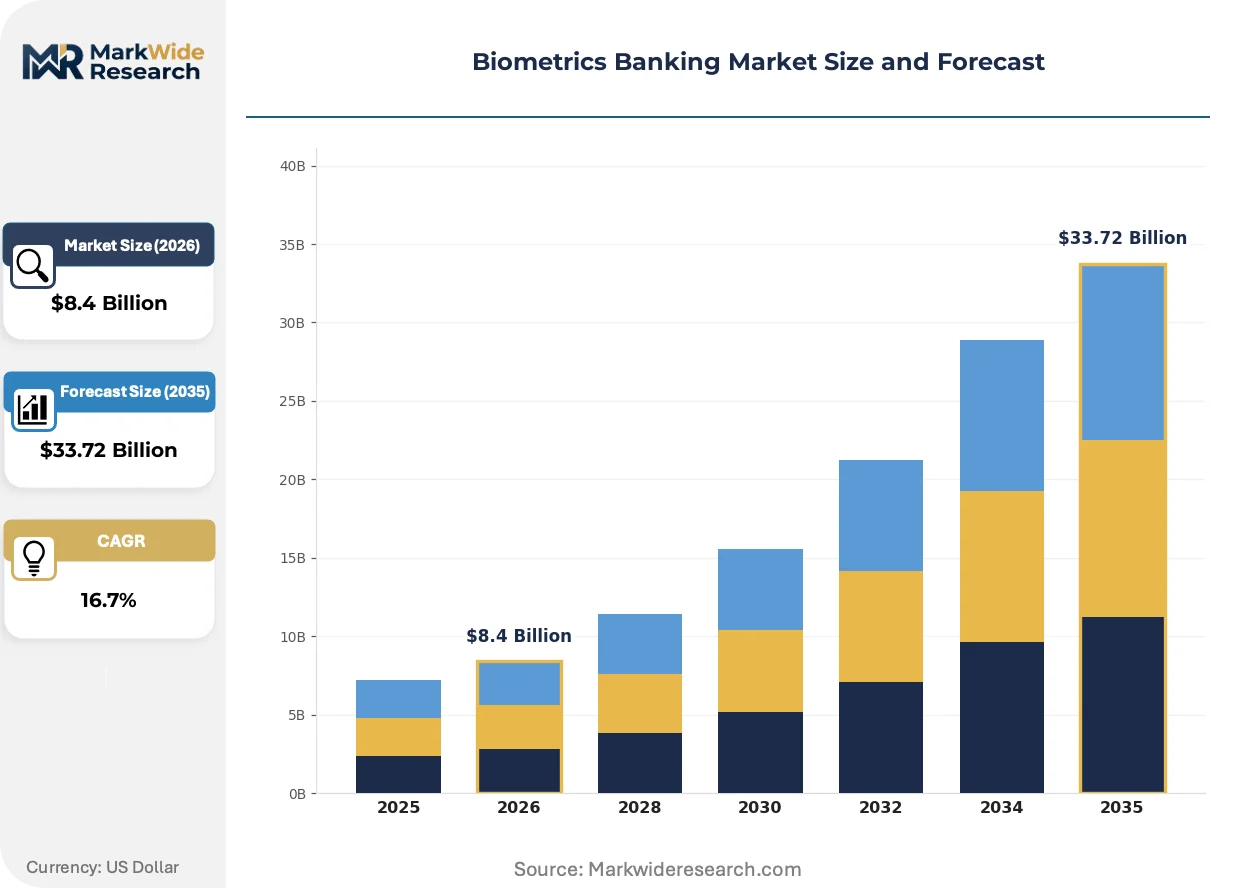
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $33.72 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Authentication Type: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition, Palm Vein Recognition, Behavioral Biometrics Application: Customer Onboarding, Transaction Authorization, Fraud Detection, Access Control, Account Management, Loan Processing End User: Retail Banks, Credit Unions, Investment Firms, Payment Processors, Asset Management Firms, Microfinance Institutions Deployment Model: Cloud-Based, On-Premises, Hybrid, Hosted Services, API Integration, Mobile SDKs |
| Companies Covered | NEC Corporation, IDEMIA, Thales Group, Synaptics Incorporated, IDEX Biometrics ASA, Infineon Technologies AG, Diebold Nixdorf, Visa, JPMorgan Chase & Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometrics Banking Market Trends and Innovations
Authentication architectures are fragmenting across edge, cloud, and hybrid deployments as banks balance latency requirements against privacy compliance, creating divergent technology roadmaps across regulatory jurisdictions.
Multimodal biometric fusion is hybridizing fingerprint, facial, and behavioral signals into single authentication scores. Tier-1 retail banks in the United States and Singapore are deploying these systems for real-time transaction authorization above $10,000 thresholds. The technology is hybridizing security and user experience design, collapsing multiple authentication steps into seamless customer journeys while maintaining sub-0.001% false acceptance rates.
The EU AI Act's risk-based classification system imposes mandatory conformity assessments on biometric identification systems deployed by European banks. High-risk applications require human oversight mechanisms and algorithmic impact documentation that reshape product development cycles. French and German regulators are interpreting these provisions most strictly, forcing vendors to maintain parallel product variants for European and non-European deployments.
Customer tolerance for authentication friction is compressing switching thresholds between competing financial institutions. Neobanks leveraging single-tap facial recognition are capturing deposit flows from incumbent banks requiring multi-step password and SMS verification. This behavioral shift is most visible in Brazil and Indonesia, where super-app embedded finance providers treat authentication speed as a primary customer acquisition lever.
Biometrics Banking Market Segmentation
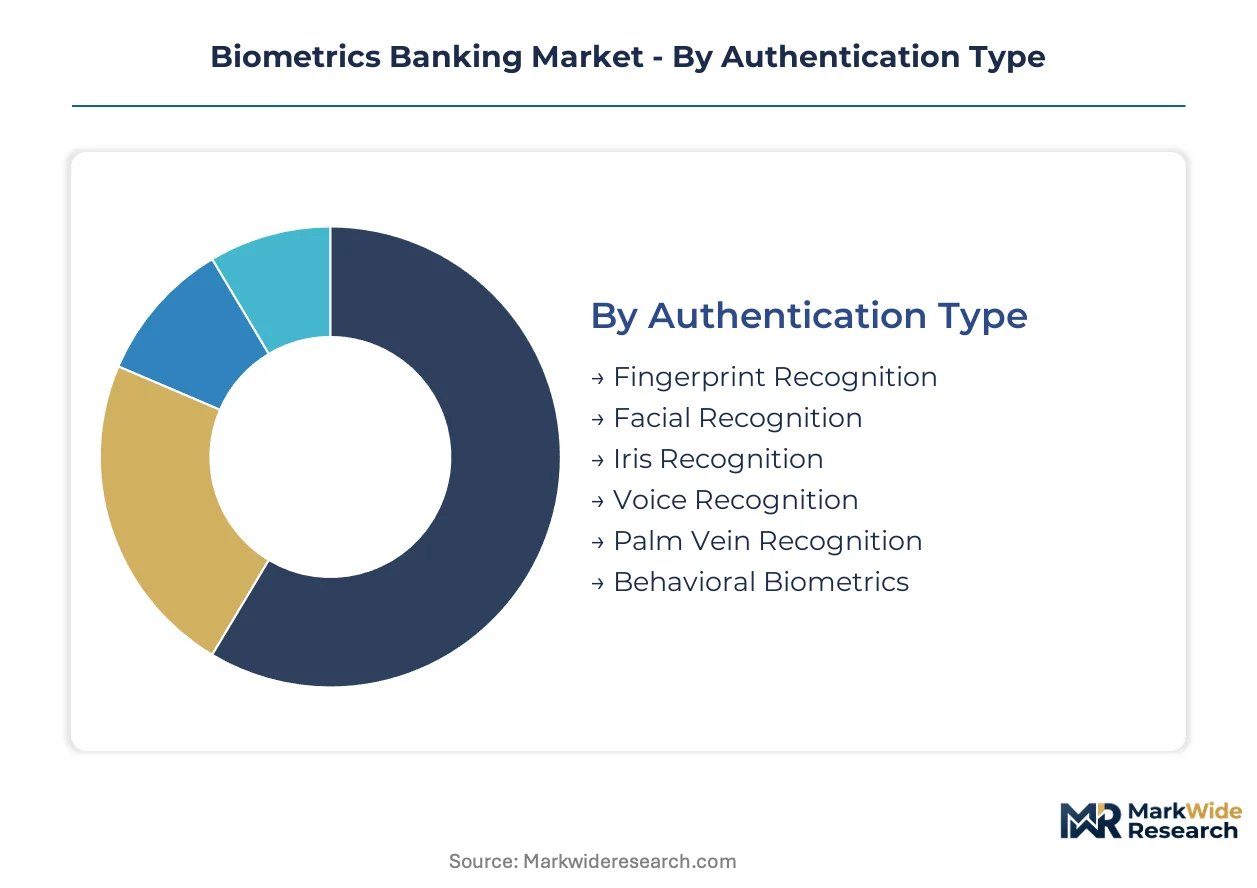
Segmentation in biometrics banking reveals divergent replacement cycles across authentication modalities, with behavioral systems refreshing every 18-24 months while fingerprint hardware persists for 7-10 years. Understanding these temporal patterns helps vendors align R&D pipelines with revenue predictability and helps banks plan infrastructure migration.
Authentication Type:
Replacement cycles vary dramatically across biometric modalities, with behavioral algorithms turning over fastest due to continuous model retraining demands while physical sensors depreciate slowly.
- Fingerprint Recognition:Capacitive and ultrasonic sensors capture ridge patterns with false acceptance rates below 0.001%. Demand concentrates in the United States where major retail banks deploy fingerprint-enabled ATMs and mobile banking apps to reduce card-not-present fraud losses.
- Behavioral Biometrics:Keystroke dynamics, mouse movement patterns, and touchscreen pressure analysis enable continuous authentication without explicit user action. Financial institutions in Singapore and Brazil integrate these systems into mobile banking workflows to reduce step-up authentication interruptions.
- Facial Recognition:3D structured light and time-of-flight cameras authenticate customers through liveness-validated facial geometry.
- Iris Recognition:Near-infrared imaging of iris patterns delivers the lowest false acceptance rates among physiological biometrics.
- Voice Recognition:Spectral analysis of vocal characteristics enables hands-free authentication for telephone banking and smart speaker integrations.
- Palm Vein Recognition:Near-infrared transillumination maps subcutaneous vein patterns for contactless authentication.
Fingerprint recognition anchors the volume base while behavioral biometrics gains share at the steepest rate.
Application:
Cost tiers stratify sharply across use cases, with fraud detection commanding premium algorithm licensing fees while account management functions compete on per-seat pricing.
- Transaction Authorization:Real-time biometric verification secures wire transfers, peer-to-peer payments, and high-value purchases above $10,000 thresholds. European banks under PSD2 Strong Customer Authentication mandates deploy multimodal systems combining facial and behavioral signals to satisfy possession-independent factor requirements.
- Fraud Detection:Continuous behavioral monitoring identifies anomalous session patterns indicative of account takeover or synthetic identity attacks. Payment processors in India integrate these capabilities into UPI transaction flows to combat rising digital payment fraud rates.
- Customer Onboarding:Remote identity verification through document authentication and selfie matching streamlines account opening.
- Access Control:Biometric credentials replace physical tokens and passwords for employee and customer entry to banking systems.
- Account Management:Voice and facial authentication secure routine balance inquiries and profile updates.
- Loan Processing:Identity verification and income validation through biometric-linked digital identity networks accelerate credit decisions.
Transaction authorization commands the highest per-deployment value while fraud detection expands most quickly as real-time monitoring becomes standard.
End User:
Procurement sophistication varies dramatically across institutional types, with tier-1 retail banks demanding custom integration while microfinance institutions prioritize off-the-shelf affordability.
- Retail Banks:Full-service commercial and consumer banking operations deploy comprehensive biometric portfolios across channels. JPMorgan Chase and Bank of America in the United States operate multimodal systems spanning facial, voice, and fingerprint authentication for differentiated risk-based access tiers.
- Payment Processors:Visa and Mastercard network participants integrate biometric verification into authorization flows to reduce chargeback liability and comply with emerging authentication standards.
- Credit Unions:Member-owned financial cooperatives adopt cloud-native biometric solutions to compete with larger institutions on digital experience without comparable IT infrastructure.
- Investment Firms:Wealth management and brokerage operations deploy voice and behavioral biometrics to secure high-net-worth client accounts against sophisticated social engineering attacks.
- Asset Management Firms:Institutional investment managers implement biometric access controls for trading systems and sensitive portfolio data.
- Microfinance Institutions:Small-scale lenders serving underbanked populations leverage low-cost fingerprint and voice authentication for rural banking service delivery.
Retail banks anchor the volume base while payment processors gain share at the steepest rate.
Deployment Model:
Margin structures diverge across delivery mechanisms, with cloud-based subscriptions capturing recurring revenue streams while on-premises installations concentrate professional services profitability.
- Cloud-Based:SaaS delivery of biometric verification services enables rapid scaling and automatic algorithm updates without client-side infrastructure investment. European banks under GDPR and EU AI Act constraints increasingly specify edge-processed cloud architectures that eliminate centralized biometric data storage.
- API Integration:RESTful and gRPC interfaces embed biometric capabilities directly into mobile banking applications and core banking systems without dedicated hardware.
- On-Premises:Dedicated hardware and software installations within bank data centers satisfy stringent data residency and security requirements.
- Hybrid:Split processing architectures perform biometric capture on-device with cloud-based template matching and risk scoring.
- Hosted Services:Managed private cloud deployments combine vendor-operated infrastructure with client-dedicated resources.
- Mobile SDKs:Native iOS and Android libraries enable banks to embed biometric capture and liveness detection into proprietary mobile applications.
Cloud-based deployment anchors the volume base while API integration gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biometric banking deployment patterns diverge sharply by jurisdiction. European institutions prioritize privacy-preserving architectures under strict regulatory mandates, while Asian markets emphasize large-scale government-linked identity integration and North American banks optimize for multimodal fraud prevention at scale.
United States
JPMorgan Chase and Bank of America operate multimodal systems combining facial recognition with voice biometrics for high-value wire transfers above $10,000 thresholds. The FFIEC authentication guidance and fragmented state-level biometric privacy laws in Illinois and Texas create compliance complexity that shapes vendor product roadmaps. Silicon Valley fintech clusters and New York financial centers drive continuous authentication protocol development for real-time fraud detection.
Germany
Thales Group anchors European banking security infrastructure with hardware security modules and biometric authentication middleware serving major retail banks. The EU AI Act's high-risk classification system imposes mandatory conformity assessments and human oversight mechanisms that extend product development cycles. Frankfurt's financial district and Munich's technology corridor concentrate demand for edge-processed cloud architectures that eliminate centralized biometric storage under GDPR constraints.
India
The RBI's digital payment push and Aadhaar-linked financial inclusion programs create demand for low-cost biometric POS terminals and voice-authenticated rural banking services. National biometric identity infrastructure enables rapid deployment across microfinance institutions serving underbanked populations. Mumbai's financial center and Bangalore's technology hub drive innovation in UPI-integrated behavioral biometrics for real-time payment fraud detection.
Singapore
Tier-1 retail banks deploy multimodal biometric fusion systems for real-time transaction authorization, collapsing multiple authentication steps into seamless customer journeys. The Monetary Authority of Singapore's technology risk management guidelines encourage adoption of liveness-validated facial geometry and continuous behavioral monitoring. The city-state's position as ASEAN financial gateway concentrates regional headquarters for biometric vendors serving Southeast Asian expansion.
Brazil
Super-app embedded finance providers treat authentication speed as a primary customer acquisition lever, capturing deposit flows from incumbent banks through single-tap facial recognition. Neobank competition compresses customer tolerance for authentication friction, driving replacement cycles for static password systems. São Paulo's fintech corridor leads deployment of behavioral biometrics analyzing keystroke dynamics and touchscreen pressure for continuous authentication without explicit user action.
Biometrics Banking Market Competitive Landscape
Capability concentration sits with algorithm specialists; scale advantage sits with integrated platform vendors. The vendor base stratifies across three tiers: government-linked system integrators with biometric portfolios, semiconductor firms with sensor-to-software stacks, and cloud-native authentication pure-plays. Strategic moves center on algorithm licensing transitions from perpetual sales to recurring subscription models, and edge-computing partnerships that localize biometric processing to satisfy data residency mandates.
Within the government-linked integration tier, NEC Corporation and IDEMIA occupy positions exemplifying divergent geographic anchoring—Tokyo-based NEC leverages algorithm dominance across Asian banking deployments, while Paris-based IDEMIA sustains presence through credential management systems spanning physical and digital identity layers. Thales Group represents the European hardware-anchored archetype, with French origins and diversified security infrastructure positioning. These three entities illustrate how vendor origin shapes regulatory compliance specialization and regional market penetration patterns.
| Leading Market Players |
|---|
| NEC Corporation |
| IDEMIA |
| Thales Group |
| Synaptics Incorporated |
| IDEX Biometrics ASA |
| Infineon Technologies AG |
| Diebold Nixdorf |
| Visa |
| JPMorgan Chase & Co |
| Others |
Pricing and Supply Chain Analysis
TSMC's 28nm foundry capacity in Taiwan anchors sensor fabrication costs for fingerprint and facial recognition hardware, concentrating margin capture with semiconductor vendors while algorithm providers downstream extract recurring SaaS revenue from banks seeking cloud-native authentication flexibility.
Pricing Analysis
Long-term algorithm licensing contracts dominate enterprise banking procurement, displacing perpetual software sales as vendors pursue recurring revenue. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—EU AI Act-compliant liveness detection commands premium positioning against basic fingerprint matching. Cost compression in hardware sensors is intensifying because capacitive fingerprint module commoditization accelerates. Microfinance institutions exhibit highest price sensitivity, prioritizing low-cost voice authentication over multimodal systems.
Supply Chain Analysis
Extended payment terms from European tier-1 banks now stretch to 90-120 days, forcing biometric vendors to secure supply-chain finance facilities to bridge working capital gaps. Hardware assembly concentrates in China, Taiwan, and Vietnam, while algorithm development clusters in the United States, Israel, and France. Advanced CMOS image sensors and near-infrared emitters draw from concentrated optoelectronics suppliers. Single-source vulnerability in 3D structured light camera modules creates exposure to export control restrictions. Distribution runs through direct enterprise sales teams for major banks, with channel partners serving mid-tier credit unions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometrics banking is crossing a platform-economics inflection where API-first authentication services displace point solutions, with open banking interoperability standards in Europe and India reshaping competitive boundaries around ecosystem integration rather than standalone capability.
For Market Incumbents: Harden algorithm portfolios against deepfake-spoofing threats through continuous liveness detection R&D investment, while consolidating channel control over cloud-native deployment partnerships to defend against API-native challengers eroding middleware margins. For New Entrants and Emerging Players: Build out voice-authenticated rural banking services in India and low-cost biometric POS terminals for microfinance institutions, where Aadhaar-linked infrastructure reduces customer acquisition friction and incumbent presence remains underdeveloped. For Investors and Strategic Acquirers: Capital is best deployed toward edge-computing biometric specialists with GDPR-compliant on-device processing architectures, as regulatory divergence between European privacy frameworks and security-driven U.S. standards creates sustained demand for parallel product variants. Watch for EU AI Act enforcement intensity in France and Germany as the signal indicating acceleration in compliance-driven replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Licensing Transition to SaaS | Recurring revenue models align vendor incentives with bank operational flexibility requirements. |
| Edge-Computing Partnership Formation | On-device processing satisfies GDPR data residency mandates without cloud infrastructure dependency. |
| Multimodal Fusion Platform Development | Single authentication scores combining facial, voice, and behavioral signals reduce customer friction. |
| Anti-Spoofing R&D Investment | Liveness detection advancement counters deepfake-synthesized voice and hyper-realistic mask threats. |
| Open Banking API Integration | PSD2 Strong Customer Authentication compliance expands addressable market for behavioral biometrics. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with bank CTOs, authentication product managers, biometric algorithm engineers, and regulatory compliance officers, validated against secondary sources including SEC filings, RBI digital payment directives, EU AI Act implementation guidance, and FFIEC authentication guidance documents, with bottom-up deployment sizing triangulated against top-down market aggregation.
Calibration against historical authentication system replacement cycles and bank IT spending patterns shaped the analytical framework across the projection horizon, modeling segmentation by authentication type, deployment model, application use case, and end-user institution tier, with CAGRs derived from algorithm adoption velocity and hardware depreciation schedules, incorporating Aadhaar-linked financial inclusion program expansion and PSD2 compliance deadlines as industry-specific demand drivers.
Stress conditions across TSMC foundry allocation constraints, EU AI Act enforcement variance, and deepfake spoofing advancement rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation timelines and bank technology refresh cycles. Macroeconomic contraction, biometric privacy litigation expansion, or quantum-resistant cryptography breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Global Multifactor Authentication Market
Biometrics & Identity Management
Biometric Lockers Market
Biometrics & Identity Management
Identity Theft Protection Services Market
Biometrics & Identity Management
Global Phone Based Authentication Solution Market
Biometrics & Identity Management
Spain Mobile Biometrics Market
Biometrics & Identity Management
Global Authentication Services Market
Biometrics & Identity Management
GCC Biometrics Market
Biometrics & Identity Management
Europe Government and Security Biometrics Market
Biometrics & Identity Management
Hand Geometry Biometrics Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
Asia Pacific Biometrics in Government Market
Biometrics & Identity Management
Flash Calling Authentication Market
Biometrics & Identity Management
Iris Recognition Market
Biometrics & Identity Management
Automated Fingerprint Identification Systems (AFIS) Market
Biometrics & Identity Management
Passive Authentication Market
Biometrics & Identity Management
Biometric ATM Market