
 Spain Mobile Biometrics Market | 2026-2036
Spain Mobile Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Mobile Biometrics Market Insights
A shift from single-source biometric component procurement to multi-vendor sourcing strategies is pivoting how Spanish enterprises build mobile authentication stacks. FacePhi Biometria SA leverages its domestic R&D base to anchor facial recognition deployments across Iberian financial institutions. IDEMIA competes through its broad credential portfolio, while Thales Group extends its defense-grade security expertise into civilian mobile applications.
Spain mobile biometrics encompasses hardware sensors and software algorithms that capture, process, and match physiological or behavioral traits against enrolled templates, typically operating with false acceptance rates below 0.001% in enterprise deployments. The technology serves to replace or supplement password-based authentication in high-risk transactions. Fingerprint recognition occupies the largest installed base due to mature sensor economics and consumer familiarity, though facial recognition is gaining fastest among financial services end users seeking contactless payment flows. Payment authentication applications command premium pricing compared to time tracking, where commoditized solutions dominate.
Spain's data protection authority enforces GDPR-mandated biometric consent protocols, while Banco de España supervises payment authentication standards under PSD2 strong customer authentication rules. The European Commission's eIDAS 2.0 framework will force cross-border interoperability testing for wallet-integrated biometrics. Stakeholders must decide whether to pursue eIDAS certification now or risk exclusion from EU public-sector procurement pipelines.
Market Dynamics
Spain's mobile biometrics sector is pivoting on the tension between PSD2-mandated strong customer authentication and the European Commission's eIDAS 2.0 interoperability deadlines, forcing financial institutions to rebuild authentication stacks before cross-border wallet integration becomes compulsory.
Growth Catalysts
- PSD2 Strong Customer Authentication:Banco de España enforcement drives fingerprint and facial recognition deployment across retail banking apps, replacing static passwords with biometric transaction signing.
- EU Digital Identity Wallet:The European Commission's framework mandates wallet-integrated biometrics for public-sector access, creating procurement pull from Spanish government digital service portals.
- Madrid-Barcelona fintech clustering:Banking headquarters concentration in these cities concentrates enterprise demand and accelerates vendor proof-of-concept cycles.
Market Restraints
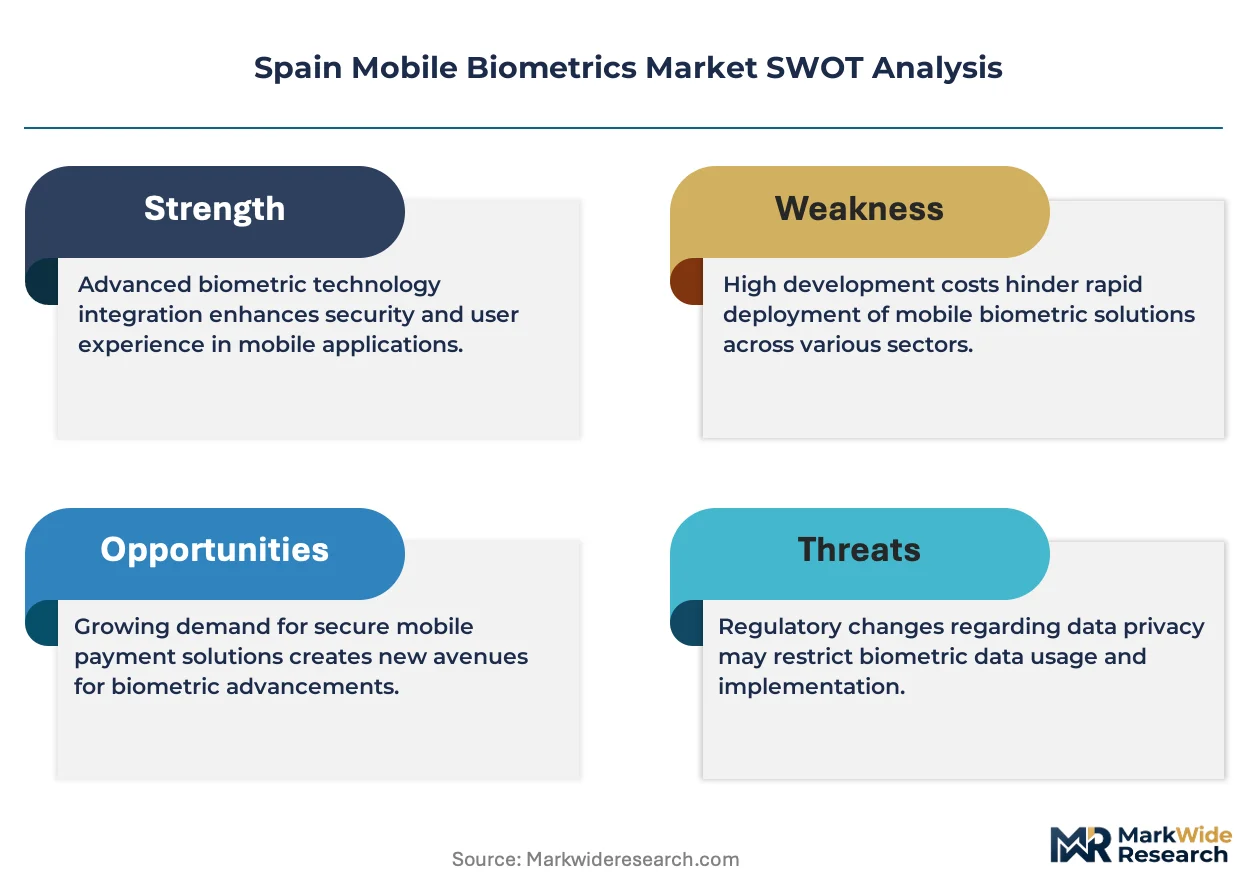
- GDPR biometric consent friction:Spain's data protection authority requires explicit opt-in for each biometric template enrollment, lengthening customer onboarding and increasing abandonment.
- Sensor supply concentration:Capacitive fingerprint module production concentrates in East Asian foundries, exposing Spanish integrators to currency volatility and shipping delays.
- Liveness detection technical gaps:Presentation attack detection for facial recognition remains vulnerable to deepfake injection, limiting high-value transaction ceilings.
Strategic Opportunities
- Andalusia and Valencia underpenetration:Regional banks outside Madrid-Barcelona corridors lag in biometric deployment, offering first-mover expansion for authentication vendors.
- Behavioral biometrics convergence:Keystroke dynamics and gait analysis layered with physiological traits creates continuous authentication for mobile banking sessions.
- Healthcare access applications:Spain's national health system digitalization opens prescription authentication and patient portal access as new biometric use cases.
Industry Challenges
- eIDAS certification timeline compression:Laboratories accredited for Common Criteria evaluation face 12-18 month backlogs, risking exclusion from EU public procurement.
- Legacy core banking integration:Spanish cajas and regional banks operate on decades-old COBOL systems, requiring expensive middleware to bridge biometric APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Mobile Biometrics Market |
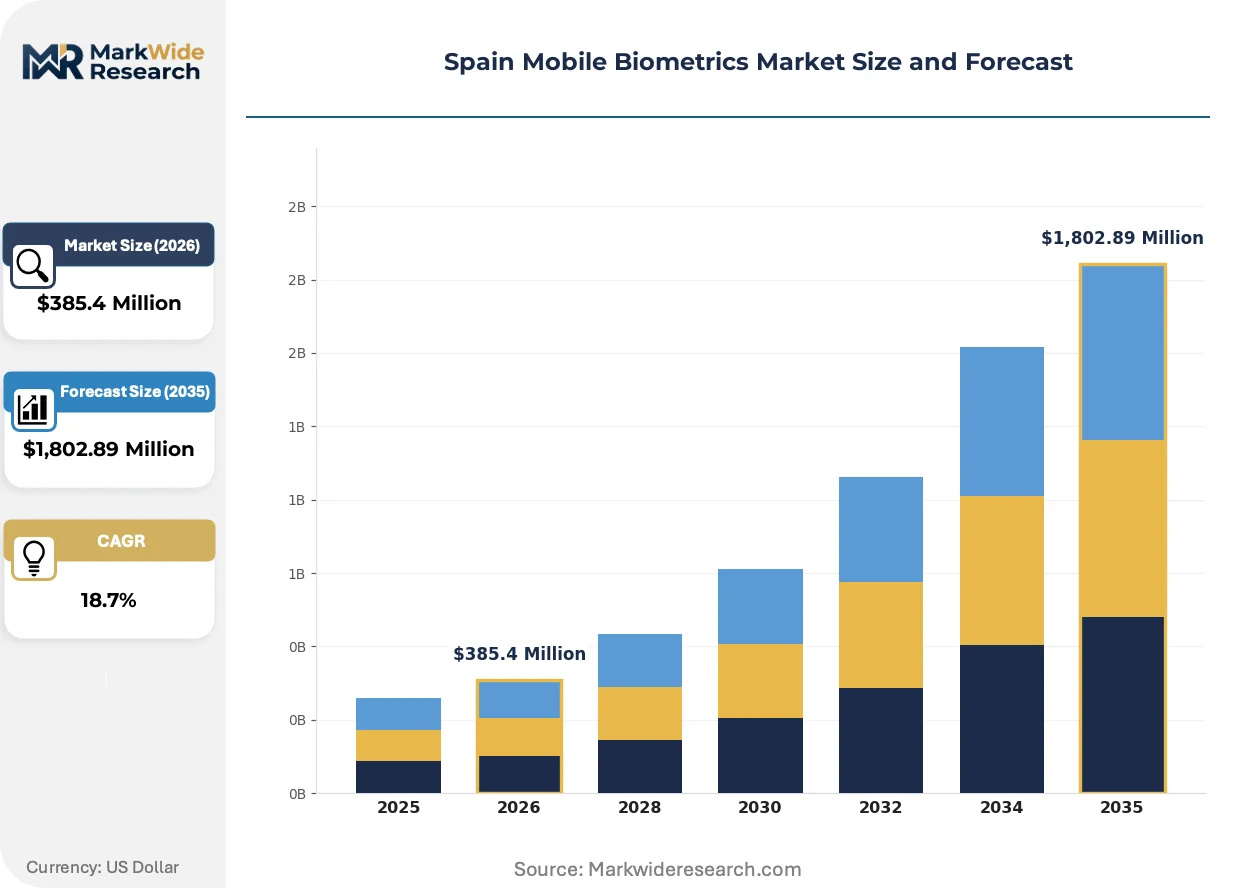
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition End User: Government, Financial Services, Healthcare, Retail Application: Access Control, Payment Authentication, Identity Verification, Time Tracking Deployment: Cloud, On-Premises, Hybrid, Device-Based |
| Companies Covered | FacePhi Biometria SA, Herta Security, NEC Corporation, IDEMIA, Thales Group, Samsung Electronics, Apple Inc, Fingerprint Cards AB, Qualcomm Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Mobile Biometrics Market Trends and Innovations
Facial recognition is displacing fingerprint sensors in Spanish payment authentication as contactless transaction volumes surge and liveness detection algorithms mature against presentation attacks.
Edge-based biometric processing is decentralizing authentication decision-making from cloud servers to secure enclaves within smartphone chipsets. CaixaBank and BBVA are piloting on-device template matching for high-value transfers. This architecture compresses latency below 200 milliseconds while eliminating network-dependent attack surfaces during transaction authorization.
The EU AI Act's risk classification framework categorizes remote biometric identification as high-risk, forcing Spanish fintechs to implement human-in-the-loop review for account recovery workflows. Compliance costs are diverting R&D budgets from algorithm accuracy toward audit trail infrastructure. Payment processors are responding by pre-certifying SDKs against harmonized standards to accelerate client deployments.
Spanish corporate buyers are consolidating vendor relationships from point-solution procurement to platform contracts spanning enrollment, matching, and lifecycle management. Large banks now demand unified biometric stacks rather than assembling components from separate fingerprint and facial recognition suppliers. Procurement teams in Barcelona's fintech cluster are leading this consolidation, using multi-year agreements to lock pricing and secure roadmap influence.
Spain Mobile Biometrics Market Segmentation
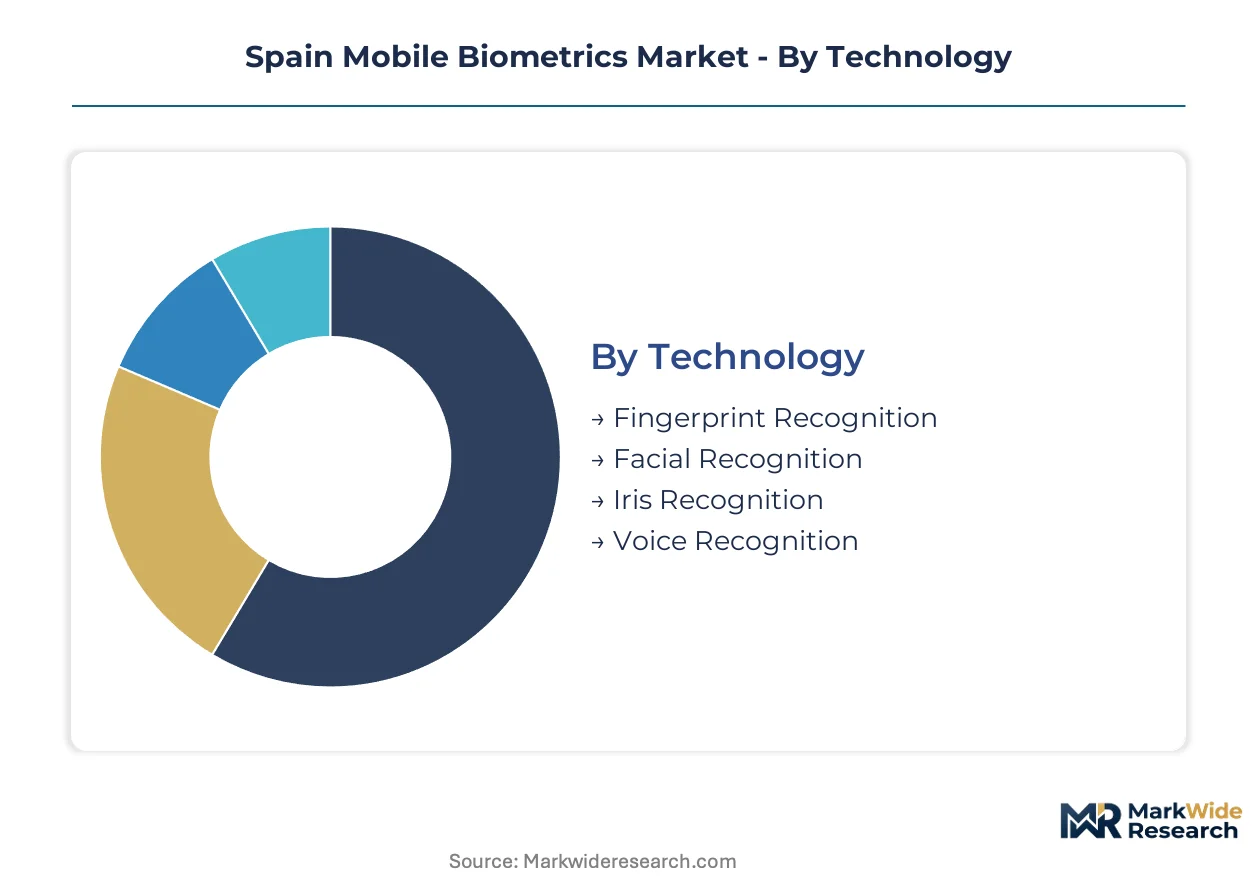
Biometric procurement patterns in Spain reflect distinct upgrade cycles across authentication technologies and deployment architectures. Financial institutions prioritize technology refresh timelines that align with PSD2 compliance deadlines and eIDAS 2.0 interoperability mandates.
Technology:
Upgrade cycles vary dramatically by modality maturity, with capacitive fingerprint sensors facing replacement pressure from contactless facial recognition systems.
- Facial Recognition:3D structured light and time-of-flight sensors enable liveness detection compliant with Banco de España payment authentication standards. BBVA and CaixaBank deployments in Madrid concentrate demand for high-value transaction ceilings above 500 euros.
- Fingerprint Recognition:Capacitive and ultrasonic sensors dominate installed base economics with sub-5-dollar module pricing at volume. Barcelona fintech procurement favors under-display ultrasonic variants for premium mobile banking applications.
- Iris Recognition:Near-infrared imaging systems serve high-security government portal access with GDPR-mandated consent workflows.
- Voice Recognition:Speaker verification algorithms deploy in call center authentication for regional banks lacking facial recognition infrastructure.
Volume placements concentrate in fingerprint recognition; the faster expansion belongs to facial recognition.
End User:
Customer procurement sophistication spans from compliance-driven public sector tenders to margin-sensitive retail pilots.
- Financial Services:Tier-one banks demand Common Criteria-certified SDKs with eIDAS pre-certification to avoid laboratory backlog delays. Madrid headquarters procurement teams consolidate vendor relationships into multi-year platform contracts.
- Government:National digital ID infrastructure projects under the EU Digital Identity Wallet framework specify cross-border interoperability testing. Spanish government digital service portals drive wallet-integrated biometric specifications.
- Healthcare:Prescription authentication and patient portal access emerge as new use cases under national health system digitalization.
- Retail:Loyalty program authentication and employee time tracking deploy commoditized solutions with minimal liveness detection requirements.
Financial services capture the largest procurement volumes; healthcare access applications are climbing the fastest.
Application:
Authentication value varies by transaction risk tier, with payment flows commanding premium pricing against workforce management utilities.
- Payment Authentication:PSD2 strong customer authentication mandates biometric transaction signing for remote payments above 30 euros. Spanish retail banking apps replace static passwords with fingerprint and facial recognition enrollment.
- Identity Verification:Account onboarding and recovery workflows face EU AI Act high-risk classification requiring human-in-the-loop review infrastructure.
- Access Control:Enterprise mobile device management and building entry systems integrate biometric factors with existing credential portfolios.
- Time Tracking:Commoditized facial recognition solutions dominate workforce management with minimal security certification requirements.
Payment authentication generates the highest margins; identity verification is gaining share fastest under regulatory pressure.
Deployment:
Architecture decisions balance latency requirements against data residency constraints under GDPR territoriality rules.
- Device-Based:Secure enclave processing within smartphone chipsets eliminates network attack surfaces during transaction authorization. On-device template matching compresses latency below 200 milliseconds for high-value transfers.
- Cloud:Centralized biometric databases serve multi-channel authentication with economies of scale in template storage and algorithm updates.
- Hybrid:Edge-cloud split architectures process liveness detection locally while delegating template matching to sovereign data centers.
- On-Premises:Air-gapped deployments satisfy defense and critical infrastructure sectors with strict data localization mandates.
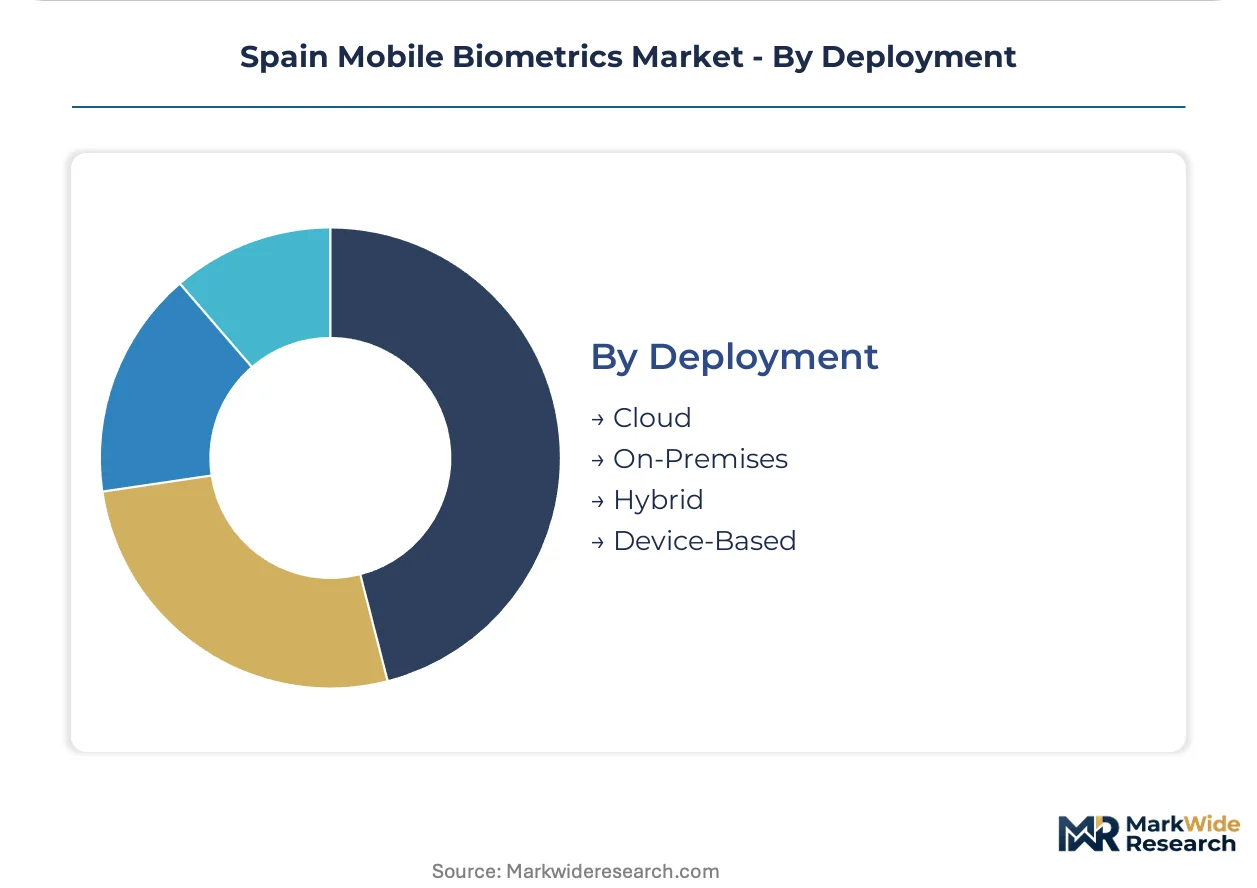
Device-based architectures lead current procurement; hybrid deployments are expanding most quickly as banks navigate GDPR territoriality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundries in East Asia supply the capacitive fingerprint sensors and 3D structured light modules that Spanish integrators embed into mobile authentication stacks. Madrid and Barcelona concentrate procurement decisions for the Iberian market. Regional deployment patterns diverge sharply between compliance-driven financial hubs and underpenetrated secondary cities.
Madrid
Headquarters of BBVA, CaixaBank, and Santander drive enterprise demand for Common Criteria-certified biometric SDKs. Banco de España's PSD2 enforcement mandates strong customer authentication for remote payments above 30 euros. The capital's fintech procurement teams consolidate vendor relationships into multi-year platform contracts spanning enrollment through lifecycle management.
Catalonia
Barcelona's fintech cluster accelerates proof-of-concept cycles for facial recognition and behavioral biometrics. The regional government aligns digital service portals with EU Digital Identity Wallet specifications. Procurement teams here lead vendor consolidation trends, demanding unified biometric stacks rather than assembled point solutions.
Basque Country
Industrial automation and defense technology heritage feeds specialized demand for iris recognition and high-security access control. Local data centers pilot hybrid edge-cloud architectures to satisfy GDPR territoriality constraints. Bilbao-based system integrators serve critical infrastructure sectors with air-gapped deployment expertise.
Andalusia
Regional banks outside Madrid-Barcelona corridors lag in biometric deployment, creating first-mover expansion opportunities for authentication vendors. Seville and Malaga healthcare networks pilot prescription authentication under national health system digitalization. The Junta de Andalucía's digital transformation programs specify wallet-integrated biometric access for public services.
Valencia
Port logistics and maritime trade drive workforce management applications with commoditized facial recognition for time tracking. The regional innovation hub supports behavioral biometrics startups developing keystroke dynamics for continuous authentication. Valencia's smaller banking sector offers lower compliance urgency but rising PSD2 adoption timelines.
Spain Mobile Biometrics Market Competitive Landscape
Global majors compete with regional champions across certification depth and compliance velocity. The vendor base organizes around three tiers: defense-grade security conglomerates with broad credential portfolios, domestic specialists leveraging proximity to Spanish regulators, and semiconductor platform owners controlling sensor supply. Consolidation pressures intensify as large banks demand unified stacks rather than multi-vendor assembly. Strategic moves center on eIDAS pre-certification racing and multi-year platform contract capture.
Within the domestic specialist tier, FacePhi Biometria SA anchors facial recognition deployments across Iberian financial institutions through its proximity to Madrid and Barcelona procurement centers. IDEMIA and Thales Group represent the defense-grade security archetype, extending credential expertise into civilian mobile applications. These three exemplify the competitive tension between regional compliance intimacy and global certification breadth.
| Leading Market Players |
|---|
| FacePhi Biometria SA |
| Herta Security |
| NEC Corporation |
| IDEMIA |
| Thales Group |
| Samsung Electronics |
| Apple Inc |
| Fingerprint Cards AB |
| Qualcomm Technologies |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between eIDAS-pre-certified biometric stacks and uncertified commodity SDKs splits pricing power along compliance capability lines, with premium tiers bundling laboratory validation and audit trail infrastructure while economy offerings strip warranty coverage to compete on per-seat licensing alone. Spanish financial institutions absorb 40-60% cost premiums for Common Criteria-certified components, yet procurement teams in Barcelona's fintech cluster increasingly demand multi-year platform contracts that lock pricing across enrollment, matching, and lifecycle management modules. This bifurcation feeds directly into supply chain configuration: vendors with captive certification pipelines command tier-one placement at BBVA and Santander, while uncertified suppliers serve regional cajas through distributor channels with minimal service obligations.
Pricing Analysis
Warranty bundling distinguishes vendor tiers, with premium contracts incorporating 24-month algorithm update guarantees and incident response SLAs against stripped-down SDK licensing that excludes liveness detection maintenance. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with Common Criteria EAL4+ products commanding 2.5-3x multiples over uncertified alternatives. Pricing pressure stems from procurement consolidation, as Madrid headquarters teams reduce vendor counts from 6-8 point solutions to 2-3 platform providers. Regional banks outside capital corridors exhibit highest price sensitivity, deferring facial recognition deployment until fingerprint sensor amortization cycles complete.
Supply Chain Analysis
Dual-sourcing mandates from Banco de España-supervised institutions require Spanish integrators to qualify second-source suppliers for capacitive fingerprint modules and 3D structured light cameras, compressing procurement timelines but diluting volume discounts. Component supply draws from Taiwan and South Korea for CMOS image sensors, China for capacitive fingerprint ASICs, and Germany for precision optics in iris recognition systems. Single-source vulnerability concentrates in East Asian foundries producing secure enclave processors, exposing authentication stacks to shipping delays and currency volatility. Distribution runs through Madrid-based system integrators serving tier-one banks, with Barcelona distributors handling mid-market fintech procurement and Seville-based channels covering Andalusian regional deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's mobile biometrics market functions as a cost-of-compliance arena where eIDAS 2.0 certification timelines erect barrier-to-entry moats favoring laboratories with Common Criteria evaluation capacity and vendors with pre-certified SDK portfolios.
For Market Incumbents: Deepen eIDAS certification pipelines through accredited laboratory partnerships to defend against emerging entrants lacking evaluation backlog access, while extending platform contracts with Madrid headquarters procurement teams to lock multi-year pricing before laboratory capacity constraints ease. Threat substitution from behavioral biometrics startups in Barcelona's innovation cluster demands R&D investment in continuous authentication layers that complement physiological trait matching. For New Entrants and Emerging Players: Begin with Andalusian and Valencian regional banks where PSD2 compliance urgency lags Madrid-Barcelona corridors, offering hybrid edge-cloud architectures that address GDPR territoriality without requiring full eIDAS pre-certification upfront. White-space concentrates in healthcare prescription authentication under national health system digitalization, where liveness detection requirements remain undefined and first-mover SDK integration secures pilot placement. For Investors and Strategic Acquirers: Re-rating potential sits with domestic specialists possessing accredited laboratory relationships and existing Banco de España procurement relationships given eIDAS 2.0 interoperability deadlines compressing vendor selection windows. Long-term viability favors platform-scale players over point-solution vendors as Spanish corporate buyers consolidate authentication stacks. Signal to watch: laboratory accreditation expansion announcements that alleviate 12-18 month Common Criteria evaluation backlogs and unlock public-sector procurement access for previously excluded vendors.| Strategic Initiative | Industry Significance |
|---|---|
| eIDAS Pre-Certification Investment | Common Criteria EAL4+ evaluation unlocks BBVA and Santander procurement pipelines before interoperability deadlines. |
| Multi-Year Platform Contract Capture | Madrid headquarters teams consolidate vendor relationships spanning enrollment through lifecycle management modules. |
| Behavioral Biometrics Layer Development | Keystroke dynamics and gait analysis integration addresses EU AI Act high-risk classification for continuous authentication. |
| Andalusian Regional Bank Expansion | Seville and Malaga healthcare networks pilot prescription authentication under national digitalization mandates. |
| Hybrid Edge-Cloud Architecture Deployment | GDPR territoriality compliance drives procurement of split liveness detection and template matching configurations. |
Research Methodology
Document review covered Banco de España PSD2 implementation guidelines, EU Digital Identity Wallet framework specifications, and AEPD biometric consent enforcement records, complemented by interviews with chief information security officers at tier-one Spanish banks, procurement directors at Barcelona fintech clusters, and technical leads at Madrid-based system integrators. Secondary validation drew from eIDAS regulatory filings, Common Criteria evaluation laboratory capacity reports, and SEC disclosures from listed biometric technology suppliers. Bottom-up demand modeling triangulated against top-down market sizing from banking app deployment counts and sensor shipment data.
Market value and volume trajectories across the analysis window reflect segment-level modeling of authentication modality adoption curves, deployment architecture migration patterns, and end-user procurement sophistication tiers. Segmentation dimensions incorporated technology type, end-user vertical, application risk tier, and deployment model complexity. CAGRs derived from logistic diffusion curves fitted to banking sector compliance deadline schedules and healthcare digitalization program timelines, with cross-checks against smartphone secure enclave penetration rates and cloud infrastructure capex disclosures from hyperscale providers.
Underlying measurement precision varies by segment; payment authentication and financial services verticals carry tighter precision than emerging healthcare access applications due to disclosed procurement volumes and regulatory filing transparency. Forecasts reflect assumptions regarding eIDAS 2.0 laboratory accreditation expansion, PSD2 enforcement consistency, and secure enclave processor supply continuity. Deviation in Common Criteria evaluation backlog resolution timelines would shift vendor competitive positioning and public-sector procurement access materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Airport Biometrics Market
Biometrics & Identity Management
Healthcare Biometrics Market
Biometrics & Identity Management
Global Biometric Identification Market
Biometrics & Identity Management
GCC Biometrics Market
Biometrics & Identity Management
Signature Verification Market
Biometrics & Identity Management
Biometric Scan Software Market
Biometrics & Identity Management
Global Biometrics Middleware Market
Biometrics & Identity Management
E-Government Identity Management Market
Biometrics & Identity Management
Mobile Devices User Authentication Services Market
Biometrics & Identity Management
Automated Fingerprint Identification Systems (AFIS) Market
Biometrics & Identity Management
Next Generation Biometric Market
Biometrics & Identity Management
Identity Theft Protection Services Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
Biometric Data Encryption Device Market
Biometrics & Identity Management
Global Behavioral Biometrics Market
Biometrics & Identity Management
IRIS Biometrics Market