
 IRIS Biometrics Market | 2026-2036
IRIS Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
IRIS Biometrics Market Analytics
Modular bundling of iris hardware with cloud analytics platforms is repositioning procurement decisions for enterprise security buyers. Thales leverages its defense-sector heritage to anchor high-assurance government contracts. IDEMIA competes across civil identity and border management with integrated biometric portfolios. NEC Corporation dominates large-scale national ID deployments through manufacturing scale in iris matching engines.
Iris biometrics encompasses automated identity verification through pattern recognition of the trabecular meshwork, typically operating at 700-900 nanometer near-infrared wavelengths to capture stable epigenetic features invisible under visible light. The technology serves critical commercial and industrial purposes in unattended border crossings, financial account recovery, and healthcare patient deduplication where fingerprint or facial methods face accuracy or hygiene constraints. Fixed iris scanners retain the largest installed base in immigration checkpoints, though mobile iris scanners are gaining fastest in field law enforcement and humanitarian registration contexts. Multi-modal biometrics, which fuse iris with fingerprint or face templates, command premium positioning where false acceptance rates must fall below one in a million.
The National Institute of Standards and Technology in the United States sets accuracy benchmarks through ongoing Iris Exchange evaluations that vendors must pass for federal eligibility. The EU AI Act imposes conformity assessments and fundamental rights impact evaluations on biometric identification systems deployed in public spaces. India's UIDAI mandates iris capture alongside fingerprints for Aadhaar enrollment, creating sustained institutional demand. Stakeholders must weigh algorithmic transparency obligations against proprietary matching performance as regulatory scrutiny intensifies across jurisdictions.
Market Dynamics
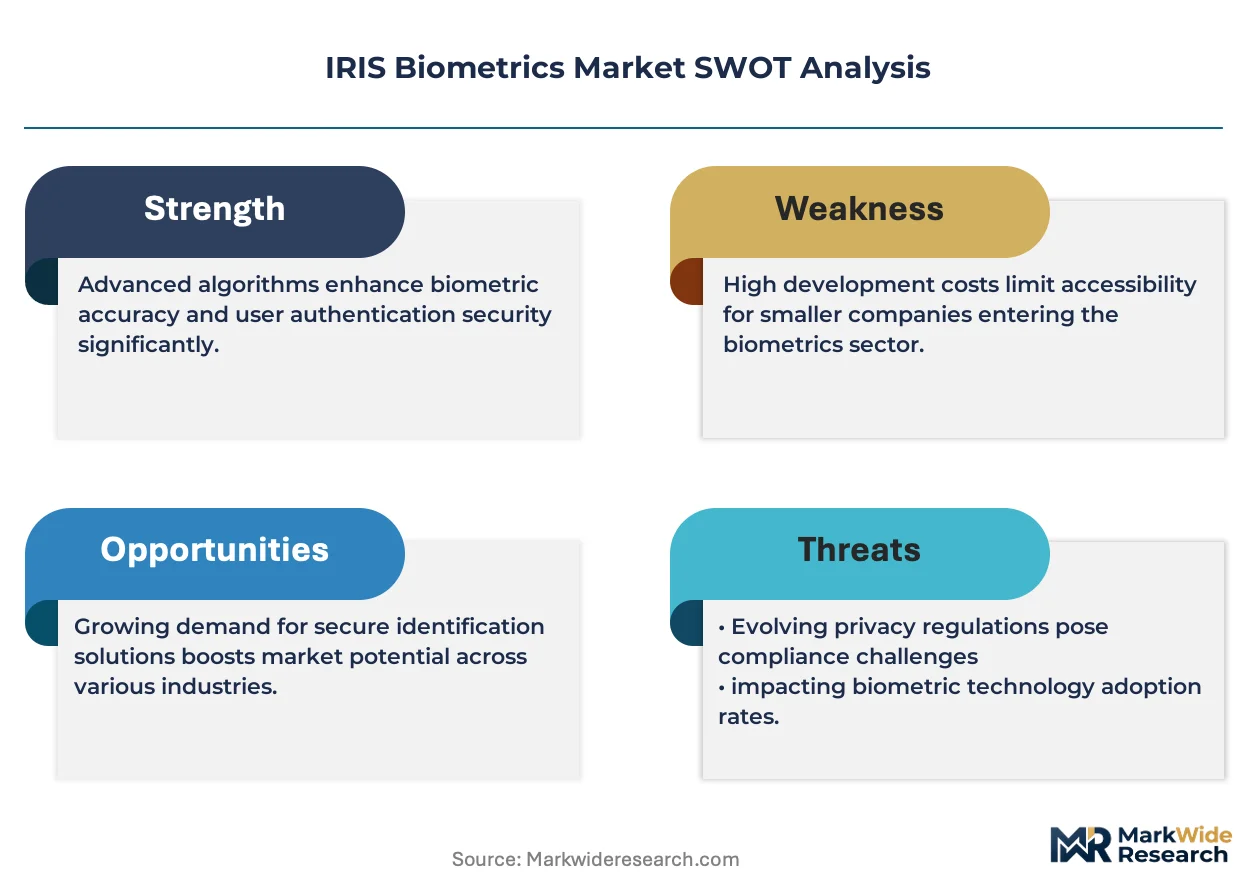
Algorithmic transparency mandates under the EU AI Act are forcing iris biometric vendors to re-architect proprietary matching engines while maintaining performance benchmarks, creating a structural tension between compliance and competitive differentiation.
Growth Catalysts
- Aadhaar Enrollment Mandate:India's UIDAI requires iris capture alongside fingerprints for national identity registration, sustaining institutional procurement of enrollment hardware and matching infrastructure.
- EU AI Act Conformity Pathways:The European Union's algorithmic transparency requirements for biometric identification systems in public spaces are accelerating vendor investment in explainable AI architectures.
- Contactless Authentication Surge:Healthcare patient deduplication and financial account recovery applications favor iris over fingerprint methods due to hygiene constraints and accuracy thresholds.
Market Restraints
- Near-Infrared Sensor Supply Concentration:Specialized 700-900 nanometer imager manufacturing concentrates among Japanese and South Korean component suppliers, creating input vulnerability.
- Template Interoperability Limitations:Proprietary iris encoding formats from major vendors resist standardization, complicating multi-supplier deployments in government identity programs.
- Facial Recognition Substitution:Lower-cost facial authentication systems encroach on access control and consumer device applications where iris accuracy advantages are less critical.
Strategic Opportunities
- Humanitarian Registration Expansion:UNHCR and NGO field operations in refugee camps present underpenetrated demand for ruggedized mobile iris enrollment kits.
- Multi-Modal Biometric Convergence:Fusion of iris templates with fingerprint and facial data commands premium positioning in high-assurance border management and financial KYC applications.
- Cloud Analytics Platform Bundling:Modular integration of iris hardware with subscription-based identity verification services enables recurring revenue models in enterprise physical security.
Industry Challenges
- Algorithmic Audit Expertise Scarcity:Fundamental rights impact assessments under EU AI Act Article 35 require specialized biometric fairness auditors that vendors struggle to source.
- Legacy System Integration Friction:Government immigration checkpoints operate decades-old biometric databases with incompatible template formats, complicating iris system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IRIS Biometrics Market |
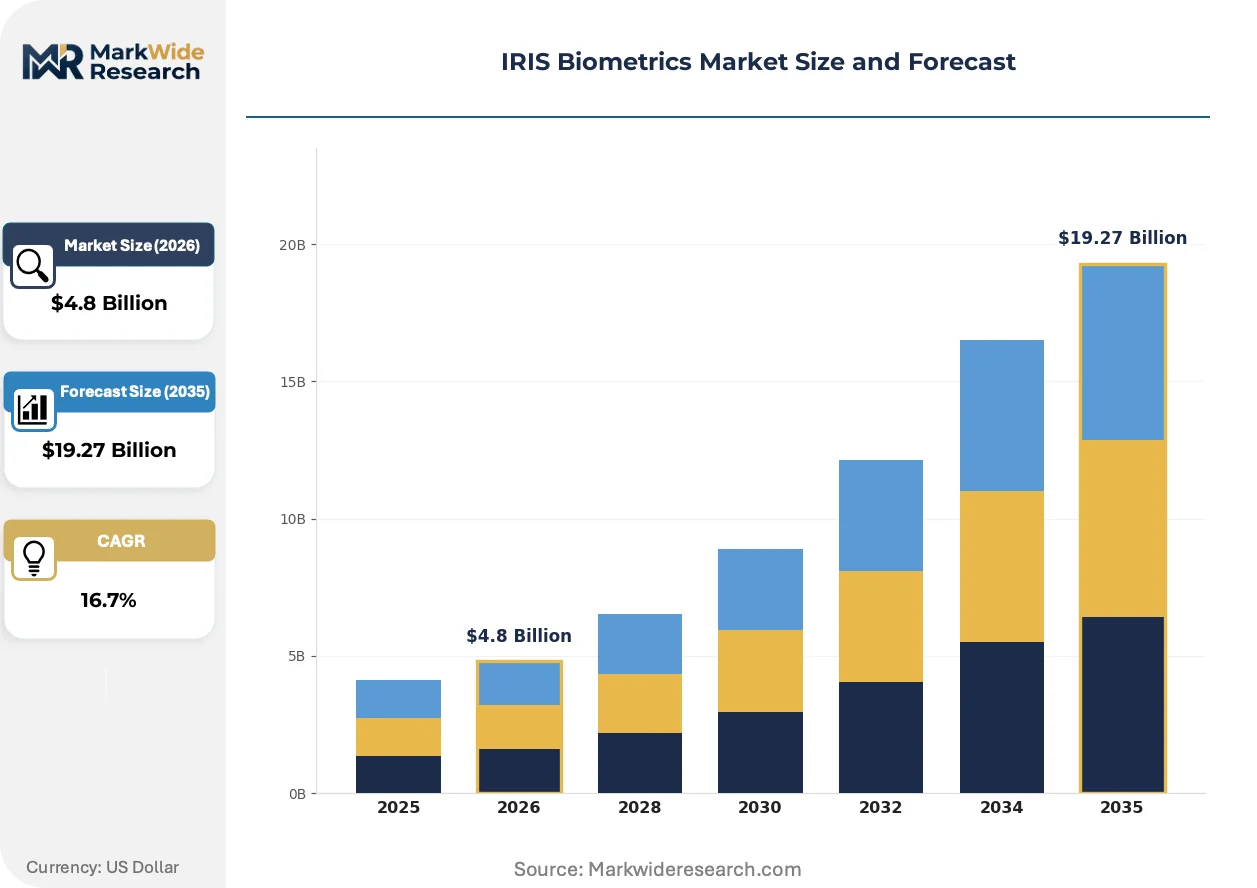
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Iris Scanners, Mobile Iris Scanners, Multi-Modal Biometrics, Embedded Iris Recognition End User: Government, Healthcare, Banking Sector, Security Services Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Mobile Deployments Technology: Active Iris Capture, Passive Iris Capture, Infrared Imaging, AI-Based Recognition |
| Companies Covered | Thales, IDEMIA, NEC Corporation, HID Global, Iris ID Inc., IriTech Inc., EyeLock LLC, IrisGuard Ltd., Princeton Identity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IRIS Biometrics Market Evolving Landscape
Edge-based iris matching is compressing latency requirements for real-time authentication, while regulatory pressure on algorithmic transparency accelerates open-architecture development across vendor ecosystems.
On-device neural processing units are automating iris template extraction and 1:N matching at the capture point, eliminating network dependency for authentication decisions. Border control agencies in Germany and the Netherlands are piloting these systems for unattended e-gates. This distributed architecture is automating the shift from centralized biometric databases toward privacy-preserving verification models.
The EU AI Act's conformity assessment framework for biometric identification systems imposes documented accuracy and bias testing protocols before public-space deployment. Vendors must submit technical documentation to notified bodies demonstrating false acceptance rates below specified thresholds. Large-scale national ID programs across EU member states are delaying procurement timelines to align with these certification requirements.
Enterprise security buyers are unbundling hardware procurement from identity-as-a-service subscriptions, compressing traditional three-year capital expenditure cycles into annual software commitments. Physical security directors at multinational corporations favor consumption-based pricing for iris-enabled access control. This preference shift is most pronounced in North American and Middle Eastern commercial real estate portfolios.
IRIS Biometrics Market Segmentation
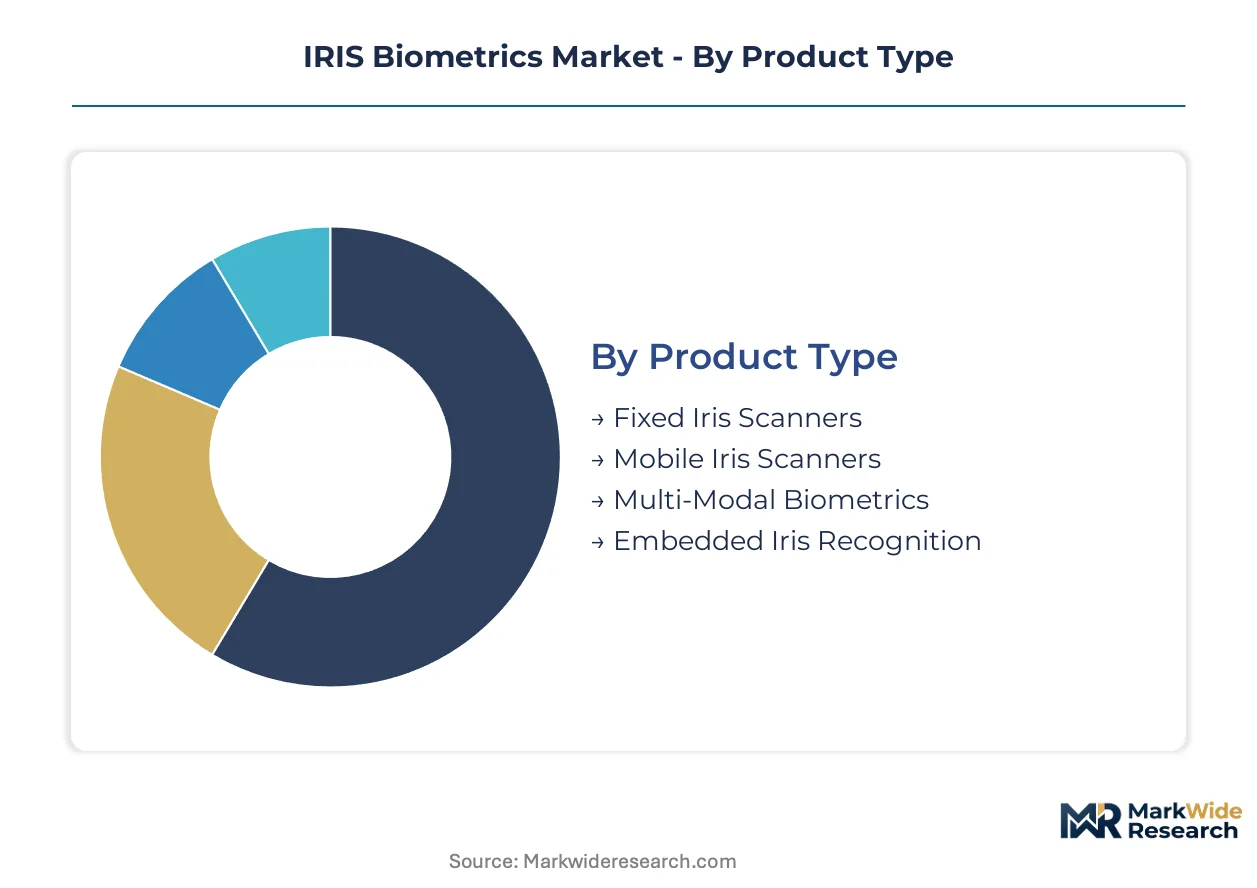
Iris biometrics procurement hinges on certification pathways that vary sharply across product architectures. Government buyers impose distinct compliance burdens on fixed versus mobile form factors, while healthcare and financial end-users prioritize interoperability standards over defense-grade assurance.
Product Type:
EU AI Act conformity assessments and NIST Iris Exchange certification create divergent compliance timelines across hardware categories, with multi-modal systems facing the most complex approval stacks.
- Fixed Iris Scanners:Stationary near-infrared imagers operating at 700-900 nanometer wavelengths dominate immigration checkpoints and high-throughput border crossings. US CBP and German Federal Police sustain procurement of these systems for e-gate deployments, though legacy template format incompatibility complicates upgrade cycles.
- Mobile Iris Scanners:Ruggedized handheld units with battery-powered NIR illumination serve UNHCR refugee registration and field law enforcement. Humanitarian operations in Jordan and Bangladesh drive demand for IP67-rated kits that operate without network connectivity.
- Multi-Modal Biometrics:Fused iris-fingerprint-face systems command premium positioning where false acceptance rates must fall below one in a million.
- Embedded Iris Recognition:Compact NIR modules integrated into smartphones and access control terminals enable consumer-grade authentication.
Fixed Iris Scanners sits at the top of the volume ranking, with Mobile Iris Scanners climbing the fastest.
End User:
Cost tier stratification separates defense-budget deployments from commercial security procurement, with banking sector buyers squeezing hardware margins through subscription bundling.
- Government:National ID programs and border management agencies anchor institutional demand. India's UIDAI mandates iris capture for Aadhaar enrollment, while UAE and Saudi Arabia expand national identity infrastructure with sovereign data residency requirements.
- Healthcare:Patient deduplication systems favor contactless iris over fingerprint methods due to hygiene protocols and latex glove interference. US hospital networks and NHS Trusts in England pilot biometric master patient index integration.
- Banking Sector:Financial account recovery and high-value transaction authentication drive demand for liveness-detection-enabled iris verification.
- Security Services:Private guarding firms and critical infrastructure operators deploy iris access control for facilities requiring multi-factor authentication.
Government captures the largest revenue share, while Healthcare expands most quickly on pandemic-accelerated contactless preferences.
Deployment:
Customer type dictates architecture choice, with multinational corporations favoring consumption-based cloud models and sovereign identity programs insisting on air-gapped on-premises infrastructure.
- Cloud-Based:Subscription identity verification services enable enterprise security buyers to compress three-year capital cycles into annual software commitments. North American commercial real estate portfolios and Middle Eastern smart city projects favor this model.
- On-Premises:Air-gapped biometric databases serve national ID programs with data sovereignty mandates. India's UIDAI and EU member state immigration authorities require localized template storage.
- Hybrid Solutions:Edge-based matching with cloud analytics backup balances latency requirements against centralized audit capabilities.
- Mobile Deployments:Fully disconnected authentication suits field humanitarian registration and remote law enforcement checkpoints.
On-Premises retains the largest installed base, with Cloud-Based gaining share fastest on enterprise preference shifts.
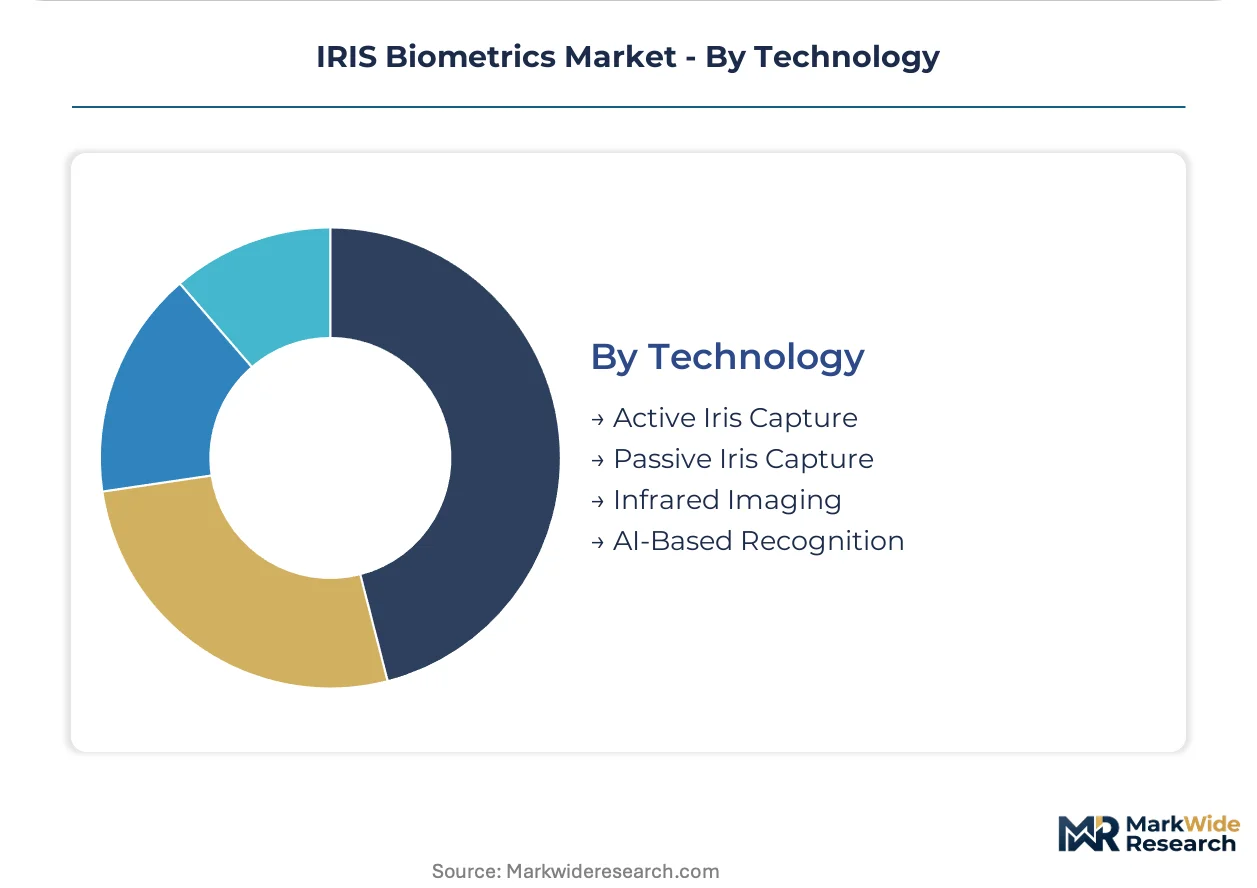
Technology:
Supply concentration in Japanese and South Korean NIR sensor manufacturing shapes which capture modalities achieve cost viability at scale.
- Active Iris Capture:Illumination-controlled systems with dedicated NIR LEDs deliver consistent image quality across ambient lighting conditions. Fixed immigration checkpoints and high-security access control deploy these for enrollment-grade accuracy.
- Passive Iris Capture:Ambient-light-dependent imaging reduces power consumption for mobile and embedded applications. Smartphone integration and extended battery field kits favor this approach despite environmental sensitivity.
- Infrared Imaging:Specialized 700-900 nanometer sensor arrays remain concentrated among Sony, Samsung, and OmniVision supply chains.
- AI-Based Recognition:On-device neural processing units automate template extraction and 1:N matching at the capture point.
Active Iris Capture leads by deployment volume, with AI-Based Recognition showing the steepest expansion trajectory on edge computing proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The iris biometrics industry traces its commercial origins to government-funded research programs in the United States during the 1990s, with subsequent scaling through India's Aadhaar national ID deployment and Middle Eastern sovereign identity infrastructure investments.
United States
US Customs and Border Protection sustains procurement of fixed iris scanners for automated e-gate installations at major international airports. NIST Iris Exchange evaluations set federal eligibility benchmarks that vendors must pass for government contracts. The Washington DC-Maryland-Virginia corridor hosts concentrated defense and homeland security contractor activity.
India
UIDAI mandates iris capture alongside fingerprints for Aadhaar enrollment, driving sustained institutional demand for enrollment hardware and matching infrastructure. The central government's digital identity program operates under sovereign data localization requirements. Bangalore and Hyderabad anchor domestic technology development and system integration capabilities.
Germany
Federal Police procurement of iris-enabled border control systems supports high-throughput passenger screening at Frankfurt and Munich airports. EU AI Act conformity assessments impose documented accuracy and bias testing protocols before public-space deployment. The Stuttgart-Karlsruhe corridor concentrates automotive and industrial biometric application development.
United Arab Emirates
MOHAP and federal identity authority programs drive large-scale iris enrollment infrastructure for national ID and healthcare patient verification. Sovereign data residency requirements mandate localized biometric template storage. Dubai and Abu Dhabi anchor smart city and airport biometric integration projects.
Saudi Arabia
SFDA and national identity program investments expand iris-based authentication for healthcare access and government service delivery. Vision 2030 digital transformation initiatives prioritize biometric-enabled citizen services. Riyadh and the Eastern Province concentrate public sector technology procurement and deployment activity.
IRIS Biometrics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and government assurance tiers, with defense-heritage vendors commanding structural pricing power in sovereign identity contracts. The vendor landscape organizes around three strategic archetypes: integrated defense contractors leveraging security clearances, civil identity specialists with multi-modal biometric portfolios, and component-scale manufacturers with iris matching engine expertise. Dominant competitive moves include modular bundling of hardware with cloud analytics subscriptions and vertical integration into near-infrared sensor supply chains.
Within the defense-contractor archetype, Thales and NEC Corporation exemplify premium-tier positioning through high-assurance government relationships. IDEMIA occupies a position across civil identity and border management segments with integrated biometric capabilities. These three anchors represent distinct strategic postures: Thales leverages aerospace and defense heritage, NEC Corporation brings manufacturing scale in matching engines, and IDEMIA competes through portfolio breadth across fingerprint, facial, and iris modalities.
| Leading Market Players |
|---|
| Thales |
| IDEMIA |
| NEC Corporation |
| HID Global |
| Iris ID Inc. |
| IriTech Inc. |
| EyeLock LLC |
| IrisGuard Ltd. |
| Princeton Identity |
| Others |
Value Network & Pricing Analysis
Government border management agencies concentrate procurement authority for high-assurance iris systems, anchoring project-based pricing with multi-year service bundling rather than per-unit transactional models. This buyer concentration enables premium-tier vendors to defend margins through certification complexity while squeezing commodity hardware suppliers.
Pricing Analysis
Three-tier pricing structure across defense-grade, civil-identity, and commercial-security levels dominates procurement, with NIST Iris Exchange certification and EU AI Act conformity assessments serving as the primary price differentiation drivers. Cost compression in commercial-access-control tiers is intensifying because facial recognition substitutes erode iris value propositions at lower accuracy thresholds. Banking sector buyers exhibit the highest price sensitivity through subscription bundling demands, while sovereign identity programs show the least sensitivity due to data residency mandates.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing and the EU AI Act's local-content traceability requirements are reshaping sourcing patterns for assembly and algorithm development. Near-infrared sensor production concentrates in Japan and South Korea, with Sony, Samsung, and OmniVision anchoring 700-900 nanometer imager supply. Specialized NIR LEDs, precision optics, and neural processing units constitute critical input dependencies. Single-source vulnerability in Japanese sensor fabrication creates structural risk for vendors lacking dual-qualified suppliers. Distribution runs through direct government contracting channels for sovereign programs and systems integrators for enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in iris biometrics rests on edge-AI cost-down curves compressing hardware BOMs while regulatory compliance complexity sustains premium-tier pricing power for certified vendors.
For Market Incumbents: Lock in long-term sensor supply agreements with Japanese and South Korean NIR imager suppliers before capacity constraints tighten. Accelerate backward integration into on-device neural processing unit design to reduce dependency on Qualcomm and MediaTek chipsets. Facial recognition substitution in commercial access control threatens hardware margins; defend position through multi-modal bundling that facial-only vendors cannot replicate. For New Entrants and Emerging Players: Cloud-native identity-verification platforms offer the lowest barrier to entry for SaaS-based iris analytics without capital-intensive hardware manufacturing. UNHCR humanitarian registration operations in Jordan and Bangladesh represent the most penetrable white-space target, with ruggedized mobile kit demand outpacing incumbent supply capacity. Pursue OEM partnerships with smartphone manufacturers seeking embedded iris modules for financial-account-recovery differentiation. For Investors and Strategic Acquirers: Defense contractors with security clearances are the most active acquirers in this space, seeking biometric capabilities for classified identity infrastructure programs. Target acquisition archetypes include edge-AI software specialists with explainable-matching IP and field-hardened mobile enrollment kit developers. Watch for EU AI Act notified-body certification backlogs as an inflection signal—delayed approvals will consolidate procurement around pre-certified vendors.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | Notified-body approval unlocks public-space deployment contracts across German and Dutch border agencies. |
| Edge-Based Matching Engine Development | On-device 1:N authentication eliminates network latency for Frankfurt Airport unattended e-gate pilots. |
| Multi-Modal Biometric Fusion | Fused iris-fingerprint-face templates command premium positioning in UAE national ID infrastructure tenders. |
| Humanitarian Registration Kit Expansion | IP67-rated mobile systems address UNHCR demand in Bangladesh refugee camps with sovereign data constraints. |
| Cloud Analytics Platform Integration | Subscription bundling compresses North American commercial real estate procurement cycles from three years to annual. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biometric procurement officers at border agencies, physical security directors at multinational corporations, algorithm engineers at matching-engine vendors, and regulatory affairs leads navigating EU AI Act conformity pathways. Secondary validation drew from NIST Iris Exchange evaluation reports, UIDAI technical specifications, EU AI Act implementing guidance, SEC filings of listed biometric vendors, and customs data on NIR sensor trade flows. Bottom-up enrollment hardware unit economics and top-down national ID program budgets were triangulated for market sizing.
Historical reference periods spanning pre-pandemic, pandemic-disrupted, and recovery-phase intervals anchored the forecast window, with growth trajectories projected across the modeling period. Segmentation dimensions included product architecture, end-user vertical, deployment model, and technology modality, with algorithmic transparency compliance tier added as a biometrics-specific dimension. CAGRs were derived from regression analysis against Aadhaar enrollment curves, CBP procurement schedules, and Middle Eastern smart city investment pipelines.
The model assumes a particular technology adoption path; alternative pathways for passive iris capture in smartphone integration would alter the outlook if ambient-light sensitivity limitations resolve faster than projected. Forecasts reflect assumptions regarding EU AI Act implementation timelines and UIDAI enrollment saturation curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Global Multifactor Authentication Market
Biometrics & Identity Management
North America Enterprise Biometrics Market
Biometrics & Identity Management
Italy Mobile Biometrics Market
Biometrics & Identity Management
Biometric ATM Market
Biometrics & Identity Management
Biometrics Banking Market
Biometrics & Identity Management
Germany Identity Verification and Authentication Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
Mobile Biometric Security and Services Market
Biometrics & Identity Management
Passive Authentication Market
Biometrics & Identity Management
Global Phone Based Authentication Solution Market
Biometrics & Identity Management
Middle East and Africa Biometrics in Government Market
Biometrics & Identity Management
Europe Biometrics Market
Biometrics & Identity Management
AI-Enabled Biometrics Market
Biometrics & Identity Management
North America Government and Security Biometrics Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Market