
 Global Biometric Identification Market | 2026-2036
Global Biometric Identification Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biometric Identification Market Foresight
Government agencies are unwinding their historical dominance as financial institutions and transportation operators command larger procurement budgets. NEC Corporation leverages its long-standing government relationships to sustain high-volume iris recognition contracts across Asia. IDEMIA anchors its position through in-house production of secure biometric credentials for civil identification programs. Thales Group competes by extending its defense-electronics heritage into border security and airport passenger processing systems.
Biometric identification refers to automated recognition of individuals based on physiological or behavioral characteristics, typically requiring capture thresholds of 500+ dots per inch for fingerprint minutiae and near-infrared illumination for iris encoding. Its primary commercial purpose is to bind a claimed identity to a live person with measurable statistical confidence, replacing token-based or knowledge-based authentication in high-assurance environments. Fingerprint recognition occupies the largest installed base due to decades of sensor cost reduction and embedded integration in consumer devices, while facial recognition represents the fastest-expanding technology segment as liveness detection algorithms harden against presentation attacks. Payment authentication applications concentrate margin pools because transaction velocity and fraud liability create premium pricing for sub-second matching latency.
The EU AI Act classifies remote biometric identification as high-risk, forcing vendors to maintain conformity assessment documentation and human oversight protocols for public-space deployment. India's BIS certification and the UIDAI's biometric standards shape product specifications for any supplier seeking access to Aadhaar-linked procurement channels. ISO/IEC 30107-3 presentation attack detection standards and the FBI's EBTS specification collectively define the technical baseline for cross-border interoperability. Stakeholders must monitor how divergent privacy enforcement between Brussels and New Delhi fragments certification requirements and splinters vendor go-to-market strategies.
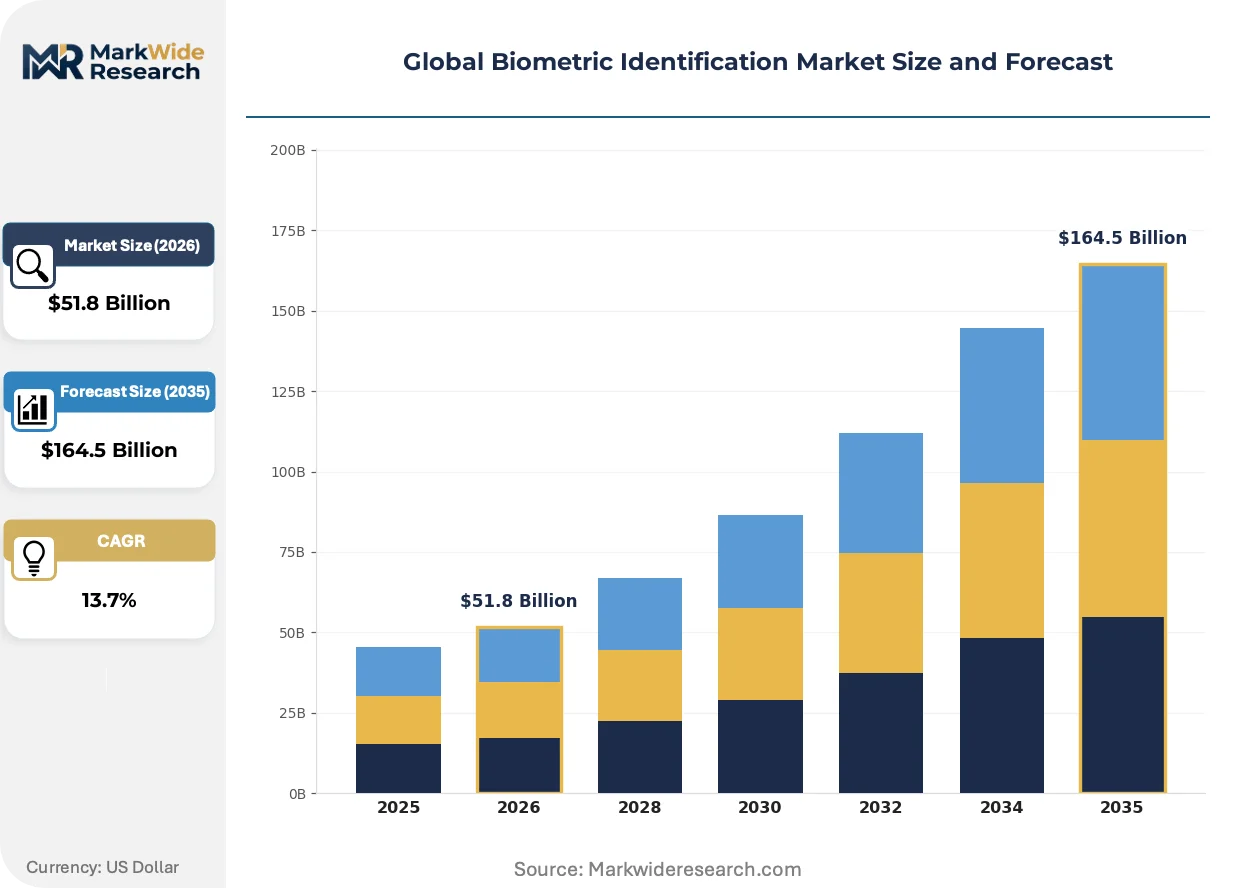
Market Dynamics
Financial institutions are displacing government agencies as the dominant procurement force, redirecting R&D investment toward multimodal authentication systems that fuse fingerprint, iris, and behavioral biometrics for real-time transaction verification.
Growth Catalysts
- EU AI Act compliance mandates:High-risk classification for remote biometric identification forces enterprises to upgrade legacy systems, creating replacement demand for certified vendors across European digital infrastructure.
- Aadhaar-linked welfare digitization:India's UIDAI standards drive large-scale fingerprint and iris deployment through government procurement channels for subsidy distribution and rural banking inclusion.
- Contactless biometric sensors:Near-field fingerprint and palm-vein modules eliminate hygiene concerns in healthcare and food service access control applications.
Market Restraints
- Specialized sensor supply concentration:High-resolution optical and capacitive fingerprint sensor manufacturing clusters in East Asia create single-source vulnerability for tier-two integrators.
- GDPR biometric data processing restrictions:Explicit consent requirements and purpose limitation rules increase legal review costs for European commercial deployments.
- Presentation attack detection hardware costs:Multi-spectral imaging and 3D depth sensors for liveness verification add 40-60% premium to baseline authentication hardware.
Strategic Opportunities
- Sub-Saharan Africa civil ID programs:National biometric voter registration and social protection systems in Nigeria, Kenya, and Ethiopia remain underpenetrated by multimodal solution providers.
- ISO/IEC 30107-3 certification acceleration:Presentation attack detection standardization creates tiered vendor qualification pathways that favor early certifiers in cross-border tenders.
- Behavioral-physiological fusion:Keystroke dynamics and gait analysis layered atop fingerprint or facial templates enables continuous authentication for high-value financial workflows.
Industry Challenges
- Biometric algorithm engineer scarcity:Deep expertise in neural network-based template extraction and matching optimization concentrates within a handful of academic and corporate research centers.
- Legacy identity system integration:Token-based and knowledge-based authentication architectures in established banking infrastructure resist modular biometric overlay without core system replacement.
- Cross-jurisdictional data residency compliance:Divergent localization requirements between Brussels, New Delhi, and Beijing fragment cloud-based biometric service architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biometric Identification Market |
| Market Size in 2026 | $51.8 Billion |
| Market Size in 2035 | $164.5 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition, Vein Pattern Recognition Application: Access Control, Border Security, Payment Authentication, Time & Attendance, Law Enforcement End User: Government Agencies, Financial Institutions, Transportation Operators, Educational Institutions, Telecom Providers Deployment: On-Premise, Cloud-Based, Hybrid, Hosted Services |
| Companies Covered | HID Global, Aware, Inc., NEC Corporation, ZKTeco, Innovatrics, IDEMIA, Entrust, Jumio, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biometric Identification Market Shifts & Advancements
Algorithmic liveness detection and edge-computing deployment models are compressing authentication latency while hardening systems against synthetic media attacks. These shifts are reconfiguring hardware-software value distribution across the supply chain.
Multimodal biometric fusion is bifurcating the competitive landscape between single-modality sensor vendors and integrated platform providers. Tier-one banks and border control agencies now demand simultaneous fingerprint, iris, and facial capture within unified enrollment workflows. This convergence is compressing margins for standalone fingerprint specialists while elevating system integrators with in-house algorithm development.
The EU AI Act's high-risk classification for remote biometric identification in public spaces is forcing vendors to maintain conformity assessment documentation and human-in-the-loop oversight protocols. Industrial consequence includes extended certification timelines and elevated legal liability for false-positive identification. Public-sector facial recognition deployments in France, Germany, and Italy are responding by segmenting procurement into enrollment-only versus real-time surveillance categories with divergent compliance burdens.
Enterprise buyers are consolidating vendor relationships around full-stack biometric platform providers capable of delivering enrollment, matching, and lifecycle management as unified service contracts. Value-added resellers and regional system integrators are losing share to direct OEM relationships in financial services and aviation verticals. This consolidation is most visible in India's digital banking and airport passenger processing sectors, where Aadhaar-linked procurement favors vendors with end-to-end credential production and authentication infrastructure capabilities.
Global Biometric Identification Market Segmentation
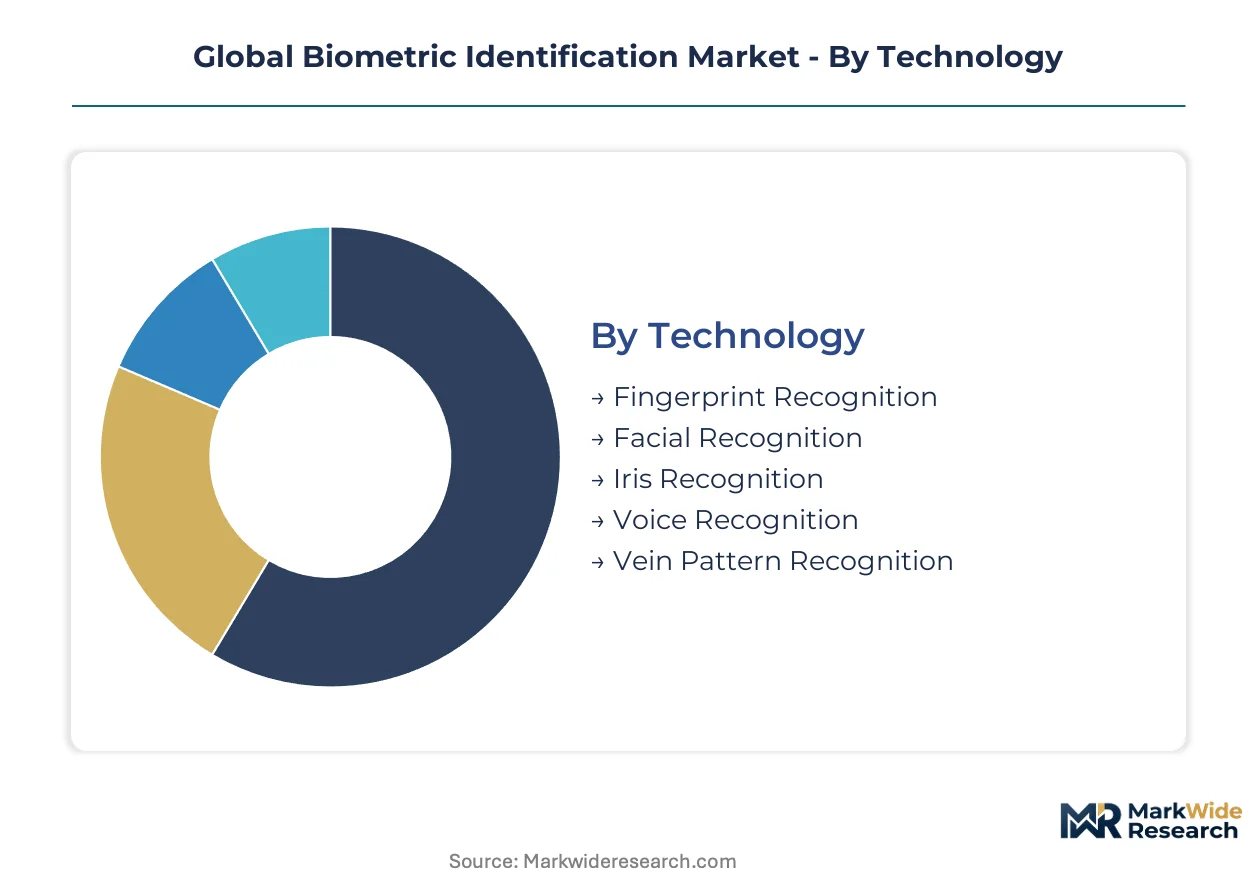
Technology and application splits reveal divergent margin profiles across the biometric value chain. Deployment models and end-user concentration determine vendor pricing power and certification requirements.
Technology:
Substitution pressure from behavioral biometrics and passwordless authentication standards threatens legacy modalities most exposed to sensor commoditization.
- Fingerprint Recognition:Capacitive and optical sensors capture ridge patterns at 500+ dots per inch for minutiae extraction. Indian banking and Aadhaar enrollment channels absorb the highest sensor volumes, though hygiene concerns in healthcare accelerate contactless alternatives.
- Facial Recognition:Neural network-based template extraction from 2D and 3D facial geometry enables passive authentication at distance. EU AI Act high-risk classification for public-space deployment forces liveness detection hardware upgrades, compressing margins for uncertified vendors.
- Iris Recognition:Near-infrared illumination encodes unique patterns in the trabecular meshwork. NEC Corporation dominates government procurement across Asia through long-standing enrollment infrastructure relationships.
- Voice Recognition:Spectral analysis of vocal tract characteristics enables telephony-based authentication. Call center and remote banking applications drive demand despite susceptibility to synthetic speech attacks.
- Vein Pattern Recognition:Near-infrared transillumination maps subcutaneous vascular structures in palm or finger. Japanese financial institutions and healthcare access control deploy palm-vein modules for hygiene-sensitive environments.
Fingerprint recognition anchors the volume base while facial recognition gains share at the steepest rate.
Application:
Margin concentration follows fraud liability exposure, with payment networks commanding sub-second matching latency premiums.
- Payment Authentication:Multimodal fusion of fingerprint, facial, and behavioral biometrics secures real-time transaction authorization. Tier-one banks in India and the United States drive procurement of certified matching engines with sub-200-millisecond response thresholds.
- Border Security:Integrated enrollment and verification workflows process millions of passenger records through airport e-gates. Thales Group leverages defense-electronics heritage to capture European and Middle Eastern government tenders.
- Access Control:Enterprise physical security and logical system entry deploy fingerprint and facial modalities. Post-pandemic hygiene requirements accelerate contactless sensor adoption in healthcare and food service verticals.
- Time & Attendance:Workforce management systems verify identity for payroll and shift tracking. Manufacturing and logistics facilities in India integrate Aadhaar-linked authentication for statutory compliance.
- Law Enforcement:Forensic identification and criminal record systems demand FBI EBTS-compliant tenprint and latent matching. FBI specification adherence limits vendor qualification to established algorithm providers.
Payment authentication captures the steepest margin expansion while time and attendance commoditizes most rapidly.
End User:
Procurement authority is shifting from sovereign buyers to commercial operators with cloud-native infrastructure requirements.
- Government Agencies:Civil identification, voter registration, and social protection programs demand in-house credential production. India's UIDAI standards and BIS certification shape supplier qualification for Aadhaar-linked channels.
- Financial Institutions:Digital banking and real-time payment networks displace government agencies as the dominant procurement force. Multimodal authentication platforms with behavioral fusion command premium pricing for fraud reduction guarantees.
- Transportation Operators:Airport passenger processing and urban transit systems require high-throughput, low-friction verification. Biometric boarding trials at Dubai International Airport and Singapore Changi demonstrate scaled deployment feasibility.
- Educational Institutions:Campus access and examination integrity applications deploy fingerprint and facial matching. Examination board contracts in India and Nigeria drive seasonal procurement spikes.
- Telecom Providers:Subscriber identity verification for SIM registration and mobile money onboarding. Regulatory mandates in Pakistan, Bangladesh, and Nigeria require biometric enrollment at point of sale.
Financial institutions now absorb the largest procurement budgets while transportation operators expand most aggressively.
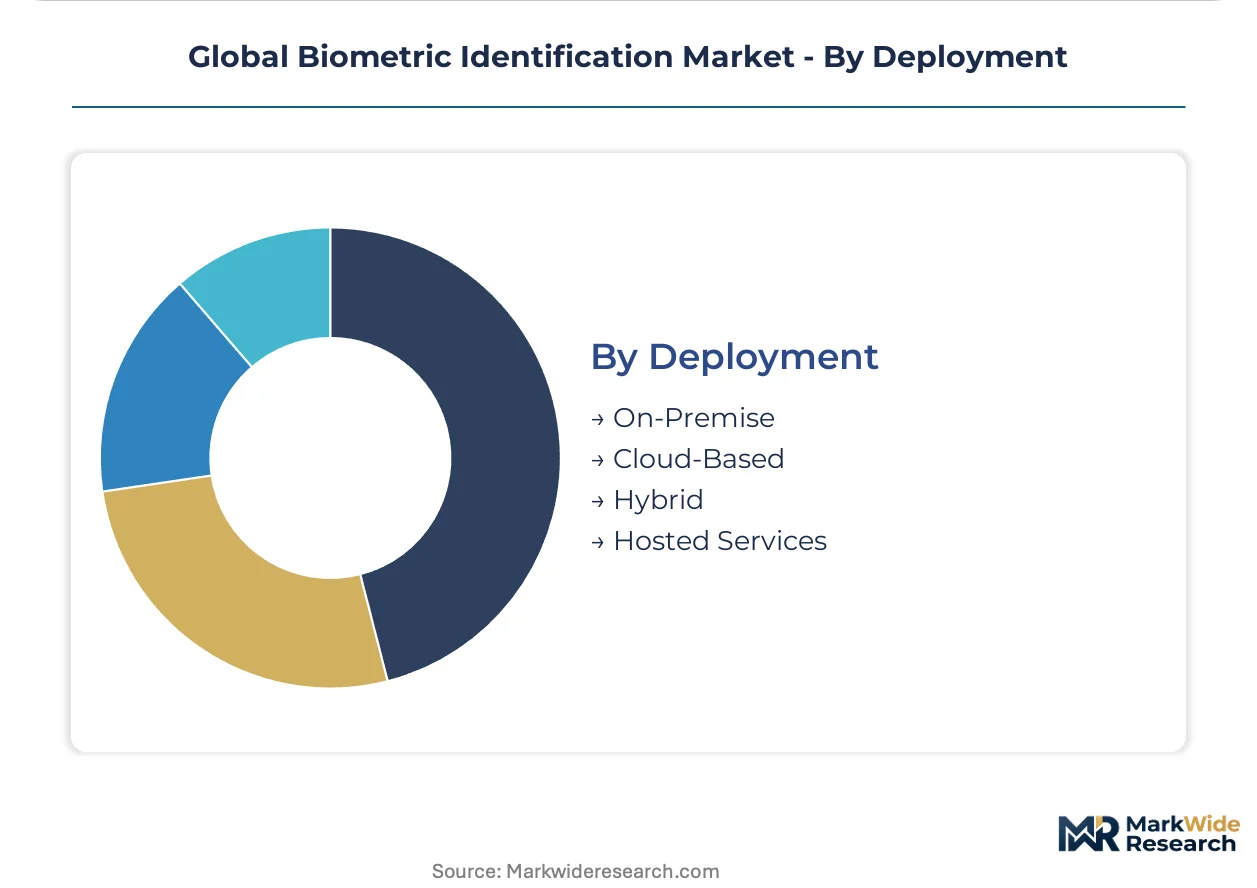
Deployment:
Data residency fragmentation between Brussels, New Delhi, and Beijing splinters cloud architecture standardization.
- On-Premise:Dedicated hardware within enterprise or government data centers maintains full data sovereignty. Law enforcement and defense applications mandate air-gapped infrastructure for criminal record systems.
- Cloud-Based:Scalable matching-as-a-service reduces capital expenditure for mid-tier financial institutions. GDPR biometric processing restrictions and India's data localization requirements fragment vendor service architectures.
- Hybrid:Enrollment at edge with centralized matching balances latency against storage efficiency. Large banks in Europe and North America deploy hybrid models to satisfy audit and performance requirements simultaneously.
- Hosted Services:Managed biometric infrastructure outsourced to specialized platform operators. Small and mid-sized enterprises without security operations expertise favor subscription-based authentication services.
On-premise deployment retains the highest security-sensitive share while cloud-based models climb fastest among commercial adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Aadhaar digital infrastructure underwrites India's commanding position in biometric enrollment volume, while the EU's regulatory framework shapes premium-tier certification requirements across European procurement channels.
United States
FBI EBTS-compliant tenprint systems and digital banking fraud reduction drive procurement of multimodal authentication platforms. HIPAA and state-level biometric privacy laws in Illinois, Texas, and Washington fragment compliance requirements for healthcare and commercial deployments. Silicon Valley and Boston-area algorithm developers concentrate neural network-based template extraction expertise for financial services clients.
India
UIDAI-linked welfare digitization and rural banking inclusion programs absorb the highest fingerprint and iris sensor volumes globally. BIS certification and the UIDAI's biometric standards create mandatory supplier qualification gates for Aadhaar procurement channels. Bangalore and Hyderabad host the densest clusters of system integrators serving government enrollment and digital payment authentication contracts.
Germany
GDPR biometric data processing restrictions and the EU AI Act's high-risk classification elevate legal review costs for public-space facial recognition deployments. KBA and federal data protection authorities enforce explicit consent requirements for commercial biometric applications. Munich and Frankfurt financial centers drive demand for sub-second matching latency in real-time payment authentication systems.
China
MIIT standards and national data localization requirements shape domestic biometric service architectures for financial and telecommunications applications. GB standards for fingerprint and facial recognition equipment define technical baselines for government and enterprise procurement. Shenzhen and Beijing concentrate sensor manufacturing and algorithm development capabilities for domestic and export markets.
United Arab Emirates
Dubai International Airport biometric boarding trials and national digital identity programs demonstrate scaled deployment feasibility for transportation and civil identification. MOHAP and federal telecommunications regulations mandate subscriber biometric enrollment for SIM registration and mobile money services. Dubai and Abu Dhabi anchor Middle East demand for high-throughput passenger processing and border security infrastructure.
Global Biometric Identification Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and government relationship durability, producing a tiered structure where full-stack platform providers capture premium pricing while component vendors face margin compression. Strategic archetypes include government-contract specialists with long-standing enrollment infrastructure relationships, financial services platform providers with in-house algorithm development, and sensor manufacturers with captive supply of optical and capacitive modules. Competitive moves concentrate on M&A to acquire presentation attack detection capabilities and geographic expansion into underpenetrated civil identification programs.
Within the government-contract tier, NEC Corporation and IDEMIA exemplify archetypes built on sustained public-sector relationships and in-house credential production capabilities. Thales Group occupies a position bridging defense-electronics heritage with civilian border security and aviation passenger processing applications. These three entities anchor the premium tier where end-to-end platform capabilities determine procurement outcomes in India and European government channels.
| Leading Market Players |
|---|
| HID Global |
| Aware, Inc. |
| NEC Corporation |
| ZKTeco |
| Innovatrics |
| IDEMIA |
| Entrust |
| Jumio |
| Thales Group |
| Others |
Supply & Pricing Matrix
East Asian sensor foundries generate steep scale economies that compress unit costs for optical and capacitive fingerprint modules while simultaneously hardening price floors for uncertified competitors. This concentration of high-resolution imaging capacity in Shenzhen and Seoul corridors funnels procurement leverage toward tier-one integrators with direct OEM relationships, leaving regional distributors exposed to margin erosion.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FBI EBTS-certified tenprint systems from ISO/IEC 30107-3 PAD-compliant mid-tier offerings and uncertified commodity sensors. Price differentiation hinges on certification grade and matching latency performance, with sub-200-millisecond engines commanding substantial premiums in Indian digital banking channels. Pricing pressure stems from liveness detection hardware costs that add 40-60% to baseline authentication equipment, forcing tier-two vendors toward software-only positioning. Tier-one banks exhibit lowest price sensitivity due to fraud liability exposure, while educational examination contracts in Nigeria and India drive aggressive commoditization.
Supply Chain Analysis
Just-in-time sensor procurement dominates tier-one integrators with direct foundry relationships, whereas government enrollment programs maintain strategic stockpiles of near-infrared illumination modules to buffer against UIDAI specification change cycles. Geographic supply concentration centers on China, South Korea, and Taiwan for optical sensor fabrication, with Japan anchoring specialized palm-vein imaging component production. Raw material dependencies include silicon wafers, near-infrared LED arrays, and precision optical glass. Single-source vulnerability concentrates in high-resolution capacitive sensor die manufacturing. Distribution runs through direct OEM contracts for financial services and aviation verticals, bypassing traditional value-added reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among tier-one banks and border control agencies is shifting bargaining power toward full-stack platform providers capable of unified enrollment-to-authentication service delivery. This buyer concentration fragments opportunities for standalone component vendors and regional system integrators without in-house algorithm development.
For Market Incumbents: Secure ISO/IEC 30107-3 certification acceleration to maintain qualification gates in European and Indian procurement channels. Deepen backward integration into presentation attack detection hardware production to defend margins against software-only entrants. Threat substitution from behavioral-physiological fusion platforms demands R&D investment in continuous authentication architectures for high-value financial workflows.
For New Entrants and Emerging Players: Lead with niche PAD certification in underpenetrated Sub-Saharan African civil ID programs, where Nigerian voter registration and Ethiopian social protection systems lack multimodal solution providers. Target hybrid cloud-on-premise deployment models for mid-tier European banks navigating GDPR biometric processing restrictions. Go-to-market angle: managed biometric infrastructure subscription services bypassing capital-intensive credential production capabilities.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors algorithm developers with neural network-based template extraction expertise concentrated in academic and corporate research centers. Long-term viability across the projection horizon rests on vendors capable of bridging government-contract durability with financial services platform scalability. Acquisition target archetype: presentation attack detection specialists with ISO/IEC 30107-3 certification pathways. Signal to watch: divergence between Brussels and New Delhi privacy enforcement fragmenting cloud architecture standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Presentation Attack Detection Certification | ISO/IEC 30107-3 compliance unlocks tiered vendor qualification in cross-border government tenders. |
| Multimodal Platform Integration | Unified fingerprint-iris-facial enrollment workflows displace standalone sensor vendors in Indian Aadhaar-linked channels. |
| Behavioral-Physiological Fusion Development | Keystroke dynamics layered atop fingerprint templates enables continuous authentication for real-time payment networks. |
| Strategic Partnership with Tier-One Banks | Direct OEM relationships bypass value-added resellers and capture premium pricing for sub-second matching latency. |
| Geographic Expansion into Sub-Saharan Africa | National biometric voter registration programs in Nigeria and Kenya remain underpenetrated by certified platform providers. |
Research Methodology
Desk research of regulatory filings, patent databases, and customs trade records preceded structured interviews with biometric algorithm engineers, government procurement officers at UIDAI and EU border agencies, financial services fraud prevention executives, and airport passenger processing system integrators. Primary intelligence combined with secondary validation from FBI EBTS specifications, ISO/IEC standards documentation, and BIS certification registries. Bottom-up sensor shipment analysis triangulated against top-down procurement budget disclosures across government and commercial channels.
Variance decomposition across technology modality, application fraud liability tier, and deployment architecture informed the analytical framework over the projection horizon. Segmentation dimensions modeled include biometric modality type, end-user procurement authority, and data residency compliance cluster. CAGRs derived from logistic diffusion curves fitted to enrollment infrastructure deployment schedules and banking digitization policy trajectories. Industry-specific forecast inputs encompassed Aadhaar-linked sensor volume commitments and EU AI Act implementation timelines.
Forecasts assume regulatory continuity in Brussels GDPR enforcement, New Delhi UIDAI standards, and Washington FBI EBTS specifications; material policy shifts would require re-modeling of certification-driven replacement demand cycles. Revision becomes warranted when cross-jurisdictional data localization mandates fragment cloud service architectures beyond hybrid deployment feasibility thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Identity Verification Market
Biometrics & Identity Management
Asia Pacific Biometrics in Government Market
Biometrics & Identity Management
Italy Mobile Biometrics Market
Biometrics & Identity Management
Password Management Market
Biometrics & Identity Management
Latin America Government & Security Biometrics Market
Biometrics & Identity Management
Biometrics As a Service in Healthcare Market
Biometrics & Identity Management
Biometric Scan Software Market
Biometrics & Identity Management
Global Biometric Authentication Identification Market
Biometrics & Identity Management
Asia-Pacific Government and Security Biometrics Market
Biometrics & Identity Management
ID Verification Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
FIDO Authentication Market
Biometrics & Identity Management
Passive Authentication Market
Biometrics & Identity Management
Global Biometric-As-A-Service Market
Biometrics & Identity Management
Biometric Passport Market
Biometrics & Identity Management
Biometric ATM Market