
 South-East Asia Civil Aviation Market | 2026-2036
South-East Asia Civil Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
South-East Asia Civil Aviation Market Analytics
Aftermarket service revenue is tilting from scheduled maintenance toward predictive analytics and component life-extension programs. Airbus SE leverages its regional training centers in Singapore to sustain technical workforce pipelines across the archipelago. The Boeing Company anchors its Southeast Asian aftermarket position through distributed parts warehousing in Kuala Lumpur and Bangkok. Embraer SA competes in the regional aircraft niche with dedicated support contracts tailored to thin-route operators in the Philippines and Myanmar.
South-East Asia civil aviation encompasses the design, manufacture, operation, and maintenance of fixed-wing aircraft serving commercial, cargo, and government missions across the ASEAN economic zone, with turbofan engines typically operating at bypass ratios exceeding five-to-one for regional fuel efficiency. The sector's primary purpose is to overcome archipelagic geography and underdeveloped ground infrastructure by providing time-sensitive passenger and freight connectivity between islands and secondary cities. Commercial jets dominate fleet orders as airlines in Vietnam and the Philippines prioritize narrowbody capacity for trunk routes, while MRO Services captures expanding margin pools as aging A320ceo and 737NG fleets require heavy checks and engine overhauls. Regional Aircraft maintains steady demand from flag carriers serving thin routes to secondary Indonesian and Laotian airports where runway limitations exclude mainline equipment.
Indonesia's Directorate General of Civil Aviation and the Civil Aviation Authority of Malaysia enforce ICAO-aligned airworthiness standards that shape fleet renewal timelines and MRO certification requirements across their jurisdictions. EASA bilateral recognition agreements with Singapore and Thailand streamline type certification for European-manufactured aircraft entering those registers. Stakeholders must monitor CAAM's ongoing restructuring in Myanmar and Vietnam's tightening environmental operating permits, as regulatory fragmentation across the ten ASEAN states will determine market access costs and fleet standardization feasibility.
Market Dynamics
The archipelagic geography of Indonesia and Vietnam's rising middle-class air travel are concentrating narrowbody fleet orders while EASA-CAAM certification alignment accelerates new aircraft entry into Southeast Asian registers.
Growth Catalysts
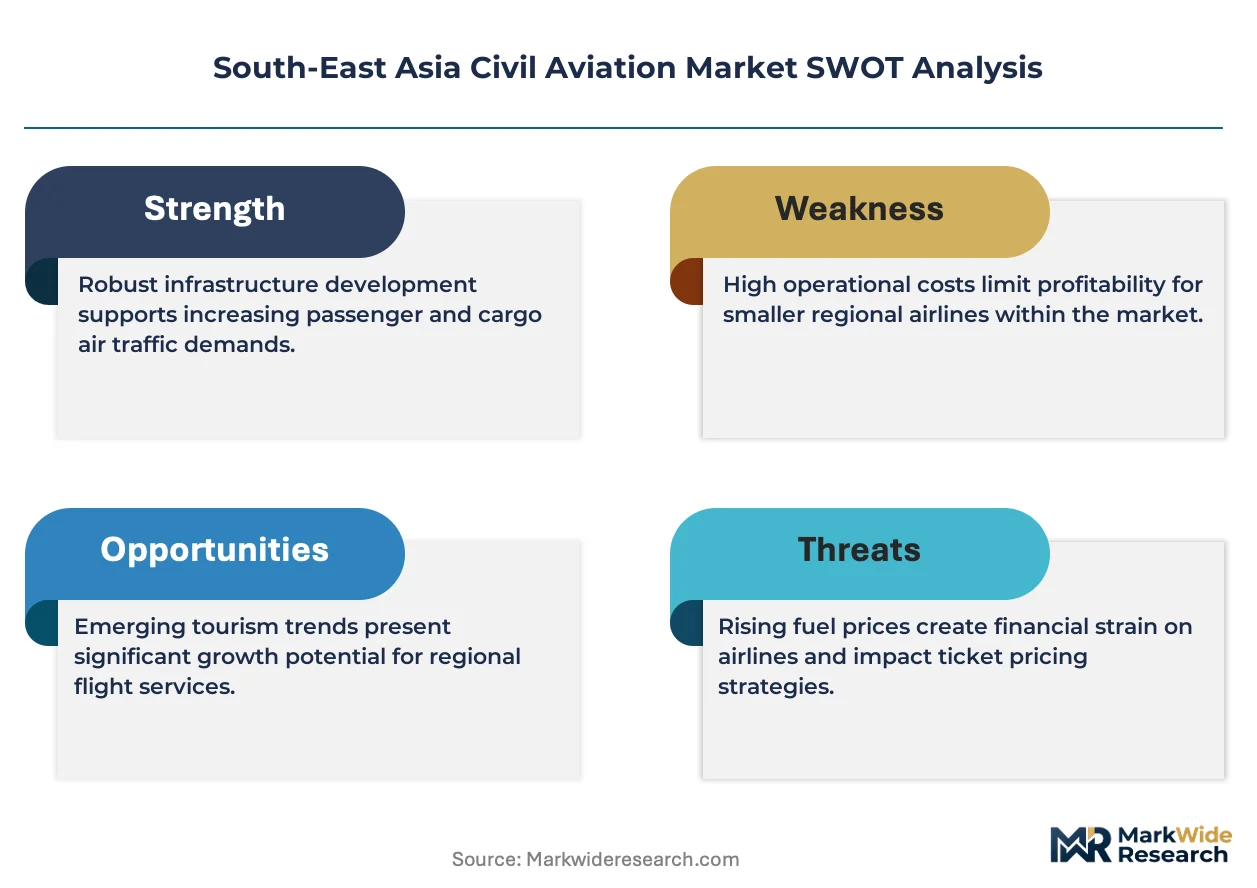
- ICAO-aligned airworthiness standards:Indonesia's Directorate General of Civil Aviation enforces standards that compress fleet renewal timelines and expand MRO certification demand across the archipelago.
- Short-haul connectivity gaps:Underdeveloped ground infrastructure between Philippine and Indonesian islands sustains demand for regional aircraft serving secondary airports with runway limitations.
- Predictive maintenance analytics:Airlines in Singapore and Thailand adopt component life-extension programs to defer heavy check costs on aging narrowbody fleets.
Market Restraints
- Jet fuel cost volatility:Airlines in Vietnam and the Philippines face margin compression from unhedged exposure to Singapore jet fuel benchmarks amid currency fluctuations.
- Regulatory fragmentation:CAAM restructuring in Myanmar and Vietnam's tightening environmental operating permits create divergent certification timelines across ASEAN jurisdictions.
- Technical workforce scarcity:Singapore's regional training centers cannot scale fast enough to meet archipelago-wide demand for airframe and powerplant certificated mechanics.
Strategic Opportunities
- Laos and Myanmar thin routes:Flag carriers serving secondary airports with runway limitations below 1,800 meters require dedicated regional aircraft support contracts.
- EASA bilateral recognition:Streamlined type certification pathways for European-manufactured aircraft entering Thai and Malaysian registers reduce time-to-market.
- Digital MRO platforms:Distributed parts warehousing in Kuala Lumpur and Bangkok enables predictive inventory positioning for unscheduled component replacements.
Industry Challenges
- A320ceo and 737NG heavy check capacity:MRO providers in Indonesia and the Philippines face slot constraints as aging fleets simultaneously reach 12-year structural inspection intervals.
- Multi-jurisdiction airworthiness compliance:Airlines operating across all ten ASEAN states must maintain parallel technical records systems to satisfy divergent national aviation authority audit protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South-East Asia Civil Aviation Market |
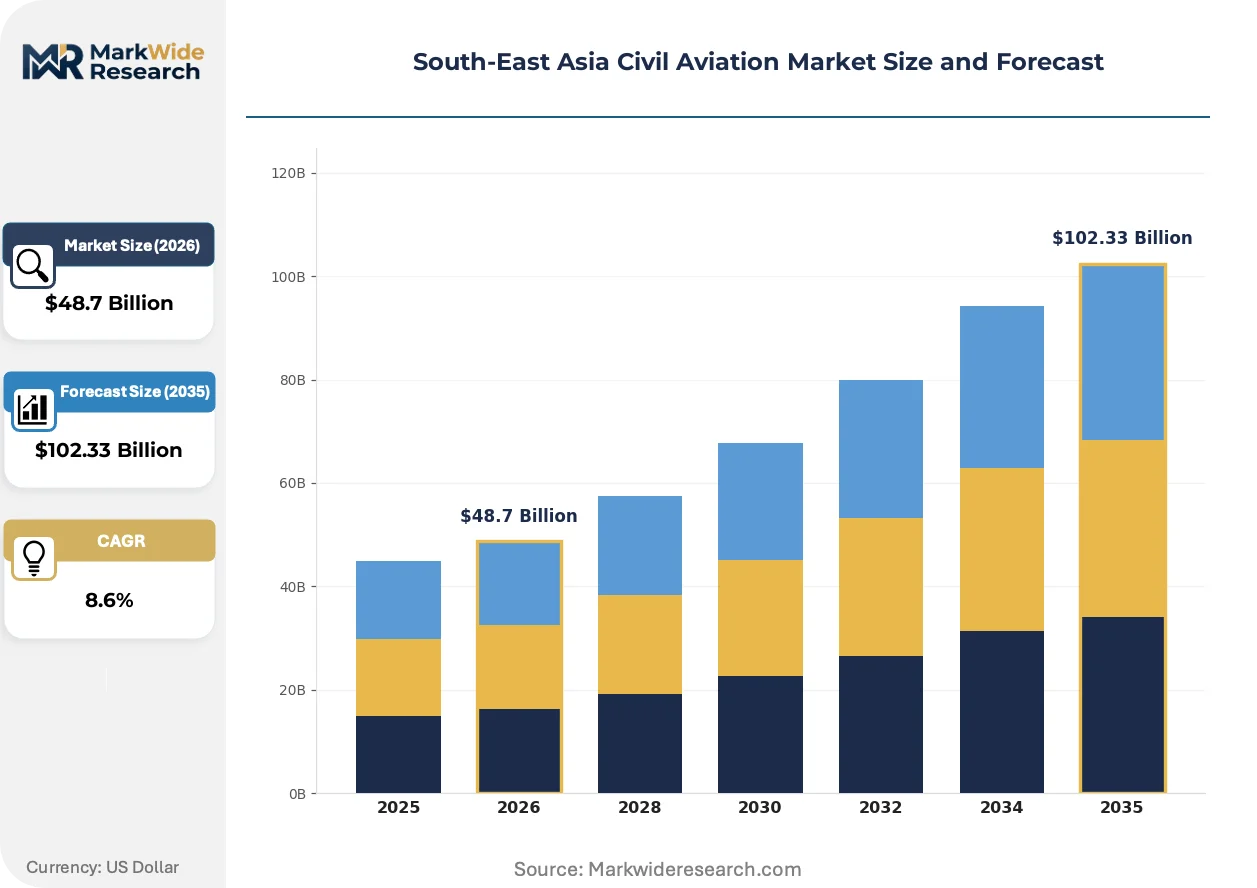
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $102.33 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Commercial Jets, Regional Aircraft, Cargo Aircraft, Business Jets Service Type: Passenger Transport, Cargo Services, Charter Services, MRO Services Technology: Avionics, Flight Control Systems, Fuel Systems, Propulsion Technology End User: Airlines, Government Agencies, Private Operators, Freight Forwarders |
| Companies Covered | ATR, COMAC, Airbus SE, Lockheed Martin Corporation, De Havilland Aircraft of Canada Ltd., The Boeing Company, Bombardier Inc., Textron Inc., Embraer SA, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South-East Asia Civil Aviation Market Evolving Landscape
Aviation technology in Southeast Asia is pivoting from scheduled maintenance to condition-based operations, while regulatory alignment and procurement compression reshape fleet economics across the archipelago.
Digital twin technology for turbofan engine monitoring is hybridizing traditional MRO workflows by integrating real-time sensor data with physics-based degradation models. Garuda Indonesia and VietJet Air deploy these systems to extend on-wing time for CFM56 and V2500 powerplants. The technology is hybridizing aftermarket service revenue from fixed-price overhauls toward usage-based contractual structures.
EASA bilateral recognition agreements with Singapore and Thailand are eliminating redundant certification testing for European-manufactured aircraft entering those registers. Indonesian and Malaysian regulators are negotiating parallel recognition frameworks to accelerate A320neo and 737 MAX fleet inductions. Narrowbody operators in Vietnam face the steepest compliance adaptation as they balance European type certificates against domestic environmental permit requirements.
Airlines across the Philippines and Indonesia are unbundling heavy maintenance from original equipment manufacturer bundled service agreements. Low-cost carriers now tender engine overhauls separately from airframe checks, compressing vendor selection cycles from annual to quarterly reviews. This pattern is most visible in Jakarta and Manila, where procurement teams maintain parallel qualification pools for LEAP-1A and PW1100G-JM shop visits.
South-East Asia Civil Aviation Market Segmentation
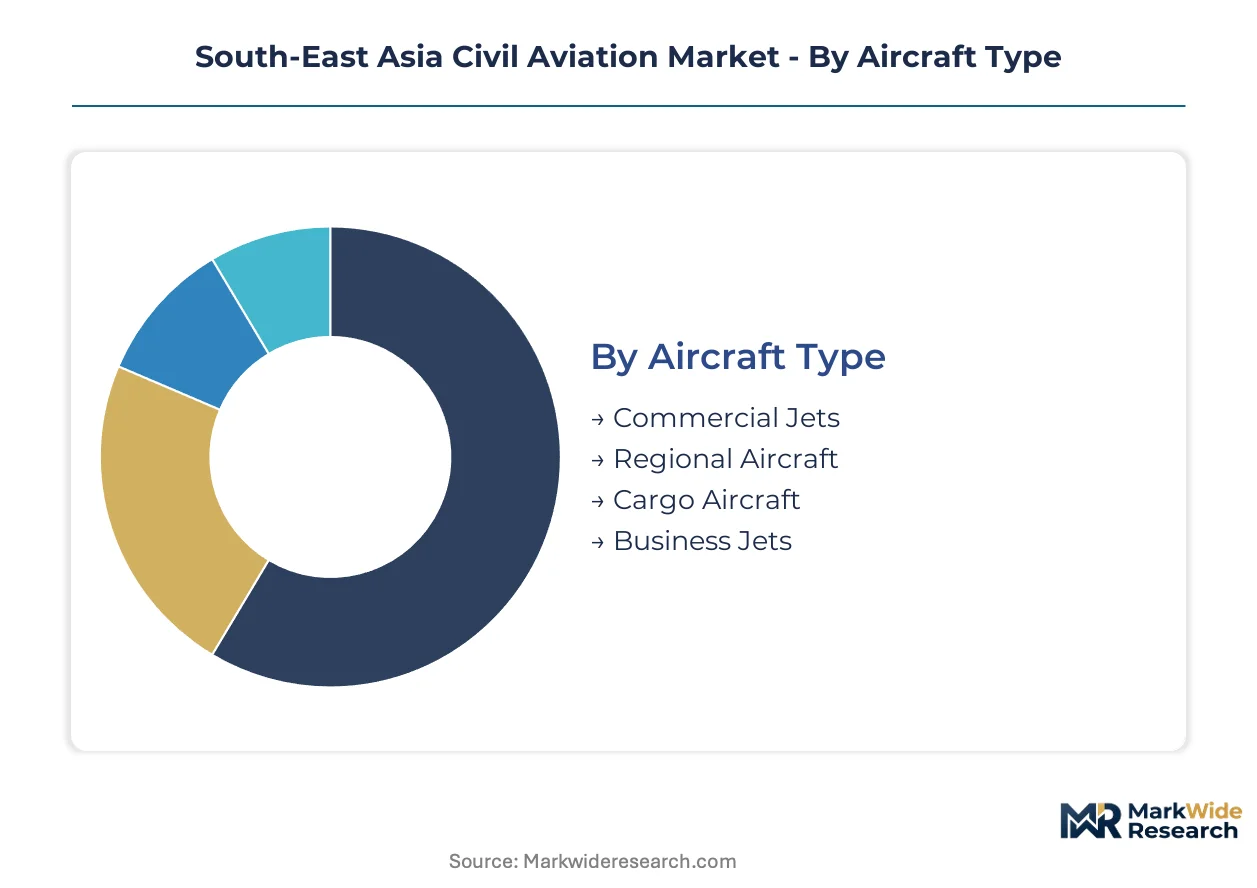
Segmentation in Southeast Asian civil aviation reflects divergent infrastructure maturity across the archipelago. Fleet composition and service models adapt to runway limitations, regulatory fragmentation, and the contrast between trunk-route density and thin-route isolation.
Aircraft Type:
Mature narrowbody platforms dominate trunk connectivity while emerging regional types capture secondary airport penetration.
- Commercial Jets:Single-aisle turbofans with bypass ratios exceeding five-to-one serve high-frequency corridors between Jakarta, Manila, and Ho Chi Minh City. Garuda Indonesia and VietJet Air concentrate orders here to capture middle-class air travel expansion on routes exceeding 800 nautical miles.
- Regional Aircraft:Turboprops and small jets with landing distances below 1,400 meters access runway-constrained destinations in the Philippines and eastern Indonesia. Demand clusters where flag carriers maintain thin-route obligations to secondary cities excluded from mainline networks.
- Cargo Aircraft:Converted narrowbody freighters and dedicated widebody cargo haulers serve e-commerce fulfillment lanes across the ASEAN economic zone.
- Business Jets:Light and mid-size jets facilitate executive travel between Singapore, Kuala Lumpur, and Jakarta financial centers.
Commercial Jets handles the majority of throughput; Regional Aircraft is expanding most quickly on share as infrastructure gaps persist.
Service Type:
Service models stratify by customer ownership economics, with scheduled operations yielding to unbundled aftermarket contracts.
- Passenger Transport:Scheduled narrowbody operations on trunk routes generate the dominant revenue pool across Indonesian and Vietnamese low-cost carriers. Seat density configurations exceed 180 passengers on A320neo and 737 MAX fleets deployed on competitive Jakarta-Singapore and Manila-Bangkok corridors.
- MRO Services:Heavy checks, engine overhauls, and component repairs capture expanding margin pools as aging A320ceo and 737NG fleets reach 12-year structural inspection intervals simultaneously. Singapore's regional training centers and Kuala Lumpur's distributed parts warehousing anchor technical capability.
- Cargo Services:Dedicated freighter operations and belly-hold cargo on passenger widebodies serve cross-border e-commerce fulfillment.
- Charter Services:Ad-hoc passenger and freight contracts address seasonal pilgrimage traffic and emergency logistics.
Passenger Transport commands the largest revenue base; MRO Services is climbing the fastest as fleet age concentrates maintenance demand.
Technology:
Technology segments concentrate where digital retrofit cycles intersect with regulatory compliance timelines.
- Avionics:Flight management systems, communication suites, and navigation equipment undergoing mandatory performance-based navigation upgrades across ASEAN registers. EASA bilateral recognition with Singapore and Thailand accelerates European-certified avionics entry.
- Propulsion Technology:High-bypass turbofans and geared turbofan architectures deliver fuel efficiency gains for narrowbody renewal programs. LEAP-1A and PW1100G-JM powerplants dominate new orders as Indonesian and Malaysian regulators negotiate type certification alignment.
- Flight Control Systems:Fly-by-wire and augmented stability systems for new-generation narrowbody and regional platforms.
- Fuel Systems:Inerting systems and thermal management for extended-range twin-engine operations across archipelagic routes.
Avionics carries the heaviest regulatory-driven replacement cycle; Propulsion Technology is gaining share fastest through fleet renewal concentration.
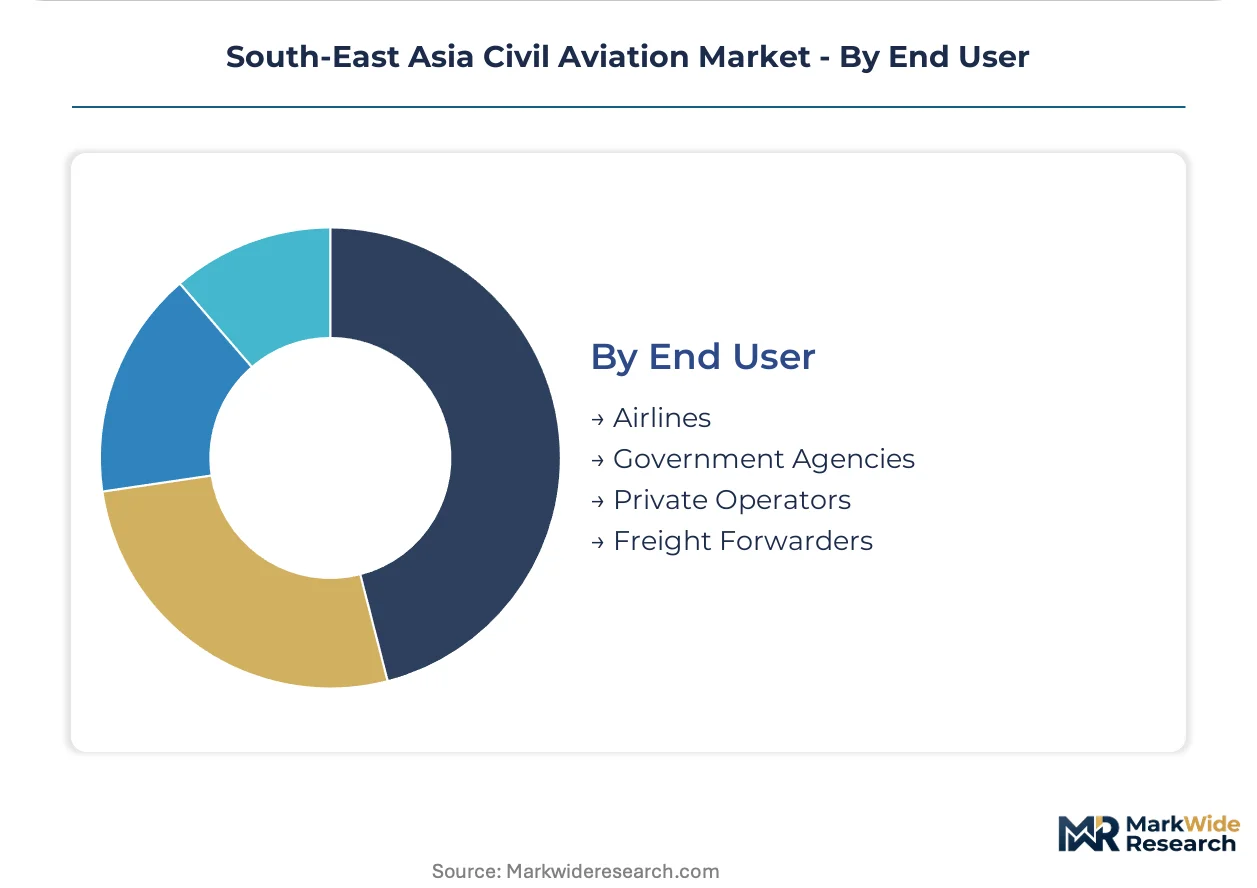
End User:
End user concentration reflects ownership structure divergence between state-subsidized flag carriers and privately capitalized low-cost operators.
- Airlines:Scheduled carriers—both full-service flag carriers and low-cost operators—account for the dominant aircraft demand across Indonesia, Vietnam, and the Philippines. Fleet decisions by Garuda Indonesia, Lion Air, and VietJet Air shape manufacturer order backlogs and MRO capacity planning.
- Government Agencies:Military transport conversions, maritime patrol platforms, and presidential fleet operations sustain specialized procurement channels outside commercial market dynamics.
- Private Operators:Corporate flight departments and high-net-worth individuals maintain business jet and turboprop fleets for point-to-point archipelago connectivity.
- Freight Forwarders:Logistics integrators and e-commerce platforms contract dedicated cargo capacity on scheduled freighter networks.
Airlines absorb the dominant capital deployment; Government Agencies is expanding fastest on share through defense modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive low-cost carriers in Indonesia and Vietnam drive volume procurement of narrowbody aircraft, while Singapore and Thai full-service operators absorb premium pricing for fleet modernization and MRO capability.
Indonesia
Archipelagic geography necessitates frequent short-haul connections between 17,000 islands, concentrating narrowbody orders at Jakarta's Soekarno-Hatta hub. The Directorate General of Civil Aviation enforces ICAO-aligned airworthiness standards that compress fleet renewal timelines. Surabaya and Makassar emerge as secondary maintenance clusters as MRO providers expand capacity for aging A320ceo heavy checks.
Vietnam
Rising middle-class air travel propels VietJet Air and Bamboo Airways toward aggressive narrowbody fleet expansion. The Civil Aviation Authority of Vietnam tightens environmental operating permits that complicate European type certificate compliance. Ho Chi Minh City's Tan Son Nhat airport anchors technical workforce development through Airbus regional training partnerships.
Singapore
Full-service carriers prioritize premium cabin configurations and MRO service exports across the ASEAN zone. EASA bilateral recognition agreements streamline type certification for European-manufactured aircraft entering the register. Seletar Aerospace Park concentrates predictive maintenance analytics and digital twin technology development for turbofan engine monitoring.
Thailand
Bangkok's Suvarnabhumi and Don Mueang airports sustain dual-hub narrowbody operations for trunk route density. EASA-Thai regulator alignment accelerates A320neo and 737 MAX fleet inductions without redundant certification testing. U-Tapao Rayong-Pattaya International Airport develops as a distributed parts warehousing node for unscheduled component replacement logistics.
Philippines
Runway-constrained secondary airports in Cebu and Davao sustain regional aircraft demand for thin-route obligations. The Civil Aviation Authority of the Philippines enforces divergent audit protocols that force parallel technical records maintenance. Clark International Airport near Manila concentrates cargo aircraft conversion activity for e-commerce fulfillment lanes.
South-East Asia Civil Aviation Market Competitive Landscape
Capability concentration sits with European and North American OEMs holding type certification authority; scale advantage sits with Asia-Pacific operators commanding narrowbody delivery slots. The market structures around three tiers: full-service airframers with integrated MRO networks, regional specialists serving runway-constrained airports, and state-backed challengers penetrating domestic procurement channels. Dominant competitive moves include EASA bilateral negotiation for accelerated certification and distributed warehousing partnerships for aftermarket parts positioning.
Within the full-service airframer tier, Airbus SE and The Boeing Company occupy positions as the primary narrowbody suppliers across Indonesian and Vietnamese registers. Embraer SA sits within the regional aircraft specialist tier, anchoring support contracts for thin-route operators in the Philippines and Myanmar. COMAC represents the state-backed challenger archetype, targeting domestic procurement channels as Chinese regulators negotiate parallel recognition frameworks with ASEAN aviation authorities.
| Leading Market Players |
|---|
| ATR |
| COMAC |
| Airbus SE |
| Lockheed Martin Corporation |
| De Havilland Aircraft of Canada Ltd. |
| The Boeing Company |
| Bombardier Inc. |
| Textron Inc. |
| Embraer SA |
| Others |
Value Network & Pricing Analysis
Overcapacity in Indonesian MRO hangars is compressing heavy-check pricing while forcing suppliers toward predictive service bundling. Narrowbody operators exploit this utilization slack to unbundle engine overhauls from airframe contracts, shifting negotiation leverage toward quarterly procurement cycles.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture as airlines unbundle heavy maintenance from OEM bundled agreements. Pricing stratifies across premium, standard, and economy tiers based on certification grade and geographic delivery cost. Cost compression in engine overhaul slots is intensifying because aging A320ceo and 737NG fleets simultaneously reach 12-year structural inspection intervals. Low-cost carriers exhibit the highest price sensitivity, while Singapore-based full-service operators absorb premium pricing for integrated MRO capability.
Supply Chain Analysis
Airbus and Boeing regional distribution centers in Singapore and Kuala Lumpur hold concentrated parts warehousing capacity for unscheduled component replacement. The supply chain draws from precision manufacturing clusters in Germany, France, and the United States for avionics and propulsion systems. Single-source vulnerability persists for LEAP-1A and PW1100G-JM powerplant modules where OEMs control proprietary repair schemes. Distribution runs through distributed warehousing nodes at Bangkok, Jakarta, and Manila to minimize aircraft-on-ground downtime across the archipelago.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-speed rail expansion across Vietnam and Thailand threatens short-haul route economics, forcing aviation incumbents to defend connectivity advantages through frequency and network density.
For Market Incumbents: Harden aftermarket revenue streams by deepening predictive maintenance analytics partnerships with Garuda Indonesia and VietJet Air. Lock in exclusive component life-extension contracts before low-cost carriers complete procurement team buildouts in Jakarta and Manila. Certification investment in CAAM-EASA alignment pathways protects type certificate authority against COMAC's state-backed challenger entry. For New Entrants and Emerging Players: Secondary airports in eastern Indonesia with runway limitations below 1,400 meters represent the most penetrable entry point for regional aircraft support contracts. Myanmar's thin-route obligations to flag carriers under CAAM restructuring create immediate white-space for dedicated maintenance partnerships. A go-to-market angle anchored to digital MRO platforms bypasses established parts warehousing incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among MRO providers with predictive analytics capabilities and distributed warehousing footprints. Long-term viability rests on technical workforce pipeline control through regional training center partnerships. The signal to watch is CAAM restructuring completion timelines in Myanmar and Vietnam, which will determine certification standardization feasibility across ASEAN jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Bilateral Negotiation | Streamlines type certification for A320neo and 737 MAX entry into Thai and Malaysian registers without redundant testing. |
| Predictive Maintenance Platform Deployment | Enables Garuda Indonesia and VietJet Air to extend on-wing time for CFM56 and V2500 powerplants through digital twin integration. |
| Distributed Parts Warehousing Expansion | Positions Kuala Lumpur and Bangkok nodes for unscheduled component replacement logistics across Indonesian archipelago routes. |
| Regional Training Center Partnership | Sustains technical workforce pipelines for airframe and powerplant certificated mechanics through Singapore-based Airbus facilities. |
| Thin-Route Support Contract Specialization | Captures flag carrier obligations to secondary airports in the Philippines and Myanmar where runway limitations exclude mainline equipment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ICAO safety audit reports, EASA bilateral agreement documentation, and ASEAN customs trade data. Primary interviews engaged fleet planning executives at Indonesian and Vietnamese low-cost carriers, MRO operations directors in Singapore and Kuala Lumpur, and regulatory affairs leads at national aviation authorities across five ASEAN states. Secondary validation drew from Directorate General of Civil Aviation airworthiness directives, CAAM restructuring disclosures, and airline procurement tender databases. Bottom-up fleet order analysis and top-down regional economic projections were triangulated against manufacturer delivery backlogs.
Forecast inputs include narrowbody fleet renewal timelines, MRO capacity utilization rates, and EASA-CAAM certification alignment progress across the projection horizon. Segmentation dimensions modeled encompass aircraft type, service category, technology retrofit cycle, and end-user ownership structure. CAGRs were derived from compound growth trajectory analysis of historical fleet data and projected middle-class air travel expansion. Industry-specific inputs incorporate jet fuel benchmark volatility and technical workforce graduation rates from regional training centers.
Stress conditions across regulatory fragmentation persistence, currency fluctuation severity, and high-speed rail corridor completion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EASA bilateral expansion timelines and CAAM restructuring completion. Quarterly review of fleet induction delays, MRO slot availability, and environmental permit tightening is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aviation and Defense Training and Simulation
US Helicopter Services Market
Aviation and Defense Training and Simulation
Middle-East and Africa Jet Charter Services Market
Aviation and Defense Training and Simulation
Helicopter Services Market
Aviation and Defense Training and Simulation
Domestic Aviation Market
Aviation and Defense Training and Simulation
Global Airlines Market
Aviation and Defense Training and Simulation
Charter Jet Services Market
Aviation and Defense Training and Simulation
North America Charter Jet Services Market
Aviation and Defense Training and Simulation
Digital Aviation Market