
 General Aviation Market | 2026-2036
General Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
General Aviation Market Intelligence
Aftermarket service revenue is rewriting how OEMs capture lifetime value from airframes. Textron Aviation leverages its Beechcraft and Cessna installed base to sustain parts and service dominance across North America. StandardAero anchors the independent MRO channel with specialized engine overhaul capabilities. Cirrus Aircraft differentiates through its CAPS parachute system and integrated flight training ecosystem.
General aviation encompasses non-scheduled civil aviation operations utilizing aircraft with maximum takeoff weights below regional jet thresholds, typically piston or turboprop propulsion with cruise speeds ranging from 120 to 400 knots, serving private transport, flight instruction, aerial work, and emergency medical roles. Fixed-wing platforms retain the largest revenue share while rotorcraft command premium unit economics in emergency services and offshore energy support. Flight schools represent a structurally growing end-user segment as pilot shortage intensifies training capacity expansion. Avionics technology generates outsized margin pools as glass cockpit retrofits and ADS-B compliance mandates sustain aftermarket demand.
FAA Part 23 reform streamlines certification for small airplanes, while EASA CS-23 alignment reduces dual-certification burdens for European market access. ASTM consensus standards govern light sport aircraft airworthiness, lowering barriers for innovative designs. Stakeholders must monitor emerging eVTOL type certification pathways and their potential convergence with traditional general aviation operational frameworks.
Market Dynamics
Fleet renewal cycles across North American business aviation are compressing as fractional ownership models mature and advanced air mobility infrastructure attracts capital deployment toward next-generation platforms.
Growth Catalysts
- FAA Part 23 Reform:Streamlined certification pathways for small airplanes reduce development timelines and enable faster market entry for innovative airframe designs.
- Fractional Ownership Programs:Asset-light access models expand the addressable buyer base beyond traditional full-aircraft purchasers into corporate flight departments.
- Glass Cockpit Retrofits:Mandated ADS-B compliance and avionics modernization sustain aftermarket demand across the installed piston and turboprop fleet.
Market Restraints
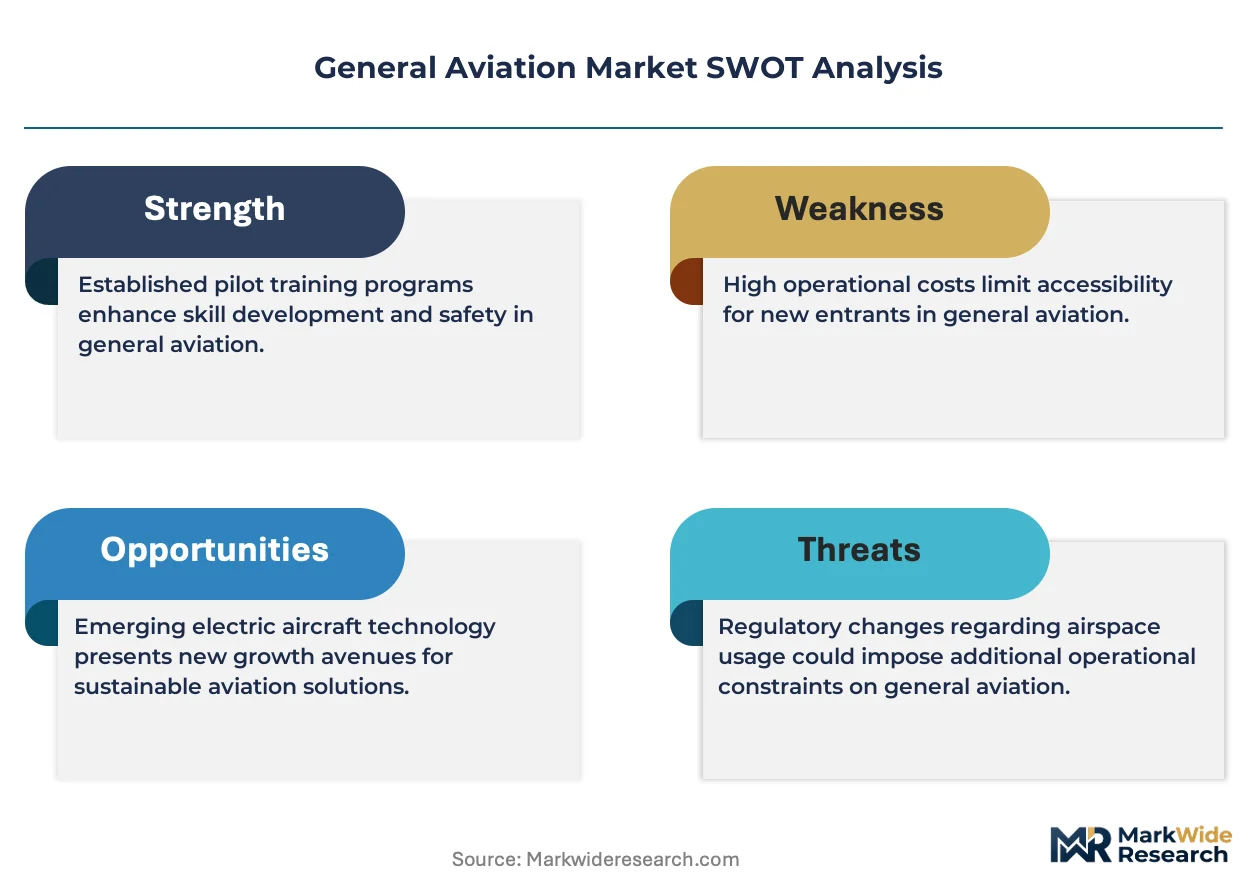
- Aviation Fuel Price Volatility:Jet A and avgas cost swings compress operating margins for flight schools and charter operators with limited fuel surcharge pass-through.
- Certification Timeline Friction:FAA type certification processes for novel propulsion systems create extended cash consumption periods before revenue recognition.
- Pilot Training Bottlenecks:Certified flight instructor availability constraints limit flight school capacity expansion despite student demand accumulation.
Strategic Opportunities
- Electric Propulsion Convergence:Battery-electric and hybrid-electric architectures open new mission profiles for urban air mobility and regional shuttle services.
- Flight Training Ecosystem Integration:Vertically structured pilot pipelines combining simulators, airframes, and career placement capture lifetime value from student enrollment.
- Emergency Medical Services Expansion:Helicopter air ambulance networks in underserved rural corridors address healthcare access gaps with premium unit economics.
Industry Challenges
- Airframe Technician Shortage:Aging maintenance workforce and limited apprenticeship pipeline create MRO capacity constraints during peak seasonal demand.
- Legacy Fleet Integration Complexity:Retrofitting aging piston aircraft with modern avionics requires structural modifications that extend downtime and escalate modification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | General Aviation Market |
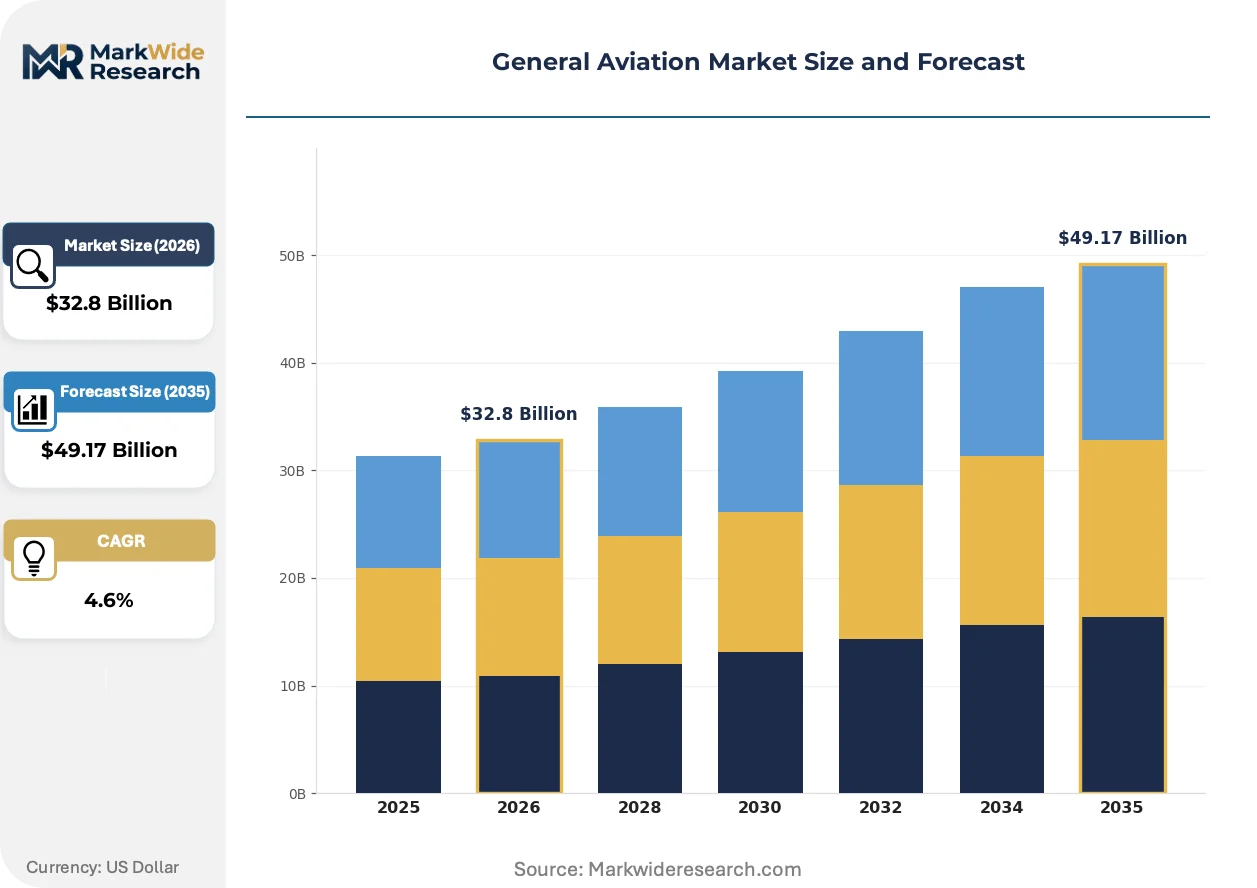
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Fixed-Wing, Rotorcraft, Light Sport, Ultralight End User: Private Owners, Flight Schools, Charters, Commercial Operators Service Type: Maintenance, Pilot Training, Charter Services, Aircraft Management Technology: Avionics, Flight Control Systems, Safety Systems, Engine Technologies |
| Companies Covered | Cirrus Aircraft, Beechcraft, Textron Aviation, Leonardo Helicopters, Airbus Helicopters, Bombardier, Piper Aircraft, StandardAero, Embraer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
General Aviation Market Strategic Shifts & Innovations
Aviation propulsion architectures are undergoing fundamental recalibration as electric and hybrid systems challenge conventional piston and turboprop dominance in specific mission profiles.
Digital engine monitoring systems with predictive maintenance algorithms are rendering obsolete scheduled overhaul intervals based on flight hours alone. Corporate flight departments and charter operators are adopting these connected platforms to minimize unscheduled downtime. The shift compresses MRO revenue recognition patterns while improving dispatch reliability for high-utilization aircraft.
EASA CS-23 alignment with FAA Part 23 reform reduces dual-certification burdens for manufacturers seeking European market access. This regulatory harmonization lowers development costs for small airplane programs. Light sport aircraft producers benefit most directly, with several designs now achieving concurrent type acceptance across both jurisdictions.
Flight schools are unbundling traditional all-inclusive training packages into modular, pay-as-you-progress structures. This model attracts career-switcher demographics with limited upfront capital and aligns revenue recognition with actual instruction delivery. The approach is most visible in United States markets where student financing alternatives remain underdeveloped relative to university aviation programs.
General Aviation Market Segmentation
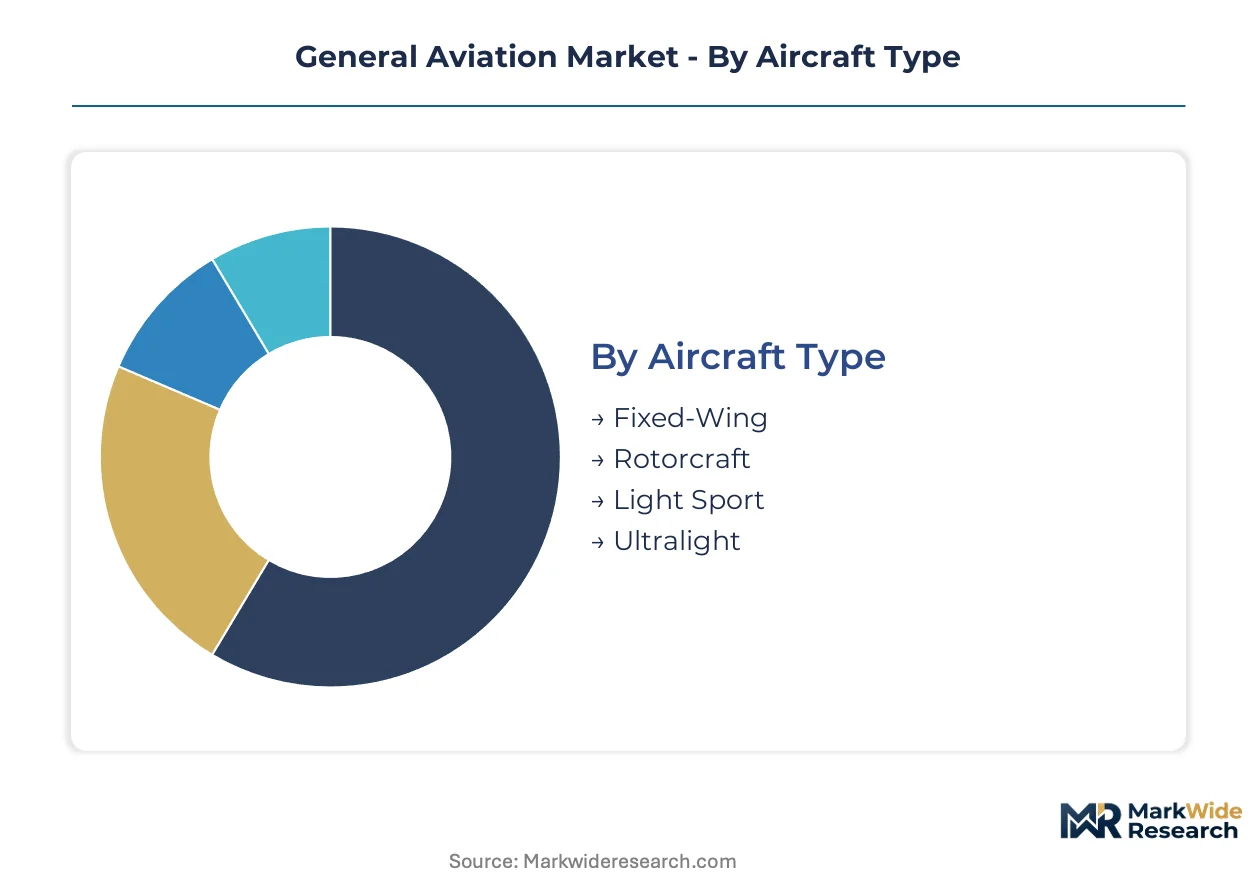
Segmentation in general aviation reveals distinct operational economics across aircraft configurations and service models. Each dimension exposes different margin structures, regulatory exposure, and capital intensity requirements for market participants.
Aircraft Type:
Use cases span from recreational weekend flying to emergency medical evacuation, with each platform optimized for specific mission profiles and payload-range requirements.
- Fixed-Wing:Piston and turboprop configurations dominate business transport and flight training with cruise speeds between 120 and 400 knots. Demand concentrates in the United States where fractional ownership programs and corporate flight departments sustain fleet renewal cycles.
- Rotorcraft:Helicopter platforms command premium unit economics in emergency medical services and offshore energy support. Demand clusters in rural healthcare corridors and Gulf of Mexico oil operations where vertical lift capability justifies operating cost premiums.
- Light Sport:ASTM consensus standards govern these two-seat aircraft with maximum takeoff weights below 1,320 pounds. Recreational pilots and sport aviation enthusiasts drive volume in uncontrolled airspace operations.
- Ultralight:Part 103 exempt aircraft operate under minimal regulatory burden with single-seat configurations and fuel capacity restrictions. Hobbyist builders and experimental aviation communities sustain niche demand.
The dominant share belongs to Fixed-Wing, while Rotorcraft is closing the gap fastest through healthcare access expansion.
End User:
Customer economics diverge sharply between asset owners seeking depreciation benefits and operators optimizing for hourly utilization rates.
- Private Owners:Individual and family purchasers prioritize cabin comfort, avionics sophistication, and residual value retention. Tax-advantaged ownership structures in the United States sustain demand for high-end piston and turboprop aircraft.
- Flight Schools:Certified training organizations operate high-cycle fleets with emphasis on dispatch reliability and standardized maintenance protocols. Pilot shortage pressures are forcing capacity expansion across Florida, Texas, and Arizona training hubs.
- Charters:On-demand air taxi and corporate shuttle operators maximize aircraft utilization through dynamic scheduling. Part 135 certificate holders concentrate in metropolitan corridors connecting secondary cities.
- Commercial Operators:Aerial application, survey, and patrol services deploy specialized mission equipment. Agricultural spraying and pipeline inspection contracts sustain turboprop demand in the Midwest and Great Plains.
Private Owners retain the largest installed base, though Flight Schools are expanding most quickly amid instructor pipeline investments.
Service Type:
Revenue recognition patterns vary from transactional hourly instruction to recurring long-term management contracts.
- Maintenance:Airframe, engine, and component overhaul services generate recurring revenue from mandatory inspection intervals. FAA Part 145 repair stations and independent MROs compete across piston, turboprop, and jet engine specializations.
- Pilot Training:Flight and ground instruction combined with simulator-based curricula produce certified pilots through modular progress structures. Career-switcher demographics are driving pay-as-you-progress unbundling in United States markets.
- Charter Services:Aircraft and crew provision for on-demand transport commands premium pricing over scheduled alternatives. Brokerage platforms and direct operators compete for corporate account contracts.
- Aircraft Management:Turnkey operational support for owner-flown aircraft includes crew scheduling, maintenance oversight, and regulatory compliance. High-net-worth individuals and corporate flight departments outsource complexity to specialist providers.
Maintenance commands the dominant revenue share, while Pilot Training is climbing the fastest through simulator integration and career pathway investments.
Technology:
Technology segmentation tracks where innovation investment concentrates and where regulatory mandates force fleet-wide upgrades.
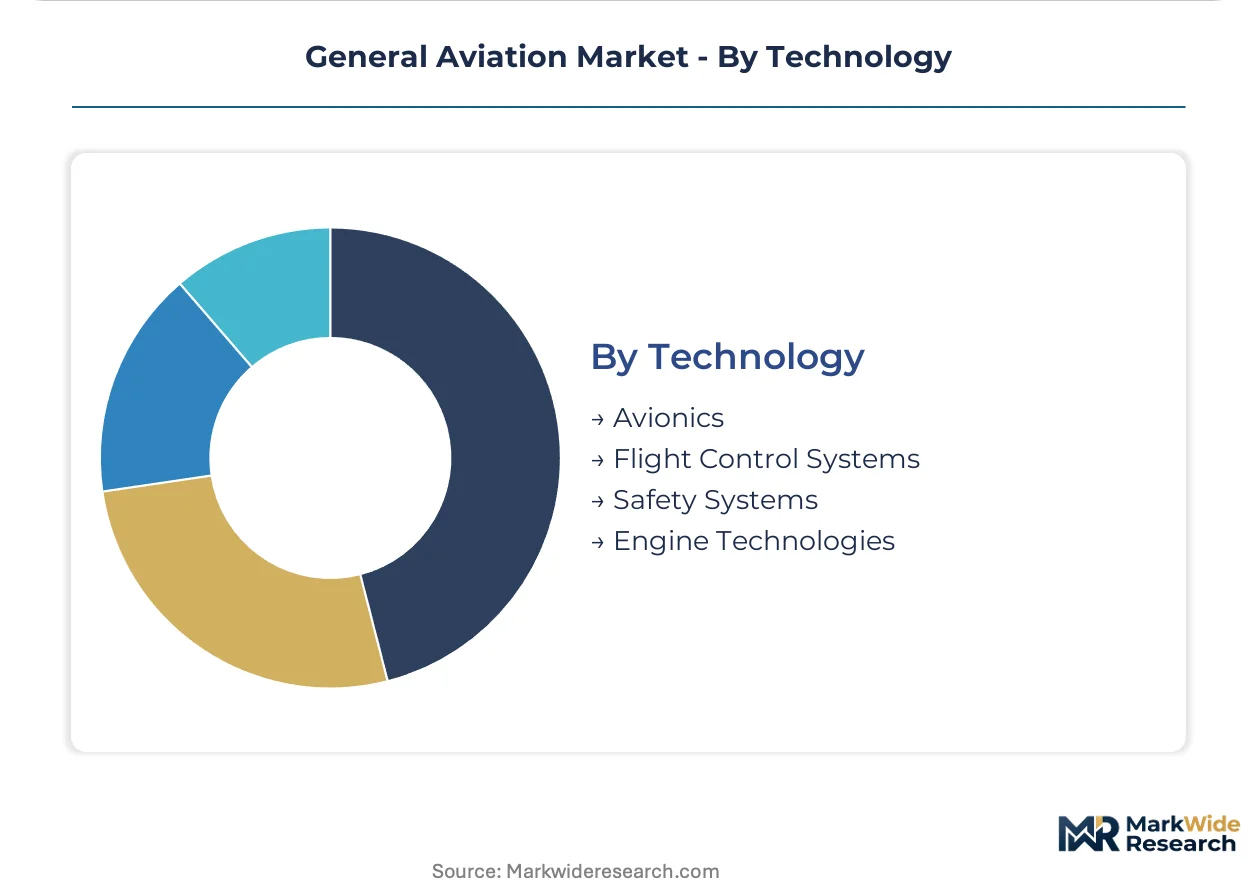
- Avionics:Glass cockpit displays, GPS navigation, and ADS-B transponders constitute the largest aftermarket spend category. Mandated ADS-B Out compliance has sustained retrofit demand across legacy piston fleets.
- Flight Control Systems:Digital fly-by-wire and stability augmentation technologies migrate from transport aircraft into high-end general aviation platforms. Cirrus Aircraft and similar OEMs integrate envelope protection and autoland capabilities.
- Safety Systems:Whole-airframe parachutes, terrain awareness systems, and automated emergency descent functions differentiate premium offerings. CAPS deployment data supports insurance rate advantages for equipped aircraft.
- Engine Technologies:Piston, turboprop, and emerging electric propulsion architectures compete across mission profiles. Diesel cycle and hybrid-electric systems challenge conventional avgas dependence for efficiency-conscious operators.
Avionics holds the dominant technology spend position, while Engine Technologies is gaining share fastest through electrification development programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
General aviation consumption patterns diverge sharply across geographies. The United States centers on fractional ownership and business transport, while European markets emphasize flight training and emergency medical services. Emerging economies prioritize aerial work applications and infrastructure connectivity over corporate aviation.
United States
Fractional ownership programs and corporate flight departments drive turboprop and light jet demand. FAA Part 23 reform accelerates certification timelines for innovative airframe designs. Wichita, Kansas anchors manufacturing concentration with Textron Aviation and Beechcraft production facilities.
Germany
Flight training organizations and aerial survey operators constitute the primary demand base. EASA CS-23 alignment with FAA standards reduces dual-certification burdens for manufacturers. Bavaria clusters maintenance, repair, and overhaul capabilities around Munich and Augsburg.
Brazil
Agricultural spraying and remote infrastructure access dominate operational profiles. ANVISA coordinates with aviation regulators on aerial application safety standards. São Paulo state concentrates charter and corporate aviation services around Congonhas and Campo de Marte airports.
Australia
Cattle station transport, mining crew rotation, and emergency medical retrieval sustain rotorcraft demand. CASA mandates ADS-B compliance across remote area operations. Queensland and Western Australia host the densest air ambulance network coverage.
United Arab Emirates
Luxury tourism and executive transport concentrate demand in Dubai and Abu Dhabi. GCAA streamlines business aviation licensing for international operators. Al Maktoum International Airport anchors the region's largest dedicated general aviation terminal infrastructure.
General Aviation Market Key Industry Players
Capability concentration sits with established airframe manufacturers holding type certification expertise; scale advantage sits with diversified aerospace conglomerates leveraging cross-program engineering resources. The market structures around three archetypes: integrated OEMs with captive MRO networks, independent airframe specialists, and engine overhaul providers. Consolidation moves center on aftermarket service integration and flight training ecosystem capture.
Within the integrated OEM tier, Textron Aviation and Cirrus Aircraft exemplify vertically structured competitors combining manufacturing with lifetime service revenue. StandardAero anchors the independent maintenance channel. These three occupy positions spanning the value chain from initial airframe delivery through decades of operational support.
| Leading Market Players |
|---|
| Cirrus Aircraft |
| Beechcraft |
| Textron Aviation |
| Leonardo Helicopters |
| Airbus Helicopters |
| Bombardier |
| Piper Aircraft |
| StandardAero |
| Embraer |
| Others |
Cost & Logistics Intelligence
Wichita, Kansas anchors North American airframe manufacturing capacity, and its production concentration grants OEMs substantial pricing leverage over downstream buyers. Textron Aviation and Beechcraft command premium positioning through captive parts distribution networks that constrain independent MRO alternatives. This geographic clustering shapes how fractional ownership programs and flight schools negotiate fleet acquisition economics.
Pricing Analysis
Long-term fleet purchase agreements dominate new airframe transactions, while spot-market charter rates adjust hourly based on seasonal demand and fuel cost pass-through structures. Three-tier pricing structure across premium turboprops, standard piston aircraft, and economy light-sport tiers reflects certification complexity and avionics sophistication. Cost compression in the training-aircraft segment is intensifying because flight schools prioritize dispatch reliability over brand premium. Charter operators exhibit the highest price sensitivity due to thin operating margins, whereas corporate flight departments prioritize residual value retention and service bundling.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for avionics components and precision-machined parts. Manufacturing concentrates in the United States, Germany, and Brazil, with each hub specializing in distinct aircraft categories and certification ecosystems. Airframe production draws from aluminum sheet, composite pre-preg, and avionics semiconductor inputs. Single-source vulnerability persists for FAA-certified engine control systems and glass cockpit displays. Distribution runs through OEM-authorized dealers, independent FBO networks, and direct-to-operator digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story because FAA type certification creates prohibitive switching costs that lock operators into manufacturer service ecosystems for decades.
For Market Incumbents: Entrench certification expertise as a barrier by accelerating ASTM consensus standard adoption for light-sport variants and expanding captive MRO capacity in Florida and Texas training corridors. Battery-electric propulsion startups threaten traditional engine overhaul revenue streams. Vertical integration into flight training simulators captures lifetime student value from enrollment through airline placement. For New Entrants and Emerging Players: Pursue modular avionics retrofit packages for legacy piston fleets as the most penetrable aftermarket segment, where ADS-B compliance mandates force upgrade decisions. Rural helicopter emergency medical services present underserved geography with premium unit economics and limited incumbent saturation. Partner with established Part 145 repair stations for distribution rather than building captive service networks from zero. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because airframe longevity and mandatory inspection intervals generate predictable aftermarket cash flows regardless of new-unit cyclicality. Target acquisition profile centers on independent MRO specialists with engine overhaul certifications and established relationships with fractional ownership fleets. Monitor FAA electric propulsion type certification timelines as the critical signal for disruptive platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Flight Training Ecosystem Integration | Captures lifetime pilot value from initial enrollment through airline placement partnerships. |
| Electric Propulsion Certification Investment | Positions manufacturers for FAA type acceptance of battery-electric and hybrid architectures. |
| Independent MRO Network Acquisition | Extends aftermarket service reach beyond captive dealer channels into high-utilization fleets. |
| Glass Cockpit Retrofit Platform Launch | Addresses mandated ADS-B compliance across aging piston aircraft installed base. |
| Fractional Ownership Program Partnership | Secures fleet renewal commitments from asset-light corporate flight departments. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with aircraft OEM product strategists, Part 145 repair station operators, fractional ownership fleet managers, and certified flight instructors; and secondary validation through FAA type certificate databases, EASA CS-23 regulatory filings, NTSB safety incident reports, and OEM annual disclosures. Bottom-up triangulation across aircraft registration data and top-down reconciliation against fleet utilization surveys anchored volume estimates.
Forecast inputs considered aircraft type segmentation across fixed-wing, rotorcraft, and emerging electric platforms; end-user categories spanning private owners, flight schools, charter operators, and commercial services; and technology dimensions including avionics, propulsion architecture, and safety systems. CAGRs were derived from fleet replacement cycle analysis and training capacity expansion models across the projection horizon. Jet A and avgas price volatility assumptions, instructor availability constraints, and electric propulsion certification timelines shaped scenario boundaries.
Sensitivities concentrate around FAA electric aircraft certification pace, aviation fuel cost trajectories, and flight school instructor pipeline expansion. Forecasts reflect documented assumptions about fleet retirement rates and fractional ownership program growth. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Cargo Winches Market
Aircraft
Wireless in-Flight Entertainment Market
Aircraft
Aircraft Ailerons Market
Aircraft
Global Aircraft Heat Exchanger Market
Aircraft
Commercial Aircraft Landing Gear Market
Aircraft
Middle East and Africa Aviation Market
Aircraft
Aircraft Oxygen System Market
Aircraft
Commercial Aircraft Aerostructures Market
Aircraft
Latin America Commercial Aircraft Market
Aircraft
Aircraft Radome Market
Aircraft
Asia-Pacific Attack Helicopter Market
Aircraft
Commercial Aircraft Wing Market
Aircraft
Global Commercial Aircraft Disassembly Market
Aircraft
Latin America Business Jet Market
Aircraft
Global Aircraft Towbars Market
Aircraft
Global Helicopter Market