
 Asia-Pacific Frozen Pizza Market | 2026-2036
Asia-Pacific Frozen Pizza Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Frozen Pizza Market Insights
Subscription-based replenishment services for frozen pizza is decoupling volume from traditional retail foot traffic across Asia-Pacific markets. Nestlé SA leverages its cold-chain logistics network to sustain shelf dominance in Japanese convenience stores. Dr. Oetker anchors premium positioning through localized topping portfolios calibrated to Korean and Australian palates. McCain Foods Ltd competes on manufacturing scale, operating production facilities that supply private-label programs for regional supermarket chains.
Asia-Pacific frozen pizza comprises par-baked or fully baked dough platforms topped with sauces, cheeses, and proteins, then blast-frozen at minus 18 to minus 30 degrees Celsius to arrest microbial activity and preserve texture. The product serves as a ready-to-heat meal solution for time-constrained households and food-service operators seeking kitchen labor reduction. Thin crust variants occupy the largest volume share due to lower production cost and faster bake times, while gluten-free and cauliflower crust formulations capture expanding margin pools from health-conscious urban consumers in Australia and Japan. Online retail channels represent the fastest-growing distribution vector, though hypermarkets retain the dominant transaction volume across Southeast Asian markets.
Japan's Ministry of Health, Labour and Welfare enforces strict frozen food labeling and additive standards that elevate compliance costs for imported pizza products. China's SAMR and NMPA coordinate on cold-chain sanitation protocols that determine market access eligibility for foreign manufacturers. Australia's FSANZ mandates nutritional panel disclosures that influence reformulation priorities for brands targeting health-positioned segments. Stakeholders must monitor evolving plant-based certification requirements and last-mile frozen delivery infrastructure investments as the primary determinants of competitive viability.
Market Dynamics
Subscription-based replenishment services are decoupling frozen pizza volume from traditional retail foot traffic across Asia-Pacific metropolitan markets, forcing manufacturers to reconfigure distribution partnerships and cold-chain investments toward direct-to-consumer fulfillment infrastructure.
Growth Catalysts
- China's NMPA cold-chain sanitation protocols:Upgraded import standards are filtering out non-compliant foreign suppliers, creating shelf space for certified manufacturers in premium supermarket channels.
- Quick-service restaurant segment in India:Labor cost pressures and kitchen standardization drives are accelerating frozen pizza adoption as a prep-time reduction solution.
- Blast-freezing at minus 18 to minus 30 degrees Celsius:Advances in cryogenic freezing technology are preserving texture quality across extended distribution distances, enabling regional hub-and-spoke supply models.
Market Restraints
- Wheat and dairy input volatility:Frozen pizza margins compress when Australian and New Zealand dairy futures spike, forcing reformulation or price pass-through decisions.
- Japan's Ministry of Health, Labour and Welfare labeling standards:Strict additive disclosure requirements elevate compliance costs for imported products, disadvantaging smaller foreign manufacturers.
- Thin crust commoditization:Low production cost and minimal differentiation are trapping volume share in margin-diluted segments across Southeast Asian hypermarkets.
Strategic Opportunities
- India's underserved quick-service pizza segment:Cold-chain infrastructure gaps in tier-two cities create first-mover advantages for manufacturers investing in localized blast-freezing capacity.
- Australia's FSANZ plant-based certification pathway:Emerging regulatory clarity on vegan cheese and meat-analog toppings is opening premium positioning for reformulated products.
- Online retail channel convergence with last-mile frozen logistics:Partnerships with temperature-controlled delivery platforms are unlocking subscriber bases unreachable through traditional retail.
Industry Challenges
- Cold-chain engineering talent scarcity:Qualified technicians for minus 30-degree blast-freezer maintenance are concentrated in Japan and South Korea, constraining facility expansion in emerging markets.
- Legacy ERP integration with subscription billing platforms:Manufacturers relying on decades-old inventory systems face data fragmentation when connecting to direct-to-consumer order management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Frozen Pizza Market |
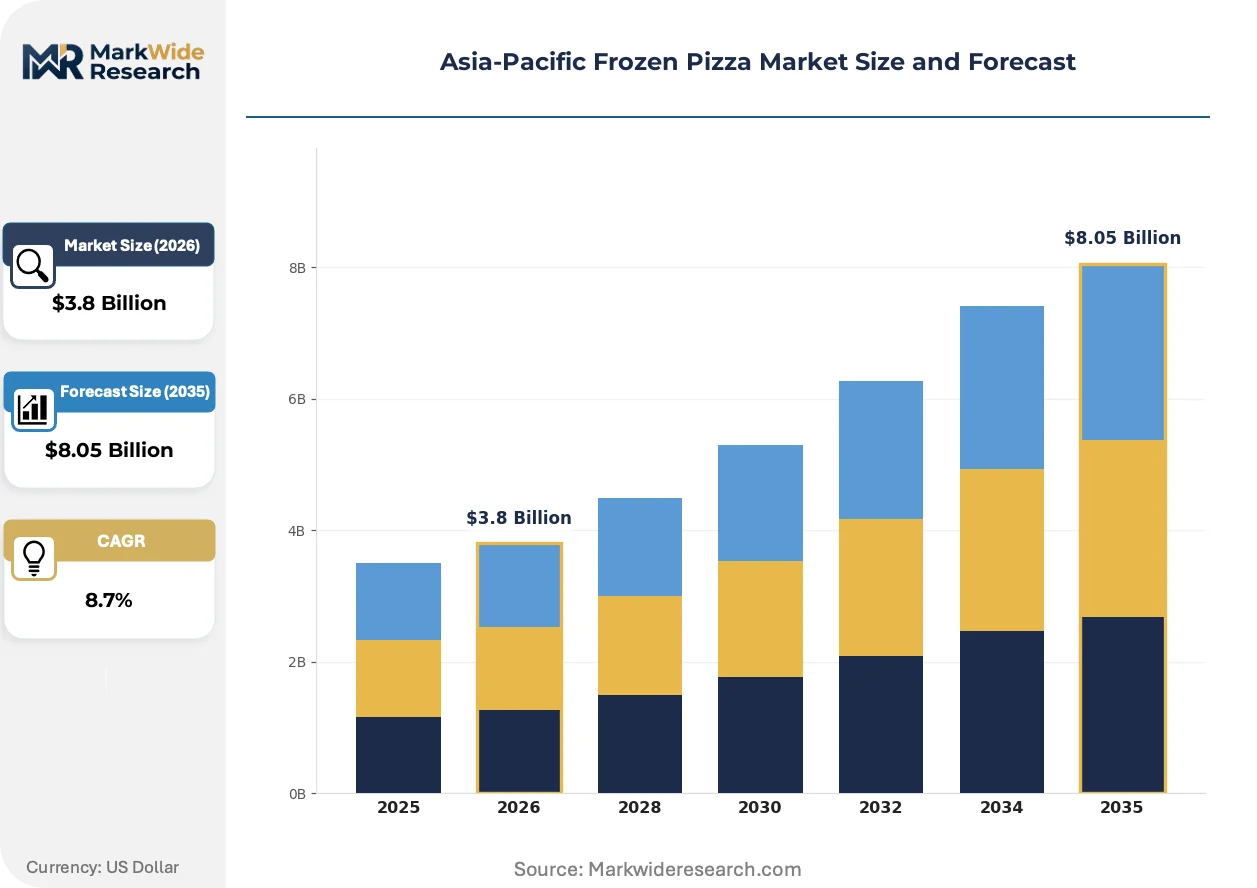
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Crust, Stuffed Crust, Gluten-Free, Cauliflower Crust Customer Type: Retail Consumers, Food Service, Restaurants, Supermarkets Distribution Channel: Online Retail, Hypermarkets, Convenience Stores, Specialty Stores Price Tier: Premium, Mid-Range, Value, Budget |
| Companies Covered | Nestlé SA, Dr. Oetker, McCain Foods Ltd, General Mills, Conagra Brands, California Pizza Kitchen, Daiya Foods Inc, Freiberger Lebensmittel GmbH Co, Bellisio Foods Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Frozen Pizza Market Trends and Innovations
Digital subscription platforms and precision freezing technologies are converging to reshape how frozen pizza reaches Asia-Pacific consumers, with regulatory pressure on ingredient transparency accelerating product reformulation cycles.
Individual quick-freezing (IQF) technology for pizza toppings is decentralizing production geography across the Asia-Pacific region. Japanese and South Korean manufacturers are adopting modular IQF units for localized topping preparation, reducing cross-border ingredient shipments. This technology is decentralizing supply chain risk by enabling smaller regional production facilities to match the quality consistency previously concentrated in large centralized plants.
Australia's FSANZ nutritional panel disclosure mandates are forcing reformulation of sodium and saturated fat levels in frozen pizza targeting health-positioned segments. Manufacturers must now submit detailed compositional data before market entry, extending product development timelines. Premium brands in Australian supermarkets are responding by accelerating clean-label topping portfolios to preempt regulatory scrutiny.
Subscription-based replenishment services are compressing purchase cycles among metropolitan households in Tokyo, Sydney, and Seoul. Traditional hypermarket and convenience store channels are losing transaction frequency to algorithm-driven reorder platforms that anticipate consumption patterns. This shift is most visible in Japan's convenience store sector, where frozen pizza shelf space is contracting as manufacturers redirect inventory to fulfillment centers serving subscriber bases.
Asia-Pacific Frozen Pizza Market Segmentation
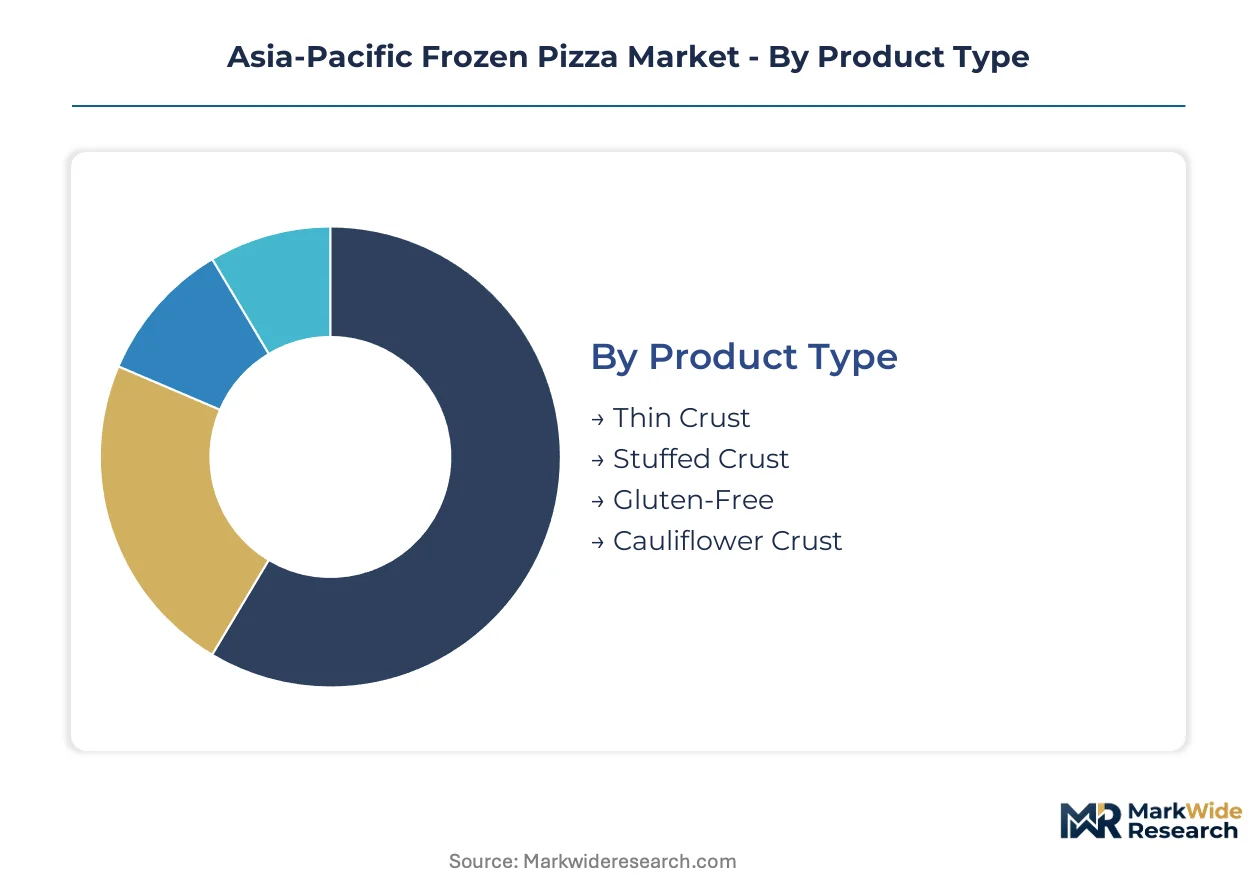
Segmentation in the Asia-Pacific frozen pizza market reveals how capital deployment, regulatory compliance, and cold-chain infrastructure requirements vary sharply across product formats and channel strategies. Manufacturers must align production investments with the specific freezing protocols and distribution economics of their target segments.
Product Type:
Capital intensity diverges dramatically across crust platforms, with cryogenic freezing equipment and dough conditioning systems representing the primary fixed-cost differentiators.
- Thin Crust:Par-baked wheat-based dough sheets require standard blast-freezing tunnels operating at minus 18 degrees Celsius. Australian and Japanese retail consumers drive volume through supermarket channels where bake-time speed determines repeat purchase.
- Stuffed Crust:Cheese-injection forming equipment and dual-zone freezing lines demand 40-60% higher capital outlay than thin crust equivalents. South Korean premium supermarkets absorb the majority of regional output as consumers trade up for differentiated texture.
- Gluten-Free:Dedicated allergen-control production lines with segregated ingredient handling and certification documentation.
- Cauliflower Crust:Vegetable-base extrusion systems and modified atmosphere packaging for moisture retention.
Thin Crust absorbs the bulk of installed capacity; Cauliflower Crust is expanding most quickly.
Customer Type:
Application-specific freezing protocols and order-fulfillment economics separate segments by working capital intensity and inventory turnover velocity.
- Retail Consumers:Individual-portion packaging and consumer-grade labeling compliance dominate. Japanese convenience stores and Australian supermarkets command strict shelf-life dating and nutritional panel accuracy per FSANZ and Ministry of Health, Labour and Welfare standards.
- Food Service:Bulk-format frozen pizza with institutional-grade portioning and extended holding-temperature tolerance. India's quick-service restaurant operators prioritize prep-time reduction over crust premiumization.
- Restaurants:Custom topping configurations and private-label branding capabilities with chef-collaboration development cycles.
- Supermarkets:Own-brand program manufacturing with promotional calendar flexibility and seasonal variety rotation.
Retail Consumers command the greatest absolute volume; Food Service is climbing the fastest as labor-cost pressures accelerate kitchen automation.
Distribution Channel:
Last-mile temperature integrity requirements and fulfillment infrastructure costs create tiered capital barriers to channel participation.
- Online Retail:Algorithm-driven subscription platforms and temperature-controlled last-mile delivery partnerships. Tokyo, Sydney, and Seoul metropolitan households are compressing purchase cycles through automated replenishment services that bypass traditional retail foot traffic.
- Hypermarkets:Pallet-scale cold-storage handoffs and promotional display logistics. Southeast Asian markets retain dominant transaction volume through centralized frozen-food sections with high-visibility aisle placement.
- Convenience Stores:High-frequency, small-format restocking with limited freezer-door facing competition.
- Specialty Stores:Curated premium assortments with artisan positioning and localized import sourcing.
Hypermarkets retain the greatest frozen-door capacity; Online Retail is gaining share fastest as direct-to-consumer cold-chain investments mature.
Price Tier:
Margin structure and ingredient cost exposure stratify manufacturing economics across premium and value-positioned production lines.
- Premium:Imported cheese blends, specialty protein toppings, and extended-fermentation dough processes. Australian health-positioned consumers and South Korean supermarket shoppers validate price premiums through clean-label certification and provenance storytelling.
- Mid-Range:Balanced reformulation flexibility with domestic dairy sourcing and regional topping adaptation.
- Value:Cost-optimized recipes with vegetable-fat cheese analogs and streamlined distribution logistics.
- Budget:Minimal ingredient specification variance and maximum production-line throughput prioritization.
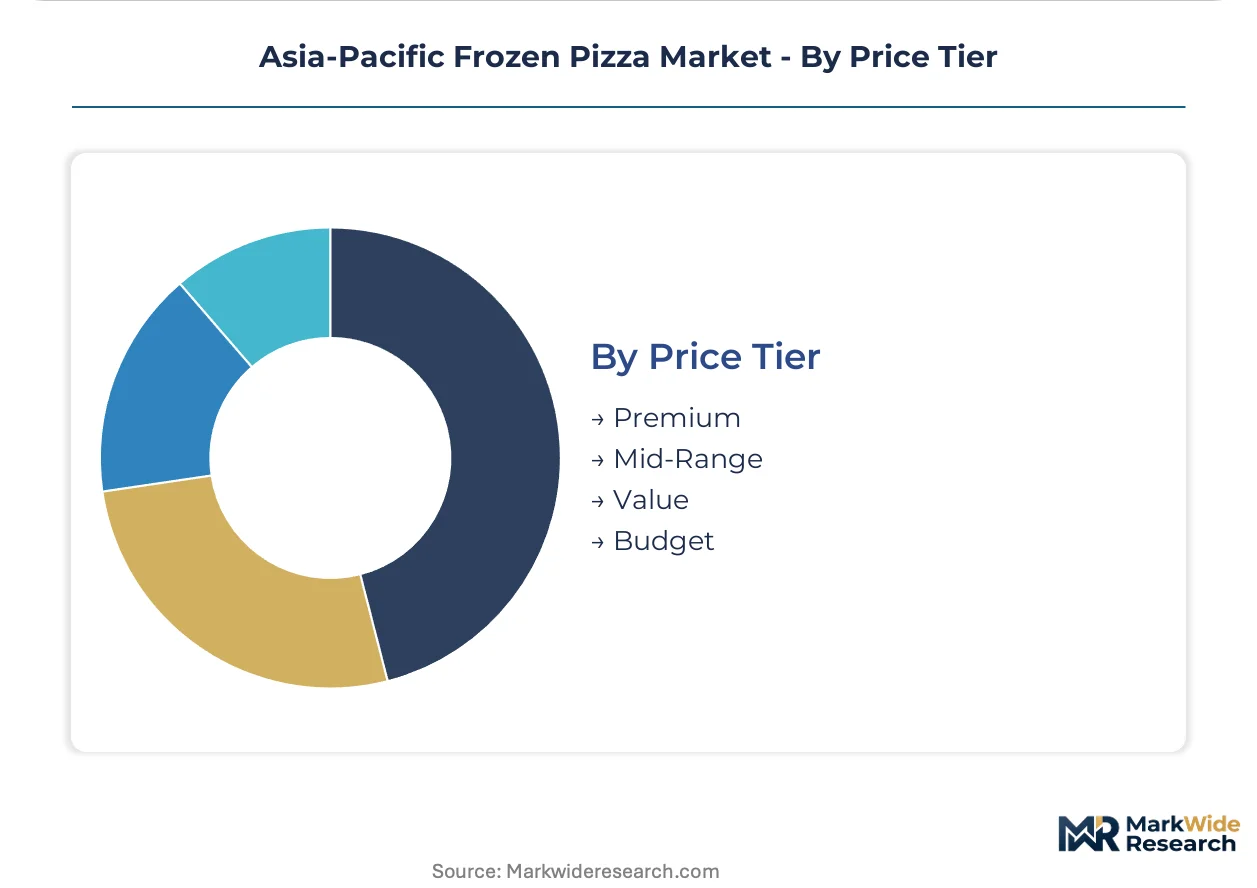
Mid-Range captures the widest manufacturing base; Premium is expanding most quickly as FSANZ disclosure mandates and consumer ingredient scrutiny intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Australia and Japan while consumption growth concentrates in India and Southeast Asian metropolitan corridors. Cold-chain infrastructure investments are redrawing distribution economics across the region.
China
Quick-service restaurant chains and premium supermarket channels are absorbing imported frozen pizza volumes at accelerating rates. SAMR and NMPA coordinate on cold-chain sanitation protocols that filter non-compliant foreign suppliers from coastal port entry points. Yangtze River Delta logistics hubs near Shanghai are expanding blast-freezing capacity to serve domestic reformulation demand.
Japan
Convenience store operators and subscription-based metropolitan households dominate purchase frequency in Tokyo and Osaka corridors. The Ministry of Health, Labour and Welfare enforces additive disclosure standards that elevate compliance costs for imported products. Kanto region distribution centers are redirecting inventory from retail freezer doors to direct-to-consumer fulfillment infrastructure.
India
Quick-service restaurant kitchen automation and labor cost pressures are accelerating frozen pizza adoption as prep-time reduction solutions. FSSAI labeling and cold-chain regulations are tightening import pathway requirements for foreign manufacturers. Tier-two cities in Maharashtra and Karnataka present first-mover opportunities for localized blast-freezing facility investments.
Australia
Health-positioned retail consumers and FSANZ disclosure mandates are driving reformulation toward clean-label topping portfolios. Nutritional panel requirements are extending product development timelines for market entry. Sydney and Melbourne metropolitan supermarkets are contracting shelf space for premium plant-based certified variants.
South Korea
Premium supermarket channels and localized topping preferences are absorbing stuffed-crust and specialty protein variants at premium price points. MFDS food safety standards influence import certification timelines for foreign manufacturers. Seoul Capital Area distribution networks are integrating temperature-controlled last-mile delivery partnerships for subscription platform fulfillment.
Asia-Pacific Frozen Pizza Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across frozen pizza manufacturing tiers. The market structure consolidates around integrated cold-chain operators and specialized topping innovators. Three archetypes dominate: multinational food conglomerates with captive logistics networks, regional private-label manufacturers with scale-driven cost positions, and premium specialists with localized formulation capabilities. Capacity expansion and direct-to-consumer channel partnerships represent the dominant competitive moves reshaping shelf access.
Among multinational food conglomerates, Nestlé SA and Dr. Oetker occupy positions anchored by cold-chain infrastructure and localized portfolio adaptation. McCain Foods Ltd exemplifies the scale-driven private-label archetype with manufacturing assets supplying regional supermarket programs. These three entities represent the competitive spectrum from integrated logistics dominance through premium positioning to manufacturing scale efficiency.
| Leading Market Players |
|---|
| Nestlé SA |
| Dr. Oetker |
| McCain Foods Ltd |
| General Mills |
| Conagra Brands |
| California Pizza Kitchen |
| Daiya Foods Inc |
| Freiberger Lebensmittel GmbH Co |
| Bellisio Foods Inc |
| Others |
Pricing and Supply Chain Analysis
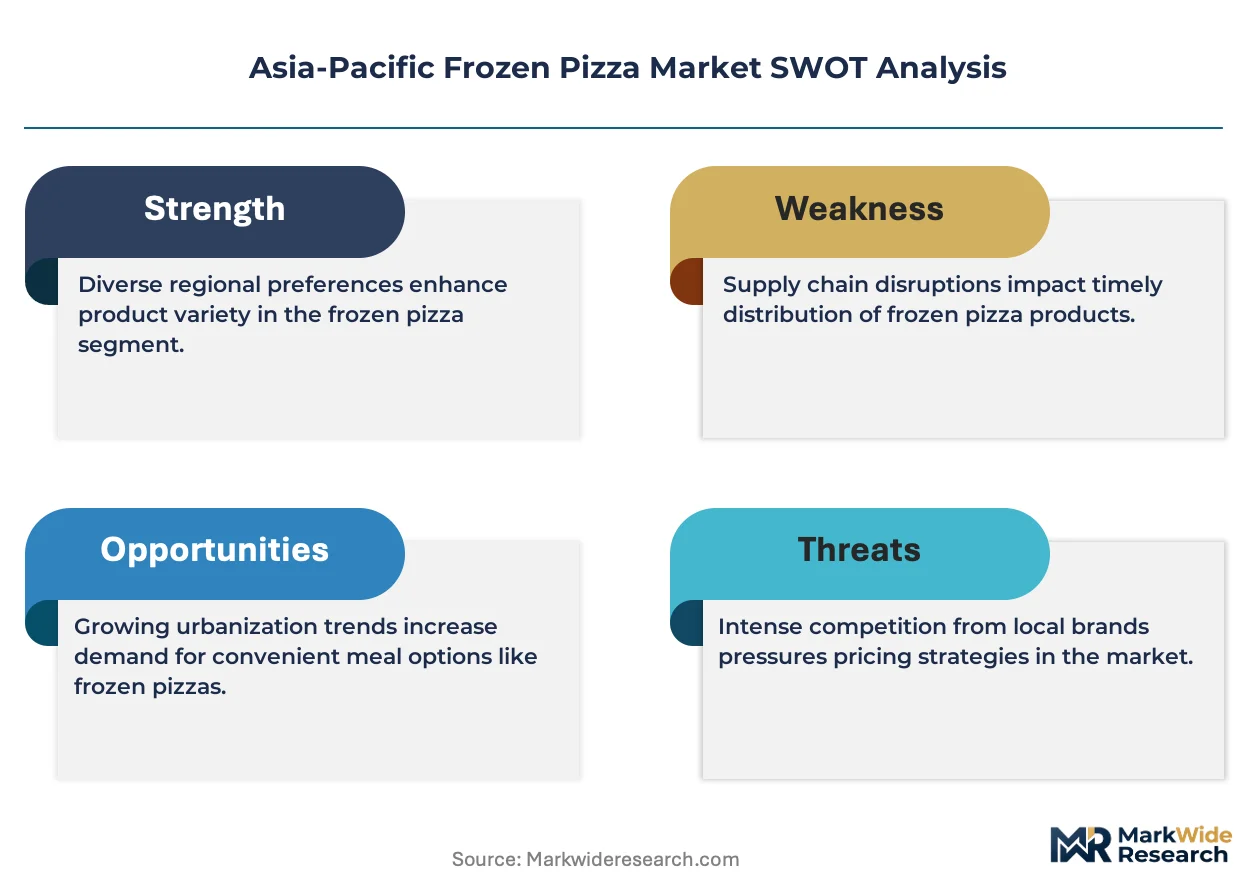
Australia's FSANZ plant-based certification pathway gates qualified supply for premium-tier frozen pizza pricing access, as manufacturers lacking compliant reformulation capabilities forfeit shelf positioning in health-positioned supermarket segments across Sydney and Melbourne metropolitan corridors.
Pricing Analysis
Margin tightening in the value tier traces to wheat and dairy input volatility from Australian and New Zealand futures markets, forcing reformulation or price pass-through decisions. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and cold-chain integrity assurance. Cost-down pressure on mid-range SKUs accelerates because thin crust commoditization traps volume in margin-diluted segments. Quick-service restaurant operators in India exhibit highest price sensitivity, while South Korean premium supermarket shoppers validate clean-label premiums.
Supply Chain Analysis
Qualified technicians for minus 30-degree blast-freezer maintenance concentrate in Japan and South Korea, constraining facility expansion in emerging markets and elevating labor premiums for cold-chain engineering talent. Production gravity centers on Australia, Japan, and South Korea for cryogenic freezing equipment and dough conditioning systems. Raw material dependencies rest on New Zealand dairy futures, Australian wheat contracts, and imported cheese blends. Single-source vulnerability pervades cryogenic equipment sourcing. Distribution feeds from regional hub-and-spoke models through temperature-controlled last-mile partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where Japan's Ministry of Health, Labour and Welfare additive disclosure standards erect barrier-to-entry moats favoring certified incumbents with established cold-chain logistics networks.
For Market Incumbents: Hedge against subscription platform disintermediation by redirecting inventory from contracting convenience store freezer doors to direct-to-consumer fulfillment infrastructure serving Tokyo and Seoul metropolitan subscriber bases. Fortify position through backward integration into localized IQF topping preparation units that decentralize supply chain risk across modular regional facilities. For New Entrants and Emerging Players: Precision freezing technology for cauliflower crust formulations offers entry wedge into Australia's FSANZ-certified health-positioned segments where incumbent reformulation timelines lag regulatory mandates. Target tier-two Indian cities in Maharashtra and Karnataka with localized blast-freezing capacity addressing cold-chain infrastructure gaps. Pursue private-label manufacturing partnerships with regional supermarket chains seeking promotional calendar flexibility. For Investors and Strategic Acquirers: Cold-chain engineering talent scarcity in emerging markets is the leading indicator that facility expansion constraints will persist, favoring acquirers of established Japanese and South Korean technical capabilities. Long-term viability centers on integrated logistics operators with captive minus 30-degree infrastructure. Monitor NMPA certification timelines for foreign manufacturers as inflection signal for China market access windows.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Cold-Chain Investment | Subscription platform partnerships unlock metropolitan subscriber bases unreachable through traditional retail channels in Tokyo and Sydney. |
| Localized IQF Topping Preparation | Modular units in Japan and South Korea decentralize production geography and reduce cross-border ingredient shipment dependencies. |
| Plant-Based Certification Pathway | FSANZ compliance opens premium positioning in Australian supermarkets contracting shelf space for clean-label variants. |
| Tier-Two City Blast-Freezing Capacity | First-mover investments in Maharashtra and Karnataka address India's quick-service restaurant kitchen automation demand. |
| Subscription Billing Platform Integration | Legacy ERP modernization enables algorithm-driven replenishment services decoupling volume from retail foot traffic. |
Research Methodology
Document review covered customs and trade data, cold-chain infrastructure investment disclosures, and regulatory filings from NMPA, SAMR, and FSANZ, complemented by interviews with frozen food category managers, cold-chain logistics directors, quick-service restaurant procurement leads, and supermarket private-label program managers. Secondary validation drew from Nielsen retail audit data, blast-freezing equipment manufacturer order books, and dairy futures market reports. Bottom-up facility capacity assessments and top-down consumption estimates were triangulated against trade flow data.
Cross-referencing historical consumption patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include crust platform type, customer application, distribution channel, and price tier. CAGRs were derived from growth driver elasticity analysis and cold-chain penetration curves. Forecast inputs incorporated NMPA certification pipeline timelines and metropolitan subscription platform adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt NMPA protocol revisions or sustained New Zealand dairy futures volatility. Forecasts reflect documented assumptions on cold-chain infrastructure buildout pacing and regulatory certification timelines. Material deviation in Japan's Ministry of Health, Labour and Welfare additive disclosure enforcement or India's FSSAI import pathway tightening warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
South America RTE Food Market
Processed and Frozen Foods
Frozen Processed Meat Market
Processed and Frozen Foods
Frozen Smoked Salmon Market
Processed and Frozen Foods
Freeze Dried Tropical Fruits Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
Commercial Walk in Freezer Market
Processed and Frozen Foods
Cold Cuts Market
Processed and Frozen Foods
Chilled Processed Food Market
Processed and Frozen Foods
Cambodia Frozen Food Market
Processed and Frozen Foods
Middle East and Africa Frozen Bread Market
Processed and Frozen Foods
Europe Freeze-Dried Products Market
Processed and Frozen Foods
GCC Frozen Fruits and Vegetables Market
Processed and Frozen Foods
Frozen Basil Leaves Market
Processed and Frozen Foods
Frozen Fruit Bars Market
Processed and Frozen Foods
Dehydrated Potato Market
Processed and Frozen Foods
Europe Frozen Food Market