
 Europe Frozen Food Market | 2026-2036
Europe Frozen Food Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Frozen Food Market Analysis
Food service procurement is pivoting toward frozen prepared meals as European hospitality operators seek kitchen labor efficiencies. Nestlé SA leverages its continental manufacturing footprint to supply private-label frozen dishes to major contract caterers. FRoSTA AG anchors its position through clean-label frozen vegetable specialization across German and Scandinavian retail channels. McCain Foods Ltd dominates frozen potato product supply to quick-service restaurant chains operating throughout the British Isles and Iberian Peninsula.
Europe frozen food encompasses thermally processed or raw foodstuffs preserved at temperatures of minus 18 degrees Celsius or below to arrest microbiological activity and maintain nutritional integrity over extended storage periods. Blast freezing and individual quick freezing constitute the dominant industrial techniques, with cryogenic freezing gaining traction for delicate fruit matrices. Frozen meals command the largest value share within product type segmentation as European consumers trade up to ethnic cuisine and diet-specific formats. Online retail distribution channels are expanding fastest among distribution channels, though supermarkets still capture the majority of frozen volume through dedicated aisle refrigeration infrastructure.
EFSA nutritional labeling requirements and the EU Green Deal cold-chain emissions protocols shape product reformulation and logistics investment decisions across the value chain. ECHA REACH compliance for food-contact packaging materials influences film and tray supplier selection, particularly for vacuum-packed premium frozen seafood exports. Stakeholders must monitor evolving F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants, as equipment replacement timelines will reshape cold storage and transport fleet economics across the continent.
Market Dynamics
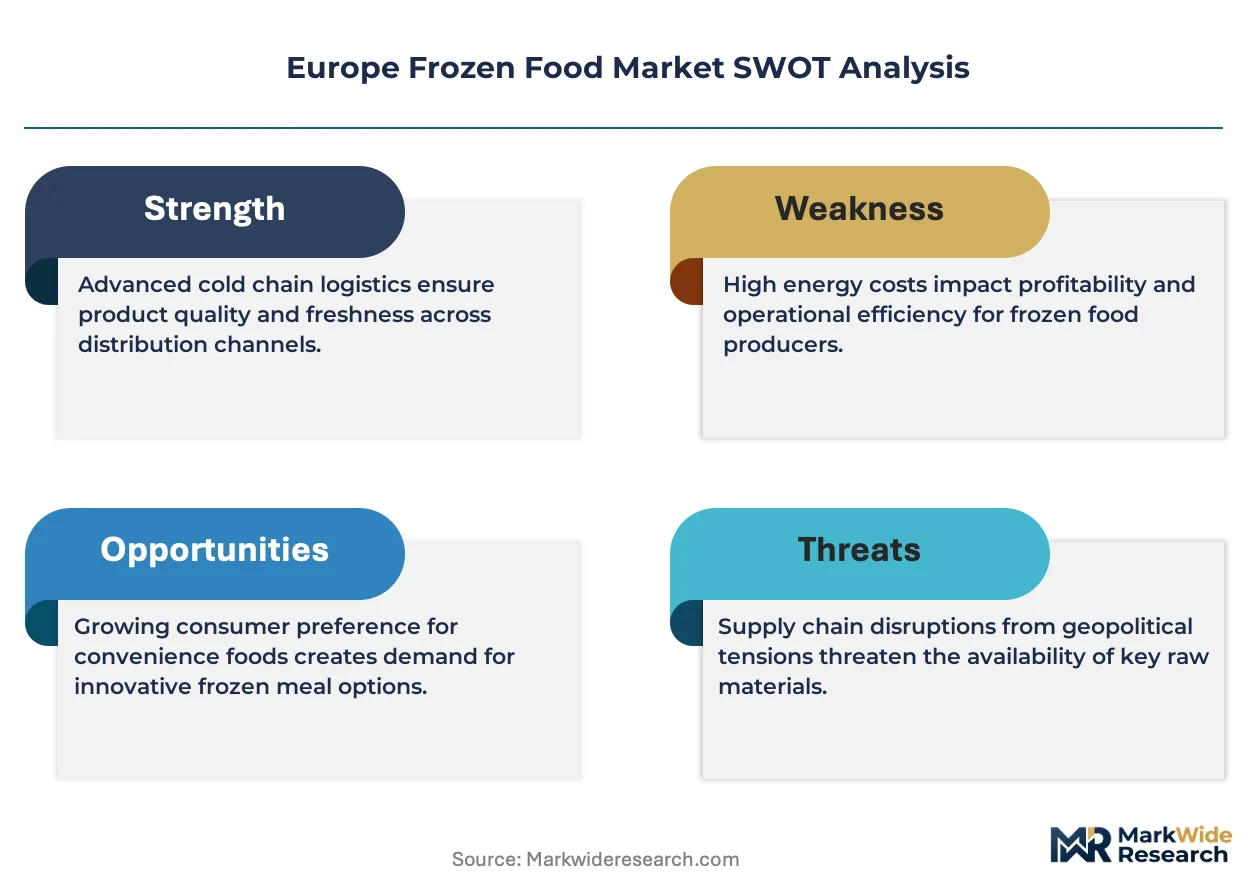
The EU Green Deal's cold-chain emissions mandates are forcing wholesale retrofit of transport refrigeration and warehouse infrastructure across European logistics networks, compressing fleet replacement timelines and reshaping capital allocation priorities for frozen food distributors.
Growth Catalysts
- Dual-income household density:Urban corridors in Germany and France exhibit concentrated demand for time-saving meal formats as labor force participation among women reaches record levels.
- EFSA nutritional labeling harmonization:Standardized front-of-pack requirements reduce cross-border formulation complexity and accelerate pan-European product rollouts.
- Blast freezing automation:Cryogenic tunnel systems cut processing energy intensity by half while preserving delicate fruit matrices for premium export positioning.
Market Restraints
- F-Gas Regulation phase-down schedules:Hydrofluorocarbon refrigerant quotas force premature equipment retirement before depreciation cycles complete, straining mid-sized cold storage operators.
- Natural gas price volatility:Blast freezing and IQF operations remain exposed to input energy cost swings that erode processor margin stability.
- Specialized logistics concentration:Temperature-controlled last-mile capacity clusters around Rotterdam, Hamburg, and Antwerp, creating bottleneck risk for peripheral markets.
Strategic Opportunities
- Eastern European retail modernization:Polish and Romanian supermarket chains are expanding dedicated frozen aisle infrastructure faster than Western saturation rates.
- Clean-label frozen vegetables:ECHA REACH compliance for food-contact films enables vacuum-packed premium positioning in Scandinavian retail channels.
- Online grocery fulfillment:Dark store networks in Paris, Berlin, and Amsterdam integrate frozen picking robotics that cut last-mile breakage below conventional store pickup.
Industry Challenges
- Refrigeration technician scarcity:F-Gas certification requirements and equipment complexity outpace vocational training pipeline output across France and Italy.
- Legacy warehouse management integration:Cold storage facilities running 1990s-era WMS platforms face data fragmentation when connecting to real-time temperature monitoring IoT architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Frozen Food Market |
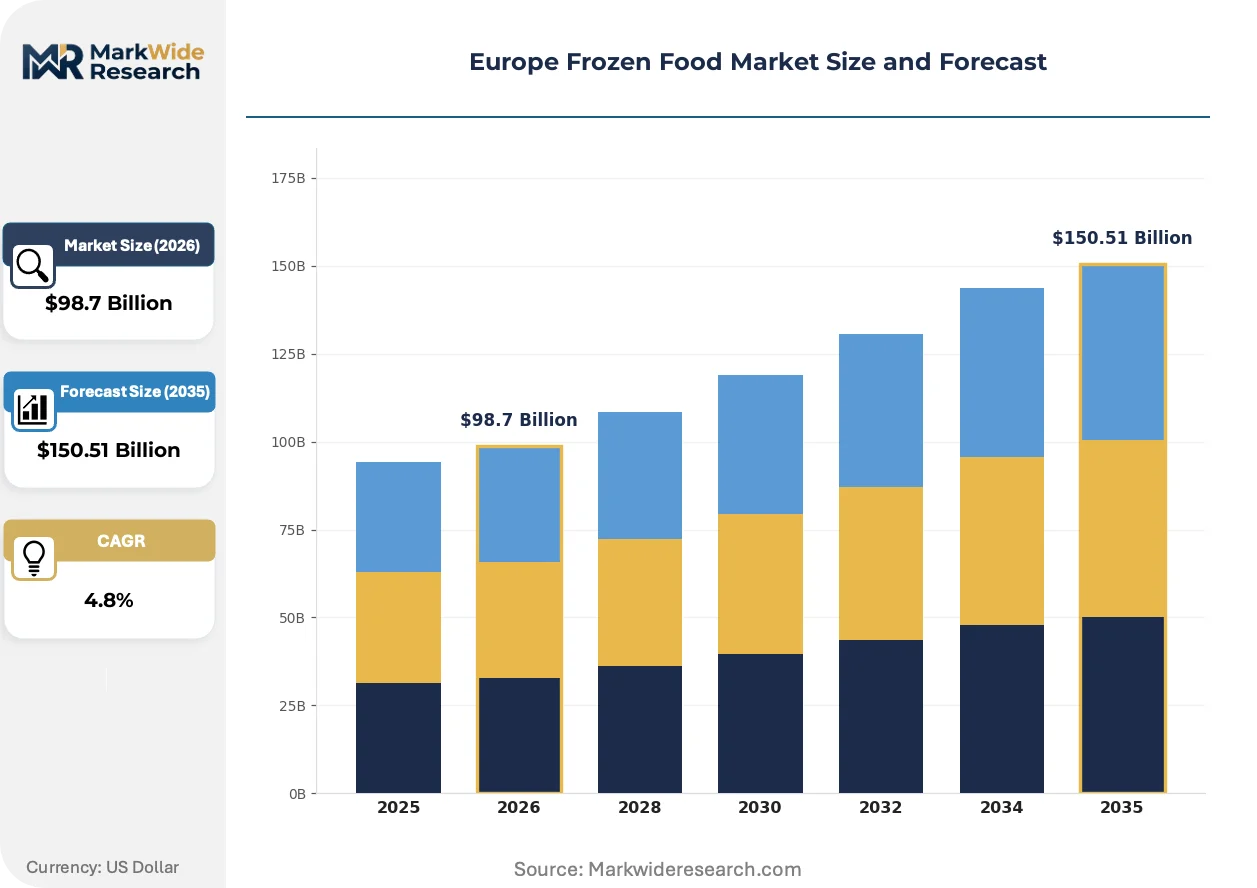
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $150.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Vegetables, Frozen Fruits, Frozen Meals, Frozen Desserts End User: Households, Food Service, Retailers, Hotels Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale Packaging Type: Vacuum Packs, Bags, Boxes, Trays |
| Companies Covered | The Kraft Heinz Company, General Mills Inc., Nestlé SA, Iceland Foods Ltd., FRoSTA AG, Nomad Foods Ltd, Dr. August Oetker KG, Cargill Inc., McCain Foods Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Frozen Food Market Emerging Trajectories
Digital traceability architectures and alternative freezing chemistries are compressing quality assurance timelines while expanding the addressable market for temperature-sensitive prepared meals across European retail and foodservice channels.
Individual quick freezing combined with cryogenic nitrogen injection is unifying the processing economics of delicate berries and prepared pasta dishes that previously required separate production lines. German contract manufacturers are consolidating multi-product facilities to capture scale advantages across seasonal crop cycles. This convergence is collapsing the traditional segmentation between commodity frozen vegetables and premium ethnic meal kits.
The F-Gas Regulation's stepped hydrofluorocarbon reduction mandates are accelerating adoption of transcritical CO2 systems in Nordic cold storage construction. Danish and Swedish warehouse operators face compressed payback calculations as 2030 equipment bans approach. Seafood exporters to Southern Europe now prioritize ammonia-CO2 cascade installations to secure long-term operational permits.
Foodservice procurement teams at British and Iberian quick-service chains are consolidating frozen potato specifications around single-supplier agreements with volume-tier pricing. This concentration displaces fragmented multi-vendor sourcing that dominated pre-pandemic tender processes. Contract caterers in London and Madrid report shortened supplier qualification cycles as risk management priorities override traditional diversification strategies.
Europe Frozen Food Market Segmentation
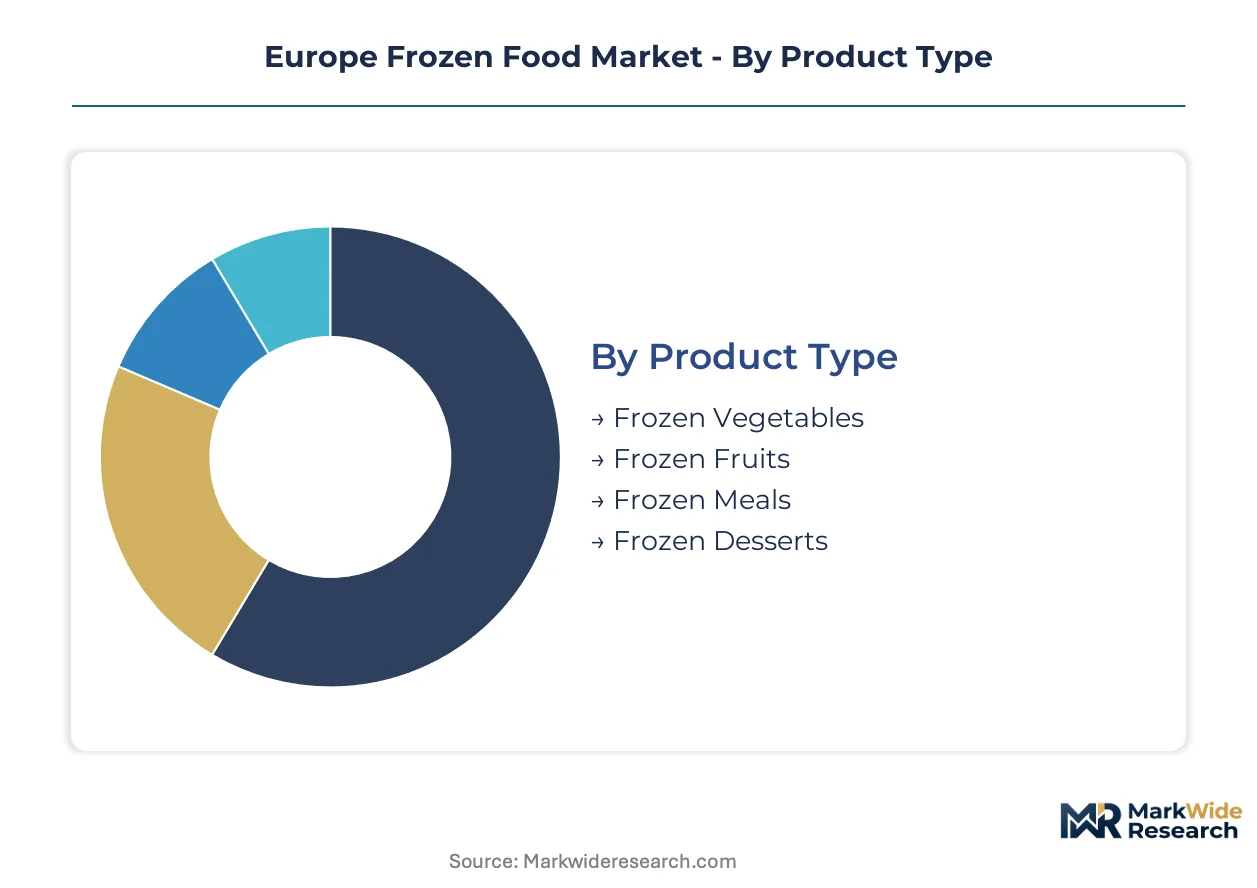
Frozen food segmentation across Europe tracks divergent upgrade cycles between retail infrastructure and foodservice procurement systems. Category boundaries are blurring as blast freezing automation collapses processing economics across previously separate product lines.
Product Type:
Replacement cycles for freezing equipment vary sharply by product matrix sensitivity, with delicate formats demanding more frequent technology refresh.
- Frozen Meals:Thermally processed complete dishes spanning ethnic cuisines and diet-specific formulations. German and French dual-income households drive concentrated demand for time-saving formats as kitchen labor costs climb across foodservice channels.
- Frozen Vegetables:Raw or blanched produce preserved through IQF or blast freezing to maintain cellular structure. Clean-label positioning dominates Scandinavian retail channels where ECHA REACH-compliant vacuum packaging commands premium shelf placement.
- Frozen Fruits:Berry and tropical fruit matrices requiring cryogenic nitrogen injection for texture preservation.
- Frozen Desserts:Ice cream, pastries, and confectionery formats with stringent cold-chain continuity requirements.
Frozen Meals sits at the top of the volume ranking, with Frozen Vegetables climbing the fastest.
End User:
Customer type determines margin structure and contract tenure, with institutional buyers locking in multi-year supply agreements.
- Food Service:Contract caterers, quick-service chains, and institutional kitchens sourcing frozen prepared meals and potato products. British and Iberian quick-service operators are consolidating around single-supplier agreements with volume-tier pricing to displace fragmented pre-pandemic tender processes.
- Households:Urban consumers in Western European corridors prioritizing convenience formats. Rotterdam and Hamburg temperature-controlled last-mile clusters serve dense metropolitan demand while peripheral markets face capacity bottlenecks.
- Retailers:Supermarket chains and independent grocers merchandising private-label and branded frozen lines.
- Hotels:Hospitality operators sourcing frozen breakfast components and banquet-ready preparations.
Food Service captures the deepest contract values, with Households expanding most quickly through online grocery adoption.
Distribution Channel:
Channel economics hinge on refrigeration infrastructure investment cycles and last-mile breakage rates.
- Supermarkets:Dedicated frozen aisle infrastructure capturing majority volume through high-capacity display refrigeration. Polish and Romanian chains are expanding frozen infrastructure faster than Western saturation rates.
- Online Retail:Dark store networks integrating frozen picking robotics. Paris, Berlin, and Amsterdam facilities cut last-mile breakage below conventional store pickup through automated temperature-controlled fulfillment.
- Convenience Stores:Limited frozen SKU counts targeting immediate consumption occasions.
- Wholesale:Cash-and-carry and delivered wholesale serving independent foodservice operators.
Supermarkets maintain volume leadership, with Online Retail gaining share fastest through urban dark store deployment.
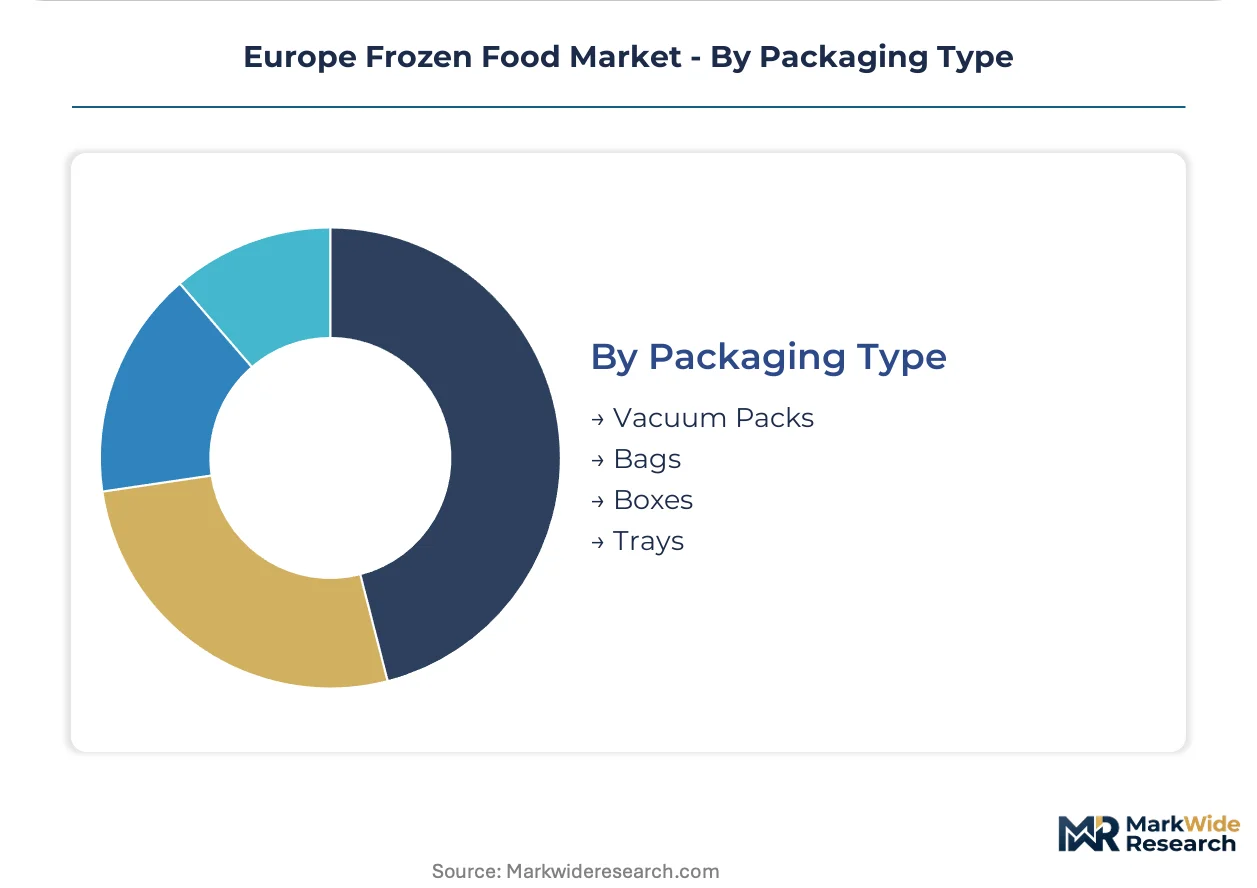
Packaging Type:
Material selection tracks ECHA REACH compliance timelines and shelf-life extension requirements for premium export positioning.
- Vacuum Packs:Barrier film configurations removing oxygen to extend frozen seafood and premium vegetable shelf life. Scandinavian retail channels prioritize REACH-compliant films for clean-label positioning.
- Trays:Rigid polymer or fiber-based containers for ready-meal presentation. German contract manufacturers favor tray formats that withstand blast freezing automation across multi-product facility consolidation.
- Bags:Flexible polyethylene or laminate structures for bulk commodity vegetables.
- Boxes:Corrugated or solid board secondary packaging for wholesale distribution.
Vacuum Packs command premium positioning, with Trays seeing steepest adoption growth through foodservice consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor anchors European frozen food distribution density, with Rotterdam and Hamburg cold-chain clusters feeding metropolitan demand across Germany, the Netherlands, and Belgium. Western European urban corridors concentrate purchasing power for convenience formats, while Eastern European retail modernization opens new infrastructure investment cycles.
Germany
Dual-income household density in Berlin, Munich, and Hamburg drives concentrated demand for time-saving frozen meal formats. The F-Gas Regulation's hydrofluorocarbon phase-down mandates accelerate transcritical CO2 system adoption in North Rhine-Westphalia cold storage construction. The Rhine-Ruhr logistics cluster hosts multi-product blast freezing facilities serving contract caterers across the Benelux region.
France
Paris metropolitan dark store networks integrate frozen picking robotics that cut last-mile breakage below conventional retail pickup. EFSA nutritional labeling harmonization reduces cross-border formulation complexity for manufacturers exporting to Iberian markets. The Île-de-France foodservice procurement hub consolidates frozen prepared meal sourcing for contract caterers operating across London and Madrid.
United Kingdom
British quick-service chains consolidate frozen potato specifications around single-supplier agreements with volume-tier pricing structures. The UK Environment Agency's cold-chain emissions protocols pressure warehouse operators toward ammonia-CO2 cascade installations. London's temperature-controlled last-mile capacity clusters serve dense metropolitan demand while peripheral Scottish and Welsh markets face logistics bottlenecks.
Poland
Polish supermarket chains expand dedicated frozen aisle infrastructure faster than Western European saturation rates. EU Green Deal cold-chain efficiency mandates accelerate retrofit investments in Warsaw and Kraków transport refrigeration networks. The Silesian industrial corridor attracts German contract manufacturers seeking lower-cost blast freezing capacity for seasonal crop processing.
Spain
Iberian quick-service operators shorten supplier qualification cycles as risk management priorities override pre-pandemic diversification strategies. ECHA REACH compliance timelines for food-contact packaging influence film supplier selection for vacuum-packed frozen seafood exports. The Barcelona logistics cluster serves Mediterranean foodservice procurement teams consolidating frozen potato and vegetable sourcing.
Europe Frozen Food Market Vendor Landscape
Capacity expansion dominates the current landscape as mid-sized operators retrofit cold storage infrastructure ahead of F-Gas Regulation deadlines. The vendor base stratifies across three tiers: multinational conglomerates with pan-European manufacturing footprints, regional specialists commanding clean-label positioning in Scandinavian retail channels, and private-label contract manufacturers serving discounter chains. Strategic archetypes include scale-driven volume players, premium-positioned clean-label specialists, and vertically integrated agricultural processors. M&A activity and technology licensing partnerships represent the dominant competitive moves reshaping market structure.
Within the multinational tier, Nestlé SA and General Mills Inc. occupy positions defined by continental manufacturing scale and private-label supply relationships. FRoSTA AG exemplifies the regional specialist archetype through its German and Scandinavian retail channel concentration. McCain Foods Ltd anchors the agricultural-processor model with frozen potato supply relationships spanning British and Iberian quick-service networks.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| General Mills Inc. |
| Nestlé SA |
| Iceland Foods Ltd. |
| FRoSTA AG |
| Nomad Foods Ltd |
| Dr. August Oetker KG |
| Cargill Inc. |
| McCain Foods Ltd |
| Others |
Supply Flow & Price Mechanics
Natural gas futures at the Dutch TTF hub cascade through European blast freezing operations into three distinct pricing tiers for frozen food procurement. Input cost volatility compresses margins at commodity vegetable processors while enabling premium positioning for cryogenic IQF berries and ethnic meal kits.
Pricing Analysis
Input-cost pass-through varies sharply by buyer archetype and contract structure. Three-tier pricing structure across premium, standard, and economy levels separates vacuum-packed Scandinavian seafood from bulk German potato products and private-label discounter lines. Price differentiation rests on ECHA REACH certification status and volume-scale procurement commitments. Pricing pressure stems from F-Gas Regulation compliance investments that cold storage operators attempt to recover through logistics surcharges. Quick-service chains exhibit lowest price sensitivity due to single-supplier consolidation, while independent foodservice operators face acute margin compression.
Supply Chain Analysis
Single-source vulnerability sits with Dutch and Belgian temperature-controlled logistics clusters feeding the Rhine-Ruhr corridor. Manufacturing concentrates in Germany, Poland, and France for blast freezing capacity, with raw material dependencies on Egyptian strawberries, Vietnamese pangasius, and Argentine beef. Supply chain risk centers on Rotterdam-Hamburg-Antwerp logistics chokepoints where last-mile refrigeration technician scarcity threatens fulfillment reliability. Distribution runs through supermarket frozen aisle infrastructure and emerging dark store networks in Paris, Berlin, and Amsterdam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal cold-chain mandates force capital redeployment that advantages scaled operators. The F-Gas Regulation's stepped hydrofluorocarbon reduction timeline compresses equipment replacement windows and reshapes competitive economics.
For Market Incumbents: Cement pan-European manufacturing footprint through multi-product facility consolidation in Germany and Poland. Lock in long-term ammonia-CO2 cascade refrigeration contracts ahead of 2030 equipment bans. Defend against private-label contract manufacturers by controlling clean-label vegetable sourcing relationships across Scandinavian retail channels.
For New Entrants and Emerging Players: Cryogenic nitrogen injection systems for delicate fruit matrices offer technology-first wedge into premium frozen dessert and berry segments underserved by legacy blast freezing infrastructure. Target Romanian and Bulgarian supermarket chains expanding frozen aisle infrastructure faster than Western saturation rates. Pursue direct dark store partnerships with Berlin and Amsterdam online grocery platforms seeking automated frozen picking capabilities.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-sized cold storage operators holding F-Gas-certified technician teams and transcritical CO2 installation expertise. Five-to-ten year viability hinges on regulatory compliance execution rather than volume growth alone. Monitor ECHA REACH film certification timelines as signal for vacuum-packed premium positioning inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Transcritical CO2 Cold Storage Buildout | Secures long-term operational permits under F-Gas Regulation phase-down mandates. |
| Clean-Label Vegetable Sourcing Partnership | Locks Scandinavian retail shelf placement ahead of ECHA REACH compliance deadlines. |
| Dark Store Frozen Fulfillment Integration | Captures online grocery growth in Paris, Berlin, and Amsterdam metropolitan corridors. |
| Single-Supplier QSR Consolidation | Displaces fragmented pre-pandemic tender processes across British and Iberian chains. |
| Multi-Product Facility Consolidation | Collapses processing economics across seasonal crop cycles for German contract manufacturers. |
Methodological Framework
Coverage spans Western Europe, Eastern Europe, and Nordic markets, with primary inputs from each region triangulated against secondary validation. Interviews with cold storage facility operators, supermarket category buyers, foodservice procurement directors, and blast freezing equipment manufacturers combined with EU customs trade data, EFSA regulatory filings, and national energy price indices. Bottom-up capacity modeling and top-down demand estimation were cross-referenced for segment-level consistency.
Rate-of-change decomposition anchored the analytical framework across product type, end user, distribution channel, and packaging format dimensions throughout the forecast period. CAGRs were derived from equipment replacement cycle analysis, retail infrastructure expansion rates, and regulatory compliance timeline modeling. Forecast inputs included F-Gas Regulation phase-down schedules, natural gas price volatility scenarios, and online grocery penetration curves by metropolitan market.
The model holds under stable regulatory enforcement timelines and energy price corridors; deviation in F-Gas quota allocations or geopolitical supply disruptions would shift capacity investment priorities. Forecasts reflect documented assumptions about cold-chain infrastructure modernization rates and dual-income household formation trends. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Chilled Meal Kits Market
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
US Frozen Food Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
Popsicle and Ice Cream Bar Market
Processed and Frozen Foods
Dehydrated Potato Products Market
Processed and Frozen Foods
Dehydrated Potato Market
Processed and Frozen Foods
Frozen Novelty Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
South America RTE Food Market
Processed and Frozen Foods
Global Chilled and Deli Foods Market
Processed and Frozen Foods
Chocolate Ice Cream Market
Processed and Frozen Foods
Frozen Mushroom Market
Processed and Frozen Foods
Freeze-Dried Food Market
Processed and Frozen Foods
Commercial Walk in Freezer Market