
 Frozen Smoked Salmon Market | 2026-2036
Frozen Smoked Salmon Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Smoked Salmon Market Foresight
Aftermarket cold-chain logistics revenue is reconfiguring margin pools away from raw commodity trading toward value-added distribution services. Mowi ASA leverages integrated aquaculture-to-retail operations across Norwegian and Scottish waters. Labeyrie Fine Foods anchors its position through artisanal smoking heritage and premium retail placement. ACME Smoked Fish differentiates via specialized Brooklyn-based smoking techniques that command urban food service loyalty.
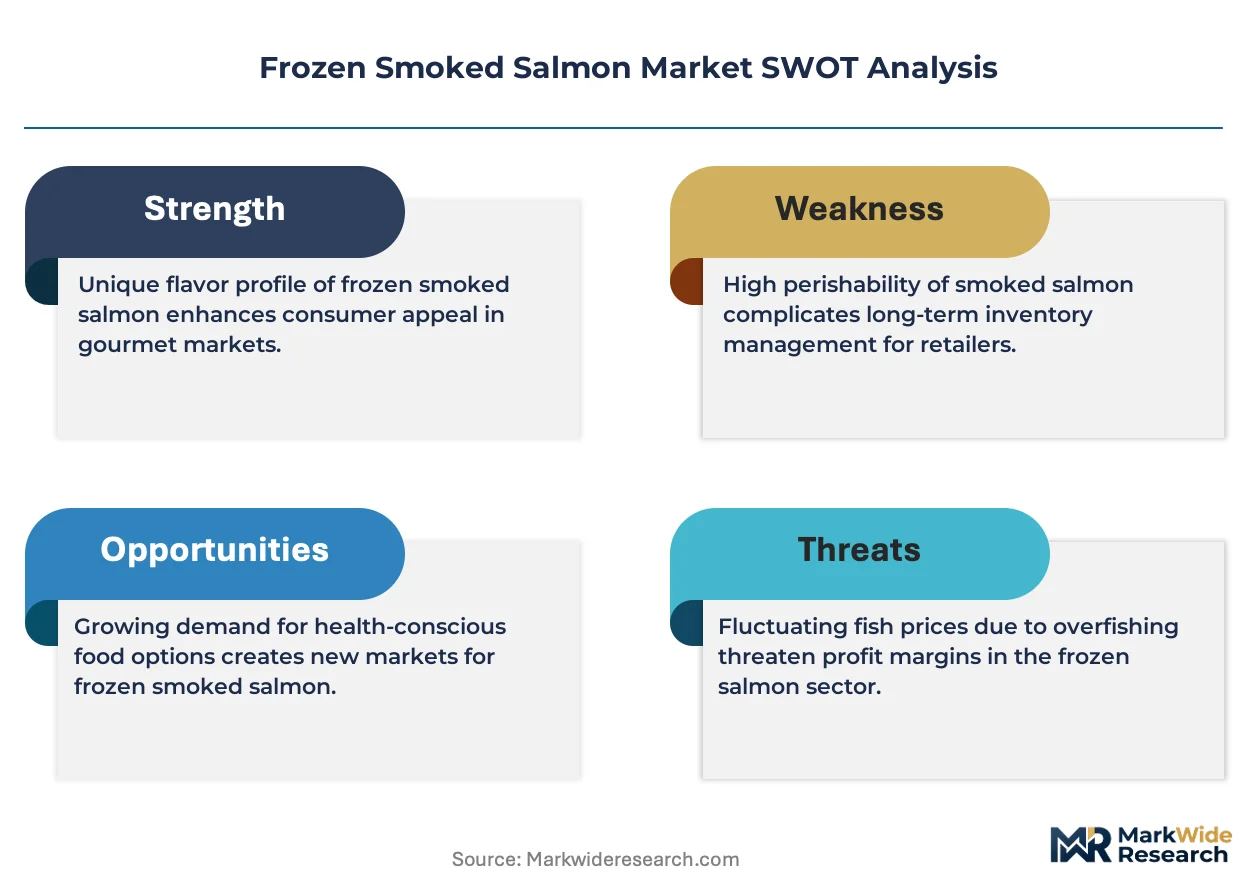
Frozen smoked salmon denotes Atlantic or Pacific salmon fillets that undergo dry or wet curing followed by controlled wood-smoking and blast-freezing to minus 18 degrees Celsius for shelf stability and flavor preservation. The product serves commercial food service operators and retail consumers seeking protein convenience without fresh supply volatility. Vacuum-sealed fillets capture the dominant margin pool due to extended shelf life and reduced spoilage rates during intercontinental transit. Food service distribution channels represent the fastest-expanding segment as hotel and restaurant chains standardize menu offerings across multiple locations. Whole salmon formats retain mature demand in European specialist retail but face compression from portion-controlled alternatives.
FDA seafood HACCP regulations and EU EFSA cold chain directives shape product standards by mandating continuous temperature logging from smokehouse to point of sale. Norway's Food Safety Authority imposes additional veterinary checks on farmed salmon destined for frozen processing, creating compliance barriers for non-integrated importers. REACH chemical frameworks in Europe restrict certain wood treatment residues in smoking equipment, influencing capital replacement cycles. Stakeholders must monitor evolving traceability mandates that will determine which suppliers retain supermarket and food service access without costly system overhauls.
Market Dynamics
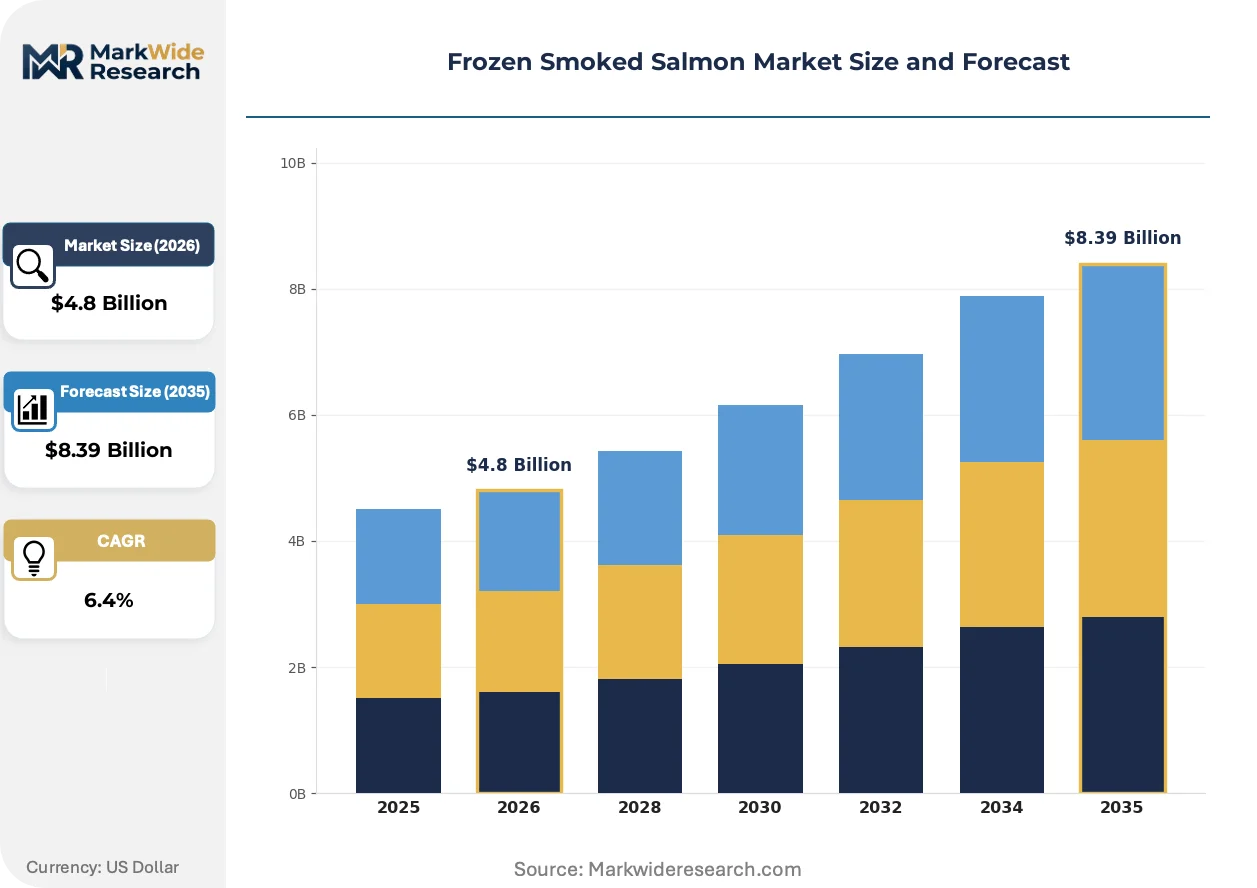
Cold chain traceability mandates from EFSA and FDA are compressing supplier margins while redirecting capital toward temperature-logging infrastructure and compliance systems. This regulatory pressure is restructuring competitive positions around integrated operations versus fragmented trading models.
Growth Catalysts
- EFSA cold chain directives:Mandates for continuous temperature logging from smokehouse to retail are forcing distributor consolidation and rewarding suppliers with captive logistics networks.
- Hotel chain menu standardization:Multi-location food service operators require consistent frozen smoked salmon specifications across properties, locking in volume commitments with qualified suppliers.
- Blast-freezing at minus 18 degrees Celsius:This preservation technology enables intercontinental shelf-stable distribution without fresh supply volatility, opening distant markets to Norwegian and Scottish production.
Market Restraints
- Farmed salmon input concentration:Norwegian aquaculture infrastructure dominates raw material supply, creating geographic single-point vulnerability for non-integrated processors.
- REACH chemical frameworks:Restrictions on wood treatment residues in smoking equipment force capital replacement cycles that disadvantage smaller smokehouse operators.
- Vacuum-packaged fresh salmon substitution:Extended shelf life innovations in chilled distribution compete for retail shelf space and food service procurement budgets.
Strategic Opportunities
- Urban food service clusters:Brooklyn, Copenhagen, and Singapore harbor dense concentrations of premium restaurants seeking specialized smoking techniques and reliable supply.
- EU Green Deal agricultural subsidies:Sustainability-linked financing instruments support cold chain electrification and renewable energy transitions in processing facilities.
- Blockchain-IoT convergence:Combined distributed ledger and sensor technologies enable real-time provenance verification that commands price premiums from transparency-demanding buyers.
Industry Challenges
- Artisanal smoking skill scarcity:Master smokehouse technicians with generational expertise in wood selection and cure timing are retiring faster than training programs replace them.
- HACCP documentation burden:FDA seafood regulations require continuous hazard analysis records that strain administrative capacity at mid-sized processing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Smoked Salmon Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Salmon, Fillets, Portions, Slices Packaging Type: Vacuum Seal, Boxed, Pouch, Bulk Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service Customer Type: Retail Consumers, Restaurants, Caterers, Wholesale Buyers |
| Companies Covered | Mowi ASA, Marine Harvest, Thai Union Frozen Products, Labeyrie Fine Foods, Multiexport Foods, Austevoll Seafood ASA, ACME Smoked Fish, Cooke Inc., Norway Royal Salmon ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Smoked Salmon Market Shifts & Advancements
Processing technology and verification systems are converging to reshape how frozen smoked salmon moves from aquaculture to plate. These shifts are elevating data infrastructure to parity with physical production assets.
Controlled atmosphere packaging with modified gas mixtures is extending frozen product quality retention windows beyond traditional vacuum sealing. High-end retail chains in Germany and Switzerland are adopting these formats for premium private label lines. This technology is hybridizing physical preservation with digital shelf-life tracking, compressing the advantage of conventional vacuum-sealed alternatives.
EU EFSA traceability mandates now require batch-level digital records linking farm origin to final distribution point. Norwegian exporters face additional veterinary inspection layers from the national Food Safety Authority. Smoked salmon destined for US food service channels bears the heaviest documentation burden, with some suppliers exiting the market rather than retrofitting legacy record systems.
Direct procurement relationships between aquaculture operators and institutional food service buyers are displacing traditional wholesale intermediaries. Hotel and restaurant groups in London, Paris, and New York now contract directly with Norwegian integrated producers for frozen portion specifications. This channel compression is most visible in the contract catering segment, where volume predictability outweighs spot market flexibility.
Frozen Smoked Salmon Market Segmentation
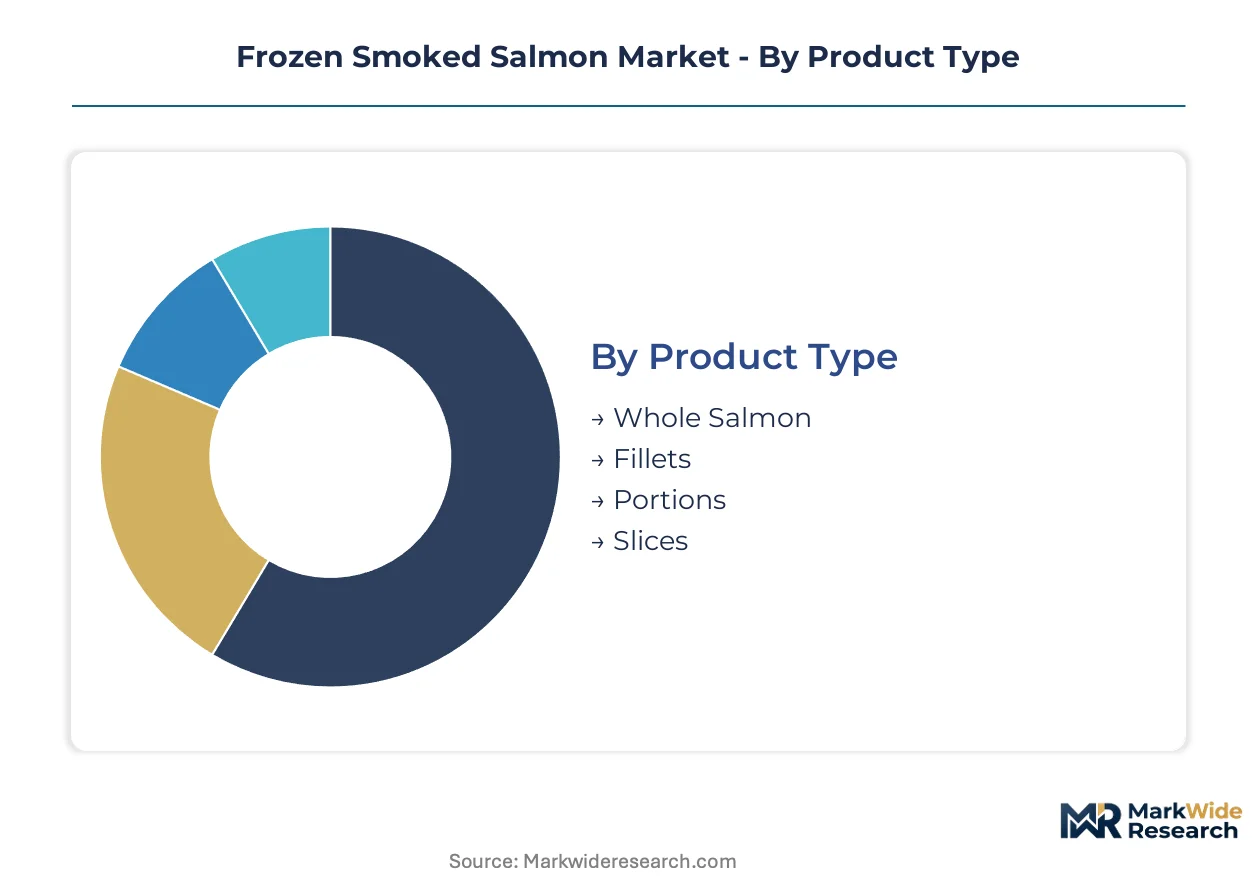
Frozen smoked salmon segmentation reveals how processing format, packaging technology, and channel configuration determine margin capture. Distinct customer workflows demand specialized product specifications that reshape supplier investment priorities.
Product Type:
After-sales service intensity varies sharply across product formats, with portion-controlled offerings requiring technical support for thawing protocols and yield optimization.
- Fillets:Side-cut sections with skin-on or skinless specifications dominate hotel and restaurant procurement. Norwegian integrated producers supply blast-frozen fillets at minus 18 degrees Celsius to London and Paris food service operators seeking consistent plate-cost control.
- Portions:Pre-cut individual servings with standardized gram weights reduce kitchen labor and waste. Demand concentrates in contract catering segments across German and Swiss institutional food service where menu engineering demands precise portion economics.
- Whole Salmon:Intact smoked fish retains specialist retail demand in European delis requiring display aesthetics and custom slicing services.
- Slices:Thin-cut ready-to-serve formats target buffet and breakfast service channels with minimal handling requirements.
Fillets hold the largest share; momentum sits with Portions as labor cost pressures intensify across food service operations.
Packaging Type:
Packaging cost tiers separate premium shelf-life extension from commodity bulk handling, with capital requirements scaling from basic boxing to intelligent atmosphere systems.
- Vacuum Seal:Oxygen-extracted polymer barriers extending frozen shelf life to 12 months while preventing freezer burn. High-end retail chains in Germany and Switzerland specify vacuum-sealed formats for private label premium lines where appearance integrity commands price premiums.
- Pouch:Flexible laminated structures with resealable features target convenience-oriented retail consumers. Demand clusters in Nordic markets where single-person households prioritize storage flexibility and repeated access without quality degradation.
- Boxed:Rigid corrugated containers with insulated liners serve food service distribution requiring stackable logistics and portion-count clarity.
- Bulk:Large-format cryogenic packaging for industrial reprocessing and private label manufacturing with minimal unit packaging overhead.
Vacuum Seal dominates value capture; Pouch formats are climbing fastest as convenience positioning penetrates premium retail.
Distribution Channel:
Channel volume concentration shapes supplier capability requirements, with direct food service contracting displacing traditional wholesale intermediaries.
- Food Service:Direct supply relationships with hotel chains, restaurant groups, and contract caterers demanding frozen portion specifications with documented cold chain custody. Multi-location operators in New York, London, and Paris now contract directly with Norwegian producers to secure volume commitments and specification consistency.
- Supermarkets:Mass retail placement requiring case-ready formats with extended shelf life and promotional display compatibility. Retail consolidation in France and the UK favors suppliers with centralized distribution and category management capabilities.
- Specialty Stores:Artisanal retail and delicatessen channels emphasizing provenance storytelling and small-batch smoking heritage.
- Online Retail:Direct-to-consumer fulfillment with insulated packaging and expedited frozen logistics, gaining traction in urban markets with premium convenience positioning.
Food Service commands the dominant volume position; Online Retail exhibits the steepest expansion trajectory as cold chain logistics mature for home delivery.
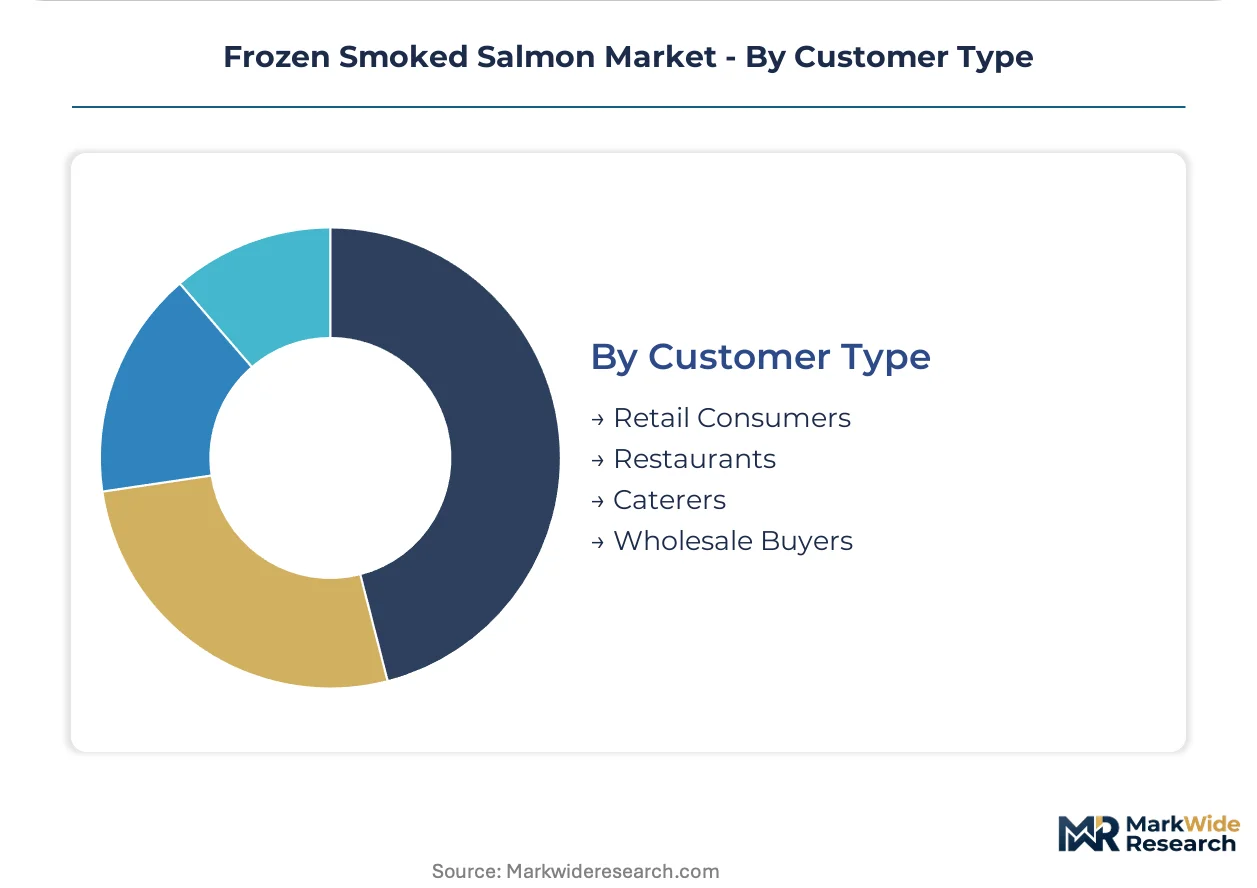
Customer Type:
Customer maturity levels determine specification complexity, with institutional buyers demanding technical documentation that exceeds retail consumer requirements.
- Restaurants:Fine dining and casual dining operators requiring consistent quality grades for menu standardization across multiple locations. Brooklyn-based smokehouses and Copenhagen restaurants specify specialized wood-smoking profiles that command supplier technical collaboration.
- Caterers:Event and institutional food service requiring volume flexibility and reliable delivery windows for banquet and conference service.
- Retail Consumers:Individual purchasers prioritizing convenience, portion size variety, and storage flexibility in home freezer applications.
- Wholesale Buyers:Trading intermediaries and redistributors serving fragmented retail and food service accounts with mixed pallet configurations.
Restaurants generate the highest value per kilogram; Caterers are gaining share fastest as institutional outsourcing expands across European and North American markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Nordic and German retail channels exhibit the strongest price elasticity, while food service operators in London, Paris, and New York prioritize specification consistency over cost minimization. This demand-elasticity contrast is reshaping supplier investment allocation across production and logistics assets.
Norway
Integrated aquaculture-to-smokehouse operations dominate supply, with Bergen and Trondheim harboring the densest processing clusters. The Norwegian Food Safety Authority imposes veterinary inspection layers on farmed salmon destined for frozen processing. Stavanger-based facilities are expanding blast-freezing capacity to capture direct food service contracts from London hotel chains.
United States
Urban food service clusters in Brooklyn and Manhattan drive specialized smoking technique demand from premium restaurants. FDA seafood HACCP regulations mandate continuous hazard analysis records that strain mid-sized processor administrative capacity. ACME Smoked Fish anchors Brooklyn-based operations commanding loyalty through differentiated urban smokehouse profiles.
Germany
Contract catering segments across institutional food service demand precise portion economics for menu engineering applications. EU EFSA cold chain directives require batch-level digital records linking farm origin to distribution point. Hamburg and Frankfurt distribution hubs are consolidating refrigerated warehouse capacity to serve centralized retail procurement.
United Kingdom
Hotel and restaurant groups in London now contract directly with Norwegian producers for frozen portion specifications. REACH chemical frameworks restrict wood treatment residues in smoking equipment, forcing capital replacement cycles. Scottish waters host Mowi ASA integrated operations supplying fillet formats to Paris and London food service operators.
France
Artisanal retail channels in Paris and Lyon emphasize provenance storytelling and small-batch smoking heritage. EU Green Deal agricultural subsidies support cold chain electrification in processing facilities. Labeyrie Fine Foods anchors premium retail placement through generational smoking expertise concentrated in southwestern production facilities.
Frozen Smoked Salmon Market Competitive Landscape
Capability concentration sits with integrated aquaculture-to-retail operators; scale advantage sits with diversified seafood conglomerates. The market structures around three tiers: vertically integrated Norwegian producers controlling raw material supply, specialized smokehouses commanding premium urban food service loyalty, and diversified seafood groups leveraging cross-species distribution infrastructure. Competitive moves center on direct procurement relationship cultivation with institutional buyers and cold chain traceability infrastructure deployment to satisfy tightening EFSA and FDA mandates.
Among Norwegian integrated producers, Mowi ASA exemplifies the aquaculture-to-retail archetype through operations spanning Norwegian and Scottish waters. Labeyrie Fine Foods occupies a position within the artisanal heritage tier, anchoring premium retail placement through generational smoking expertise. ACME Smoked Fish represents the specialized urban smokehouse archetype, with Brooklyn-based operations commanding food service loyalty through differentiated technique profiles.
| Leading Market Players |
|---|
| Mowi ASA |
| Marine Harvest |
| Thai Union Frozen Products |
| Labeyrie Fine Foods |
| Multiexport Foods |
| Austevoll Seafood ASA |
| ACME Smoked Fish |
| Cooke Inc. |
| Norway Royal Salmon ASA |
| Others |
Supply & Pricing Matrix
Bergen's blast-freezing capacity expansion is compressing spot market premiums for London and Paris food service buyers while locking in contract-based pricing power for Norwegian integrated producers with captive cold chain infrastructure.
Pricing Analysis
Long-term offtake contracts between Norwegian aquaculture operators and multi-location hotel chains dominate volume allocation, displacing spot market liquidity. Three-tier pricing structure across premium artisanal, standard food service, and economy private label levels separates Mowi ASA's integrated fillet supply from Labeyrie Fine Foods' heritage-positioned retail lines and bulk industrial reprocessing tiers. Cost compression in economy segments is intensifying because vacuum-packaged fresh salmon substitutes are capturing chilled retail shelf space. Contract caterers in German institutional channels exhibit the highest price sensitivity, while Brooklyn-based premium restaurants prioritize smokehouse technique differentiation over unit cost.
Supply Chain Analysis
Tariff exposure between Norway and post-Brexit United Kingdom dominates cross-border shipment planning for Scottish-sourced fillet formats. Raw material supply draws from Norwegian farmed salmon aquaculture, Scottish coastal waters, and Chilean Pacific production as secondary sourcing. Single-source vulnerability concentrates in Bergen and Trondheim processing clusters where veterinary inspection layers from the Norwegian Food Safety Authority create compliance bottlenecks. Distribution runs through direct procurement relationships between aquaculture operators and institutional food service buyers, bypassing traditional wholesale intermediaries in London, Paris, and New York.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frozen smoked salmon is fundamentally a cold chain service-attach opportunity where aftermarket logistics revenue and compliance documentation layers are expanding faster than raw commodity trading margins.
For Market Incumbents: Pre-empt vacuum-packaged fresh salmon substitution by deepening captive cold chain infrastructure and securing EFSA batch-level digital record certification before traceability mandates tighten. Lock in direct procurement relationships with hotel chain procurement officers to displace fragmented distributor intermediaries. Prioritize backward integration into blast-freezing capacity in Bergen and Stavanger to capture margin pools shifting toward value-added distribution.
For New Entrants and Emerging Players: Pursue urban food service clusters in Singapore and Copenhagen where specialized smoking technique demand outstrips artisanal smokehouse supply. Target contract catering segments across Swiss and German institutional channels where portion-controlled format penetration remains below saturation. Lead with blockchain-IoT provenance verification as a differentiated go-to-market angle for transparency-demanding premium restaurant buyers.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory compliance burdens and capital replacement cycles from REACH chemical frameworks are forcing smaller smokehouse operators toward exit. Acquisition targets should cluster around mid-sized Norwegian processors with veterinary inspection clearance and direct food service contracting relationships. Watch for FDA seafood HACCP documentation system retrofits as the inflection signal separating qualified suppliers from market exits.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Infrastructure Expansion | Blast-freezing capacity in Bergen and Stavanger captures direct food service contracts from London hotel chains. |
| Backward Integration into Aquaculture | Mowi ASA's Norwegian and Scottish waters operations secure raw material supply against farmed salmon input concentration. |
| Blockchain-IoT Provenance Deployment | Real-time farm-to-plate verification commands price premiums from transparency-demanding Brooklyn and Copenhagen restaurants. |
| Artisanal Smoking Heritage Positioning | Labeyrie Fine Foods' generational expertise anchors premium retail placement in Paris and Lyon specialty channels. |
| Direct Procurement Relationship Cultivation | Hotel and restaurant groups in New York and Paris now contract directly with Norwegian producers for frozen portion specifications. |
Research Methodology
A spread of perspectives from smokehouse operations managers, food service procurement directors at hotel chains, cold chain logistics coordinators, and retail category buyers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against Norwegian Food Safety Authority inspection records, EU EFSA cold chain directive documentation, FDA seafood HACCP compliance filings, and customs trade data tracking Atlantic salmon movements. Bottom-up volume modeling from processing facility capacities and top-down demand estimation from food service operator procurement patterns were triangulated for cross-verification.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation dimensions spanning product format, packaging technology, distribution channel configuration, and customer type maturity. CAGRs were derived from trend extrapolation of historical volume movements adjusted for regulatory compliance cost absorption and channel compression dynamics. Industry-specific forecast inputs incorporated blast-freezing capacity expansion timelines and EFSA traceability mandate implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified seafood conglomerates or technology-enabled traceability specialists would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
North America Frozen Desserts Market
Processed and Frozen Foods
Frozen Baby Food Market
Processed and Frozen Foods
Frozen Food and Snacks Market
Processed and Frozen Foods
Frozen Meat Grinder Market
Processed and Frozen Foods
North America Freeze Dried Products Market
Processed and Frozen Foods
Canned Vegetables Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
Vegan Frozen Pizza Market
Processed and Frozen Foods
Chilled Soup Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
Dehydrated Potato Market
Processed and Frozen Foods
Middle East and Africa Frozen Bread Market
Processed and Frozen Foods
GCC Frozen Fruits and Vegetables Market
Processed and Frozen Foods
Frozen Processed Meat Market