
 Cold Cuts Market | 2026-2036
Cold Cuts Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Cuts Market Analysis
Asset-light leasing models for slicing and packaging equipment is fragmenting capital barriers among mid-sized processors. JBS S.A. leverages its protein-diversified portfolio to sustain cold cut volume across multiple geographies. Hormel Foods Corporation anchors its position through vertical integration from hog production to branded retail. Tyson Foods competes on manufacturing scale, operating some of the highest-throughput deli meat facilities in North America.
Cold cuts comprise cured, cooked, or smoked meat products—typically pork, beef, poultry, or blends—sliced to uniform thickness for direct consumption or sandwich assembly, with sodium content, water-binding capacity, and sliceability serving as critical quality parameters. The category spans retail-ready packaged formats and foodservice bulk offerings designed for speed of preparation in commercial kitchens. Salami and turkey segments lead value contribution where premium positioning and perceived health attributes concentrate margin pools. Vacuum-sealed packaging dominates shelf-life extension while resealable formats capture growing retail preference for portion control and reduced food waste.
USDA FSIS inspection protocols and FDA nutrition labeling requirements govern processing standards and front-of-pack claims across the United States, directly influencing sodium-reduction R&D priorities and clean-label formulation investments. EU EFSA guidelines on nitrite preservatives and CE-marked equipment standards shape export compliance costs for North American suppliers accessing European retail channels. Stakeholders must monitor evolving sodium thresholds and alternative-cure technologies that could reclassify competitive advantage between legacy processors and reformulation-ready entrants.
Market Dynamics
USDA and FDA sodium disclosure mandates are compressing formulation timelines while forcing R&D reallocation toward clean-label cure alternatives and natural preservation systems.
Growth Catalysts
- Foodservice grab-and-go expansion:Commercial sandwich programs at convenience retailers and institutional cafeterias are standardizing pre-sliced deli meat procurement, locking in volume commitments with regional processors.
- EU EFSA nitrite guidance revision:Anticipated tightening of preservative thresholds is accelerating investment in celery powder and fermentation-derived alternatives among export-oriented North American suppliers.
- Vacuum skin packaging adoption:Extended shelf-life technology is enabling direct-store-delivery models that bypass traditional warehouse distribution for fresh-format retail.
Market Restraints
- Pork belly input volatility:Concentration of hog farming in the Midwestern United States creates price transmission risk during seasonal supply contractions or disease outbreaks.
- Nitrite substitute performance gaps:Natural curing agents currently fail to match synthetic sodium nitrite for color stability and botulism inhibition in extended shelf-life applications.
- California Proposition 65 enforcement:Litigation exposure for processed meat warnings is elevating compliance insurance costs and discouraging premium positioning in that state.
Strategic Opportunities
- Plant-forward hybrid formulations:Blended meat-vegetable cold cuts are capturing trial among flexitarian households in urban coastal markets without requiring full product line conversion.
- Direct-to-foodservice e-procurement platforms:Digital ordering systems are disintermediating traditional broadline distributors for independent delis and small-chain sandwich concepts.
- USDA BioPreferred procurement preference:Federal and state institutional purchasing mandates for bio-based packaging are creating first-mover advantage for compostable tray-sealed formats.
Industry Challenges
- Clean-label formulation expertise scarcity:Protein chemists with applied knowledge of natural preservation and phosphate replacement command premium compensation, constraining mid-sized processor hiring.
- Legacy slicing equipment integration:Retrofitting high-speed lines for modified-atmosphere packaging without throughput degradation requires extended downtime that conflicts with just-in-delivery contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Cuts Market |
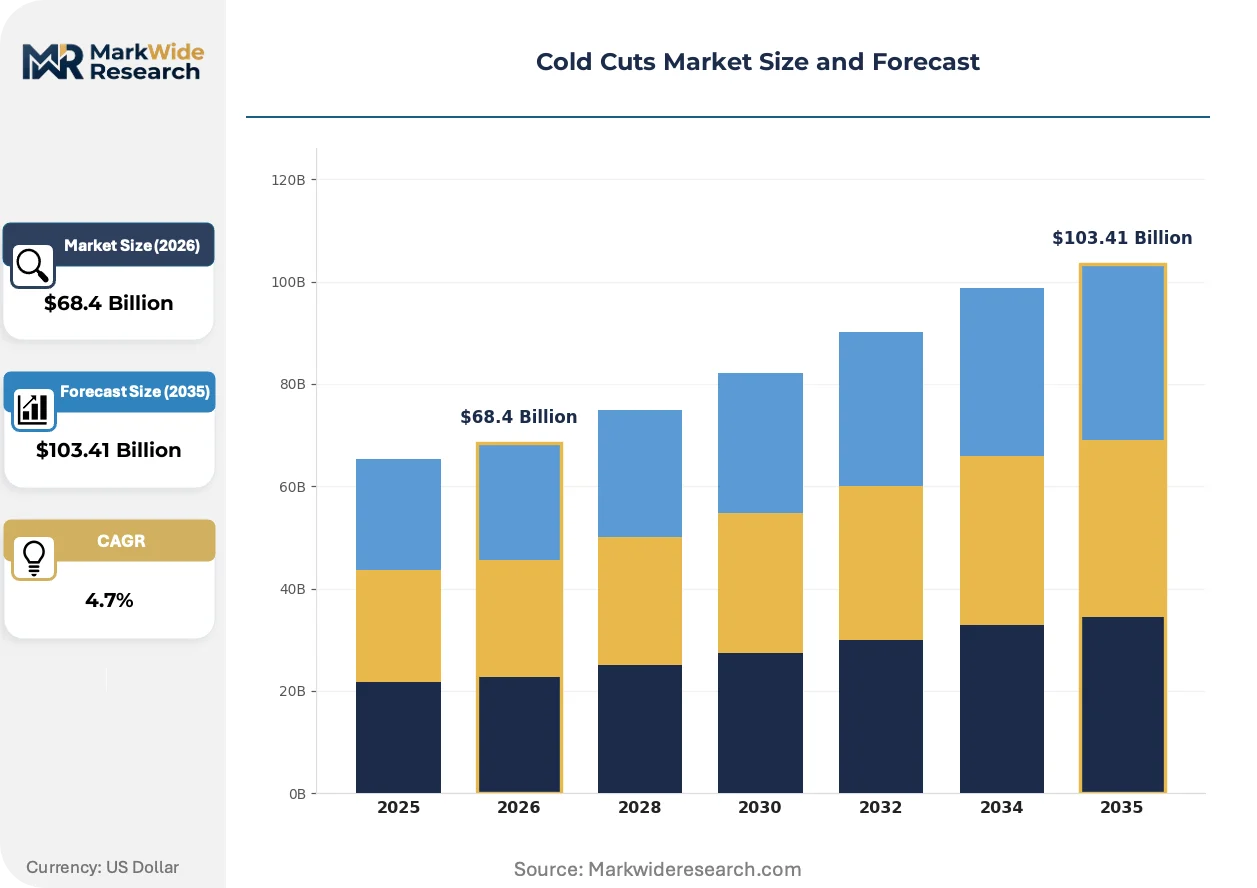
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
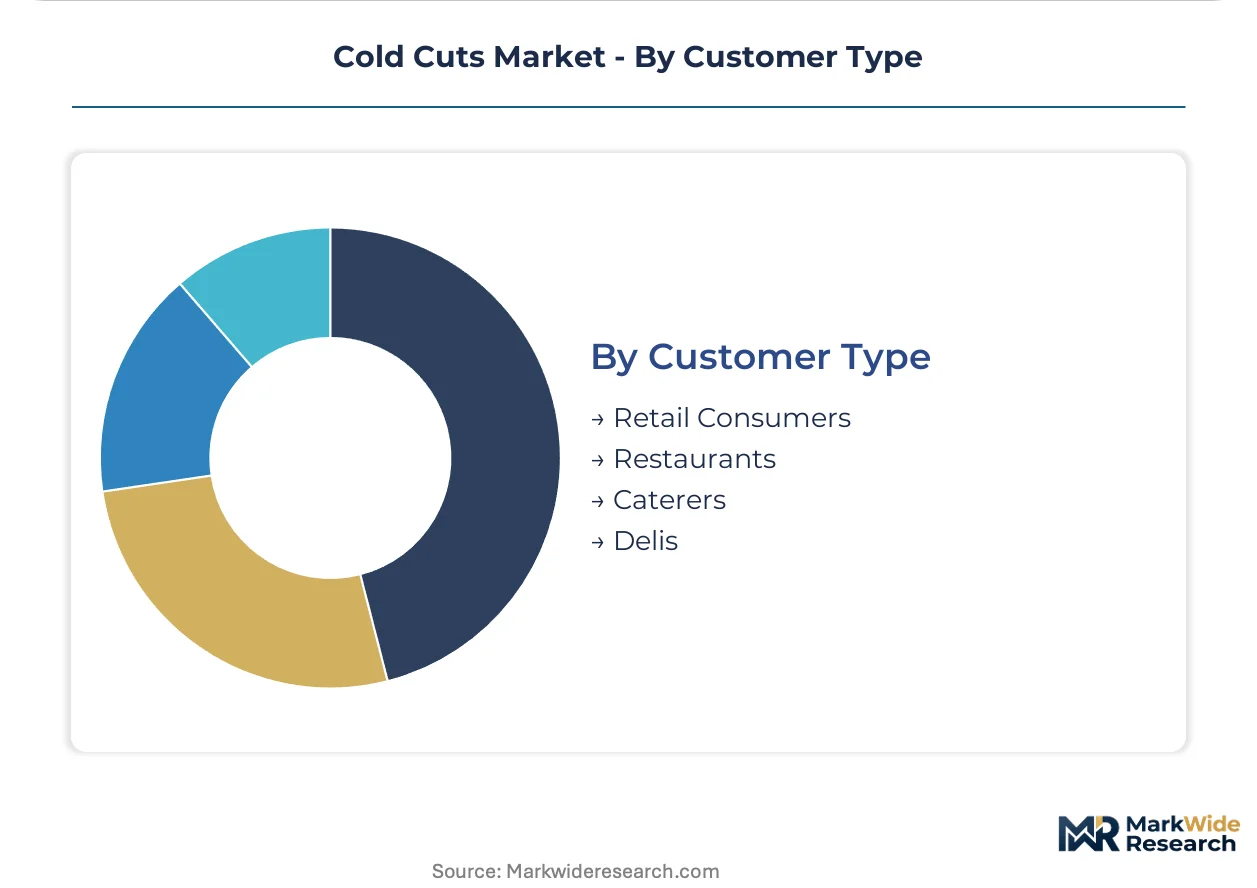
| Segmentation | Type: Salami, Ham, Turkey, Bologna Packaging Type: Vacuum-Sealed, Tray Pack, Bulk, Resealable Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Foodservice Customer Type: Retail Consumers, Restaurants, Caterers, Delis |
| Companies Covered | Hormel Foods Corporation, BRF S.A., Kraft Heinz Company, Seaboard Corporation, Maple Leaf Foods, Tyson Foods, WH Group Limited, Conagra Brands, JBS S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Cuts Market Emerging Trajectories
Active packaging technologies and reformulation chemistry are converging to extend shelf life without synthetic additives, while digital traceability systems reshape supplier accountability.
High-pressure processing equipment is digitizing quality assurance workflows across North American deli meat facilities. Mid-sized processors in the Great Lakes region are deploying inline sensors that map bacterial load in real time, compressing hold-and-release cycles from days to hours. This technology is digitizing the interface between production and regulatory documentation, reducing USDA FSIS inspection friction.
The FDA's updated Nutrition Facts label mandate requiring added sugars disclosure has forced reformulation of honey-glazed and maple-cured product lines. Manufacturers are responding by reducing sugar content in brine solutions or switching to non-nutritive sweeteners that do not trigger the disclosure threshold. Smoked turkey and chicken breast segments face the steepest compliance costs given their higher incidence of sweetened cure applications.
Foodservice operators are consolidating supplier relationships around single-source accountability for both product and packaging sustainability claims. Broadline distributors are losing share to processor-direct programs that bundle carbon footprint verification with volume pricing. This consolidation is most visible in the Northeastern United States, where institutional buyers at universities and hospital systems have embedded environmental scoring into formal procurement criteria.
Cold Cuts Market Segmentation

Cold cuts segmentation reveals how texture, preservation method, and procurement context reshape margin structures. Each dimension carries distinct regulatory exposure and capital intensity requirements that determine competitive viability.
Type:
Product composition dictates curing complexity, input cost volatility, and permissible shelf-life claims under USDA FSIS protocols.
- Salami:Fermented and dry-cured preparations rely on controlled mold cultures and extended aging cycles. Italian-style varieties command premium positioning in Northeastern US urban markets where artisan deli culture sustains direct-import competition.
- Ham:Wet-cured pork shoulder and leg cuts dominate institutional foodservice procurement through standardized portion control. Honey-glazed sub-varieties face reformulation pressure from FDA added-sugar disclosure mandates affecting brine formulations.
- Turkey:Lean protein positioning drives health-claim eligibility and school lunch program compliance.
- Bologna:Emulsified texture and lower price point anchor value-tier retail placement.
Salami holds installed capacity. Turkey is rotating up the share rankings.
Packaging Type:
Barrier properties and consumer interface design determine distribution reach and waste liability exposure.
- Vacuum-Sealed:Oxygen exclusion extends refrigerated shelf life while enabling case-ready retail distribution. This format dominates club store and mass retail channels where inventory velocity justifies equipment amortization.
- Resealable:Zipper-equipped pouches reduce household food waste and support portion-controlled consumption patterns. Adoption concentrates in suburban household formats where multi-use occasions justify per-unit packaging premiums.
- Tray Pack:Modified-atmosphere overwrap serves fresh deli counter presentation.
- Bulk:Foodservice totes and chubs minimize per-pound packaging cost for high-volume operators.
Vacuum-sealed holds installed capacity. Resealable is rotating up the share rankings.
Distribution Channel:
Channel selection governs temperature control requirements, payment terms, and private-label exposure.
- Supermarkets:Full-service deli counters and refrigerated case sets demand SKU breadth and promotional funding. Chains in the Midwestern United States leverage direct-store-delivery networks to minimize warehouse handling.
- Foodservice:Broadline distributor and processor-direct models compete on traceability documentation and sustainability scoring. University and hospital procurement in the Northeastern United States embeds carbon footprint verification into vendor selection.
- Convenience Stores:Grab-and-go sandwich programs standardize pre-sliced portion packs.
- Online Retail:Direct-to-consumer fulfillment requires insulated packaging investment and last-mile cold chain reliability.
Supermarkets hold installed capacity. Foodservice is rotating up the share rankings.
Customer Type:
End-user sophistication shapes specification tolerance, delivery frequency, and regulatory documentation burden.
- Retail Consumers:Household purchasers respond to front-of-pack sodium claims and resealable convenience features. Clean-label preference concentrates in coastal metropolitan markets where ingredient literacy exceeds national averages.
- Restaurants:Sandwich concepts and casual dining operators prioritize slice consistency and labor-minimizing formats. Independent delis in urban centers sustain demand for thin-sliced specialty cuts despite higher per-pound cost.
- Caterers:Event-volume requirements favor bulk chubs and rapid-slice equipment compatibility.
- Delis:Traditional counter service depends on whole-muscle display aesthetics and custom thickness requests.
Retail consumers hold installed capacity. Restaurants are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold cuts trade flows reveal persistent export surpluses from North American and European processing hubs against import dependence in emerging consumption centers. Currency-adjusted unit economics favor regional production for fresh-format distribution, while shelf-stable categories sustain longer trade corridors.
United States
Deli counter culture and convenience retail penetration sustain the world's highest per-capita consumption of sliced processed meats. USDA FSIS inspection protocols and FDA sodium disclosure mandates compress formulation timelines for domestic processors. Chicago and the broader Midwest anchor hog farming concentration, with JBS S.A. and Tyson Foods operating high-throughput facilities across Iowa and Illinois.
Germany
Artisan charcuterie traditions coexist with industrial-scale wurst production serving Central European retail and foodservice channels. EU EFSA guidelines on nitrite preservatives shape reformulation investments among export-oriented suppliers. The North Rhine-Westphalia cluster around Cologne and Düsseldorf hosts specialized slicing equipment manufacturers and modified-atmosphere packaging innovators.
Brazil
BRF S.A. leverages integrated poultry and pork supply chains to capture Latin American cold cut demand and penetrate North American private-label channels. ANVISA processed meat standards govern sodium thresholds and labeling requirements for domestic and export-bound production. São Paulo state concentrates slaughtering, curing, and packaging capacity within a 200-kilometer radius of the metropolitan region.
China
Western-style sandwich adoption and convenience store expansion drive processed meat demand in tier-one cities despite traditional fresh-meat preferences. SAMR food safety regulations and GB standards for processed meat products impose traceability and additive disclosure requirements. The Yangtze River Delta around Shanghai hosts the highest concentration of foreign-invested cold cut facilities serving premium retail channels.
Canada
Maple Leaf Foods anchors domestic production while supplying cross-border private-label programs under USMCA tariff preferences. Health Canada and CFIA inspection protocols align closely with USDA standards, facilitating integrated North American supply chains. Ontario's southwestern corridor between Toronto and Windsor concentrates hog processing and value-added meat manufacturing.
Cold Cuts Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with curing technology, slicing equipment, and natural preservation inputs. The cold cuts sector exhibits tiered consolidation, with diversified protein conglomerates controlling volume manufacturing and mid-sized regional processors occupying specialty and private-label niches. Three archetypes dominate: vertically integrated livestock-to-retail operators, asset-light co-manufacturing specialists, and fermentation-derived preservation technology vendors. Competitive dynamics center on M&A-driven geographic expansion and backward integration into hog and poultry farming to secure input cost stability.
Among Brazil-based protein conglomerates, BRF S.A. exemplifies the diversified-platform archetype spanning poultry, pork, and processed meat value chains. JBS S.A. occupies a parallel position with multi-protein manufacturing scale across North and South American facilities. Hormel Foods Corporation represents the integrated-model specialist, with captive hog supply and branded retail anchoring its competitive position. These three entities collectively illustrate the strategic segmentation between geographic diversification, protein breadth, and vertical control that defines tier-one competitive positioning.
| Leading Market Players |
|---|
| Hormel Foods Corporation |
| BRF S.A. |
| Kraft Heinz Company |
| Seaboard Corporation |
| Maple Leaf Foods |
| Tyson Foods |
| WH Group Limited |
| Conagra Brands |
| JBS S.A. |
| Others |
Supply Flow & Price Mechanics
Pork belly input volatility in the Midwestern United States determines both the spread between premium and economy-tier cold cut pricing and the geographic clustering of slicing and packaging capacity. USDA and FDA sodium disclosure mandates compress formulation timelines, forcing processors to absorb R&D costs or pass them through to foodservice buyers locked into annual volume contracts.
Pricing Analysis
Foodservice operators anchor cold cut pricing through standardized pre-sliced portion pack procurement. Pricing stratifies across premium, standard, and economy tiers based on curing method complexity and slice consistency grade. Cost compression in the economy tier is intensifying because private-label retailers demand volume rebates without quality degradation. Independent delis show least price sensitivity, while institutional cafeterias negotiate aggressively on per-pound landed cost.
Supply Chain Analysis
Hog farming concentration in Iowa, Illinois, and Minnesota feeds the North American cold cut manufacturing base. Raw material sourcing draws from corn-fed pork shoulder, poultry breast trim, and imported spice blends for cure formulations. Single-source vulnerability exists in Midwestern hog farming density during seasonal disease outbreaks. Distribution runs through direct-store-delivery networks bypassing traditional warehouse handling for fresh-format retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foodservice grab-and-go expansion signals early-cycle penetration growth as convenience retailers standardize pre-sliced deli meat programs. Vacuum skin packaging adoption accelerates shelf-life extension, enabling new distribution models that bypass legacy warehouse infrastructure.
For Market Incumbents: Harden formulation expertise in natural preservation systems before EU EFSA nitrite guidance revisions tighten export compliance thresholds. Acquire celery powder and fermentation-derived cure technology vendors to secure clean-label supply chains. Expand captive hog production in the Southeastern United States to reduce Midwestern supply concentration risk.
For New Entrants and Emerging Players: Establish a beachhead in plant-forward hybrid cold cuts targeting flexitarian households in coastal metropolitan markets. White-space exists in direct-to-foodservice e-procurement platforms disintermediating broadline distributors for independent delis. Lead with carbon footprint verification bundled with volume pricing to capture institutional procurement mandates.
For Investors and Strategic Acquirers: FDA sodium disclosure mandates reshaping the acquisition landscape toward reformulation-ready mid-sized processors with applied protein chemistry capabilities. Long-term viability favors targets with backward integration into poultry farming and USDA BioPreferred packaging certification. Monitor California Proposition 65 litigation exposure as an inflection indicator for premium positioning risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | USDA and FDA sodium mandates force R&D reallocation toward natural cure alternatives. |
| Backward Integration into Hog Production | Captive supply of pork shoulder reduces price transmission risk during Midwestern supply contractions. |
| Vacuum Skin Packaging Scale-Up | Extended shelf-life technology enables direct-store-delivery models bypassing warehouse distribution. |
| Foodservice E-Procurement Platform Launch | Digital ordering systems disintermediate broadline distributors for independent sandwich concepts. |
| EU Export Compliance Certification | EFSA nitrite guidance alignment opens Central European retail channels for North American suppliers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured interviews with deli counter managers, foodservice procurement directors, protein chemists at mid-sized processors, and sustainability officers at institutional buyers. Secondary validation drew from USDA FSIS inspection protocols, FDA nutrition labeling databases, EU EFSA preservative guidance documents, and trade flow records. Bottom-up volume modeling triangulated against top-down protein consumption benchmarks.
Calibration against historical price transmission patterns and regulatory implementation timelines anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type, packaging format, distribution channel, and customer archetype. CAGRs were derived from elasticity-adjusted demand curves incorporating foodservice expansion rates and clean-label adoption velocity.
Stress conditions across hog farming disease outbreaks, nitrite substitute performance gaps, and California litigation exposure were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timelines and technology adoption curves. Cross-checking against USDA livestock inventory reports and foodservice distributor earnings disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
Asia Pacific Freeze Dried Product Market
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
North America Dehydrated Food Market
Processed and Frozen Foods
South America Freeze Dried Products Market
Processed and Frozen Foods
Individual Quick Frozen Cheese Market
Processed and Frozen Foods
Frozen Smoked Salmon Market
Processed and Frozen Foods
Icebreakers Market
Processed and Frozen Foods
Commercial Walk in Freezer Market
Processed and Frozen Foods
Freeze-Dried Food Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
Freeze Dried Vegetables Market
Processed and Frozen Foods
Global Chilled and Deli Foods Market
Processed and Frozen Foods
South America Frozen Food Market
Processed and Frozen Foods
North America Frozen Food Market