
 Commercial Walk in Freezer Market | 2026-2036
Commercial Walk in Freezer Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Walk in Freezer Market Outlook
Dealer-direct and foodservice equipment distributor networks are tilting toward integrated cold storage solutions that bundle installation, refrigerant compliance, and remote monitoring. Hussmann Corporation leverages its vertical manufacturing footprint to control panel production and refrigeration systems under one supply chain. Nor-Lake, Inc. anchors its position through geographic density across North American foodservice corridors with rapid-ship modular programs. Carrier Commercial Refrigeration competes on scale by extending its commercial HVAC service infrastructure into walk-in freezer lifecycle contracts.
A commercial walk-in freezer is an insulated, enclosed refrigerated space with floor area typically exceeding 30 square feet, designed for bulk frozen food storage at temperatures of 0°F or below, constructed from interlocking polyurethane or polystyrene foam panels with cam-lock joining systems. Its primary industrial purpose is to preserve perishable inventory across foodservice, retail grocery, and distribution operations while enabling high-volume stock rotation and regulatory-compliant cold chain custody. Modular units dominate volume shipments due to faster lead times and lower site labor requirements, while blast freezer configurations command premium positioning in protein processing and seafood distribution where rapid temperature pull-down preserves product quality. Hydrocarbon and CO2 refrigerant categories are gaining specification share as operators anticipate phasedown compliance deadlines and seek energy efficiency improvements.
The EPA AIM Act refrigerant phasedown, DOE commercial refrigeration efficiency standards, and OSHA workplace safety requirements for ammonia systems collectively reshape equipment specifications and replacement timelines across the installed base. California's Title 24 building energy codes and similar state-level efficiency mandates add compliance layering that favors higher-insulation panel systems and variable-speed compressor technologies. Stakeholders must monitor refrigerant transition timelines, assess retrofit versus replacement economics, and align procurement cycles with evolving federal and state efficiency thresholds.
Market Dynamics
The EPA's AIM Act refrigerant phasedown is compressing replacement cycles across the installed base, forcing operators to choose between retrofitting existing hydrocarbon systems or full equipment replacement before compliance deadlines tighten.
Growth Catalysts
- Ghost Kitchen Infrastructure:Restaurant chains are expanding dedicated cold storage footprints to support centralized prepared meal production and last-mile delivery fulfillment.
- California Title 24:The state's building energy codes are mandating higher-insulation panel systems and variable-speed compressor technologies that reduce operating costs.
- CO2 Transcritical Systems:Supermarket and protein processing operators are specifying lower-GWP refrigerant architectures to preempt federal phasedown enforcement.
Market Restraints
- Polyurethane Foam Input Costs:Volatility in isocyanate and blowing agent pricing compresses panel manufacturer margins and extends quote validity periods.
- Specialized Refrigeration Technician Scarcity:The limited pool of certified installers for hydrocarbon and CO2 systems constrains deployment velocity in secondary markets.
- Ammonia System Regulatory Burden:OSHA Process Safety Management requirements add compliance overhead that deters smaller operators from industrial-scale freezer adoption.
Strategic Opportunities
- Remote Monitoring Convergence:Integration of IoT sensors with predictive maintenance platforms is creating recurring revenue streams for equipment vendors.
- DOE Efficiency Standards:Federal commercial refrigeration mandates are accelerating replacement demand among operators with aging single-speed compressor fleets.
- Seafood Distribution Modernization:Blast freezer configurations are capturing specification share in Pacific Northwest and Gulf Coast processing corridors.
Industry Challenges
- Refrigerant Transition Timing:Operators face compressed decision windows to assess retrofit economics against full system replacement before AIM Act phase-down milestones.
- Legacy Control System Integration:Facilities with existing building automation architectures encounter protocol incompatibility when upgrading to smart-connected freezer monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Walk in Freezer Market |
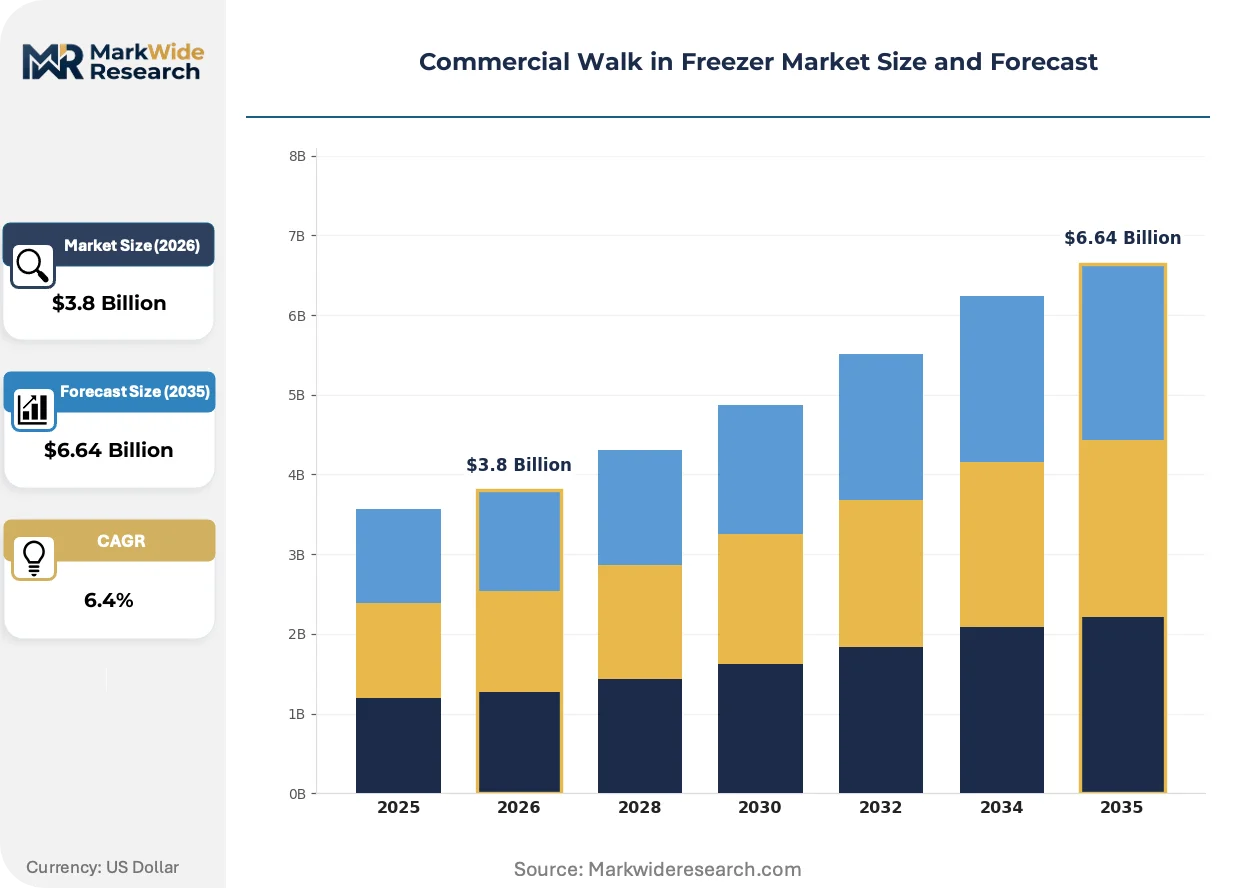
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
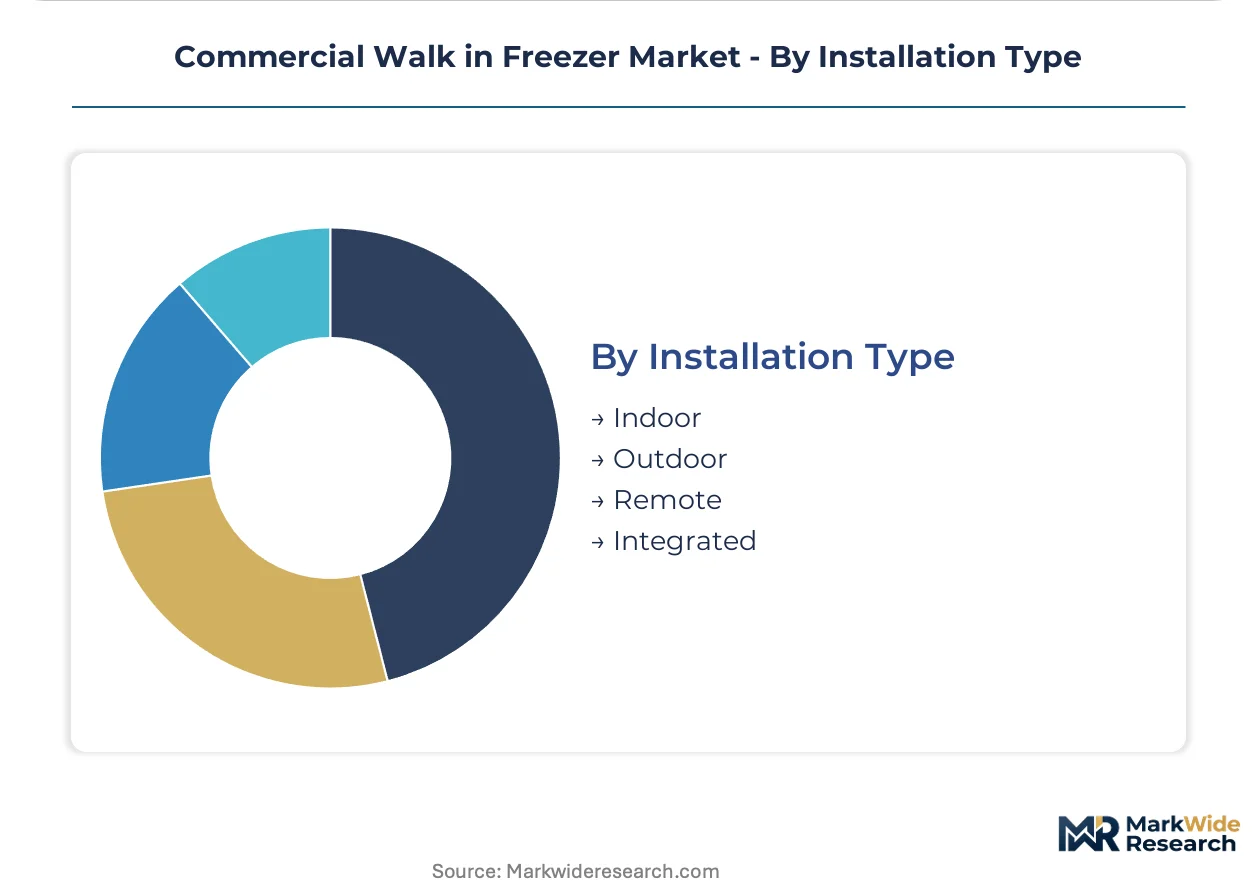
| Segmentation | Product Type: Modular, Custom Built, Blast Freezers, Display Freezers End User: Restaurants, Grocery Stores, Food Distributors, Warehouses Refrigerant Type: HFC, CO2, Ammonia, Hydrocarbon Installation Type: Indoor, Outdoor, Remote, Integrated |
| Companies Covered | Hussmann Corporation, Kolpak, Nor-Lake, Inc., Master-Bilt, SRC Refrigeration, Arctic Walk in Coolers & Walk In Freezers, American Panel Corporation, Carrier Commercial Refrigeration, Danfoss A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Walk in Freezer Market Strategic Shifts
Digital infrastructure is virtualizing how cold storage assets are monitored, maintained, and monetized across foodservice and retail operations. Three developments are restructuring competitive positioning.
Remote diagnostics platforms are virtualizing the traditional service technician dispatch model. Large restaurant chains and grocery distributors are deploying cloud-connected compressor and temperature monitoring systems that enable predictive failure detection. This compression of the maintenance response cycle is reducing unplanned downtime and shifting vendor relationships toward subscription-based service tiers.
The EPA's AIM Act implementation is forcing refrigerant architecture decisions across the installed base. Equipment purchasers face narrowing windows to transition from high-GWP hydrofluorocarbon systems to hydrocarbon or CO2 alternatives. Foodservice operators in California and New York are responding earliest due to overlapping state efficiency mandates that accelerate payback calculations for premium insulation and variable-speed drive configurations.
Equipment procurement is consolidating through integrated solution contracts that bundle panels, refrigeration systems, installation, and compliance documentation. Independent restaurants and regional grocery chains are bypassing traditional distributor markups by purchasing directly from manufacturers with captive installation networks. This channel compression is most pronounced in Texas and Florida corridors where rapid-ship modular programs compete on lead time rather than specification depth.
Commercial Walk in Freezer Market Segmentation
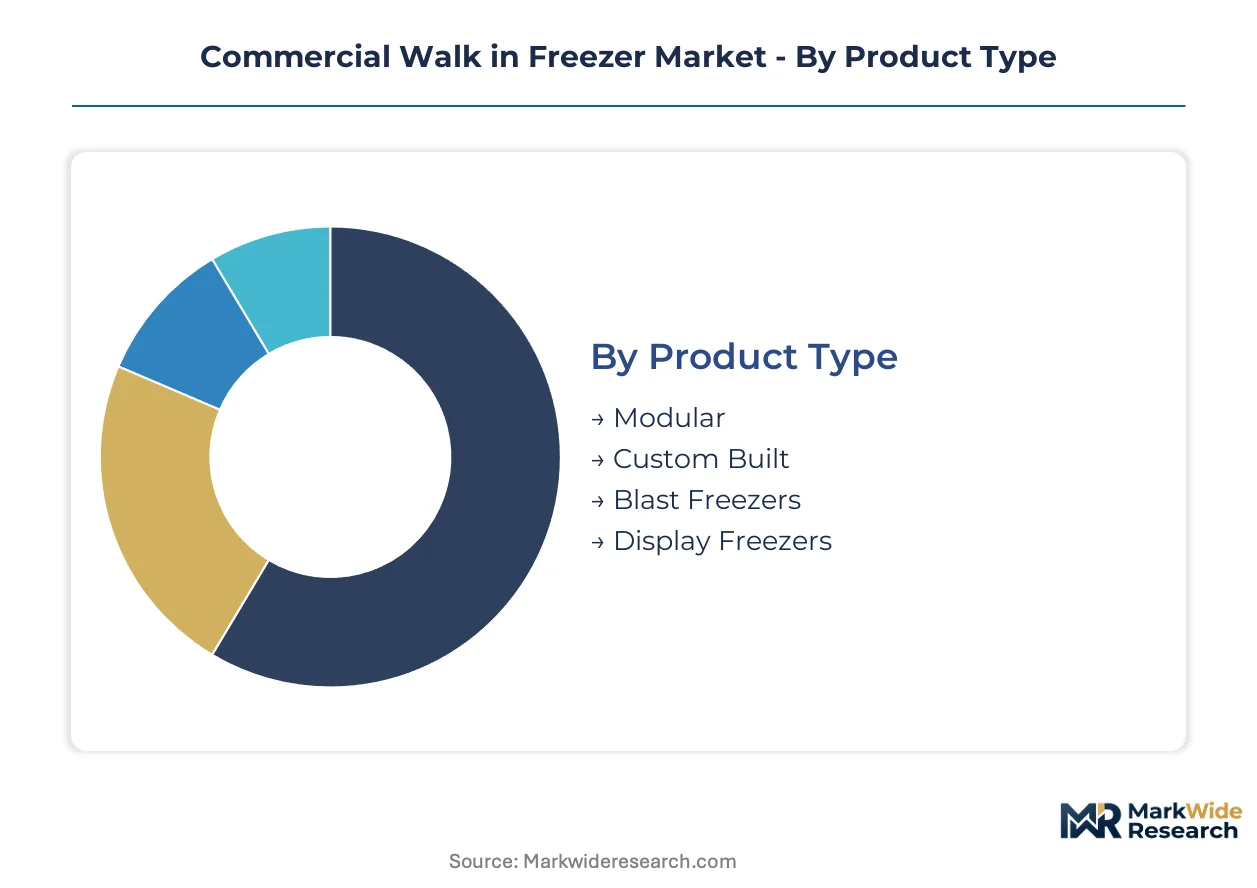
Commercial walk-in freezer procurement decisions cluster around installation complexity, refrigerant compliance timelines, and operational throughput requirements. Service contract structures and lifecycle cost models vary dramatically across these segment boundaries, reshaping vendor-customer relationships.
Product Type:
After-sales service intensity escalates with panel customization depth and temperature pull-down specifications, driving multi-year maintenance attachments.
- Modular:Prefabricated polyurethane panel systems with cam-lock joints enable rapid field assembly and standardized replacement protocols. Demand concentrates among quick-service restaurant chains and regional grocery operators in Texas and Florida corridors where rapid-ship programs compress project timelines. Service intensity remains moderate due to interchangeable component availability.
- Custom Built:Site-fabricated enclosures accommodate irregular footprints and extreme capacity requirements in protein processing facilities. Specifications from Pacific Northwest seafood distributors emphasize blast-compatible configurations with reinforced floor systems. These installations demand specialized technician networks and extended warranty negotiations.
- Blast Freezers:High-velocity airflow systems achieve rapid temperature reduction for quality-sensitive inventory.
- Display Freezers:Glass-front configurations merge storage with customer-facing retail presentation.
By volume, Modular leads. By growth pace, Blast Freezers is ahead.
End User:
Capital deployment cycles and refrigerant transition urgency diverge sharply across operator categories, with enterprise-scale buyers front-running compliance investments.
- Restaurants:Ghost kitchen infrastructure expansion and prepared meal delivery centralization are driving dedicated cold storage footprints. National chains specify remote monitoring integration to synchronize with existing kitchen automation architectures. California operators face overlapping Title 24 efficiency mandates that accelerate equipment replacement.
- Grocery Stores:Supermarket operators are specifying CO2 transcritical systems to preempt EPA AIM Act enforcement milestones. Large-format retailers bundle walk-in installations with HVAC lifecycle contracts through integrated service providers. Energy cost exposure drives premium insulation specifications.
- Food Distributors:Third-party logistics operators manage multi-temperature custody requirements across regional distribution networks.
- Warehouses:Bulk storage facilities prioritize cubic efficiency and pallet density over temperature pull-down speed.
By installed base, Restaurants dominate. By specification sophistication, Grocery Stores pulls ahead.
Refrigerant Type:
Regulatory phasedown timelines are compressing decision windows, with state-level efficiency mandates layering additional compliance complexity onto federal requirements.
- HFC:Hydrofluorocarbon systems face declining specification share as EPA AIM Act milestones approach. Existing installed base retrofits dominate current service revenue for legacy equipment providers. Replacement economics favor full system swaps over refrigerant conversions in most applications.
- CO2:Transcritical architectures command premium positioning in supermarket and protein processing segments where energy efficiency improvements offset higher capital outlays. California and New York operators are responding earliest to overlapping state mandates. Technician certification scarcity constrains deployment velocity in secondary markets.
- Ammonia:Industrial-scale systems retain cost advantages in facilities above 100,000 square feet despite OSHA Process Safety Management overhead.
- Hydrocarbon:Propane and isobutane alternatives are gaining traction in smaller-capacity installations with charge limits.
By current installed base, HFC retains dominance. By specification momentum, CO2 is climbing the fastest.
Installation Type:
Site constraints and existing building automation compatibility determine procurement channel selection and integration cost exposure.
- Indoor:Climate-controlled mechanical room installations minimize compressor exposure and simplify maintenance access. Foodservice operators in dense urban markets prioritize these configurations to satisfy fire code and ventilation requirements. Integration with existing building management systems drives specification complexity.
- Outdoor:Weatherized condensing units reduce indoor space allocation but introduce ambient temperature performance variability. Gulf Coast and Southwest operators specify enhanced corrosion protection and elevated mounting platforms. Remote monitoring becomes essential for failure detection in unattended exterior configurations.
- Remote:Split-system architectures separate evaporator and condenser locations across facility footprints.
- Integrated:Packaged refrigeration systems ship pre-charged from factory, minimizing field labor and leak risk.
By shipment volume, Indoor leads. By growth trajectory, Outdoor is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach cold chain corridor anchors North American walk-in freezer procurement velocity, connecting trans-Pacific protein imports to inland distribution networks through temperature-controlled rail and trucking infrastructure.
United States
Ghost kitchen proliferation across Texas and Florida corridors drives modular freezer specification for rapid deployment timelines. The EPA's AIM Act refrigerant phasedown compresses replacement cycles, with California Title 24 codes layering efficiency mandates atop federal requirements. Pacific Northwest seafood processors concentrate blast freezer demand in Seattle-Tacoma industrial zones.
Germany
Supermarket operators accelerate CO2 transcritical system adoption ahead of EU F-Gas Regulation enforcement milestones. The country's national energy efficiency regulator mandates commercial refrigeration performance thresholds that favor variable-speed compressor architectures. Bavarian food distributors anchor specification sophistication in Munich-Stuttgart industrial corridors.
China
Cold chain modernization for domestic protein consumption drives bulk freezer infrastructure investment across Yangtze River Delta logistics hubs. The Ministry of Ecology and Environment enforces dual carbon goals that constrain hydrofluorocarbon refrigerant availability. Qingdao seafood processing clusters specify rapid-pull-down configurations for export-quality preservation.
Japan
Convenience store chains consolidate prepared meal production into centralized commissary freezers with remote monitoring integration. METI commercial refrigeration efficiency standards accelerate equipment replacement among aging installed base operators. Osaka-Kobe port logistics zones concentrate blast freezer demand for imported protein redistribution.
Brazil
Beef export processors expand cold storage capacity to maintain temperature custody through port-to-vessel handoffs. The national agricultural regulator enforces sanitary certification requirements that favor modular replacement protocols over custom fabrication. São Paulo state foodservice distributors drive specification volume for rapid-ship panel systems.
Commercial Walk in Freezer Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream, supplying panels and refrigeration units to downstream assemblers. The vendor base clusters around three strategic archetypes: captive-installation manufacturers, pure-play panel fabricators, and lifecycle service contractors. Consolidation pressure concentrates among mid-scale regional distributors facing channel compression from direct manufacturer engagement. Competitive moves center on geographic density investments and refrigerant transition readiness.
Within the integrated-manufacturer tier, Hussmann Corporation and Nor-Lake, Inc. exemplify archetypes combining vertical manufacturing control with rapid-ship distribution networks. Carrier Commercial Refrigeration occupies a position bridging HVAC service infrastructure into walk-in freezer lifecycle contracts. These three anchors represent divergent strategic postures: captive supply chain integration, corridor-focused geographic density, and cross-platform service extension.
| Leading Market Players |
|---|
| Hussmann Corporation |
| Kolpak |
| Nor-Lake, Inc. |
| Master-Bilt |
| SRC Refrigeration |
| Arctic Walk in Coolers & Walk In Freezers |
| American Panel Corporation |
| Carrier Commercial Refrigeration |
| Danfoss A/S |
| Others |
Value Chain & Pricing Dynamics
Polyurethane foam feedstock concentration in the US Gulf Coast and Northeast Asian petrochemical corridors directly shapes where margin pools accumulate across the walk-in freezer value chain. Panel fabricators with captive isocyanate supply agreements command pricing power over distributors dependent on spot-market blowing agent procurement.
Pricing Analysis
Volume-discount tiering structures separate national restaurant chains from independent operators and regional grocery distributors. Three-tier pricing stratifies across premium CO2 transcritical systems, standard hydrocarbon configurations, and economy HFC legacy replacements. Price differentiation centers on refrigerant compliance certification grade and remote monitoring integration depth. Pricing pressure stems from isocyanate cost volatility compressing panel manufacturer margins. Independent restaurants exhibit highest price sensitivity, while supermarket operators with energy cost exposure accept premium specifications for efficiency gains.
Supply Chain Analysis
Upstream feedstock flows from US, Chinese, and German petrochemical complexes supply polyurethane panel production. Component sourcing draws from Canadian aluminum extruders for cam-lock framing, South Korean compressor OEMs for refrigeration units, and domestic steel mills for reinforced floor systems. Single-source vulnerability concentrates in specialized blowing agent formulations subject to EPA phasedown restrictions. Distribution runs through dealer-direct channels and foodservice equipment distributors with captive installation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial walk-in freezer market is experiencing high-growth disruption as EPA AIM Act refrigerant mandates force replacement cycles and CO2 transcritical technology reshapes competitive positioning.
For Market Incumbents: Insulate market position by deepening backward integration into panel foam production to offset isocyanate cost volatility. Secure certified technician networks in Texas and Florida corridors before hydrocarbon and CO2 system deployment accelerates. Defend against modular rapid-ship competitors through lifecycle service contract bundling. For New Entrants and Emerging Players: Establish a beachhead in ghost kitchen infrastructure serving national restaurant chains with subscription-based remote monitoring offerings. Target Pacific Northwest seafood processing clusters where blast freezer specifications command premium positioning. Pursue direct procurement channel disruption in secondary markets with limited distributor density. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed foodservice equipment distributors facing channel compression from manufacturer-direct engagement. Long-term viability favors platforms with refrigerant transition readiness and IoT-enabled service revenue streams. Watch CO2 transcritical technician certification expansion rates as inflection indicator for deployment velocity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Readiness | EPA AIM Act compliance deadlines compress decision windows for HFC replacement across installed base. |
| Remote Monitoring Platform Integration | IoT sensor deployment creates recurring revenue streams and predictive maintenance differentiation. |
| Geographic Density Investment | Texas and Florida corridor coverage enables rapid-ship modular program competitiveness. |
| Technician Certification Expansion | CO2 transcritical and hydrocarbon system expertise constrains deployment velocity in secondary markets. |
| Backward Integration into Panel Production | Captive polyurethane foam supply insulates margins from isocyanate cost volatility. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with foodservice equipment distributors, restaurant chain procurement directors, refrigeration contractor networks, and cold storage facility operators; and secondary validation through EPA regulatory filings, DOE efficiency standard documentation, customs trade records for polyurethane panel imports, and foodservice industry association datasets. Bottom-up shipment estimates triangulated against top-down market sizing across product type, end user, and refrigerant category dimensions.
Forecast inputs considered replacement cycle acceleration from AIM Act phasedown milestones, ghost kitchen infrastructure expansion rates, and state-level efficiency mandate layering across the projection horizon. Segmentation modeling captured product type, end user category, refrigerant architecture, and installation configuration. CAGRs derived from equipment replacement velocity assumptions and cold chain modernization investment patterns.
Macroeconomic conditions sit as an overlay; deviation in construction activity indices, foodservice employment trends, or energy cost trajectories would shift the trajectory. Cross-checking against USDA cold storage capacity reports and EPA refrigerant consumption data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
Middle East and Africa Frozen Food Market
Processed and Frozen Foods
United Arab Emirates Frozen Food Market
Processed and Frozen Foods
United States Frozen Yogurt Market
Processed and Frozen Foods
Chilled Processed Food Market
Processed and Frozen Foods
Frozen Bread Market
Processed and Frozen Foods
Frozen Tart Shells Market
Processed and Frozen Foods
Middle East and Africa Ice Cream Market
Processed and Frozen Foods
Europe Frozen Pizza Market
Processed and Frozen Foods
Middle East and Africa Frozen Bread Market
Processed and Frozen Foods
Dehydrated Food Market
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Vegan Frozen Pizza Market
Processed and Frozen Foods
Asia Pacific Freeze Dried Product Market
Processed and Frozen Foods
Popsicle Market