
 Cleanroom Apparels Market | 2026-2036
Cleanroom Apparels Market Size, Share, and Industry Trends Forecast 2026-2036
Cleanroom Apparels Market Analysis
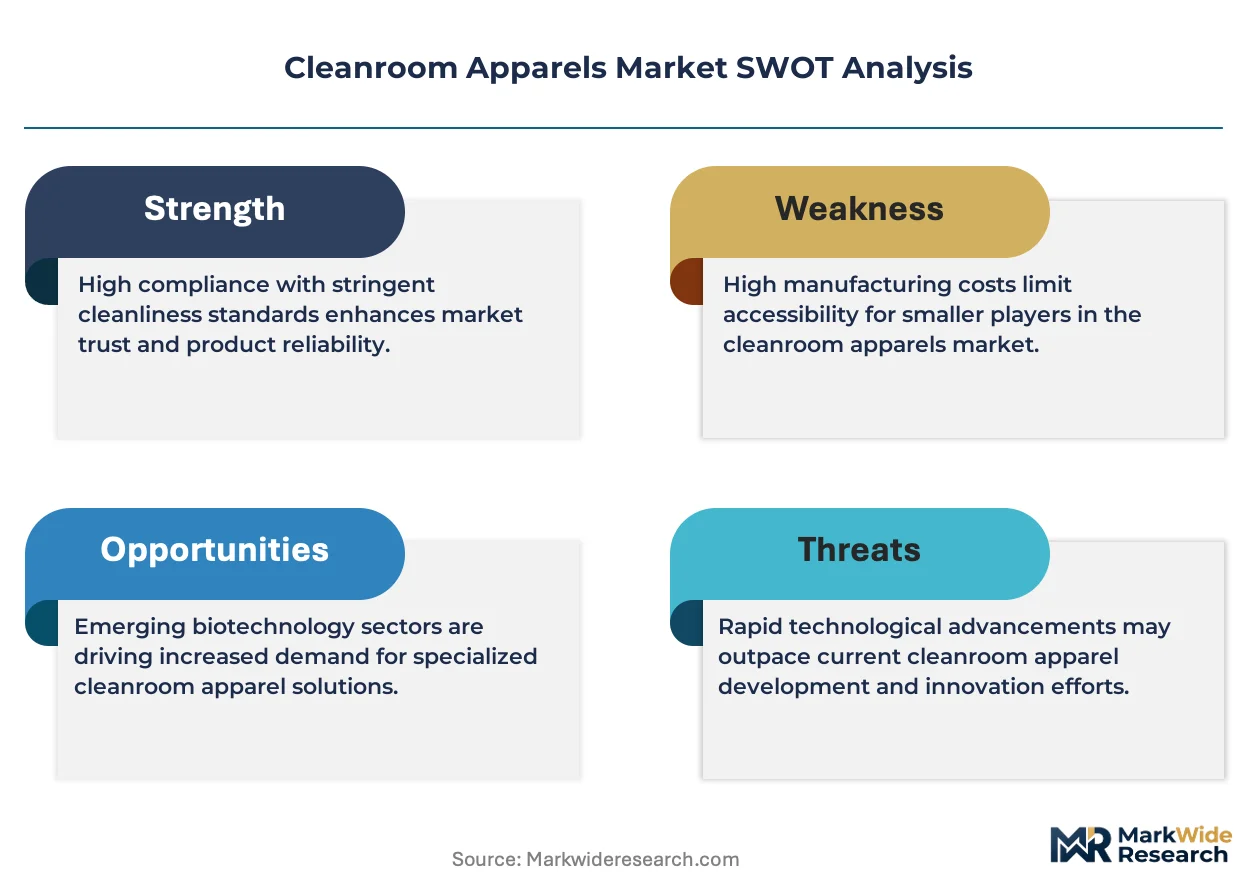
The EU Green Deal's textile sustainability benchmarks are restructuring procurement criteria for cleanroom consumables across European pharmaceutical operations. DuPont de Nemours Inc. leverages its Tyvek and ProShield material platforms to dominate high-barrier garment segments in semiconductor and biopharma cleanrooms. Lakeland Industries Inc. competes through specialized chemical protective apparel that extends into ISO Class 5-8 environments, while Ansell Ltd. anchors its position via integrated hand and body protection systems for sterile manufacturing suites.
Cleanroom apparels encompass controlled-environment garments engineered from non-linting synthetic substrates—typically polypropylene spunbond, polyester filament, or microporous polyethylene film laminates—to maintain particulate counts below specified ISO 14644 thresholds. These garments function as personnel-borne contamination barriers in environments where a single 0.5-micrometer particle can compromise batch integrity or microcircuit yield. Coveralls and gowns command the largest product-type revenue pools due to universal donning requirements across all ISO classifications, whereas microporous film and SMS materials capture expanding share as pharmaceutical aseptic processing and EU MDR compliance intensify barrier-performance specifications. The end-user concentration in pharmaceuticals and biotechnology generates the steepest margin premiums, with electronics and aerospace segments operating on higher-volume, lower-unit-cost procurement structures.
FDA quality system regulation and ISO 14644-1 standards govern particulate shedding and bioburden limits for US and international cleanroom operations, while the EU MDR imposes stricter sterile-barrier validation on garments entering European medical device supply chains. ECHA REACH compliance further constrains chemical treatments used in durable water-repellent finishes and antistatic coatings, elevating R&D costs for material suppliers. Stakeholders must monitor evolving convergence between pharmaceutical GMP requirements and semiconductor contamination-control protocols, as cross-industry standard harmonization threatens to obsolete single-use garment portfolios not engineered for dual-certification compliance.
Market Dynamics
ISO 14644-1 classification tightening and EU MDR sterile-barrier mandates are compressing the addressable market for legacy single-use garments while expanding specification requirements for reusable, dual-certified apparel systems.
Growth Catalysts
- Semiconductor Fab Expansion:Taiwan and South Korea fabrication facilities are scaling procurement of reusable polyester coveralls as contamination thresholds tighten below 0.5-micrometer particulate limits.
- EU MDR Barrier Mandates:European medical device regulations are elevating sterile-processing garment specifications, redirecting pharmaceutical demand toward microporous film laminates and SMS composites.
- Reusable Material Platforms:Polyester filament and spunbond polypropylene advances are extending garment lifecycle economics, capturing procurement preference in ISO Class 5-8 environments.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and polyethylene resin costs fluctuate with crude oil indices, compressing margin stability for spunbond and film laminate manufacturers.
- East Asian Supply Concentration:Taiwan, South Korea, and China host dominant textile substrate production, exposing downstream apparel assemblers to geographic concentration risk.
- REACH Chemical Constraints:ECHA restrictions on durable water-repellent fluorochemicals and antistatic coatings are elevating R&D compliance costs without immediate performance-equivalent substitutes.
Strategic Opportunities
- Indian Pharmaceutical Manufacturing:CDSCO and PLI scheme incentives are expanding sterile processing capacity, creating underpenetrated demand for ISO-certified garment systems.
- Biopharma Cell Therapy Suites:Aseptic processing for CAR-T and gene therapy manufacturing requires specialized barrier apparel with validated bioburden control.
- EU Green Deal Textile Benchmarks:Circular economy procurement criteria are creating preference for take-back and recycling programs in European pharmaceutical operations.
Industry Challenges
- Dual-Certification Engineering:Harmonizing pharmaceutical GMP and semiconductor contamination-control protocols demands material scientists capable of bridging ISO 14644 and FDA quality system requirements.
- Antistatic Coating Reformulation:Eliminating legacy chemical treatments while maintaining surface resistivity specifications is extending product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cleanroom Apparels Market |
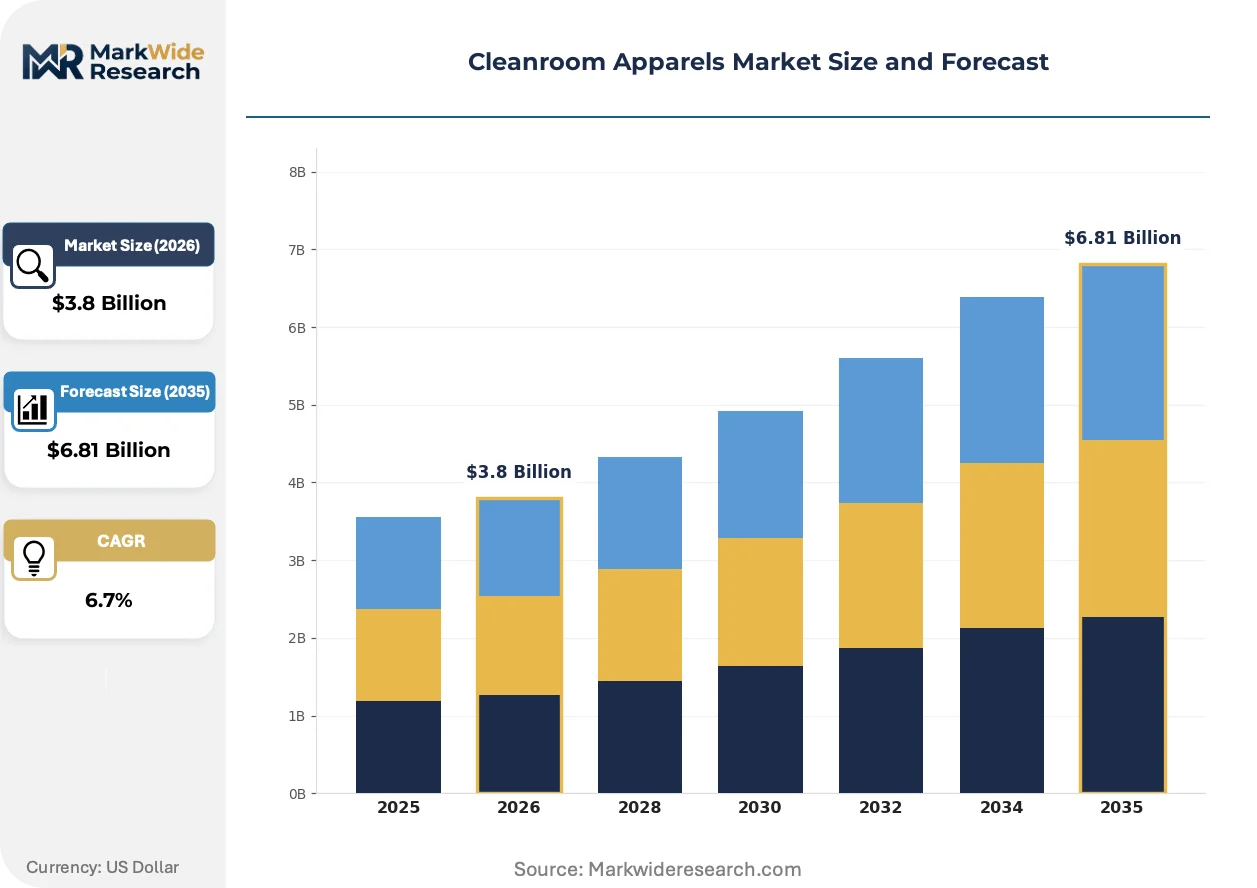
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coveralls, Gowns, Hoods, Shoe Covers Material: Polypropylene, Polyester, Microporous Film, SMS End User: Pharmaceuticals, Biotechnology, Electronics, Aerospace Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Kimberly-Clark Corporation, Lakeland Industries Inc., Ansell Ltd., Micronclean Ltd., Veltek Associates Inc., DuPont de Nemours Inc., Alpha Pro Tech Ltd., Valutek Inc., 3M Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cleanroom Apparels Market Emerging Trajectories
Material science convergence and regulatory specification layering are compressing the viable technology set for cleanroom apparel while expanding performance requirements across substrate categories.
Spunbond-meltblown-spunbond (SMS) composite fabrics are absorbing demand from traditional spunbond polypropylene in pharmaceutical aseptic suites. Biopharma sterile processors in Germany and Switzerland are specifying SMS for enhanced bacterial filtration efficiency. This material transition is absorbing volume share from lower-barrier alternatives as EU MDR validation requirements intensify.
EU MDR sterile-barrier validation mandates are restructuring garment qualification protocols for European medical device supply chains. Manufacturers must now demonstrate validated microbial barrier performance across distribution cycles. Pharmaceutical and biotechnology cleanrooms in France, Italy, and the Netherlands are responding with accelerated qualification of microporous film laminate garments.
Direct manufacturer contracting is displacing distributor intermediaries in high-volume semiconductor fabrication procurement. Taiwan and South Korea fab operators are consolidating vendor bases to capture lifecycle cost transparency. This channel compression is most visible in Hsinchu and Pyeongtaek industrial clusters where multi-year reusable garment service agreements are replacing spot purchasing.
Cleanroom Apparels Market Segmentation
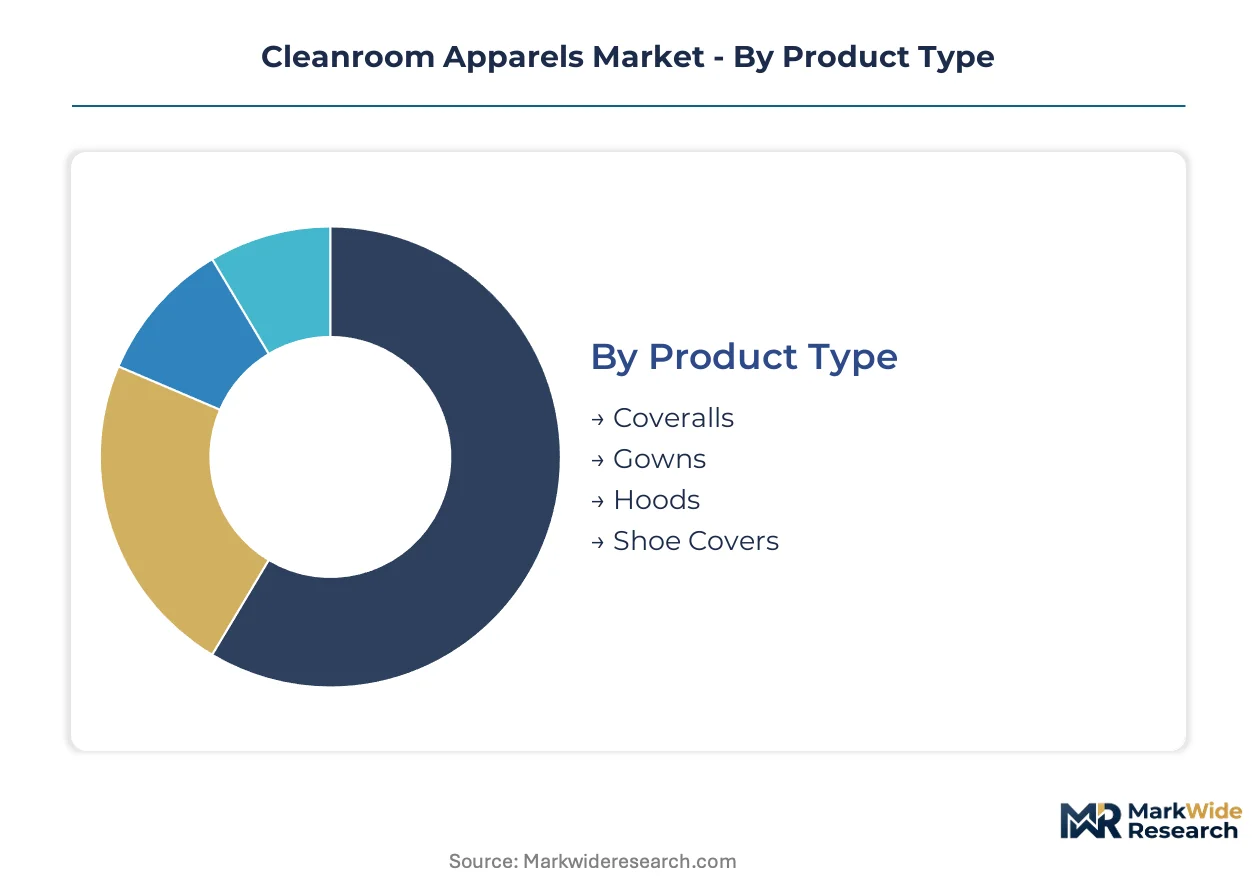
Cleanroom apparel procurement decisions cascade through material specifications, contamination thresholds, and end-use regulatory requirements. Understanding how buyers prioritize across these dimensions reveals where margin concentration and specification pressure concentrate.
Product Type:
Buyer prioritization hinges on body coverage requirements and ISO classification stringency, with universal donning mandates creating divergent volume-growth profiles across garment categories.
- Coveralls:Full-body polyester or polypropylene garments engineered for ISO Class 5-8 environments where particulate shedding from street clothing must be fully encapsulated. Semiconductor fabrication facilities in Taiwan and South Korea are scaling multi-year service agreements for reusable coveralls as contamination thresholds tighten below 0.5-micrometer limits.
- Gowns:Torso-and-limb coverage systems dominating pharmaceutical aseptic processing where frequent donning-doffing cycles demand tear-resistant spunbond or SMS constructions. EU MDR sterile-barrier mandates are redirecting procurement toward microporous film laminates and SMS composites with validated microbial barrier performance.
- Hoods:Head and neck enclosure systems preventing hair and dander release in biotechnology suites.
- Shoe Covers:Disposable polypropylene footwear barriers deployed universally across all ISO classifications for floor-borne particulate control.
Volume sits with coveralls; growth tilts toward gowns as pharmaceutical barrier specifications intensify.
Material:
Cost-performance tradeoffs and regulatory compliance layers are restructuring procurement preference across substrate technologies, with lifecycle economics and chemical treatment constraints driving material transitions.
- Polypropylene:Spunbond nonwoven substrates delivering baseline particulate filtration at lowest unit cost for high-consumption environments. Electronics and aerospace segments favor polypropylene for volume procurement structures where frequent replacement outweighs durability premiums.
- Polyester:Filament-woven or spun constructions enabling 50-100 wash cycles in reusable garment service programs. Semiconductor fabs in Hsinchu and Pyeongtaek industrial clusters are consolidating vendor bases around polyester lifecycle agreements to capture total cost transparency.
- Microporous Film:Polyethylene laminates providing liquid and microbial barrier performance for pharmaceutical sterile processing. EU MDR validation requirements are accelerating qualification of microporous film garments in France, Italy, and Netherlands biotechnology operations.
- SMS:Spunbond-meltblown-spunbond composites absorbing demand from traditional spunbond in Germany and Switzerland biopharma suites where bacterial filtration efficiency specifications have tightened.
Polypropylene dominates shipment volume; SMS and microporous film are climbing the fastest as barrier-performance specifications layer onto pharmaceutical procurement criteria.
End User:
Margin structure and specification intensity diverge sharply across end-use verticals, with regulatory burden and contamination consequence determining willingness-to-pay for premium barrier technologies.
- Pharmaceuticals:Sterile processing operations for injectables and biologics commanding steepest margin premiums due to FDA quality system regulation and EU MDR compliance burdens. Aseptic filling lines require validated garment systems with documented bioburden control across distribution cycles.
- Biotechnology:CAR-T and gene therapy manufacturing suites creating specialized demand for barrier apparel with cell therapy-specific contamination protocols. Cell therapy aseptic processing in Basel and Boston corridors is specifying SMS and microporous film combinations for enhanced environmental control.
- Electronics:Semiconductor and flat-panel display fabrication operating on higher-volume, lower-unit-cost procurement structures where particulate control targets yield tolerance rather than sterility.
- Aerospace:Satellite assembly and precision optics manufacturing requiring ISO 14644-1 compliance with less frequent garment changeout cycles than pharmaceutical operations.
Electronics generates largest unit volume; biotechnology represents the steepest expansion trajectory as cell therapy manufacturing capacity scales.
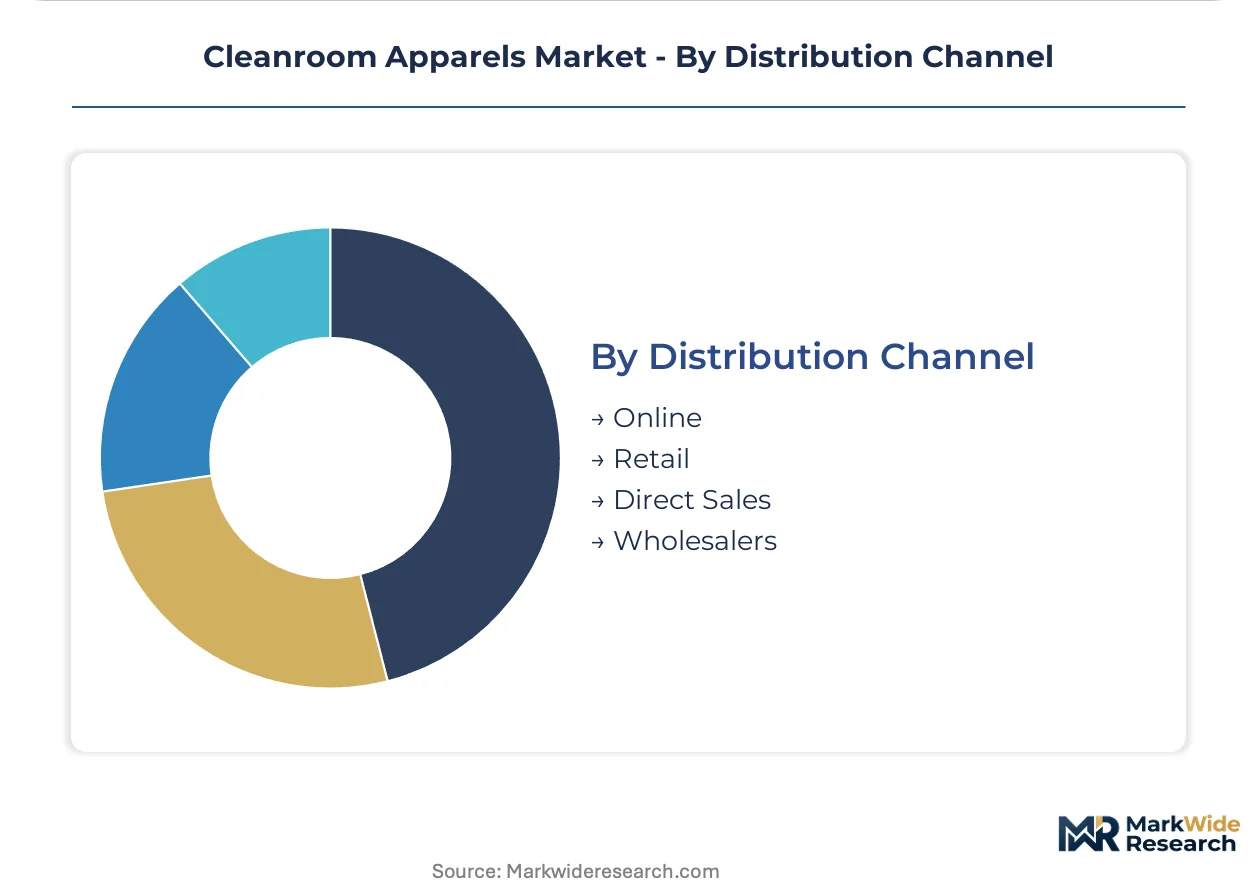
Distribution Channel:
Channel economics and procurement scale determine where direct manufacturer relationships displace intermediary margins, with volume concentration enabling vendor base consolidation.
- Direct Sales:Multi-year service agreements with garment laundering and replacement logistics bundled into per-use pricing. Taiwan and South Korea semiconductor clusters are compressing channel structure through direct contracting with reusable apparel specialists.
- Online:E-procurement platforms capturing spot purchasing for standardized disposable garments in lower-volume operations.
- Retail:Limited to emergency replenishment and small-scale laboratory operations lacking centralized procurement functions.
- Wholesalers:Distributor intermediaries maintaining inventory positions for pharmaceutical and biotechnology clients requiring rapid fulfillment of multiple garment SKUs.
Direct sales commands the largest contract value; online channels are gaining share fastest among mid-sized biotechnology operations consolidating vendor bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian fabrication clusters dominate cleanroom apparel consumption while European pharmaceutical operations drive specification intensity. Production concentrates in textile substrate manufacturing corridors that feed downstream garment assembly. Procurement patterns diverge sharply between semiconductor yield-management priorities and pharmaceutical sterility mandates.
United States
FDA quality system regulations govern sterile processing garment validation for pharmaceutical and biotechnology operations. The agency's bioburden control requirements are tightening documentation standards for reusable apparel systems. Greater Boston and Research Triangle Park clusters are scaling CAR-T manufacturing capacity, creating specialized demand for SMS composite garments with validated barrier performance.
Germany
EU MDR sterile-barrier mandates are restructuring qualification protocols for medical device supply chain garments. ECHA REACH constraints on fluorochemical treatments are elevating R&D costs for durable water-repellent finishes. Basel corridor biopharma operations are specifying microporous film laminates for aseptic filling lines as bacterial filtration efficiency thresholds tighten.
South Korea
MFDS pharmaceutical manufacturing standards are converging with semiconductor contamination-control protocols in multi-use cleanroom facilities. Pyeongtaek industrial cluster fab operators are consolidating vendor bases around multi-year reusable polyester coverall service agreements. Direct manufacturer contracting is displacing distributor intermediaries to capture lifecycle cost transparency.
Taiwan
ISO 14644-1 classification tightening below 0.5-micrometer particulate limits is accelerating procurement of washable polyester filament garments. Hsinchu Science Park semiconductor fabrication facilities are scaling procurement of reusable coverall systems with integrated antistatic performance. Channel compression toward direct sales is most visible in this cluster where spot purchasing is yielding to bundled service contracts.
India
CDSCO sterile manufacturing requirements and PLI scheme incentives are expanding pharmaceutical processing capacity. Maharashtra and Gujarat pharmaceutical corridors are creating underpenetrated demand for ISO-certified garment systems with validated bioburden control. Domestic textile substrate production is scaling to reduce import dependence for spunbond and SMS materials.
Cleanroom Apparels Market Vendor Landscape
The competitive structure tilts toward material-science specialists with integrated polymer platforms and regulatory validation capabilities. Consolidation pressure concentrates among spunbond and film laminate substrate suppliers while garment assembly remains fragmented across regional specialists. Two strategic archetypes dominate: diversified chemical conglomerates leveraging proprietary polymer platforms, and focused protective apparel specialists competing through certification depth. Capacity expansion in SMS composite manufacturing and geographic extension into Indian pharmaceutical corridors represent the primary competitive vectors.
Among diversified material-science conglomerates, DuPont de Nemours Inc. and 3M Co. occupy positions anchored by proprietary microporous film and nonwoven platforms. Lakeland Industries Inc. exemplifies the specialized protective apparel archetype, competing through chemical protective expertise that extends into controlled-environment applications. These three entities represent contrasting strategic postures: integrated polymer-to-garment control versus focused certification and application engineering.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| Lakeland Industries Inc. |
| Ansell Ltd. |
| Micronclean Ltd. |
| Veltek Associates Inc. |
| DuPont de Nemours Inc. |
| Alpha Pro Tech Ltd. |
| Valutek Inc. |
| 3M Co. |
| Others |
Supply Flow & Price Mechanics
Multi-year reusable garment service agreements in Taiwan and South Korea semiconductor clusters are compressing spot-purchasing premiums and forcing suppliers toward lifecycle pricing models anchored in total cost-per-use transparency.
Pricing Analysis
Yield-protection value anchors pricing for semiconductor-grade polyester coveralls, with foundries paying premiums for validated particulate control below 0.5-micrometer thresholds. Three-tier pricing structure across premium, standard, and economy levels separates ISO Class 5-6 validated garments from Class 7-8 alternatives and generic polypropylene disposables. Price differentiation rests on certification depth and laundering-logistics bundling. Cost compression in standard-tier spunbond polypropylene is intensifying because petrochemical feedstock volatility compresses margin buffers. Electronics procurement teams exhibit highest price sensitivity; biopharma sterile processors show lowest sensitivity due to batch-integrity risk exposure.
Supply Chain Analysis
Direct-to-fab channels handle high-volume semiconductor demand in Hsinchu and Pyeongtaek, while wholesaler intermediaries maintain inventory positions for fragmented pharmaceutical operations. Raw material supply draws from polypropylene and polyethylene resin production concentrated in China, South Korea, and Saudi Arabia, with polyester filament weaving centered in Taiwan and Vietnam. Antistatic coating chemistries hinge on fluorochemical feedstocks constrained by ECHA REACH restrictions. Single-source vulnerability in specialized SMS composite manufacturing elevates qualification risk for European biopharma garment suppliers. Distribution runs through direct manufacturer contracting for reusable programs and e-procurement platforms for disposable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR sterile-barrier validation mandates have erected a compliance moat that rewards incumbent material-science specialists with documented microbial barrier performance while filtering out undifferentiated garment assemblers.
For Market Incumbents: Extend certification depth into dual-use pharmaceutical-semiconductor applications before ISO 14644-1 harmonization accelerates. Invest in captive SMS composite manufacturing capacity to reduce dependence on concentrated substrate suppliers. Threat substitution from reusable polyester lifecycle economics demands backward integration into filament-woven production to defend margin position against vertically integrated competitors. For New Entrants and Emerging Players: Capture underpenetrated demand in Indian pharmaceutical corridors where CDSCO compliance requirements are expanding faster than domestic garment qualification capacity. Target Maharashtra and Gujarat sterile processing facilities with ISO-certified coverall systems priced below imported alternatives. Go-to-market angle: bundled bioburden validation documentation that accelerates customer regulatory audits. For Investors and Strategic Acquirers: The window for entry favors material-science specialists with proprietary polymer platforms and existing FDA master file documentation. Long-term viability hinges on exposure to biotechnology cell therapy manufacturing expansion rather than commoditized electronics volume. Signal to watch: acceleration of direct manufacturer contracting in East Asian semiconductor clusters as channel compression indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SMS Composite Manufacturing | Captures margin from substrate suppliers while securing supply continuity for EU MDR-validated garment production. |
| Dual-Certification R&D Investment | Positions portfolios for ISO 14644-1 and FDA quality system harmonization across pharmaceutical and semiconductor end uses. |
| Indian Pharmaceutical Corridor Expansion | Exploits CDSCO capacity expansion and PLI scheme incentives with localized ISO-certified garment assembly. |
| Take-Back and Recycling Program Launch | Aligns procurement preference with EU Green Deal textile benchmarks in European pharmaceutical operations. |
| Direct Manufacturer Contracting Scale-Up | Mirrors Taiwan and South Korea fab procurement consolidation with lifecycle service agreements replacing distributor intermediaries. |
Methodological Framework
Multi-period observation of ISO 14644-1 classification tightening, EU MDR implementation timelines, and semiconductor fab capacity announcements anchored the trend analysis, supplemented by interviews with cleanroom operations managers, pharmaceutical quality assurance directors, textile substrate procurement leads, and regulatory affairs specialists at EMA-notified bodies. Secondary validation drew from FDA 483 inspection observations, ECHA REACH restriction dossiers, SEC 10-K filings of listed protective apparel manufacturers, and customs trade data for polypropylene and polyethylene resin flows. Bottom-up garment shipment estimates triangulated against top-down end-use capacity projections across semiconductor, pharmaceutical, and biotechnology verticals.
Input-output matrices modeled demand as a function of cleanroom square footage expansion, personnel density per ISO classification, and garment changeout frequency protocols. Segmentation dimensions spanned product type, material substrate, end-user industry, and distribution channel structure across the projection horizon. CAGRs were derived from regression analysis of historical procurement patterns against regulatory implementation schedules and capacity buildout announcements. Industry-specific forecast inputs included semiconductor yield-loss cost models and pharmaceutical batch-rejection risk valuations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH chemical restriction scope expansion and petrochemical feedstock price volatility. Practitioners should monitor ECHA restriction proposal timelines and East Asian fab capital expenditure announcements for early signals of material specification shifts and procurement volume inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Rolle Market
Apparel Textiles
Uniform Market
Apparel Textiles
School Uniform Market
Apparel Textiles
Maternity Wear Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
Global Prom Dresses Market
Apparel Textiles
Global Maternity Innerwear Market
Apparel Textiles
Global Textile Garment Market
Apparel Textiles
Horse Riding Apparel Market
Apparel Textiles
Dye Sublimated Apparel Market
Apparel Textiles
TIC for Apparel Market
Apparel Textiles
Insect Repellent Apparel Market
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
China Denim Jeans Market
Apparel Textiles
Zipper Market
Apparel Textiles
Down Jacket Market