
 North America Footwear Sole Material Market | 2026-2036
North America Footwear Sole Material Market Size, Share, and Industry Trends Forecast 2026-2036
North America Footwear Sole Material Market Analytics
Subscription-based material performance monitoring is consolidating how footwear brands evaluate sole durability across product lifecycles. Dow Inc. leverages its integrated polyurethane precursor supply chain to serve athletic footwear compounders along the Gulf Coast. Huntsman Corporation sustains R&D intensity in low-density EVA formulations for running shoe midsoles. BASF SE anchors its position through specialty elastomer grades that meet brand-specific rebound and compression-set requirements.
Footwear sole material encompasses the structural bottom layer of shoes, engineered from rubber compounds, ethylene-vinyl acetate foam, polyurethane elastomers, or treated leather to provide abrasion resistance, energy return, and ground contact stability. Manufacturing typically involves injection molding of thermoplastic polyurethane at temperatures between 180°C and 220°C, followed by surface texturing for traction pattern definition. EVA dominates volume in athletic applications where weight reduction drives specification, while polyurethane commands premium positioning in work boots and outdoor footwear requiring oil and chemical resistance. Rubber maintains share in specialty segments where wet-grip performance and moldability for complex lug geometries remain critical.
The EPA enforces volatile organic compound limits under TSCA Section 5 for new chemical introductions in adhesive and coating formulations used in sole assembly, pushing manufacturers toward water-based bonding systems. The Consumer Product Safety Commission monitors phthalate content in plasticized sole components, particularly for children's footwear categories. State-level extended producer responsibility frameworks in California and New York are beginning to require recyclability disclosures for footwear sold in those jurisdictions. Stakeholders must track how evolving chemical restriction timelines interact with material substitution lead times to avoid supply discontinuities.
Market Dynamics
Bio-based polyurethane formulations are overtaking petroleum-derived alternatives as athletic footwear brands impose lifecycle carbon thresholds on sole material suppliers, compressing the addressable market for conventional chemistries.
Growth Catalysts
- EPA TSCA volatility standards:The agency's tightening limits on solvent-based adhesive emissions are accelerating water-based bonding system adoption across southeastern US manufacturing clusters.
- Extended producer responsibility frameworks:California and New York state mandates for recyclability disclosures are forcing material transparency that favors suppliers with certified circular supply chains.
- Polymer compounding cluster proximity:Concentrated raw material processing along the Gulf Coast reduces logistics friction for contract manufacturers serving major athletic brands.
Market Restraints
- Petrochemical feedstock volatility:Crude oil price instability directly impacts TPU and EVA resin cost structures, compressing compounder margins during upstream spikes.
- Adhesive formulation transition costs:Water-based bonding systems require capital-intensive equipment retooling that smaller sole assembly operations cannot absorb.
- Phthalate substitution complexity:The Consumer Product Safety Commission's monitoring of plasticized components in children's footwear forces reformulation cycles that extend product development timelines.
Strategic Opportunities
- Subscription-based performance monitoring:Brands are consolidating sole durability evaluation across product lifecycles, creating recurring revenue streams for material data analytics providers.
- Mexican nearshoring expansion:Footwear contract manufacturers are establishing compounding capabilities in Guanajuato and Querétaro to serve US brands seeking tariff-advantaged supply.
- Work boot premiumization:Oil-resistant polyurethane grades command specification premiums in industrial safety segments where ASTM F2413 compliance is mandatory.
Industry Challenges
- Injection molding technician scarcity:TPU processing at 180°C to 220°C requires specialized thermal management expertise that vocational programs are not producing at sufficient scale.
- Multi-material sole integration:Complex midsole-outsole bonding across EVA-PU-rubber combinations creates defect-rate variability that automated vision systems struggle to detect.
- State-level regulatory fragmentation:Divergent chemical disclosure requirements between California's Safer Consumer Products program and New York's emerging framework force redundant compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Footwear Sole Material Market |
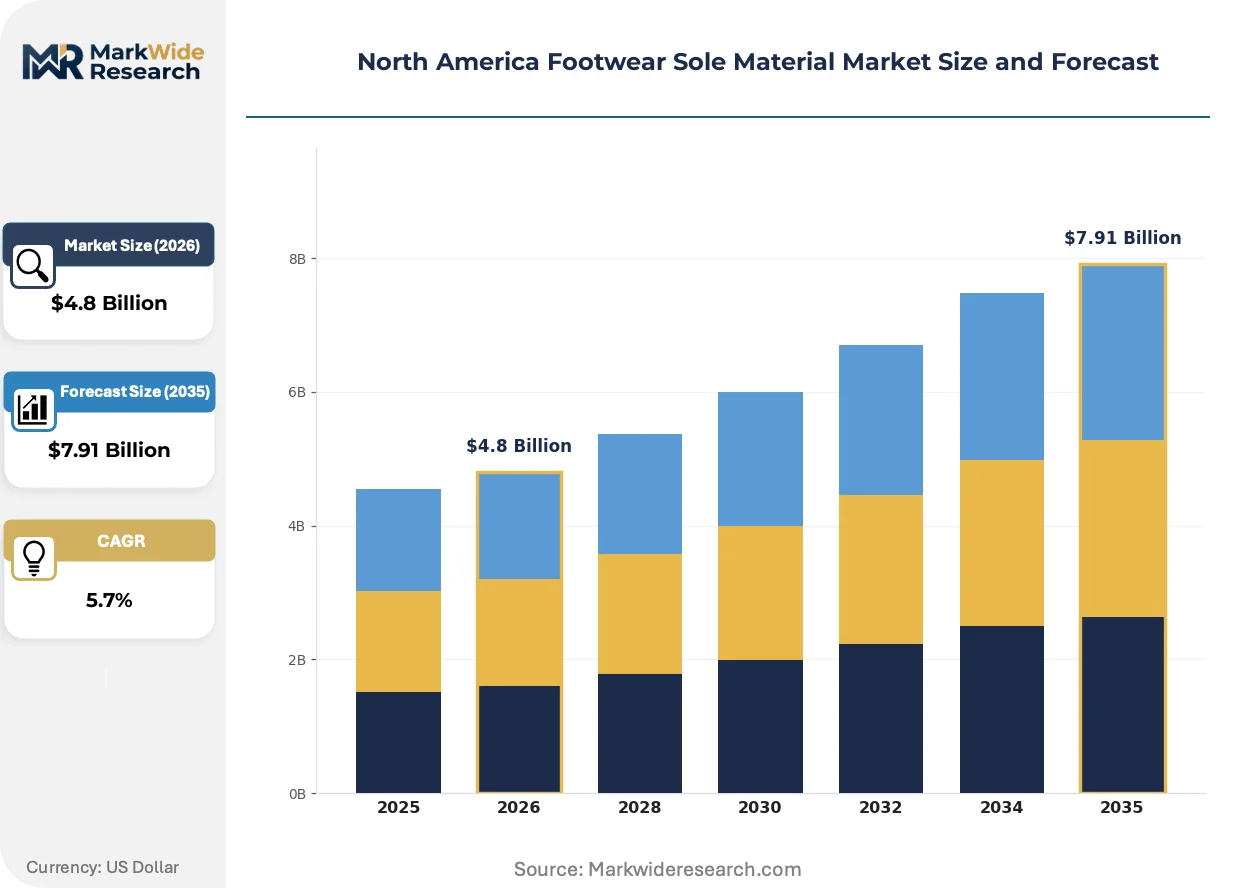
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Rubber, EVA, Polyurethane, Leather End User: Sports Brands, Fashion Retailers, Casual Footwear, Specialty Stores Manufacturing Process: Injection Molding, Compression Molding, Extrusion, Handcrafted Application: Outdoor Footwear, Athletic Footwear, Dress Shoes, Work Boots |
| Companies Covered | Dow Inc., Huntsman Corporation, BASF SE, Covestro AG, Solvay S.A., Evonik Industries AG, SABIC, Arkema S.A., Vibram S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Footwear Sole Material Market Evolving Landscape
Material science convergence with digital manufacturing is restructuring how sole properties are specified, tested, and validated before physical prototyping begins.
Supercritical foam expansion is overtaking traditional chemical blowing agents in running shoe midsole production. The process injects nitrogen or carbon dioxide into TPU pellets under extreme pressure, creating cell structures that deliver superior energy return. Major athletic brands have shifted specification sheets toward this chemistry. Conventional EVA compression molding is losing share in performance segments where rebound metrics determine shelf placement.
EPA enforcement of volatile organic compound limits under TSCA Section 5 is forcing adhesive manufacturers to retire solvent-based formulations. The industrial consequence is a supply bottleneck for water-based alternatives that cure at lower temperatures. Children's footwear categories face the tightest compliance timelines, pushing brands toward pre-certified bonding systems from established suppliers.
Direct-to-brand material specification is displacing traditional distributor-mediated procurement in high-volume athletic segments. Compounders now maintain technical sales teams that engage footwear developers during early design phases. This pattern concentrates most visibly in Portland, Oregon and Boston, Massachusetts, where major brand headquarters sit adjacent to regional material innovation labs.
North America Footwear Sole Material Market Segmentation
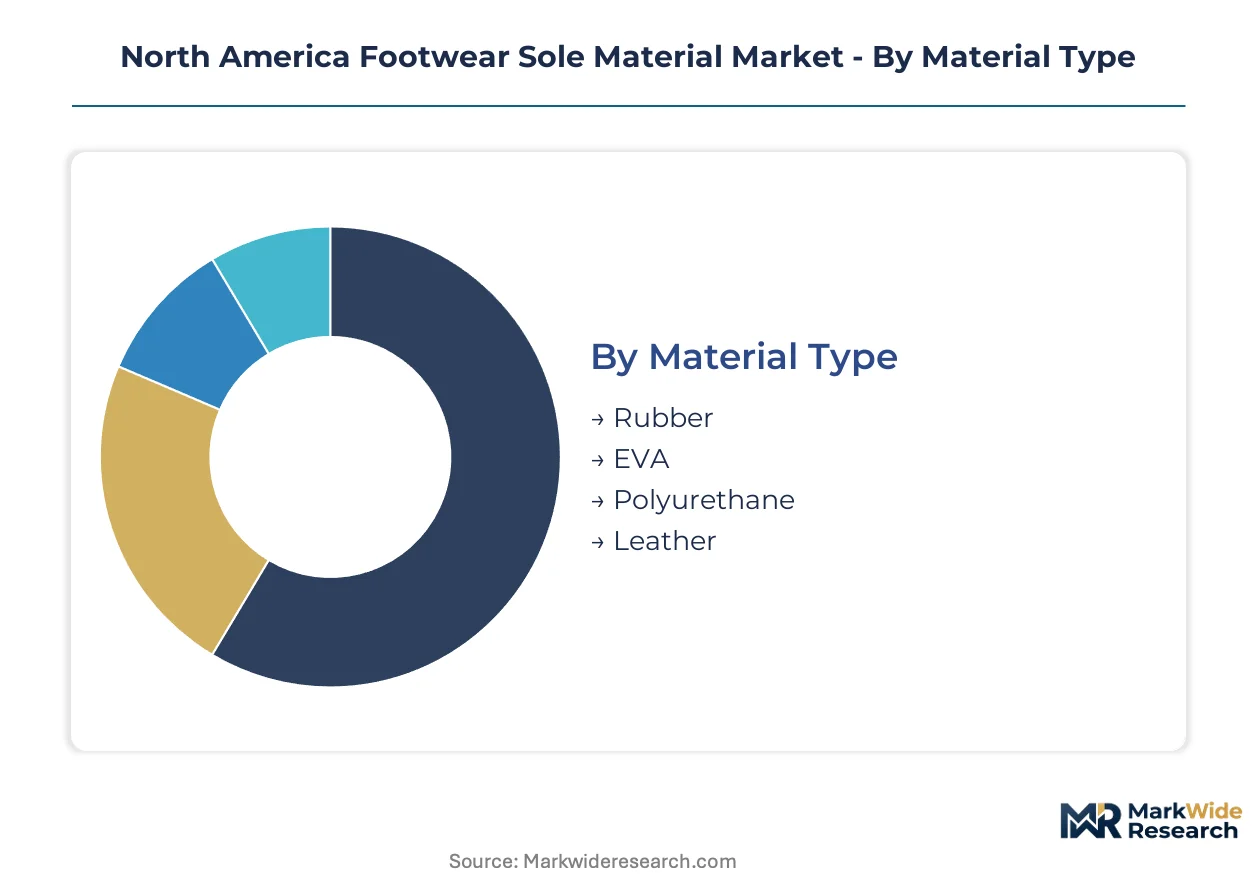
Sole material specification varies sharply across end-use categories, with athletic brands demanding compression-set performance that dress shoe manufacturers ignore. Material selection directly determines manufacturing process compatibility and regional supply chain configuration.
Material Type:
Capital intensity peaks with polyurethane systems requiring precursor storage and reaction injection equipment, while rubber compounding demands less sophisticated mixing infrastructure.
- Polyurethane:Thermoplastic and cast elastomer grades deliver oil resistance and rebound energy for industrial safety applications. Demand concentrates in southeastern US manufacturing clusters serving work boot brands under ASTM F2413 compliance mandates. The chemistry commands premium positioning but faces feedstock volatility from crude-linked isocyanate pricing.
- EVA:Ethylene-vinyl acetate foam dominates athletic midsole volume through supercritical nitrogen expansion, replacing chemical blowing agents in running shoe specifications. Portland and Boston brand headquarters drive formulation requirements for this segment.
- Rubber:Natural and synthetic compounds maintain wet-grip performance in outdoor lug patterns where moldability for complex geometries remains critical.
- Leather:Treated hides serve heritage dress shoe categories with limited volume but stable artisanal supply chains.
Most installed capacity flows through EVA. Expansion is steepest in polyurethane bio-based formulations.
End User:
Procurement scale separates the segment, with sports brands consolidating specification authority while fashion retailers fragment across seasonal collections.
- Sports Brands:Athletic footwear manufacturers impose lifecycle carbon thresholds and durability testing protocols on compounders. Direct technical engagement during design phases has displaced distributor-mediated procurement in high-volume segments.
- Fashion Retailers:Seasonal trend cycles drive shorter material commitment windows and higher SKU volatility.
- Casual Footwear:Mid-market positioning balances cost sensitivity with basic performance requirements.
- Specialty Stores:Niche outdoor and medical footwear demands command specialized compound formulations at lower volumes.
Sports brands absorb the majority of premium material R&D investment. Specialty stores are gaining specification influence in sustainability-certified segments.
Manufacturing Process:
Process selection locks in equipment amortization schedules and labor skill requirements that vary dramatically across the technology spectrum.
- Injection Molding:TPU processing at 180°C to 220°C requires thermal management expertise that vocational programs are not producing at sufficient scale. The method dominates athletic outsole production where dimensional precision matters.
- Compression Molding:EVA sheet forming retains share in cost-sensitive casual segments despite slower cycle times.
- Extrusion:Continuous profile production serves specific geometries in work boot midsoles.
- Handcrafted:Artisanal methods persist in leather sole attachment for heritage dress footwear.
Injection molding holds the most installed equipment base. Compression molding is losing share fastest to supercritical foam alternatives.
Application:
Performance certification requirements fragment the segment, with industrial safety mandates creating specification barriers that athletic and fashion segments avoid.
- Work Boots:Oil-resistant polyurethane grades command specification premiums where ASTM F2413 compliance is mandatory. Mexican nearshoring expansion in Guanajuato and Querétaro targets this segment's tariff-sensitive supply needs.
- Athletic Footwear:Energy return metrics determine shelf placement, with supercritical TPU foams displacing conventional EVA in performance running categories.
- Outdoor Footwear:Wet-grip rubber formulations and multi-material bonding complexity create defect-rate challenges.
- Dress Shoes:Aesthetic finish and leather compatibility constrain material innovation in this traditional segment.
Work boots concentrate the highest material specification premiums. Athletic footwear is expanding most quickly in bio-based polyurethane adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's footwear manufacturing base is expanding faster than Canada's established polymer distribution network, creating divergent sourcing patterns across the continent.
United States
Athletic brands headquartered in Portland and Boston drive specification requirements for supercritical foam formulations. EPA enforcement of TSCA Section 5 volatility limits accelerates water-based adhesive adoption across southeastern manufacturing clusters. Polymer compounding operations along the Gulf Coast reduce logistics friction for contract manufacturers serving major sports brands.
Mexico
Nearshoring momentum concentrates in Guanajuato and Querétaro as brands seek tariff-advantaged supply for work boot production. Mexican labor costs attract injection molding operations that serve ASTM F2413-compliant industrial safety segments. Querétaro's emerging compounding capabilities target oil-resistant polyurethane grades for premium work footwear.
Canada
Ontario's chemical distribution infrastructure supports footwear manufacturers importing specialty elastomer grades from European suppliers. Health Canada monitors phthalate content in children's footwear under the Canada Consumer Product Safety Act. Toronto-area logistics hubs facilitate just-in-time delivery of TPU resins to mid-market athletic brands.
North America Footwear Sole Material Market Competitive Landscape
Top-tier vendors anchor premium elastomer supply, while regional compounders occupy cost-sensitive segments. The structure splits between integrated petrochemical producers and specialized formulation houses. Three archetypes dominate: precursor-integrated suppliers, performance-grade compounders, and niche sustainability-certified operators. Capacity expansion and direct technical sales engagement constitute the primary competitive vectors.
Within the integrated chemical producer tier, Dow Inc., Huntsman Corporation, and BASF SE exemplify backward control over polyurethane precursor supply chains. These entities occupy positions that span from raw material processing through specialty grade formulation. Their geographic footprints align with Gulf Coast petrochemical infrastructure and European headquarters operations serving North American demand through established import channels.
| Leading Market Players |
|---|
| Dow Inc. |
| Huntsman Corporation |
| BASF SE |
| Covestro AG |
| Solvay S.A. |
| Evonik Industries AG |
| SABIC |
| Arkema S.A. |
| Vibram S.p.A. |
| Others |
Value Network & Pricing Analysis
Athletic footwear brand procurement offices in Portland and Boston concentrate specification authority for sole materials, anchoring a contract-based long-term offtake pricing model that rewards compounders with certified circular supply chains and direct technical engagement capabilities.
Pricing Analysis
Capacity additions in Guanajuato and Querétaro are reshaping price floors for oil-resistant polyurethane grades serving ASTM F2413-compliant work boot segments. Three-tier pricing structure across premium bio-based formulations, standard petroleum-derived grades, and economy EVA compounds separates suppliers by certification level and volume scale. Cost compression in conventional TPU is intensifying because crude-linked isocyanate pricing remains volatile. Mid-market casual footwear manufacturers exhibit highest price sensitivity, while industrial safety buyers prioritize performance certification over unit cost.
Supply Chain Analysis
Injection molding technician shortages across southeastern US manufacturing clusters and emerging Querétaro operations constrain TPU processing capacity expansion. Raw material flows draw from Gulf Coast petrochemical infrastructure for polyurethane precursors, Alberta-based ethylene feedstock for EVA production, and imported specialty elastomer grades from European suppliers. Single-source vulnerability concentrates in supercritical nitrogen expansion equipment for running shoe midsole production. Distribution runs through polymer compounding clusters serving contract manufacturers with just-in-time TPU resin delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-based polyurethane formulation premiums are expanding addressable margins for compounders that achieve lifecycle carbon certification, as athletic brands shift procurement spend toward suppliers with transparent circular supply chains.
For Market Incumbents: Hedge against petroleum-derived chemistry obsolescence by accelerating backward integration into bio-based precursor supply and securing water-based adhesive formulation certifications ahead of EPA TSCA enforcement timelines. Dow Inc. and Huntsman Corporation's Gulf Coast infrastructure positions them to capture work boot premiumization demand if they expand Querétaro compounding partnerships. For New Entrants and Emerging Players: Begin with Mexican nearshoring expansion targeting oil-resistant polyurethane grades for industrial safety segments where ASTM F2413 compliance creates specification barriers. Guanajuato's tariff-advantaged labor costs and emerging technical workforce offer the most penetrable geography. Direct technical sales engagement with Portland and Boston brand headquarters provides the essential go-to-market angle for athletic segment entry. For Investors and Strategic Acquirers: Specialty chemical producers with footwear sector exposure are the most active acquirer in this space, seeking formulation capabilities that complement existing elastomer portfolios. Five-to-ten year viability hinges on bio-based chemistry transition execution rather than scale alone. Acquisition targets should demonstrate certified circular supply chains and direct brand technical engagement relationships. Monitor supercritical foam expansion equipment order backlogs as the inflection indicator for athletic segment material substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Polyurethane Scale-Up | Lifecycle carbon certification unlocks athletic brand procurement preferences under tightening EPA thresholds. |
| Water-Based Adhesive Transition | TSCA Section 5 volatility compliance eliminates solvent-based formulation suppliers from children's footwear categories. |
| Mexican Compounding Expansion | Guanajuato and Querétaro operations capture tariff advantages for ASTM F2413-compliant work boot supply. |
| Direct Technical Sales Investment | Early design-phase engagement with Portland and Boston headquarters displaces distributor-mediated procurement. |
| Subscription Performance Monitoring | Material data analytics creates recurring revenue from athletic brands consolidating sole durability evaluation. |
Research Methodology
Bottom-up athletic and work boot end-use modeling reconciled against top-down polyurethane and EVA resin supply tracking forms the analytical core. Primary interviews with footwear brand procurement directors, compounder plant managers, polymer distribution channel partners, and EPA regulatory affairs specialists combined with secondary validation from customs trade data, ACC chemical industry reports, SEC 10-K filings, and state-level extended producer responsibility framework disclosures. Triangulation across these sources calibrated volume and value estimates.
Input-output matrices mapped material type, end user category, manufacturing process, and application segments across the projection horizon. CAGRs derived from segment-level demand elasticity analysis and supply-side capacity expansion schedules. Forecast inputs incorporated supercritical foam expansion technology adoption curves, bio-based polyurethane formulation cost parity trajectories, and Mexican nearshoring investment flows.
Several conditions sit outside the modeled scope, including abrupt crude oil price dislocations, unilateral tariff regime changes, and accelerated EPA chemical restriction timelines beyond current TSCA Section 5 enforcement patterns. Forecasts reflect assumptions about vocational program output scaling for injection molding technicians and water-based adhesive curing equipment availability. Material deviation in bio-based feedstock cost parity or supercritical equipment delivery timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Bridal Gowns Market
Apparel Textiles
Smart Clothing Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
Bridal Wear Market
Apparel Textiles
China Denim Jeans Market
Apparel Textiles
Middle East and Africa Footwear Sole Material Market
Apparel Textiles
Maternity Wear Market
Apparel Textiles
Japan Denim Jeans Market
Apparel Textiles
Denim Market
Apparel Textiles
Asia Pacific Garment Steamers Market
Apparel Textiles
TIC for Apparel Market
Apparel Textiles
Women's Cheongsam Market
Apparel Textiles
Functional Apparel Market
Apparel Textiles
Europe Footwear Sole Material Market
Apparel Textiles
Hunting Apparel Market
Apparel Textiles
Women's Jerseys, Sweatshirts and Pullovers Market