
 OEM Clothing Manufacturer Service Market | 2026-2036
OEM Clothing Manufacturer Service Market Size, Share, and Industry Trends Forecast 2026-2036
OEM Clothing Manufacturer Service Market Insights
Vietnam's industrial zone expansion is reshaping regional capacity allocation for cut-and-sew operations. Shenzhou International Group leverages vertical integration across knitting, dyeing, and finishing to sustain margin control. Crystal International anchors its competitive position through specialized activewear production. MAS Holdings differentiates via ethical manufacturing certifications and Sri Lankan operational density.
OEM clothing manufacturer services encompass third-party production arrangements where brands outsource garment construction, pattern development, and quality assurance to external facilities, typically involving minimum order thresholds, specified textile compositions, and defined lead times. These services functionally enable brand owners to scale output without captive factory investments while accessing specialized machinery for technical fabrics or complex construction. Full package and design development segments command premium pricing due to embedded creative labor and sampling overhead, whereas cut-and-sew retains volume dominance in commoditized categories. Automated production methods are gaining traction among e-commerce clients demanding compressed turnaround cycles, while small batch capabilities serve independent fashion designers with limited capital commitments.
REACH in Europe, OEKO-TEX standards, and California's Safer Consumer Products regulations collectively elevate compliance costs for dye chemistry and finishing processes. Bangladesh's Accord on Fire and Building Safety and evolving EU due diligence directives reshape sourcing decisions by penalizing opaque subcontracting networks. Stakeholders must monitor regulatory divergence between major destination markets to avoid stranded inventory or supplier disqualification.
Market Dynamics
Automation investments and regulatory fragmentation are compressing supplier qualification timelines while fragmenting production geography across South and Southeast Asian manufacturing clusters.
Growth Catalysts
- EU Due Diligence Directives:Mandatory supply chain transparency requirements are accelerating consolidation among compliant Tier-1 OEMs capable of documenting subcontractor networks.
- Technical Activewear Demand:Moisture-wicking and compression fabric specifications from performance sportswear brands are pulling specialized knitting and finishing capabilities into OEM service portfolios.
- Vietnam Industrial Zone Expansion:Government-backed infrastructure development in Binh Duong and Dong Nai provinces is expanding cut-and-sew capacity for mid-volume brand contracts.
Market Restraints
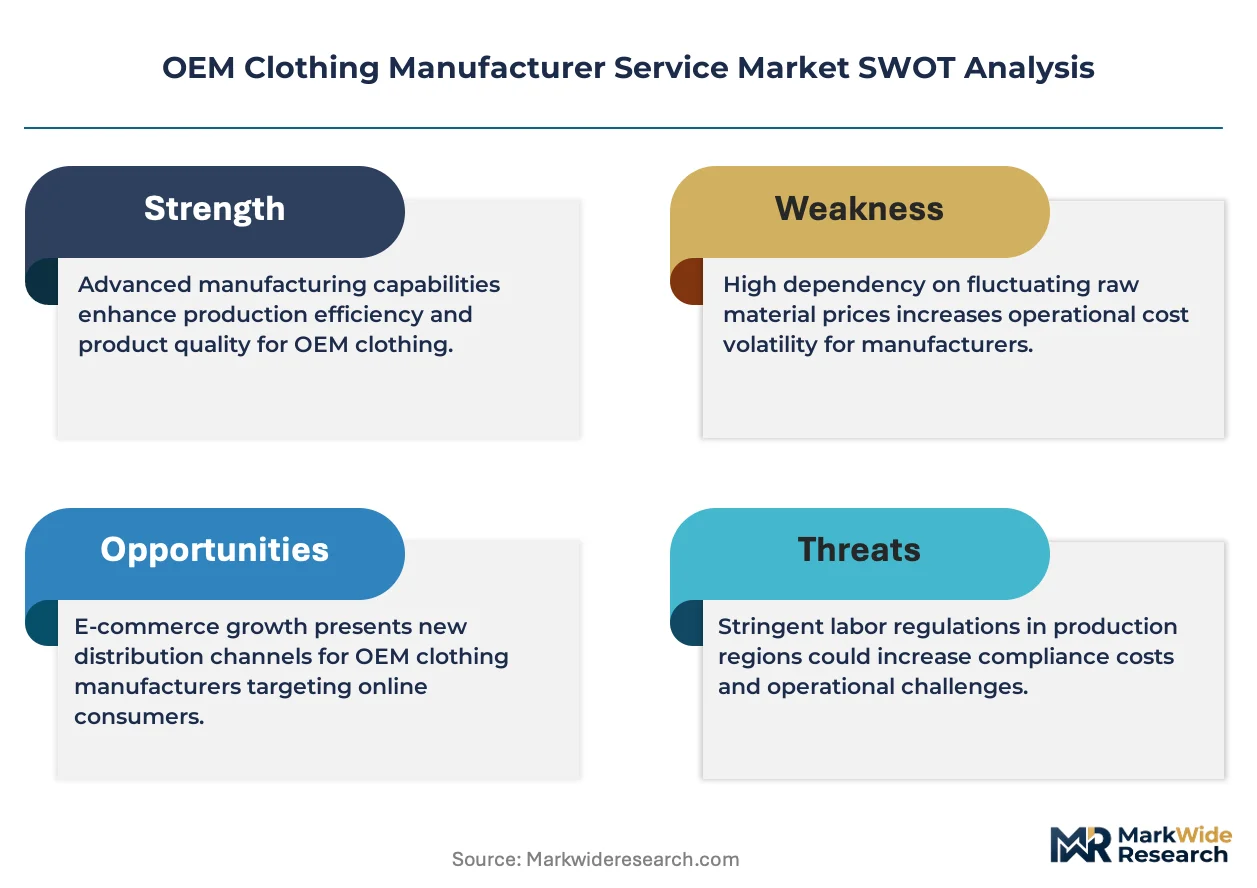
- Cotton Price Volatility:Input cost swings for natural fibers compress margin predictability for full-package OEMs locked into annual pricing agreements with brand clients.
- Bangladesh Supplier Concentration:Heavy reliance on Dhaka-Chittagong corridor facilities creates systemic disruption exposure from monsoon flooding and political labor actions.
- REACH Compliance Costs:ECHA chemical registration requirements for azo dyes and formaldehyde-based finishes elevate fixed compliance overhead for European-bound production.
Strategic Opportunities
- Nearshoring to Mexico:USMCA tariff advantages and compressed shipping timelines for North American e-commerce brands are opening capacity expansion in Puebla and Yucatán.
- India PLI Scheme:Production-linked incentives for man-made fiber apparel are subsidizing polyester and nylon garment OEM investments in Tamil Nadu and Gujarat.
- Blockchain Traceability:Integration of distributed ledger systems with OEKO-TEX certification is creating premium service tiers for sustainability-focused brand procurement teams.
Industry Challenges
- Technical Pattern Engineering Talent:Shortage of CAD-operating graders and markers capable of 3D sampling workflows is extending product development timelines for complex construction.
- Multi-Certification Overlap:Simultaneous compliance with OEKO-TEX, GOTS, and brand-specific chemical restricted substance lists requires redundant testing protocols and documentation systems.
- Legacy ERP Integration:Disconnection between factory-floor MES platforms and client-side PLM systems creates order-status visibility gaps and invoice reconciliation delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OEM Clothing Manufacturer Service Market |
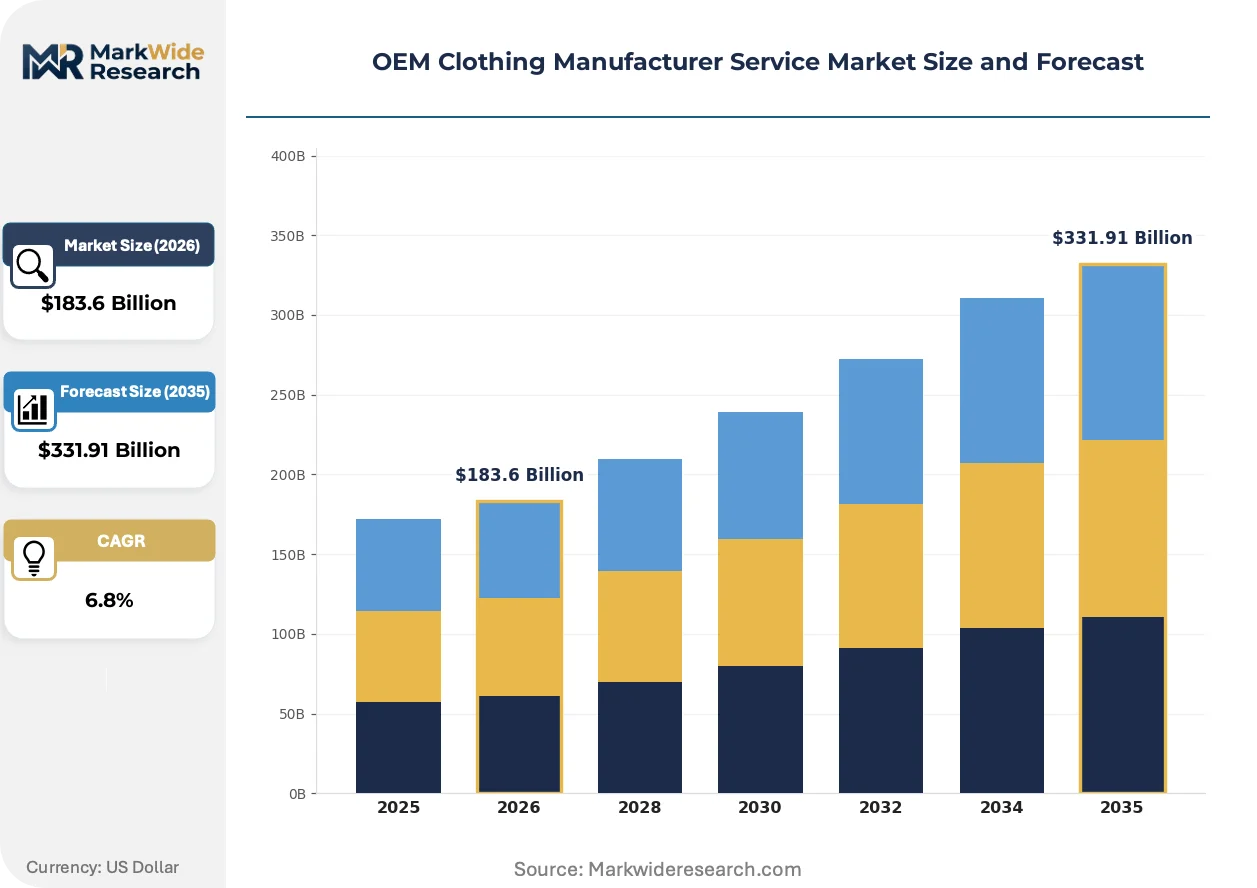
| Market Size in 2026 | $183.6 Billion |
| Market Size in 2035 | $331.91 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cut & Sew, Private Label, Full Package, Design Development Production Method: Mass Production, Made-to-Order, Small Batch, Automated Production Client Type: Retail Brands, E-commerce Companies, Fashion Designers, Corporate Clients Fabric Type: Cotton, Polyester, Wool, Blends |
| Companies Covered | Jiangsu Guotai International Group, MAS Holdings, Shenzhou International Group, SiATEX, Smart Clothing Ltd., Esquel Group, Crystal International, Billoomi Fashion, Hodo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OEM Clothing Manufacturer Service Market Trends and Innovations
Digital thread technologies and automated cutting systems are compressing sample-to-production timelines while regulatory chemical restrictions are reshaping dye house capital allocation across supplier networks.
3D virtual sampling software is digitizing the traditional physical prototyping workflow. Fast-fashion and direct-to-consumer brands are adopting CLO and Browzwear platforms at accelerating rates to compress six-week sampling cycles into days. This compression is digitizing the competitive basis for OEM selection away from pure unit cost toward digital collaboration capability.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances (PFAS) are eliminating durable water repellent chemistries from European-bound outerwear. Dye houses serving performance apparel OEMs are retooling finishing lines toward silicone and hydrocarbon alternatives. The transition imposes capital-heavy equipment swaps on suppliers in Portugal and Turkey serving mid-tier brand clients.
Micro-batch production requests from digitally native vertical brands are fragmenting traditional minimum order quantity structures. These brands are bypassing conventional seasonal buying calendars in favor of weekly replenishment drops. The behavioral shift is most visible in Los Angeles and New York-based label operations sourcing from Mexican and Central American cut-and-sew facilities.
OEM Clothing Manufacturer Service Market Segmentation
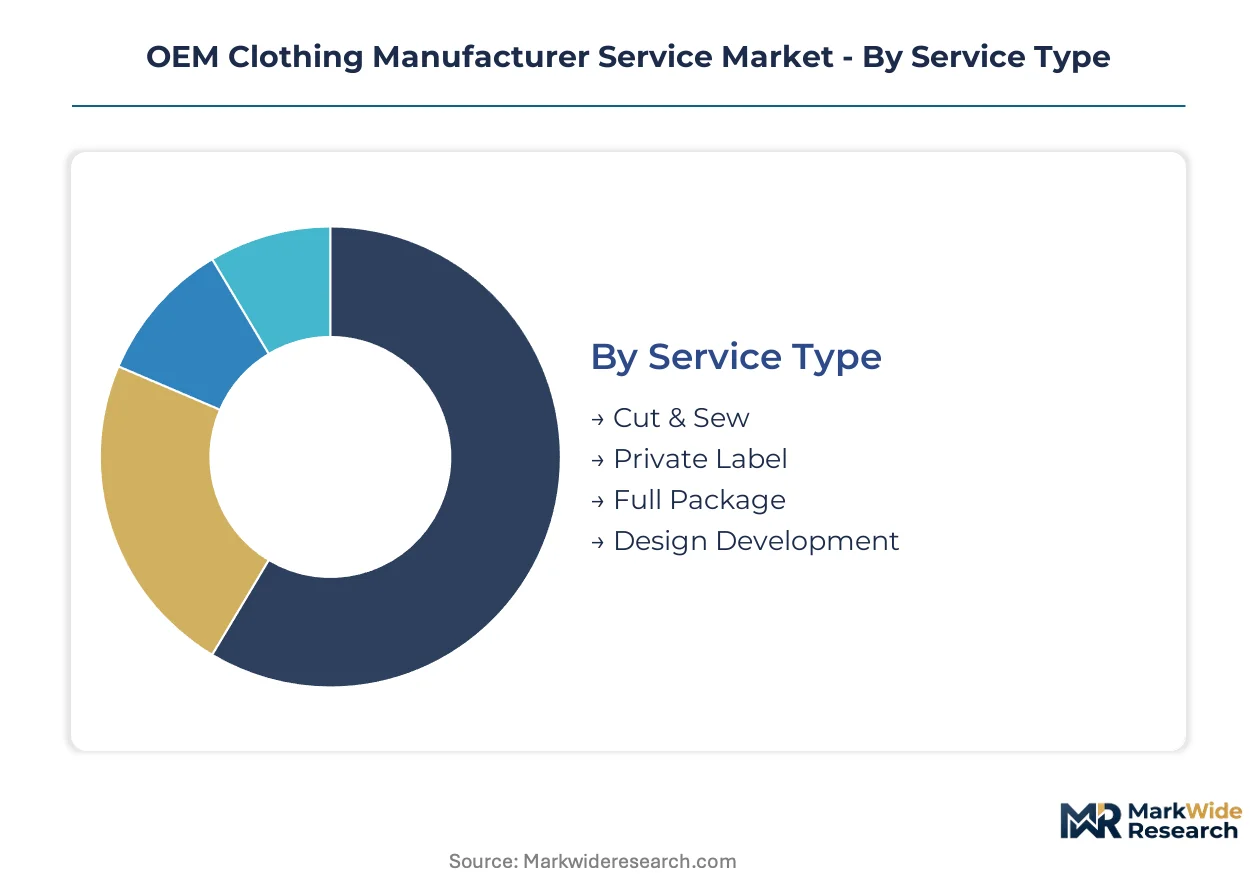
OEM clothing services fragment across service depth, production scale, and client sophistication, with each axis commanding distinct margin profiles and capital requirements. Understanding these divisions reveals where supplier capabilities align with brand procurement strategies.
Service Type:
After-sales service intensity escalates from basic assembly to design partnership, with warranty exposure and technical support obligations expanding proportionally with creative input embedded in contracts.
- Cut & Sew:Brands supply pre-cut fabric panels and finished trim for assembly-only execution. Volume concentrates in Bangladesh and Vietnam facilities serving mass-market retailers with rigid seasonal calendars and minimal design iteration.
- Full Package:OEMs assume end-to-end responsibility from fabric sourcing through final delivery, embedding quality assurance and logistics coordination. Corporate uniform programs and mid-tier retail brands in Germany and France pull this segment for consolidated vendor management.
- Private Label:Manufacturers produce unbranded garments for retailer-exclusive lines with specified silhouettes but limited creative direction. Discount chains and supermarket apparel divisions in Poland and Spain source heavily here.
- Design Development:Collaborative pattern engineering and 3D sampling services precede production commitment. Independent designers in Los Angeles and London leverage this for capsule collections without captive technical teams.
By volume, Cut & Sew leads. By growth pace, Design Development is ahead.
Production Method:
Cost tier stratification separates commodity volume plays from premium responsiveness, with automation investments creating a distinct pricing band between manual and digitally enabled workflows.
- Mass Production:High-volume lines with standardized operations and extended lead times for predictable demand. Fast-fashion giants in Turkey and Morocco deploy this for core seasonal programs with six-month forward planning.
- Small Batch:Flexible lines handling sub-thousand-unit runs with rapid changeover capability. Direct-to-consumer brands in New York and Stockholm utilize Portuguese and Romanian facilities for weekly drop models.
- Made-to-Order:Single-unit or micro-lot production triggered by confirmed consumer purchase. Bespoke suiting operations in Naples and Hoi An serve this niche with extended craftsmanship timelines.
- Automated Production:Robotic cutting, sewing, and finishing systems compress cycle times for technical fabric assembly. Performance outerwear brands in Switzerland and Norway specify this for seam-sealed construction with precision tolerances.
Mass Production captures the largest revenue pool. Small Batch claims the steepest expansion trajectory.
Client Type:
Application-specific requirements differentiate procurement behavior, with technical specifications, compliance documentation, and payment terms varying sharply across end-user categories.
- Retail Brands:Established chains with seasonal buying calendars, quality manuals, and social compliance audits. Department store private labels in Japan and Australia maintain long-term OEM relationships with multi-year capacity reservations.
- E-commerce Companies:Digital-native retailers demanding real-time inventory visibility and compressed replenishment cycles. Flash-sale platforms in São Paulo and Jakarta source from Mexican and Indonesian cut-and-sew networks for cross-border fulfillment.
- Fashion Designers:Creative-led operations prioritizing sampling speed and construction experimentation over unit cost. Emerging labels in Copenhagen and Milan access Portuguese and Bulgarian ateliers for limited-edition production.
- Corporate Clients:Institutional buyers procuring standardized workwear and promotional apparel with logo application requirements. Energy sector contractors in Alberta and Texas specify flame-resistant fabric assemblies from specialized North American OEMs.
Retail Brands dominate absolute contract value. E-commerce Companies are climbing the fastest.
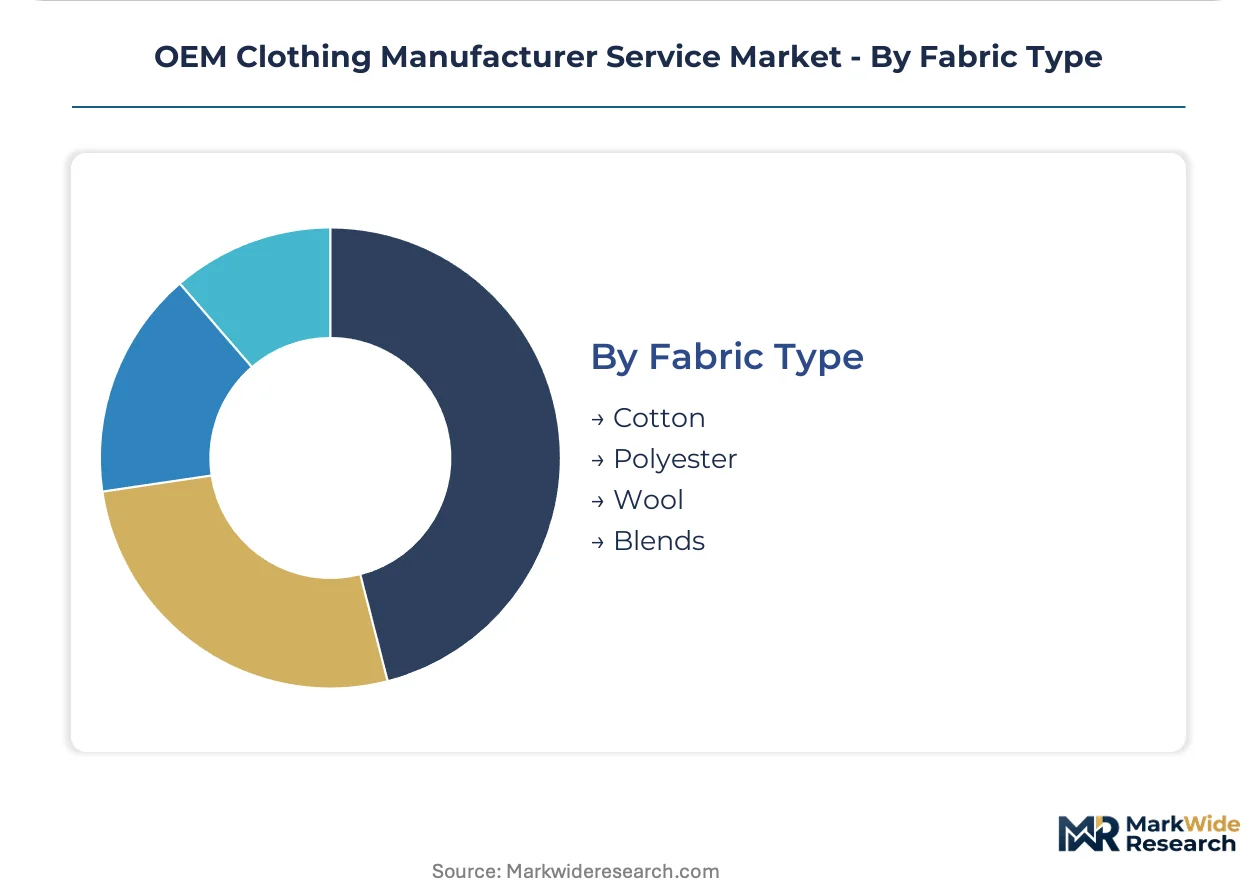
Fabric Type:
Supply concentration and price volatility characteristics shape sourcing strategies, with natural fiber exposure creating margin risk distinct from synthetic stability.
- Cotton:Natural cellulosic fiber dominant in casualwear and basic knit categories. Pakistani and Indian spinning mills supply ring-spun and open-end varieties to cut-and-sew facilities in Sri Lanka and Cambodia.
- Polyester:Petroleum-derived synthetic with moisture-wicking and dimensional stability properties. Taiwanese and South Korean filament producers feed activewear OEMs in Vietnam and Indonesia for performance garment construction.
- Wool:Protein fiber from sheep and alpaca retaining thermal regulation and crease resistance. Italian and Australian raw material sources supply worsted and woolen processing to tailored clothing manufacturers in Biella and Prato.
- Blends:Engineered fiber combinations balancing comfort, durability, and care properties. Cotton-polyester and wool-nylon unions serve mid-market outerwear and corporate apparel segments across Portuguese and Turkish production bases.
Polyester leads by volume throughput. Blends are gaining share fastest as brands optimize performance-to-cost ratios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cai Mep-Thi Vai deepwater port complex underwrites Vietnam's ascendancy in cut-and-sew export capacity. Bangladesh's Padma Bridge rail link has compressed Dhaka-Chittagong transit times for raw cotton imports. Turkey's Marmaray tunnel connects European fabric suppliers to Anatolian garment factories with same-day logistics.
Vietnam
Performance sportswear procurement from Swiss and Norwegian brands is accelerating specialized knitting investments. The government's Decree 57 on industrial zone development fast-tracks factory construction permits in Binh Duong. Ho Chi Minh City's surrounding provinces host Shenzhou International Group's vertically integrated dyeing and finishing campuses serving compression fabric contracts.
Bangladesh
Fast-fashion volume contracts from German and French retailers concentrate in Dhaka-Chittagong corridor facilities. The Accord on Fire and Building Safety mandates structural remediation timelines that disqualify non-compliant subcontractors. Gazipur's export processing zones are absorbing relocated capacity from non-compliant Dhaka facilities following ECHA-aligned chemical audits.
Turkey
Nearshoring demand from UK and Netherlands e-commerce brands is pulling small-batch production into Izmir and Denizli. REACH Annex XVII enforcement through Turkey's Ministry of Environment eliminates azo dye formulations from European-bound outerwear. Bursa's organized industrial zones are retooling finishing lines toward PFAS-free water repellent chemistries for performance apparel OEMs.
India
Man-made fiber apparel incentives are redirecting polyester garment investment toward Tamil Nadu and Gujarat spinning corridors. The PLI scheme for textiles subsidizes capital equipment for technical fabric assembly. Tiruppur's knitwear cluster is expanding circular knitting capacity for moisture-wicking base layer contracts from Australian retail brands.
Mexico
USMCA tariff advantages are attracting direct-to-consumer brand sourcing for compressed North American replenishment cycles. Mexico's Federal Labor Law reforms mandate union representation transparency that aligns with California's Safer Consumer Products audit requirements. Puebla's apparel manufacturing corridor is absorbing capacity expansion from Los Angeles-based label operations seeking weekly drop fulfillment.
OEM Clothing Manufacturer Service Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on fabric and trim inputs. The supplier base fragments across vertically integrated conglomerates and specialized cut-and-sew operators. Three archetypes dominate: full-package aggregators with captive textile mills, design-development boutiques with 3D sampling capabilities, and compliance-forward operators with multi-certification documentation systems. Capacity expansion and strategic partnerships constitute the dominant competitive moves as brands consolidate vendor lists under EU due diligence pressure.
Within the vertically integrated tier, Shenzhou International Group and Crystal International exemplify scale-driven platform operators with knitting-through-finishing control. MAS Holdings anchors the compliance-specialist archetype through Sri Lankan operational density and ethical manufacturing certification density. Jiangsu Guotai International Group represents the diversified conglomerate model with cross-sector trading and manufacturing exposure. These three occupy distinct positioning vectors rather than direct overlap, reducing price-only competition in technical activewear segments.
| Leading Market Players |
|---|
| Jiangsu Guotai International Group |
| MAS Holdings |
| Shenzhou International Group |
| SiATEX |
| Smart Clothing Ltd. |
| Esquel Group |
| Crystal International |
| Billoomi Fashion |
| Hodo Group |
| Others |
Pricing and Supply Chain Analysis
Binh Duong province's industrial zone expansion is compressing unit costs for mid-volume sportswear contracts while elevating pricing power for OEMs with integrated dyeing and finishing capabilities. This geographic concentration enables compliant Tier-1 suppliers to command premium positioning against fragmented cut-and-sew operators in Bangladesh's Dhaka periphery.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with full-package OEMs embedding fabric sourcing and quality assurance into per-unit rates that decline across 10,000-unit thresholds. Pricing stratifies across premium certification tiers, standard compliance baselines, and economy-grade cut-and-sew assembly, with OEKO-TEX and GOTS credentials commanding 15-20% uplifts. Cost compression in economy tiers is intensifying because Bangladeshi suppliers absorb REACH compliance overhead without pass-through mechanisms. E-commerce companies exhibit highest price sensitivity due to weekly replenishment models, while corporate uniform programs prioritize total-cost-of-ownership over unit rates.
Supply Chain Analysis
Raw cotton shipments from Pakistani and Indian spinning mills feed cut-and-sew networks across Bangladesh, Vietnam, and Sri Lanka, with polyester filament drawing from Taiwanese and South Korean chemical fiber producers. Synthetic fabric assembly rests on petroleum-derived input volatility, while natural fiber sourcing hinges on monsoon-dependent agricultural yields. Single-source vulnerability concentrates in Dhaka-Chittagong corridor facilities exposed to flooding disruption. Distribution runs through Cai Mep-Thi Vai deepwater terminals for trans-Pacific routes and Chittagong port for European-bound container traffic.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU due diligence directives are accelerating vendor consolidation, creating acquisition opportunities for compliance-forward OEMs with documented subcontractor networks. This regulatory inflection favors operators investing in blockchain traceability and multi-certification infrastructure.
For Market Incumbents: Entrench competitive position through backward integration into circular knitting and technical fabric finishing in Vietnam's Binh Duong corridor. Acquire distressed capacity from non-compliant Bangladeshi facilities following Accord remediation timelines. Prioritize 3D sampling capability investments to capture design-development premiums from Los Angeles and London-based independent labels.
For New Entrants and Emerging Players: Establish a beachhead in small-batch automated production serving direct-to-consumer brands with weekly drop models. Target Puebla and Yucatán manufacturing corridors for USMCA-advantaged nearshoring contracts. Differentiate through blockchain-integrated OEKO-TEX certification tiers that command sustainability premiums from procurement teams at Swiss and Norwegian performance brands.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated operators with captive textile mills and digital sampling workflows. Five-to-ten-year viability concentrates in OEMs consolidating vendor lists under EU transparency mandates. Monitor ECHA chemical restriction expansions as inflection indicators for finishing line retooling requirements across European-bound production.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical Fabric Production | Shenzhou International Group's dyeing campuses capture margin control from compression fabric contracts. |
| Blockchain Traceability Implementation | Distributed ledger integration with OEKO-TEX certification creates premium service tiers for sustainability-focused procurement. |
| Small-Batch Automated Capacity Expansion | Robotic cutting systems in Puebla serve Los Angeles label operations seeking weekly replenishment cycles. |
| Multi-Certification Compliance Investment | MAS Holdings' ethical manufacturing density qualifies for EU due diligence directive vendor consolidation. |
| 3D Virtual Sampling Platform Adoption | CLO and Browzwear deployment compresses six-week prototyping into days for Copenhagen and Milan designers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with brand sourcing directors, OEM factory managers, textile chemical suppliers, and logistics coordinators; and secondary validation through customs trade databases, ECHA chemical registration filings, Bangladesh Accord remediation reports, and Vietnam industrial zone development disclosures. Bottom-up capacity assessments across Binh Duong, Dhaka-Chittagong, and Tiruppur clusters were triangulated against top-down brand procurement spend estimates.
Forecast inputs incorporated service type segmentation, production method tiers, fabric category splits, and client archetype demand patterns across the projection horizon. CAGRs were derived from regression analysis of historical capacity expansion rates against brand outsourcing intensity indices. Modeled variables included REACH compliance cost trajectories, automation capital expenditure cycles, and nearshoring tariff advantage shifts under USMCA.
Stress conditions across cotton price volatility bands, monsoon disruption frequencies, and EU due diligence enforcement timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation pacing and brand consolidation behavior. Cross-checking against customs export volume data from Vietnam General Statistics Office and Bangladesh Garment Manufacturers and Exporters Association is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Middle East and Africa Textile Garment Market
Apparel Textiles
Asia-Pacific Footwear Sole Material Market
Apparel Textiles
Apparel Supply Chain Market
Apparel Textiles
Japan Denim Jeans Market
Apparel Textiles
Braille Clothing Tags Market
Apparel Textiles
Down Jacket Market
Apparel Textiles
Europe Textile Garment Market
Apparel Textiles
Maternity Leggings Market
Apparel Textiles
Organic Baby Clothes Market
Apparel Textiles
Hunting Apparel Market
Apparel Textiles
Cosplay Clothing Market
Apparel Textiles
Waterproof Fabrics for Sports Apparel Market
Apparel Textiles
Flame Retardant Apparel Market
Apparel Textiles
Smart Clothing Market
Apparel Textiles
Asia Pacific Garment Steamers Market
Apparel Textiles
Asia-Pacific Digital Clothing Market