
 Flame Retardant Apparel Market | 2026-2036
Flame Retardant Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Flame Retardant Apparel Market Analysis
China is reconfiguring regional supply dynamics through expanded aramid fiber manufacturing clusters in Shandong and Jiangsu provinces. DuPont de Nemours Inc. leverages its integrated Nomex supply chain to sustain premium positioning in North American industrial channels. Honeywell International Inc. anchors its portfolio with advanced thermal-barrier technologies for military and first-responder applications. MSA Safety Incorporated competes through respiratory-integrated ensemble systems that bundle flame protection with gas detection.
Flame retardant apparel denotes garments engineered with inherent or treated fibers that self-extinguish upon flame exposure, typically meeting thermal protective performance thresholds of 4-8 cal/cm² in arc-flash scenarios and char lengths under 100mm per vertical flame testing. These garments protect workers in environments with flash-fire, electric arc, or molten-metal exposure hazards across industrial, energy, and emergency-response settings. Coveralls dominate volume shipments across oil and gas end users due to full-body coverage requirements in drilling and downstream operations, while Nomex-based material categories command margin premiums through inherent flame resistance that outlasts treated-cotton alternatives through repeated industrial laundering cycles. Kevlar-reinforced segments occupy specialized niches in metalworking and foundry applications where cut and thermal risks converge.
OSHA 1910.269 standards mandate flame-resistant clothing for electrical utility and petrochemical workers exposed to energized equipment, while NFPA 2112 governs flash-fire performance criteria for industrial personnel, and EN 11612 certification governs European market access through limited flame spread and heat-transfer testing protocols. Regulatory divergence between US OSHA-driven specifications and EU CE-marking requirements under the PPE Regulation fragments product development roadmaps and testing budgets for multinational suppliers. Stakeholders must monitor emerging state-level amendments to federal standards and evaluate dual-certification investments against regional revenue concentration.
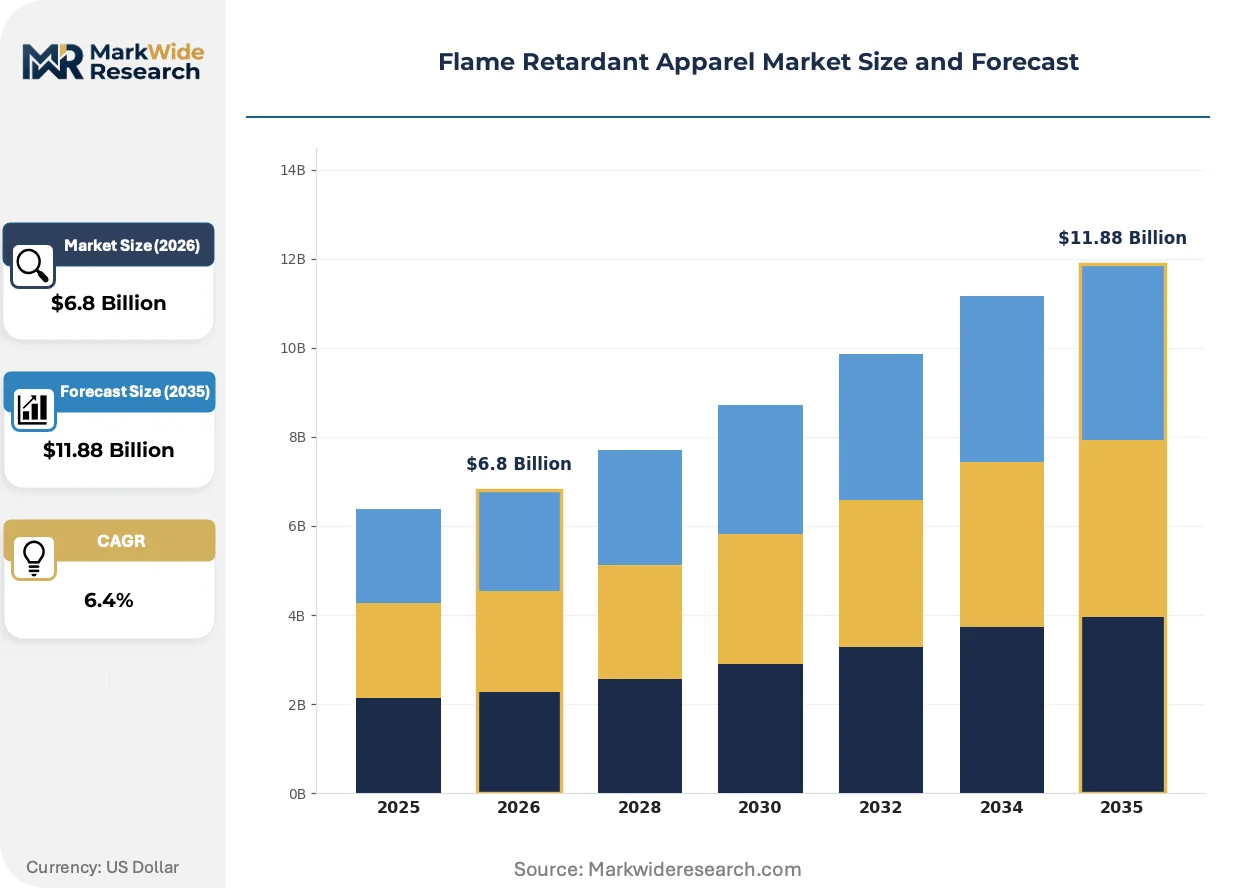
Market Dynamics
OSHA enforcement of workplace burn-protection standards tightens compliance thresholds across the United States, forcing replacement cycles for untreated cotton workwear and accelerating certified flame-resistant procurement in oil and gas operations.
Growth Catalysts
- OSHA 1910.269 Mandates:Electrical utility and petrochemical workers exposed to energized equipment now require flame-resistant clothing, driving systematic fleet upgrades across transmission and refining operations.
- Aramid Fiber Manufacturing Clusters:Expanded production bases in Shandong and Jiangsu provinces are reducing raw material lead times and enabling regional suppliers to compete on specification-grade apparel.
- NFPA 2112 Certification Uptake:Industrial personnel facing flash-fire hazards increasingly specify certified garments, displacing generic treated-cotton alternatives in metalworking and chemical processing environments.
Market Restraints
- Meta-Aramid Supply Concentration:Nomex fiber production remains concentrated among limited specialty chemical producers, exposing apparel manufacturers to input cost volatility and allocation constraints.
- Regulatory Divergence Costs:Dual-certification requirements for US OSHA specifications and EU CE-marking under the PPE Regulation fragment testing budgets and delay product launches for multinational suppliers.
- Inherent-Treated Cotton Substitution:Lower-cost treated-cotton alternatives retain share in price-sensitive maintenance and construction segments despite shorter effective lifespans.
Strategic Opportunities
- Emergency Responder Modernization:Fire departments and industrial brigades are upgrading to thermal-barrier ensembles integrating flame protection with respiratory and gas detection systems.
- State-Level Amendment Tracking:Proposed amendments to federal standards in Texas and California create first-mover advantages for suppliers with compliant inventory positioned ahead of enforcement dates.
- Foundry Application Expansion:Kevlar-reinforced segments serving metalworking environments where cut and thermal risks converge remain underpenetrated relative to oil and gas saturation.
Industry Challenges
- Certification Timeline Compression:EN 11612 and NFPA 2112 testing protocols require extended laboratory queues, delaying seasonal product releases and straining working capital.
- Technical Talent Scarcity:Apparel engineers with dual expertise in textile chemistry and industrial safety standards command premium compensation, constraining mid-tier supplier R&D expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flame Retardant Apparel Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shirts, Pants, Coveralls, Jackets Material: Nomex, Kevlar, Cotton, Wool End User: Manufacturing, Oil & Gas, Firefighting, Construction Certification: NFPA, OSHA, UL, EN 11612 |
| Companies Covered | 3M Co., DuPont de Nemours Inc., Honeywell International Inc., Ansell Ltd., Lakeland Industries Inc., National Safety Apparel Inc., Carhartt Inc., Cintas Corp., MSA Safety Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flame Retardant Apparel Market Emerging Trajectories
Material science advances and regulatory harmonization pressures are reshaping competitive positioning in protective workwear, with fiber technology and certification strategies becoming primary differentiation vectors.
Inherent flame-resistant fiber technology is migrating from premium oil and gas applications into broader industrial maintenance and utility segments. DuPont de Nemours Inc. leverages its integrated Nomex supply chain to sustain positioning in North American channels, while regional aramid producers capture specification-grade contracts. This migration compresses margins for treated-cotton processors unable to meet thermal protective performance thresholds of 4-8 cal/cm².
REACH restrictions on halogenated flame retardants in European textile applications are accelerating substitution toward phosphorus-based and inherent fiber solutions. The ECHA regulatory trajectory forces reformulation of treated-cotton finishing chemistries, with EN 11612 certification becoming a mandatory gating factor for EU market access. Apparel suppliers with established CE-marking capabilities are capturing share from US-centric competitors facing retesting burdens.
Integrated ensemble procurement is consolidating previously separate respiratory, flame, and gas detection purchases into single-vendor contracts. Oil and gas operators in the Gulf Coast petrochemical corridor now specify bundled systems reducing vendor management overhead. This consolidation favors suppliers with cross-category certification depth and penalizes single-product specialists.
Flame Retardant Apparel Market Segmentation
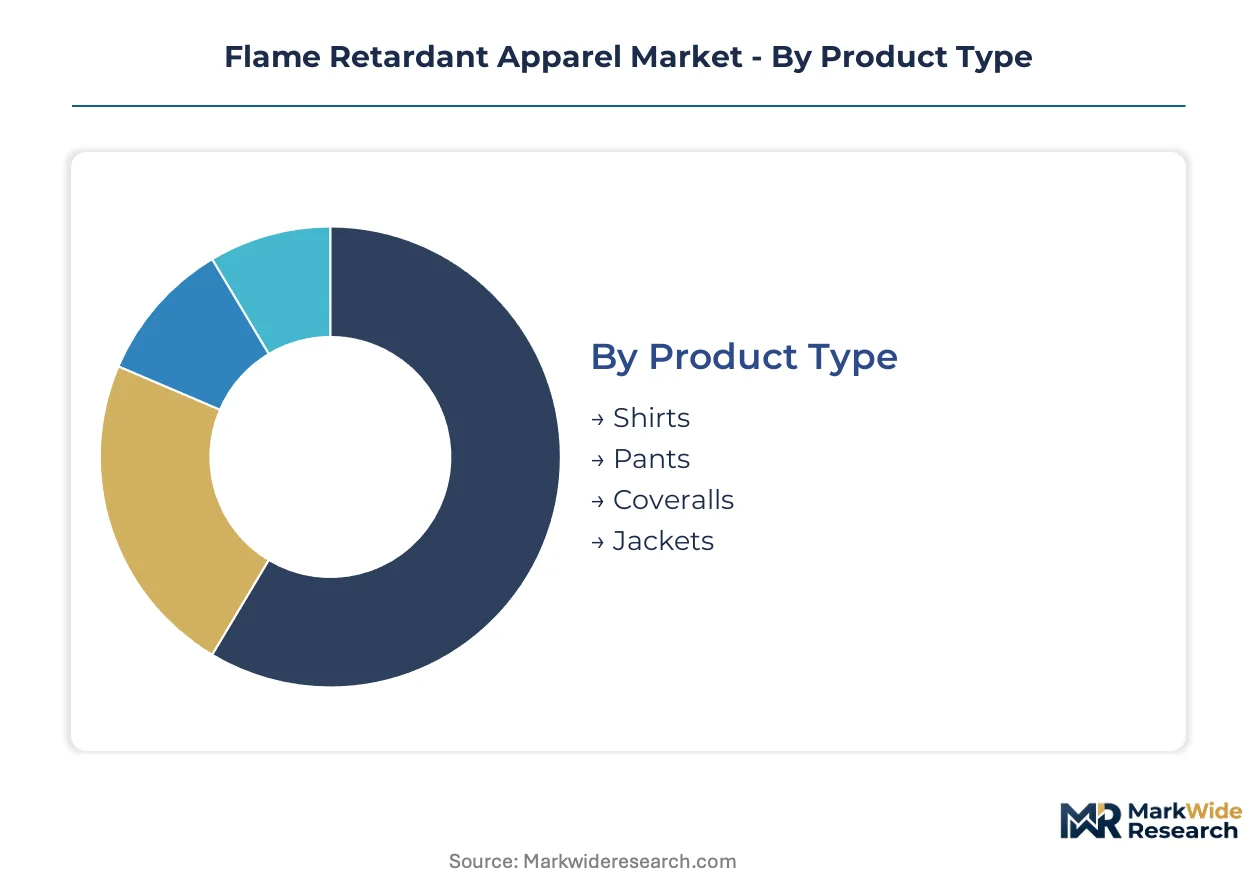
Flame retardant apparel segmentation reflects divergent hazard exposures and compliance requirements across industrial environments. Product configurations, fiber technologies, and certification standards each create distinct procurement criteria and margin structures for suppliers.
Product Type:
Mature full-body coverage garments anchor procurement volumes, while specialized upper-body pieces capture replacement-cycle premiums.
- Coveralls:One-piece garments delivering continuous protection from neck to ankle dominate oil and gas drilling operations. Gulf Coast petrochemical corridor refineries mandate these for downstream maintenance crews exposed to flash-fire and chemical splash hazards simultaneously.
- Jackets:Upper-body thermal barriers with adjustable cuffs and storm flaps concentrate demand among electrical utility linemen. OSHA 1910.269 compliance drives systematic fleet upgrades as transmission operators replace untreated cotton outerwear.
- Shirts:Flame-resistant work shirts serve manufacturing maintenance and construction trades requiring mobility with baseline protection.
- Pants:Protective trousers complement upper-body coverage in mixed-hazard environments where full coveralls exceed operational requirements.
Coveralls retain volume leadership; jackets hold the steepest expansion curve.
Material:
Cost tiers separate inherent fiber solutions from treated natural alternatives, with performance durability determining lifecycle economics.
- Nomex:Meta-aramid fiber delivering permanent flame resistance without chemical finishing dominates premium industrial channels. DuPont's integrated supply chain sustains specification-grade positioning despite regional aramid manufacturing expansion in Shandong province.
- Cotton:Flame-retardant treated cotton retains share in price-sensitive construction and maintenance segments where garment replacement frequency justifies lower unit costs.
- Kevlar:Para-aramid reinforcement serves metalworking and foundry niches where cut resistance and thermal protection converge.
- Wool:Naturally flame-resistant protein fiber occupies limited emergency responder and military applications requiring moisture management alongside thermal protection.
Nomex commands margin premiums; treated cotton maintains the broadest installed base.
End User:
Application intensity varies sharply across sectors, with energy extraction and chemical processing driving the most stringent specification requirements.
- Oil & Gas:Upstream drilling and downstream refining operations mandate certified ensembles across Texas and Gulf Coast petrochemical corridors. Flash-fire exposure from hydrocarbon releases drives replacement cycles for coveralls and thermal outerwear.
- Firefighting:Municipal and industrial brigades specify thermal-barrier ensembles integrating flame protection with respiratory systems. Emergency responder modernization programs accelerate procurement of next-generation turnout gear.
- Manufacturing:Metalworking and chemical processing facilities require NFPA 2112-certified garments for personnel facing molten metal splash and flash-fire hazards.
- Construction:Electrical utility contractors and general building trades represent the most price-sensitive demand segment, with treated-cotton alternatives retaining significant share.
Oil and gas retains volume leadership; firefighting holds the steepest expansion curve.
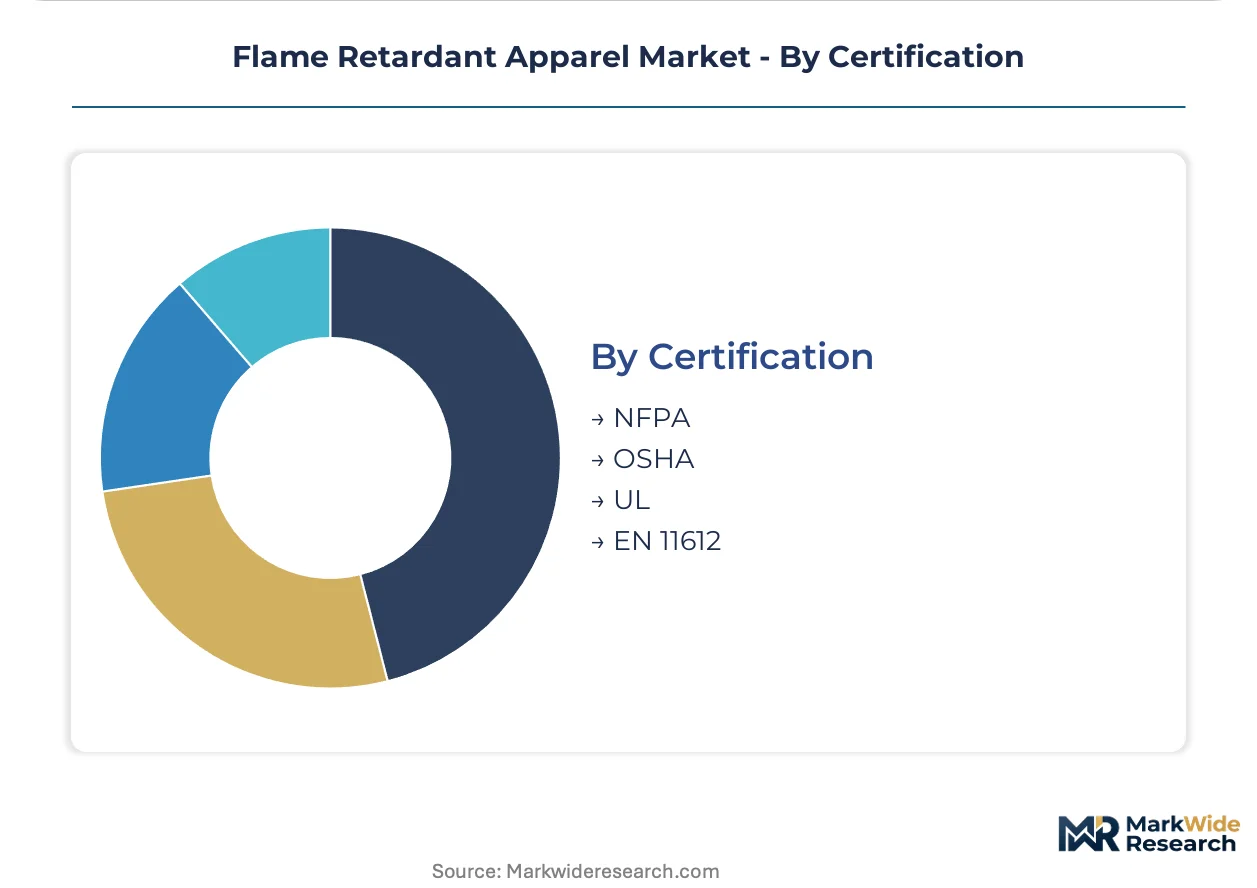
Certification:
Geographic scope of operations dictates certification portfolio requirements, with multinational suppliers facing fragmented testing burdens.
- NFPA:National Fire Protection Association standards govern flash-fire performance for industrial personnel in North American markets. NFPA 2112 certification displaces generic alternatives in metalworking and chemical processing procurement specifications.
- OSHA:Occupational Safety and Health Administration 1910.269 mandates flame-resistant clothing for electrical utility and petrochemical workers exposed to energized equipment, driving systematic fleet upgrades.
- EN 11612:European limited flame spread and heat-transfer testing protocols govern EU market access under PPE Regulation requirements, forcing reformulation of halogenated flame-retardant chemistries.
- UL:Underwriters Laboratories certification provides third-party validation for arc-flash protective performance in electrical applications.
OSHA compliance drives North American volume; EN 11612 represents the most demanding expansion pathway for US-centric suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aramid fiber manufacturing clusters in Shandong and Jiangsu provinces concentrate upstream supply, while downstream apparel fabrication disperses across industrial demand centers in North America, Europe, and Asia-Pacific.
United States
OSHA 1910.269 mandates flame-resistant clothing for electrical utility and petrochemical workers exposed to energized equipment. Gulf Coast petrochemical corridor refineries in Texas and Louisiana drive systematic replacement cycles for certified coveralls and thermal outerwear. Houston anchors the densest concentration of oil and gas procurement activity.
China
Expanded meta-aramid production bases in Shandong province reduce raw material lead times for domestic apparel manufacturers. GB standards and MIIT industrial safety directives tighten workplace protection requirements across energy and chemical sectors. Yangtze River Delta fabricators capture specification-grade contracts for export markets.
Germany
REACH restrictions on halogenated flame retardants accelerate substitution toward phosphorus-based and inherent fiber solutions. ECHA regulatory trajectory forces reformulation of treated-cotton finishing chemistries for EU market access. North Rhine-Westphalia chemical industry clusters drive demand for EN 11612-certified ensembles.
Saudi Arabia
Saudi Aramco procurement specifications mandate certified flame-resistant apparel for upstream drilling and downstream refining operations. The country's national industrial safety regulator enforces thermal protective performance thresholds aligned with NFPA 2112 equivalents. Eastern Province petrochemical cities concentrate replacement demand for coveralls and jackets.
Flame Retardant Apparel Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in fiber and fabric supply. The market structures around three tiers: integrated fiber-to-garment suppliers, specialized apparel fabricators, and rental-service operators managing fleet logistics. Strategic archetypes include aramid fiber producers backward integrating into finished goods, industrial laundries expanding into certified garment provisioning, and safety-equipment distributors bundling flame protection with respiratory systems. Dominant competitive moves encompass capacity expansion in Asian manufacturing bases and strategic partnerships between fiber suppliers and regional garment producers.
Among integrated chemical-industry players, DuPont de Nemours Inc. exemplifies the fiber-to-garment archetype through its captive Nomex supply chain. Honeywell International Inc. occupies a position in the thermal-barrier technology tier, while MSA Safety Incorporated represents the integrated ensemble approach combining flame protection with gas detection capabilities. These three anchors illustrate divergent paths to market positioning without overlapping strategic territory.
| Leading Market Players |
|---|
| 3M Co. |
| DuPont de Nemours Inc. |
| Honeywell International Inc. |
| Ansell Ltd. |
| Lakeland Industries Inc. |
| National Safety Apparel Inc. |
| Carhartt Inc. |
| Cintas Corp. |
| MSA Safety Incorporated |
| Others |
Supply Flow & Price Mechanics
Shanghai-Ningbo port freight corridors transmit cost volatility from Shandong aramid fiber clusters to Gulf Coast petrochemical buyers, compressing margins for treated-cotton processors while amplifying premium capture for Nomex-integrated suppliers with captive raw material positions.
Pricing Analysis
OSHA 1910.269 dictates the pricing tier structure across the North American market, separating certified flame-resistant ensembles from untreated cotton workwear. Three-tier pricing structure across premium, standard, and economy levels aligns with NFPA 2112 certification grades, thermal protective performance thresholds, and garment durability specifications. Cost compression in treated-cotton segments is intensifying because regional aramid manufacturing expansion in Jiangsu province erodes the cost gap with inherent fiber solutions. Construction trades exhibit the highest price sensitivity, while oil and gas operators prioritize lifecycle durability over unit cost.
Supply Chain Analysis
Extended payment terms from Gulf Coast petrochemical operators strain working capital for apparel fabricators sourcing meta-aramid fiber from China, South Korea, and the United States. Raw material dependencies center on meta-aramid pulp, para-aramid reinforcement yarns, and phosphorus-based finishing chemistries. Single-source vulnerability concentrates around DuPont's integrated Nomex supply chain, which anchors premium tier availability. Distribution runs through industrial safety distributors bundling flame protection with respiratory systems, plus rental-service operators managing fleet logistics for large-scale refinery contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flame retardant apparel sits in early-cycle expansion as OSHA enforcement tightens compliance thresholds and displaces untreated cotton workwear across energy and utility sectors.
For Market Incumbents: Harden certification portfolio depth against regulatory divergence costs by securing dual NFPA 2112 and EN 11612 credentials ahead of state-level amendments in Texas and California. Anchor backward integration into meta-aramid fiber sourcing through partnerships with Shandong manufacturing clusters to defend margin position against regional competitor price aggression. For New Entrants and Emerging Players: Foundry applications in metalworking environments where Kevlar-reinforced cut and thermal protection converges represent the most penetrable entry point, given oil and gas saturation and firefighting incumbent lock-in. Target EN 11612 certification as the gating credential for EU chemical processing procurement, leveraging phosphorus-based fiber solutions to bypass REACH restrictions on halogenated chemistries. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant flame-resistant apparel divisions lacking certification depth or integrated ensemble capabilities. Long-term viability hinges on regulatory enforcement durability and fiber technology substitution patterns. Monitor OSHA state-level amendment adoption velocity as the primary inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Fiber | Captive Nomex supply secures margin control against Shandong competitor expansion. |
| Dual Certification Investment | NFPA 2112 plus EN 11612 credentials unlock multinational oil and gas procurement contracts. |
| Integrated Ensemble Development | Respiratory-flame-gas detection bundling captures Gulf Coast petrochemical single-vendor contracts. |
| Regional Manufacturing Footprint | Jiangsu province fabrication reduces lead times for Asia-Pacific utility sector demand. |
| Rental Service Network Expansion | Fleet logistics capabilities deepen account control with Texas refinery maintenance operators. |
Methodological Framework
Desk research of customs trade databases, OSHA enforcement records, and NFPA certification registries preceded structured interviews with oil and gas procurement directors, industrial laundry fleet managers, aramid fiber technical sales leads, and safety equipment distribution executives. Primary fieldwork across the Gulf Coast petrochemical corridor and Yangtze River Delta manufacturing zones combined with secondary validation from SEC filings of listed protective apparel suppliers and ECHA regulatory guidance documents. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Fixed assumptions across the analysis window held OSHA enforcement intensity, REACH regulatory trajectory, and aramid fiber capacity expansion schedules constant while varying oil and gas capital expenditure cycles, utility fleet replacement timing, and emergency responder modernization budget allocations. Segmentation modeling incorporated product type, material technology, end-use intensity, and certification jurisdiction dimensions. CAGRs derived from regression of historical replacement cycle data against regulatory mandate adoption curves, with thermal protective performance thresholds and laundering durability specifications as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in energy sector employment levels, petrochemical capital expenditure commitments, or industrial safety budget allocations would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timing and fiber technology substitution elasticities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Global Socks Market
Apparel Textiles
Europe Textile Garment Market
Apparel Textiles
Denim Market
Apparel Textiles
Bridal Wear Market
Apparel Textiles
China Flame Retardant Apparel Market
Apparel Textiles
Asia Pacific Garment Steamers Market
Apparel Textiles
Bamboo Apparel Market
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
Smart Apparel Market
Apparel Textiles
School Uniform Market
Apparel Textiles
OEM Clothing Manufacturer Service Market
Apparel Textiles
Cooling Apparel Market
Apparel Textiles
Horse Riding Apparel Market
Apparel Textiles
Uniform Market
Apparel Textiles
Welding Apparels Market
Apparel Textiles
Automotive Textiles Market