
 Braille Clothing Tags Market | 2026-2036
Braille Clothing Tags Market Size, Share, and Industry Trends Forecast 2026-2036
Braille Clothing Tags Market Outlook
Multi-source sourcing among specialty converters is recalibrating how brands secure compliant tactile labels. Brady Corporation leverages its identification-materials heritage to sustain dominance in industrial-grade tag formats. American Printing House for the Blind anchors nonprofit-scale production with deep institutional relationships across education and government channels. Braille Plus, Inc. specializes in small-batch customization, competing on turnaround speed for boutique apparel clients.
Braille clothing tags are tactile identification labels manufactured from woven or printed substrates with raised-dot patterns conforming to standardized Braille cell structures, typically affixed to garments via sewing, adhesive backing, or mechanical fasteners to convey fiber content, care instructions, and size data to visually impaired consumers. Polyester tag material leads unit economics due to dimensional stability under repeated laundering and compatibility with thermal transfer and embossing equipment. Screen printing retains share in high-volume uniform contracts, while digital printing gains ground in short-run fashion applications where variable data and rapid design iteration matter.
The U.S. Department of Justice enforces ADA Title III accessibility standards that extend to retail labeling, while the EU Accessibility Act mandates tactile information on consumer products sold across member states. The European Medicines Agency framework does not govern apparel directly, but CE marking requirements for consumer goods influence how exporters structure compliance documentation. Stakeholders must monitor evolving national implementation timelines for the EU Accessibility Act and track state-level procurement amendments in the United States that could expand mandatory Braille coverage beyond current institutional segments.
Market Dynamics
Specialty converters are consolidating embossing and printing capabilities to meet tightening disability inclusion mandates across institutional procurement channels. This supply-side concentration is redrawing competitive boundaries between industrial-scale label manufacturers and boutique accessibility service providers.
Growth Catalysts
- EU Accessibility Act implementation:The European Union's phased rollout of tactile labeling requirements for consumer goods is creating predictable demand corridors for compliant tag suppliers serving cross-border apparel distribution.
- Polyester substrate advances:Thermal-stabilized woven materials now withstand industrial laundering cycles above 50 washes, expanding addressable market from institutional uniforms into premium workwear segments.
- United States procurement expansion:State-level amendments to procurement codes in California, New York, and Illinois are extending Braille tag mandates beyond federal contracts into municipal and educational purchasing.
Market Restraints
- Embossing equipment concentration:Precision rotary embossing machinery is manufactured by a narrow base of German and Japanese capital equipment suppliers, creating bottleneck risk for capacity expansion.
- Cotton fiber cost volatility:Natural fiber tag alternatives face input price swings that compress margin stability for converters serving price-sensitive uniform contractors.
- Screen printing displacement limits:Thermal transfer technologies cannot yet match screen printing's cost position for single-color, ultra-high-volume military and corrections uniform contracts.
Strategic Opportunities
- India apparel export compliance:Indian garment manufacturers supplying EU and US markets represent an underpenetrated client base requiring retrofit labeling capabilities for accessibility compliance.
- Digital printing convergence:Variable-data inkjet systems combined with tactile varnish deposition enable short-run customization for fashion brands testing limited accessible product lines.
- Direct-to-consumer channel development:E-commerce platforms specializing in adaptive apparel are bypassing traditional wholesale label procurement, creating demand for direct-fulfillment tag services.
Industry Challenges
- Certified Braille transcription talent scarcity:Accurate grade 2 contracted Braille translation requires certified linguists, and training pipeline capacity lags demand growth in North American and European markets.
- Multi-jurisdiction compliance complexity:Converters must maintain parallel quality systems for ADA Title III, EU Accessibility Act, and divergent national implementation timelines, increasing overhead without proportional revenue scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Braille Clothing Tags Market |
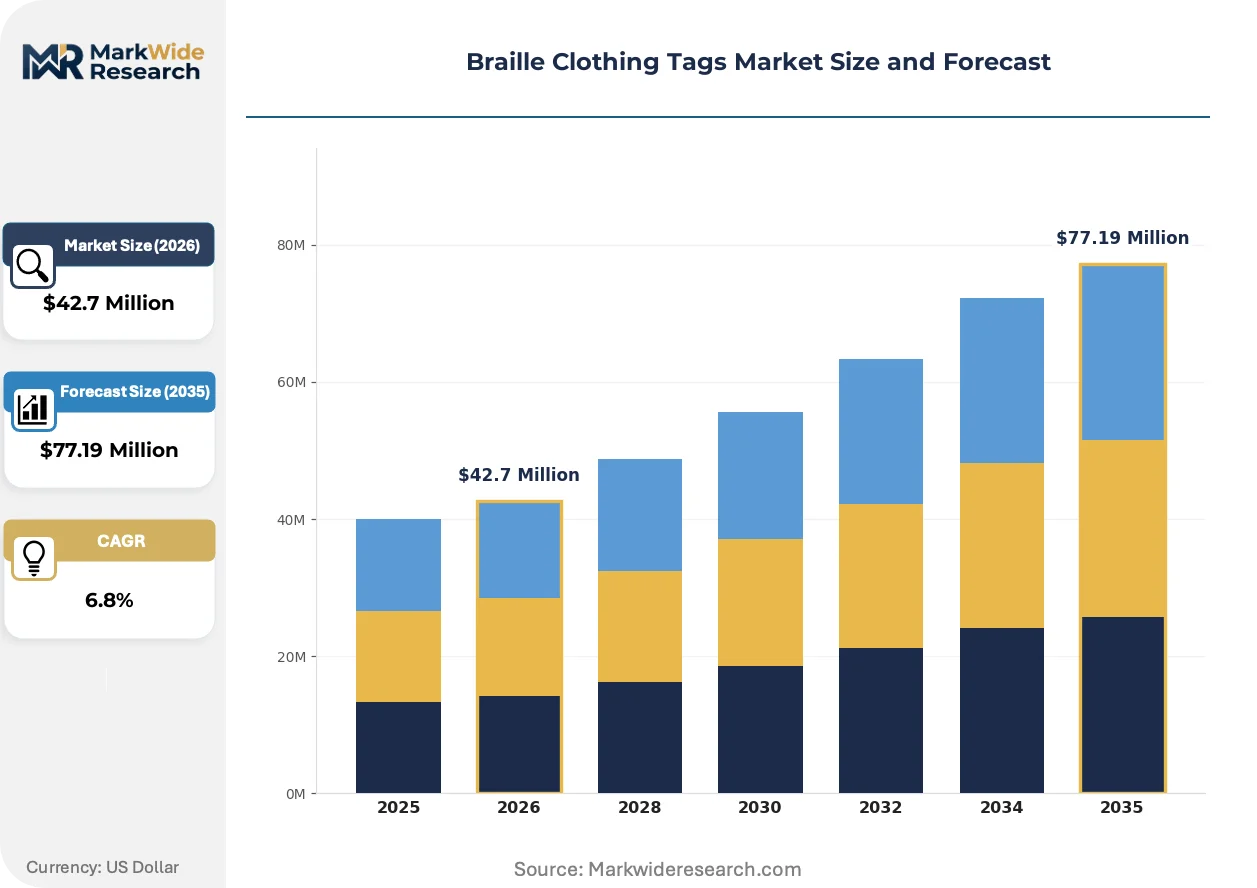
| Market Size in 2026 | $42.7 Million |
| Market Size in 2035 | $77.19 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tag Material: Polyester, Cotton, Nylon, Leather Printing Method: Digital Printing, Screen Printing, Thermal Transfer, Embossing Market Segment: Apparel, Accessories, Footwear, Home Textiles Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Smurfit Kappa, DS Smith, Labels Inc., International Paper, Mondi Group, Brady Corporation, WestRock, Braille Plus, Inc., American Printing House for the Blind, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Braille Clothing Tags Market Strategic Shifts
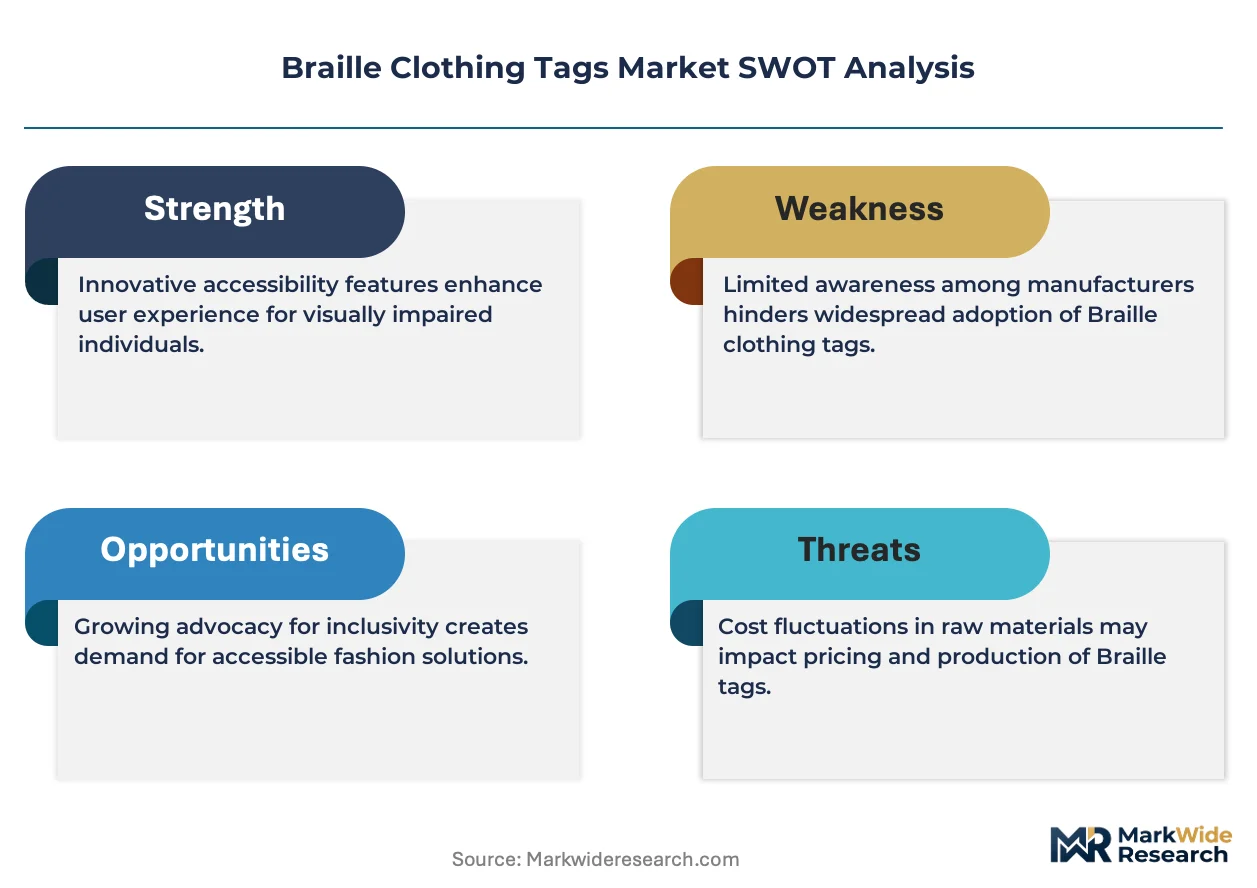
Tactile labeling technology is bifurcating between high-throughput industrial systems and agile digital workflows. This divergence is reshaping how converters segment their capabilities and which customer tiers they can profitably serve.
Laser micro-embossing systems are automating the conversion of digital design files into physical Braille cells without mechanical die setup. Specialty uniform contractors in the United States are adopting these systems for mid-volume government contracts where lot sizes fluctuate. The technology is automating changeover processes that previously required skilled technician intervention, compressing minimum efficient scale thresholds.
The EU Accessibility Act's 2025-2030 implementation timeline is mandating tactile information layers on consumer-facing garment labels sold across member states. Apparel exporters to the European Union are restructuring compliance documentation and supplier qualification protocols. Fashion brands with seasonal product cycles are most affected, accelerating partnerships with converters capable of rapid certification turnaround.
Adaptive apparel specialists are consolidating purchasing authority previously dispersed across nonprofit intermediaries. Direct relationships between label converters and disability-focused retailers are displacing traditional wholesale channel structures. This concentration is most visible in United States e-commerce, where vertically integrated adaptive brands now specify tactile labeling requirements at the design stage rather than retrofitting standard products.
Braille Clothing Tags Market Segmentation
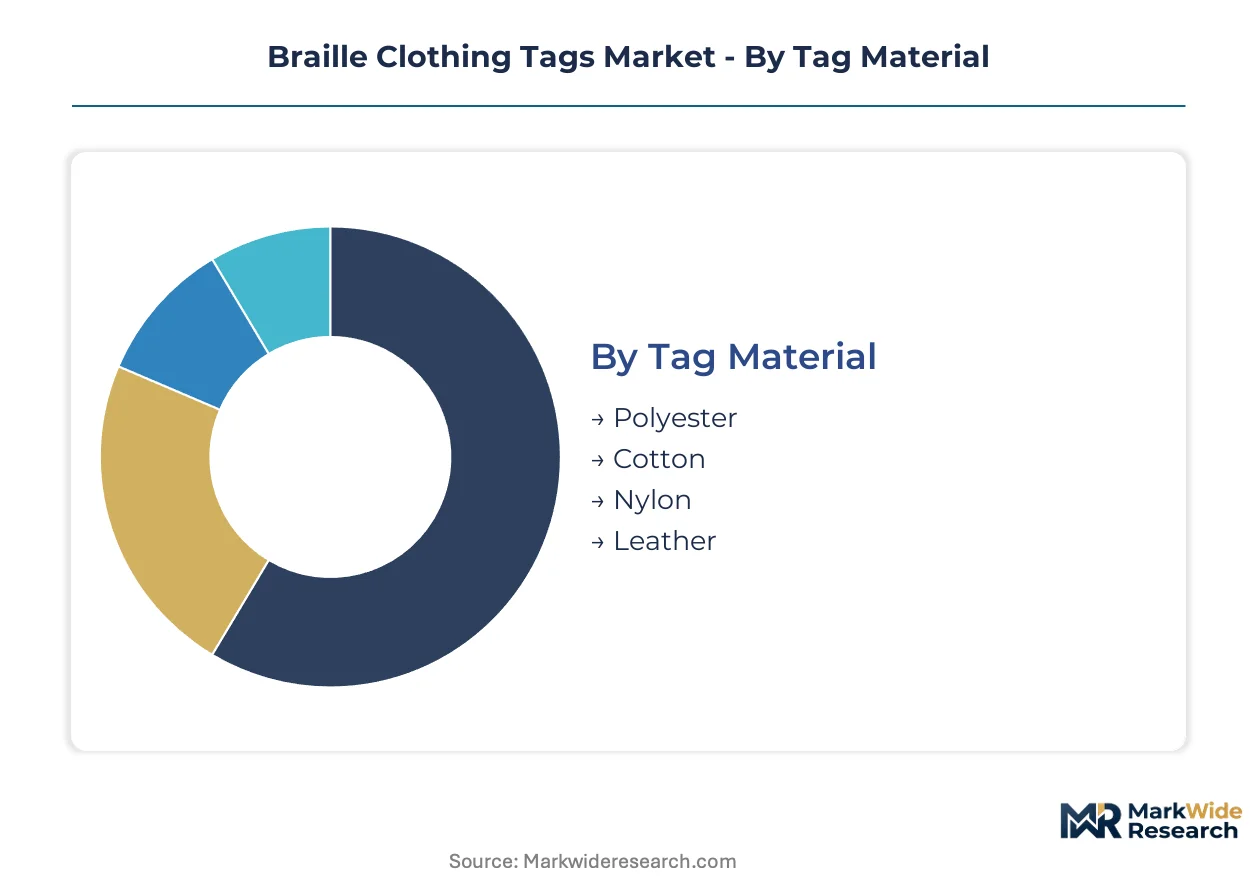
Braille clothing tag procurement varies sharply by material durability requirements, production scale, and regulatory exposure. Converters must align substrate and printing choices with end-use laundering intensity and jurisdiction-specific compliance mandates.
Tag Material:
Material selection tracks integration depth: polyester and nylon embed into high-cycle institutional supply chains, while cotton and leather serve standalone premium and fashion applications.
- Polyester:Woven thermoplastic substrates deliver dimensional stability across industrial laundering cycles exceeding fifty washes. United States uniform contractors specify polyester for federal and state procurement contracts where thermal transfer embossing compatibility reduces per-unit processing cost.
- Cotton:Natural fiber constructions offer tactile softness valued in direct-to-consumer adaptive apparel. California-based specialty retailers favor cotton tags for premium positioning, though fiber price volatility compresses converter margins on small-batch orders.
- Nylon:High-tenacity synthetic withstands abrasion in workwear and outdoor gear segments.
- Leather:Embossed hide substrates serve luxury accessories and heritage footwear lines requiring elevated aesthetic differentiation.
Volume placements concentrate in polyester; the faster expansion belongs to cotton.
Printing Method:
Process economics stratify by run length and color complexity, with capital-intensive methods dominating institutional channels and digital workflows penetrating fashion-adjacent segments.
- Digital Printing:Variable-data inkjet systems enable rapid design iteration for limited accessible product lines. European fashion brands testing EU Accessibility Act compliance deploy digital printing for seasonal collections where lot sizes fall below screen printing minimums.
- Thermal Transfer:Ribbon-based imaging produces crisp Braille cells on polyester substrates with consistent dot height. Illinois municipal uniform contractors specify thermal transfer for mid-volume educational procurement where color consistency matters less than durability certification.
- Screen Printing:Stencil-based deposition retains cost advantage for single-color, ultra-high-volume military contracts.
- Embossing:Mechanical and laser micro-embossing systems create tactile relief without ink, preferred for applications requiring chemical-free labeling.
Screen printing anchors current volume; digital printing is gaining share fastest.
Market Segment:
End-use diversification reflects how accessibility mandates penetrate apparel versus adjacent textile categories at different regulatory velocities.
- Apparel:Government-funded uniforms, institutional garments, and adaptive fashion lines constitute the core demand base. New York state procurement amendments now require Braille tags on municipal employee workwear, expanding addressable volume beyond federal contracts.
- Accessories:Bags, belts, and wearable items face emerging tactile labeling requirements under EU Accessibility Act implementation timelines.
- Footwear:Size and care information in Braille remains optional in most jurisdictions, though specialty adaptive brands are voluntarily adopting standards.
- Home Textiles:Bedding and bath products fall outside current mandate scope, limiting converter investment in category-specific certification.
Apparel dominates placement volume; accessories show the steepest expansion trajectory.
Distribution Channel:
Channel structure determines whether converters serve wholesale intermediaries or build direct relationships with specification-setting end customers.
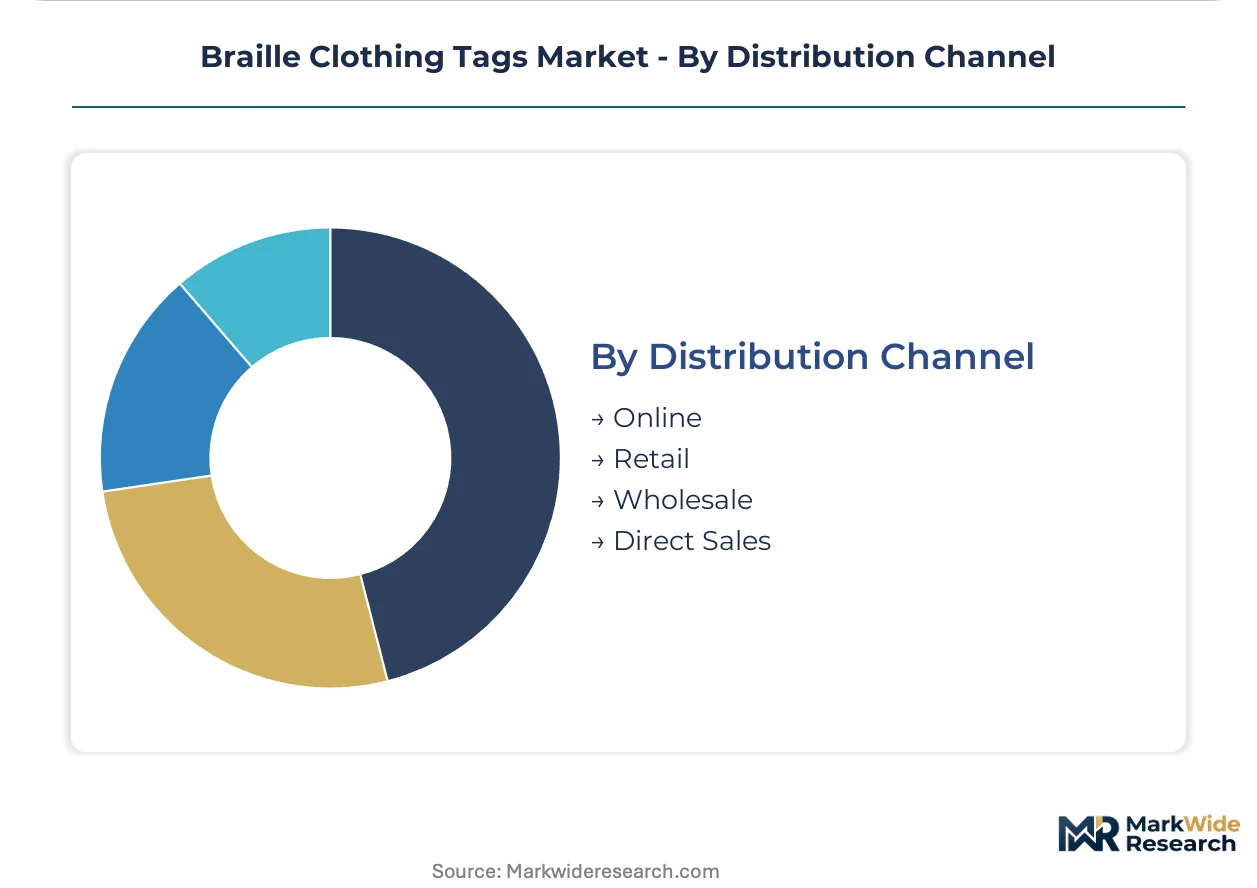
- Online:E-commerce platforms specializing in adaptive apparel are consolidating purchasing authority previously dispersed across nonprofit intermediaries. Vertically integrated brands now specify tactile requirements at design stage.
- Retail:Specialty apparel retailers expanding accessible product lines drive demand for rapid-turnaround tag services.
- Wholesale:Traditional bulk procurement channels serve institutional uniform contractors with predictable volume but compressed pricing.
- Direct Sales:Converter-to-brand relationships are displacing distributor intermediaries for compliance-critical contracts requiring certification documentation.
Wholesale channels handle current volume concentration; online distribution is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement mandates concentrate demand for Braille clothing tags, with federal and state-level requirements driving institutional uniform adoption. European regulatory timelines are accelerating exporter compliance investments. Asian manufacturing hubs face retrofit labeling demands as accessibility standards tighten in destination markets.
United States
Federal uniform contracts and state procurement amendments in California, New York, and Illinois anchor North American volume. The Department of Justice enforces ADA Title III accessibility standards extending to retail labeling requirements. Chicago-based specialty converters serve municipal and educational purchasing channels with thermal-stabilized polyester tags.
Germany
Industrial-grade embossing equipment manufacturing and EU Accessibility Act implementation timelines drive converter investment decisions. CE marking requirements for consumer goods influence how apparel exporters structure compliance documentation. Bavarian precision machinery suppliers dominate rotary embossing equipment production for European tag converters.
United Kingdom
Post-Brexit regulatory alignment discussions and adaptive fashion e-commerce growth reshape channel structures. The Equality Act 2010 provisions inform tactile labeling expectations across retail and institutional segments. London-based specialty retailers are consolidating direct relationships with label converters for rapid-turnaround accessible product lines.
India
Garment export compliance requirements for EU and US markets create retrofit labeling demand among apparel manufacturers. The Bureau of Indian Standards framework influences domestic quality expectations for textile labeling. Tirupur and Bengaluru industrial clusters are developing in-house embossing capabilities to meet importer accessibility documentation.
France
Luxury fashion houses and heritage footwear brands drive premium leather tag demand with elevated aesthetic differentiation requirements. ANSM and CNIL regulatory frameworks inform consumer protection expectations for tactile information disclosure. Paris-based adaptive apparel specialists are specifying Braille requirements at the design stage for limited accessible collections.
Braille Clothing Tags Market Competitive Environment
Capacity expansion dominates the current landscape as specialty converters consolidate embossing and printing capabilities to meet tightening disability inclusion mandates. The vendor base stratifies between industrial-scale label manufacturers with thermal transfer and screen printing infrastructure and boutique accessibility service providers competing on turnaround speed. Three archetypes define competitive positioning: diversified packaging conglomerates with label divisions, dedicated tactile labeling specialists, and nonprofit-scale producers with institutional channel relationships. Geographic expansion and strategic partnerships represent the dominant competitive moves, with converters pursuing certification reciprocity across multiple jurisdictions.
Within the diversified industrial tier, Brady Corporation and Smurfit Kappa occupy positions spanning identification materials and packaging solutions. American Printing House for the Blind anchors the nonprofit archetype with deep institutional relationships across education and government channels. Braille Plus, Inc. exemplifies the boutique specialist model, competing on customization velocity for smaller apparel clients.
| Leading Market Players |
|---|
| Smurfit Kappa |
| DS Smith |
| Labels Inc. |
| International Paper |
| Mondi Group |
| Brady Corporation |
| WestRock |
| Braille Plus, Inc. |
| American Printing House for the Blind |
| Others |
Value Chain & Pricing Dynamics
Polyester fiber price indices cascade through Braille tag supply chains into three distinct pricing tiers, with thermal-stabilized woven substrates commanding premium positioning against cotton alternatives facing volatile input costs from agricultural commodity swings.
Pricing Analysis
Volume-mass procurement anchors economy-tier positioning for federal uniform contractors, while margin-rich customization serves boutique adaptive fashion brands. Three-tier pricing structure across premium, standard, and economy levels separates certified-grade transcription services from rapid-turnaround digital workflows. Cost compression in cotton-based tags is intensifying because natural fiber price volatility compresses converter margins without proportional demand scaling. Municipal procurement officers exhibit highest price sensitivity, whereas vertically integrated adaptive apparel brands absorb premium positioning for design-stage specification control.
Supply Chain Analysis
Reverse-logistics flows for mis-embossed tags and transcription errors concentrate quality-control investments at converter facilities rather than downstream distribution nodes. Precision rotary embossing equipment draws from German and Japanese capital goods manufacturers, while polyester substrate supply rests on petrochemical value chains anchored in the United States and South Korea. Single-source vulnerability around certified Braille transcription talent creates bottleneck risk for capacity expansion. Distribution runs through converter-to-brand direct relationships for compliance-critical contracts, with wholesale channels serving institutional uniform contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Braille clothing tag supply chains are becoming a vertical-integration race as converters pursue in-house embossing equipment capabilities to bypass German and Japanese machinery bottlenecks.
For Market Incumbents: Deploy certification reciprocity investments to defend against emerging digital-printing specialists eroding share in short-run fashion segments. Consolidate thermal transfer capacity in Illinois and California to capture state procurement amendment volume before competitors qualify. Channel control through direct relationships with adaptive apparel e-commerce platforms offsets pricing pressure from wholesale intermediaries. For New Entrants and Emerging Players: Indian garment exporters retrofitting for EU Accessibility Act compliance represent the most penetrable buyer archetype requiring outsourced labeling capabilities without in-house embossing investment. Fashion brands testing limited accessible collections offer white-space demand for variable-data digital printing with tactile varnish deposition. Go-to-market positioning as rapid-certification specialists for seasonal product cycles differentiates against incumbent turnaround constraints. For Investors and Strategic Acquirers: The window for entry favors boutique tactile labeling specialists with certified transcription pipelines and established converter-to-brand relationships. Five-to-ten year viability hinges on EU Accessibility Act enforcement velocity and US state-level procurement expansion beyond current federal contract scope. Monitor Indian Bureau of Indian Standards framework evolution for domestic quality expectation signals that could accelerate exporter compliance investment.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Micro-Embossing Adoption | Automated digital-to-tactile conversion compresses minimum efficient scale thresholds for mid-volume government contracts. |
| Certified Transcription Pipeline Investment | Grade 2 contracted Braille linguist training capacity lags demand growth in North American and European markets. |
| India Export Market Development | Tirupur and Bengaluru garment clusters require retrofit labeling capabilities for EU and US accessibility documentation. |
| Direct-to-Consumer Channel Partnership | Vertically integrated adaptive brands now specify tactile requirements at design stage rather than retrofitting standard products. |
| Multi-Jurisdiction Certification Reciprocity | Parallel quality systems for ADA Title III and EU Accessibility Act reduce overhead without proportional revenue scaling. |
Study Parameters
Trade publications, customs records, and SEC filings from packaging conglomerates formed the secondary backbone for supply-side capacity mapping. Primary interviews with label converter operations managers, adaptive apparel brand procurement directors, municipal uniform contracting officers, and certified Braille transcription specialists combined with secondary validation through bottom-up and top-down triangulation approaches.
Bottom-up modeling aggregated segment-level unit economics across material, printing method, and distribution channel dimensions, while top-down cross-checks validated aggregate market sizing against procurement volume disclosures. CAGRs were derived from regression analysis of historical mandate implementation velocity and projected regulatory expansion timelines. Industry-specific forecast inputs included EU Accessibility Act national implementation schedules and US state-level procurement amendment tracking.
Revisions become necessary when regulatory enforcement timelines accelerate or delay, certified transcription training pipeline capacity shifts, or raw material price volatility alters converter margin structures. Practitioners should monitor Bureau of Indian Standards framework evolution and EU member state implementation decrees for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
Global Prom Dresses Market
Apparel Textiles
Blank Apparel Market
Apparel Textiles
Rolle Market
Apparel Textiles
Smart Apparel Market
Apparel Textiles
Japan Denim Jeans Market
Apparel Textiles
Women's Cheongsam Market
Apparel Textiles
Head Scarves Market
Apparel Textiles
OEM Clothing Manufacturer Service Market
Apparel Textiles
Knitwear Market
Apparel Textiles
Functional Apparel Market
Apparel Textiles
Uniform Market
Apparel Textiles
Global Socks Market
Apparel Textiles
Denim Market
Apparel Textiles
Clothing Manufacturing Service Market
Apparel Textiles
Equestrian Apparel Market