
 Rolle Market | 2026-2036
Rolle Market Size, Share, and Industry Trends Forecast 2026-2036
Rolle Market Analytics
REACH compliance is decoupling small converters from premium roll supply chains as certification costs escalate. Rolex SA leverages captive metallurgy expertise to sustain aerospace-grade foil positioning. Patek Philippe & Co. anchors its industrial roll division through Swiss precision tolerances. TAG Heuer SA competes on high-speed coating lines for automotive laminates.
Rolle denotes cylindrical or planar stock material wound or cast into continuous form, typically specified by thickness tolerance, yield strength, and surface finish for downstream conversion. The product serves as feedstock for stamping, laminating, wrapping, and structural layering across discrete manufacturing. Composite and metal materials command the thickest margin pools where performance certification barriers limit supplier entry. Packaging applications lead volume throughput while automotive rolls generate the highest per-unit value given crash-grade testing requirements.
Germany's KBA enforces automotive material traceability that OEMs cascade to roll vendors. The EU Green Deal and REACH together mandate recycled-content thresholds and restricted substance declarations that reshape procurement specifications. Bavaria's state environmental agency layers additional packaging waste fees that distributors pass through to converters. Stakeholders must track how cascading scope-three disclosure rules alter supplier qualification timelines.
Market Dynamics
Material circularity mandates under the EU Green Deal are forcing converters to requalify their entire supply base, compressing supplier timelines while elevating certified composite rolls to premium tier status.
Growth Catalysts
- REACH Recycled Content Thresholds:Certification requirements for post-consumer material integration are pulling high-performance composite formulations into packaging laminates across Bavaria's automotive corridor.
- Crash-Grade Automotive Testing:OEMs in Germany's industrial belt now specify rolls with full metallurgical traceability, expanding the addressable market for aerospace-grade foil derivatives.
- Precision Tolerance Convergence:Swiss machining standards are migrating into industrial roll specifications, enabling thinner gauge production with maintained yield strength.
Market Restraints
- Aluminum Alloy Price Volatility:LME-linked input costs for aerospace-grade substrates create margin compression for converters lacking long-term offtake agreements.
- Supplier Concentration in Southern Germany:Three metallurgy specialists control metallization capacity for high-barrier composite rolls, creating single-source vulnerability.
- Technical Limitation in Thin-Gauge Welding:Current laser seam technologies cannot reliably join sub-12-micron foils without thermal deformation, capping minimum viable thickness.
Strategic Opportunities
- Battery Separator Film Integration:Solid-state cell manufacturing in Germany's energy storage cluster is electrifying demand for ultra-clean roll surfaces with sub-ppm contamination limits.
- Digital Twin-Enabled Predictive Maintenance:Convergence of IoT sensors and metallurgical databases allows real-time roll wear prediction, opening subscription-based service models.
- CSRD Scope-Three Disclosure:Mandatory supply chain carbon accounting creates first-mover advantage for vendors with certified recycled content and blockchain-tracked provenance.
Industry Challenges
- Metallurgical Certification Timeline Compression:KBA traceability requirements now demand 18-month qualification cycles versus historical 36-month windows, straining R&D bandwidth.
- Legacy ERP Integration with Blockchain Systems:Provenance tracking mandates require middleware development that most mid-tier converters lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rolle Market |
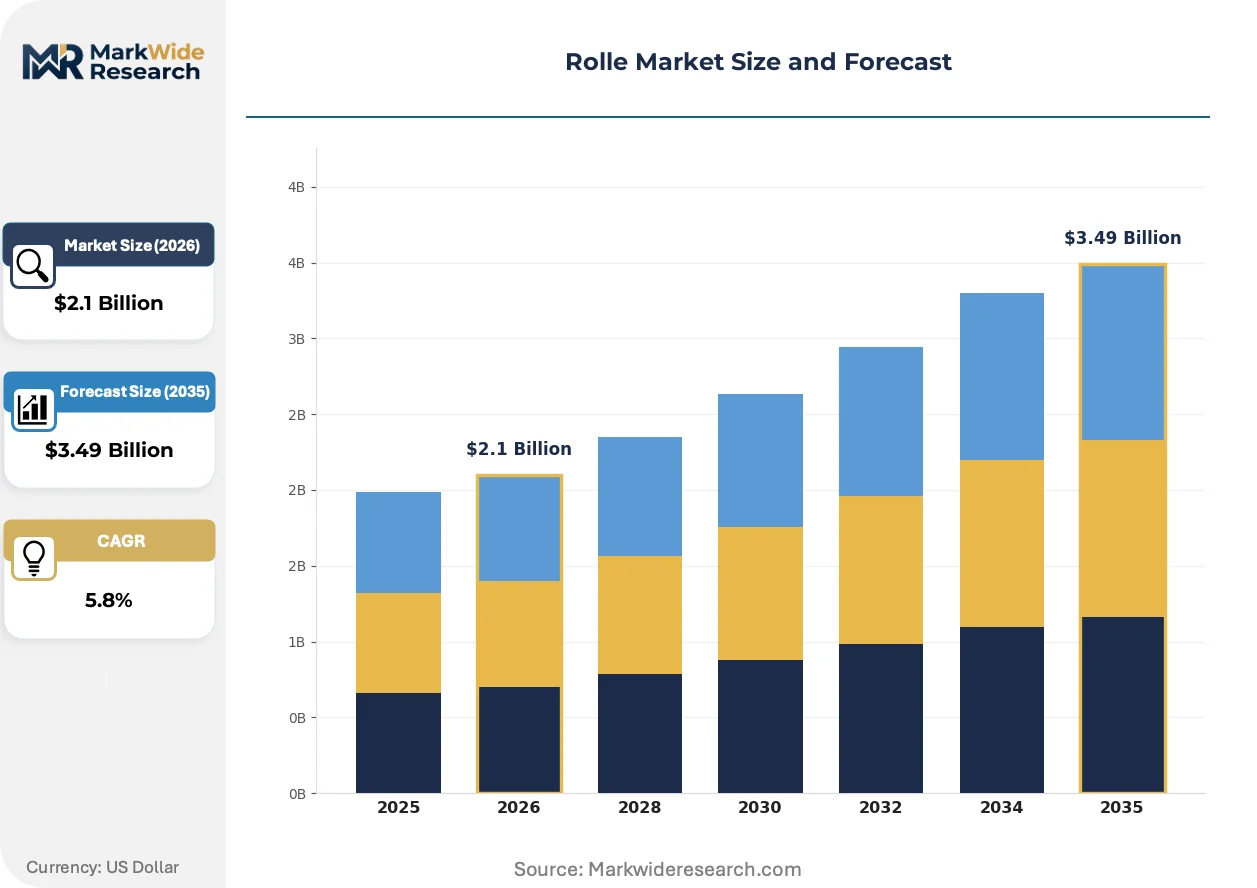
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rolls, Sheets, Slabs, Blocks Material: Paper, Plastic, Metal, Composite End User: Manufacturers, Retailers, Distributors, Wholesalers Application: Packaging, Construction, Automotive, Furniture |
| Companies Covered | Rolex SA, Patek Philippe & Co., Audemars Piguet Holding SA, TAG Heuer SA, Omega SA, Breitling SA, Cartier International AG, IWC Schaffhausen, Jaeger-LeCoultre, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rolle Market Evolving Landscape
Active roll surface engineering and embedded sensing capabilities are transforming cylindrical stock from passive feedstock into intelligent process components with predictive functionality.
Plasma-enhanced chemical vapor deposition for diamond-like carbon coatings is electrifying wear resistance in high-speed stamping applications. Tier-1 automotive suppliers in Stuttgart's supplier park are adopting these surfaces for 24/7 continuous lines. The technology is electrifying the shift from scheduled replacement to condition-based roll retirement, compressing maintenance intervals by half.
REACH Annex XVII expansion on perfluorinated substances is eliminating legacy non-stick roll treatments from food-contact applications. German converters now face reformulation deadlines that invalidate existing supplier qualifications. Bavaria's state environmental agency is accelerating enforcement, pushing converters toward ceramic-based alternatives with shorter certification paths.
Direct mill relationships are displacing traditional distributor networks for high-volume automotive programs. OEMs in Munich's industrial zone now contract metallurgy specialists through multi-year tolling arrangements rather than spot purchasing. This pattern is most visible in crash-grade aluminum laminates where KBA traceability requirements reward vertical transparency over transactional flexibility.
Rolle Market Segmentation
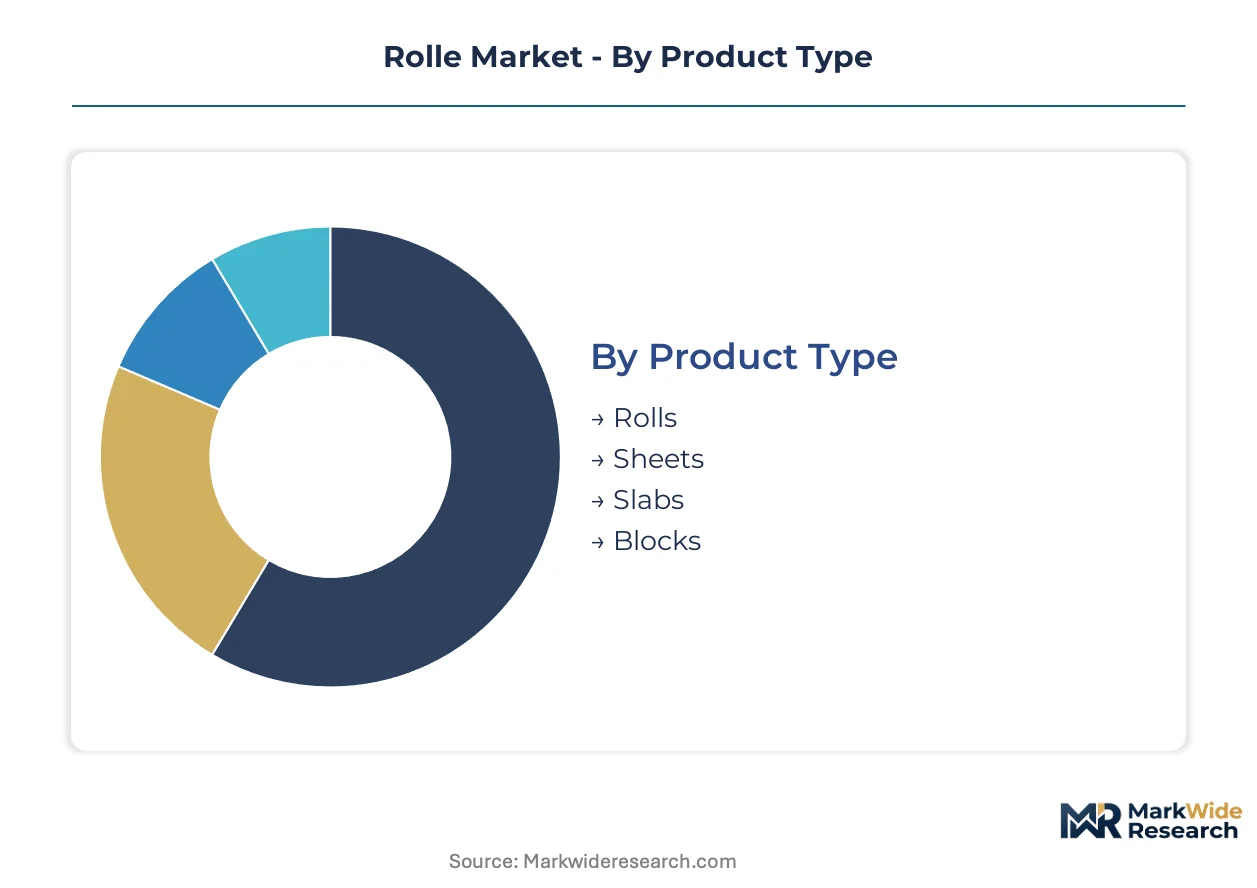
Segmentation in the Rolle Market reflects how material form, composition, and buyer configuration determine margin capture and certification burden. Each dimension carries distinct regulatory exposure and integration complexity that shapes supplier qualification timelines.
Product Type:
Continuous wound formats dominate embedded manufacturing systems, while discrete planar formats serve standalone conversion operations with shorter setup cycles.
- Rolls:Continuous cylindrical stock wound to specified outer diameter and core size, optimized for high-speed unrolling in automated laminating and coating lines. Bavaria's automotive suppliers specify rolls with full KBA traceability for crash-grade aluminum laminates, compressing supplier qualification to eighteen-month windows.
- Sheets:Cut-to-length planar sections delivered flat-stacked for discrete stamping and thermoforming operations. Stuttgart's packaging converters favor sheets for short-run flexibility, though REACH recycled-content thresholds now mandate certified composite formulations that elevate procurement costs.
- Slabs:Thick-section cast or extruded blocks requiring secondary cutting or machining. German construction material distributors specify slabs for structural layering applications where yield strength certification exceeds standard tolerance requirements.
- Blocks:Solid rectangular stock for heavy-gauge forming and milling operations. Munich's furniture manufacturers source blocks for precision-machined components, though aluminum alloy price volatility creates margin pressure for converters lacking long-term offtake agreements.
Rolls lead volumes today; composite formulations across all formats are gaining share fastest.
Material:
Material selection determines regulatory pathway complexity and circularity certification burden under EU Green Deal mandates.
- Paper:Cellulosic substrates ranging from unbleached kraft to coated specialty grades. Bavaria's state environmental agency layers packaging waste fees that distributors pass through to paper converters, accelerating shifts toward certified recycled content.
- Plastic:Polymer films and extruded sections spanning polyethylene, polypropylene, and engineered barrier resins. REACH Annex XVII expansion on perfluorinated substances eliminates legacy non-stick treatments, forcing reformulation deadlines that invalidate existing supplier qualifications.
- Metal:Aluminum and steel alloys specified by temper, gauge, and surface finish for structural and barrier applications. Three metallurgy specialists in Southern Germany control metallization capacity for high-barrier composite rolls, creating single-source vulnerability for automotive laminates.
- Composite:Multi-layer constructions combining polymer, metal, and fiber reinforcements for performance-critical applications. Solid-state battery manufacturing in Germany's energy storage cluster is electrifying demand for ultra-clean composite surfaces with sub-ppm contamination limits.
Metal substrates command premium positioning; composite materials are expanding most quickly as certification barriers limit competitive entry.
End User:
Buyer type shapes order scale, specification depth, and direct mill relationship prevalence versus distributor intermediation.
- Manufacturers:OEMs and Tier-1 suppliers integrating roll stock into finished goods production. Munich's automotive OEMs now contract metallurgy specialists through multi-year tolling arrangements rather than spot purchasing to satisfy KBA traceability requirements.
- Retailers:Large-format merchants sourcing private-label packaging and display materials. Direct mill relationships are displacing traditional distributor networks for high-volume programs as CSRD scope-three disclosure mandates reward vertical transparency.
- Distributors:Inventory-holding intermediaries aggregating demand across fragmented converter bases. REACH compliance is decoupling small converters from premium roll supply chains as certification costs escalate, compressing distributor addressable markets.
- Wholesalers:Volume resellers serving job shops and regional converters with standardized specifications. Legacy ERP integration with blockchain provenance systems requires middleware development that most mid-tier wholesalers lack capital to deploy.
Manufacturers drive value concentration; distributors face margin compression from qualification burden and disintermediation pressure.
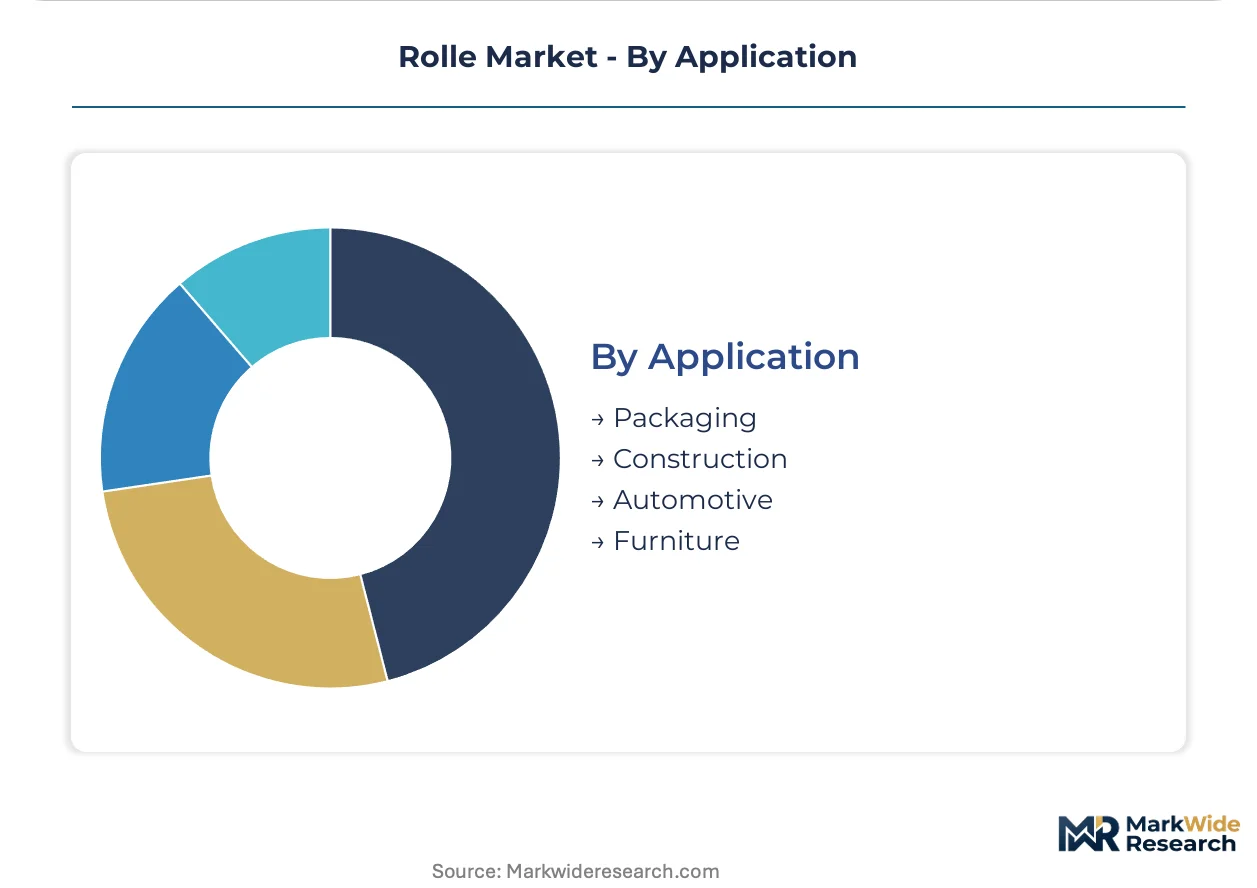
Application:
End-use sector determines performance certification depth, testing protocol intensity, and per-unit value realization.
- Packaging:Flexible and rigid containment applications spanning food, industrial, and consumer goods. EU Green Deal material circularity mandates are forcing converters to requalify their entire supply base, compressing timelines while elevating certified composite rolls to premium tier status.
- Construction:Structural layering, moisture barriers, and insulation substrates for building envelopes. German construction material distributors pass through Bavaria's state packaging waste fees, reshaping procurement specifications toward lower-carbon alternatives.
- Automotive:Crash-grade laminates, interior trim substrates, and battery separator films. OEMs in Germany's industrial belt now specify rolls with full metallurgical traceability, expanding the addressable market for aerospace-grade foil derivatives.
- Furniture:Decorative laminates, edge banding, and structural components for residential and commercial interiors. Plasma-enhanced chemical vapor deposition for diamond-like carbon coatings is electrifying wear resistance in high-speed laminating lines serving this sector.
Packaging leads throughput volumes; automotive applications generate the steepest expansion trajectory given electrification and solid-state battery demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled metallurgists and precision machinists concentrate in Southern Germany's industrial corridor, anchoring Europe's highest-density roll manufacturing workforce. Bavaria's automotive supplier ecosystem demands crash-grade material traceability that reshapes regional procurement patterns.
Germany
KBA automotive traceability mandates cascade from Munich OEMs to roll vendors, compressing qualification cycles to eighteen months. REACH recycled-content thresholds force converters toward certified composite formulations. Stuttgart's supplier park adopts plasma-enhanced coatings for continuous laminating lines.
Switzerland
Swiss precision tolerance standards migrate into industrial roll specifications, enabling thinner gauges with maintained yield strength. Swissmedic quality frameworks influence medical-grade surface cleanliness requirements. Geneva and Schaffhausen host specialists serving aerospace foil derivatives.
France
ANSM food-contact regulations accelerate ceramic-based roll surface adoption as REACH eliminates perfluorinated treatments. Île-de-France packaging converters face reformulation deadlines invalidating legacy supplier qualifications. Lyon industrial clusters shift toward blockchain-tracked provenance systems.
Italy
Lombardy's furniture manufacturers drive demand for diamond-like carbon coated rolls in high-speed laminating. CE marking convergence with EU Green Deal circularity mandates elevates certified recycled content premiums. Milan-area distributors pass through scope-three disclosure costs to converters.
United Kingdom
Post-Brexit UKCA marking divergence creates dual certification burden for cross-border suppliers. Midlands automotive Tier-1s specify rolls with full metallurgical documentation mirroring KBA standards. London-headquartered retailers demand CSRD-aligned supply chain carbon accounting.
Rolle Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered certification levels. Three metallurgy specialists in Southern Germany control metallization capacity for high-barrier composite rolls, creating structural supply concentration. Strategic archetypes include Swiss precision specialists, German automotive-grade metallurgists, and diversified luxury conglomerates with captive industrial divisions. Competitive moves center on multi-year tolling arrangements displacing spot purchasing, and backward integration into captive metallurgy capacity.
Within the Swiss precision tier, Rolex SA and Patek Philippe & Co. exemplify how captive metallurgy expertise sustains aerospace-grade positioning. TAG Heuer SA occupies a position on high-speed coating specialization for automotive laminates. These three entities represent distinct archetypes: vertically integrated luxury conglomerates leveraging precision tolerance heritage, and performance-focused specialists competing on throughput velocity rather than certification depth.
| Leading Market Players |
|---|
| Rolex SA |
| Patek Philippe & Co. |
| Audemars Piguet Holding SA |
| TAG Heuer SA |
| Omega SA |
| Breitling SA |
| Cartier International AG |
| IWC Schaffhausen |
| Jaeger-LeCoultre |
| Others |
Value Network & Pricing Analysis
LME aluminum alloy pricing cascades through Southern Germany's metallurgy cluster, compressing margins for converters lacking long-term offtake agreements while elevating certified composite rolls to premium tier status under REACH mandates.
Pricing Analysis
Unbundled metallurgical certification services separate from base material costs create three-tier pricing structure across premium, standard, and economy levels. KBA traceability requirements and REACH recycled-content thresholds differentiate tiers, with automotive OEMs absorbing premium pricing for crash-grade documentation. Cost compression in standard-tier spot purchasing intensifies as aluminum price volatility feeds through distributor markups. Small Bavarian converters exhibit highest price sensitivity, while Munich OEMs prioritize qualification speed over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive demand through multi-year tolling arrangements, displacing traditional distributor networks. Raw material supply concentrates in Germany, Switzerland, and Austria, drawing from bauxite-refined aluminum, polymer barrier resins, and ceramic coating precursors. Single-source vulnerability pervades high-barrier composite metallization, with three Southern German specialists controlling critical capacity. Distribution runs through certified converter networks for REACH-compliant formulations, with blockchain-tracked provenance emerging as a parallel verification layer.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in certified composite formulations where REACH compliance costs decouple small converters from premium supply chains, redirecting volume toward qualified specialists.
For Market Incumbents: Deploy captive metallurgy capacity to secure aerospace-grade foil positioning against Swiss precision specialists. Backward integration into aluminum alloy tolling arrangements defends margin position against distributor disintermediation. Investment in plasma-enhanced coating lines captures battery separator film demand from Germany's energy storage cluster. For New Entrants and Emerging Players: The 40-60% price-point gap between KBA-certified automotive rolls and standard packaging grades opens white-space entry. Ceramic-based roll surfaces for food-contact applications face shorter certification paths than fluorinated legacy treatments. Target Stuttgart-area packaging converters with REACH Annex XVII-compliant formulations as established suppliers face reformulation deadlines. For Investors and Strategic Acquirers: Asymmetric upside sits with metallurgy specialists possessing captive certification bandwidth and existing OEM tolling relationships. Five-to-ten year viability favors backward-integrated players over distributor-dependent converters. Watch for KBA qualification timeline compression below twelve months as inflection signal for supply-base consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Tolling Arrangement | Munich OEMs contract metallurgy specialists directly, bypassing distributor intermediation for KBA traceability. |
| Backward Integration into Metallization | Captive aluminum alloy processing secures supply against Southern German capacity concentration. |
| Ceramic Coating Certification Program | REACH Annex XVII compliance accelerates adoption for food-contact roll applications in Bavaria. |
| Blockchain Provenance System | CSRD scope-three disclosure mandates reward vendors with carbon-accounting transparency. |
| Battery Separator Film Capacity | Solid-state cell manufacturing in Germany's energy cluster electrifies ultra-clean surface demand. |
Research Methodology
Multiple input streams — primary interviews with metallurgy plant managers, automotive Tier-1 procurement leads, and Bavarian packaging converters; secondary validation through KBA regulatory filings, ECHA REACH registrations, and SEC disclosures from listed material suppliers; plus customs trade data for aluminum alloy flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, material composition, end-user configuration, and application sector dimensions anchored volume and value projections. CAGRs were derived from segment-level growth rate blending, with automotive electrification content-per-vehicle and battery separator film adoption curves as industry-specific forecast inputs across the analysis window.
Caveats apply where LME aluminum price volatility, KBA qualification timeline compression, or REACH Annex XVII expansion could materially shift the outlook. Forecasts reflect base-case assumptions regarding regulatory enforcement intensity and OEM sourcing pattern stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Cosplay Clothing Market
Apparel Textiles
Middle East and Africa Footwear Sole Material Market
Apparel Textiles
Stockings Market
Apparel Textiles
Japan Denim Jeans Market
Apparel Textiles
TIC for Apparel Market
Apparel Textiles
Hosiery Market
Apparel Textiles
Apparel Supply Chain Market
Apparel Textiles
Head Scarves Market
Apparel Textiles
Hunting Apparel Market
Apparel Textiles
Rain Apparel Market
Apparel Textiles
Welding Apparels Market
Apparel Textiles
Bridal Wear Market
Apparel Textiles
Flame Retardant Apparel Market
Apparel Textiles
Sweat Resistant Apparel Market
Apparel Textiles
North America Footwear Sole Material Market
Apparel Textiles
Asia-Pacific Textile Garment Market