
 Asia Pacific Garment Steamers Market | 2026-2036
Asia Pacific Garment Steamers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Garment Steamers Market Insights
Aftermarket service revenue for garment steamer replacement tanks, heating elements, and descaling kits is fragmenting across independent repair networks and authorized service channels. Panasonic Corporation leverages its established appliance service infrastructure across Japan and Southeast Asia to capture recurring maintenance spend. Haier Group anchors its position through integrated supply chain control over heating coil production, while Midea Group competes aggressively on manufacturing scale in Guangdong province.
Asia Pacific garment steamers are pressurized or gravity-fed electrical appliances that deliver saturated steam at temperatures between 100°C and 150°C through a handheld nozzle or vertical pole to relax fabric fibers and remove wrinkles without mechanical pressing. The primary commercial purpose spans residential garment care, hospitality linen preparation, and salon textile finishing where speed and fabric preservation outweigh traditional ironing throughput. Handheld units lead volume shipments across urban households in China and India, while standing and commercial-grade systems command higher margin pools in hotel and salon procurement channels. The 1500W power rating segment dominates mainstream residential sales, though above-2000W commercial systems represent the fastest-growing category as boutique hotels upgrade back-of-house equipment.
Japan's METI enforces stringent electrical appliance safety standards under the Electrical Appliance and Material Safety Law, requiring thermal cutoff mechanisms and insulation testing for all steam-generating devices sold domestically. China's SAMR monitors product quality through national GB standards for household electrical heaters, while India's BIS mandates ISI certification for heating appliances sold through formal retail channels, effectively filtering out unbranded imports. Stakeholders must monitor how evolving energy-efficiency benchmarks across these three regulatory regimes reshape product design roadmaps and factory certification costs.
Market Dynamics
Housekeeping efficiency mandates across Southeast Asian luxury hotels are compressing linen preparation windows, forcing procurement departments to specify rapid-recovery garment steamers with sub-60-second heat-up cycles. This operational pressure cascades through manufacturing roadmaps as thermal engineering specifications tighten.
Growth Catalysts
- India's BIS certification expansion:Mandatory ISI marking for electrical heating appliances is filtering unbranded imports from formal retail channels, creating shelf space for certified manufacturers.
- Hotel procurement standardization:Southeast Asian hospitality groups are consolidating supplier lists around equipment vendors offering fleet-wide maintenance contracts and rapid parts availability.
- 1500W handheld unit penetration:Compact residential systems with ceramic heating elements are displacing traditional irons in Chinese tier-one city apartments where storage space constrains appliance selection.
Market Restraints
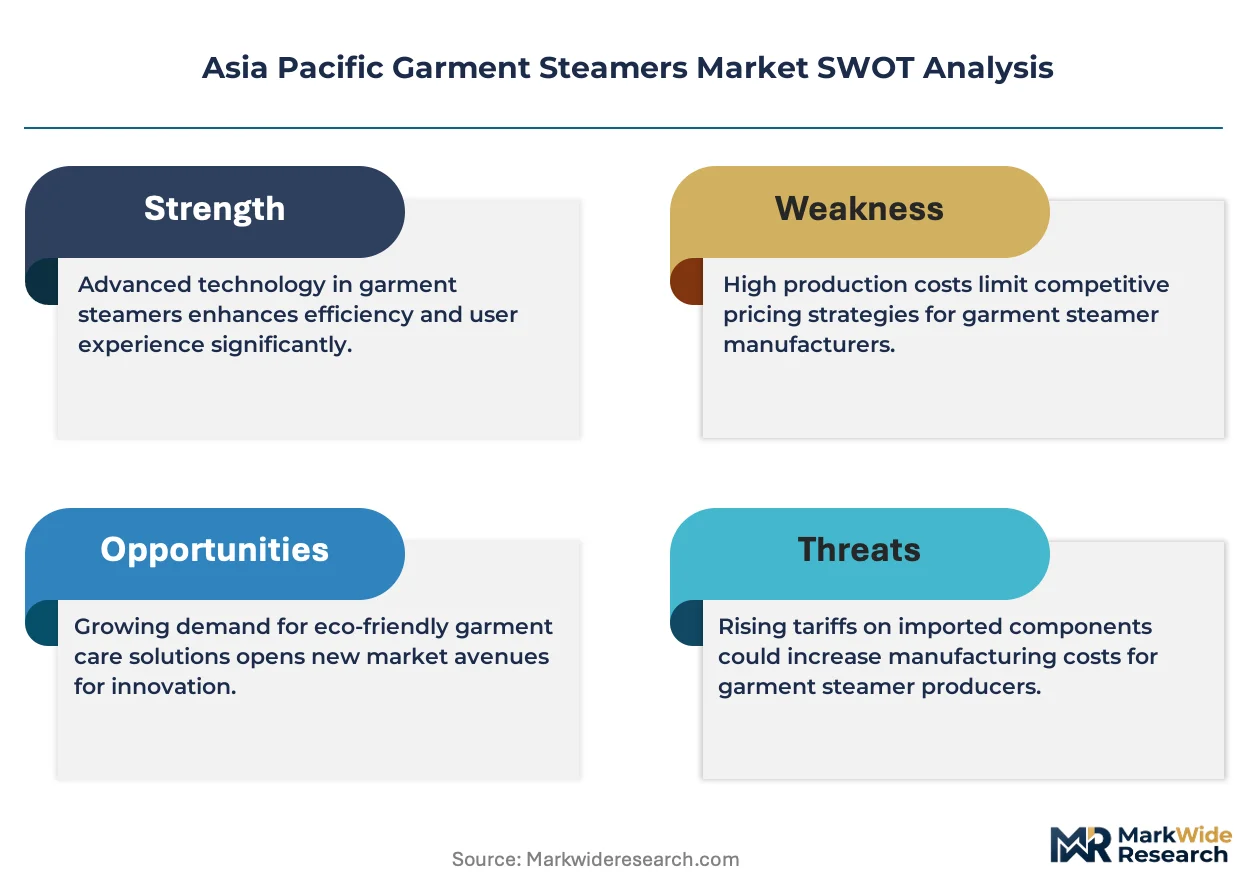
- Copper coil supply concentration:Heating element production clusters in Guangdong province, exposing manufacturers to regional logistics disruptions and input price volatility.
- Japan's METI thermal safety enforcement:The Electrical Appliance and Material Safety Law mandates redundant cutoff mechanisms that extend product development timelines and certification costs.
- Steam iron substitution:Conventional pressing equipment retains cost advantages in price-sensitive Indian and Indonesian residential segments.
Strategic Opportunities
- Vietnam hospitality buildout:Boutique hotel construction in Da Nang and Phu Quoc is generating demand for commercial-grade standing steamers with continuous-fill water systems.
- China's dual carbon goals:Provincial energy-efficiency rebates for household appliances are steering R&D toward variable-wattage heating elements that modulate power draw.
- IoT-enabled predictive maintenance:Connected sensors monitoring heating coil degradation are enabling subscription-based service models for hospitality fleet operators.
Industry Challenges
- Cross-border certification parallelism:Manufacturers must simultaneously navigate BIS testing in India, GB standard compliance in China, and METI filings in Japan, fragmenting quality assurance resources.
- Descaling chemistry compatibility:Regional water hardness variation requires formulation adjustments for maintenance kits, complicating aftermarket inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Garment Steamers Market |
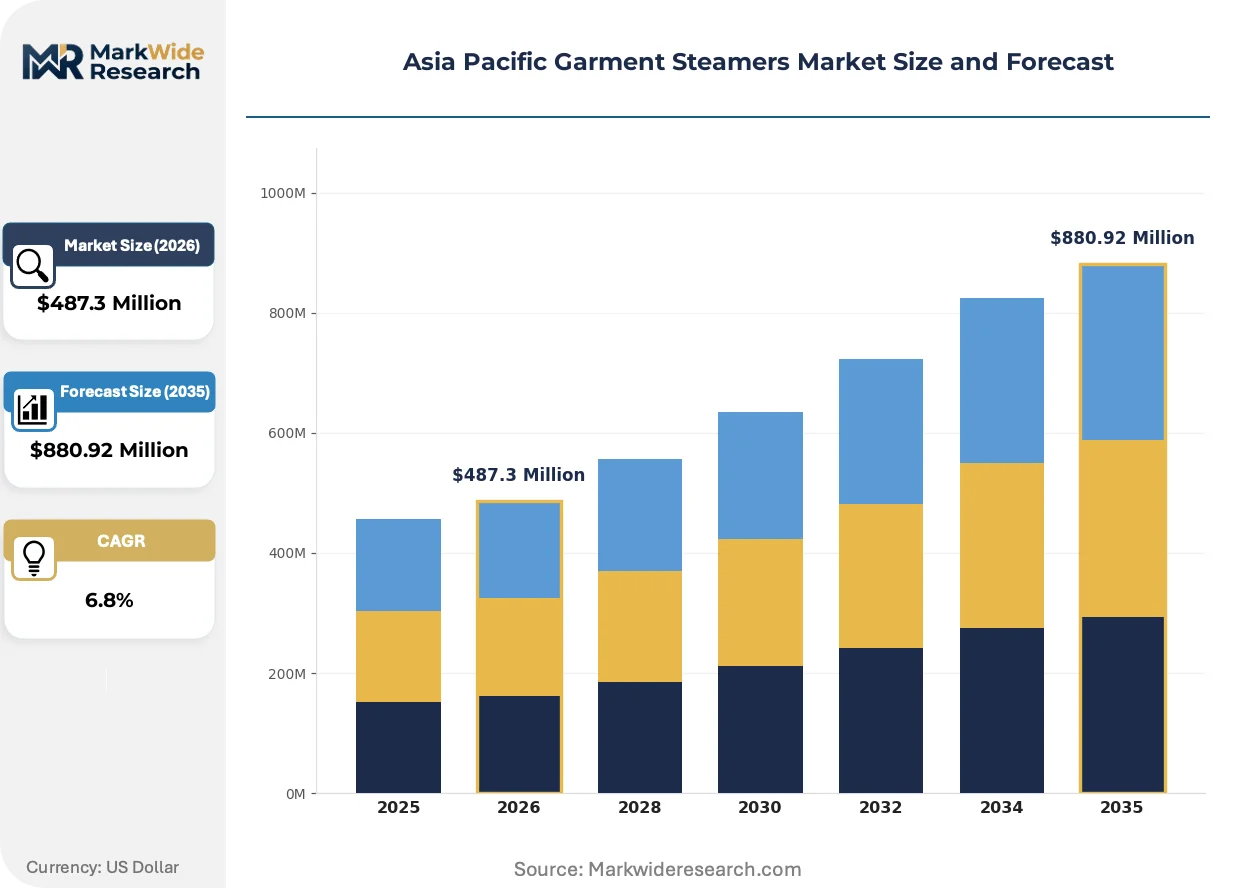
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Standing, Commercial, Multi-Functional End User: Households, Salons, Hotels, Retail Stores Technology: Vertical, Horizontal, Automatic, Portable Power Rating: 900W, 1500W, 1800W, Above 2000W |
| Companies Covered | Koninklijke Philips N.V., Panasonic Corporation, Haier Group Corporation, Groupe SEB, Conair Corporation, Reliable Corporation, Midea Group, Jiffy Steamer Company, SALAV USA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Garment Steamers Market Trends and Innovations
Product engineering across Asia Pacific garment steamers is converging on thermal precision and connectivity, with manufacturers racing to integrate smart diagnostics while regulatory bodies tighten energy and safety benchmarks.
Microprocessor-controlled heating elements with PID temperature regulation are digitizing thermal management in premium handheld units. Boutique hotels in Bangkok and Singapore are specifying these systems for guest room deployment, valuing the elimination of temperature overshoot that damages delicate fabrics. This precision engineering is compressing warranty claim rates and shifting supplier selection criteria toward firmware capability.
China's SAMR is intensifying GB standard enforcement for household electrical heaters, requiring documented thermal runaway testing and insulation resistance verification. Factory audit frequency has doubled in Guangdong manufacturing zones, with non-compliant production lines facing suspension until corrective action completion. Exporters targeting multiple Asia Pacific jurisdictions are consolidating test protocols to reduce redundant certification expenditure.
Salon textile finishing operations in Seoul and Tokyo are unbundling equipment procurement from maintenance contracts, treating garment steamers as depreciating assets with defined service lifecycles. Independent service networks are capturing replacement tank and heating element revenue that manufacturer channels previously dominated. This disintermediation is most pronounced in South Korea's fragmented beauty salon segment, where owner-operators prioritize parts availability over brand loyalty.
Asia Pacific Garment Steamers Market Segmentation
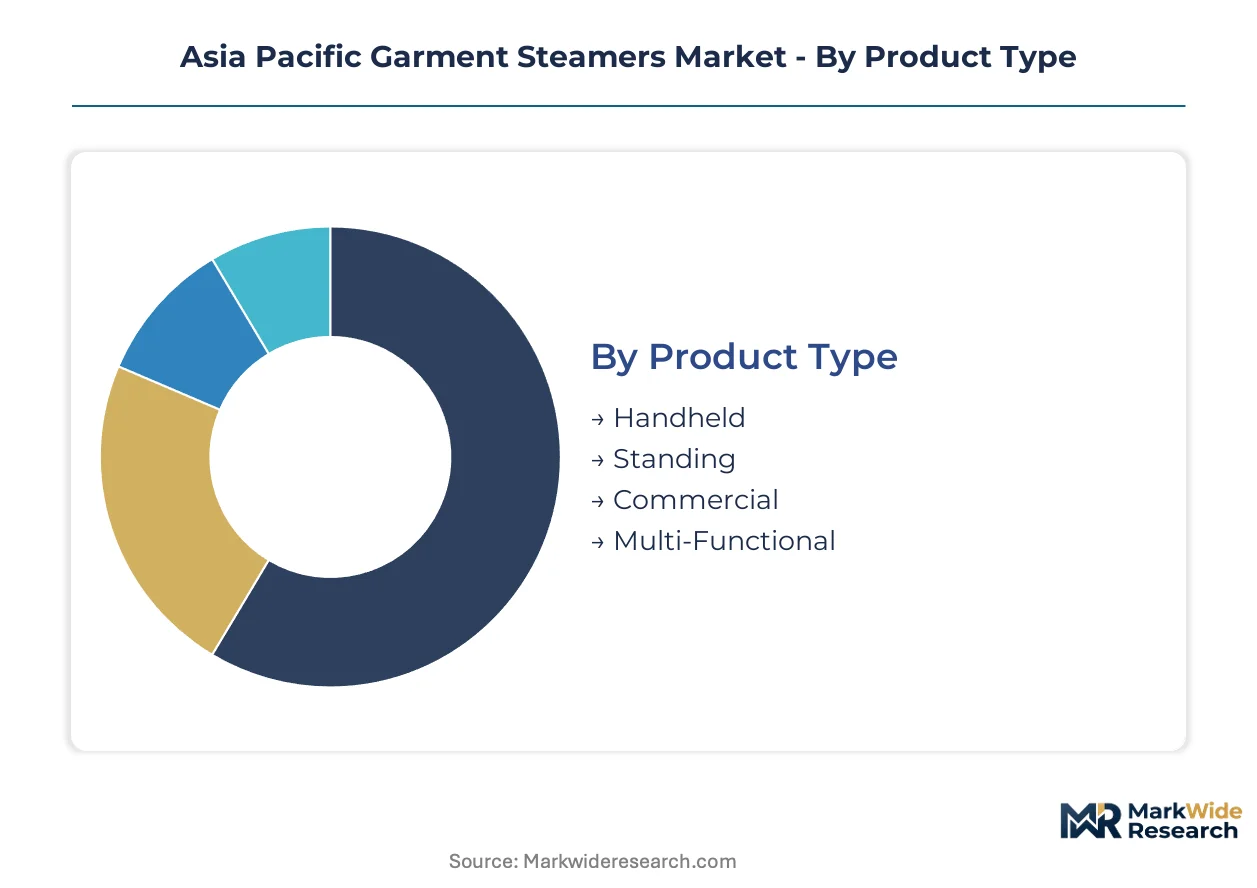
Garment steamer purchasing decisions across Asia Pacific diverge sharply across use contexts, from space-constrained urban apartments to high-throughput hospitality operations. Segmentation reveals how thermal engineering specifications, physical form factors, and power requirements map to distinct procurement budgets and replacement cycles.
Product Type:
Physical form factor determines installation footprint, water reservoir capacity, and steam pressure output across residential and commercial deployments.
- Handheld:Compact units with integrated water tanks and ceramic heating elements deliver 100-120°C steam through pistol-grip nozzles. Demand clusters in Shanghai, Beijing, and Shenzhen apartments where storage space is measured in centimeters, with rapid 30-second heat-up cycles displacing traditional irons in premium residential segments.
- Standing:Vertical pole systems with separate base-mounted boilers generate sustained high-volume steam for batch garment processing. Boutique hotels across Bangkok and Singapore specify these for back-of-house linen preparation, valuing continuous-fill water systems that eliminate operator downtime during peak housekeeping windows.
- Commercial:Industrial-grade pressure vessels with brass heating elements serve high-throughput textile finishing operations in Seoul garment districts and Osaka salon chains.
- Multi-Functional:Hybrid units incorporating steam cleaning and sanitization capabilities target Japanese households with dual-use appliance preferences under METI energy-efficiency benchmarks.
Handheld units command the established base. The steepest expansion runs through commercial systems as Vietnam's hospitality buildout accelerates.
End User:
Customer type segmentation isolates procurement authority structures, replacement frequency, and sensitivity to total cost of ownership versus upfront capital expenditure.
- Households:Individual purchasers prioritize compact footprint and sub-60-second heat-up cycles for daily garment care in dense urban environments.
- Salons:Beauty and textile finishing operations in Seoul and Tokyo treat steamers as depreciating assets with defined 3-5 year replacement cycles, driving demand for maintenance contracts and parts availability.
- Hotels:Southeast Asian luxury hospitality groups are consolidating supplier lists around vendors offering fleet-wide service agreements, with housekeeping efficiency mandates compressing linen preparation windows and specifying rapid-recovery thermal systems.
- Retail Stores:Apparel merchandising teams in Mumbai and Jakarta deploy steamers for floor-ready presentation, prioritizing portability between display zones over boiler capacity.
Households anchor volume shipments. Hotels deliver the steepest margin expansion as procurement standardization consolidates vendor relationships.
Technology:
Steam delivery orientation and automation level differentiate product architectures across precision fabric care and operator efficiency requirements.
- Vertical:Upright steaming configurations with gravity-fed water delivery dominate residential and hospitality applications where garment hanging space is available.
- Horizontal:Flat-surface steaming systems with pressurized delivery accommodate tailored suiting and delicate textiles in premium salon segments across Tokyo and Osaka.
- Automatic:Microprocessor-controlled units with PID temperature regulation and moisture sensors are gaining traction in Bangkok and Singapore boutique hotels, eliminating temperature overshoot that damages silk and linen.
- Portable:Battery-capable or dual-voltage systems target cross-border travelers and mobile service providers in Australia's dispersed regional markets.
Vertical systems hold the installed base. Automatic configurations are climbing fastest as firmware capability shifts supplier selection criteria.
Power Rating:
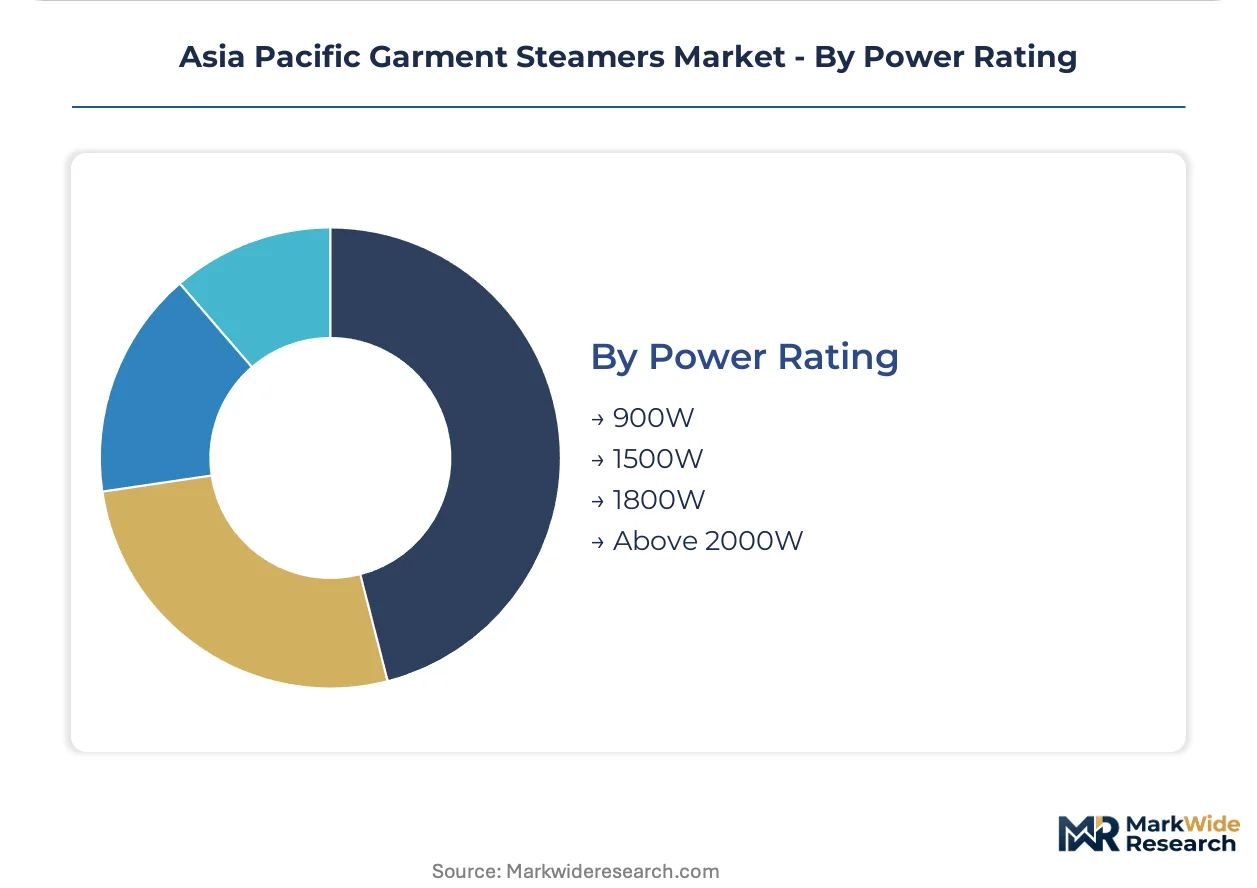
Wattage segmentation maps directly to thermal recovery speed, steam volume output, and compatibility with residential electrical infrastructure across varying grid standards.
- 900W:Entry-level residential units with aluminum heating elements serve price-sensitive Indian and Indonesian households where steam iron substitution remains a competitive threat.
- 1500W:Mainstream ceramic-element systems balance heat-up speed against circuit breaker compatibility in Chinese tier-one city apartments, representing the dominant configuration for urban household penetration.
- 1800W:Mid-tier commercial units bridge residential hospitality applications in South Korea and Taiwan, offering faster recovery without requiring dedicated electrical infrastructure.
- Above 2000W:High-capacity brass-element boilers deliver continuous steam for commercial batch processing. Boutique hotels across Da Nang and Phu Quoc are specifying these systems as housekeeping efficiency mandates tighten, with above-2000W configurations representing the most rapid demand acceleration across the analysis window.
1500W systems anchor mainstream residential sales. Above-2000W commercial systems are expanding most quickly as hospitality procurement upgrades accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across Asia Pacific garment steamer procurement. Indian and Indonesian households prioritize sub-900W entry units, while Southeast Asian luxury hotels absorb premium commercial systems without volume sensitivity.
China
Tier-one city apartment dwellers drive handheld 1500W ceramic-element penetration where storage constraints favor compact footprints. SAMR intensifies GB standard enforcement for household electrical heaters, doubling factory audit frequency in Guangdong manufacturing zones. Shenzhen and Shanghai clusters concentrate microprocessor-controlled heating element production for PID-regulated premium units.
Japan
Dual-use appliance preferences under METI energy-efficiency benchmarks sustain multi-functional hybrid demand combining steam cleaning with garment care. The Electrical Appliance and Material Safety Law mandates redundant thermal cutoff mechanisms that extend certification timelines. Osaka and Tokyo salon chains treat steamers as depreciating assets with defined 3-5 year replacement cycles.
India
Price-sensitive residential segments retain steam iron substitution risk at the entry level, though BIS ISI certification mandates are filtering unbranded imports from formal retail. Mandatory marking requirements for electrical heating appliances create shelf space for certified manufacturers. Mumbai and Delhi-NCR retail stores deploy portable units for floor-ready apparel presentation between display zones.
Vietnam
Boutique hotel construction in Da Nang and Phu Quoc generates commercial-grade standing steamer demand with continuous-fill water systems. Housekeeping efficiency mandates compress linen preparation windows, specifying above-2000W rapid-recovery thermal systems. Hospitality procurement consolidation favors vendors offering fleet-wide maintenance contracts and rapid parts availability.
South Korea
Fragmented beauty salon owner-operators prioritize parts availability over brand loyalty, enabling independent service networks to capture replacement tank and heating element revenue. Seoul textile finishing operations unbundle equipment procurement from maintenance contracts. Automatic microprocessor-controlled configurations with moisture sensors gain traction for silk and linen precision care.
Asia Pacific Garment Steamers Market Competitive Landscape
Diversified appliance conglomerates and specialized thermal equipment fabricators split the market across distinct capability vectors. Consolidation pressure concentrates around manufacturing scale in Guangdong province and established service infrastructure across Japan and Southeast Asia. Three archetypes dominate: integrated heating coil producers, multi-category appliance platforms with captive distribution, and precision thermal engineering specialists. Competitive moves center on backward integration into heating element supply and subscription-based fleet maintenance contracting for hospitality operators.
Among diversified appliance platforms, Panasonic Corporation and Haier Group anchor distinct strategic positions, while Midea Group occupies a scale-driven manufacturing posture in Guangdong province. Panasonic exemplifies the service-integrated archetype through established appliance infrastructure spanning Japan and Southeast Asia. Haier represents supply chain control through integrated heating coil production. Midea sits within the high-volume ceramic-element fabrication tier competing on manufacturing throughput.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Panasonic Corporation |
| Haier Group Corporation |
| Groupe SEB |
| Conair Corporation |
| Reliable Corporation |
| Midea Group |
| Jiffy Steamer Company |
| SALAV USA |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Ningbo port freight corridors transmit Guangdong manufacturing cost volatility directly into landed pricing across Southeast Asian hospitality procurement, compressing margins for distributors while enabling certified manufacturers to command premium positioning through thermal safety documentation.
Pricing Analysis
Aftermarket service revenue from replacement tanks, heating elements, and descaling kits drives lifetime value capture across the installed base. Pricing stratifies across premium automatic units with PID regulation, standard 1500W ceramic-element systems, and economy 900W aluminum models. Cost compression in entry-tier handheld units is intensifying as unbranded imports compete on raw wattage specifications. Indian residential segments exhibit highest price sensitivity, while Vietnamese luxury hotel procurement absorbs premium commercial systems without volume negotiation.
Supply Chain Analysis
Contract manufacturing capacity concentrates in Guangdong province OEM clusters and selected Taiwanese electronics fabricators with thermal appliance experience. Heating coil production draws from Chinese copper processing, Japanese ceramic substrate supply, and South Korean microprocessor sourcing. Single-source vulnerability runs through Guangdong heating element concentration exposed to regional logistics disruption. Distribution runs through authorized service networks in Japan, fragmented independent repair channels in South Korea, and consolidated hospitality fleet contractors across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific garment steamers constitute a high-growth disruption as BIS certification mandates and METI thermal safety enforcement simultaneously filter unbranded competition and elevate engineering barriers to entry.
For Market Incumbents: Pre-empt margin erosion from independent service networks by capturing replacement parts revenue through subscription-based fleet maintenance contracts for hospitality operators. Anchor backward integration into heating coil production to secure input cost stability against Guangdong copper price volatility. Fortify certification compliance teams to navigate parallel BIS, SAMR, and METI filing requirements without product launch delays. For New Entrants and Emerging Players: Pursue white-space opportunity in Vietnam's boutique hotel buildout where above-2000W commercial system demand outpaces established vendor service infrastructure. Target Da Nang and Phu Quoc hospitality procurement with rapid parts availability guarantees that incumbent fleet contractors cannot match. Lead with continuous-fill water system specifications that compress housekeeping preparation windows. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified appliance conglomerates seeking to divest non-core thermal equipment divisions with stranded heating element production assets. Long-term viability hinges on firmware capability for PID regulation and IoT-enabled predictive maintenance subscription models. Monitor BIS certification expansion pace as the inflection signal for formal retail channel shelf space reallocation toward certified manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Coil Production | Haier Group's captive supply of ceramic elements insulates margin from Guangdong copper volatility. |
| IoT-Enabled Predictive Maintenance Launch | Connected sensors monitoring coil degradation enable recurring revenue from Bangkok hotel fleet operators. |
| BIS Certification Fast-Track Investment | ISI marking compliance filters unbranded competition from Indian formal retail channels. |
| Vietnam Hospitality Fleet Contracting | Da Nang boutique hotel procurement consolidates around vendors with rapid parts availability. |
| Multi-Functional Hybrid Product Extension | METI energy-efficiency benchmarks in Japan sustain dual-use appliance demand combining steam cleaning with garment care. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with appliance manufacturing executives, hospitality procurement directors, and aftermarket service network operators; and secondary validation through SAMR GB standard filings, BIS certification registries, METI safety compliance databases, and customs trade records for heating element imports. Bottom-up shipment estimates by power rating and product type triangulated against top-down hospitality capital expenditure surveys and residential appliance retail audits.
Forecast inputs span product type segmentation across handheld, standing, commercial, and multi-functional configurations; end-user categories from households through hotels; technology tiers including vertical, horizontal, automatic, and portable systems; and power rating bands from 900W through above-2000W. CAGRs derive from elasticity modeling against household formation rates, hospitality construction permits, and regulatory compliance cost trajectories. Energy-efficiency rebate programs under China's dual carbon goals and India's BIS expansion timeline anchored scenario-weighted projections across the analysis window.
Macroeconomic conditions sit as an overlay; deviation in copper commodity pricing, regional logistics costs, or currency volatility across RMB, JPY, INR, and VND would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline stability and hospitality procurement standardization pace. Quarterly review of BIS enforcement intensity, SAMR factory audit suspension notices, and Vietnam hospitality construction permit issuance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Zipper Market
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
China Denim Jeans Market
Apparel Textiles
Bamboo Apparel Market
Apparel Textiles
South America Lingerie Market
Apparel Textiles
Waterproof Fabrics for Sports Apparel Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
Rain Apparel Market
Apparel Textiles
School Uniform Market
Apparel Textiles
Sweat Resistant Apparel Market
Apparel Textiles
Japan Denim Jeans Market
Apparel Textiles
Embroidery Market
Apparel Textiles
Global Prom Dresses Market
Apparel Textiles
Maternity Wear Market
Apparel Textiles
Bridal Gowns Market
Apparel Textiles
Welding Apparels Market