
 Asia-Pacific Flat Glass Coating Market | 2026-2036
Asia-Pacific Flat Glass Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Flat Glass Coating Market Analytics
China's GB standards for building energy efficiency is rebalancing the cost-of-entry calculus for flat glass coating producers seeking commercial project approvals. Saint-Gobain leverages its European technical heritage to anchor premium low-E coating supply across Chinese megaprojects. Fuyao Group sustains dominant automotive glazing relationships with both domestic EV builders and multinational OEMs. AGC Inc. differentiates through advanced sputtering technology leadership in solar control coatings.
Asia-Pacific flat glass coating encompasses thin-film depositions applied to soda-lime silica substrates, typically achieving emissivity below 0.15 through silver-based multi-layer stacks in magnetron sputtering lines, primarily to manage thermal radiation transmission in enclosed structures. Low-E coatings command the largest value pool across the region as mandatory green building codes spread, while anti-reflective coatings for photovoltaic panels represent the fastest-expanding segment amid utility-scale solar ramp-ups. Sol-gel technology occupies a specialized niche in electronics display protection, whereas PVD processes dominate architectural volume production due to throughput scalability.
China's MEE enforces industrial emission thresholds that filter out smaller coating operations without gas abatement infrastructure, while India's BIS certification mandates thermal performance disclosure for imported coated glass products. Japan's METI directs building retrofit subsidies toward high-performance glazing, tightening specification standards across its domestic supply chain. Stakeholders must monitor how ASEAN harmonization of energy-efficiency labeling reshapes cross-border procurement rules and factory location decisions.
Market Dynamics
China's GB 50189 building energy efficiency standards are forcing architectural glass specification upgrades across commercial construction, compressing the window for non-compliant coating technologies while expanding certified low-E capacity requirements.
Growth Catalysts
- MEE emission thresholds:China's Ministry of Ecology and Environment filters out smaller coating operations lacking gas abatement infrastructure, consolidating demand toward compliant producers with magnetron sputtering scale.
- Utility-scale solar ramp-ups:Southeast Asian photovoltaic installations accelerate anti-reflective coated glass procurement for module efficiency gains.
- METI retrofit subsidies:Japan's Ministry of Economy, Trade and Industry directs building renovation funding toward high-performance glazing, tightening domestic supply chain specifications.
Market Restraints
- Silver price volatility:Low-E coating stacks depend on silver multi-layer deposition, exposing margin structures to precious metal commodity swings.
- Sputtering equipment concentration:Magnetron sputtering line supply concentrates among German and Japanese capital equipment builders, creating capex bottlenecks for new entrants.
- BIS certification friction:India's Bureau of Indian Standards mandates thermal performance disclosure for imported coated glass, extending approval timelines for foreign suppliers.
Strategic Opportunities
- Indonesia commercial corridors:Jakarta and Surabaya construction activity outpaces domestic coating capacity, creating import substitution openings for regional producers.
- Electronics display protection:Sol-gel coating applications for smartphone and tablet cover glass represent an emerging specialty segment beyond architectural volume.
- ASEAN harmonization:Cross-border energy-efficiency labeling alignment is reshaping procurement rules, favoring producers with multi-country certification capabilities.
Industry Challenges
- Sputtering technician scarcity:Magnetron process optimization requires specialized vacuum deposition expertise that outpaces regional vocational training output.
- Dual certification timelines:Simultaneous GB standard compliance in China and JIS alignment for Japan extends product qualification cycles for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Flat Glass Coating Market |
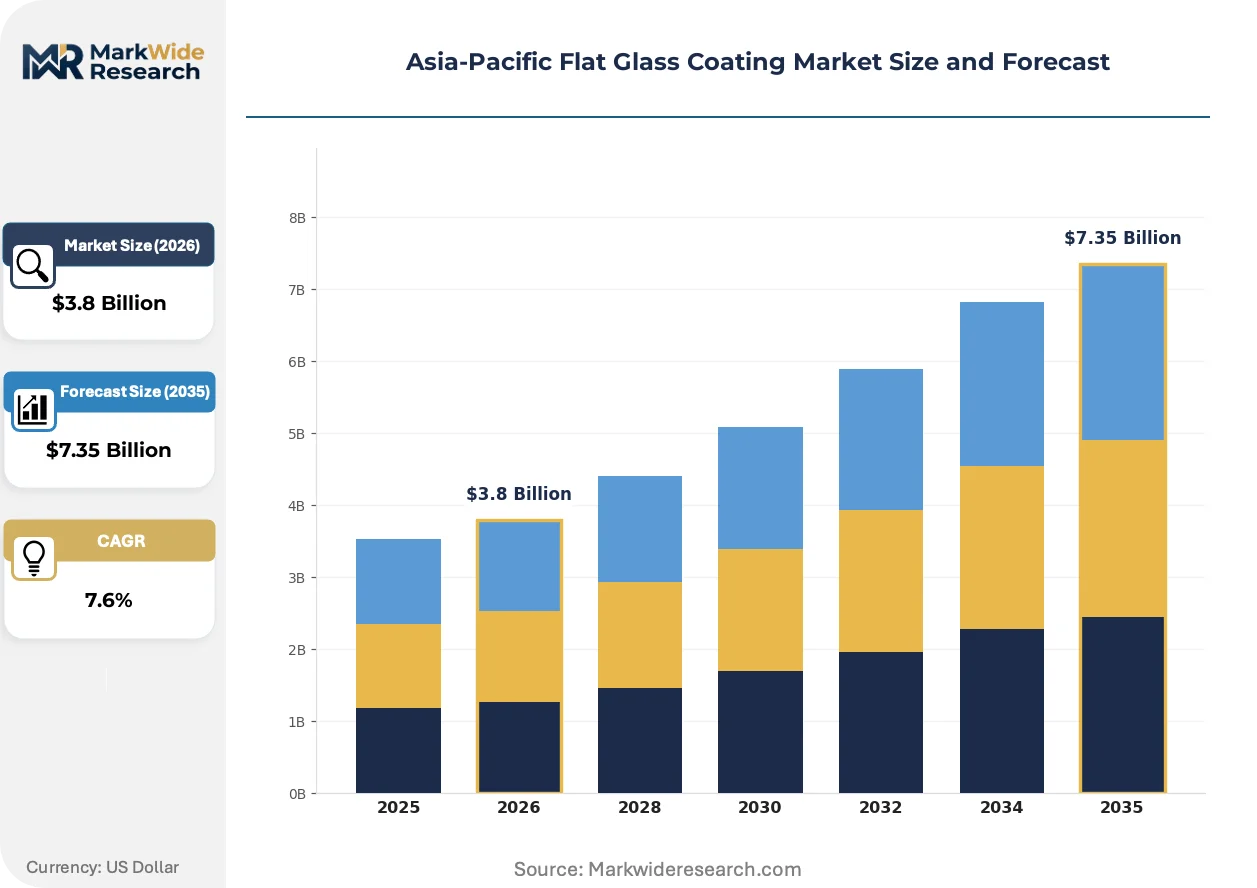
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-E Coatings, Anti-Reflective Coatings, Specialty Coatings, Solar Control Coatings Application: Automotive, Architectural, Solar Energy, Electronics Technology: PVD, CVD, Sol-Gel, Screen Printing End User: OEMs, Construction Companies, Electronics Manufacturers, Renewable Energy Firms |
| Companies Covered | Saint-Gobain, Fuyao Group, AGC Inc., Jinjing (Group) Co., Ltd., KIBING GROUP, Xinyi Glass Holdings Co. Ltd., China Glass Holdings Limited, Guardian Industries, Nippon Sheet Glass Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Flat Glass Coating Market Evolving Landscape
Coating technology architecture is fragmenting from monolithic production lines toward configurable deposition platforms, enabling faster product changeovers and smaller batch economics for specialized applications.
Magnetron sputtering hardware is modularizing from fixed-configuration lines into swappable cathode arrays and chamber segments. Regional architectural glass producers in Thailand and Vietnam are adopting these reconfigurable systems to alternate between solar-control and low-E recipes within single shifts. This flexibility is compressing minimum efficient scale thresholds and enabling mid-volume players to serve project-specific coating specifications without dedicated plant investments.
China's evolving GB 50189 standard suite is tightening thermal transmittance coefficients for commercial building envelopes. The regulation is forcing glazing contractors to source double-silver and triple-silver low-E configurations that exceed legacy single-layer performance. High-rise developments in Shanghai and Shenzhen are responding by consolidating procurement around certified coating houses with documented emissivity testing protocols.
Building developers are compressing supplier qualification cycles from multi-year framework agreements toward project-specific coating performance bonds. General contractors in India's Delhi-NCR corridor are displacing traditional annual supply contracts with milestone-based acceptance criteria tied to installed U-value verification. This shift is most visible in commercial tower developments where glazing subcontractor selection now hinges on rapid sample turnaround rather than historical relationship tenure.
Asia-Pacific Flat Glass Coating Market Segmentation
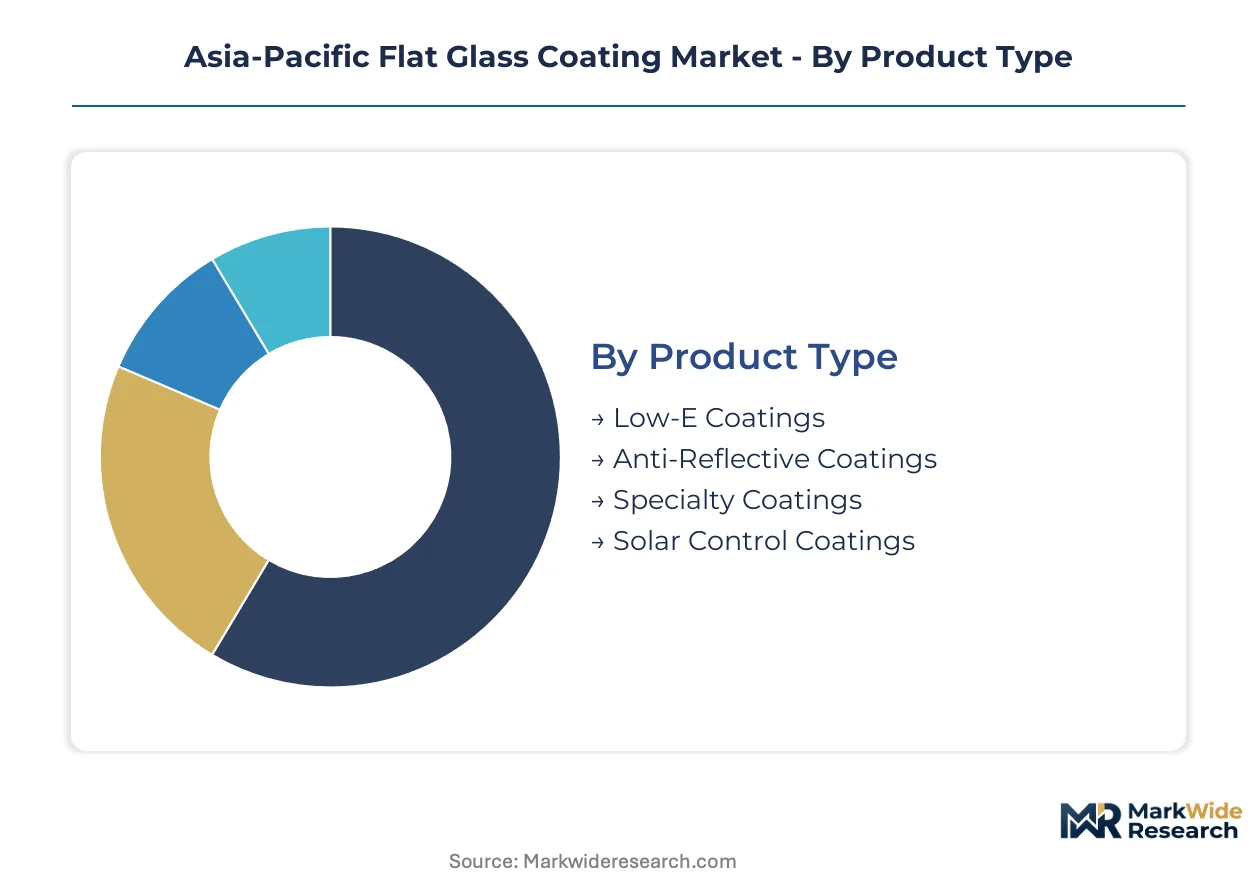
Flat glass coating segmentation reveals how specification requirements diverge across thermal performance, optical clarity, and durability demands. Each category carries distinct certification burdens and capital intensity thresholds that reshape procurement patterns across the Asia-Pacific region.
Product Type:
Replacement cycles for glazing systems are shortening as building codes tighten thermal performance baselines, forcing asset owners to reassess coating upgrade economics.
- Low-E Coatings:Silver-based multi-layer stacks deposited via magnetron sputtering achieve emissivity below 0.15. Procurement concentrates in China's commercial high-rise developments around Shanghai and Shenzhen where GB 50189 compliance is mandatory.
- Anti-Reflective Coatings:Nanostructured surface treatments reduce reflection losses to under 2% across visible wavelengths. Demand clusters in Southeast Asian utility-scale solar installations where module efficiency gains justify premium glass costs.
- Specialty Coatings:Scratch-resistant and hydrophobic formulations serve niche automotive and display applications with exacting durability specifications.
- Solar Control Coatings:Spectrally selective layers manage solar heat gain coefficients for tropical climates without sacrificing daylight transmission.
Volume placements concentrate in Low-E Coatings; the faster expansion belongs to Anti-Reflective Coatings.
Application:
Cost tier differentiation separates specification-grade architectural projects from volume automotive supply contracts.
- Architectural:Curtain wall and fenestration systems require certified thermal performance documentation for green building ratings. Procurement in India's Delhi-NCR and Mumbai corridors is shifting toward project-specific performance bonds rather than annual frameworks.
- Automotive:Windshield and side-light glazing demands optical clarity combined with head-up display compatibility. Fuyao Group and AGC Inc. dominate supply relationships with domestic EV builders and multinational OEMs across China and Japan.
- Solar Energy:Photovoltaic module cover glass requires anti-reflective and anti-soiling surface treatments to maintain output in high-humidity environments.
- Electronics:Smartphone and tablet cover glass uses sol-gel hard coatings for scratch resistance and oleophobic properties.
Architectural commands the largest value pool; Solar Energy is climbing the fastest as Southeast Asian capacity additions accelerate.
Technology:
Application type dictates process selection between high-throughput architectural volume and precision electronics batch production.
- PVD:Magnetron sputtering dominates low-E and solar control coating production with deposition rates exceeding 200 nm-meters per minute on float glass lines.
- CVD:Atmospheric and low-pressure chemical vapor deposition serves pyrolytic hard coatings for automotive glazing with integrated heating functions.
- Sol-Gel:Dip and spray processes enable thin silica-titania layers for electronics display protection at lower capital intensity than vacuum methods.
- Screen Printing:Ceramic frit deposition for spandrel and decorative applications in commercial facades.
PVD holds the dominant share; Sol-Gel is expanding most quickly in electronics specialty applications.
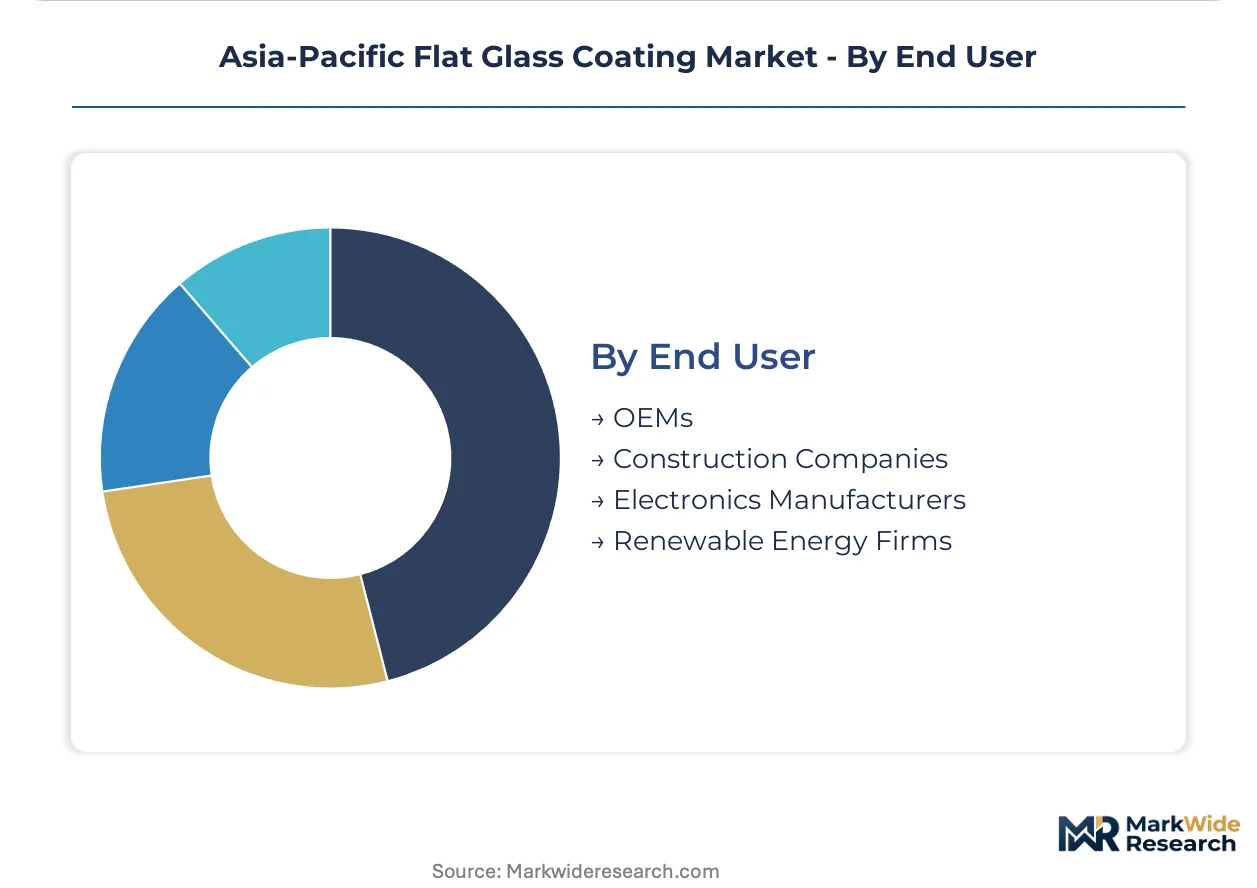
End User:
Customer type determines contract structure, with OEMs demanding longest-term supply security and construction companies accepting project-specific terms.
- Construction Companies:General contractors in Jakarta and Surabaya are consolidating procurement around coating houses with rapid sample turnaround and installed U-value verification capabilities.
- OEMs:Automotive and electronics manufacturers require statistical process control documentation and line-side delivery synchronization.
- Renewable Energy Firms:Solar developers in Vietnam and Thailand specify anti-reflective coated glass with performance warranties tied to module output degradation rates.
- Electronics Manufacturers:Display panel producers in South Korea and Taiwan source cover glass with nanometer-scale thickness uniformity for touch sensor integration.
Construction Companies generate the heaviest volume flow; Renewable Energy Firms are gaining share fastest as solar procurement scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate magnetron sputtering capacity for low-E glass exports. Vietnam's coastal industrial parks attract coating equipment relocation from maturing Chinese manufacturing bases. Indonesia's new capital development zone drives procurement consolidation among Jakarta-based glazing contractors.
China
Commercial high-rise construction in Shanghai and Shenzhen mandates GB 50189-compliant double-silver low-E configurations. The Ministry of Ecology and Environment filters non-compliant coating operations without gas abatement infrastructure. Yangtze River Delta float glass corridors anchor certified low-E capacity serving domestic megaprojects and Southeast Asian export demand.
Japan
Building retrofit subsidies from METI redirect renovation funding toward high-performance glazing specifications. JIS alignment requirements extend product qualification cycles for multi-market suppliers. Kanto region glazing contractors consolidate procurement around documented emissivity testing protocols for commercial tower developments.
India
Delhi-NCR and Mumbai commercial construction corridors shift procurement toward project-specific performance bonds. BIS certification mandates thermal performance disclosure for imported coated glass products. General contractors displace traditional annual supply contracts with milestone-based acceptance criteria tied to installed U-value verification.
Vietnam
Utility-scale solar installations accelerate anti-reflective coated glass procurement for module efficiency gains. Coastal industrial parks attract magnetron sputtering equipment relocation from maturing Chinese manufacturing bases. Ho Chi Minh City glazing subcontractors specify rapid sample turnaround capabilities from regional coating houses.
Indonesia
Jakarta and Surabaya construction activity outpaces domestic coating capacity, creating import substitution openings. The new capital development zone in East Kalimantan drives procurement consolidation among national glazing contractors. Commercial tower developers specify coating houses with multi-country certification capabilities for ASEAN cross-border projects.
Asia-Pacific Flat Glass Coating Market Competitive Landscape
Chinese producers anchor volume-tier supply; Japanese and European specialists hold premium coating technology positions. The vendor base fragments across magnetron sputtering scale players, sol-gel electronics specialists, and regional automotive glazing integrators. Three archetypes dominate: certified low-E houses with GB compliance documentation, automotive glazing partners with OEM line-side synchronization, and solar-control specialists serving tropical climate specifications. Competitive moves concentrate on modular sputtering equipment adoption and multi-country certification stacking.
Within the certified architectural tier, Saint-Gobain and AGC Inc. exemplify premium low-E supply positions anchored by technical heritage and sputtering technology leadership. Fuyao Group occupies a distinct automotive glazing archetype, sustaining dominant relationships with domestic EV builders and multinational OEMs across the region. These three companies represent the strategic spectrum from European technical heritage deployment to Chinese-scale automotive integration and Japanese advanced coating process leadership.
| Leading Market Players |
|---|
| Saint-Gobain |
| Fuyao Group |
| AGC Inc. |
| Jinjing (Group) Co., Ltd. |
| KIBING GROUP |
| Xinyi Glass Holdings Co. Ltd. |
| China Glass Holdings Limited |
| Guardian Industries |
| Nippon Sheet Glass Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Silver bullion costs cascade through magnetron sputtering lines into three-tier pricing structure across premium, standard, and economy levels, with double-silver low-E configurations commanding spreads over single-layer alternatives as China's GB 50189 compliance deadlines compress procurement windows for glazing contractors in Shanghai and Shenzhen.
Pricing Analysis
Short lead-time premiums of 15-20% apply to certified low-E coating houses with documented emissivity testing protocols and rapid sample turnaround capabilities. Project-based pricing dominates architectural procurement, with general contractors in India's Delhi-NCR corridor displacing annual frameworks for milestone-based acceptance criteria tied to installed U-value verification. Cost compression in economy-tier supply is intensifying because smaller coating operations lacking gas abatement infrastructure face MEE emission threshold exclusions. Renewable energy firms exhibit highest price sensitivity due to module cost pressures, while premium automotive OEMs prioritize optical clarity over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle automotive glazing demand from Fuyao Group and AGC Inc., while project-specific coating performance bonds flow through glazing subcontractors to construction developers. Magnetron sputtering equipment concentrates in China, Japan, and Germany, with raw material dependencies on silver cathodes, argon process gas, and soda-lime silica float glass. Single-source vulnerability rests on German and Japanese capital equipment builders creating capex bottlenecks for new entrants. Distribution runs through certified coating houses with multi-country certification capabilities for ASEAN cross-border procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as MEE emission thresholds filter out smaller coating operations without gas abatement infrastructure, forcing acquisition-driven exits among sub-scale regional players.
For Market Incumbents: To counter modular sputtering equipment adoption by mid-volume Thai and Vietnamese competitors, Saint-Gobain and AGC Inc. should deepen backward integration into silver cathode supply and accelerate capacity addition in Indonesia's new capital development zone to capture import substitution demand from Jakarta-based glazing contractors. For New Entrants and Emerging Players: Launch via project-specific performance bond offerings targeting Indonesia's Surabaya commercial corridor where domestic coating capacity lags construction activity. The most penetrable white space sits in sol-gel electronics display protection for South Korean and Taiwanese smartphone manufacturers, with go-to-market anchored by nanometer-scale thickness uniformity guarantees for touch sensor integration. For Investors and Strategic Acquirers: ASEAN harmonization of energy-efficiency labeling is the leading indicator that multi-country certification capabilities will separate viable acquisition targets from stranded assets. The 5-10 year viability window favors certified low-E houses with GB compliance documentation and documented emissivity testing protocols. Monitor BIS certification timeline extensions for foreign suppliers as an early signal of import substitution opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Sputtering Equipment Adoption | Thai and Vietnamese producers gain shift-flexibility between solar-control and low-E recipes. |
| Backward Integration into Silver Supply | Coating houses hedge precious metal commodity exposure affecting margin structures. |
| Multi-Country Certification Stacking | Producers capture ASEAN cross-border procurement as labeling harmonization advances. |
| Project-Specific Performance Bonds | Glazing contractors in Delhi-NCR displace annual frameworks with milestone-based terms. |
| Sol-Gel Capacity Expansion | Specialists target South Korean display panel producers seeking touch sensor integration. |
Research Methodology
Document review covered trade customs data, BIS certification registries, and GB standard compliance filings, complemented by interviews with magnetron sputtering line operators, glazing procurement managers at general contractors, solar module developers, and automotive OEM platform engineers. Secondary validation drew from MEE emission disclosure records, METI retrofit subsidy documentation, and ASEAN energy-efficiency labeling harmonization protocols. Bottom-up capacity assessments triangulated against top-down construction spend projections.
Market sizing outputs segment across coating technology, application type, and end-user archetype, with additional dimensioning by certification tier and regional production hub concentration. CAGRs derive from installed base replacement cycles, code compliance deadlines, and solar capacity addition pipelines. Forecast inputs include silver price trajectory assumptions and sputtering technician training pipeline constraints across the analysis window.
Silver price volatility, MEE regulatory enforcement intensity, and ASEAN labeling harmonization delays are the dominant revision risks to coating demand projections. Forecasts reflect assumptions around GB 50189 compliance timelines and utility-scale solar procurement schedules. Practitioners should monitor BIS certification friction levels and sputtering equipment delivery lead times for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Polyurethane Powder Coatings Market
Coatings
Middle East and Africa Super Hydrophobic Coatings Market
Coatings
Germany Automotive OEM Coatings Market
Coatings
Color-Shifting Coating Market
Coatings
Global Conformal Coatings Market
Coatings
Electron Beam Curable Coating Market
Coatings
Rail Coatings Market
Coatings
Clear Coatings Market
Coatings
Water-Based Alkyd Coatings Market
Coatings
Global Polyaspartic Coatings Market
Coatings
Global Coil Coatings Market
Coatings
Anti-Friction Coatings Market
Coatings
Canada Industrial Wood Coatings Market
Coatings
Global Fluorine Carbon Coatings Market
Coatings
Insulation Coating Market
Coatings
Canada Automotive OEM Coatings Market