
 Asia-Pacific Fighter Aircraft Market | 2026-2036
Asia-Pacific Fighter Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fighter Aircraft Market Outlook
A widening capability gap between fifth-generation stealth programs and legacy fleet upgrades is redrawing competitive boundaries across the Asia-Pacific fighter aircraft sector. Lockheed Martin leverages its F-35 supply chain footprint to sustain long-term positioning in Japan and Australia. Mitsubishi Heavy Industries anchors Japan's indigenous F-X program while competing for regional technology partnerships. Hindustan Aeronautics Limited dominates India's Tejas production line and navigates offset requirements for foreign platform assembly.
Fighter aircraft are fixed-wing military platforms engineered for air-to-air combat, ground attack, and reconnaissance missions, typically achieving supersonic speeds through afterburning turbofan engines and incorporating advanced aerodynamic designs with thrust-vectoring capabilities for enhanced maneuverability. Their primary purpose is to establish air superiority and deliver precision strike capacity in contested operational environments. Multi-role configurations now lead procurement budgets as air forces prioritize fleet flexibility over single-mission specialization, while stealth technology commands premium investment despite extended development timelines. Trainer segments occupy stable replacement cycles across established fleets, and avionics integration increasingly determines platform competitiveness rather than airframe performance alone.
Japan's Ministry of Economy, Trade and Industry (METI) coordinates industrial policy with the Ministry of Defense to shape domestic manufacturing requirements, while Australia's Defence Export Controls regulate technology transfer thresholds for regional partners. India's Defence Research and Development Organisation and the Ministry of Defence enforce indigenous content mandates that reshape foreign OEM market access. Procurement committees must weigh interoperability commitments against sovereign industrial development objectives as regional alliance structures evolve.
Market Dynamics
The Asia-Pacific fighter aircraft sector is rebalancing around fifth-generation stealth proliferation as territorial air defense postures harden. Sovereign industrial mandates from Tokyo to New Delhi are fragmenting traditional supplier relationships while accelerating indigenous platform development.
Growth Catalysts
- Japan's National Defence Strategy:Revised defense spending targets and technology partnership frameworks are unlocking co-development capital for next-generation air superiority platforms.
- Multi-role avionics convergence:Integrated sensor fusion architectures are compressing procurement cycles as air forces retire single-mission airframes for flexible strike configurations.
- Southeast Asian fleet modernization:Aging F-5 and MiG-21 replacements across Indonesia, Malaysia, and Vietnam are driving sustained import demand for fourth-generation plus platforms.
Market Restraints
- Engine supply concentration:Turbofan propulsion systems for advanced fighters depend on a narrow supplier base concentrated in the United States and Western Europe, exposing programs to export control volatility.
- Stealth coating technical limitations:Radar-absorbent material maintenance requirements and climate degradation in tropical operating environments constrain sortie availability across equatorial basing.
- India's Defence Acquisition Procedure:Indigenous content thresholds and offset mandates create procurement friction for foreign OEMs, extending contract negotiation timelines.
Strategic Opportunities
- Australia's AUKUS alignment:Nuclear-powered submarine technology sharing is creating precedent for deeper fighter aircraft industrial integration with American and British supply chains.
- Unmanned loyal wingman convergence:Manned-unmanned teaming architectures are opening new product categories as South Korea's KF-21 and Australia's MQ-28 programs mature in parallel.
- South Korea's KF-X export pathway:Indonesia's continued program participation and prospective Southeast Asian marketing create regional manufacturing scale beyond domestic requirements.
Industry Challenges
- Flight control software certification:Fly-by-wire and autonomous maneuvering systems face extended airworthiness validation timelines, compressing initial operational capability schedules.
- Skilled airframe engineering scarcity:Stealth shaping, composite fabrication, and advanced metallurgy expertise pools are concentrating at legacy primes, constraining indigenous program staffing.
- Legacy fleet integration complexity:New platform datalink architectures must interoperate with existing command networks, forcing costly middleware development for mixed-generation operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fighter Aircraft Market |
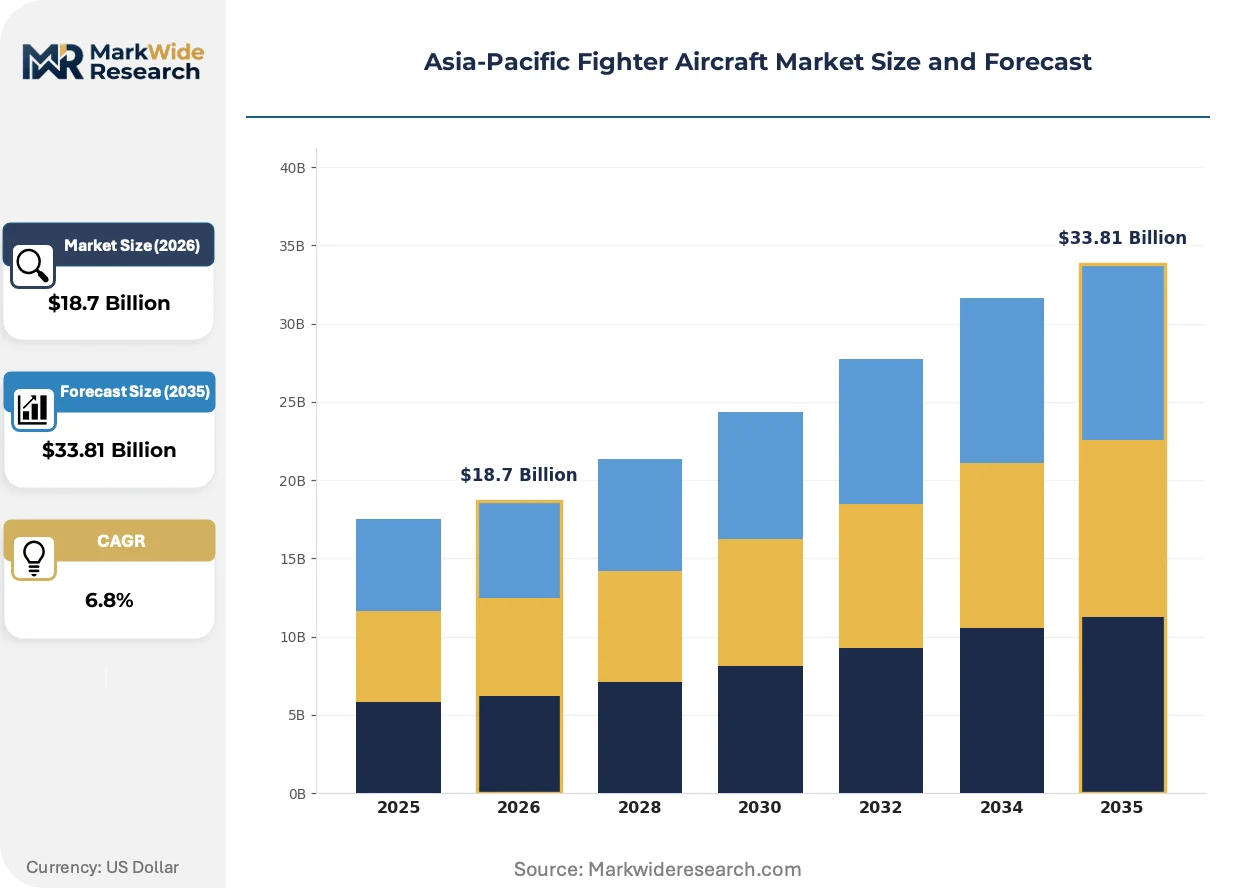
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-role, Stealth, Trainer, Attack End User: Military, Government, Defence Contractors, Private Technology: Fly-by-wire, Avionics, Radar, Missiles Installation: Onshore, Offshore, Facility-based, Mobile |
| Companies Covered | Lockheed Martin Corporation, The Boeing Company, Mitsubishi Heavy Industries, Ltd., Hindustan Aeronautics Limited, Aviation Industry Corporation of China, Airbus SE, Dassault Aviation, Saab AB, Korea Aerospace Industries, Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fighter Aircraft Market Strategic Shifts
Active electronically scanned array radar and low-observable shaping are redistributing competitive advantage away from kinematic performance metrics. Platform economics now hinge on software upgrade velocity and sensor open architecture standards.
Digital engineering and model-based systems engineering are decomposing traditional airframe development timelines. South Korea's Korea Aerospace Industries and Japan's Mitsubishi Heavy Industries have adopted these methodologies for their respective indigenous programs. The approach is compressing prototype-to-production intervals while enabling parallel subsystem integration that previously required sequential testing.
Australia's Defence Export Controls framework is tightening technology transfer thresholds for regional partners, particularly affecting maintenance training and source code access. The regulation is forcing OEMs to establish sovereign maintenance facilities within customer nations rather than centralized regional hubs. Southeast Asian operators are responding by negotiating deeper industrial participation clauses in procurement contracts.
Air force procurement committees are consolidating vendor relationships around platform families rather than discrete aircraft purchases. Australia's F-35A commitment and follow-on sustainment contracting exemplify this pattern. The behavior is most visible in nations with established alliance structures, where interoperability certification and logistics commonality override unit acquisition cost considerations.
Asia-Pacific Fighter Aircraft Market Segmentation
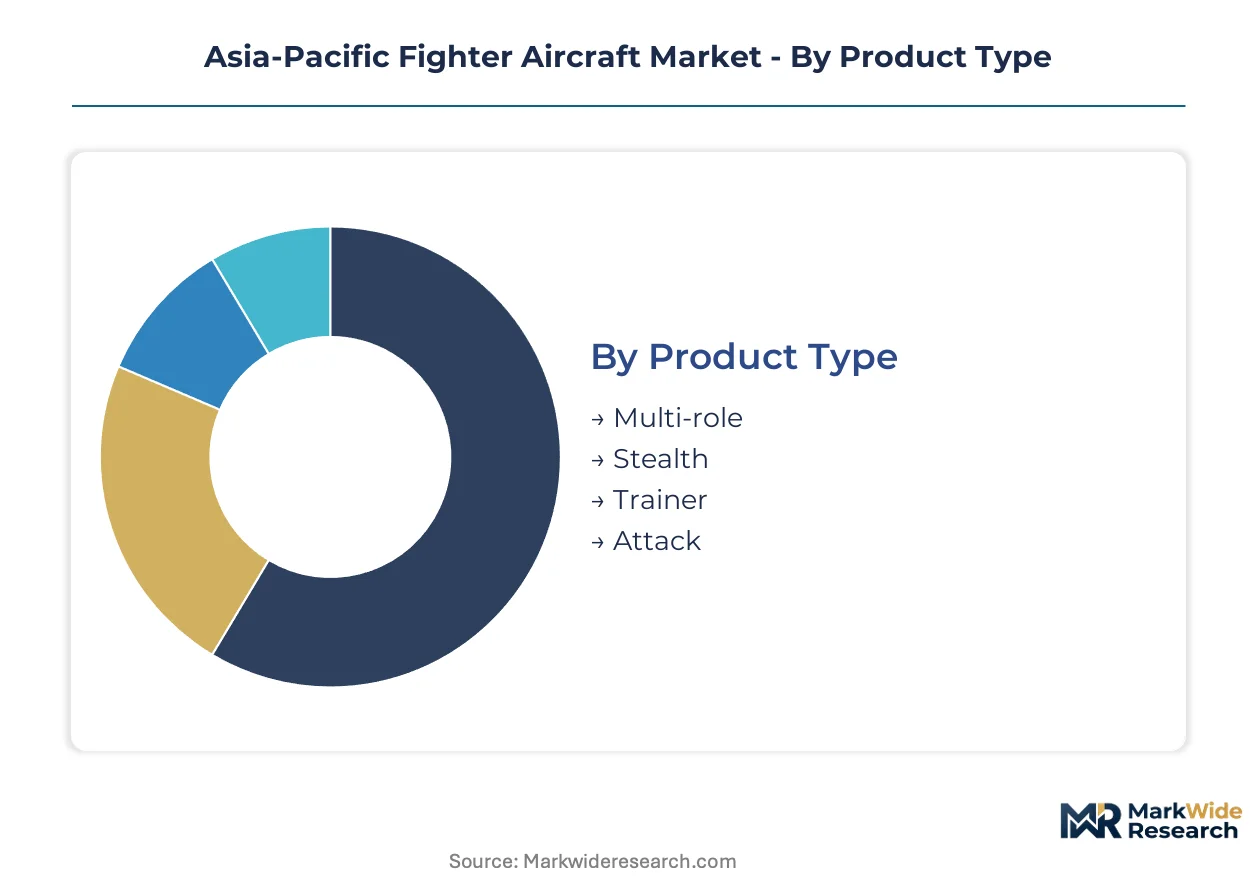
Fighter aircraft procurement in the Asia-Pacific fragments across mission profiles, technology maturity, and sovereign industrial mandates. Understanding these segment boundaries clarifies where defense budgets concentrate and where indigenous development disrupts traditional supplier relationships.
Product Type:
Margin pools concentrate in platforms combining stealth characteristics with multi-mission flexibility, as air forces prioritize fleet consolidation over specialized airframes.
- Multi-role:These platforms integrate air-to-air combat, ground strike, and reconnaissance capabilities through modular weapon stations and reprogrammable mission computers. Australia's F-35A acquisition and India's Tejas production line exemplify demand concentration where operational flexibility offsets higher unit costs. Procurement committees favor configurations that minimize logistics footprints across dispersed basing architectures.
- Stealth:Radar cross-section reduction through faceted shaping, internal weapons bays, and radar-absorbent materials defines this premium tier. Japan's F-X program and South Korea's KF-21 Block II roadmap anchor regional investment as territorial air defense postures harden against integrated air defense networks. Development timelines extend due to coating maintenance protocols and thermal management complexity.
- Trainer:Advanced jet trainers with glass cockpits and embedded tactical simulation prepare pilots for fourth-generation plus transitions. Lead-in fighter training requirements from Indonesia to Vietnam sustain replacement cycles.
- Attack:Dedicated ground-attack configurations persist in niche roles requiring heavy weapons carriage and extended loiter endurance. Close air support missions in contested littoral environments retain procurement priority.
The dominant share belongs to Multi-role, while Stealth is closing the gap fastest.
End User:
Volume concentration tracks military service branch modernization schedules, with sovereign procurement authorities exercising tightening industrial participation requirements.
- Military:Air force, naval aviation, and army aviation branches constitute the primary demand channel. India's Ministry of Defence and Japan's Acquisition, Technology and Logistics Agency steer platform selection through technical evaluation committees that weight operational requirements against offset obligations.
- Government:Coast guard and paramilitary air wings acquire lighter fighter derivatives for maritime patrol and airspace policing. Australia's Border Force and Japan's Coast Guard operate surveillance-configured platforms with reduced weapons integration.
- Defence Contractors:Private military companies and training service providers source retired military airframes for adversary simulation and pilot instruction contracts.
- Private:Heritage flight organizations and technical museums acquire demilitarized examples for display and ceremonial formation flying.
Military branches command the largest procurement volumes, though Government operators are expanding fastest as maritime security missions proliferate.
Technology:
Competitive differentiation increasingly hinges on software upgrade velocity rather than airframe performance metrics alone.
- Fly-by-wire:Digital flight control systems with triple-redundant architectures enable relaxed static stability designs and automatic spin recovery. South Korea's KF-21 and India's Tejas Mk2 incorporate indigenous control law development to reduce foreign dependency.
- Avionics:Integrated sensor fusion cockpits with large-area displays and helmet-mounted cueing systems compress pilot workload during multi-target engagements. Open architecture standards are fragmenting supplier relationships as air forces demand source code access.
- Radar:Active electronically scanned array systems with gallium nitride transmit-receive modules deliver track-while-scan and electronic attack capabilities. Regional production lines for antenna arrays are concentrating in Japan and South Korea.
- Missiles:Beyond-visual-range air-to-air and precision standoff weapons integration determines platform export viability. Indigenous missile development programs in India and Japan are displacing legacy supplier relationships.
Avionics capture the steepest investment trajectory, while Fly-by-wire systems anchor baseline platform economics.
Installation:
Deployment mode selection reflects basing vulnerability assessments and expeditionary operational concepts across archipelagic and continental theaters.
- Onshore:Permanent main operating bases with hardened aircraft shelters and integrated logistics hubs support sustained high-tempo operations. Australia's RAAF Tindal and Japan's Nyutabaru Air Base exemplify infrastructure investments hardened against precision strike threats.
- Offshore:Carrier-based and amphibious assault ship operations extend airpower projection beyond land-based range arcs. Japan's Izumo-class conversion and India's Vikrant carrier integration drive naval fighter procurement.
- Facility-based:Contractor logistics support depots with sovereign maintenance, repair, and overhaul capabilities satisfy indigenous content mandates. Australia's Defence Export Controls framework mandates local deep maintenance for F-35 sustainment.
- Mobile:Deployable forward arming and refueling point configurations enable dispersed operations from austere airfields. Southeast Asian operators prioritize rapid runway repair and bare-base deployment kits.
Onshore basing retains the largest installed base, though Offshore configurations are gaining share fastest as naval aviation expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across the Asia-Pacific fighter aircraft sector. Southeast Asian air forces prioritize acquisition cost and operational simplicity, while Japan and Australia absorb premium pricing for sovereign industrial participation and interoperability integration.
Australia
The Royal Australian Air Force's F-35A acquisition anchors regional fifth-generation deployment, with RAAF Tindal and Williamtown bases receiving hardened infrastructure investment. The Defence Export Controls framework mandates sovereign deep maintenance capabilities, forcing Lockheed Martin to establish domestic sustainment facilities rather than regional hubs. Melbourne's defense industrial corridor concentrates software integration and logistics support contracts for the national fleet.
Japan
Japan's Acquisition, Technology and Logistics Agency steers platform selection through the revised National Defence Strategy, which elevates indigenous development priority alongside foreign procurement. METI coordinates industrial policy with the Ministry of Defense to shape domestic manufacturing requirements for the F-X program. Nagoya's aerospace cluster hosts Mitsubishi Heavy Industries' final assembly lines and composite fabrication facilities for next-generation airframes.
India
The Ministry of Defence enforces indigenous content thresholds through the Defence Acquisition Procedure, reshaping foreign OEM market access and extending contract negotiation timelines. Hindustan Aeronautics Limited dominates Tejas production while navigating offset requirements for foreign platform assembly. Bangalore's defense aerospace ecosystem concentrates avionics integration and flight control software development for indigenous programs.
South Korea
Korea Aerospace Industries drives KF-21 development with Indonesia's continued program participation creating regional manufacturing scale beyond domestic requirements. The Defense Acquisition Program Administration balances technology transfer demands against alliance interoperability commitments. Sacheon's aerospace complex houses final assembly and active electronically scanned array radar production lines for indigenous and export configurations.
Indonesia
The Indonesian Air Force accelerates F-5 and MiG-21 replacements through fourth-generation plus platform imports, prioritizing acquisition cost and maintenance simplicity over advanced stealth capabilities. National procurement committees negotiate industrial participation clauses to satisfy domestic political requirements. Bandung's aerospace manufacturing zone sustains regional maintenance, repair, and overhaul operations for imported fighter fleets.
Asia-Pacific Fighter Aircraft Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific fighter aircraft sector. The market structure consolidates around legacy primes with established supply chain footprints while fragmenting among indigenous developers seeking sovereign capability. Three archetypes dominate: American and European primes with mature stealth platforms, state-owned Asian aerospace conglomerates with indigenous development mandates, and mid-tier European specialists with modular upgrade offerings. Competitive dynamics center on strategic partnerships for technology transfer and sovereign maintenance facility establishment.
Among American primes with regional supply chain integration, Lockheed Martin Corporation and The Boeing Company occupy positions exemplifying technology-leadership archetypes with established F-35 and F-15 sustainment networks. Mitsubishi Heavy Industries, Ltd. anchors Japan's indigenous tier through the F-X program while competing for regional technology partnerships. Hindustan Aeronautics Limited represents the state-owned development archetype dominating India's Tejas production line and foreign platform assembly offset arrangements.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| The Boeing Company |
| Mitsubishi Heavy Industries, Ltd. |
| Hindustan Aeronautics Limited |
| Aviation Industry Corporation of China |
| Airbus SE |
| Dassault Aviation |
| Saab AB |
| Korea Aerospace Industries, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Performance-based logistics contracts with sovereign maintenance clauses lock in decades of aftermarket revenue while anchoring unit pricing visibility for procurement committees across Australia, Japan, and South Korea. These arrangements bind foreign OEMs to domestic facility investments, transforming transactional aircraft sales into captive service relationships that resist price competition.
Pricing Analysis
Sustainment and upgrade services generate lifetime value multiples exceeding initial airframe acquisition, with Australia's F-35A sovereign deep maintenance mandates exemplifying this revenue architecture. Three-tier pricing structure across fifth-generation stealth, fourth-generation plus multi-role, and legacy trainer platforms reflects capability differentiation and industrial participation depth. Cost compression in equatorial basing configurations intensifies as Southeast Asian operators prioritize acquisition simplicity over advanced coatings. Government procurement committees exhibit highest price sensitivity, while allied air forces absorb premium positioning for interoperability certification.
Supply Chain Analysis
The United States and United Kingdom anchor propulsion system and mission computer production, while Japan and South Korea concentrate active electronically scanned array radar and composite airframe fabrication. Gallium nitride transmit-receive modules, high-temperature turbine alloys, and radar-absorbent material precursors draw from concentrated specialty chemical and semiconductor foundry bases. Single-source vulnerability in turbofan engine supply exposes programs to export control volatility under ITAR and national disclosure policy frameworks. Distribution runs through sovereign maintenance facilities established under Defence Export Controls mandates rather than centralized regional hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
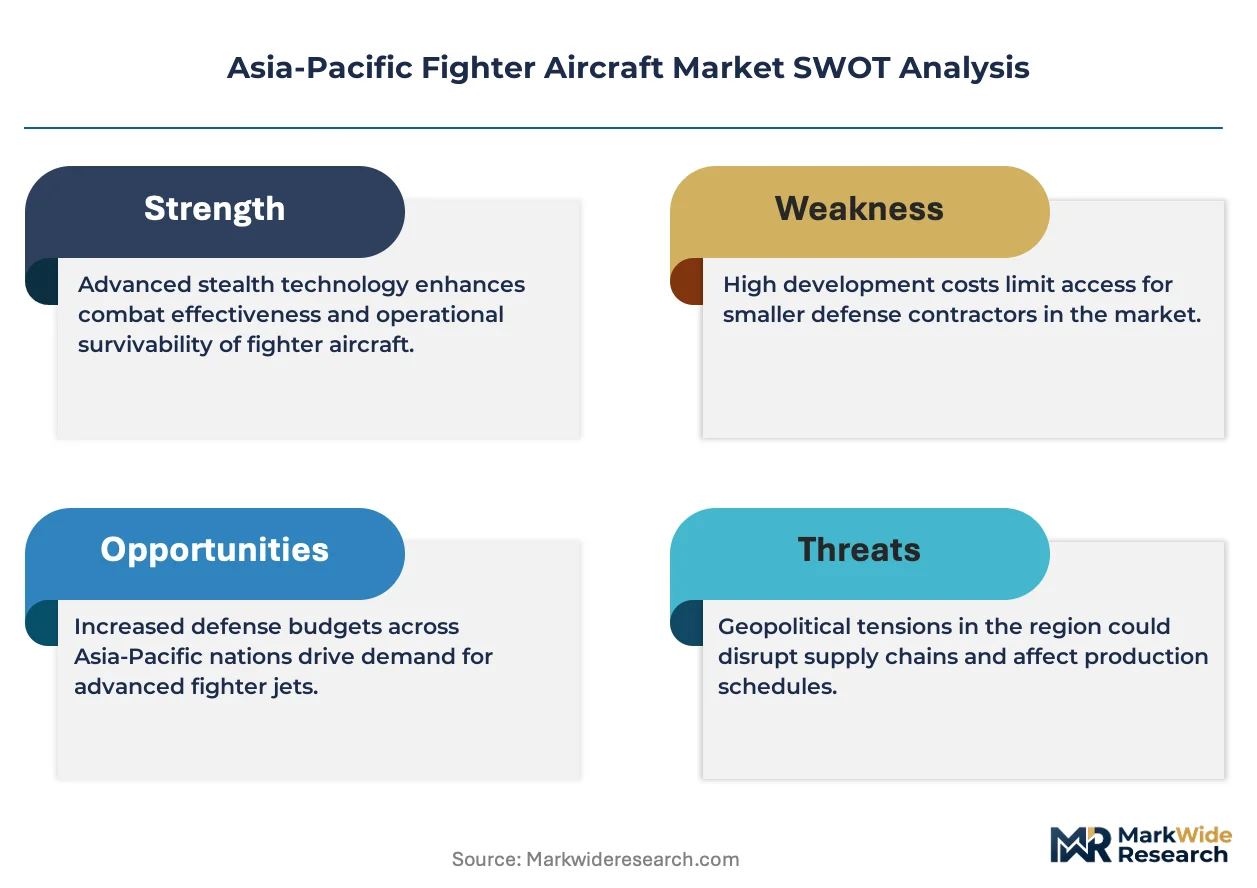
This market operates as a defensive-moat structure where regulatory entrenchment through indigenous content mandates and sovereign maintenance requirements creates insurmountable switching costs for foreign OEMs.
For Market Incumbents: Secure long-term sustainment contracts with source code escrow provisions that preempt avionics upgrade competition from indigenous developers. Deepen sovereign facility footprints in Nagoya, Bangalore, and Sacheon to satisfy Defence Acquisition Procedure offset thresholds and METI manufacturing requirements, insulating against emerging platform challenges from Korea Aerospace Industries and Mitsubishi Heavy Industries. For New Entrants and Emerging Players: Lead with unmanned loyal wingman architectures and manned-unmanned teaming software stacks where certification pathways remain unsettled and incumbent lock-in is weakest. Indonesia's F-5 replacement cycle and Vietnam's MiG-21 succession represent the most penetrable demand pockets for modular fourth-generation plus configurations with simplified logistics footprints. For Investors and Strategic Acquirers: Specialized avionics integration houses with active electronically scanned array radar or flight control software expertise present acquisition targets with asymmetric value capture potential. Long-term viability rests on positioning ahead of KF-21 and F-X program export phases. Watch Indonesia's continued KF-21 program participation as an inflection signal for regional manufacturing scale validation.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Maintenance Facility Establishment | Lockheed Martin's Australian F-35A deep maintenance hub satisfies Defence Export Controls while capturing decades of aftermarket revenue. |
| Indigenous Radar Development Partnership | Mitsubishi Heavy Industries' gallium nitride array production in Nagoya reduces dependency on US transmit-receive module supply. |
| Multi-role Platform Export Certification | Korea Aerospace Industries' KF-21 Indonesian partnership validates regional manufacturing scale beyond domestic air force requirements. |
| Avionics Open Architecture Adoption | India's Tejas Mk2 integrated sensor fusion cockpit enables source code access that fragments traditional supplier relationships. |
| Unmanned Teaming System Integration | Boeing Australia's MQ-28 Ghost Bat program with RAAF creates precedent for loyal wingman procurement categories. |
Study Parameters
A spread of perspectives from air force procurement officers, defense acquisition program administrators, avionics engineering directors, and sovereign maintenance facility operators converged on the working assumptions driving this analysis. Primary fieldwork across Australia's Defence Export Controls framework, Japan's METI industrial policy coordination, and India's Defence Acquisition Procedure enforcement was cross-validated against secondary sources including RAAF capability investment program disclosures, ATLA budget submissions, and HAL production line reports. Bottom-up platform delivery schedules and top-down defense budget appropriations were triangulated to anchor volume and value estimates.
Segmentation dimensions modeled include product type tier, end user service branch, technology maturity level, installation basing mode, and sovereign industrial participation depth across the projection horizon. CAGRs were derived from trend extrapolation of historical procurement cycles adjusted for policy acceleration effects. Forecast inputs incorporated territorial air defense posture hardening indices and multi-role fleet consolidation trajectories specific to Southeast Asian archipelagic operating environments.
The analysis sits within stated boundaries; outcomes outside sustained defense spending commitments, intact technology transfer agreements, and stable regional alliance structures would require recalibration. Forecasts reflect documented assumptions regarding indigenous program development timelines and foreign OEM market access negotiations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Commercial Aircraft Manufacturing Market
Aircraft
Global LW Sport Aircraft Market
Aircraft
Water Bomber Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Airplane and Helicopter Hangar Doors Market
Aircraft
UK Aviation Market
Aircraft
Utility Aircraft Market
Aircraft
Military Transport Aircraft Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Attack Helicopter Market
Aircraft
Commercial Aircraft Wing Market
Aircraft
UK Military Aviation Market
Aircraft
North America Business Jet Market
Aircraft
Aircraft Oxygen System Market
Aircraft
General Aviation Market
Aircraft
US Aviation Market