
 Asia-Pacific Feed Mycotoxin Detoxifiers Market | 2026-2036
Asia-Pacific Feed Mycotoxin Detoxifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Feed Mycotoxin Detoxifiers Market Outlook
Clay-based binders is decoupling from premium pricing as yeast-derived alternatives demonstrate superior efficacy against multiple mycotoxin classes. DSM Nutritional Products AG leverages its vitamin premix infrastructure to bundle detoxifiers into complete nutritional packages across Southeast Asia. Kemin Industries anchors its position through specialized R&D facilities in India that tailor formulations to regional contamination profiles. Adisseo competes aggressively on manufacturing scale, operating integrated fermentation capacity that lowers unit costs for bacterial detoxifier lines.
Asia-Pacific feed mycotoxin detoxifiers comprise functional additives designed to neutralize, adsorb, or biotransform fungal metabolites in animal feed matrices, typically formulated with specific surface-area thresholds exceeding 600 m²/g for aluminosilicate clays or containing defined colony-forming units for live yeast cell walls. These products serve the primary commercial purpose of safeguarding feed conversion ratios and preventing residue transfer into meat, milk, and egg outputs across intensive livestock systems. Clay products dominate volume throughput due to established cost structures and broad-spectrum aflatoxin binding, while enzyme-based segments capture expanding margin pools through targeted degradation of trichothecenes and zearalenone. Poultry application leads absolute consumption across the region, though aquaculture represents the fastest-growing end-use as shrimp and finfish producers confront emerging T-2 toxin pressures in tropical feed ingredients.
China's SAMR enforces mandatory GB 13078 feed hygiene standards that prohibit detectable aflatoxin B1 levels above strict thresholds, while India's FSSAI and BIS coordinate on imported additive registration requirements that delay market entry for non-domestic suppliers. The EU F-Gas Regulation indirectly shapes regional formulation trends as Asia-Pacific exporters align with European import tolerances for livestock product residues. Stakeholders must monitor evolving national maximum residue limits and invest in multi-toxin analytical capabilities before regulatory harmonization accelerates across ASEAN veterinary drug control frameworks.
Market Dynamics
Climate-induced mold pressure across Southeast Asian feed belts is accelerating the displacement of clay-based binders by biotransformation technologies that neutralize multiple mycotoxin classes simultaneously.
Growth Catalysts
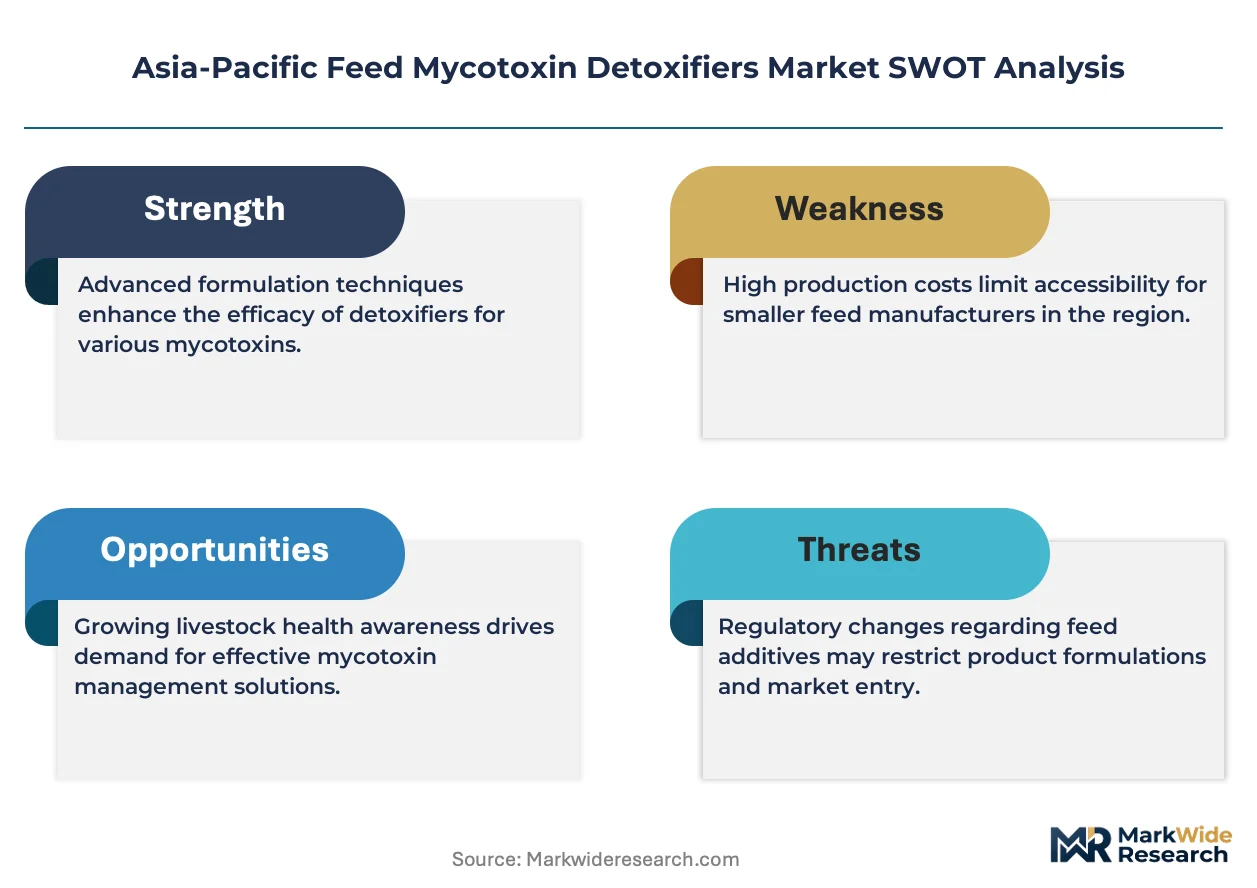
- GB 13078 feed hygiene standards:China's SAMR enforces strict aflatoxin B1 thresholds that compel feed mills to upgrade from basic adsorbents to validated detoxifier systems with documented efficacy data.
- Aquaculture expansion:Shrimp producers in Vietnam's Mekong Delta confront emerging T-2 toxin pressures in tropical fishmeal, creating specialized demand for trichothecene-targeting formulations.
- Integrated livestock operations:Consolidated poultry houses across Thailand and Indonesia seek bundled nutritional packages that combine vitamins with mycotoxin risk management to protect feed conversion ratios.
Market Restraints
- Aluminosilicate raw material concentration:High-purity bentonite deposits concentrate in specific mining districts, exposing formulators to supply disruptions when climate events affect extraction.
- Live yeast cell wall cultivation costs:Fermentation-based production requires sterile bioreactor infrastructure that elevates unit economics above clay alternatives by substantial margins.
- FSSAI-BIS registration friction:India's dual agency review process for imported additives extends market entry timelines and favors domestic suppliers with established compliance dossiers.
Strategic Opportunities
- Philippines feed mill modernization:Underpenetrated regions in Luzon and Visayas lack analytical capabilities for multi-toxin screening, creating service-anchored entry points for diagnostic-detoxifier bundles.
- Enzyme-clay hybrid formulations:Converging biotransformation and adsorption mechanisms address zearalenone and aflatoxin simultaneously, commanding premium positioning in high-value dairy applications.
- EU F-Gas Regulation alignment:Exporters targeting European livestock product markets must demonstrate residue compliance, accelerating demand for detoxifiers with verified metabolite degradation pathways.
Industry Challenges
- Mycotoxin analytical capability gaps:Feed mills across secondary Vietnamese and Indonesian markets lack LC-MS/MS infrastructure to validate detoxifier performance against multiple toxin classes.
- Formulation integration complexity:Yeast cell wall products require precise pH and temperature controls during pelleting that legacy equipment in smaller mills cannot consistently maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Feed Mycotoxin Detoxifiers Market |
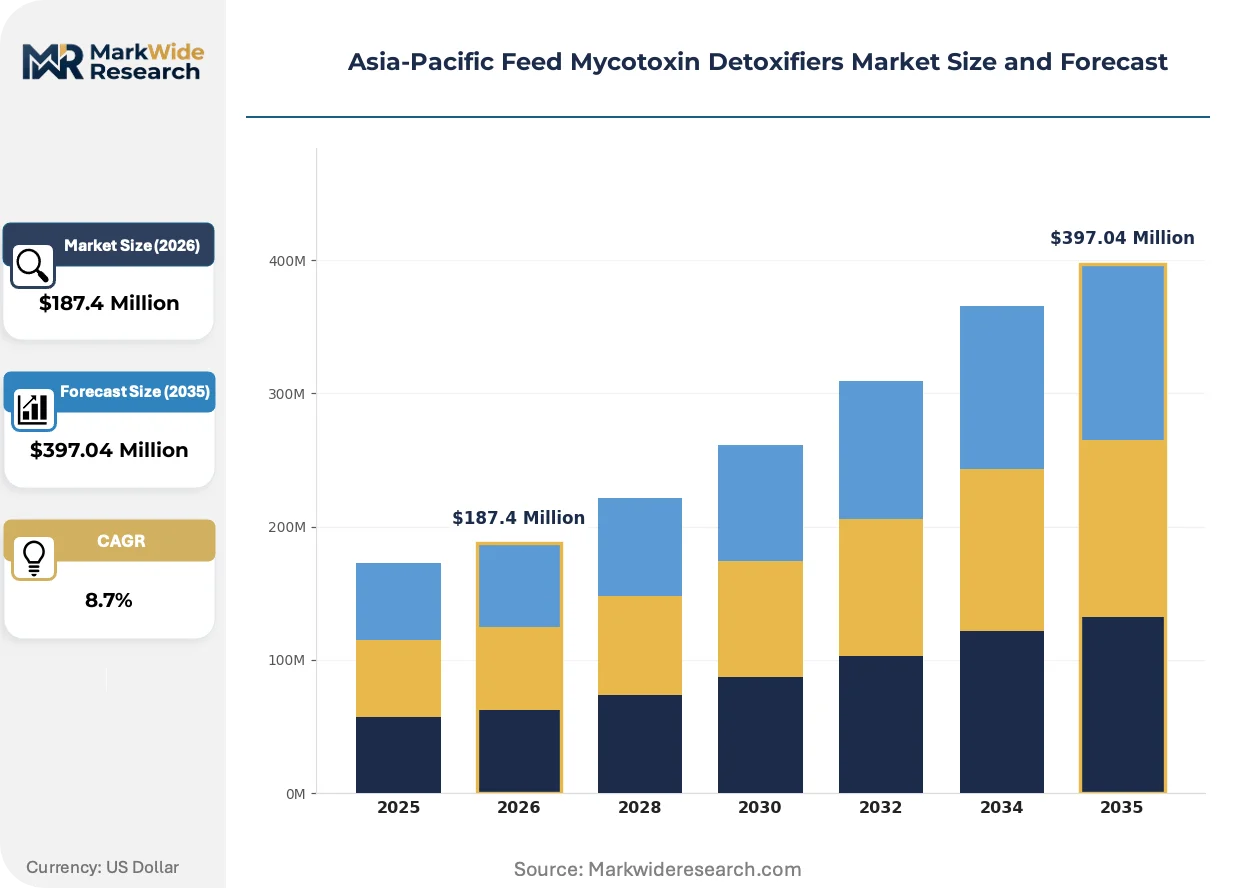
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clay, Yeast, Bacteria, Enzymes Application: Poultry, Swine, Ruminants, Aquaculture Form: Granular, Liquid, Powder, Pellet Distribution Channel: Online, Distributors, Retail, Direct Sales |
| Companies Covered | DSM Nutritional Products AG, Kemin Industries, Adisseo, AMLAN International, Biomin Holding, BASF SE, Land O'Lakes, Impextraco, Cargill Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Feed Mycotoxin Detoxifiers Market Strategic Shifts
Biological detoxification approaches are compressing the performance gap between premium and standard product tiers while regulatory verification requirements reshape competitive positioning across the region.
Yeast-derived cell wall technologies with defined beta-glucan and mannan-oligosaccharide profiles are electrifying the competitive landscape for aflatoxin management. Poultry integrators in Thailand and Vietnam deploy these systems at scale after field trials demonstrated superior binding kinetics compared to unmodified clays. The technology is electrifying margin structures by enabling suppliers to capture value previously allocated to veterinary interventions for subclinical mycotoxicosis.
ASEAN veterinary drug control frameworks are converging toward harmonized maximum residue limits that mirror EU F-Gas Regulation stringency for exported livestock products. Feed additive manufacturers must now maintain dual registration dossiers for domestic sale and export certification, elevating compliance costs for smaller regional players. Aquaculture feed producers targeting European retail channels face the most acute adaptation pressure and are consolidating supplier relationships to secure traceable detoxifier supply chains.
Integrated livestock operations are consolidating procurement decisions at the group level rather than individual mill autonomy, compressing vendor lists to suppliers with multi-country technical service capabilities. This concentration displaces local distributors who previously managed relationships with smaller independent feed mills. The pattern is most visible in Vietnam's Mekong Delta, where three large integrators now control additive selection for over sixty percent of regional feed volume.
Asia-Pacific Feed Mycotoxin Detoxifiers Market Segmentation
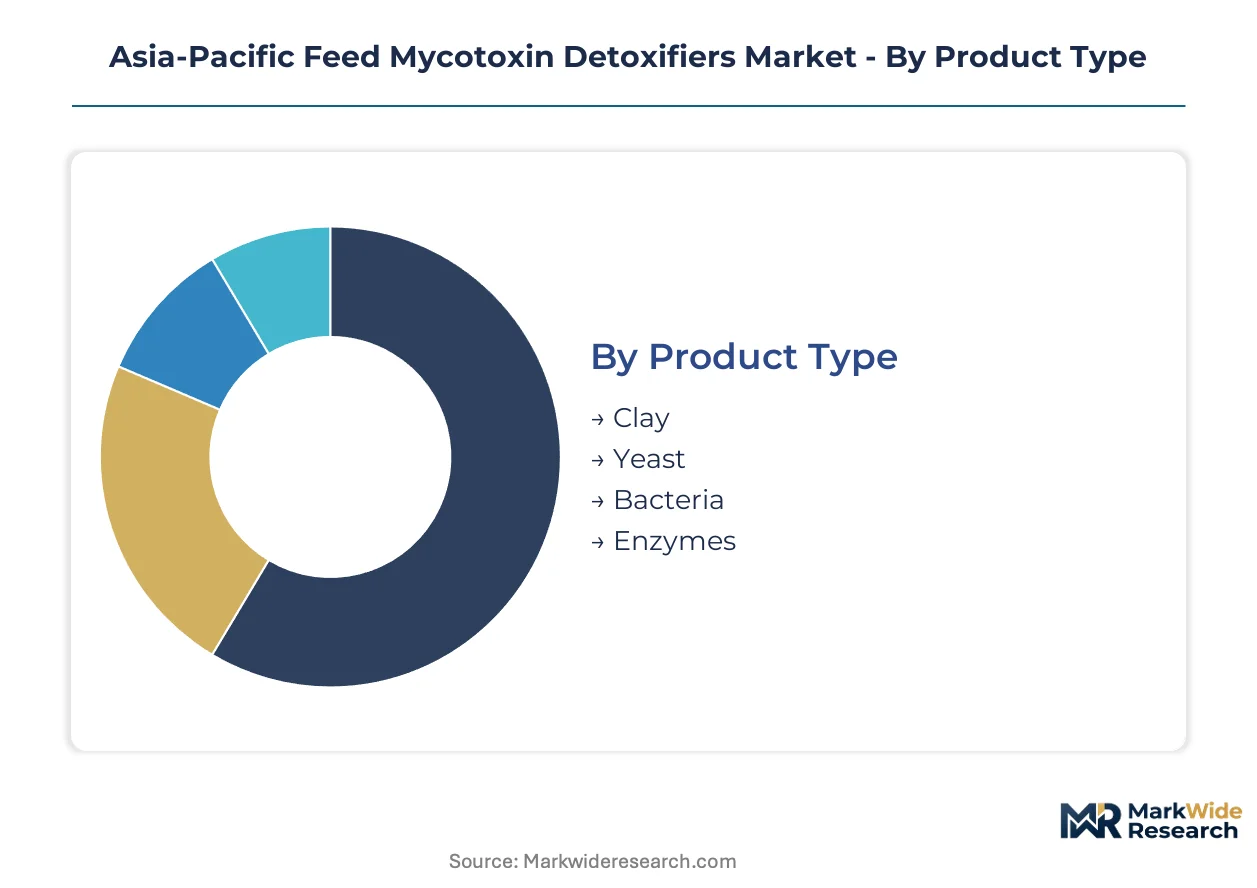
Product architecture in feed mycotoxin detoxifiers determines both efficacy profiles and cost structures across Asia-Pacific livestock systems. Formulation choices cascade through application protocols, storage requirements, and procurement patterns that differ sharply between integrated poultry houses and independent aquaculture operations.
Product Type:
Volume throughput concentrates in established mineral technologies while margin capture shifts toward biological systems with multi-toxin capabilities.
- Clay:Aluminosilicate binders with surface area thresholds exceeding 600 m²/g deliver broad-spectrum aflatoxin adsorption at unit economics that dominate feed mill procurement in Vietnam's Mekong Delta clusters. Thailand's integrated poultry houses specify these products for baseline contamination protocols where cost efficiency outweighs targeted degradation requirements.
- Yeast:Defined beta-glucan and mannan-oligosaccharide profiles from Saccharomyces cerevisiae cell walls demonstrate superior binding kinetics against multiple mycotoxin classes simultaneously. Indonesia's expanding broiler operations are displacing unmodified clays in premium ration formulations as climate-induced mold pressures intensify across Southeast Asian feed belts.
- Bacteria:Fermentation-derived biotransformation agents degrade trichothecenes through enzymatic pathways that clay binders cannot access.
- Enzymes:Targeted protein formulations address zearalenone and T-2 toxin specifically in high-value dairy and aquaculture applications.
Today's leader: Clay. Tomorrow's challenger: Yeast.
Application:
End-use concentration patterns reflect livestock density gradients and export orientation across regional protein production zones.
- Poultry:Intensive broiler and layer systems across Thailand, Indonesia, and Vietnam consume the largest absolute volumes as integrators bundle detoxifiers into complete nutritional packages to protect feed conversion ratios. China's zero-tolerance aflatoxin rules under GB 13078 compel mill upgrades to validated systems with documented efficacy data.
- Aquaculture:Shrimp producers in Vietnam's Mekong Delta confront emerging T-2 toxin pressures in tropical fishmeal, creating specialized demand for trichothecene-targeting formulations that command premium positioning. Finfish operations in Indonesia and the Philippines are expanding adoption fastest as European retail channel compliance requirements tighten.
- Swine:Sow and finishing operations in China and Vietnam prioritize zearalenone management for reproductive performance protection.
- Ruminants:Dairy applications in India and China favor enzyme-clay hybrids that address aflatoxin M1 residue risks in milk outputs.
Poultry maintains volume dominance. Aquaculture claims the steepest expansion trajectory.
Form:
Physical presentation dictates integration feasibility with legacy mill infrastructure and climate-specific storage stability requirements.
- Granular:Low-dust flowability suits automated dosing systems in Thailand's large-scale feed manufacturing plants where pelleting temperatures exceed yeast cell wall tolerance thresholds.
- Powder:Maximum surface area exposure optimizes adsorption kinetics for clay binders in Vietnam's independent mill sector.
- Liquid:Post-pelleting application preserves live yeast viability where temperature controls are inconsistent.
- Pellet:Pre-formulated integration reduces handling steps for smaller Indonesian operations with limited technical staff.
Granular forms dominate throughput. Liquid presentations gain share in yeast-based segments.
Distribution Channel:
Procurement centralization at integrated group level is compressing traditional channel structures across the region.
- Direct Sales:Technical service teams from multinational suppliers maintain relationships with Vietnam's three largest poultry integrators controlling additive selection for over sixty percent of Mekong Delta feed volume. DSM and Kemin deploy specialized staff for formulation support and multi-toxin analytical validation.
- Distributors:Regional networks retain relevance in the Philippines' underpenetrated Luzon and Visayas markets where independent mills lack diagnostic capabilities and service-anchored bundles create entry points.
- Online:Digital procurement platforms emerge for standardized clay products in China's fragmented feed mill landscape.
- Retail:Farm supply stores serve smallholder livestock operations in Indonesia's outer islands with basic binder formulations.
Direct sales capture integrated volume. Distributors defend position in fragmented secondary markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Mekong Delta feed mill clusters anchor Asia-Pacific demand for validated mycotoxin detoxifier systems as climate pressures intensify across Southeast Asian feed belts. Procurement centralization among integrated poultry operations concentrates additive selection decisions among three dominant regional integrators.
China
Zero-tolerance aflatoxin enforcement under SAMR's GB 13078 feed hygiene standards compels mill upgrades to documented detoxifier systems with verified efficacy data. The country's national feed safety regulator mandates strict aflatoxin B1 thresholds that eliminate basic adsorbent options. Yangtze River Delta feed manufacturing hubs drive premium formulation demand as integrators bundle complete nutritional packages.
Vietnam
Shrimp producers in the Mekong Delta confront emerging T-2 toxin pressures in tropical fishmeal, creating specialized demand for trichothecene-targeting formulations. SAMR-aligned import standards for feed additives delay market entry for non-domestic suppliers lacking established compliance dossiers. Three large poultry integrators now control additive selection for over sixty percent of regional feed volume.
Thailand
Integrated broiler and layer operations specify clay-based binders for baseline contamination protocols where cost efficiency outweighs targeted degradation requirements. The country's national agricultural ministry coordinates with ASEAN veterinary drug control frameworks on harmonizing maximum residue limits. Bangkok-centered feed manufacturing plants deploy automated dosing systems optimized for granular detoxifier forms.
Indonesia
Expanding broiler operations displace unmodified clays with yeast-derived alternatives as climate-induced mold pressures intensify across tropical feed belts. The national food and drug regulator enforces imported additive registration requirements that favor suppliers with established technical service networks. Java-based feed mill clusters represent the primary consumption concentration for bundled vitamin-detoxifier nutritional packages.
India
FSSAI and BIS dual agency review processes for imported additives extend market entry timelines and strengthen domestic supplier positions with established compliance dossiers. The national food safety regulator coordinates with BIS on certification requirements that delay foreign market access. Maharashtra and Gujarat feed manufacturing corridors concentrate procurement for zearalenone management in sow and finishing operations.
Asia-Pacific Feed Mycotoxin Detoxifiers Market Competitive Environment
Global majors compete with regional champions across technical service capabilities and multi-country registration infrastructure. The vendor base stratifies into three tiers: multinational nutrition houses with vitamin premix bundling power, fermentation specialists with captive biotransformation capacity, and mineral-focused suppliers anchored to high-purity bentonite deposits. Dominant competitive moves include geographic expansion through specialized R&D facilities and portfolio diversification into enzyme-clay hybrid formulations.
Among multinational nutrition houses, DSM Nutritional Products AG and Kemin Industries exemplify the technical service-intensive archetype, while Adisseo occupies a position representing manufacturing scale advantages. These three companies anchor the competitive landscape through differentiated approaches to formulation support, regional adaptation capabilities, and integrated production infrastructure.
| Leading Market Players |
|---|
| DSM Nutritional Products AG |
| Kemin Industries |
| Adisseo |
| AMLAN International |
| Biomin Holding |
| BASF SE |
| Land O'Lakes |
| Impextraco |
| Cargill Inc. |
| Others |
Value Chain & Pricing Dynamics
Integrated livestock procurement consolidation across Vietnam's Mekong Delta is forcing detoxifier suppliers to absorb fermentation infrastructure costs while maintaining price competitiveness against mineral alternatives, compressing margin structures throughout the value chain.
Pricing Analysis
Input-cost pass-through from high-purity bentonite mining and sterile bioreactor operations anchors a three-tier pricing structure across premium, standard, and economy levels. Certification grade under China's SAMR GB 13078 standards and volume scale differentiate price bands, with pricing pressure intensifying as yeast-derived alternatives displace clay binders in premium poultry rations. Independent feed mills in Indonesia's outer islands exhibit highest price sensitivity, while Thailand's integrated poultry houses prioritize performance validation over unit cost.
Supply Chain Analysis
High-purity aluminosilicate feedstock rests on concentrated bentonite deposits in India, China, and select Southeast Asian mining districts, while live yeast cell wall cultivation draws from fermentation facilities in India and China. Single-source vulnerability in sterile bioreactor capacity and regulatory restriction through India's FSSAI-BIS dual review process constrain supply flexibility. Distribution runs through direct technical service teams for integrated operations and regional distributor networks for fragmented secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific feed mycotoxin detoxifiers market functions as a geographic-arbitrage play where India's FSSAI-BIS registration friction creates extended market entry timelines that domestic suppliers exploit against foreign competitors facing compliance delays.
For Market Incumbents: To counter biotransformation technology displacement of clay binders, DSM Nutritional Products AG and Kemin Industries should deepen backward integration into captive yeast fermentation capacity in India while expanding multi-toxin analytical service capabilities across Vietnam's Mekong Delta integrator relationships.
For New Entrants and Emerging Players: Independent aquaculture feed mills in the Philippines' Luzon and Visayas regions represent the most penetrable buyer archetype, with diagnostic-detoxifier bundles offering a service-anchored entry point where legacy analytical infrastructure gaps persist.
For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation specialists possessing integrated biotransformation capacity and established ASEAN veterinary drug control framework registrations. Watch for harmonized maximum residue limit acceleration across ASEAN as the inflection indicator for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yeast Fermentation | Captive bioreactor capacity in India lowers unit costs for bacterial detoxifier lines against clay alternatives. |
| Multi-Toxin Analytical Service Expansion | LC-MS/MS infrastructure deployment across Vietnam's Mekong Delta secures integrator procurement decisions. |
| Enzyme-Clay Hybrid Formulation Development | Converging biotransformation and adsorption mechanisms command premium positioning in high-value dairy applications. |
| ASEAN Regulatory Harmonization Alignment | Dual registration dossiers for domestic sale and EU F-Gas Regulation export certification accelerate market access. |
| Diagnostic-Detoxifier Bundle Launch | Service-anchored entry points in Philippines' underpenetrated Luzon and Visayas markets displace pure product vendors. |
Study Parameters
Direct dialogue with feed mill procurement managers, veterinary nutritionists at integrated poultry operations, regulatory affairs specialists navigating FSSAI-BIS processes, and technical directors at fermentation facilities grounded qualitative insights. Secondary validation drew from SAMR GB standard publications, ASEAN veterinary drug control framework documentation, customs trade data on aluminosilicate imports, and SEC filings of listed nutrition houses. Bottom-up and top-down triangulation reconciled volume estimates across product type, application, and geography.
Bottom-up modeling aggregated country-level consumption patterns by livestock species density and feed manufacturing capacity, while top-down analysis calibrated aggregate market size against macro protein production trends across the projection horizon. Segmentation dimensions included product architecture (clay, yeast, bacteria, enzymes), end-use application (poultry, aquaculture, swine, ruminants), physical form, and distribution channel structure. CAGRs derived from regression analysis of historical adoption curves and regulatory enforcement intensity proxies.
Inputs from SAMR enforcement bulletins and ASEAN harmonization working papers were available through the study window; gaps in proprietary efficacy trial data from non-public supplier filings introduce uncertainty bands around biotransformation technology penetration assumptions. Forecasts reflect documented regulatory trajectories and climate-induced mold pressure projections. A small set of triggers—GB 13078 threshold revisions, EU F-Gas Regulation alignment acceleration, and FSSAI-BIS process simplification—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Feed Pigments Market
Agricultural Chemicals
Neem Extract Market
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
Seed Binders Market
Agricultural Chemicals
Thailand Feed Additives Market
Agricultural Chemicals
Global Agricultural Micronutrients Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
Strobilurin Fungicide Market
Agricultural Chemicals
North America Silage Additives Market
Agricultural Chemicals
Global Seed Colorant Market
Agricultural Chemicals
China Feed Amino Acids Market
Agricultural Chemicals
Turf and Ornamental Inputs Market
Agricultural Chemicals
Foliar Spray Market
Agricultural Chemicals
Argentina Feed Additives Market
Agricultural Chemicals
Europe Silage Additives Market
Agricultural Chemicals
Global Cattle Feed and Feed Additives Market