
 Asia-Pacific Exhaust Heat Recovery System Market | 2026-2036
Asia-Pacific Exhaust Heat Recovery System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Exhaust Heat Recovery System Market Insights
Modular skid-mounted configurations is pivoting buyer preference away from site-built installations across the Asia-Pacific Exhaust Heat Recovery System Market. Mitsubishi Heavy Industries leverages its turbine engineering heritage to dominate large-scale industrial deployments. IHI Corporation anchors its position through integrated boiler and heat exchanger packages for power utilities. Denso competes in automotive applications with compact thermoelectric modules designed for passenger vehicle integration.
Asia-Pacific exhaust heat recovery systems capture thermal energy from exhaust streams through heat exchangers, turbochargers, or organic Rankine cycle generators operating at temperatures between 150°C and 600°C, converting otherwise wasted heat into mechanical work or electricity for industrial processes and vehicle propulsion. Heat exchangers sustain the largest installed base due to proven reliability in marine and power generation settings where salt corrosion resistance determines equipment longevity. Organic Rankine cycle technology leads growth trajectory as lower-temperature industrial waste streams become economically recoverable across Southeast Asian manufacturing clusters.
China's MIIT enforces corporate average fuel consumption limits that compel automakers to integrate exhaust heat recovery into heavy commercial vehicles, while Japan's METI energy conservation standards mandate periodic efficiency audits for industrial boilers exceeding designated thermal thresholds. India's BIS certification requirements for pressure vessels create compliance barriers for imported heat exchanger assemblies. Stakeholders must monitor how Australia's TGA-equivalent pressure equipment safety regime and South Korea's MFDS industrial energy efficiency codes evolve to determine regional product standardization versus localization strategies.
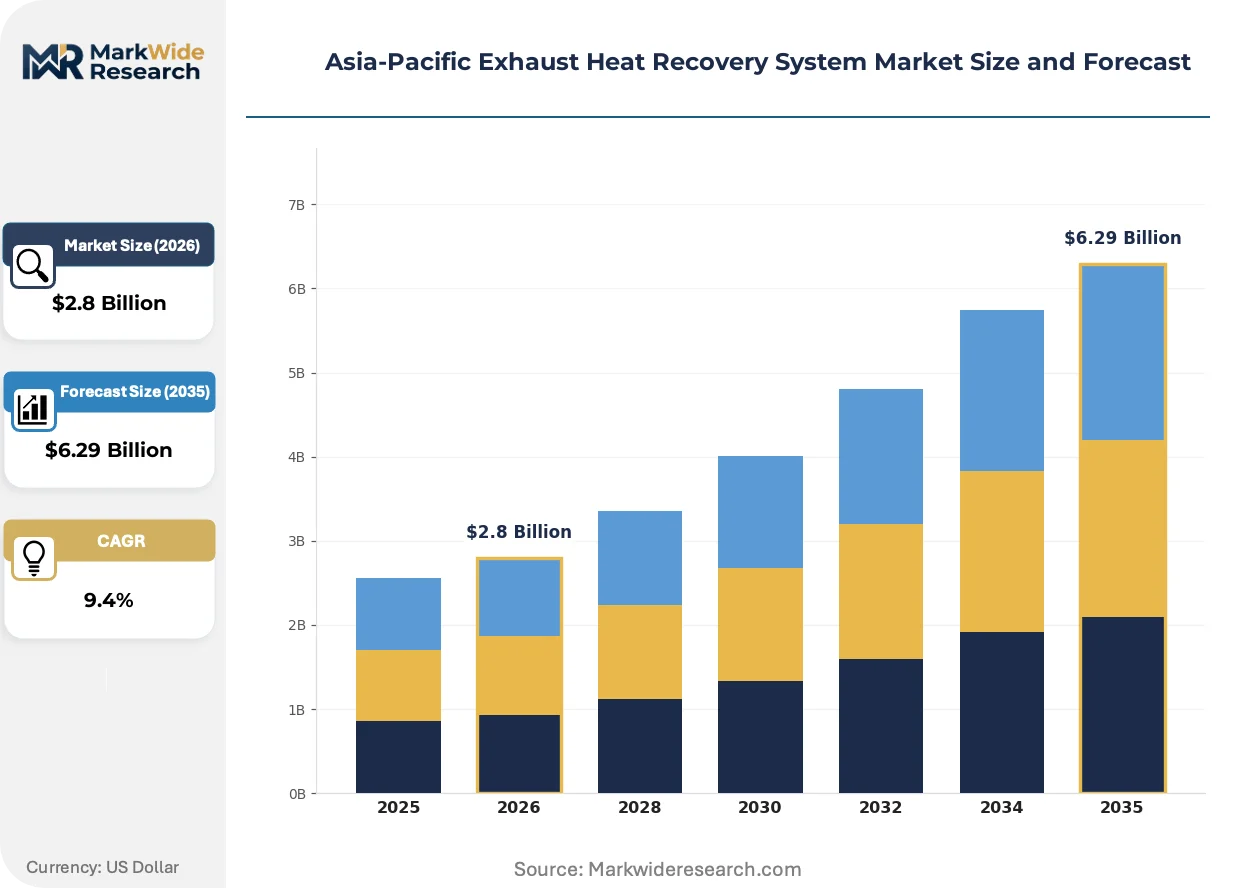
Market Dynamics
China's MIIT fuel efficiency mandates are compressing deployment timelines for exhaust heat recovery systems across heavy commercial vehicle fleets, forcing automakers to integrate thermal recovery modules ahead of original product roadmaps.
Growth Catalysts
- Japan's METI Energy Conservation Standards:Mandatory efficiency audits for industrial boilers exceeding thermal thresholds drive retrofit demand across steel and cement facilities.
- Organic Rankine cycle advancement:Lower-temperature waste stream recovery becomes economically viable for Southeast Asian manufacturing clusters operating between 150°C and 300°C.
- Jiangsu-Shandong-Guangdong industrial corridor:Concentrated heavy industry base creates scale economies for cogeneration equipment deployment.
Market Restraints
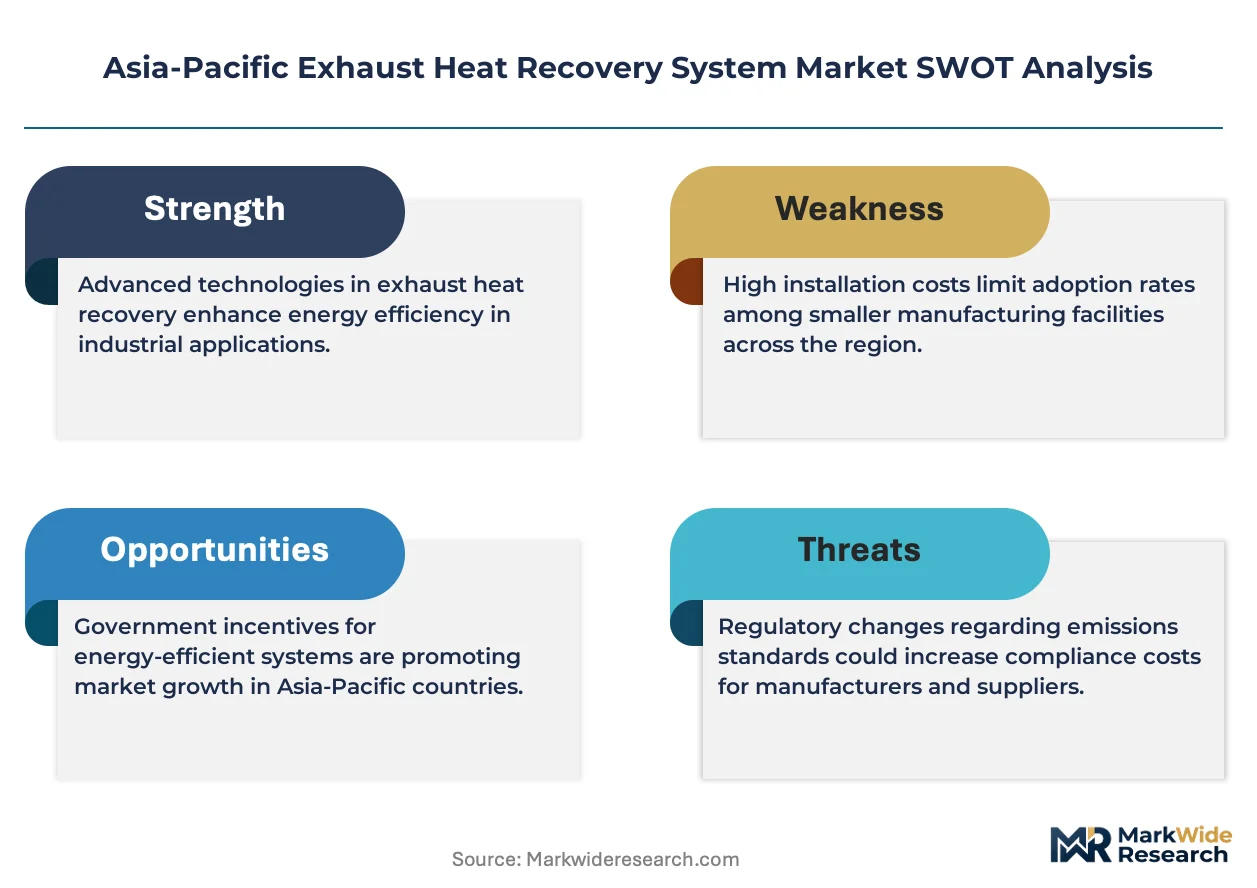
- Specialized alloy input volatility:Nickel-based heat exchanger materials face price instability from concentrated mining supply.
- India's BIS pressure vessel certification:Import compliance barriers delay foreign heat exchanger assembly market entry.
- High-temperature ceramic substitution:Advanced insulation materials reduce recoverable thermal differential in some furnace applications.
Strategic Opportunities
- Vietnam and Indonesia manufacturing expansion:Greenfield textile and food processing facilities present first-mover advantage for integrated heat recovery design.
- Australia's pressure equipment safety regime evolution:Regulatory harmonization potential with ASEAN standards reduces certification duplication costs.
- Thermoelectric-automotive convergence:Passenger vehicle integration of compact modules opens volume manufacturing scale previously reserved for heavy-duty applications.
Industry Challenges
- ORC system integration engineering:Shortage of technicians trained in organic working fluid handling and turbine synchronization.
- Legacy boiler retrofit compatibility:Custom engineering requirements extend project timelines for pre-2010 industrial installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Exhaust Heat Recovery System Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Exchangers, Turbochargers, Economizers, Condensers Application: Industrial, Power Generation, Marine, Automotive End User: Manufacturers, Utilities, Transportation, Energy Providers Technology: Steam Rankine Cycle, Organic Rankine Cycle, Thermoelectric Generators, Heat Pumps |
| Companies Covered | Mitsubishi Heavy Industries, IHI Corporation, Denso, BorgWarner, Continental, MAHLE, Tenneco, Eberspaecher, Faurecia, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Exhaust Heat Recovery System Market Trends and Innovations
Technology trajectories across the Asia-Pacific exhaust heat recovery market center on configurational flexibility, regulatory anticipation, and procurement recalibration rather than incremental efficiency gains.
Modular skid-mounted organic Rankine cycle units are modularizing project execution for Southeast Asian manufacturing facilities. Plant operators in Vietnam and Indonesia now specify containerized systems that ship complete with pre-commissioned turbines and heat exchangers. This configurational shift compresses installation timelines from months to weeks and reduces site labor dependency.
China's MIIT corporate average fuel consumption rules are tightening enforcement mechanisms for heavy commercial vehicle OEMs. Automakers now face penalties for non-compliance that exceed module integration costs, accelerating thermoelectric generator adoption in 12-ton-plus truck segments. Japanese suppliers are responding with compact designs that fit existing exhaust geometries without structural chassis modification.
Procurement patterns among Australian mining operators now emphasize performance-guaranteed service contracts over capital purchase. Equipment providers absorb operational risk through heat-recovery-as-a-service arrangements where payment ties to verified thermal output. This model transfers technology obsolescence risk from resource extractors to system integrators and concentrates vendor selection on operational track record rather than unit cost.
Asia-Pacific Exhaust Heat Recovery System Market Segmentation
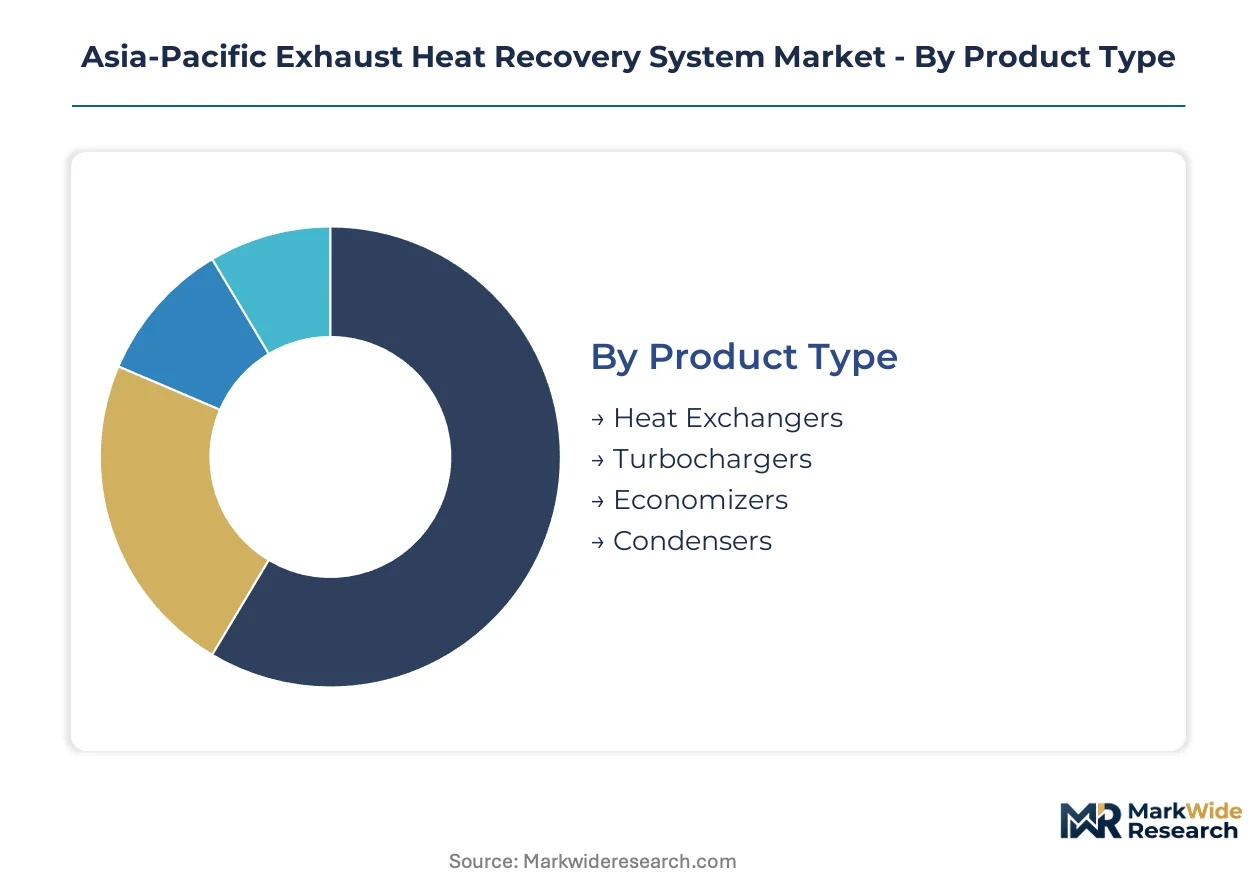
Technology configurations and application contexts determine equipment specifications across the Asia-Pacific Exhaust Heat Recovery System Market. Upgrade cycles vary sharply between heavy industrial retrofits and first-fit automotive integration, creating divergent procurement rhythms for suppliers.
Product Type:
Replacement cycles for core heat transfer equipment accelerate where China's MIIT fuel efficiency mandates force fleet-wide retrofits ahead of scheduled maintenance windows.
- Heat Exchangers:Shell-and-tube and plate-fin configurations dominate marine and power generation installations where salt corrosion resistance determines service intervals. Steel mills across China's Jiangsu corridor specify nickel-alloy variants to withstand sulfur-laden exhaust streams above 400°C.
- Turbochargers:Variable-geometry turbine designs extract mechanical work from high-velocity exhaust flows in heavy commercial vehicles. India's expanding truck manufacturing base drives demand for compact units that integrate with existing engine architectures without structural modification.
- Economizers:Pre-heat boiler feedwater using residual flue gas temperatures between 150°C and 250°C. Cement plants in Shandong province deploy these as lowest-cost entry points into waste heat recovery.
- Condensers:Surface and air-cooled designs complete organic Rankine cycle loops by returning working fluid to liquid phase. Southeast Asian textile processors favor these for low-temperature industrial streams.
Volume placements concentrate in Heat Exchangers; the faster expansion belongs to Turbochargers.
Application:
Cost tiers separate project-scale deployments from mass-manufactured vehicle integration, with margins compressing fastest where standardization permits.
- Industrial:Steel, cement, and chemical facilities retrofit cogeneration equipment to meet Japan's METI energy audit requirements. Custom engineering for legacy furnace integration extends sales cycles but sustains premium pricing.
- Automotive:Thermoelectric modules and turbo-compounding systems address corporate average fuel consumption rules for heavy commercial vehicles. Japanese suppliers dominate compact designs that fit existing exhaust geometries.
- Power Generation:Combined-cycle plants and waste-to-energy facilities deploy large-scale organic Rankine cycle units. Australia's mining sector increasingly procures through performance-guaranteed service contracts rather than capital purchase.
- Marine:Slow-speed diesel engines on cargo vessels integrate exhaust gas boilers to generate auxiliary power. Singapore and Busan shipyards specify corrosion-resistant heat exchanger materials for salt-air environments.
Revenue concentration sits with Industrial applications; Automotive integration climbs the fastest.
End User:
Customer sophistication determines specification depth, with energy providers demanding integrated performance guarantees that manufacturers resist.
- Manufacturers:Steel, cement, and chemical producers operate captive power systems where waste heat recovery reduces grid dependency. These buyers prioritize equipment reliability over capital cost minimization.
- Utilities:Power generators and district heating operators procure multi-megawatt organic Rankine cycle installations. Procurement teams emphasize heat rate improvements and carbon intensity reductions in vendor evaluation.
- Transportation:Fleet operators and commercial vehicle OEMs face regulatory compliance deadlines that compress integration timelines. Module standardization becomes critical where chassis modifications are prohibited.
- Energy Providers:Independent power producers and renewable energy developers seek turnkey waste heat recovery solutions. These customers transfer operational risk to equipment suppliers through output-based contracting structures.
Contract volumes cluster with Manufacturers; Energy Providers are expanding most quickly.
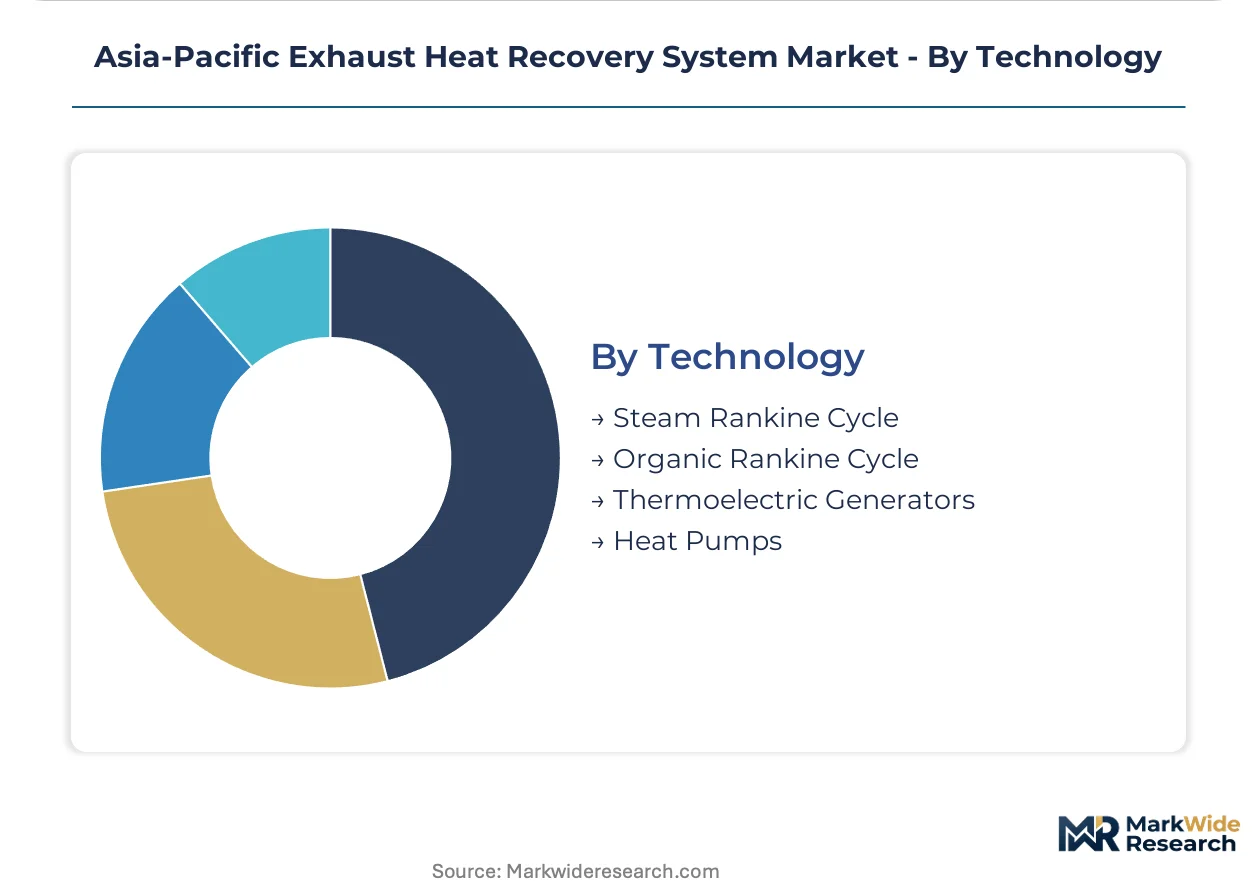
Technology:
Maturity curves separate proven thermal cycles from emerging solid-state conversion, with training infrastructure lagging adoption in frontier segments.
- Organic Rankine Cycle:Low-temperature working fluids enable economic recovery from industrial waste streams between 150°C and 300°C previously considered unviable. Southeast Asian manufacturing clusters adopt containerized, skid-mounted configurations to reduce installation complexity.
- Steam Rankine Cycle:High-temperature applications above 400°C in steel and cement production rely on water-based working fluids and established turbine engineering. Chinese industrial corridors represent the largest installed base.
- Thermoelectric Generators:Solid-state semiconductor modules convert thermal gradients directly to electricity without moving parts. Compact designs suit automotive applications where vibration tolerance and maintenance elimination matter.
- Heat Pumps:Mechanical vapor compression upgrades low-grade waste heat to process-usable temperatures. Food processing and textile facilities in Vietnam and Indonesia specify these for drying and sterilization applications.
Deployment scale favors Steam Rankine Cycle; Organic Rankine Cycle gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of exhaust heat recovery equipment for Asia-Pacific deployment while Japan and South Korea absorb premium-tier imports for automotive integration. Domestic consumption concentrates in heavy industrial corridors where steel, cement, and chemical facilities retrofit cogeneration assets under tightening efficiency mandates.
China
Heavy-duty truck fleets and steel plants drive equipment demand across Jiangsu, Shandong, and Guangdong provinces. MIIT corporate average fuel consumption rules compel automakers to integrate thermal recovery modules ahead of original product roadmaps. The Jiangsu-Shandong-Guangdong industrial corridor hosts concentrated cogeneration retrofits as cement and steel producers face emissions intensity targets.
Japan
Automotive thermoelectric applications and industrial boiler efficiency upgrades anchor domestic demand. METI energy conservation standards mandate periodic efficiency audits for industrial boilers exceeding designated thermal thresholds. Kanto and Kansai manufacturing belts deploy compact heat recovery systems to meet facility-level carbon reduction commitments.
India
Expanding heavy commercial vehicle manufacturing and captive power installations in steel plants create dual demand streams. BIS certification requirements for pressure vessels create compliance barriers for imported heat exchanger assemblies. Maharashtra and Gujarat industrial zones see accelerated waste heat recovery adoption as cement producers seek grid independence.
South Korea
Shipbuilding and power utility sectors procure large-scale organic Rankine cycle installations for auxiliary power generation. MFDS industrial energy efficiency codes govern equipment specifications for manufacturing facility retrofits. Busan shipyards specify corrosion-resistant heat exchanger materials for salt-air marine environments.
Australia
Mining operators increasingly procure through performance-guaranteed service contracts rather than capital purchase. The country's pressure equipment safety regime evolves toward potential harmonization with ASEAN standards. Western Australia mining corridors transfer technology obsolescence risk to system integrators through heat-recovery-as-a-service arrangements.
Asia-Pacific Exhaust Heat Recovery System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers. Tier-one suppliers leverage turbine engineering heritage and integrated boiler packages to dominate large-scale industrial deployments. Mid-tier automotive specialists concentrate on compact module designs for regulatory-driven vehicle integration. Dominant competitive moves include strategic partnerships for organic Rankine cycle working fluid supply and geographic expansion through skid-mounted containerized configurations.
Among Japan-based industrial conglomerates, Mitsubishi Heavy Industries and IHI Corporation exemplify the diversified engineering archetype with positions spanning power generation and heavy manufacturing equipment. Denso occupies a position within the automotive-focused tier, representing compact thermoelectric module specialization for passenger and commercial vehicle integration. These three anchors illustrate the geographic clustering of competitive capability within Northeast Asian industrial centers.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| IHI Corporation |
| Denso |
| BorgWarner |
| Continental |
| MAHLE |
| Tenneco |
| Eberspaecher |
| Faurecia |
| Others |
Pricing and Supply Chain Analysis
Performance-grade certification divergence between MIIT-compliant heavy commercial vehicle modules and uncertified industrial heat exchanger assemblies manifests in pricing power concentration among Japanese automotive suppliers and supply chain fragmentation across Chinese boiler manufacturers. This bifurcation rewards integrated turbine-to-heat-exchanger producers while pressuring commodity fabricators facing nickel-alloy input volatility.
Pricing Analysis
Cost-down pressure on standard-grade economizers accelerates because Indonesian and Vietnamese textile processors prioritize capital cost minimization over efficiency guarantees. Project-based contracting dominates industrial deployments where customization requirements prevent commoditization, while automotive thermoelectric modules command premium positioning through MIIT fuel efficiency compliance certification. Price differentiation separates nickel-alloy heat exchanger variants specified by Jiangsu steel mills from carbon-steel alternatives in Southeast Asian cement plants. Fleet operators exhibit highest price sensitivity where chassis modification prohibitions force module standardization, whereas Australian mining operators demonstrate lowest sensitivity through heat-recovery-as-a-service arrangements that transfer operational risk.
Supply Chain Analysis
Regional distribution centers in Shanghai, Busan, and Singapore anchor hub-and-spoke patterns for Southeast Asian manufacturing clusters seeking compressed installation timelines. Manufacturing concentration in China, Japan, and South Korea supplies turbine engineering, heat exchanger fabrication, and compact thermoelectric module production respectively. Raw material dependencies center on nickel-based alloys for high-temperature corrosion resistance, organic working fluids for Rankine cycle systems, and semiconductor materials for thermoelectric generators. Single-source vulnerability in nickel mining supply from Indonesia and the Philippines creates input price instability. Distribution runs through skid-mounted containerized configurations that reduce site labor dependency and accelerate deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where captive control over organic working fluid supply and turbine synchronization capabilities determines margin capture. Players pursuing backward integration into specialized alloy processing secure input cost stability against nickel price volatility.
For Market Incumbents: Anticipate ceramic insulation substitution threats in furnace applications by deepening heat pump and low-temperature Rankine cycle portfolios. Defensive consolidation through organic working fluid supply partnerships with chemical producers locks in formulation expertise that emerging competitors cannot replicate. Capacity addition in Vietnam and Indonesia manufacturing corridors captures greenfield textile and food processing demand before local fabrication competitors mature.
For New Entrants and Emerging Players: Engineering procurement construction contractors represent the most accessible channel partners for penetrating Australia's mining sector where performance-guaranteed service contracts concentrate vendor selection on operational track record. White-space targets include Vietnam and Indonesia greenfield facilities specifying containerized skid-mounted configurations, plus India's heavy commercial vehicle aftermarket where BIS certification barriers delay foreign assembly entry. Go-to-market positioning as ORC system integration specialists addresses technician shortage constraints that extend legacy boiler retrofit timelines.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated turbine-to-heat-exchanger specialists given METI audit mandate expansion across Japanese steel and cement facilities. Long-term viability over a multi-year horizon favors producers with demonstrated salt corrosion resistance in marine applications and containerized configuration capabilities for Southeast Asian deployment. Acquisition target archetypes include compact thermoelectric module designers with existing exhaust geometry integration and regional distribution infrastructure in Busan or Singapore. Signal to monitor: harmonization progress between Australia's pressure equipment safety regime and ASEAN standards that would reduce certification duplication costs and accelerate vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel-Alloy Processing | Captive supply of corrosion-resistant materials insulates margin from Indonesian mining price volatility. |
| Organic Working Fluid Supply Partnership | Formulation expertise lock-in creates switching costs for Southeast Asian Rankine cycle adopters. |
| Containerized Skid-Mounted Configuration Expansion | Pre-commissioned turbine and heat exchanger packages compress Vietnamese installation timelines from months to weeks. |
| Performance-Guaranteed Service Contract Model | Heat-recovery-as-a-service transfers technology obsolescence risk from Australian mining operators to integrators. |
| Thermoelectric-Automotive Convergence Investment | Compact module designs for 12-ton-plus truck segments capture MIIT compliance-driven demand acceleration. |
Research Methodology
Multi-period observation of MIIT fuel efficiency mandate enforcement patterns, METI audit completion rates, and BIS certification processing timelines anchored the trend analysis, supplemented by interviews with plant engineers at Jiangsu steel facilities, procurement leads at Australian mining operators, automotive platform engineers at Japanese OEMs, and aftermarket service heads at Indian truck fleet operators. Secondary validation drew from MIIT corporate average fuel consumption filings, METI energy conservation standard audit reports, BIS pressure vessel certification databases, and customs trade data on heat exchanger assembly imports. Bottom-up equipment shipment tracking and top-down industrial energy efficiency spending estimates were triangulated to constrain forecast variance.
Segment-weighting across product type, application, end user, and technology dimensions informed the analytical framework over the projection horizon. Heat exchanger replacement cycles, turbocharger adoption curves in Indian truck manufacturing, organic Rankine cycle working fluid cost trajectories, and thermoelectric module automotive integration rates constituted industry-specific forecast inputs. CAGRs were derived from installed base evolution modeling and regulatory mandate compliance deadline impacts.
Caveats apply where nickel price volatility, ceramic insulation substitution rates, or technician training infrastructure development could materially shift the outlook. Forecasts reflect documented assumptions regarding MIIT enforcement consistency, METI audit expansion scope, and ASEAN regulatory harmonization progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Heat Meter Market
Energy Management
Electric Sub-Meter Market
Energy Management
Smart Energy Solutions Market
Energy Management
Europe Exhaust Heat Recovery System Market
Energy Management
Thermostat Market
Energy Management
European Building Energy Management Systems Market
Energy Management
Middle-East and Africa Demand Response Management Systems Market
Energy Management
Testing, Inspection, and Certification (TIC) in the Energy and Power Market
Energy Management
Energy Security Market
Energy Management
APAC Building Energy Management Systems Market
Energy Management
Energy Harvesting System Market
Energy Management
Global Utility Asset Management Market
Energy Management
Energy ESO Market
Energy Management
Power SCADA Market
Energy Management
Electric Service Companies (Escos) Market
Energy Management
Connected Energy Market