
 Energy Harvesting System Market | 2026-2036
Energy Harvesting System Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Harvesting System Market Analysis
Modular sensor-to-gateway bundling is expanding as industrial buyers seek turnkey energy harvesting kits rather than discrete components. STMicroelectronics leverages its MEMS fabrication scale to dominate piezoelectric transducer supply. Texas Instruments anchors its position through integrated power management ICs that condition harvested micro-watts into stable outputs. EnOcean GmbH differentiates via proprietary wireless protocols purpose-built for battery-free building automation networks.
An energy harvesting system captures ambient mechanical, thermal, electromagnetic, or radiant energy and converts it into usable electrical power through transducers, rectifiers, and storage buffers, typically generating milliwatts to watts for distributed electronics. These systems eliminate battery replacement cycles in remote or inaccessible installations. Solar photovoltaic modules lead the type category due to mature silicon supply chains and declining panel costs, while piezoelectric technology represents the fastest-growing segment as MEMS manufacturing scales reduce unit economics for vibration-powered industrial sensors. Thermal harvesting occupies a specialized margin pool in aerospace and process industries where extreme temperature differentials persist.
The EU Ecodesign Directive and REACH substance restrictions shape component material selection and recyclability requirements for European deployments. The US FCC regulates radio-frequency emissions from wireless energy harvesting transmitters, directly constraining product architecture and antenna design choices. China's GB standards and dual carbon goals mandate efficiency benchmarks that filter market access for imported harvester modules. Stakeholders must monitor evolving interoperability standards between energy harvesting platforms and emerging low-power wide-area networks.
Market Dynamics
Industrial automation clusters in Germany are forcing rapid standardization of battery-free sensor networks, compressing procurement cycles from component sourcing to integrated system deployment.
Growth Catalysts
- EU Green Deal mandates:Battery efficiency standards under the Ecodesign Directive accelerate replacement of conventional power sources with ambient energy harvesters in building automation systems.
- MEMS manufacturing scale:Piezoelectric transducer production economics improve as semiconductor foundries apply silicon wafer processing to vibration-powered industrial sensors.
- Smart factory sensor density:Industrial IoT deployments in automotive and electronics manufacturing create sustained pull for self-powered wireless nodes eliminating maintenance cycles.
Market Restraints
- Silicon supply concentration:Photovoltaic cell production clusters in China create input vulnerability for solar harvester module assemblers elsewhere.
- Power output variability:Ambient source intermittency limits thermal and piezoelectric systems to supplementary rather than primary power roles in critical applications.
- REACH substance compliance:European material restrictions constrain lead-zirconate-titanate formulations in high-performance piezoelectric ceramics.
Strategic Opportunities
- India industrial corridors:PLI scheme incentives for electronics manufacturing create greenfield demand for energy-autonomous condition monitoring in new plant construction.
- LPWAN protocol convergence:Interoperability between EnOcean wireless standards and emerging low-power wide-area networks opens utility-scale smart grid deployments.
- Aerospace thermal harvesting:Extreme temperature differentials in jet engine monitoring applications offer premium-margin specialization beyond commoditized solar modules.
Industry Challenges
- Multi-physics simulation talent:Scarcity of engineers combining electromechanical transducer design with RF power management constrains product development velocity.
- FCC certification timelines:Radio-frequency emission testing for wireless energy harvesting transmitters extends time-to-market for novel antenna architectures.
- Legacy building system integration:Battery-free retrofits require custom mechanical interfaces to existing HVAC and lighting control infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Harvesting System Market |
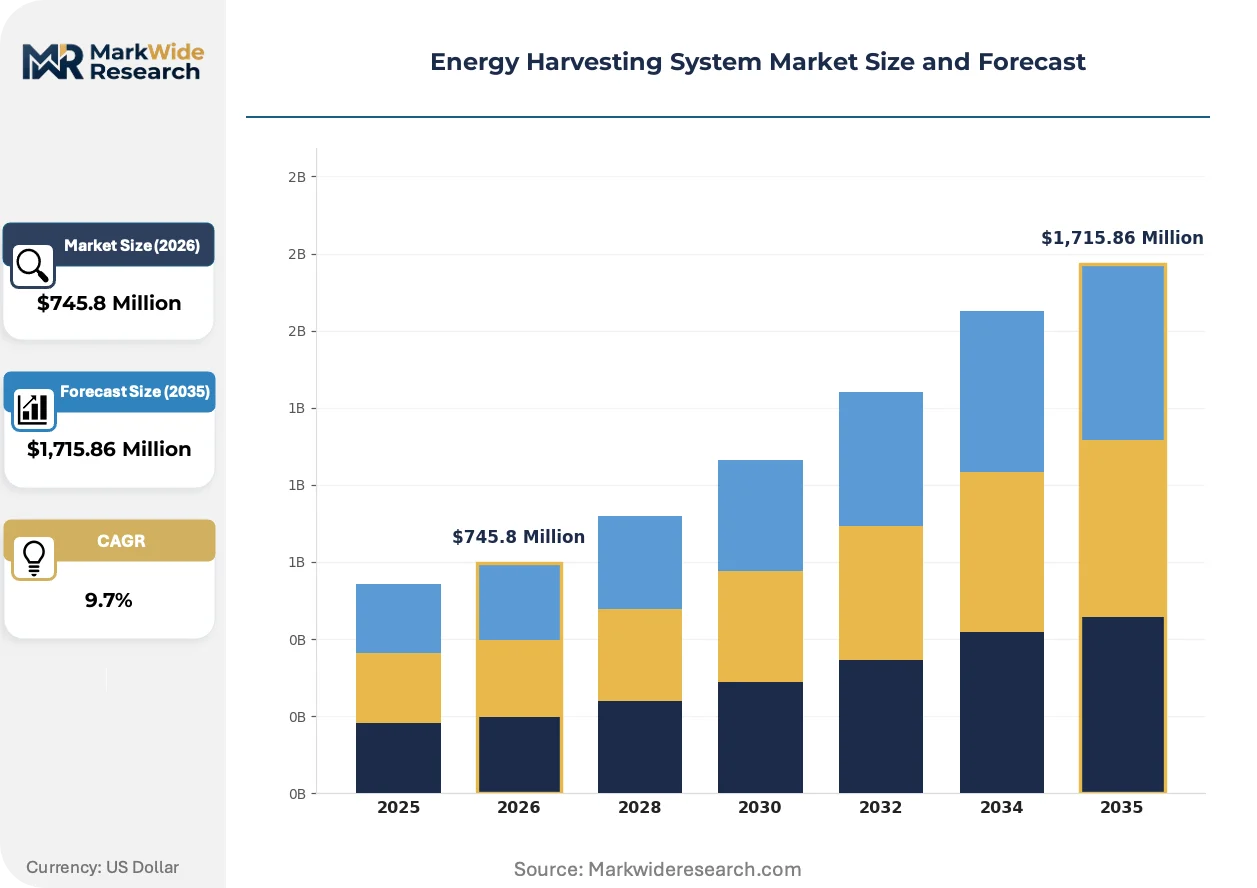
| Market Size in 2026 | $745.8 Million |
| Market Size in 2035 | $1,715.86 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Mechanical, Thermal, Solar, Electromagnetic End User: Industrial, Consumer Electronics, Automotive, Smart Homes Technology: Piezoelectric, Thermoelectric, Photovoltaic, RFID Application: Wearable Devices, Wireless Sensor Networks, IoT Devices, Energy Storage |
| Companies Covered | Microchip Technology, EnOcean GmbH, STMicroelectronics, Schneider Electric, ABB, Texas Instruments, Infineon Technologies, Powercast Corporation, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Harvesting System Market Emerging Trajectories
Technology convergence between microelectromechanical fabrication and wireless power management is compressing the traditional boundaries between energy generation, storage, and transmission hardware.
Perovskite-enhanced photovoltaic layers are consolidating the performance gap between rigid silicon panels and flexible thin-film harvesters for curved industrial surfaces. Automotive tier-one suppliers adopt these formulations for vehicle-integrated solar applications where aerodynamic constraints prohibit conventional module mounting. The technology is consolidating supplier tiers as chemical firms and semiconductor equipment makers enter territory previously held by dedicated solar cell manufacturers.
REACH substance restrictions and RoHS recast directives are forcing reformulation of piezoelectric ceramics across European supply chains. Industrial sensor manufacturers face material qualification delays as they substitute bismuth-based compositions for legacy lead-containing formulations. Germany's building automation sector absorbs these compliance costs fastest due to proximity to EnOcean protocol development resources and regional chemical R&D clusters.
Turnkey sensor-to-gateway bundling now dominates industrial procurement as buyers reject discrete component integration risk. System integrators in automotive and electronics manufacturing displace traditional distributor relationships with direct vendor-managed inventory agreements. This pattern concentrates most visibly in Baden-Württemberg automation corridors where factory engineering teams lack bandwidth for multi-vendor power subsystem validation.
Energy Harvesting System Market Segmentation
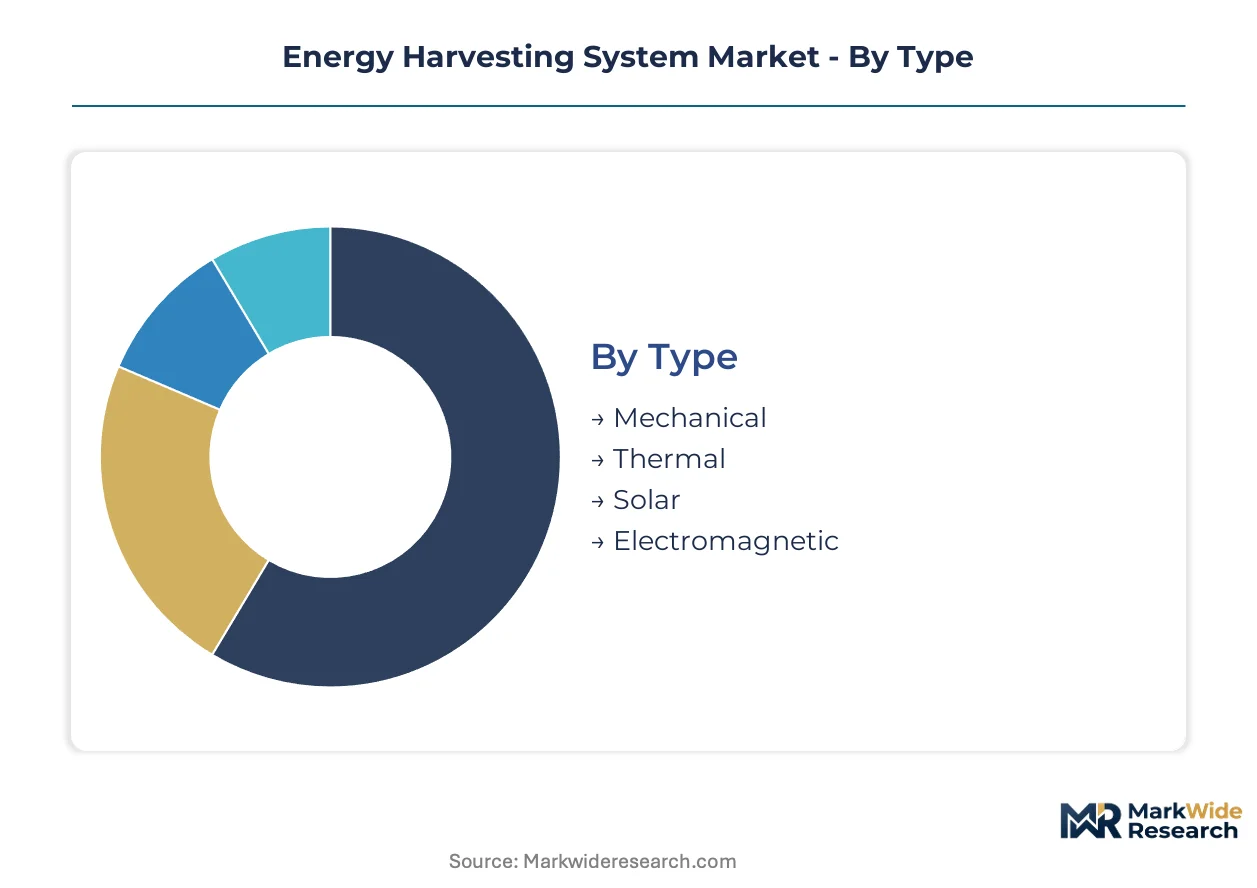
Energy harvesting system buyers face divergent capital requirements across transducer technologies and end-use applications. Procurement patterns split between high-volume solar deployments and specialized thermal installations for aerospace monitoring. Component selection directly determines integration complexity and total cost of ownership for autonomous power architectures.
Type:
Solar photovoltaic modules demand the heaviest upfront capital outlay due to silicon wafer processing infrastructure and panel mounting systems. Mechanical harvesters require moderate tooling investment for piezoelectric ceramic fabrication. Thermal and electromagnetic variants occupy lower capital tiers with specialized but narrower equipment needs.
- Solar:Silicon photovoltaic cells convert ambient light through mature p-n junction architectures. German automotive manufacturing clusters and Bavarian building automation projects absorb the majority of module shipments, driven by EU Green Deal efficiency mandates and rooftop integration subsidies.
- Mechanical:Piezoelectric transducers transform kinetic vibration into electrical charge via lead-zirconate-titanate or bismuth-based ceramic formulations. Industrial condition monitoring in Stuttgart automation corridors and vibration-heavy process equipment drives procurement volumes.
- Thermal:Thermoelectric generators exploit Seebeck effect temperature differentials across semiconductor junctions. Aerospace engine monitoring and chemical process industries in the Rhine-Ruhr region concentrate specialized demand.
- Electromagnetic:Inductive coils capture ambient radio-frequency or kinetic energy through Faraday principle architectures. Low-power RFID infrastructure and wireless charging pads in logistics hubs represent primary deployment zones.
Solar absorbs the bulk of installed capacity; mechanical harvesting is expanding most quickly.
End User:
Industrial buyers dominate procurement volumes with factory-wide sensor network deployments. Consumer electronics and smart home segments operate at lower unit values but higher shipment frequencies. Automotive applications command premium pricing for vehicle-integrated power systems.
- Industrial:Factory automation networks deploy battery-free sensors for predictive maintenance and environmental monitoring. Baden-Württemberg manufacturing clusters and Saxony electronics plants anchor European demand.
- Automotive:Tire pressure monitoring, keyless entry systems, and interior climate sensors integrate micro-harvesters for cable elimination. Tier-one suppliers in Stuttgart and Wolfsburg specify vibration-powered modules.
- Smart Homes:Building automation controllers, wireless light switches, and HVAC sensors eliminate battery maintenance through EnOcean protocol networks. German residential retrofit programs and new construction in Hamburg drive adoption.
- Consumer Electronics:Wearable fitness trackers and wireless earbuds incorporate kinetic and thermal harvesting for charging reduction. Design constraints limit harvester size and power output in this segment.
Industrial deployments command the largest revenue share; smart home installations are climbing the fastest.
Technology:
Piezoelectric fabrication requires semiconductor foundry access and ceramic sintering equipment. Photovoltaic production scales through silicon supply chain integration. Thermoelectric and RFID technologies operate with narrower supplier bases and specialized material requirements.
- Piezoelectric:MEMS-scale cantilevers and bulk ceramics generate micro-watts from mechanical strain. REACH substance restrictions in Europe and MEMS manufacturing scale improvements are reshaping material selection and unit economics.
- Photovoltaic:Crystalline silicon and emerging perovskite layers capture radiant energy across indoor and outdoor spectra. Perovskite-enhanced formulations are consolidating flexible thin-film applications for curved industrial surfaces.
- Thermoelectric:Bismuth telluride and skutterudite compounds convert temperature gradients with 5-8% conversion efficiency. Jet engine monitoring and chemical process control in extreme thermal environments sustain niche demand.
- RFID:Passive backscatter and semi-passive tag architectures harvest interrogator radio energy for data transmission. Logistics tracking and retail inventory systems in Duisburg port operations deploy high volumes.
Photovoltaic technology holds the greatest installed base; piezoelectric systems are gaining share fastest.
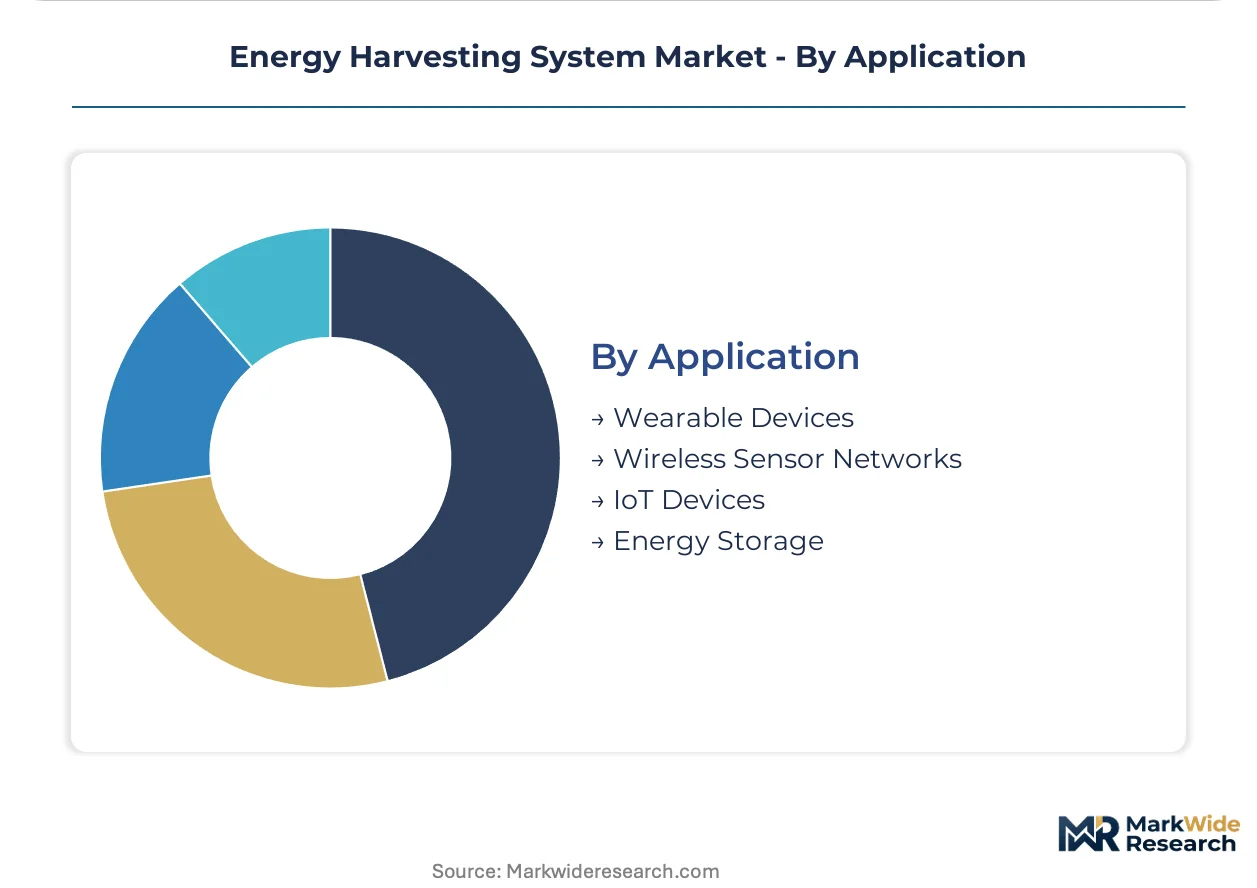
Application:
Wireless sensor networks require the most extensive site preparation and gateway infrastructure investment. Wearable devices and IoT endpoints concentrate on miniaturization and power management integration. Energy storage applications demand coupling with supercapacitors or thin-film batteries.
- Wireless Sensor Networks:Distributed nodes monitor vibration, temperature, and humidity across factory floors and building systems. German industrial automation corridors and EnOcean protocol deployments anchor regional specialization.
- Wearable Devices:Kinetic harvesters in footwear and thermal harvesters in wrist-worn form factors supplement primary batteries. Fitness and medical monitoring segments in Munich and Berlin drive design requirements.
- IoT Devices:Smart agriculture soil sensors, structural health monitors, and asset trackers eliminate field maintenance through ambient harvesting. Agricultural deployments in Lower Saxony and infrastructure monitoring in Cologne concentrate demand.
- Energy Storage:Hybrid architectures combine harvesters with supercapacitors or solid-state batteries for load leveling. Grid-edge applications and backup power systems in industrial microgrids represent emerging use cases.
Wireless sensor networks absorb the bulk of deployed units; wearable applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates photovoltaic cell fabrication while Germany absorbs the highest-value industrial deployments. Japan and South Korea concentrate MEMS-scale piezoelectric production. The United States leads in RF harvesting intellectual property and aerospace thermal applications.
Germany
Baden-Württemberg automotive clusters and Bavarian building automation networks drive battery-free sensor procurement. The EU Ecodesign Directive and REACH substance restrictions force rapid material reformulation in piezoelectric ceramics. EnOcean protocol development in Oberhaching anchors proprietary wireless standards for industrial IoT.
China
Silicon wafer processing infrastructure in Jiangsu and Zhejiang provinces supplies cost-competitive photovoltaic modules globally. GB standards and dual carbon goals under MIIT oversight mandate efficiency benchmarks for imported harvester certification. Yangtze River Delta electronics manufacturing corridors integrate energy-autonomous sensors into smart factory retrofits.
United States
Aerospace thermal harvesting for jet engine monitoring and FCC-regulated RF power transmission shape specialized demand. The Inflation Reduction Act provisions accelerate building automation efficiency upgrades in commercial real estate. Greater Boston and Pacific Northwest industrial corridors deploy vibration-powered condition monitoring in precision manufacturing.
Japan
METI-funded smart factory initiatives and JIS standardization for industrial wireless sensors concentrate procurement in Kanto and Kansai regions. MEMS foundry scale in Chubu-Nagoya reduces unit economics for piezoelectric transducers. Automotive tier-one suppliers in Toyota City specify kinetic harvesters for tire pressure and keyless entry systems.
South Korea
Seoul Capital Area electronics conglomerates integrate energy harvesting into consumer wearable form factors. The national renewable energy portfolio standards create pull for building-integrated photovoltaic modules. Daegu-Gyeongbuk industrial zones deploy self-powered environmental sensors in chemical process monitoring.
Energy Harvesting System Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across transducer fabrication and power management integration. The vendor base stratifies into three tiers: semiconductor giants leveraging MEMS scale, industrial automation incumbents bundling harvesters into building systems, and RF protocol specialists defending proprietary wireless standards. Consolidation pressure intensifies as turnkey sensor-to-gateway procurement displaces discrete component sourcing. Dominant competitive moves include backward integration into ceramic material supply and strategic partnerships with LPWAN infrastructure providers.
Among European protocol specialists, EnOcean GmbH anchors proprietary wireless standards purpose-built for battery-free automation networks. STMicroelectronics and Texas Instruments exemplify semiconductor-scale players conditioning harvested micro-watts through integrated power management architectures. These three entities represent the dominant archetypes: protocol-locked specialists, MEMS fabrication leaders, and analog power management integrators.
| Leading Market Players |
|---|
| Microchip Technology |
| EnOcean GmbH |
| STMicroelectronics |
| Schneider Electric |
| ABB |
| Texas Instruments |
| Infineon Technologies |
| Powercast Corporation |
| Analog Devices |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up MEMS fabrication specialists concentrate pricing power through captive silicon wafer processing, while REACH compliance costs and photovoltaic panel commoditization squeeze margin structures across European and Asian supply bases.
Pricing Analysis
Margin tightening in standard-grade photovoltaic modules reflects Jiangsu province silicon oversupply and aggressive Chinese export pricing. Three-tier pricing structure across premium aerospace thermal systems, standard industrial sensor kits, and economy-grade RFID tags separates EnOcean protocol-certified bundles from unbranded alternatives. Cost-down pressure on piezoelectric ceramics accelerates because bismuth-based REACH-compliant formulations command 15-20% raw material premiums over legacy lead-zirconate-titanate. Industrial automation buyers in Baden-Württemberg exhibit lowest price sensitivity due to maintenance-avoidance value, while smart home distributors in Hamburg face intense margin compression from turnkey bundling demands.
Supply Chain Analysis
Photovoltaic cell supply rests on Jiangsu and Zhejiang province wafer foundries, South Korean MEMS-scale piezoelectric foundries in Chubu-Nagoya, and German ceramic sintering specialists in Saxony. Critical inputs span polysilicon ingots, bismuth telluride thermoelectric compounds, and lead-free piezoelectric powders. Single-source vulnerability concentrates in Chinese silicon purification capacity, where export license volatility threatens module assemblers in Stuttgart and Wolfsburg. Distribution runs through EnOcean-certified system integrators in German automation corridors, direct vendor-managed inventory agreements with automotive tier-ones, and electronics distributor networks serving smart factory retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign Directive and REACH substance restrictions erect a cost-of-compliance moat that favors incumbents with qualified material supply chains and protocol certification investments, filtering out undercapitalized entrants lacking European regulatory infrastructure.
For Market Incumbents: Anchor proprietary wireless protocol positions through deeper EnOcean standard integration and backward integration into bismuth-based ceramic supply. Defend against MEMS-scale Chinese entrants by accelerating REACH-qualified material qualification timelines and locking automotive tier-ones into multi-year vendor-managed inventory agreements in Stuttgart corridors.
For New Entrants and Emerging Players: Industrial system integrators represent the most accessible channel wedge for battery-free sensor kits lacking brand recognition. Target India's PLI-subsidized electronics manufacturing corridors in Tamil Nadu and Karnataka, where greenfield plant construction lacks incumbent supplier relationships and demands turnkey energy-autonomous condition monitoring solutions.
For Investors and Strategic Acquirers: Distressed-cycle entries favor MEMS fabrication specialists with qualified European material supply and automotive certification pipelines in Saxony and Bavaria. Long-term viability hinges on protocol convergence plays bridging EnOcean wireless standards with emerging LPWAN infrastructure. Watch for MIIT efficiency benchmark tightening as the signal for Chinese import filtration intensifying and compressing margins for non-compliant module assemblers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Supply | Captive bismuth-based powder production secures REACH compliance margins against raw material volatility. |
| LPWAN Protocol Convergence Partnership | EnOcean standard integration with emerging wide-area networks unlocks utility-scale smart grid deployments. |
| Perovskite Photovoltaic Layer Licensing | Chemical firm entry into flexible thin-film applications consolidates supplier tiers beyond dedicated solar manufacturers. |
| India PLI Corridor Manufacturing Scale-Up | Tamil Nadu electronics manufacturing zones absorb turnkey energy-autonomous sensor demand from greenfield construction. |
| Aerospace Thermal Harvesting Specialization | Jet engine monitoring applications in Rhine-Ruhr chemical corridors sustain premium-margin positioning beyond commoditized solar. |
Methodological Framework
Document review covered EU Ecodesign Directive implementation guidance, MIIT GB standard efficiency benchmarks, and FCC RF emission testing protocols, complemented by interviews with MEMS fabrication engineering directors, industrial automation procurement leads in Baden-Württemberg, building automation system integrators, and EnOcean protocol development specialists. Secondary validation drew from customs trade data, SEC semiconductor equipment filings, and automotive tier-one supplier disclosures. Bottom-up sensor deployment unit estimates triangulated against top-down industrial IoT infrastructure spending projections.
Historical capacity utilization patterns cross-referenced against expert panel input on MEMS manufacturing scale economics and REACH material qualification timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include transducer technology type, end-user industry vertical, application architecture, and regional regulatory cluster. CAGRs derived from unit shipment trajectories and average selling price compression curves, with specific inputs from photovoltaic silicon spot price volatility and piezoelectric ceramic formulation cost transitions.
Several conditions sit outside the modeled scope, including unforeseen tariff escalations on Chinese silicon wafers, abrupt REACH substance list expansions, and LPWAN protocol standard fragmentation. Forecasts reflect documented assumptions on MEMS foundry capacity expansion and automotive electrification sensor content growth. A small set of named triggers warrants ongoing watch: MIIT import certification delays, FCC RF testing backlog accumulation, and perovskite photovoltaic layer commercialization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Europe Exhaust Heat Recovery System Market
Energy Management
APAC Building Energy Management Systems Market
Energy Management
Electric Sub-Meter Market
Energy Management
Demand Response Management System Market
Energy Management
Australia Energy-As-A-Service Market
Energy Management
Smart Power Management Market
Energy Management
Solar Panel Monitoring System Market
Energy Management
Smart Power Technologies Market
Energy Management
APAC Energy Management Systems (EMS) Market
Energy Management
Electric Service Companies (Escos) Market
Energy Management
Testing, Inspection, and Certification (TIC) in the Energy and Power Market
Energy Management
Middle-East and Africa Demand Response Management Systems Market
Energy Management
Connected Energy Market
Energy Management
Energy ESO Market
Energy Management
Brazil Energy Sector Market
Energy Management
Industrial Energy Management System Market