
 Electric Sub-Meter Market | 2026-2036
Electric Sub-Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Sub-Meter Market Intelligence
Utility procurement channels across Europe is reconfiguring how electric sub-meter vendors reach end customers. Schneider Electric leverages its integrated building management portfolio to dominate large commercial deployments. Siemens anchors its position through deep relationships with German industrial conglomerates seeking ISO 50001-compliant energy tracking. Kamstrup competes in the Nordic district heating crossover segment where thermal and electric sub-metering converge.
An electric sub-meter is a secondary metering device installed downstream from a utility's primary meter to measure consumption at specific circuits, floors, or equipment clusters with accuracy classes typically spanning 0.5 to 2.0. These devices enable load profiling, tenant billing, and demand response participation in multi-occupancy buildings and industrial campuses. Smart meters command the dominant share of product type revenue due to their two-way communication capability and integration with building automation systems. Wireless meters represent the fastest-expanding technology segment as Zigbee and Wi-Fi protocols reduce installation costs in retrofit applications across aging European building stock.
EU member states enforce sub-metering requirements through the Energy Efficiency Directive and national transpositions overseen by country-level energy regulators, while CE marking mandates electromagnetic compatibility and safety testing for all devices sold across the single market. EMAS-registered industrial facilities in Germany and France must maintain certified energy management systems that rely on sub-meter data for verification audits. Stakeholders should monitor how the EU AI Act classifies automated energy optimization algorithms that process sub-meter streams, as compliance obligations could reshape vendor software architectures and customer procurement criteria.
Market Dynamics
EU Green Deal enforcement is compressing building energy accountability timelines, forcing facility managers to install granular sub-metering infrastructure ahead of regulatory deadlines.
Growth Catalysts
- Corporate Sustainability Mandates:Commercial real estate portfolios now require circuit-level consumption data to validate net-zero claims and satisfy ESG disclosure requirements under the EU Corporate Sustainability Reporting Directive.
- ISO 50001 Certification Expansion:Industrial facilities across Germany and France pursue energy management system certification, creating installed base demand for sub-meter networks that feed audit-grade data streams.
- Wireless Protocol Maturation:Zigbee and Wi-Fi HaLow implementations slash retrofit installation costs in aging European building stock, accelerating replacement cycles for hardwired legacy meter deployments.
Market Restraints
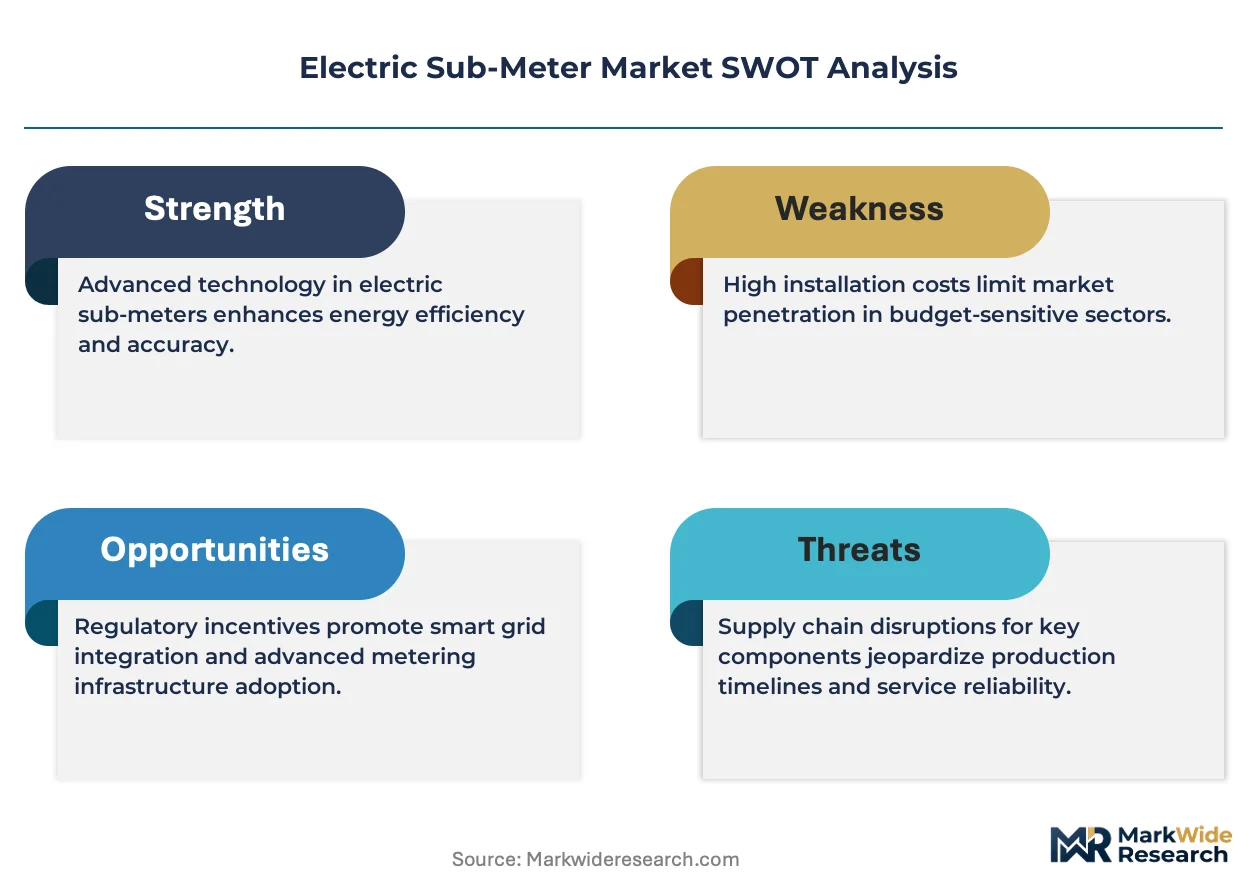
- Semiconductor Component Volatility:Sub-meter manufacturers face input cost pressure from specialized ADC and communication chip supply constraints concentrated in East Asian foundry networks.
- Interoperability Fragmentation:Proprietary data protocols from dominant building automation vendors lock sub-meter data into siloed ecosystems, limiting customer switching flexibility.
- Cybersecurity Compliance Burden:The EU Cybersecurity Act imposes certification overhead on connected metering devices, extending product development cycles and raising non-recurring engineering costs.
Strategic Opportunities
- District Heating Convergence:Nordic utilities seek unified thermal-electric metering platforms, opening crossover segments where combined heat and power facilities require integrated sub-metering solutions.
- AI-Driven Optimization:The EU AI Act's risk classification framework creates demand for sub-meter data pipelines that feed automated building energy algorithms requiring auditable input streams.
- Service Revenue Unbundling:Meter-as-a-service models displace capital purchase patterns in mid-market commercial deployments, shifting vendor economics toward recurring data analytics subscriptions.
Industry Challenges
- Legacy System Integration:BACnet and Modbus protocol translation complexity extends deployment timelines in brownfield industrial sites where decades-old SCADA infrastructure persists.
- Calibration Workforce Scarcity:Certified meter technicians capable of maintaining accuracy class 0.5 certification standards remain concentrated in Germany and the Netherlands, creating service coverage gaps in Southern Europe.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Sub-Meter Market |
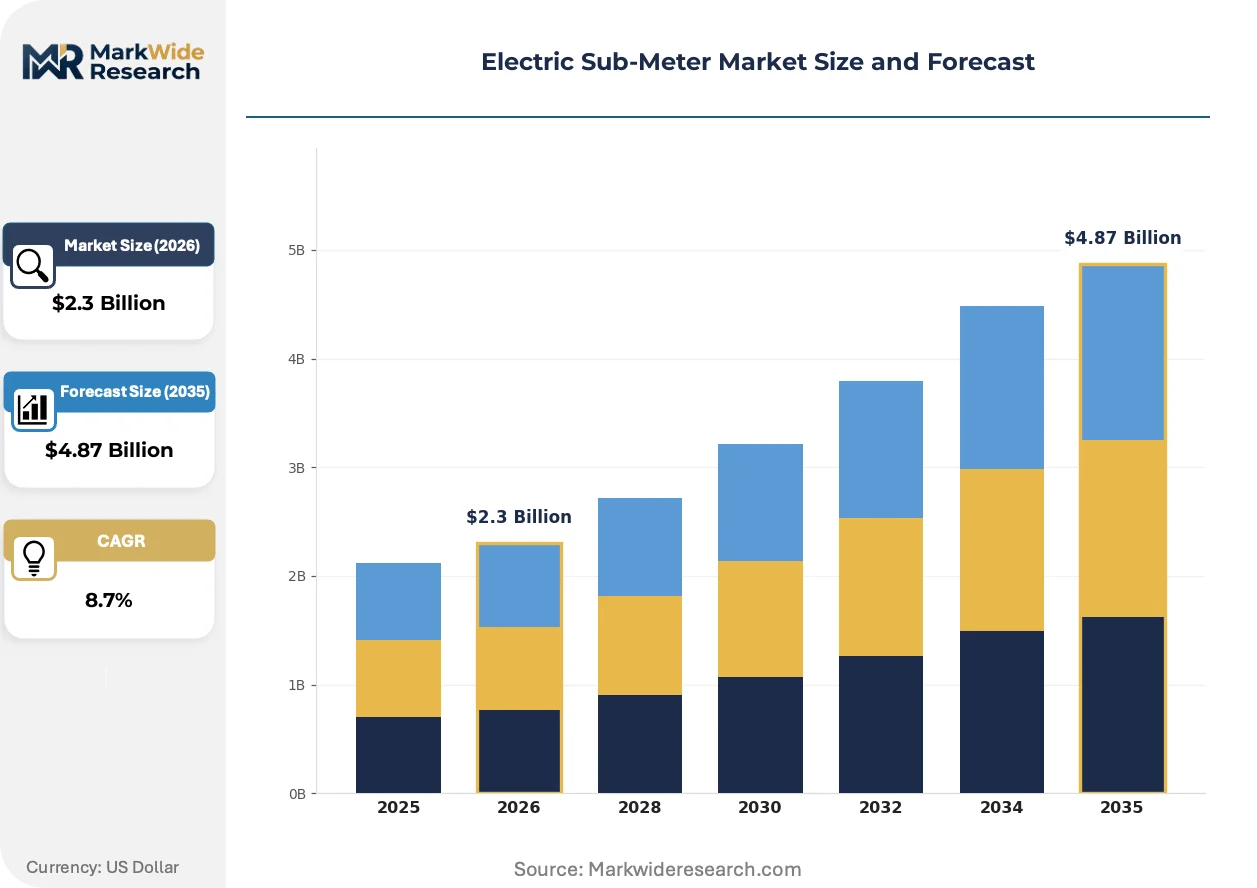
| Market Size in 2026 | $2.3 Billion |
| Market Size in 2035 | $4.87 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
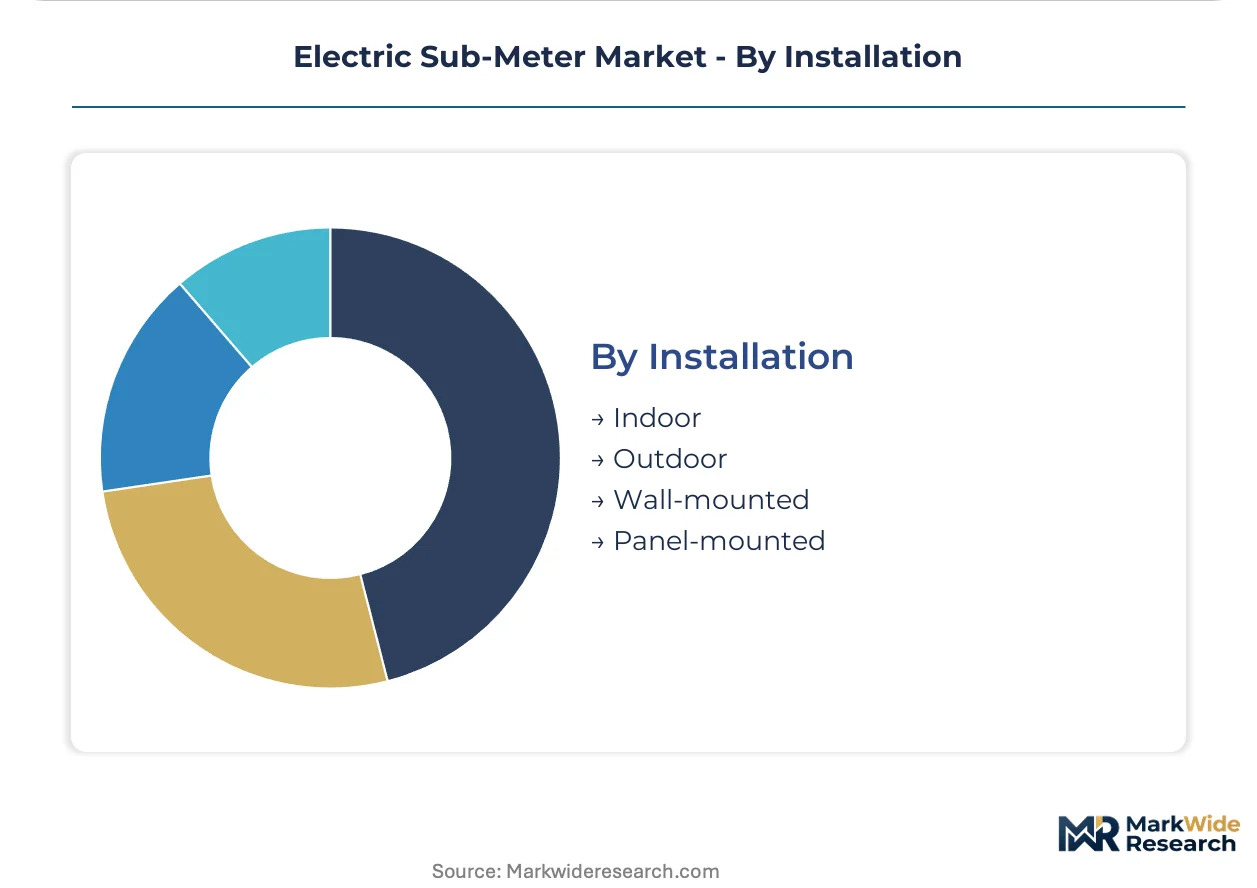
| Segmentation | Product Type: Smart Meters, Analog Meters, Wireless Meters, Prepaid Meters Technology: RFID, Zigbee, Power Line Communication, Wi-Fi End User: Utilities, Residential Buildings, Commercial Establishments, Industrial Facilities Installation: Indoor, Outdoor, Wall-mounted, Panel-mounted |
| Companies Covered | Schneider Electric, Siemens AG, Honeywell International Inc., ABB, Landis+Gyr, Itron, Inc., General Electric, Eaton, Kamstrup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Sub-Meter Market Strategic Shifts & Innovations
Digital twin architectures are virtualizing physical meter infrastructure, compressing the boundary between measurement hardware and software-defined energy analytics platforms.
Edge computing capabilities embedded directly into smart sub-meter hardware is virtualizing traditional gateway architectures, eliminating centralized data concentrators in multi-tenant commercial buildings. Facility operators in Germany and the Netherlands now deploy meters with onboard analytics that process consumption patterns locally rather than transmitting raw telemetry to cloud platforms. This architecture reduces latency for demand response participation while compressing ongoing SaaS subscription costs that previously scaled with data volume.
The EU F-Gas Regulation's phase-down schedule for fluorinated greenhouse gases is accelerating heat pump deployment across commercial building retrofits, creating derived demand for sub-metering that isolates electrified thermal loads from base building consumption. Industrial facilities in Northern France must now document thermal energy separately from process electricity to satisfy national transpositions of the Energy Efficiency Directive. Sub-meter vendors are responding with combined sensing packages that measure both electrical parameters and thermal fluid temperatures through single hardware footprints.
Building owners increasingly specify open API access as a procurement prerequisite, displacing closed-system vendor relationships that historically bundled metering hardware with proprietary software licenses. Large commercial portfolios in Spain and Italy now require RESTful data interfaces that feed third-party energy management platforms rather than accepting siloed vendor dashboards. This pattern concentrates purchasing power with facility management consultancies capable of integrating heterogeneous meter fleets, compressing margins for hardware-only suppliers.
Electric Sub-Meter Market Segmentation
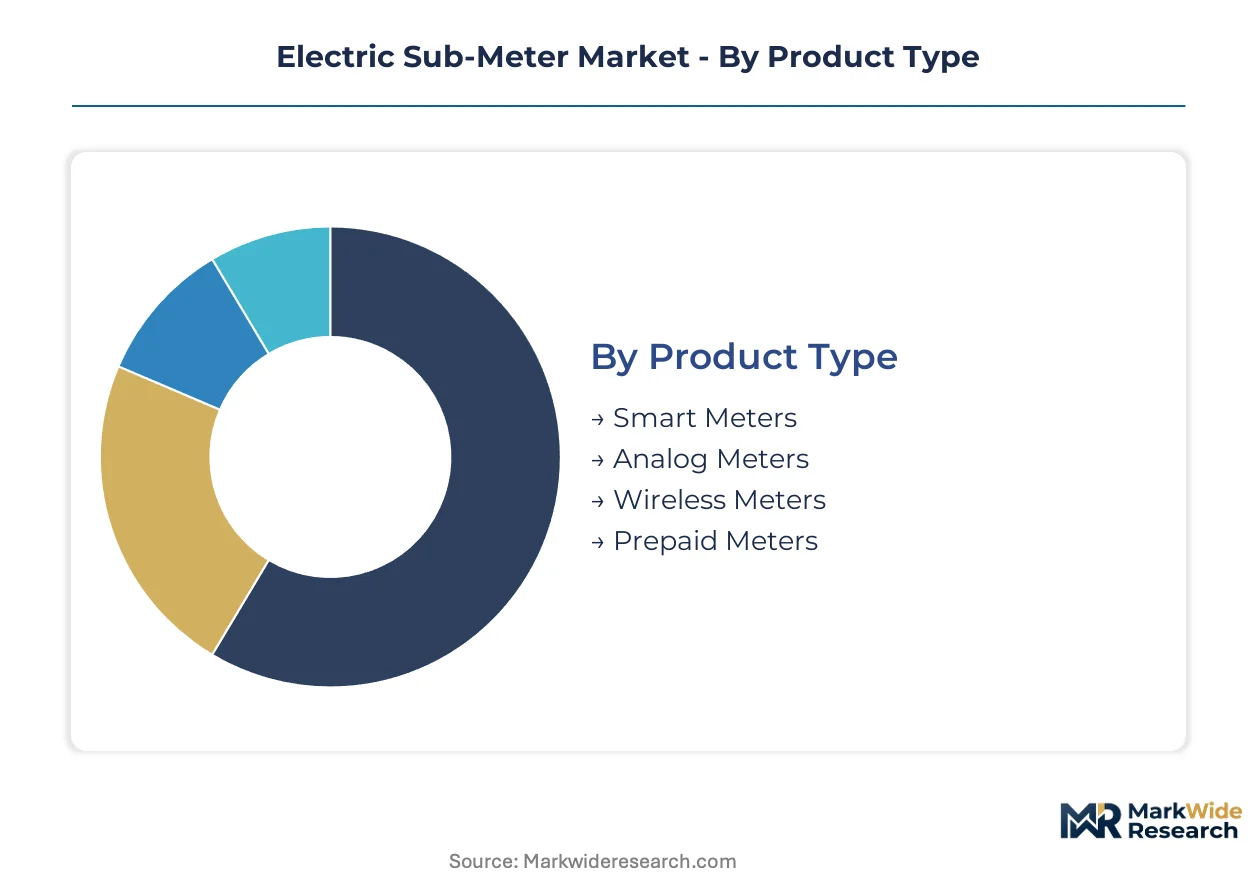
Segmentation in the electric sub-meter market reveals divergent replacement cycles and margin structures across hardware categories. Procurement patterns vary sharply between retrofit wireless deployments and legacy analog replacements, while end-use requirements dictate accuracy class specifications and communication protocol choices.
Product Type:
Smart meters turn over fastest as firmware obsolescence drives 5-7 year refresh cycles, while analog meters persist for 15-20 years in cost-sensitive installations. Wireless meters occupy the middle ground with hardware lifespans of 10-12 years but more frequent communication module upgrades.
- Smart Meters:These devices integrate two-way communication, onboard processing, and building automation system compatibility with accuracy classes typically at 0.5 or 1.0. Demand concentrates in German commercial real estate portfolios pursuing CSRD-compliant ESG disclosure where circuit-level granularity validates net-zero claims.
- Wireless Meters:Zigbee and Wi-Fi HaLow implementations eliminate conduit runs in aging European building stock, slashing retrofit labor costs by 40-60% compared to hardwired alternatives. French facility managers specify these for multi-tenant residential conversions where tenant billing accuracy must meet national metrology standards.
- Analog Meters:Electromechanical induction mechanisms persist in Southern European residential sub-metering where capital constraints delay smart grid investments.
- Prepaid Meters:Token-based or keypad-enabled devices serve social housing providers in Spain and Italy seeking to reduce utility arrears exposure.
Smart meters dominate installed base revenue. Wireless meters are where expansion concentrates fastest.
Technology:
Protocol selection determines interoperability boundaries and recurring cost structures across deployment scales. Cost tiers separate proprietary licensed solutions from open-standard implementations.
- Zigbee:Mesh networking protocol purpose-built for low-power device communication in building automation contexts, operating in the 2.4 GHz band with self-healing topology. German industrial facilities adopt this for ISO 50001-compliant energy management systems requiring reliable sub-meter data aggregation.
- Power Line Communication:Modulated signals transmit across existing electrical infrastructure, eliminating dedicated communication wiring. Italian utilities deploy this in dense urban residential blocks where wireless spectrum congestion interferes with meter reliability.
- RFID:Near-field manual read capabilities serve walk-by meter reading applications in remote French rural installations where cellular backhaul remains uneconomical.
- Wi-Fi:Standard 802.11 protocols enable direct cloud connectivity for sub-meters in Dutch commercial buildings with robust IT infrastructure and cybersecurity management.
Power Line Communication anchors legacy utility deployments. Zigbee is climbing the fastest in new commercial specifications.
End User:
Customer type dictates accuracy requirements, procurement authority, and software integration depth. Volume concentrates in fragmented residential channels while margin concentrates in industrial applications.
- Commercial Establishments:Multi-occupancy office and retail properties require tenant-grade billing accuracy with RESTful API access for third-party energy management platforms. Spanish facility management consultancies now mandate open data interfaces that prevent vendor lock-in.
- Industrial Facilities:Process manufacturing and heavy industry demand accuracy class 0.5 certification with calibration traceability to national metrology institutes. Northern French industrial sites must isolate thermal energy from process electricity to satisfy Energy Efficiency Directive transpositions.
- Utilities:Distribution network operators specify sub-meters for technical loss analysis and demand response aggregation in Nordic district heating crossover applications.
- Residential Buildings:Landlord-tenant sub-metering for cost allocation operates at lower accuracy tolerances with simpler billing software requirements.
Commercial establishments generate the steepest expansion trajectory. Industrial facilities capture premium pricing through certification requirements.
Installation:
Physical mounting configuration determines environmental protection ratings, wiring complexity, and service accessibility. Application context drives specification divergence between new construction and retrofit contexts.
- Panel-mounted:DIN-rail integration within electrical distribution panels serves German industrial control rooms where centralized meter visibility supports operator workflows.
- Wall-mounted:Surface-mounted enclosures with IP ratings for corridor or utility room placement dominate French and Italian multi-tenant residential retrofits.
- Indoor:Climate-controlled environments allow reduced enclosure specifications and lower unit costs for Netherlands commercial office deployments.
- Outdoor:Weatherproof housings with extended temperature ranges serve Nordic district heating substations and remote French agricultural processing facilities.
Panel-mounted configurations dominate industrial specifications. Wall-mounted designs are gaining share fastest in residential retrofit channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and Energy Efficiency Directive are compressing installation timelines across Europe, forcing facility managers to deploy granular sub-metering infrastructure ahead of 2030 regulatory checkpoints.
Germany
Industrial conglomerates in Baden-Württemberg and North Rhine-Westphalia pursue ISO 50001 certification with audit-grade sub-meter networks. The F-Gas Regulation drives heat pump retrofits requiring isolated thermal load monitoring. Munich's commercial real estate sector mandates circuit-level granularity for CSRD-compliant ESG disclosure.
France
Northern French industrial facilities must document thermal energy separately from process electricity under national Energy Efficiency Directive transpositions. EMAS-registered sites in Île-de-France rely on sub-meter data for verification audits. Lyon-based facility managers specify open API access to prevent vendor lock-in.
Netherlands
Dutch commercial buildings deploy edge-enabled smart meters with onboard analytics to reduce cloud subscription costs. The national energy regulator enforces strict cybersecurity standards under the EU Cybersecurity Act. Amsterdam's multi-tenant office sector leads Zigbee mesh implementations for tenant billing accuracy.
Italy
Dense urban residential blocks in Milan and Rome favor Power Line Communication to avoid wireless spectrum congestion. Social housing providers in Southern Italy deploy prepaid meters to reduce utility arrears exposure. National metrology standards mandate calibration traceability for sub-meter installations.
Spain
Facility management consultancies in Madrid and Barcelona require RESTful data interfaces for third-party energy platform integration. The national building code increasingly references sub-metering for new commercial construction. Valencia's retail portfolios accelerate wireless retrofit deployments to meet corporate sustainability targets.
Electric Sub-Meter Market Key Industry Players
On the supply side, the industry is consolidating around integrated building management portfolios and deep utility relationships. The vendor base separates into three strategic archetypes: diversified electrical conglomerates with automation ecosystems, specialized metering pure-plays with metrology expertise, and utility-captive suppliers with regulatory navigation capabilities. Dominant competitive moves include strategic partnerships with facility management consultancies and portfolio diversification into thermal-electric crossover sensing.
Among diversified electrical conglomerates, Schneider Electric and Siemens AG exemplify the integrated automation archetype, leveraging building management portfolios to anchor large commercial deployments. Kamstrup occupies a specialized position within the Nordic district heating crossover segment. These three entities represent distinct competitive vectors: ecosystem breadth, industrial certification depth, and thermal-electric convergence expertise.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens AG |
| Honeywell International Inc. |
| ABB |
| Landis+Gyr |
| Itron, Inc. |
| General Electric |
| Eaton |
| Kamstrup |
| Others |
Cost & Logistics Intelligence
East Asian foundry concentration for specialized ADC and communication chips concentrates pricing power with semiconductor suppliers, compressing hardware margins while pushing value downstream toward firmware and analytics subscriptions.
Pricing Analysis
Volume-discount tiering structures separate enterprise-scale deployments from mid-market commercial installations and residential retrofit projects. Pricing stratifies across premium, standard, and economy tiers based on accuracy class certification and after-sales service bundling. Cost compression in the standard tier is intensifying because Zigbee module commoditization erodes hardware differentiation. Residential retrofit buyers exhibit the highest price sensitivity, while German industrial facilities pursuing ISO 50001 certification demonstrate the lowest.
Supply Chain Analysis
Contract-manufacturing concentration rests with Taiwanese and South Korean EMS providers holding capacity for precision metering assembly. Raw material dependencies center on silicon wafers, copper winding wire, and rare-earth magnets for current transformers. Single-source vulnerability for specialized metrology-grade ADCs creates supply chain risk. Distribution runs through electrical wholesale channels and direct utility procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across protocol standards and regional certification requirements creates niche opportunities for specialized vendors. The EU AI Act's risk classification framework splinters demand for auditable sub-meter data pipelines.
For Market Incumbents: Pre-empt emerging pure-play competitors by acquiring Zigbee protocol specialists and embedding edge analytics capabilities directly into hardware. Schneider Electric and Siemens AG should deepen backward integration into semiconductor sourcing to offset foundry pricing power. Certification investment in EU Cybersecurity Act compliance creates switching costs that lock mid-market commercial accounts. For New Entrants and Emerging Players: Build out thermal-electric crossover sensing capabilities for Nordic district heating utilities seeking unified metering platforms. Southern European social housing providers represent the most penetrable segment given prepaid meter replacement cycles and limited incumbent service coverage. A meter-as-a-service subscription model bypasses capital-constrained procurement committees. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed metering pure-plays that consolidated regional metrology specialists. Long-term viability hinges on software-defined energy analytics capabilities rather than hardware shipment volumes. Watch for EU AI Act enforcement actions against automated optimization algorithms as an inflection signal for compliance-focused acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Protocol Standardization Partnership | Open API alliances with facility management consultancies in Spain prevent vendor lock-in and expand addressable market. |
| Edge Analytics Hardware Integration | Onboard processing in Dutch commercial deployments eliminates gateway costs and reduces cloud subscription dependency. |
| Thermal-Electric Sensing Convergence | Combined heat and power metering addresses F-Gas Regulation compliance in German industrial retrofit projects. |
| Cybersecurity Certification Investment | EU Cybersecurity Act compliance extends product development cycles but creates procurement barriers for uncertified competitors. |
| Meter-as-a-Service Model Launch | Recurring revenue subscriptions displace capital purchases in French and Italian mid-market commercial segments. |
Research Approach
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings. The research team conducted structured conversations with facility management directors, energy procurement officers at German industrial conglomerates, metrology calibration technicians, and utility planning officers across five EU member states. Secondary sources include CE marking documentation, Energy Efficiency Directive national transpositions, ISO 50001 certification registries, and customs trade data for metering equipment. Bottom-up unit economics and top-down regulatory mandate sizing were reconciled through iterative triangulation.
Calibration against historical installation trajectories and regulatory deadline schedules shaped the projection framework. The analytical model segments by product type, communication protocol, end-user vertical, and national regulatory cluster across the analysis window. CAGRs were derived from fitted adoption curves calibrated to EU Green Deal enforcement timelines. Forecast inputs incorporate utility procurement cycle data and EMAS-registered facility expansion patterns.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by semiconductor suppliers would shift outcomes beyond modeled ranges. Forecasts assume steady EU Cybersecurity Act implementation without accelerated enforcement. Quarterly review of CE marking approval backlogs and ISO 50001 certification rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Distributed Energy Resource Management System (DERMS) Market
Energy Management
Power SCADA Market
Energy Management
South Korea Residential Heat Pump Market
Energy Management
Middle-East and Africa Demand Response Management Systems Market
Energy Management
Energy Security Market
Energy Management
Germany Demand Response Management Systems Market
Energy Management
Electric Service Companies (Escos) Market
Energy Management
Energy Harvesting System Market
Energy Management
Solar Panel Monitoring System Market
Energy Management
Australia Energy-As-A-Service Market
Energy Management
Asia-Pacific Exhaust Heat Recovery System Market
Energy Management
Industrial Energy Management System Market
Energy Management
Heat Meter Market
Energy Management
Global Energy Consumption Market
Energy Management
Connected Energy Market
Energy Management
APAC Building Energy Management Systems Market