
 Middle-East and Africa Demand Response Management Systems Market | 2026-2036
Middle-East and Africa Demand Response Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Demand Response Management Systems Market Foresight
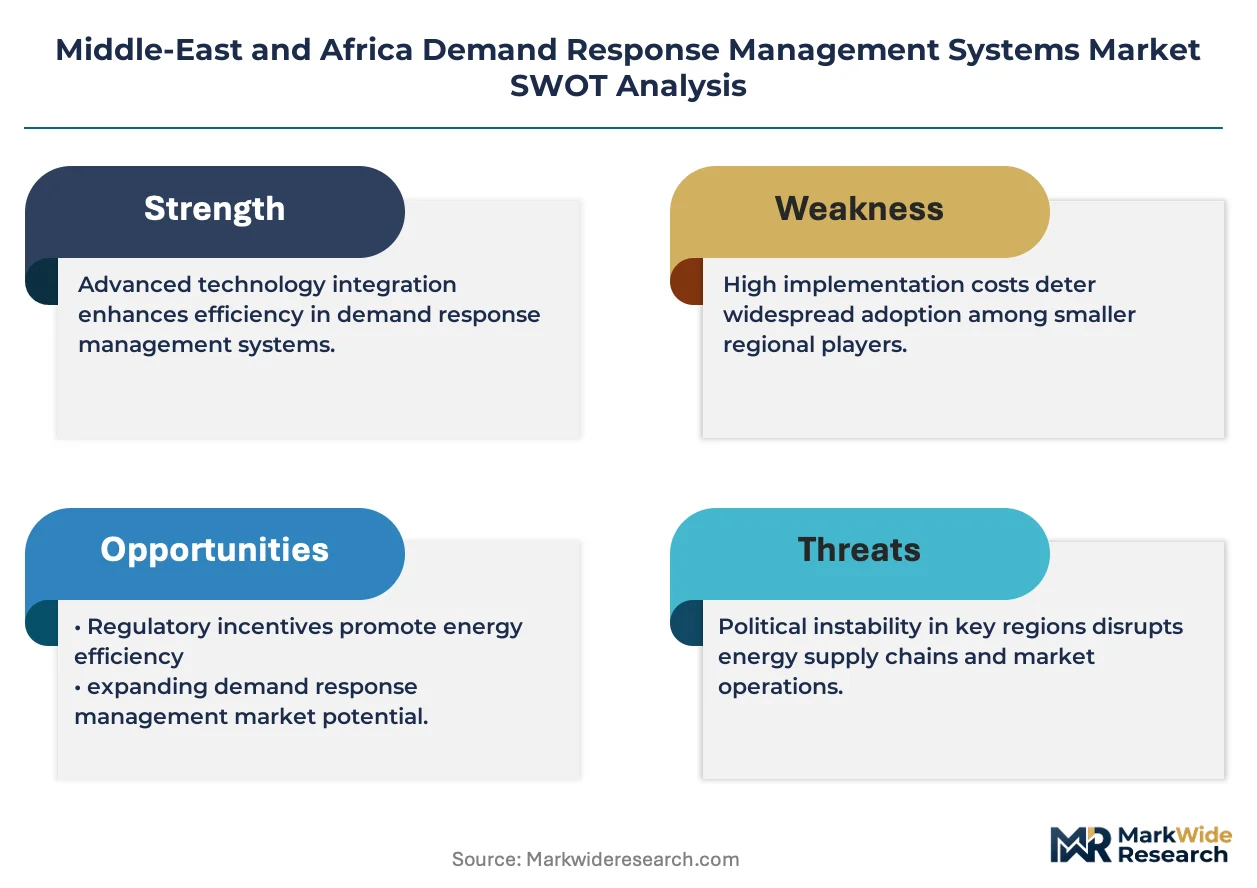
The capability gap between hardware-heavy integrators and software-native specialists is rotating competitive capital allocation across the Middle-East and Africa. Schneider Electric leverages its EcoStruxure platform to anchor utility-scale deployments across the Gulf. Siemens AG sustains R&D intensity in grid-edge automation, while ABB Ltd competes through manufacturing scale in substation-linked demand response hardware.
Demand Response Management Systems coordinate curtailable loads, distributed generation, and storage assets through real-time telemetry and automated control protocols to stabilize grid frequency and defer capacity investment. The platform ingests SCADA and AMI data streams, executes dispatch algorithms, and settles performance against baseline consumption models. Load shedding services dominate current revenue pools across utilities, while automated demand response technology captures the fastest expansion as Saudi Electricity Company and South African municipalities upgrade legacy direct load control infrastructure. Industrial facilities represent the deepest margin pool given their contractual flexibility and megawatt-scale curtailment blocks.
Saudi Arabia's Electricity and Cogeneration Regulatory Authority, South Africa's National Energy Regulator, and the UAE's Federal Electricity and Water Authority each mandate grid code compliance for demand-side resources, embedding technical standards into market access. Egypt's Electricity Utility Regulatory Agency is drafting similar frameworks. Stakeholders must monitor which regulators adopt capacity-market remuneration versus energy-only settlements, as this choice determines project finance structures and vendor business models.
Market Dynamics
The transition from manual load shedding to automated demand response protocols is compressing procurement cycles across Middle Eastern utilities while forcing legacy SCADA integrators to acquire cloud-native software capabilities.
Growth Catalysts
- Saudi Electricity Company modernization mandates:The national utility's grid code revisions now require automated telemetry for all curtailable loads above 10 MW, creating immediate replacement demand across industrial zones.
- Eskom reliability-driven procurement:South Africa's power utility is contracting private aggregators to manage commercial peak shaving, opening revenue streams for technology vendors capable of sub-second frequency response.
- AMI infrastructure deployment:Advanced metering rollouts across UAE emirates are generating real-time data streams that enable algorithmic dispatch previously impossible under manual meter-reading regimes.
Market Restraints
- Semiconductor supply concentration:Power electronics and communication modules for load control hardware face extended lead times from East Asian foundries, delaying project commissioning.
- Regulatory fragmentation:Divergent grid code standards between Gulf Cooperation Council members and North African regulators force vendors to maintain multiple product certifications.
- Capital intensity of utility-scale deployments:Substation automation upgrades require dedicated fiber networks and redundant control centers, constraining municipal budgets outside hydrocarbon-exporting economies.
Strategic Opportunities
- Egyptian regulatory framework development:The country's electricity regulator is drafting demand-side resource standards that will open Africa's largest population market to compliant technology providers.
- Behind-the-meter storage convergence:Battery systems paired with demand response software create stacked revenue streams from frequency regulation and energy arbitrage.
- Industrial microgrid expansion:Mining and petrochemical complexes in South Africa and Saudi Arabia are procuring island-capable control systems that integrate on-site generation with grid-responsive load management.
Industry Challenges
- Control systems engineering talent scarcity:The specialized skill set combining power systems expertise with software development is concentrated in European and North American labor markets.
- Legacy direct load control integration:Rip-and-replace timelines for electromechanical relay systems extend project delivery schedules and inflate commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Demand Response Management Systems Market |
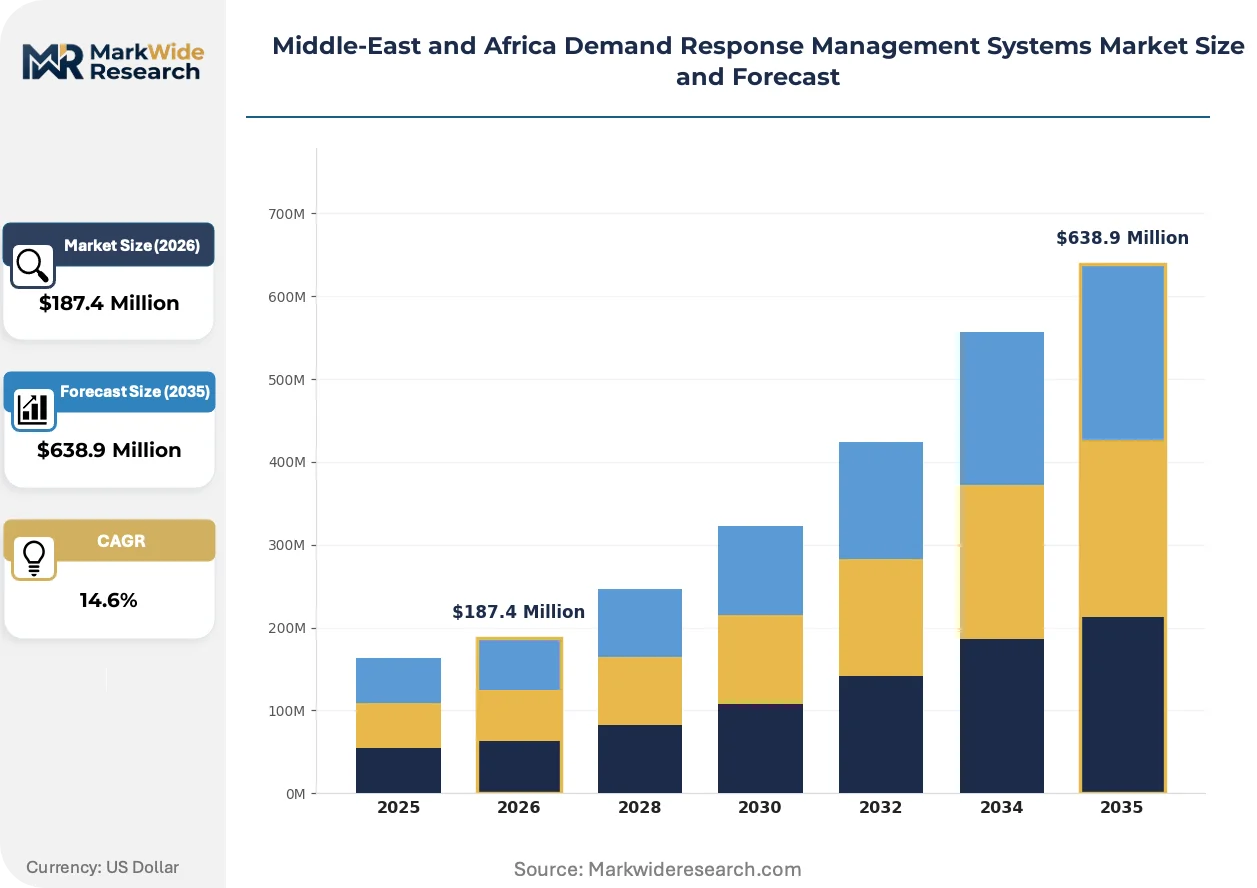
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Load Shedding, Peak Shaving, Frequency Regulation, Voltage Control End User: Utilities, Commercial Buildings, Industrial Facilities, Residential Users Technology: Automated Demand Response, Direct Load Control, Incentive-Based Programs, Time-Based Rates Application: Energy Management Systems, Grid Support, Renewable Integration, Demand Forecasting |
| Companies Covered | Schneider Electric, Siemens AG, ABB Ltd, General Electric Company, Hitachi Ltd, Mitsubishi Electric Corporation, Eaton Corporation, Saudi Electricity Company, Alstom SA, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Demand Response Management Systems Market Shifts & Advancements
Telemetry density and algorithmic dispatch speed are becoming the primary axes of vendor differentiation, compressing margins for hardware-centric integrators while elevating software-native platform providers.
Cloud-native demand response platforms is supplanting on-premise SCADA architectures in utility procurement specifications. Saudi Electricity Company and Dubai Electricity and Water Authority are mandating API-first control systems capable of third-party aggregator integration. This architectural shift is compressing hardware maintenance revenue pools while expanding recurring software license streams.
South Africa's National Energy Regulator has introduced performance-based remuneration for frequency containment reserves, altering how demand response providers contract with Eskom. Industrial facilities must now demonstrate measured frequency response rather than contractual availability. Mining operations in the platinum belt are upgrading control system latency to capture these payments.
Aggregated procurement through energy service companies is displacing direct utility contracting for commercial and industrial demand response. South African municipalities and Saudi industrial cities are channeling installations through specialized intermediaries that assume performance risk. This concentration is visible in Johannesburg's commercial district and Jubail's petrochemical corridor.
Middle-East and Africa Demand Response Management Systems Market Segmentation
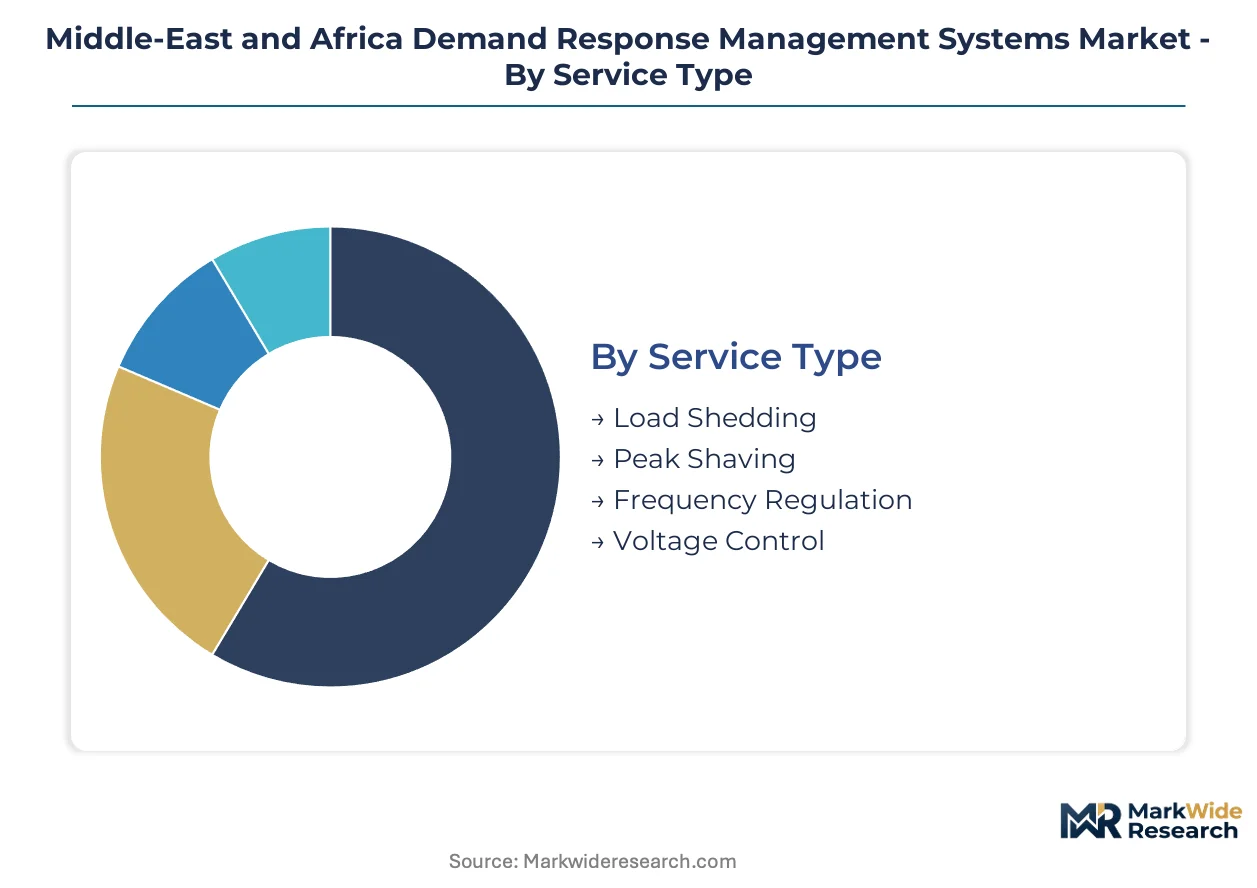
Segmentation in Middle-East and Africa Demand Response Management Systems reveals how procurement patterns diverge between Gulf utilities with capital for full automation and African municipalities constrained by legacy infrastructure. Each dimension exposes distinct vendor opportunity sets across hardware, software, and service layers.
Service Type:
Load shedding services dominate procurement in hydrocarbon-exporting economies where utilities maintain capital reserves for infrastructure investment, while frequency regulation contracts concentrate in South Africa's reliability-constrained grid.
- Load Shedding:Emergency curtailment protocols that disconnect non-critical loads during supply shortfalls. Saudi Electricity Company and Dubai Electricity and Water Authority mandate automated shedding for industrial customers above 10 MW, creating replacement demand across Jubail's petrochemical corridor.
- Peak Shaving:Scheduled load reduction during maximum demand periods to defer generation capacity investment. Eskom's aggregator contracts in Johannesburg's commercial district are expanding this segment fastest as mining operations seek contractual revenue from curtailable loads.
- Frequency Regulation:Sub-second response to grid frequency deviations through automated load modulation. South Africa's National Energy Regulator performance-based remuneration is accelerating adoption in platinum belt mining operations.
- Voltage Control:Reactive power management through capacitor switching and load adjustment. Deployment concentrates in UAE emirates with high distributed solar penetration requiring voltage stabilization at distribution substations.
Load shedding commands the established base. The steepest expansion runs through peak shaving.
End User:
Industrial facilities generate the deepest margins given their megawatt-scale curtailment blocks and contractual flexibility, while residential participation remains nascent outside AMI-enabled Gulf markets.
- Utilities:Grid operators procuring system-wide demand response as capacity resources. Saudi Electricity Company modernization mandates and Eskom reliability-driven aggregator contracts anchor this segment across Riyadh industrial zones and Gauteng province.
- Commercial Buildings:Office complexes and retail centers participating through energy service company intermediaries. Johannesburg's commercial district and Dubai's business clusters concentrate current deployment.
- Industrial Facilities:Mining, petrochemical, and manufacturing operations with process-flexible loads. Saudi Arabia's Jubail and Yanbu industrial cities plus South Africa's platinum and gold mining belts represent the highest-value curtailment blocks.
- Residential Users:Household participation through direct load control of water heaters and air conditioning. Limited to UAE emirates with advanced metering infrastructure; negligible elsewhere due to capital constraints.
Industrial facilities capture premium pricing. Commercial buildings are climbing the fastest as municipal procurement channels installations through aggregators.
Technology:
Automated demand response protocols are supplanting legacy direct load control as Saudi Electricity Company and Dubai Electricity and Water Authority mandate API-first architectures, while incentive-based programs expand in South African municipalities lacking capital for full automation.
- Automated Demand Response:Machine-to-machine communication enabling sub-second load modulation without human intervention. Saudi grid code revisions mandate this technology for loads above 10 MW, compressing procurement cycles for compliant vendors.
- Direct Load Control:Utility-operated switches cycling air conditioning and water heating equipment. Legacy electromechanical relay systems in North African municipalities face extended rip-and-replace timelines.
- Incentive-Based Programs:Payments for measured performance against baseline consumption. South Africa's frequency containment reserve remuneration structure favors this approach for mining operations with existing telemetry.
- Time-Based Rates:Price signals encouraging voluntary load shifting. Limited deployment in Gulf Cooperation Council markets where flat-rate tariffs persist for residential customers.
Direct load control retains installed base dominance. Automated demand response is expanding most quickly as cloud-native platforms displace on-premise SCADA.
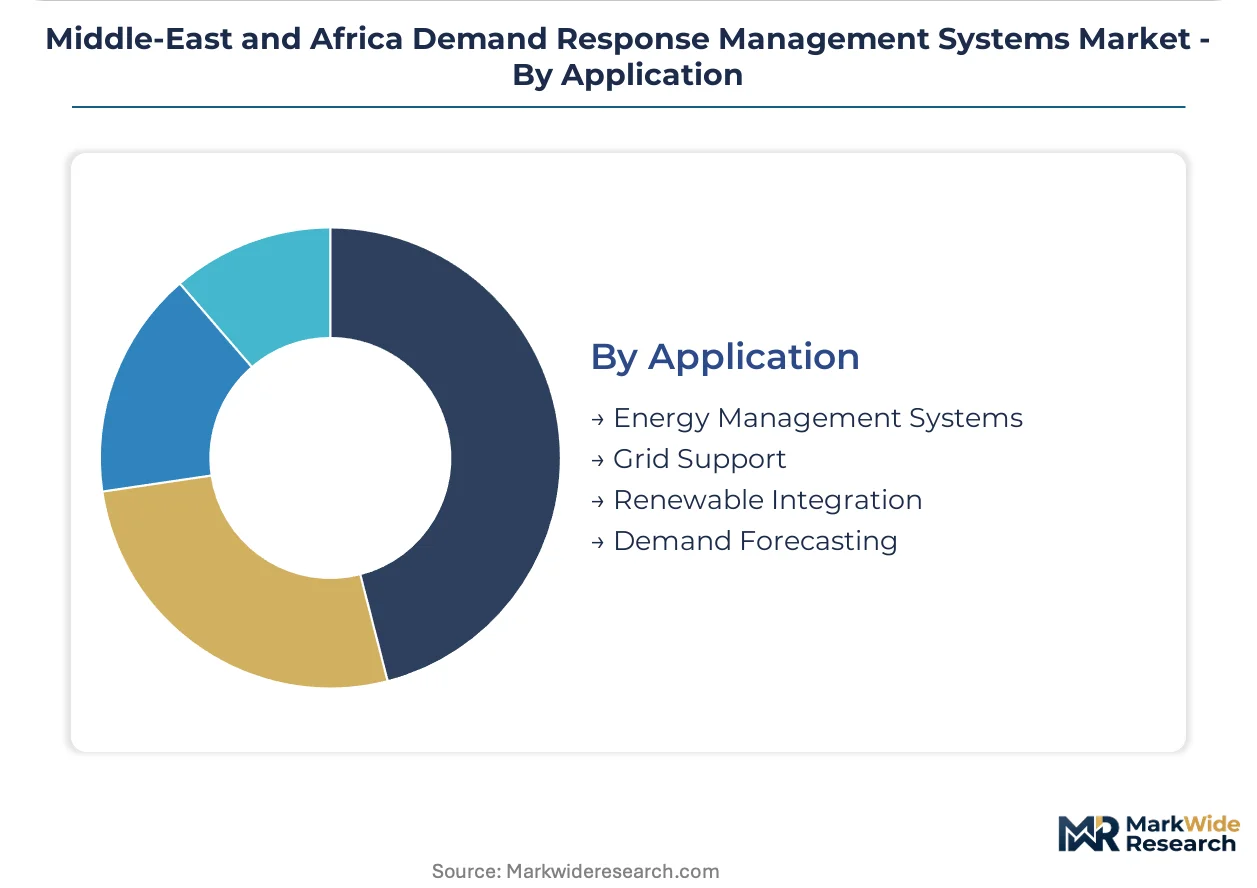
Application:
Grid support applications concentrate revenue in utility-scale deployments, while renewable integration is emerging fastest in UAE emirates with aggressive solar capacity targets requiring demand-side balancing.
- Energy Management Systems:Integrated platforms optimizing on-site generation, storage, and curtailable loads. Industrial microgrids in Saudi petrochemical complexes and South African mining operations deploy these systems for island-capable operation.
- Grid Support:Ancillary services providing frequency response, voltage regulation, and spinning reserves. Eskom's reliability challenges and Saudi grid code mandates anchor this application across both regions.
- Renewable Integration:Demand response balancing variable solar and wind output. Dubai Electricity and Water Authority's solar expansion is accelerating procurement for ramp management and duck curve mitigation.
- Demand Forecasting:Algorithmic prediction of load patterns to optimize dispatch scheduling. Advanced metering infrastructure in UAE emirates enables this application through real-time data streams.
Grid support commands established revenue pools. Renewable integration is gaining share fastest as solar capacity expansion outpaces storage deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Africa and Egypt demonstrate acute price sensitivity due to capital constraints and currency volatility, while Gulf Cooperation Council utilities in Saudi Arabia and the UAE absorb premium pricing for fully automated systems without procurement hesitation.
Saudi Arabia
Petrochemical complexes in Jubail and Yanbu industrial cities drive demand for megawatt-scale curtailment systems. The Electricity and Cogeneration Regulatory Authority mandates automated telemetry for all loads above 10 MW under revised grid codes. Riyadh's industrial zones are replacing legacy direct load control infrastructure with API-first architectures.
United Arab Emirates
Dubai Electricity and Water Authority's solar expansion accelerates procurement for ramp management and duck curve mitigation. The Federal Electricity and Water Authority embeds technical standards for demand-side resources into market access rules. Advanced metering infrastructure across Abu Dhabi and Dubai emirates generates real-time data streams enabling algorithmic dispatch.
South Africa
Eskom's reliability challenges drive commercial investment in peak shaving services across Johannesburg's commercial district. The National Energy Regulator introduced performance-based remuneration for frequency containment reserves, altering provider contracting structures. Platinum belt mining operations upgrade control system latency to capture these payments.
Egypt
Industrial facilities in the Suez Canal Economic Zone seek curtailable load contracts amid grid instability. The Electricity Utility Regulatory Agency is drafting demand-side resource standards that will open Africa's largest population market. Cairo's manufacturing corridors concentrate early adoption as regulatory frameworks solidify.
Middle-East and Africa Demand Response Management Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle-East and Africa Demand Response Management Systems market. The vendor base separates into three tiers: multinational industrial conglomerates with integrated hardware-software stacks, regional utility-affiliated technology providers, and specialized software-native platform developers. Dominant competitive moves include strategic partnerships between Gulf utilities and technology licensors, plus portfolio diversification into behind-the-meter storage convergence.
Within the multinational tier, Schneider Electric, Siemens AG, and ABB Ltd occupy positions as archetypal integrated industrial technology providers. Schneider Electric represents the software-native platform approach through its EcoStruxure architecture. Siemens AG exemplifies sustained engineering intensity in grid-edge automation. ABB Ltd anchors the manufacturing-scale hardware segment for substation-linked demand response infrastructure. These three companies collectively illustrate the capability gap between hardware-heavy integrators and software-specialized competitors that is rotating competitive capital allocation across the region.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens AG |
| ABB Ltd |
| General Electric Company |
| Hitachi Ltd |
| Mitsubishi Electric Corporation |
| Eaton Corporation |
| Saudi Electricity Company |
| Alstom SA |
| Others |
Supply & Pricing Matrix
Cloud-native software stacks displacing on-premise SCADA architectures are rerouting procurement budgets from Gulf industrial zones toward European and North American platform developers while compressing hardware maintenance margins across Middle Eastern utilities. This substitution simultaneously concentrates pricing power with software licensors holding API-first intellectual property and fragments hardware assembly economics across East Asian contract manufacturers.
Pricing Analysis
Recurring software license revenue drives lifetime value across utility-scale deployments, with subscription tiers for telemetry density and dispatch latency creating three-tier pricing structure across premium, standard, and economy levels. Certification against Saudi Electricity Company grid code mandates and UAE Federal Electricity and Water Authority technical standards differentiates premium tiers. Cost compression in hardware integration is intensifying because semiconductor lead times from East Asian foundries extend project commissioning cycles. Municipal buyers in Egypt and South Africa demonstrate acute price sensitivity, while Gulf Cooperation Council utilities absorb premium automated system pricing without procurement hesitation.
Supply Chain Analysis
Strategic stockpiling of power electronics and communication modules dominates procurement behavior as East Asian foundry concentration creates single-source vulnerability for load control hardware. Manufacturing concentrates in China, South Korea, and Taiwan for semiconductor components, while final system integration localizes in Saudi Arabia and UAE industrial zones. Raw material dependencies span silicon wafers, rare earth magnets for relay systems, and copper for substation interconnects. Distribution runs through utility-affiliated technology providers and energy service company intermediaries in South African municipalities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East and Africa Demand Response Management Systems market represents a platform-economics inflection where API-first architectures are displacing proprietary SCADA protocols, with interoperability mandates from Saudi Electricity Company and Dubai Electricity and Water Authority creating winner-take-most dynamics for compliant software vendors.
For Market Incumbents: Secure cloud-native software capabilities through acquisition or accelerated R&D to defend against specialized platform developers capturing recurring license revenue. Backward integration into semiconductor sourcing mitigates East Asian foundry concentration risk. Certification maintenance against evolving Gulf Cooperation Council grid codes preserves market access as Egyptian and South African regulators draft comparable standards. For New Entrants and Emerging Players: Aggregator service layers in South African municipalities and Egyptian industrial cities represent the most penetrable white-space where incumbents under-serve price-constrained buyers lacking capital for full automation. Frequency regulation performance contracting for mining operations offers immediate revenue capture given National Energy Regulator remuneration structures. Partner with local energy service companies to assume performance risk and bypass direct utility procurement barriers. For Investors and Strategic Acquirers: The market sits at a standards-adoption phase that favors software-native platform developers with existing API-first architectures over hardware-heavy integrators facing margin compression. Long-term viability centers on recurring revenue models and multi-utility deployment scalability rather than project-based system sales. Watch Egyptian Electricity Utility Regulatory Agency demand-side resource standard finalization as the signal indicating addressable market expansion across Africa's largest population economy.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Development | Schneider Electric's EcoStruxure architecture demonstrates how cloud-native stacks capture recurring utility license revenue. |
| Backward Integration into Semiconductors | Power electronics sourcing control reduces exposure to East Asian foundry lead times affecting project commissioning. |
| Aggregator Partnership Formation | Energy service company intermediaries in Johannesburg and Jubail concentrate procurement channels and assume performance risk. |
| Grid Code Certification Investment | Compliance with Saudi Electricity Company mandates above 10 MW loads creates immediate replacement demand. |
| Behind-the-Meter Storage Convergence | Battery pairing with demand response software enables stacked revenue from frequency regulation and energy arbitrage. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, grid operators at Saudi Electricity Company and Eskom, energy service company executives, industrial facility energy managers, and demand response software engineers. Secondary validation drew from regulatory filings with Saudi Arabia's Electricity and Cogeneration Regulatory Authority, South Africa's National Energy Regulator, and UAE's Federal Electricity and Water Authority, plus advanced metering infrastructure deployment disclosures and utility procurement databases. Bottom-up project pipeline analysis triangulated against top-down market sizing across service type, end user, technology, and application dimensions.
Across the analysis window, the forecasting framework modeled revenue trajectories by service type segmentation including load shedding, peak shaving, frequency regulation, and voltage control, crossed with end user categories spanning utilities, commercial buildings, industrial facilities, and residential users. Technology diffusion curves for automated demand response, direct load control, and incentive-based programs informed adoption pacing. CAGRs were derived from utility capital expenditure plans, regulatory mandate timelines, and industrial load growth projections across Jubail, Riyadh, Johannesburg, and Dubai industrial zones.
Forecasts assume regulatory continuity in Saudi Arabia, South Africa, UAE, and Egypt; material policy shifts in grid code standards or capacity market remuneration structures would require re-modeling. Revision becomes warranted when semiconductor supply concentration or currency volatility in African markets crosses thresholds affecting project finance viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Distributed Energy Resource Management System (DERMS) Market
Energy Management
Testing, Inspection, and Certification (TIC) in the Energy and Power Market
Energy Management
Smart Power Technologies Market
Energy Management
Asia-Pacific Exhaust Heat Recovery System Market
Energy Management
Industrial Energy Management System Market
Energy Management
Brazil Energy Sector Market
Energy Management
APAC Energy Management Systems (EMS) Market
Energy Management
Smart Energy Solutions Market
Energy Management
Heat Meter Market
Energy Management
Europe Exhaust Heat Recovery System Market
Energy Management
Demand Response Management System Market
Energy Management
Electric Sub-Meter Market
Energy Management
Energy Harvesting System Market
Energy Management
Energy Security Market
Energy Management
Residential Demand Response Management Systems Market
Energy Management
Connected Energy Market