
 Transmission Repair Market | 2026-2036
Transmission Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Transmission Repair Market Analysis
Electrification of drivetrain architectures is rewriting how transmission repair providers must retool their service capabilities. ZF Friedrichshafen AG anchors its competitive position through deep manufacturing integration across both conventional and electrified transmission platforms. BorgWarner specializes in dual-clutch and electric drive module technologies that reshape technician training requirements. Schaeffler Group leverages its bearing and precision component leadership to supply the rebuild aftermarket with OE-grade replacement parts.
Transmission repair encompasses the diagnostic assessment, disassembly, component refurbishment, and reassembly of gearboxes to restore torque transfer efficiency, typically involving clutch pack replacement, synchronizer ring machining, and valve body recalibration to manufacturer tolerances. Automatic service categories dominate current revenue as torque converter shudder and planetary gear wear drive recurring maintenance among high-mileage passenger cars. Heavy-duty vehicle rebuild work captures concentrated margin pools due to specialized tooling requirements and certified technician scarcity.
The National Highway Traffic Safety Administration enforces recall and defect reporting standards that influence rebuild-versus-replace decisions, while the EPA regulates hazardous fluid disposal and remanufacturing emissions. State-level BAR (Bureau of Automotive Repair) inspections in California and similar bodies in Texas and New York enforce consumer protection standards that shape shop certification requirements. Stakeholders must monitor electrification penetration rates and calibrate training investments against the residual internal combustion fleet service horizon.
Market Dynamics
The EPA's tightened emissions enforcement on heavy-duty vehicles is forcing fleet operators toward preventive transmission rebuilds rather than premature replacements, compressing service cycles and elevating certified rebuild volumes across the aftermarket.
Growth Catalysts
- EPA Emissions Enforcement:Heavy-duty vehicle owners facing stricter compliance deadlines are accelerating scheduled maintenance to avoid costly penalties, driving rebuild demand over replacement purchases.
- Aging Vehicle Parc:Extended ownership cycles across the United States sustain high-mileage transmission service volumes as consumers retain vehicles beyond 150,000 miles.
- Electrified Drivetrain Training:Technician certification programs for electric drive modules create new revenue streams for shops investing in hybrid and EV-capable service bays.
Market Restraints
- Specialized Tooling Costs:Precision diagnostic equipment for modern automatic transmissions requires capital outlays that strain independent repair shops.
- Remanufactured Component Supply:Concentration of OE-grade valve body and torque converter remanufacturing in Mexico creates geographic supply vulnerability for North American distributors.
- Extended Drain Intervals:Synthetic transmission fluids rated for 100,000-mile service intervals reduce frequency of routine maintenance visits.
Strategic Opportunities
- Texas Fleet Corridors:Underpenetrated independent repair presence along I-35 and I-10 trucking routes offers expansion potential for transmission specialists targeting owner-operator segments.
- Telematics-Integrated Predictive Maintenance:Remote diagnostic platforms enabling pre-failure intervention create subscription revenue models for shops with connected service capabilities.
- California BAR Certification Premium:Bureau of Automotive Repair licensed facilities command pricing power through consumer protection positioning in the state's high-regulation environment.
Industry Challenges
- Electric Drive Module Competency:Scarcity of technicians trained in power electronics and motor-generator unit repair limits shop capacity to service electrified transmissions.
- OE Software Access Restrictions:Manufacturer-controlled calibration files and proprietary diagnostic protocols create integration friction for independent rebuilders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transmission Repair Market |
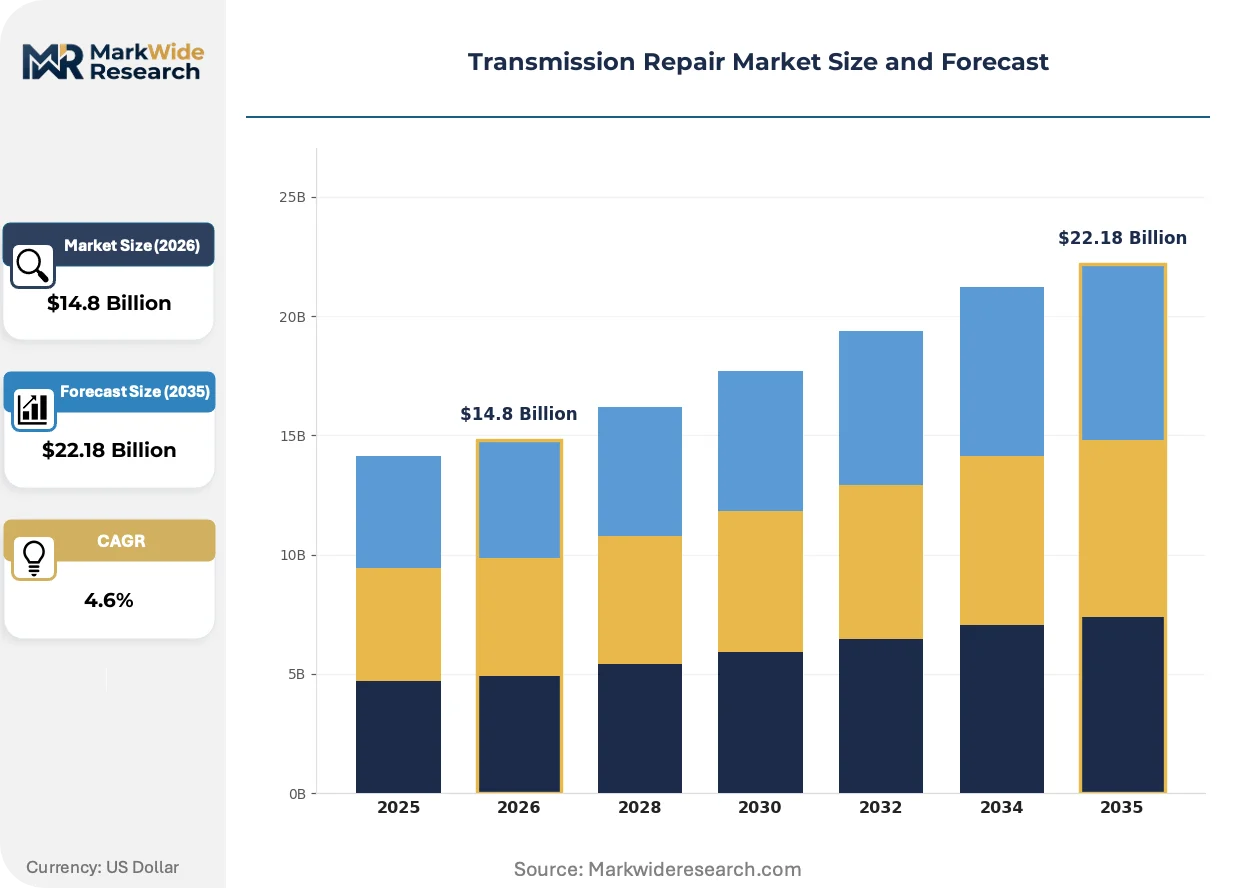
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Automatic, Manual, Hybrid, CVT Vehicle Type: Passenger Cars, Light Trucks, Heavy-Duty Vehicles, SUVs Repair Technique: Rebuild, Replacement, Fluid Change, Diagnostics Customer Type: Individual Owners, Fleets, Dealerships, Repair Shops |
| Companies Covered | Schaeffler Group, ZF Friedrichshafen AG, Continental, Allison Transmission, BorgWarner, AAMCO Transmissions, Cottman Transmission and Total Auto Care, Mister Transmission, Firestone Complete Auto Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transmission Repair Market Emerging Trajectories
Digital diagnostic platforms and electrified drivetrain architectures are compressing traditional service models while expanding the technical competency perimeter for transmission specialists.
Dual-clutch transmission architectures are hybridizing service requirements as conventional hydraulic systems integrate with electric actuation. Fleet maintenance departments are adopting these platforms for fuel efficiency gains. The convergence is forcing independent shops to acquire both mechanical rebuild and low-voltage electrical diagnostic capabilities.
REACH substance restrictions in Europe are phasing out specific friction modifiers and seal compounds used in legacy transmission fluids. Rebuild suppliers must reformulate additive packages to maintain OE performance specifications. North American remanufacturers importing European-designed components face accelerated compliance timelines for material substitutions.
Subscription-based predictive maintenance programs are displacing transactional repair relationships among commercial fleet operators. Large logistics companies now contract directly with telematics-enabled service networks for transmission health monitoring. This shift concentrates procurement power with technology-integrated providers in the United States freight corridor markets.
Transmission Repair Market Segmentation
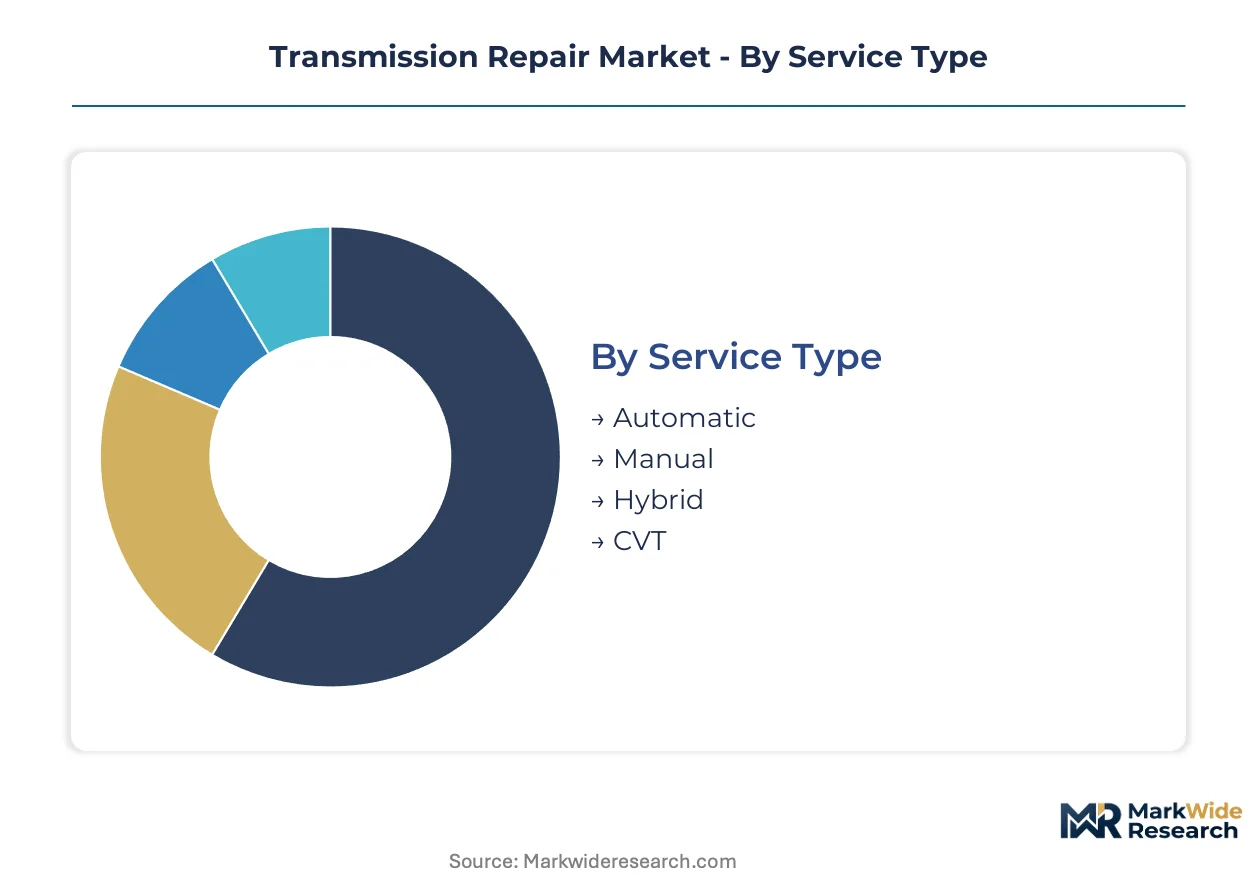
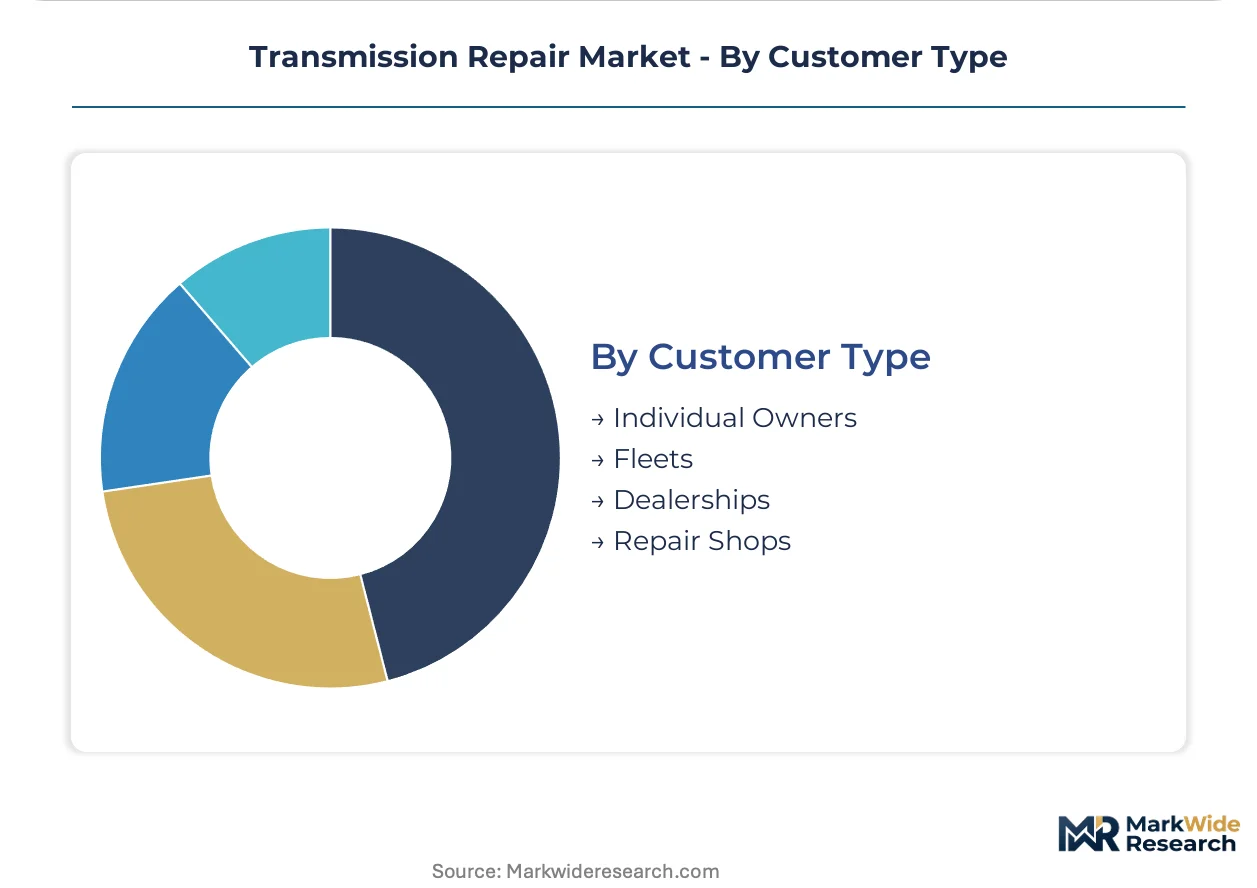
Transmission repair service intensity varies sharply across drivetrain architectures and customer profiles. Fleet operators generate predictable high-volume demand while individual owners concentrate spend on failure-mode interventions. Understanding segment-level economics helps providers calibrate tooling investments and technician training priorities.
Service Type:
After-sales-service intensity escalates with electronic control complexity and thermal management requirements across transmission architectures.
- Automatic:Torque converter assemblies and planetary gear sets generate recurring maintenance demand among high-mileage vehicles. Fleet operators in the United States sustain scheduled rebuild volumes as EPA emissions enforcement compresses service cycles for heavy-duty applications.
- Hybrid:Power-split devices and motor-generator units integrate mechanical torque paths with high-voltage electronics. Technician certification scarcity limits shop capacity, creating margin premiums for early movers investing in electrified drivetrain bays.
- Manual:Synchronizer ring wear and clutch disc replacement dominate service profiles. Independent shops retain strong position due to lower diagnostic equipment barriers compared with automatic architectures.
- CVT:Pulley-and-belt systems with finite fatigue life require specialized tooling for ratio control recalibration. Belt pack replacement intervals cluster around manufacturer-specified mileage thresholds.
Automatic holds the largest share; momentum sits with Hybrid as electrification penetration accelerates.
Vehicle Type:
Cost tier stratification separates commodity fluid services from capital-intensive rebuild work requiring certified technicians.
- Heavy-Duty Vehicles:Class 8 transmissions endure extreme duty cycles demanding predictive maintenance protocols. Fleets along Texas I-35 and I-10 corridors generate concentrated demand for certified rebuild facilities.
- Passenger Cars:High-mileage ownership patterns sustain aftermarket volumes as vehicles age beyond powertrain warranty periods. Extended drain intervals with synthetic fluids compress routine service frequency.
- Light Trucks:Towing applications accelerate torque converter and clutch pack degradation. Owner-operators balance rebuild-versus-replace decisions against residual vehicle value.
- SUVs:All-wheel-drive transfer case integration complicates transmission service scope. Multi-plate clutch maintenance adds labor hours to standard gearbox work.
Heavy-Duty Vehicles command premium pricing; Passenger Cars deliver volume scale.
Repair Technique:
Application maturity separates established mechanical rebuild practices from emerging predictive and connected service models.
- Rebuild:Component-level refurbishment restores OE tolerances through valve body remanufacturing and clutch pack replacement. EPA emissions enforcement on heavy-duty vehicles elevates preventive rebuild demand over premature full replacements.
- Diagnostics:Electronic control module interrogation and telematics-integrated health monitoring enable pre-failure intervention. Subscription revenue models emerge among fleet operators contracting for connected service capabilities.
- Replacement:Full unit swap minimizes downtime for critical fleet assets. Remanufactured component supply concentration in Mexico creates geographic vulnerability for North American distributors.
- Fluid Change:Synthetic formulations rated for extended service intervals reduce visit frequency. Routine maintenance margins compress as drain intervals stretch toward manufacturer maximums.
Rebuild captures the deepest margin pools; Diagnostics is expanding most quickly.
Customer Type:
Volume concentration and margin structure diverge sharply between fragmented retail demand and consolidated fleet procurement.
- Fleets:Scheduled maintenance contracts and telematics integration centralize procurement with technology-capable providers. Large logistics operators now contract directly for transmission health monitoring subscriptions.
- Individual Owners:Failure-driven service patterns concentrate spend at end-of-warranty milestones. California BAR-licensed facilities command pricing power through consumer protection positioning.
- Dealerships:Warranty work and manufacturer-certified rebuild programs sustain captive service volumes. OE software access restrictions create friction for independent competitive response.
- Repair Shops:Independent rebuilders compete on speed and cost for out-of-warranty vehicles. Specialized tooling capital requirements strain smaller operators serving price-sensitive segments.
Fleets concentrate procurement power; Individual Owners fragment across price tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement managers concentrate transmission rebuild demand in corridors with heavy freight density and emissions enforcement pressure. Individual owners sustain aftermarket volumes in aging vehicle markets with extended ownership cycles.
United States
Class 8 truck fleets along the I-35 and I-10 corridors generate concentrated demand for certified rebuild facilities. The EPA enforces heavy-duty vehicle emissions standards that compress preventive maintenance cycles. Dallas-Fort Worth anchors the Southwest rebuild market with specialized shops serving owner-operators.
Germany
Precision manufacturing clusters sustain demand for OE-grade remanufactured components and valve body refurbishment. REACH substance restrictions accelerate reformulation of transmission fluid additive packages. Stuttgart's automotive engineering concentration drives technician training standards across European rebuild operations.
China
Rapid fleet expansion and commercial vehicle production sustain high-volume transmission service demand. MIIT enforces fuel consumption standards that elevate preventive maintenance adoption. The Yangtze River Delta manufacturing belt concentrates remanufacturing capacity for domestic and export markets.
Mexico
Cross-border supply chains position the country as a remanufactured component source for North American distributors. The central bank monitors inflation impacts on fleet capital expenditure cycles. Nuevo León's industrial corridor hosts transmission component production serving US aftermarket channels.
Japan
Hybrid drivetrain penetration creates specialized service demand for power-split devices and motor-generator units. METI promotes circular economy frameworks that elevate remanufacturing investment. Nagoya's automotive supplier cluster integrates precision bearing and gear production with rebuild aftermarket supply.
Transmission Repair Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where manufacturing-integrated suppliers hold technical authority and independent service chains capture consumer proximity. The market organizes around three archetypes: OE-anchored component suppliers, national franchise networks, and independent specialist shops. Consolidation pressures favor players with captive remanufacturing capacity and telematics-integrated service platforms. Geographic expansion and strategic partnerships dominate competitive moves as firms seek corridor density and fleet contract access.
Within the manufacturing-integrated tier, ZF Friedrichshafen AG and BorgWarner occupy positions defined by deep production expertise across conventional and electrified architectures. Schaeffler Group represents the precision-component archetype, anchoring rebuild supply through bearing and synchronizer ring leadership. These entities exemplify how OE-grade manufacturing integration translates into aftermarket parts authority and technician training influence.
| Leading Market Players |
|---|
| Schaeffler Group |
| ZF Friedrichshafen AG |
| Continental |
| Allison Transmission |
| BorgWarner |
| AAMCO Transmissions |
| Cottman Transmission and Total Auto Care |
| Mister Transmission |
| Firestone Complete Auto Care |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Mexican remanufactured valve bodies and torque converters compresses pricing tier spreads while forcing North American distributors into dual-sourcing arrangements that reshape inventory carrying costs and regional procurement patterns.
Pricing Analysis
Cost-plus contracts with steel and aluminum indexation dominate heavy-duty transmission rebuild agreements, insulating certified facilities from commodity volatility while squeezing margin at independent shops lacking volume scale. Price differentiation separates BAR-licensed California operators from uncertified competitors, with fleet procurement managers negotiating subscription-based predictive maintenance premiums. Pricing pressure stems from extended synthetic fluid drain intervals reducing routine service frequency. Individual owners exhibit highest price sensitivity, while telematics-integrated fleet contracts command lowest elasticity.
Supply Chain Analysis
Export-control restrictions on precision diagnostic software and calibration protocols limit cross-border flows of proprietary OE tools, fragmenting technician training standardization. Component supply concentrates in Mexico, Germany, and China, with valve body remanufacturing anchored in Nuevo León and precision bearings sourced from Stuttgart and Nagoya clusters. Rare earth magnet dependencies for hybrid motor-generator units and specialized friction materials for clutch packs create input vulnerabilities. Single-source exposure on remanufactured torque converters generates geographic risk. Distribution runs through authorized dealer networks, national franchise chains, and independent specialist shops with diverging technical capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification-driven competency fragmentation creates white-space niches for specialists bridging mechanical rebuild and power electronics diagnostics.
For Market Incumbents: Harden competitive position through captive remanufacturing capacity in Mexico and telematics platform integration that locks fleet procurement managers into subscription relationships. Acquire hybrid-certified technician pipelines to defend against emerging EV-native service entrants. Prioritize BAR certification investments in high-regulation states to sustain pricing power. For New Entrants and Emerging Players: Texas I-35 and I-10 corridor owner-operators represent the most penetrable entry point, with undercertified independent presence and concentrated Class 8 fleet density. Hybrid drivetrain bays in secondary US metro areas offer equipment arbitrage against legacy automatic specialists. Lead with telematics-integrated predictive maintenance subscriptions rather than transactional repair positioning. For Investors and Strategic Acquirers: EPA heavy-duty emissions enforcement deadlines reshape the acquisition landscape toward preventive maintenance-capable providers with fleet contract concentration. Five-to-ten-year viability favors shops with electrified drivetrain training infrastructure and corridor-density positioning. Monitor electrification penetration rates in commercial vehicle segments as the critical inflection signal for rebuild-versus-replacement demand mix.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables subscription revenue capture from fleet operators requiring predictive transmission health monitoring. |
| Hybrid Certification Investment | Addresses technician scarcity in power electronics and motor-generator unit repair across electrified drivetrains. |
| Corridor Density Expansion | Captures owner-operator segments along Texas I-35 and I-10 freight routes with specialized heavy-duty capabilities. |
| Remanufacturing Capacity Buildout | Reduces geographic vulnerability from Mexican component concentration through captive valve body production. |
| Regulatory Certification Acquisition | Secures California BAR licensing premium and EPA emissions compliance positioning for fleet contracts. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of NHTSA recall databases, EPA enforcement disclosures, state BAR inspection records, and automotive aftermarket trade data. Interviews with fleet maintenance directors, independent shop owners, OEM aftermarket managers, and transmission component distributors informed demand-side calibration. SEC filings from manufacturing-integrated suppliers and customs records on remanufactured component trade flows provided supply-side validation. Bottom-up service volume estimates triangulated against top-down vehicle parc and mileage accumulation models.
Forecast inputs incorporate drivetrain architecture mix shifts, technician certification penetration rates, and fleet telematics adoption curves across the projection horizon. Segmentation dimensions modeled include service type, vehicle class, repair technique, and customer procurement structure. CAGRs derived from elasticity-adjusted demand curves and replacement cycle compression factors. Industry-specific inputs encompass EPA enforcement intensity timelines and electrified vehicle sales penetration assumptions.
Practitioners should monitor regulatory enforcement escalation, electrification subsidy modifications, and remanufactured component trade policy for early signals of demand trajectory revision. Forecasts reflect assumptions on fleet retention patterns and synthetic fluid technology stability. Material shifts in heavy-duty emissions compliance deadlines or hybrid drivetrain reliability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Engine Cylinder Liners Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
Automotive Slipper Clutch Market
Powertrain
Exhaust System Muffler Market
Powertrain
EV Drivetrain Systems Market
Powertrain
Car Active Purge Pump Market
Powertrain
Drive Shaft Market
Powertrain
Automotive Engine Piston Rings Market
Powertrain
Electric Powertrain Systems Market
Powertrain
New Energy Vehicle Scroll Compressor Market
Powertrain
LNG Engine Market
Powertrain
Global Automotive Electric Drivetrain System Market
Powertrain
Global Industrial Turbocharger Market
Powertrain
Automotive Variable Oil Pump Market
Powertrain
Automotive Carburetor Market
Powertrain
Global Automotive Damper Pulley Market