
 Lithium-Ion Forklift Battery Market | 2026-2036
Lithium-Ion Forklift Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Forklift Battery Market Insights
High-cycle-life phosphate chemistry is redrawing performance expectations for industrial motive power. CATL leverages its cell-scale manufacturing to supply integrated pack solutions for OEM forklift programs. EnerSys anchors the aftermarket service layer through its network of authorized dealers and on-site maintenance contracts. BYD Company Ltd. differentiates by controlling cathode production and battery assembly under one corporate structure.
Lithium-ion forklift batteries store electrical energy in lithium iron phosphate or nickel manganese cobalt oxide cells, delivering deep-cycle durability above two thousand charge cycles at stable voltage curves. Their primary purpose is to replace lead-acid traction batteries in electric material handling equipment, eliminating watering intervals and acid spills while supporting opportunity charging during operator breaks. High-capacity product types command the strongest margin pools as cold storage and multi-shift manufacturing facilities demand sustained amp-hour output across extended duty cycles. Fast charging technology is gaining share fastest among technology segments because warehouses prioritize fleet uptime over battery swap logistics. Indoor use applications dominate volume, though cold storage represents the highest-specification tier with heated cell architectures and thermal management systems.
OSHA indoor air quality enforcement and EPA emissions standards are restricting propane and diesel forklift operation in enclosed facilities, directly expanding addressable demand for electric alternatives. The EU F-Gas Regulation and REACH chemical compliance frameworks are shaping cell chemistry selection and thermal management fluid specifications for equipment sold in Europe. Stakeholders must monitor cell raw material cost volatility and charging infrastructure deployment timelines as they evaluate fleet conversion schedules and total cost of ownership models.
Market Dynamics
Opportunity charging infrastructure is compressing fleet downtime economics and eroding the residual value logic that once favored lead-acid battery swapping systems in multi-shift warehousing operations.
Growth Catalysts
- OSHA indoor air quality enforcement:EPA emissions standards and OSHA workplace exposure limits are prohibiting propane forklift operation in enclosed distribution centers across the United States, forcing electric conversion.
- Iron phosphate cell chemistry:Lithium iron phosphate formulations deliver cycle life exceeding two thousand deep discharges without voltage sag, eliminating the watering and equalization labor burden of lead-acid alternatives.
- Cold storage specification tier:Heated cell architectures with active thermal management are capturing premium positioning in frozen food logistics where sub-zero ambient temperatures degrade conventional battery output.
Market Restraints
- Lithium carbonate price volatility:Cathode raw material cost swings compress pack margin structures and destabilize total cost of ownership calculations against lead-acid baselines.
- Cell supply concentration:Cylindrical and prismatic cell output clusters in China, creating geographic single-source risk for OEMs assembling packs outside domestic tariff jurisdictions.
- Charging infrastructure capex:High-amperage opportunity charging stations require electrical service upgrades that strain facility capital budgets and utility interconnection timelines.
Strategic Opportunities
- Secondary life applications:Retired forklift packs with seventy percent residual capacity are entering stationary energy storage for solar-buffered charging depots, extending value capture beyond motive power.
- EU F-Gas Regulation alignment:Thermal management system refrigerant selection for European-bound equipment must transition to low-global-warming-potential fluids, favoring suppliers with compliant engineering pipelines.
- Telematics-integrated battery management:Real-time state-of-health monitoring via cellular-connected battery management systems enables predictive maintenance contracts and usage-based financing structures.
Industry Challenges
- Electrical technician scarcity:High-voltage pack diagnostics and cell balancing repair require specialized training that outpaces vocational program output in mature warehousing markets.
- UL 2580 certification timelines:Third-party abuse testing and thermal runaway propagation validation for new pack form factors extend product launch schedules by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Forklift Battery Market |
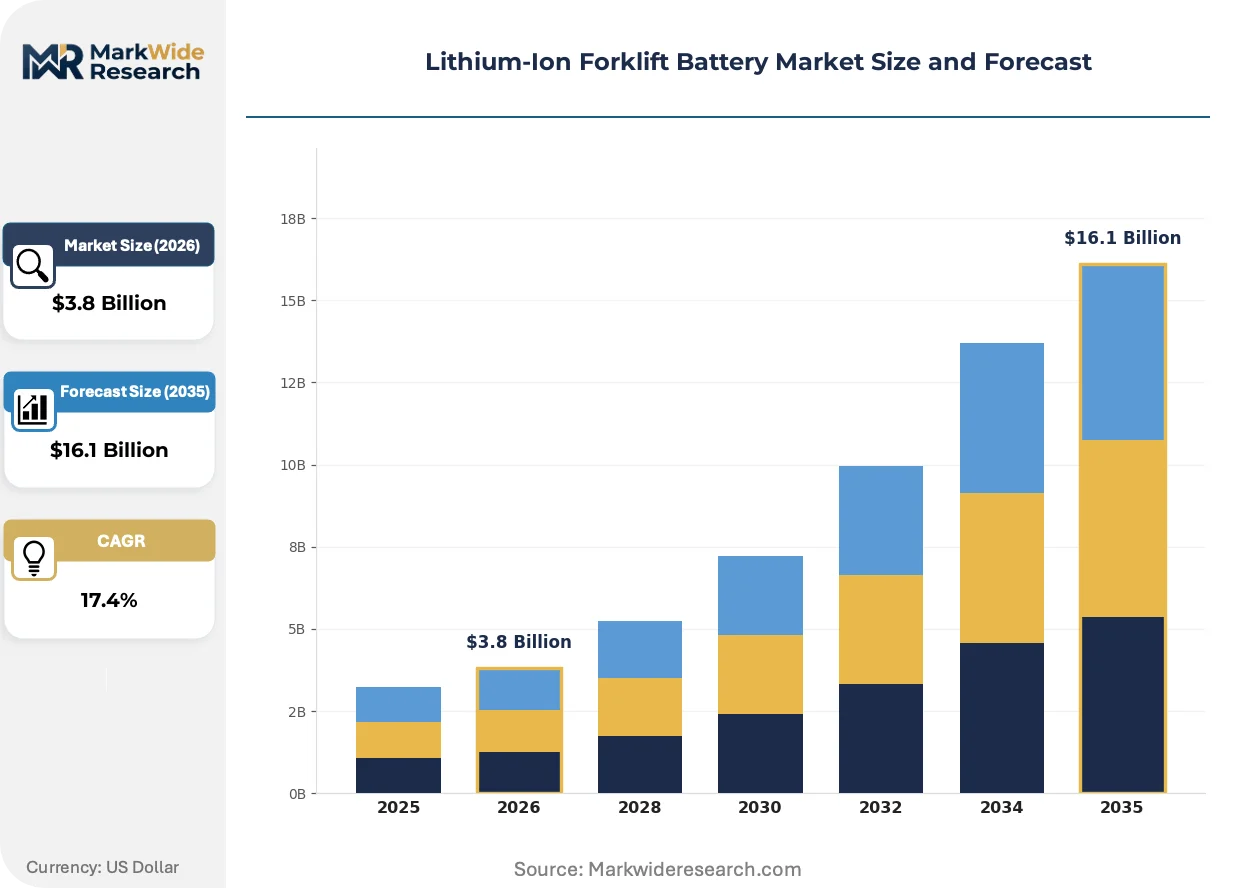
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.1 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact, Standard, High-Capacity, Heavy-Duty End User: Logistics, Manufacturing, Retail, Warehousing Technology: Smart Battery Management, Fast Charging, Scalable Systems, Battery Recyclability Application: Indoor Use, Outdoor Use, Cold Storage, Specialized Equipment |
| Companies Covered | BYD Company Ltd., CATL, Exide Technologies, EnerSys, Hiitio New Energy, LG Energy Solution, KION Group, Crown Equipment Corporation, Toyota Industries Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Forklift Battery Market Trends and Innovations
Modular pack architectures and intelligent thermal management are converging to enable platform-agnostic battery systems that span multiple forklift OEM form factors without custom engineering.
Cell-to-pack structural designs are miniaturizing auxiliary components by eliminating module housings and bussing layers. Cold storage operators and automotive parts distributors are adopting these denser configurations to maximize amp-hour capacity within existing battery compartment envelopes. The technology is miniaturizing the physical footprint of high-capacity systems while maintaining the thermal stability required for opportunity charging cycles.
REACH chemical compliance frameworks are restricting thermal management fluid formulations and cell electrolyte additives for equipment sold in Europe. Industrial vehicle manufacturers are reformulating coolant chemistries and securing substance registration dossiers to maintain market access. The regulation is compressing supplier qualification timelines and favoring pack assemblers with established European chemical safety documentation.
Leasing structures are displacing outright purchase for forklift battery procurement as fleet operators prioritize operational expenditure treatment and technology refresh flexibility. Third-party battery-as-a-service providers are capturing mid-market warehousing accounts with bundled maintenance and guaranteed capacity contracts. Germany and the Netherlands exhibit the highest penetration of usage-based financing models, reflecting mature energy-as-a-service infrastructure in those markets.
Lithium-Ion Forklift Battery Market Segmentation
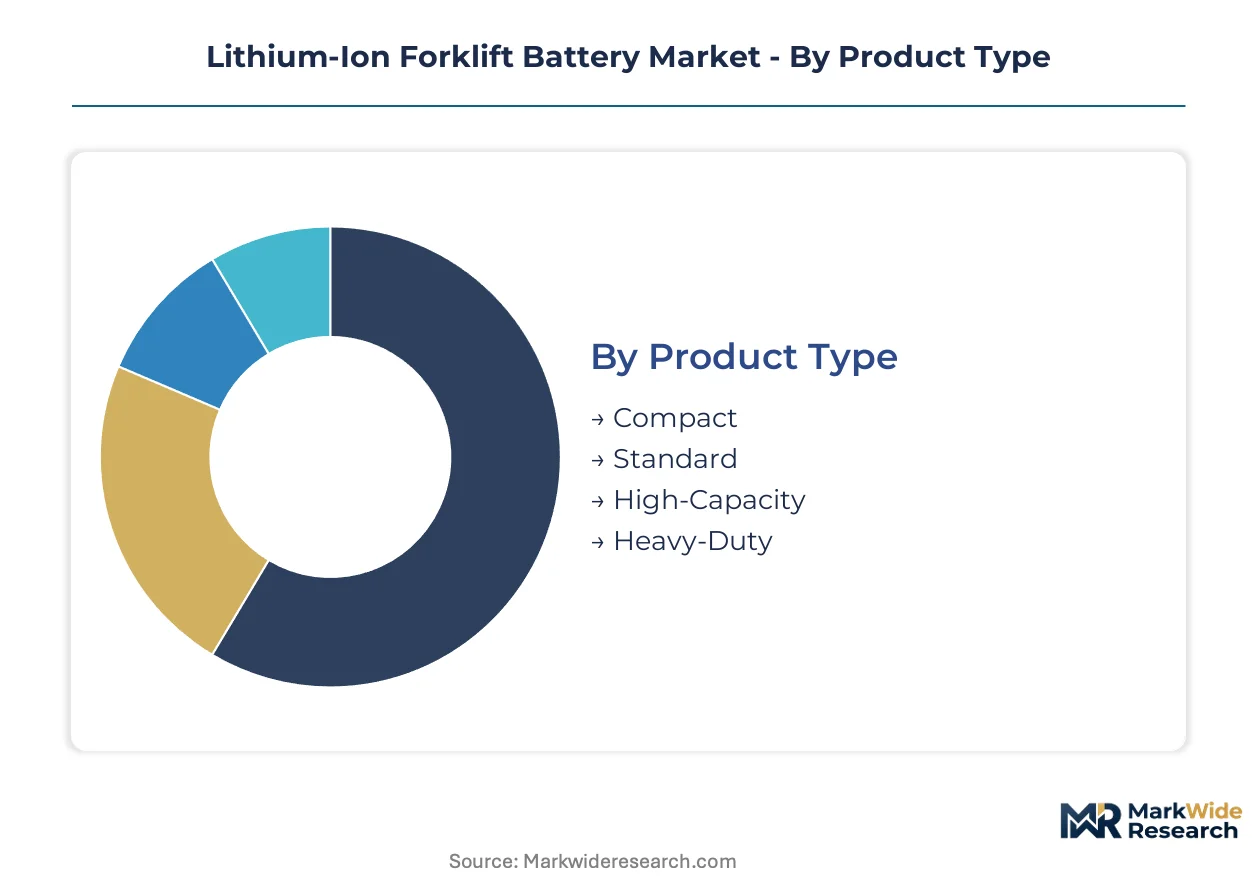
Segmentation in the lithium-ion forklift battery market reveals where lead-acid substitution pressure concentrates and which technical specifications command premium positioning. Understanding these divides helps suppliers align cell chemistry, thermal architecture, and service models to specific operational demands.
Product Type:
Substitution pressure from lead-acid systems intensifies with battery scale, as larger facilities face the steepest downtime penalties from legacy watering and swap logistics.
- High-Capacity:These packs deliver sustained amp-hour output across extended duty cycles for multi-shift manufacturing and cold storage facilities. Demand concentrates in frozen food logistics and automotive parts distribution where heated cell architectures preserve performance in sub-zero ambient conditions. OSHA indoor air quality enforcement in enclosed U.S. distribution centers accelerates displacement of propane fleets in this segment.
- Heavy-Duty:Engineered for the highest draw applications including container handling and steel coil transport. Procurement clusters at port terminals in Germany, the Netherlands, and the U.S. Gulf Coast where electrification timelines align with EPA emissions compliance deadlines for harbor craft and cargo handling equipment.
- Standard:Mid-range configurations serve single-shift warehousing with moderate throughput requirements.
- Compact:Smaller form factors fit narrow-aisle forklifts and pedestrian pallet trucks in retail backrooms.
Standard configurations anchor the volume base while high-capacity systems gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive facilities with dedicated maintenance staff from lean operations prioritizing operational expenditure treatment.
- Warehousing:Third-party logistics operators and e-commerce fulfillment centers drive the largest absolute demand. Multi-shift facilities in China, Germany, and the United States adopt opportunity charging infrastructure to compress fleet downtime economics. The segment favors battery-as-a-service procurement models with bundled maintenance contracts.
- Manufacturing:Automotive and electronics assembly plants require synchronized battery fleets for just-in-time material flow. Production concentration in Mexico, Thailand, and Hungary shapes regional pack specification requirements.
- Logistics:Freight forwarding and drayage operators at intermodal terminals face electrification mandates from port authorities.
- Retail:Big-box distribution centers and grocery chains prioritize compact footprints and rapid deployment timelines.
Warehousing anchors installed capacity while manufacturing exhibits the steepest expansion trajectory as production reshoring accelerates fleet refresh cycles.
Technology:
Application maturity varies sharply, with some technologies already standard and others still navigating certification and infrastructure deployment hurdles.
- Fast Charging:High-amperage opportunity charging enables continuous operation without battery swaps, eliminating the residual value logic that favored lead-acid systems. Deployment concentrates in the United States and Germany where electrical service upgrades and utility interconnection timelines strain facility capital budgets. The technology compresses total cost of ownership calculations for multi-shift operations.
- Smart Battery Management:Cellular-connected state-of-health monitoring enables predictive maintenance and usage-based financing structures. Adoption runs highest in the Netherlands and Germany where energy-as-a-service infrastructure supports telematics-integrated fleet management.
- Scalable Systems:Modular pack architectures allow capacity expansion without full replacement.
- Battery Recyclability:Design-for-disassembly protocols and secondary life applications extend value capture beyond motive power.
Smart battery management anchors current deployment volumes while fast charging climbs the fastest as warehouse operators prioritize uptime over infrastructure capex deferral.
Application:
Geography and climate dictate thermal architecture requirements, with sub-zero specifications commanding the most specialized engineering pipelines.
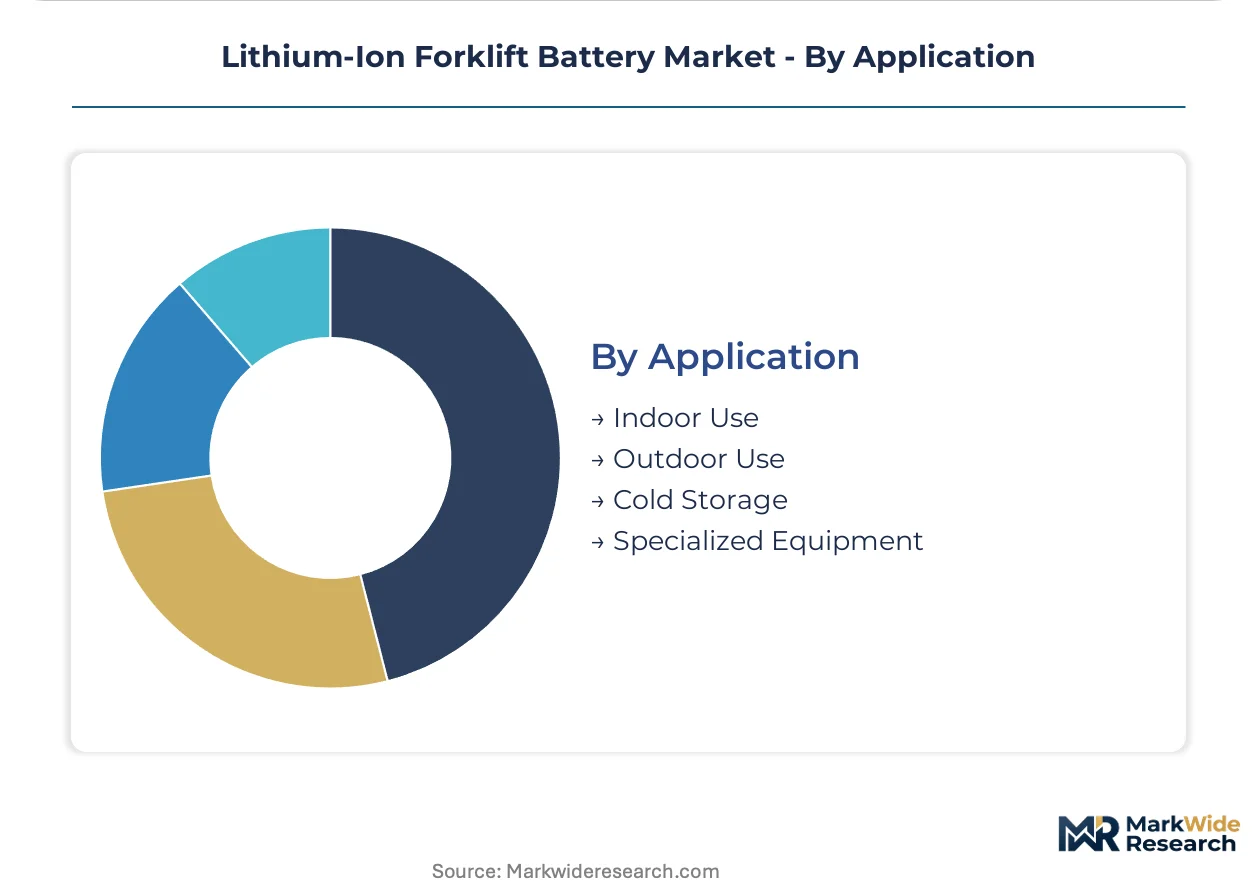
- Cold Storage:Heated cell architectures with active thermal management capture premium positioning in frozen food logistics. Demand concentrates in the United States, Germany, and China where pharmaceutical cold chains and grocery distribution networks face stringent temperature integrity requirements. EU F-Gas Regulation compliance for thermal management fluids shapes supplier qualification timelines.
- Indoor Use:Enclosed distribution centers and manufacturing floors represent the largest volume application. EPA emissions standards and OSHA workplace exposure limits in the United States prohibit propane forklift operation, forcing electric conversion across the segment.
- Outdoor Use:Yard trucks and container handlers at intermodal terminals face weatherproofing and vibration resistance requirements.
- Specialized Equipment:Narrow-aisle reach trucks, order pickers, and automated guided vehicles demand customized form factors.
Indoor use anchors the volume base while cold storage gains share fastest as pharmaceutical and frozen food logistics expand temperature-controlled capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and Germany exhibit low price elasticity as total cost of ownership calculations favor lithium-ion lifecycle economics, while operators in India and Southeast Asia remain acutely sensitive to upfront pack premiums against lead-acid baselines.
United States
Multi-shift e-commerce fulfillment centers in California and Texas drive fleet electrification at the fastest pace among OECD markets. OSHA workplace exposure limits and EPA emissions standards prohibit propane forklift operation in enclosed distribution centers, forcing electric conversion across the segment. The Inland Empire logistics cluster east of Los Angeles anchors the largest concentration of opportunity charging infrastructure deployment.
China
Domestic cell manufacturing scale from BYD and CATL compresses pack costs below import parity for warehousing operators in the Yangtze River Delta. MIIT industrial policy and dual carbon goals accelerate the phase-out of internal combustion material handling equipment in state-owned logistics networks. Shenzhen and Dongguan manufacturing corridors supply integrated battery-forklift systems for export markets across Southeast Asia.
Germany
Automotive parts distributors and pharmaceutical cold chain operators in Bavaria and Baden-Württemberg demand heated cell architectures for sub-zero warehouse specifications. The EU F-Gas Regulation shapes thermal management fluid selection for equipment sold across the single market, compressing supplier qualification timelines. The Port of Hamburg electrification timeline for cargo handling equipment aligns with harbor craft emissions compliance deadlines.
Netherlands
Third-party logistics operators in the Randstad cluster adopt battery-as-a-service procurement models with bundled maintenance contracts at the highest penetration rate in Europe. REACH chemical compliance frameworks restrict electrolyte additive formulations for equipment sold in the Dutch market. Eindhoven Region warehousing parks deploy telematics-integrated fleet management systems for real-time state-of-health monitoring.
India
Price-sensitive single-shift warehousing operators in Maharashtra and Karnataka defer lithium-ion conversion until pack costs approach lead-acid parity on a capital expenditure basis. BIS certification requirements and PLI scheme incentives for domestic cell manufacturing reshape supplier qualification pathways for OEMs assembling packs locally. The Delhi-NCR logistics corridor concentrates demand from e-commerce fulfillment centers with multi-shift operations capable of capturing opportunity charging economics.
Lithium-Ion Forklift Battery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with cell-scale manufacturers anchoring the upstream while pack integrators and aftermarket service networks compete on deployment velocity. The market structure concentrates around three strategic tiers: captive cell producers with backward integration into cathode materials, independent pack assemblers sourcing cylindrical and prismatic cells from third parties, and industrial battery specialists with authorized dealer networks for on-site maintenance. Dominant competitive moves include capacity expansion in phosphate cell chemistry and strategic partnerships between pack suppliers and forklift OEMs for platform-agnostic battery systems.
Among cell-scale producers, BYD Company Ltd. and CATL exemplify the captive manufacturing archetype with in-house cathode production and integrated pack assembly, while EnerSys anchors the aftermarket service tier through its network of authorized dealers and on-site maintenance contracts. These three players occupy positions that span the value chain from raw material processing through fleet deployment, representing the dominant competitive configurations in the current market structure.
| Leading Market Players |
|---|
| BYD Company Ltd. |
| CATL |
| Exide Technologies |
| EnerSys |
| Hiitio New Energy |
| LG Energy Solution |
| KION Group |
| Crown Equipment Corporation |
| Toyota Industries Corporation |
| Others |
Pricing and Supply Chain Analysis
Lead-acid fleet replacement by lithium-ion packs simultaneously redraws supply geography toward Chinese cell production clusters and compresses pack margin structures as cathode raw material costs dominate total cost of ownership calculations for warehousing operators.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions drive lifetime value capture beyond initial pack sales. Three-tier pricing structure across premium, standard, and economy levels separates heated cold-storage architectures with active thermal management from basic indoor configurations. Cost compression in standard-tier packs is intensifying because lithium carbonate price volatility feeds directly into cathode cost stacks. Single-shift warehousing operators in India and Southeast Asia exhibit the highest price sensitivity, while multi-shift facilities in Germany and the United States prioritize uptime economics over capital expenditure minimization.
Supply Chain Analysis
Yangtze River Delta port congestion and Panama Canal transit constraints expose just-in-time cell delivery schedules to logistics disruption. Cylindrical and prismatic cell output clusters in China, South Korea, and Japan. Pack assembly draws from lithium iron phosphate cathode precursors, copper foil current collectors, and electrolyte formulations. Single-source vulnerability concentrates in Chinese cathode active material production. Distribution runs through authorized dealer networks for aftermarket service and direct OEM supply agreements for new forklift integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified high-voltage technician shortages and UL 2580 thermal runaway validation bottlenecks constrain how quickly pack suppliers can scale deployment velocity against surging warehouse electrification timelines.
For Market Incumbents: Secure captive cathode supply through backward integration into lithium iron phosphate precursor production or long-term offtake agreements with Chinese chemical processors. Expand fast-charging infrastructure deployment partnerships with third-party logistics operators to lock in multi-shift warehousing accounts before battery-as-a-service entrants capture mid-market share. For New Entrants and Emerging Players: Predictive maintenance service gaps in the aftermarket layer offer white-space entry points where incumbents under-serve single-shift operators with limited in-house electrical technician staff. Target India's Maharashtra and Karnataka warehousing corridors where BIS certification requirements and PLI scheme incentives reshape supplier qualification pathways for locally assembled packs. Lead with telematics-integrated battery management subscriptions to differentiate from transactional pack sales. For Investors and Strategic Acquirers: The market sits at a substitution-acceleration phase that favors pack assemblers with established European chemical safety documentation and REACH-compliant thermal management fluid pipelines. Long-term viability hinges on secondary-life stationary storage revenue streams and circular economy positioning. Monitor EU F-Gas Regulation enforcement timelines as the inflection signal for thermal management system supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursors | Captive lithium iron phosphate supply insulates margin structures from carbonate price volatility. |
| Fast-Charging Infrastructure Partnerships | High-amperage opportunity charging stations lock in multi-shift warehousing accounts with uptime guarantees. |
| Battery-as-a-Service Launch | Usage-based financing with bundled maintenance captures mid-market operators prioritizing operational expenditure treatment. |
| REACH-Compliant Thermal Management Reformulation | Low-global-warming-potential coolant selection preserves European market access under F-Gas Regulation. |
| Telematics-Integrated Predictive Maintenance | Cellular-connected state-of-health monitoring enables subscription revenue and usage-based insurance structures. |
Research Methodology
Initial hypotheses were tested against primary input from warehouse operations directors, forklift OEM procurement teams, aftermarket service technicians, and battery pack engineering leads and refined through secondary validation against customs trade data, MIIT industrial policy filings, SEC 10-K disclosures, and OSHA enforcement records. Bottom-up unit economics from individual facility fleet conversions were triangulated against top-down market sizing from regional production and import data.
Variance decomposition across product type, end-user industry, technology tier, application environment, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from logistic diffusion modeling of lead-acid substitution rates combined with charging infrastructure deployment timelines. Industry-specific forecast inputs included utility interconnection queue data for high-amperage opportunity charging stations and BIS certification pathway timelines for Indian market entry.
Underlying assumptions cover lithium carbonate price stabilization, OSHA indoor air quality enforcement continuity, and EU F-Gas Regulation compliance deadlines, with deviation risk concentrated in cell supply concentration and electrical technician training program output. Practitioners should keep alternative scenarios live as cathode raw material cost volatility and tariff jurisdiction shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Cobalt Oxide Market
Lithium-ion Battery
EV SOLID State Battery Market
Lithium-ion Battery
Lithium Battery Components Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
Canada Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium Solid-State Battery Market
Lithium-ion Battery
Lithium Battery in Myanmar Market
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
Nanobolt Lithium Tungsten Batteries Market
Lithium-ion Battery
Lithium Battery Cells for Passenger Car Market
Lithium-ion Battery
Cathode Material of Power Lithium Battery Market
Lithium-ion Battery
Pouch Lithium-Ion Batteries Market
Lithium-ion Battery
North America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
Bangladesh Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Hydroxide Market