
 Southeast Asia Lithium-Ion Battery Market | 2026-2036
Southeast Asia Lithium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Lithium-Ion Battery Market Analytics
Battery-as-a-service and subscription-based energy storage contracts is repositioning how industrial buyers procure lithium-ion systems across Southeast Asia. CATL leverages its integrated cell-to-pack manufacturing footprint to anchor supply relationships with regional EV assemblers. Samsung SDI differentiates through high-nickel cathode chemistry leadership for premium electric vehicle programs. BYD Co Ltd extends its competitive position through in-house production of lithium iron phosphate cells for stationary storage deployments.
Southeast Asia lithium-ion batteries are rechargeable electrochemical cells employing lithium intercalation compounds in graphite anodes and metal oxide cathodes, typically operating at nominal voltages of 3.2V to 3.7V per cell with energy densities ranging from 150Wh/kg to 300Wh/kg depending on cathode chemistry; these systems store and discharge electrical energy through reversible lithium ion migration between electrodes during charge and discharge cycles. Electric Vehicle applications command the dominant share of regional investment as automotive OEMs localize battery pack assembly. Grid Storage represents the fastest-expanding application segment as utilities in the Philippines and Vietnam deploy lithium-ion systems for frequency regulation and renewable firming. Portable product types retain mature demand profiles tied to consumer electronics manufacturing clusters in Malaysia and Thailand.
Thailand's Board of Investment incentive frameworks and Indonesia's downstream mineral processing regulations are reshaping where cathode active material production localizes across ASEAN. BIS-equivalent standards adoption in Vietnam and CDSCO-aligned import certification requirements in India create divergent compliance pathways for cell suppliers entering adjacent South and Southeast Asian markets. Stakeholders must track how Indonesia's nickel export ban enforcement and evolving ASEAN harmonized technical regulations for battery safety will determine which manufacturing configurations achieve cost-competitive scale.
Market Dynamics
Indonesia's nickel export ban enforcement is forcing cathode active material production to localize within ASEAN, compressing supply chain distances for regional EV assemblers while reshaping where battery-grade precursor chemicals achieve cost-competitive scale.
Growth Catalysts
- Thailand's BOI incentive frameworks:Battery pack assembly investments qualify for eight-year tax holidays and import duty exemptions on manufacturing equipment, accelerating EV supply chain localization.
- Utility-scale storage tenders:Vietnam's revised power development plan mandates 300MW of grid-connected battery systems by 2030, creating immediate procurement pipelines for lithium-ion integrators.
- Nickel-manganese-cobalt chemistry:Indonesian integrated industrial corridors now produce battery-grade nickel sulfate from laterite ore, reducing raw material transit costs for regional cell manufacturers.
Market Restraints
- Lithium carbonate price volatility:Spot market swings for battery-grade lithium salts compress cell producer margins and destabilize long-term offtake contract negotiations.
- Single-source cathode precursor dependence:Southeast Asian pack assemblers rely on Chinese refined nickel and cobalt intermediates, exposing production schedules to export license delays.
- Thermal runaway containment costs:Stringent UN 38.3 and IEC 62619 testing requirements for maritime battery transport add certification overhead to export-bound production.
Strategic Opportunities
- Philippines grid storage deployment:Island utilities seek 100MWh-class battery systems for diesel displacement and renewable firming, with procurement frameworks favoring turnkey EPC contractors.
- Battery-as-a-service contracts:Industrial offtakers in Thai manufacturing zones are piloting subscription-based energy storage without upfront capital expenditure, opening new revenue models for system integrators.
- ASEAN harmonized technical regulations:Draft battery safety standards under ASEAN sectoral bodies promise mutual recognition agreements, reducing multi-country certification burdens for regional suppliers.
Industry Challenges
- Cell engineering talent scarcity:Southeast Asian universities produce insufficient electrochemistry and battery management system firmware specialists, forcing manufacturers to recruit from South Korean and Chinese labor pools.
- BIS-equivalent standard alignment:Vietnamese certification bodies require 12-18 month testing cycles for cell imports, delaying product launches versus Thai and Indonesian regulatory pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Lithium-Ion Battery Market |
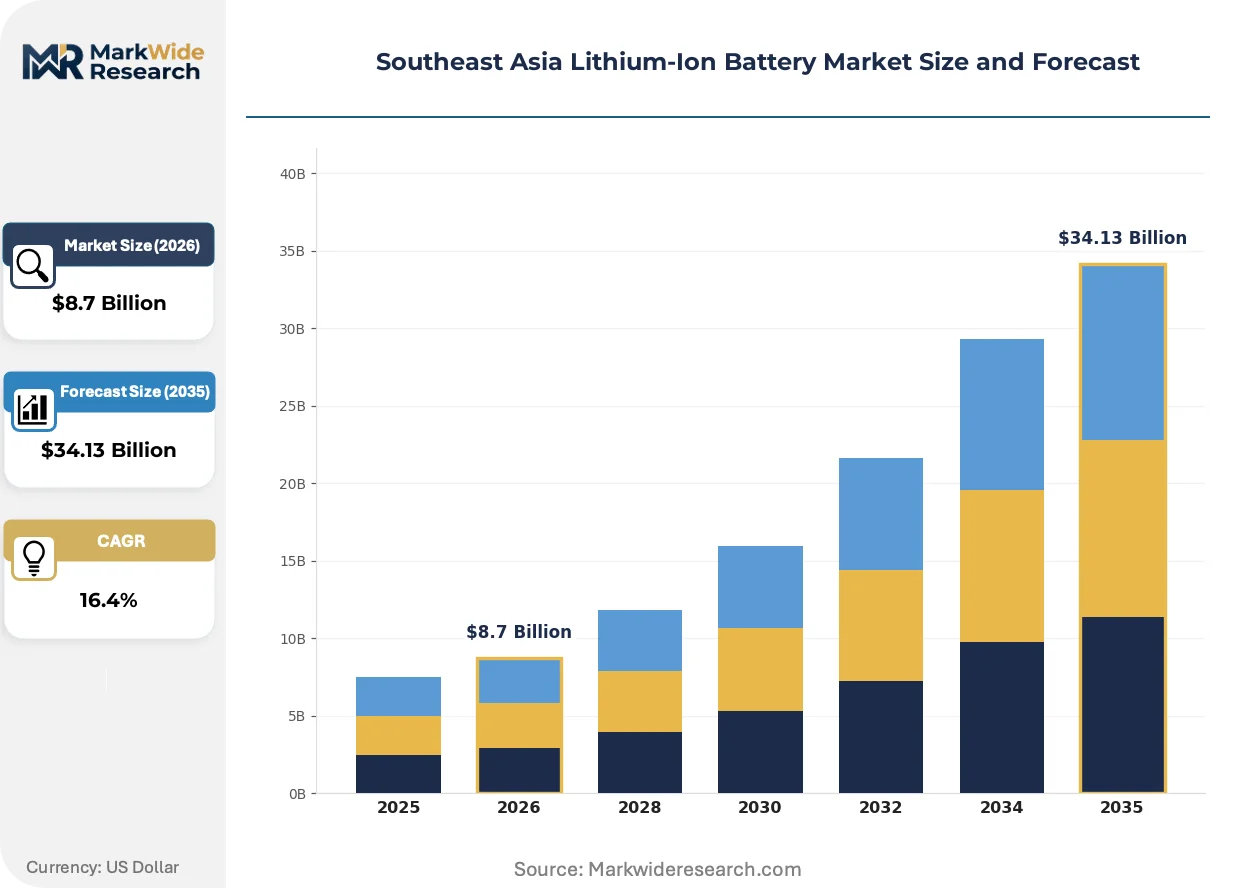
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
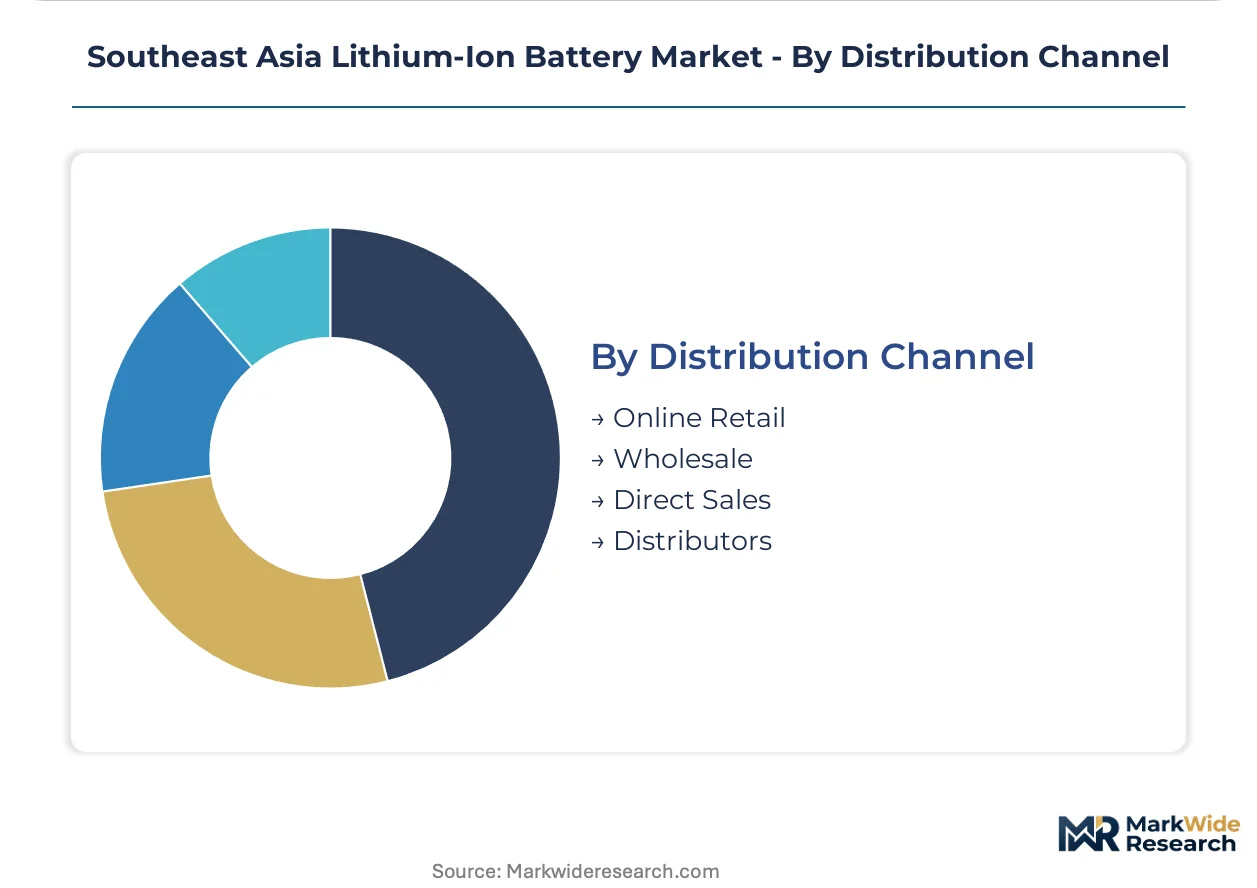
| Segmentation | Product Type: Portable, Stationary, Electric Vehicle, Industrial Application: Consumer Electronics, Electric Vehicles, Renewable Energy, Grid Storage End User: Automobile Manufacturers, Electronics Companies, Utilities, Aerospace Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | BYD Co Ltd, Sunwoda, CATL (Contemporary Amperex Technology Co Ltd), GS Yuasa Corporation, EVE Energy, LG Energy Solution, Panasonic Corporation, Saft Groupe SA, Samsung SDI, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Lithium-Ion Battery Market Evolving Landscape
Lithium iron phosphate chemistry is absorbing capital allocation across Southeast Asian stationary storage deployments as procurement criteria prioritize cycle life and thermal stability over energy density.
Lithium iron phosphate cathode technology offers 6,000+ cycle lifespans and inherent thermal stability without cobalt content. Thai and Vietnamese utility procurement teams specify LFP cells for 4-hour grid storage tenders. This chemistry is absorbing market share from nickel-manganese-cobalt alternatives in stationary applications where volumetric energy density carries lower priority.
Indonesia's downstream mineral processing regulations mandate that exported nickel products meet minimum refining thresholds, compelling battery precursor producers to locate smelting and hydrometallurgical facilities within Indonesian industrial zones. Cell manufacturers seeking nickel sulfate offtake agreements must now negotiate directly with Indonesian state-linked mining consortia rather than trading houses. Thai and Malaysian pack assemblers are responding by securing multi-year supply contracts with Indonesian refining ventures.
Industrial buyers in Vietnam's manufacturing corridors are unbundling battery system procurement from engineering services, contracting separate vendors for cell supply, container integration, and software control layers. This disaggregation enables price discovery across subsystem tiers but complicates warranty liability allocation. The pattern is most visible in Ho Chi Minh City industrial zones where foreign-owned manufacturers operate captive solar-plus-storage microgrids.
Southeast Asia Lithium-Ion Battery Market Segmentation

Segmentation reveals how capital requirements and procurement patterns diverge across Southeast Asian lithium-ion battery demand. Each dimension exposes distinct margin structures and localization incentives for cell producers and pack integrators.
Product Type:
Capital intensity varies sharply across product categories, with Electric Vehicle and Industrial systems requiring the heaviest upfront manufacturing investment.
- Electric Vehicle:Nickel-manganese-cobalt and lithium iron phosphate cell configurations dominate regional EV pack assembly. Thai and Indonesian automotive OEMs are localizing battery module production to capture Board of Investment incentives and reduce import duty exposure.
- Industrial:Heavy-duty motive power and stationary systems for manufacturing facilities demand 50-100 kWh rack configurations with active thermal management. Vietnamese industrial zones are deploying these systems for peak shaving and backup power.
- Stationary:Grid-tied and behind-the-meter storage systems prioritize cycle life over energy density.
- Portable:Cylindrical and pouch cells for consumer devices retain mature demand profiles in Malaysian electronics clusters.
Most installed capacity flows through Electric Vehicle. Expansion is steepest in Industrial.
Application:
Application segments map directly to divergent procurement cycles and contract structures across ASEAN utilities and manufacturers.
- Grid Storage:Utility-scale battery systems for frequency regulation and renewable firming require 4-hour duration configurations. Vietnam's power development plan mandates procurement through competitive tenders, while Philippine island utilities seek diesel displacement solutions.
- Electric Vehicles:Passenger and commercial vehicle electrification programs in Thailand and Indonesia are driving cell demand through localized pack assembly partnerships with Chinese and Korean suppliers.
- Renewable Energy:Solar-plus-storage hybrid projects in Vietnam and the Philippines require DC-coupled battery inverters with grid-forming capabilities.
- Consumer Electronics:Smartphone, laptop, and power tool battery demand concentrates in Malaysian and Thai contract manufacturing zones.
Grid Storage is gaining share fastest. Electric Vehicles retains the largest revenue base.
End User:
End user categories reflect fundamentally different technical specifications and supplier qualification requirements.
- Automobile Manufacturers:Thai and Indonesian EV assemblers specify cell-to-pack architectures with integrated battery management systems and thermal runaway containment.
- Utilities:State-owned power companies in Vietnam and the Philippines procure turnkey energy storage systems through EPC contractors with 15-20 year service agreements.
- Electronics Companies:Consumer device OEMs in Malaysia source standardized cylindrical cells through established trading relationships with Korean and Chinese suppliers.
- Aerospace:Defense and aviation applications in Singapore and Thailand require UN 38.3 certified cells with extended qualification testing.
Automobile Manufacturers absorb the greatest cell volume. Utilities are scaling procurement most aggressively.
Distribution Channel:
Channel selection determines margin capture and technical support obligations for battery system vendors.
- Direct Sales:Large-scale utility and automotive contracts bypass intermediaries, with cell manufacturers negotiating directly with Indonesian state-linked mining consortia and Thai BOI-registered assemblers for multi-year offtake agreements.
- Distributors:Regional trading houses stock cylindrical cells and small-format packs for industrial replacement markets across ASEAN manufacturing corridors.
- Wholesale:Volume procurement of standard cell formats serves Malaysian and Thai electronics contract manufacturers with predictable consumption patterns.
- Online Retail:E-commerce platforms distribute replacement batteries and power banks to consumer and small commercial segments.
Direct Sales commands the highest contract values. Distributors are adding technical service capabilities fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where battery production migrates across ASEAN, as cost-of-compliance gaps between national certification regimes determine where cell assembly and pack integration achieve scale. Thailand's accelerated approval pathways and Indonesia's downstream mineral mandates are pulling investment away from markets with protracted testing cycles.
Indonesia
Integrated EV-battery industrial corridors in Morowali and Bintan are absorbing the majority of regional nickel processing investment. The country's downstream mineral processing regulations mandate domestic refining of laterite ore into battery-grade nickel sulfate. Korean and Chinese cell manufacturers are negotiating long-term offtake agreements directly with state-linked mining consortia to secure precursor chemical supply.
Thailand
Automotive OEMs are localizing battery module production to capture Board of Investment incentives including eight-year tax holidays. The BOI framework qualifies pack assembly investments for import duty exemptions on manufacturing equipment. Rayong and Chonburi industrial zones are concentrating EV supply chain activity as Chinese and Japanese assemblers establish captive battery operations.
Vietnam
Revised power development plans mandate 300MW of grid-connected battery systems by 2030, creating immediate procurement pipelines for lithium-ion integrators. The country's national technical regulator requires 12-18 month testing cycles for cell imports, compressing product launch timelines versus Thai pathways. Ho Chi Minh City industrial zones are deploying solar-plus-storage microgrids with unbundled procurement separating cell supply from system integration.
Philippines
Island utilities are seeking 100MWh-class battery systems for diesel displacement and renewable firming, with procurement frameworks favoring turnkey EPC contractors. The archipelago geography creates distributed demand for frequency regulation assets. Batangas and Cebu manufacturing corridors are emerging as integration hubs for containerized storage systems serving off-grid and weak-grid applications.
Singapore
Advanced battery testing and certification services are concentrating in Singapore to serve ASEAN-wide compliance needs. The city-state's technical infrastructure supports UN 38.3 and IEC 62619 certification for maritime battery transport. Research partnerships between local institutes and Korean cell manufacturers are developing thermal management systems for tropical climate deployments.
Southeast Asia Lithium-Ion Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cell producers commanding premium positions in automotive supply chains while pack integrators compete on assembly efficiency in stationary storage. The vendor base concentrates around three strategic archetypes: integrated mineral-to-cell producers leveraging Indonesian nickel access, Korean and Japanese technology licensors partnering with regional assemblers, and Chinese scale players with captive LFP chemistry expertise. Competitive moves center on multi-year offtake negotiations with Indonesian state mining ventures and capacity commitments tied to Thai BOI incentive windows.
Within the integrated mineral-to-cell tier, CATL and BYD Co Ltd exemplify archetypes of upstream-backed expansion, with the former representing technology-licensing approaches to regional EV partnerships and the latter occupying a position in LFP-dominant stationary storage procurement. Samsung SDI anchors the premium-tier vector for high-nickel cathode supply to automotive programs. These three sit within distinct competitive lanes defined by chemistry specialization and geographic production footprints.
| Leading Market Players |
|---|
| BYD Co Ltd |
| Sunwoda |
| CATL (Contemporary Amperex Technology Co Ltd) |
| GS Yuasa Corporation |
| EVE Energy |
| LG Energy Solution |
| Panasonic Corporation |
| Saft Groupe SA |
| Samsung SDI |
| Others |
Value Network & Pricing Analysis
Lithium carbonate spot indices cascading from Qinghai and Sichuan refining hubs transmit volatility through Southeast Asian cell procurement, compressing margins for pack assemblers while forcing tiered contract structures that separate long-term offtake from spot-exposed volumes.
Pricing Analysis
Direct-to-OEM discount structures dominate large-scale procurement, with Thai automotive assemblers negotiating cell supply agreements that strip distributor margins entirely. Price differentiation hinges on cathode chemistry grade and UN 38.3 certification tier, with high-nickel cells commanding premiums over LFP alternatives. Cost compression in mid-tier stationary storage is intensifying because Vietnamese utilities unbundle engineering from hardware procurement. Industrial buyers in Indonesian manufacturing zones show highest price sensitivity, while Singaporean aerospace contractors absorb premiums for extended qualification testing.
Supply Chain Analysis
Maritime freight costs from Chinese cathode precursor ports to Jakarta and Laem Chabang fluctuate with Red Sea routing disruptions, adding unpredictable landed cost layers to nickel sulfate and cobalt hydroxide shipments. Geographic concentration centers on China, South Korea, and Indonesia, with Indonesian laterite processing now feeding regional nickel sulfate demand. The chain rests on Chinese refined lithium carbonate, Korean separator membranes, and Japanese electrolyte formulations. Single-source vulnerability in cathode precursor supply exposes Thai pack assemblers to export license delays. Distribution runs through direct sales for utility and automotive contracts, with regional distributors serving replacement markets.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Southeast Asian lithium-ion procurement is shifting toward premium-tier specifications as utilities prioritize 6,000-cycle LFP assets and automotive OEMs demand cell-to-pack architectures with integrated thermal management.
For Market Incumbents: Extend manufacturing footprints into Indonesian industrial corridors to secure nickel sulfate offtake under downstream mineral mandates. Deepen backward integration into cathode active material production to offset margin compression from lithium price volatility. CATL and Samsung SDI face emerging pressure from Chinese LFP specialists capturing Vietnamese grid storage tenders.
For New Entrants and Emerging Players: The 15-20% price-point gap between premium Korean high-nickel supply and economy-tier Chinese LFP offerings creates entry space for mid-tier integrators. Philippine island utilities present the most penetrable demand cluster, with diesel displacement procurements favoring turnkey EPC capability over brand heritage. A battery-as-a-service subscription model bypasses capital-constrained industrial buyers in Thai manufacturing zones.
For Investors and Strategic Acquirers: Asymmetric upside sits with Indonesian state-linked refining ventures holding captive nickel access and offtake relationships with Korean cell manufacturers. Long-term viability favors upstream-backed players with chemistry-agnostic production flexibility. Watch Vietnamese regulatory acceleration as the inflection signal—compressed testing cycles would unlock product launch velocity for qualified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Indonesian Nickel Refining Joint Venture | Secures battery-grade nickel sulfate supply under downstream mineral mandates, reducing precursor transit costs for regional cell manufacturers. |
| Thai BOI-Registered Pack Assembly Capacity | Captures eight-year tax holidays and equipment import duty exemptions, anchoring EV supply chain localization in Rayong industrial zones. |
| LFP Chemistry Platform Standardization | Enables Vietnamese utilities to procure 4-hour grid storage with 6,000-cycle warranties, displacing NMC alternatives in stationary applications. |
| ASEAN Harmonized Safety Certification | Reduces multi-country testing burdens through mutual recognition agreements, accelerating product launches across Thai and Indonesian pathways. |
| Battery-as-a-Service Contract Pilot | Opens subscription revenue streams with industrial offtakers in Ho Chi Minh City zones, eliminating upfront capital barriers for captive microgrids. |
Research Methodology
Bottom-up grid storage and EV procurement modeling reconciled against top-down cathode material trade flow tracking forms the analytical core of this study. Primary interviews with utility planning officers, EPC contractors, automotive Tier 1 procurement leads, and BOI investment promotion specialists combined with secondary validation from Indonesian mining ministry disclosures, Vietnamese power development plan documents, Thai customs import records, and ASEAN sectoral body draft standards. This dual approach enables triangulation between announced capacity commitments and actual material flow data.
Input-output matrices map cell production capacity, cathode chemistry allocation, and end-use demand across the projection horizon. Segmentation dimensions include product type, application, end user category, and distribution channel, with chemistry-specific energy density and cycle life parameters informing substitution dynamics. CAGRs derive from fitted growth curves against utility tender pipelines and automotive localization timelines, with lithium carbonate price scenarios and nickel export policy enforcement as sensitivity inputs.
Caveats apply where Indonesian nickel export ban enforcement intensity or Vietnamese regulatory cycle compression could materially shift the outlook. Forecasts reflect assumptions about ASEAN harmonization progress and BOI incentive continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Salt Lake Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Materials Market
Lithium-ion Battery
France SLI Battery Market
Lithium-ion Battery
Lithium-Sulfur Battery Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Storage Market
Lithium-ion Battery
United States Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Lithium Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Lithium-Ion Battery Packs Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Anode Market
Lithium-ion Battery
Large Capacity Lithium Battery Packs Sales Market
Lithium-ion Battery
Global Pin Type Lithium-Based Battery Market
Lithium-ion Battery
France Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Industrial Lithium-Ion Batteries Market
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Automotive Lithium-Ion Battery Cell Market