
 Lithium-Ion Battery Separator Market | 2026-2036
Lithium-Ion Battery Separator Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Battery Separator Market Intelligence
Supply chain contracting for lithium-ion battery separators is fragmenting as cell makers diversify procurement across multiple tiers to reduce concentration risk. Asahi Kasei Corporation anchors Japanese automotive supply relationships through its wet-process membrane leadership. SK IE Technology Co. Ltd leverages Korean chaebol integration into battery cell manufacturing. SEMCORP competes aggressively on cost from its Chinese base, while Toray Industries Inc. sustains premium positioning through polyolefin film specialization.
A lithium-ion battery separator is a microporous membrane, typically 12-30 microns thick, placed between the anode and cathode to prevent electrical short circuits while permitting ionic transport through liquid electrolyte impregnation. Polyethylene and polypropylene dominate material selection, though ceramic-coated composites are gaining share as thermal runaway protection becomes critical for electric vehicle packs. Wet-process technology leads manufacturing volume due to its ability to produce uniform sub-20-micron films, while coating technology commands the fastest growth as OEMs mandate shutdown separators for next-generation cells. Electric Vehicles represents the most concentrated end-user margin pool, with Consumer Electronics remaining mature and price-sensitive.
China's SAMR enforces GB standards for battery separator mechanical strength and pore size distribution, while the EU's REACH and RoHS frameworks restrict hazardous substances in European-bound supply chains. Japan's METI coordinates with JIS standards bodies to align separator thermal stability benchmarks with domestic automotive requirements. Stakeholders must monitor how diverging national safety certifications reshape the cost structure of serving multiple geographic markets simultaneously.
Market Dynamics
China's NMPA and MIIT are tightening safety standards for battery components, forcing separator suppliers to upgrade ceramic coating capabilities while electric vehicle manufacturers scale orders for high-performance separators as cell chemistry evolves toward higher energy densities.
Growth Catalysts
- EV Battery Energy Density Targets:Automotive OEMs mandate shutdown separators for next-generation cells, pulling wet-process membrane demand upward.
- China's Dual Carbon Goals:MEE enforcement accelerates domestic separator capacity expansion in Jiangsu and Zhejiang provinces.
- REACH and RoHS Compliance:European-bound supply chains require hazardous substance restrictions, filtering out low-grade polyolefin suppliers.
Market Restraints
- Polyolefin Feedstock Volatility:Polyethylene and polypropylene price swings compress separator margins unpredictably.
- East Asian Supply Concentration:Wet-process technology and coating equipment cluster in China, Japan, and Korea, creating single-source vulnerability.
- Sub-12-Micron Film Limitations:Mechanical strength degradation below current thresholds blocks next-generation cell architectures.
Strategic Opportunities
- Solid-State Battery Interface Materials:Ceramic-coated composites position for solid-state electrolyte cell commercialization.
- India PLI Scheme:Cell manufacturing incentives create first-mover separator supply contracts for domestic battery plants.
- EU Battery Regulation Traceability:Digital passport mandates favor separator suppliers with integrated quality documentation systems.
Industry Challenges
- Coating Technician Scarcity:Ceramic layer uniformity control requires specialized operators unavailable at scale outside East Asia.
- Multi-Standard Certification Timelines:GB, JIS, and REACH compliance testing extends product qualification cycles by 8-14 months.
- Legacy Equipment Retrofit Costs:Dry-process lines require complete replacement to achieve wet-process film uniformity standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Battery Separator Market |
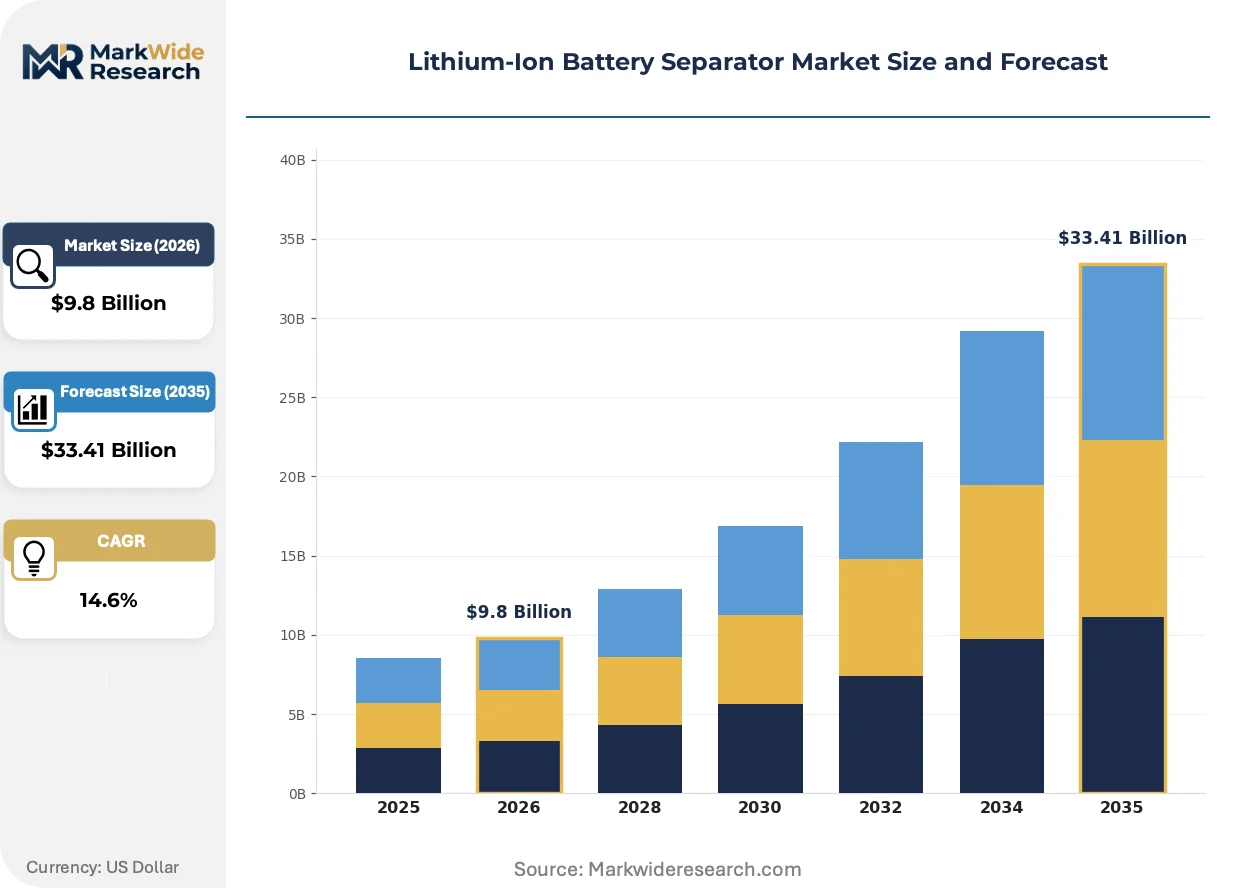
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $33.41 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Ceramic, Composite End User: Consumer Electronics, Electric Vehicles, Energy Storage Systems, Industrial Applications Thickness: 25 Microns, 30 Microns, 50 Microns, 60 Microns Technology: Dry Process, Wet Process, Coating Technology, Hybrid Technology |
| Companies Covered | Celgard LLC, W-Scope Corporation, Asahi Kasei Corporation, Senior Technology Material, SEMCORP, Toray Industries Inc., Entek International LLC, Sinoma Science & Tech, SK IE Technology Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Battery Separator Market Strategic Shifts & Innovations
Ceramic-polyolefin composite separators are hybridizing manufacturing processes and performance specifications. Three developments dominate: coating technology integration, regulatory pressure on thermal stability, and procurement consolidation around qualified suppliers.
Coating technology is hybridizing separator construction by bonding ceramic particles to polyolefin substrates for thermal runaway protection. Electric vehicle pack manufacturers specify these composites for 800-volt architectures. The technology is hybridizing cost structures, compressing commodity-grade separator margins while expanding premium-tier pricing power.
China's SAMR enforces updated GB standards for pore size distribution and mechanical strength. Separator suppliers serving European markets simultaneously navigate REACH substance restrictions and RoHS hazardous material limits. Automotive-bound production lines face the strictest compliance burden, driving dual-certification investments.
Cell makers are consolidating qualified supplier lists from twelve-plus vendors to four-to-six strategic partners. Long-term offtake agreements with ceramic coating capability requirements now dominate procurement. This concentration is most visible in China's Yangtze River Delta, where cathode and electrolyte co-location accelerates supplier selection decisions.
Lithium-Ion Battery Separator Market Segmentation
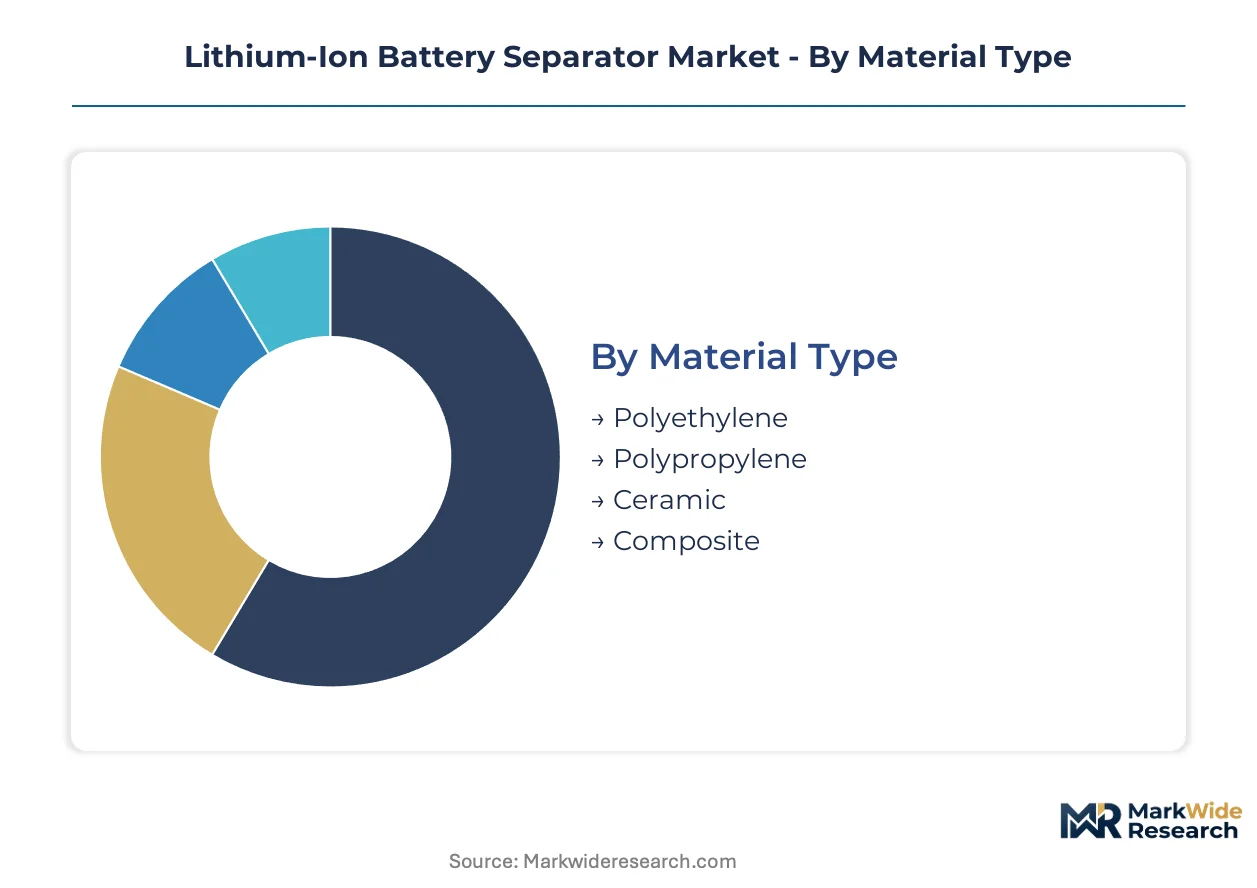
Separator segmentation tracks how cell chemistry evolution and safety mandates split procurement across material grades and manufacturing methods. Each dimension carries distinct margin profiles and qualification barriers.
Material Type:
Cost tier stratification separates commodity polyolefin supply from ceramic composite premiums.
- Polyethylene:Dominates wet-process membrane construction with sub-20-micron capability and uniform pore distribution. Electric vehicle pack manufacturers in Jiangsu province specify PE substrates for 800-volt architectures requiring shutdown functionality.
- Polypropylene:Offers superior thermal stability above 130°C, making it preferred for high-temperature cylindrical cell formats. Demand concentrates in Japan's automotive supply chain where METI thermal benchmarks exceed standard requirements.
- Ceramic:Alumina and boehmite coatings provide thermal runaway protection for next-generation cells.
- Composite:Hybrid polyolefin-ceramic constructions balance cost and safety performance.
Polyethylene holds installed capacity. Ceramic is rotating up the share rankings.
End User:
Application maturity determines pricing power and contract structure across customer segments.
- Electric Vehicles:Automotive OEMs mandate ceramic-coated separators with 12-25 micron specifications and documented thermal shutdown profiles. Long-term offtake agreements with coating capability requirements now dominate procurement in China's Yangtze River Delta.
- Energy Storage Systems:Grid-scale battery installations prioritize thicker 30-50 micron films for mechanical durability during deep cycling. Utility procurement in Zhejiang province favors domestic suppliers with integrated quality documentation systems.
- Consumer Electronics:Mature smartphone and laptop demand emphasizes cost minimization over performance differentiation.
- Industrial Applications:Forklift and stationary power systems require mid-tier specifications with reliable supply continuity.
Electric Vehicles commands margin concentration. Energy Storage Systems is climbing the fastest.
Thickness:
Volume distribution reflects the tension between energy density targets and mechanical integrity limits.
- 25 Microns:Standard for premium automotive cells balancing ionic conductivity with physical robustness. Korea's cell manufacturers specify this grade for pouch cell formats in European-bound electric vehicle programs.
- 30 Microns:Dominates energy storage and commercial vehicle applications where cycle life outweighs pack-level energy density optimization.
- 50 Microns:Legacy industrial and backup power specifications with declining share in new cell designs.
- 60 Microns:Niche applications in heavy-duty equipment with extreme mechanical stress tolerance requirements.
25 Microns anchors automotive qualification. 30 Microns is gaining share in utility-scale procurement.
Technology:
Manufacturing method determines film uniformity, pore size control, and capital intensity thresholds.
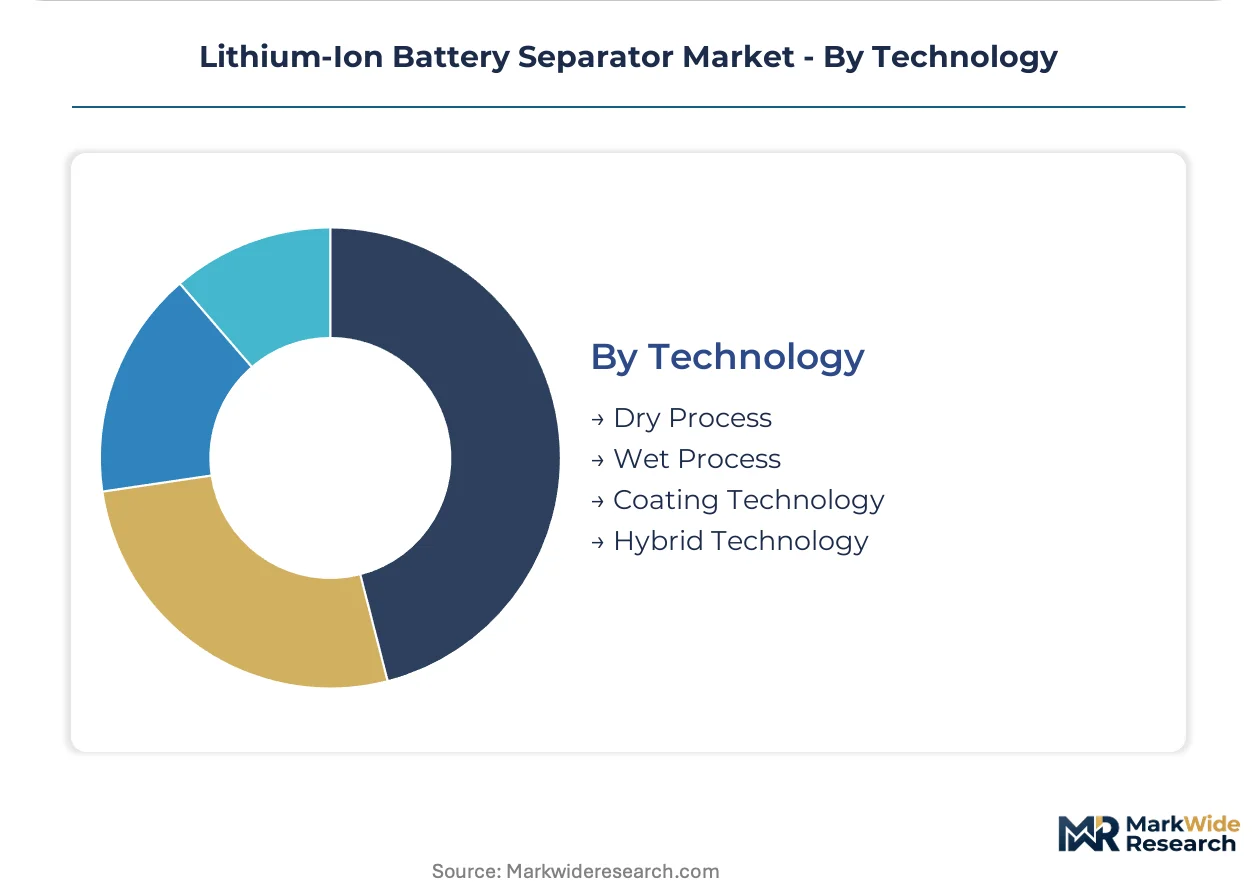
- Wet Process:Biaxial stretching of polyethylene in solvent baths produces sub-20-micron films with narrow pore distribution. Japanese and Korean equipment suppliers dominate wet-process line installation, creating geographic concentration in East Asian production.
- Coating Technology:Ceramic particle deposition commands the steepest expansion trajectory as OEMs mandate shutdown separators. Technician scarcity for layer uniformity control limits capacity scaling outside established manufacturing clusters.
- Dry Process:Melt-stretching of polypropylene without solvents suits thicker film production at lower capital cost.
- Hybrid Technology:Combines wet-process substrates with ceramic coating in integrated production lines.
Wet Process holds volume leadership. Coating Technology is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese wet-process membrane supply while Chinese ceramic coating capacity competes on scale. German automotive OEMs import premium separators under REACH substance restrictions. Korean chaebol integration locks regional cell makers into captive supply relationships.
China
Domestic EV manufacturers in Jiangsu province scale orders for 12-25 micron ceramic-coated separators as cell energy density targets tighten. SAMR enforces updated GB standards for pore size distribution and mechanical strength. Zhejiang province hosts the densest cluster of domestic separator makers co-located with cathode and electrolyte producers.
Japan
Automotive OEMs specify polypropylene substrates exceeding METI thermal stability benchmarks for high-temperature cylindrical formats. JIS standards bodies coordinate separator qualification timelines with domestic battery cell roadmaps. Kansai region wet-process equipment suppliers anchor regional membrane uniformity capabilities.
South Korea
Cell manufacturers specify 25-micron wet-process films for European-bound electric vehicle pouch cell programs. Korean chaebol integration into battery manufacturing creates captive demand for affiliated separator supply. Seoul Capital Area concentration of coating technicians limits independent capacity scaling.
Germany
Automotive OEMs mandate REACH-compliant ceramic composites for 800-volt battery architectures entering production. ECHA substance restrictions filter out low-grade polyolefin suppliers from European-bound supply chains. Bavaria-based cell manufacturing investments pull qualified separator qualification timelines forward.
United States
Battery cell manufacturing incentives under the IRA accelerate domestic separator plant announcements. EPA and OSHA frameworks govern ceramic coating facility permitting and worker exposure limits. Michigan and Ohio industrial corridors attract separator suppliers seeking proximity to automotive OEM cell joint ventures.
Lithium-Ion Battery Separator Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper process control. The vendor base organizes around wet-process membrane leadership, ceramic coating capability, and geographic proximity to cell manufacturing clusters. Three archetypes dominate: Japanese wet-process specialists, Korean chaebol-affiliated suppliers, and Chinese cost-scale competitors. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines stretch to 8-14 months.
Among Japanese wet-process specialists, Asahi Kasei Corporation and Toray Industries Inc. occupy positions defined by polyolefin film specialization and automotive supply relationships. SK IE Technology Co. Ltd represents the Korean chaebol-affiliated archetype, sitting within integrated battery manufacturing ecosystems. These three companies exemplify how regional industrial structure shapes competitive positioning without converging on identical capability profiles.
| Leading Market Players |
|---|
| Celgard LLC |
| W-Scope Corporation |
| Asahi Kasei Corporation |
| Senior Technology Material |
| SEMCORP |
| Toray Industries Inc. |
| Entek International LLC |
| Sinoma Science & Tech |
| SK IE Technology Co. Ltd |
| Others |
Cost & Logistics Intelligence
The Shanghai-Rotterdam maritime corridor carries ceramic-coated separator shipments where freight cost volatility amplifies the spread between Jiangsu province spot pricing and European automotive contract rates. Wet-process membrane supply concentration in East Asia compresses procurement alternatives for cell makers, forcing acceptance of premium tiering tied to coating capability certification.
Pricing Analysis
The customization-premium spread separates standard polyethylene substrates from ceramic-coated configurations qualifying for 800-volt automotive programs. Three-tier pricing structure across premium, standard, and economy levels reflects wet-process membrane uniformity grades and SAMR GB certification status. Cost compression in commodity polyolefin tiers is intensifying because SEMCORP and domestic Chinese rivals expand wet-process capacity in Zhejiang province. Energy storage system buyers exhibit highest price sensitivity due to utility procurement frameworks, while automotive OEMs prioritize thermal shutdown documentation over unit cost.
Supply Chain Analysis
Contract-manufacturing concentration for ceramic coating services clusters around Seoul Capital Area technicians and Jiangsu province production lines. Wet-process equipment and coating capacity concentrate in China, Japan, and South Korea. Polyethylene resin, polypropylene feedstock, and alumina ceramic particles constitute critical input dependencies. Single-source vulnerability pervades sub-20-micron wet-process line supply where Japanese and Korean equipment makers dominate installation. Distribution runs through long-term offtake agreements with qualified supplier lists rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
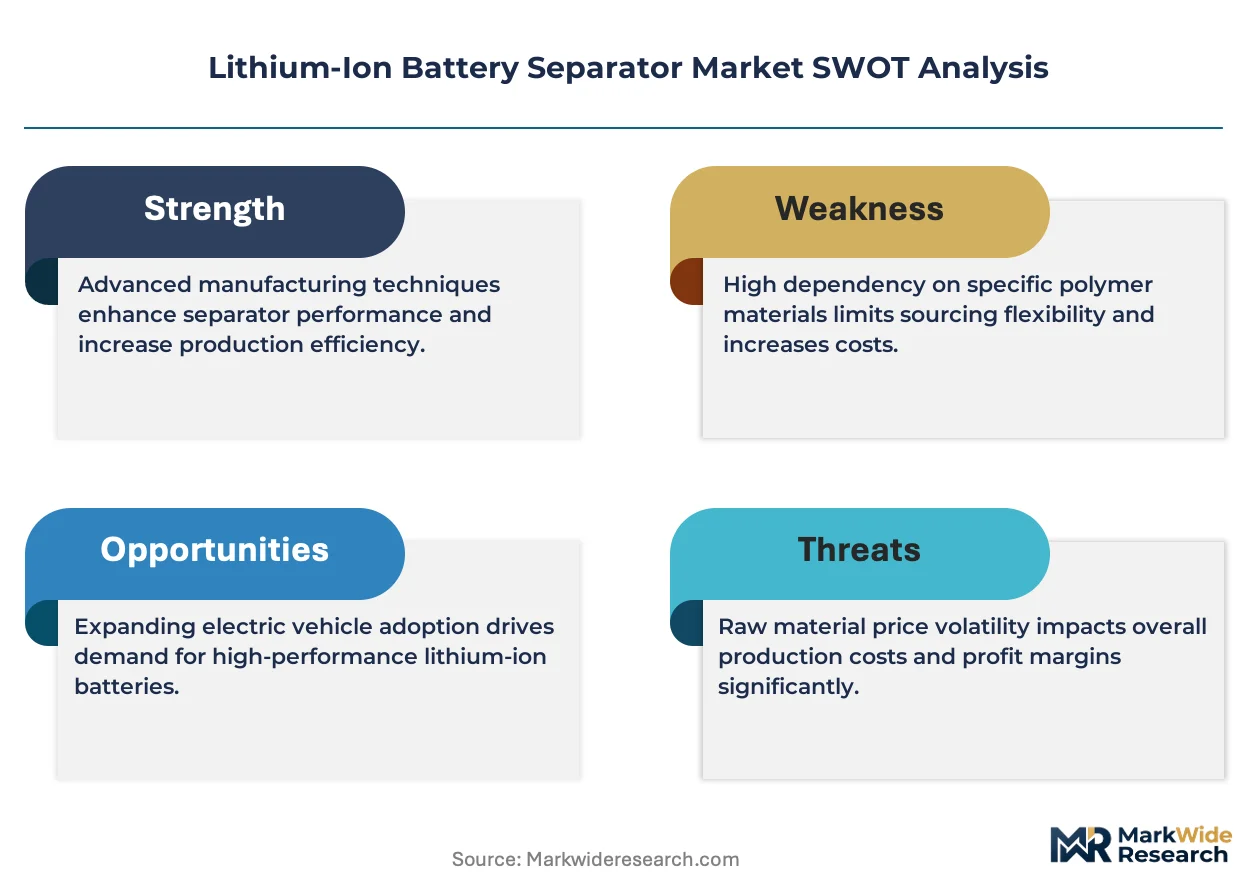
The lithium-ion battery separator market sits at an inflection where solid-state electrolyte commercialization threatens polyolefin substrate relevance. China's NMPA safety standard tightening accelerates this technological disruption window.
For Market Incumbents: Harden ceramic coating technician pipelines through captive training programs in Jiangsu and Zhejiang provinces to offset Seoul Capital Area labor scarcity. Lock automotive OEM qualification timelines through integrated GB-JIS-REACH certification investments before solid-state interface materials displace conventional separator architectures. Backward integration into alumina ceramic particle supply secures coating uniformity control against feedstock volatility. For New Entrants and Emerging Players: India's PLI scheme cell manufacturing incentives represent the most penetrable entry point for first-mover separator supply contracts before domestic coating capacity matures. Utility-scale energy storage procurement in Zhejiang province offers secondary white-space where 30-50 micron specifications face less stringent qualification barriers than automotive programs. Partner with established wet-process equipment suppliers for technology licensing rather than greenfield process development. For Investors and Strategic Acquirers: EU Battery Regulation traceability mandates reshape the acquisition landscape toward separator suppliers with integrated quality documentation systems and digital passport readiness. Five-to-ten year viability hinges on ceramic-polyolefin hybrid positioning for solid-state transition rather than pure commodity polyolefin exposure. Monitor solid-state battery pilot production announcements from Korean chaebol cell manufacturers as inflection indicator for conventional separator demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Capacity Expansion | Captures automotive OEM mandates for 800-volt thermal shutdown protection in Jiangsu province. |
| Multi-Standard Certification Investment | Accelerates product qualification timelines across GB, JIS, and REACH compliance frameworks. |
| Backward Integration into Ceramic Feedstock | Secures alumina particle supply continuity against coating technician scarcity constraints. |
| Long-Term Offtake Agreement Structuring | Locks procurement consolidation trends as cell makers reduce qualified supplier lists. |
| Solid-State Interface Material R&D | Positions for electrolyte cell commercialization threatening conventional separator demand. |
Research Approach
Initial hypotheses were tested against primary input from cell manufacturing procurement directors, ceramic coating production engineers, automotive OEM battery platform engineers, and wet-process equipment specialists and refined through secondary validation. Primary fieldwork drew from separator plant managers in Jiangsu and Zhejiang provinces, cathode material procurement leads at Korean chaebol cell makers, and regulatory affairs managers navigating SAMR GB standard updates. Secondary sources encompassed MIIT and NMPA regulatory filings, customs trade data for polyolefin resin imports, and SEC disclosures from listed separator manufacturers. Bottom-up capacity modeling and top-down demand aggregation from electric vehicle production forecasts were triangulated for cross-validation.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with cell chemistry evolution and safety mandate tightening as core demand drivers against wet-process line installation lead times. Segmentation dimensions encompassed material type, end-use application, thickness specification, and manufacturing technology method. CAGRs were derived from regression analysis of historical capacity expansion rates and projected electric vehicle battery demand trajectories. Industry-specific inputs included ceramic coating technician availability indices and multi-standard certification timeline distributions.
Practitioners should monitor solid-state battery pilot production scale-up, NMPA safety standard enforcement intensity, and polyolefin feedstock price volatility for early signals of forecast revision necessity. Quarterly review of automotive OEM separator qualification pipeline status and ceramic coating capacity utilization rates in East Asian manufacturing clusters is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Automotive Sodium-Ion Battery Market
Lithium-ion Battery
Solid State Battery Market
Lithium-ion Battery
Lithium Cobalt Oxide Market
Lithium-ion Battery
South America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
United States Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Lithium-Air Battery Market
Lithium-ion Battery
Lithium Polymer Battery Market
Lithium-ion Battery
France Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Automotive Lithium-Sulfur Battery Market
Lithium-ion Battery
Europe Electric Vehicle Battery Anode Market
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
China Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Automotive Lithium-Ion Battery Cell Market
Lithium-ion Battery
UAV Lithium Battery Market