
 Asia-Pacific Distributed Antenna System Market | 2026-2036
Asia-Pacific Distributed Antenna System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Distributed Antenna System Market Outlook
CE marking under the EU's Radio Equipment Directive is unwinding competitive access for non-compliant hardware vendors across Asia-Pacific export channels. CommScope Inc. leverages its fiber optic backbone expertise to anchor large-scale indoor deployments in Singapore's integrated resort complexes. Huawei Technologies Co., Ltd. sustains cost advantages in active DAS components through captive semiconductor sourcing and domestic manufacturing scale. ZTE Corporation competes aggressively on 5G NR upgrade paths for Chinese rail operators expanding tunnel coverage.
A distributed antenna system comprises a network of spatially separated antenna nodes connected to a common source through fiber optic or coaxial cabling, typically operating between 700 MHz and 3.5 GHz to distribute cellular signals uniformly across structurally complex environments. The architecture employs remote radio units, bidirectional amplifiers, and passive splitters to overcome penetration losses in concrete, steel, and low-emissivity glass that cripple macro tower reach indoors. Active DAS commands the premium tier of project budgets due to digital signal processing capabilities that support multi-operator, multi-band aggregation essential for 5G NR densification. Hybrid DAS configurations are gaining fastest traction among mid-budget hospitality and education clients seeking phased migration from passive legacy infrastructure without full rip-and-replace capital outlay. Small Cell deployments concentrate margin pools in software-defined radio licensing and cloud-RAN orchestration layers rather than hardware alone.
China's MIIT enforces GB standards compliance for radio transmission equipment, while India's WPC mandates ETA certification for imported RF devices, collectively elevating technical barriers that filter out uncertified component suppliers. Japan's MIC spectrum allocation frameworks for 5G millimeter wave directly shape antenna density requirements in Tokyo and Osaka commercial districts. Australia's ACMA electromagnetic energy exposure standards constrain transmitter power thresholds in healthcare and education end-user environments. Stakeholders must monitor evolving national security review thresholds for foreign telecom infrastructure as Australia, India, and Japan tighten supply chain scrutiny on Chinese-origin equipment.
Market Dynamics
5G NR mid-band densification mandates across Asia-Pacific are compressing deployment timelines for venue operators and transit authorities, forcing rapid migration from passive coaxial infrastructure to fiber-fed active DAS architectures capable of supporting 3.5 GHz carrier aggregation.
Growth Catalysts
- MIIT spectrum reallocation:China's 5G mid-band assignments at 3.3-3.6 GHz compel venue owners to upgrade legacy passive systems for higher-frequency propagation.
- Stadium modernization wave:Southeast Asian arena operators in Thailand, Vietnam, and the Philippines prioritize fan-facing connectivity as ticket revenue models shift toward experiential monetization.
- Rail corridor densification:Indonesia's Jakarta-Bandung high-speed rail and metro extensions create contiguous coverage requirements that macro towers cannot satisfy through tunnel penetration.
Market Restraints
- Semiconductor supply concentration:RF front-end module fabrication concentrates in Taiwan and South Korea, exposing project timelines to foundry allocation volatility.
- Certification timeline friction:India's WPC ETA and China's GB standards compliance add 4-6 month pre-deployment validation cycles that compress installation windows.
- Passive-to-active capital cliff:Hybrid migration paths still require 40-60% of full rip-and-replace expenditure, stranding mid-budget hospitality and education clients.
Strategic Opportunities
- Vietnam manufacturing pivot:Electronics assembly migration from China creates localized DAS component sourcing hubs reducing landed cost for ASEAN projects.
- Healthcare vertical penetration:Australia's ACMA electromagnetic exposure standards and Japan's MIC frameworks open certified low-power deployments in hospital campuses.
- Software-defined RAN convergence:Integration of DAS remote radio units with cloud-native orchestration layers enables multi-tenant neutral host business models.
Industry Challenges
- RF engineering talent scarcity:Specialized skills in 3.5 GHz propagation modeling and fiber-to-the-antenna design lag deployment demand across Southeast Asia.
- Neutral host commercial complexity:Revenue-sharing negotiations between venue owners, mobile network operators, and DAS integrators prolong contract finalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Distributed Antenna System Market |
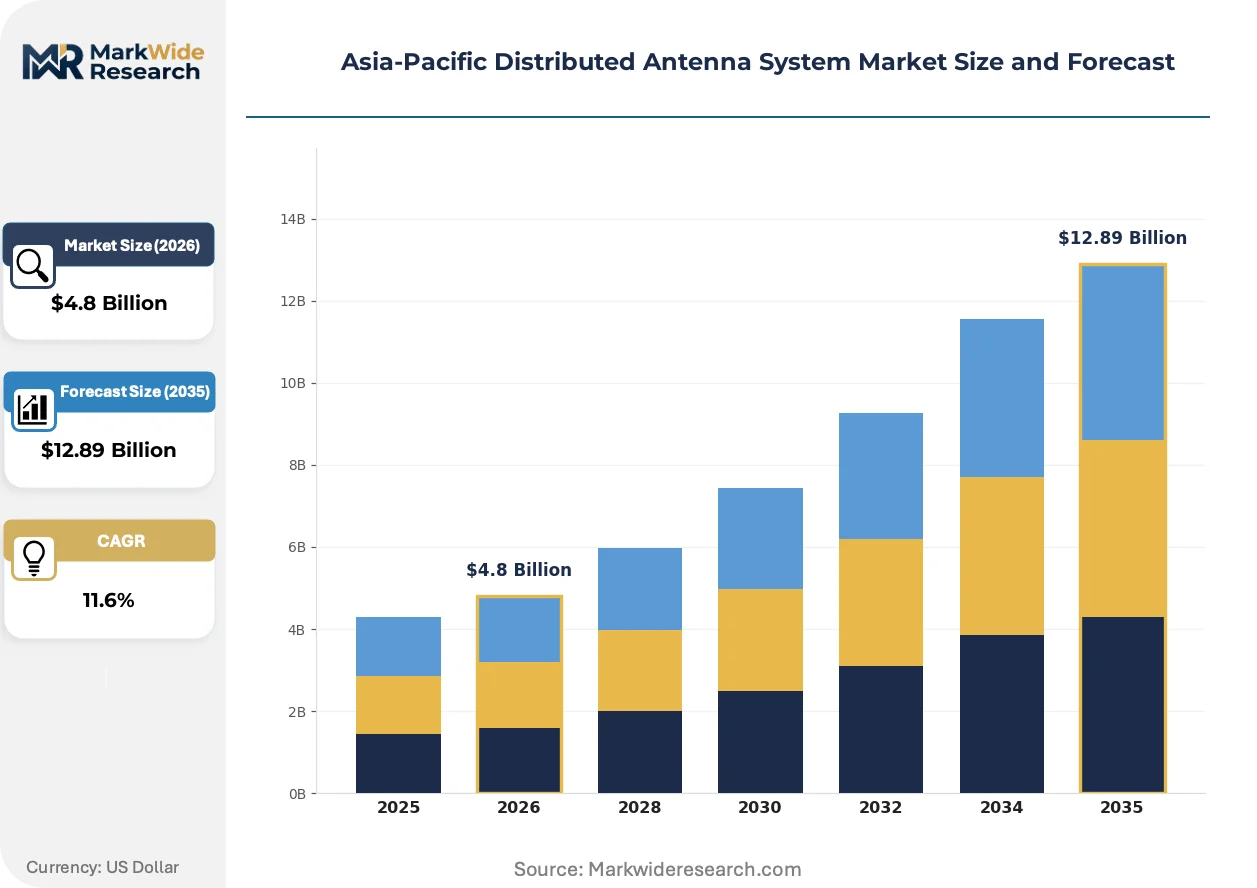
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active DAS, Passive DAS, Hybrid DAS, Small Cell Technology: 4G LTE, 5G NR, Wi-Fi, Fiber Optics End User: Healthcare, Education, Hospitality, Transportation Installation Type: Indoor, Outdoor, In-Building, Rooftop |
| Companies Covered | CommScope Inc., Corning Incorporated, Comba Telecom Systems Holdings Ltd., AT&T, American Tower Corporation, Huawei Technologies Co., Ltd., ZTE Corporation, Cobham Wireless, PT Tower Bersama Infrastructure TBK, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Distributed Antenna System Market Strategic Shifts
Digital signal processing capabilities are migrating from centralized baseband units toward antenna-integrated remote radio heads, compressing latency and enabling real-time spectrum coordination across multi-operator environments.
Open RAN architectures are supplanting proprietary vendor-locked DAS implementations in Singapore's integrated resort and commercial district deployments. Property developers specify O-RAN compliant interfaces to avoid single-source dependency for 10-15 year infrastructure lifecycles. This interoperability mandate fragments procurement toward modular component suppliers and away from vertically integrated system vendors.
Japan's MIC 5G millimeter-wave allocation frameworks at 28 GHz and sub-6 GHz coordination rules are mandating antenna density increases in Tokyo and Osaka commercial districts. Building owners face revised technical conformance certificates requiring documented coverage uniformity metrics. Premium office and retail developments are responding by pre-installing fiber backbone capacity to support future antenna node augmentation without structural disruption.
Service unbundling is separating DAS hardware procurement from ongoing optimization and spectrum management contracts. Australian healthcare and education end-users increasingly source equipment through capital budgets while outsourcing RF planning and interference mitigation to specialized managed service providers. This bifurcation concentrates margin pools in recurring software licensing and cloud-based performance analytics rather than one-time installation revenue.
Asia-Pacific Distributed Antenna System Market Segmentation
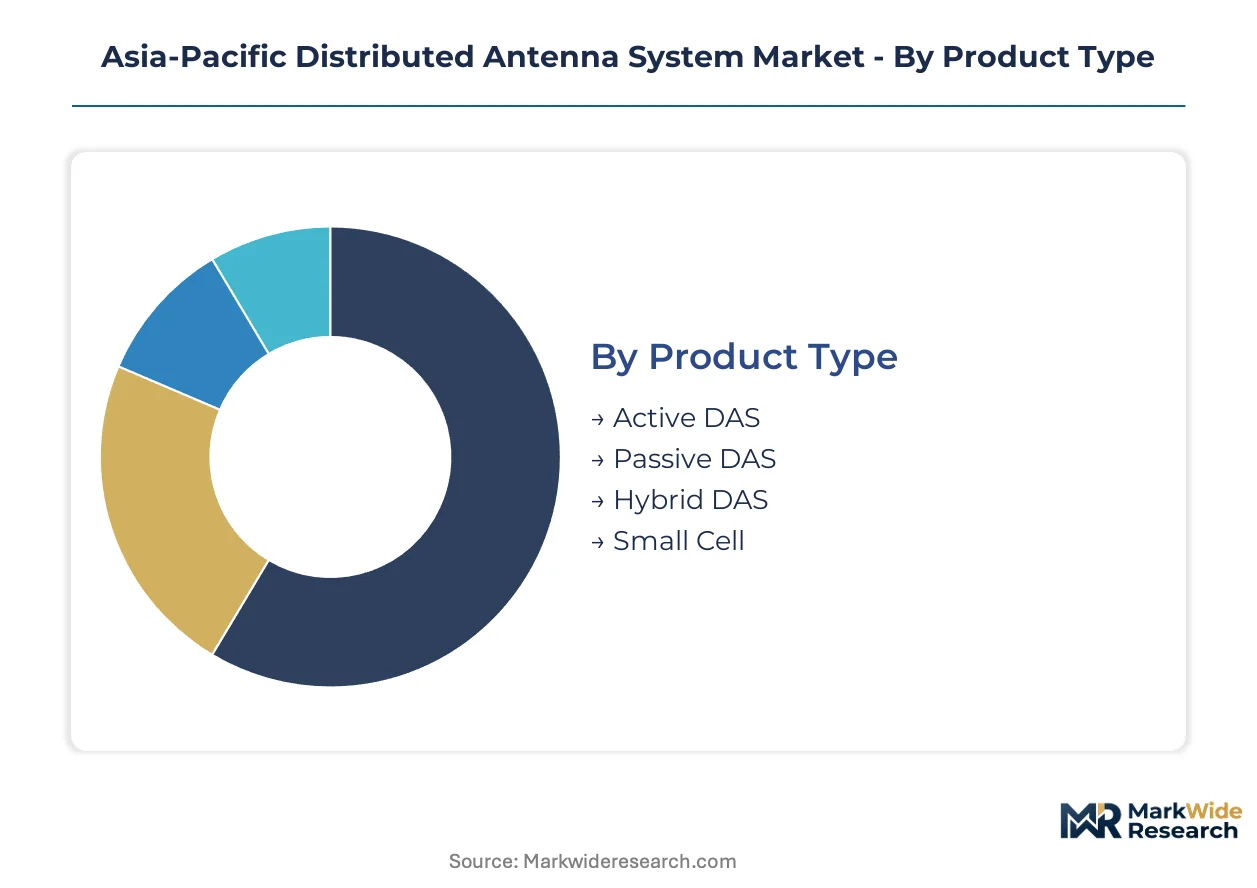
Segmentation in the Asia-Pacific Distributed Antenna System Market reveals how regulatory pressure, propagation physics, and venue economics fragment procurement decisions across technology tiers. Understanding these divides enables vendors to align certification investments with addressable demand pockets.
Product Type:
China's MIIT GB standards and India's WPC ETA certification create divergent compliance burdens across active and passive architectures, filtering supplier participation by technical capability.
- Active DAS:Fiber-fed digital architectures with remote radio units and baseband processing enable multi-operator, multi-band aggregation essential for 5G NR mid-band densification. Demand concentrates in Singapore's integrated resort complexes and Jakarta-Bandung rail corridors where venue operators require guaranteed coverage uniformity under tight deployment timelines.
- Passive DAS:Coaxial distribution networks using bidirectional amplifiers and passive splitters operate without digital signal processing, limiting carrier aggregation to lower frequency bands. Legacy installations across Southeast Asian stadiums face replacement pressure as Thailand and Vietnam mandate 3.5 GHz readiness for international event hosting.
- Hybrid DAS:Phased migration path combining existing coaxial infrastructure with fiber-fed active overlays reduces capital outlay for mid-budget hospitality and education clients.
- Small Cell:Compact radio nodes with software-defined baseband concentrate margin in cloud-RAN orchestration licensing rather than hardware procurement alone.
Established volume favors Passive DAS; emerging adoption favors Active DAS.
Technology:
Propagation characteristics at higher frequencies reshape antenna density requirements and fiber backbone specifications across deployment scenarios.
- 4G LTE:Mature macro network technology operating across 700 MHz to 2.6 GHz bands delivers reliable indoor penetration with lower node density. Australia's ACMA electromagnetic exposure standards and Japan's MIC frameworks still certify LTE-only deployments in healthcare campuses where 5G migration lacks budget priority.
- 5G NR:New radio interfaces at 3.3-3.6 GHz and 28 GHz millimeter-wave demand antenna-integrated remote radio heads with real-time spectrum coordination. Tokyo and Osaka commercial districts face revised technical conformance certificates requiring documented coverage uniformity metrics under Japan's MIC allocation rules.
- Wi-Fi:Unlicensed spectrum overlay for offload and neutral host monetization in hospitality and education verticals.
- Fiber Optics:Physical transport layer enabling low-latency fronthaul between centralized baseband and distributed antenna nodes.
Deployment concentration favors 4G LTE; steepest expansion trajectory favors 5G NR.
End User:
Vertical-specific electromagnetic exposure standards and revenue models determine procurement authority and contract structure.
- Healthcare:Hospital campuses in Australia and Japan require certified low-power transmitter configurations meeting ACMA and MIC exposure thresholds. Procurement bifurcates between capital equipment budgets and recurring managed service contracts for RF planning and interference mitigation.
- Transportation:Rail operators in Indonesia and China face contiguous coverage requirements through tunnels and cuttings that macro towers cannot satisfy. ZTE Corporation and Huawei Technologies compete aggressively on 5G NR upgrade paths for Chinese rail expansion projects.
- Education:Campus-wide density requirements strain mid-tier capital budgets, favoring hybrid migration paths over full active DAS replacement.
- Hospitality:Integrated resort developers in Singapore specify O-RAN compliant interfaces to avoid single-source dependency across 10-15 year infrastructure lifecycles.
Contract maturity favors Healthcare; infrastructure expansion favors Transportation.
Installation Type:
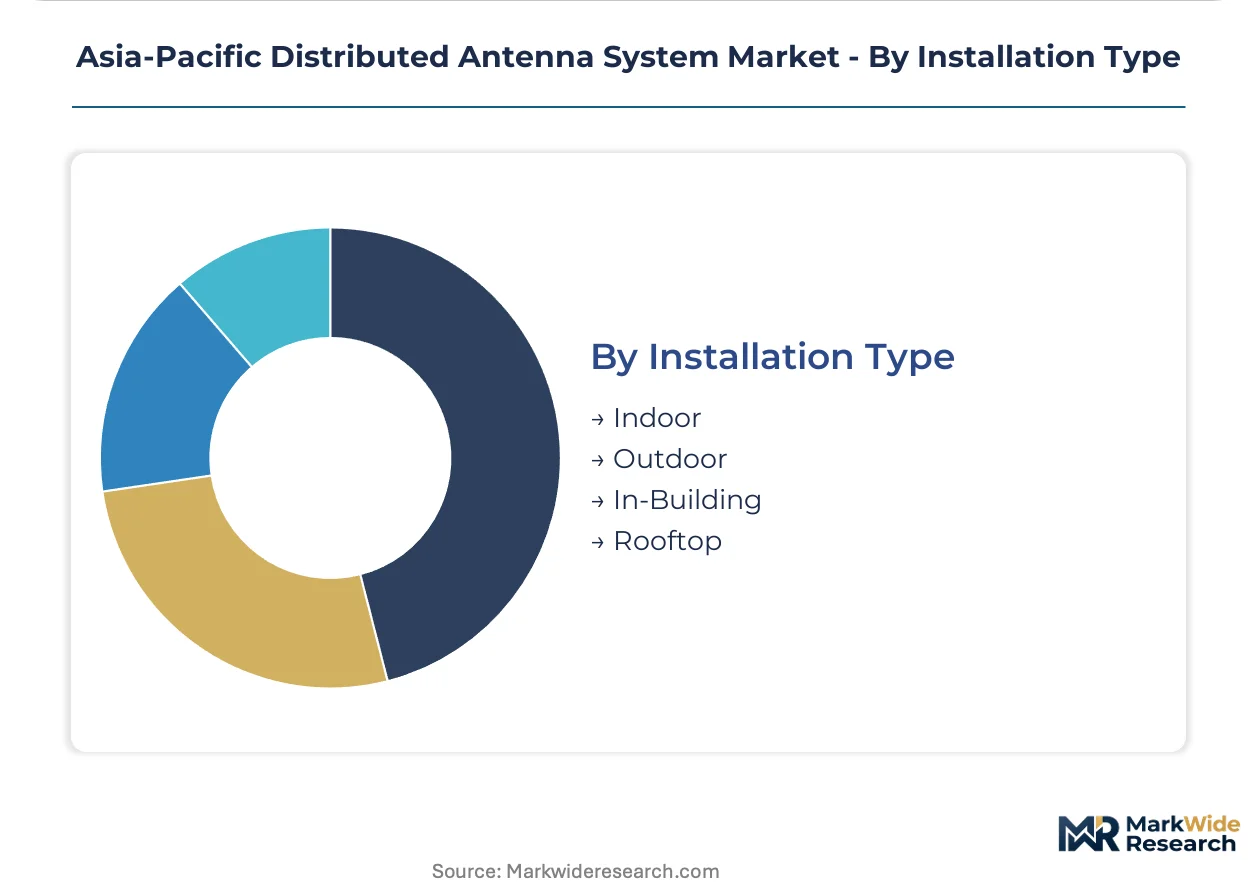
Structural constraints and aesthetic requirements differentiate hardware form factors and mounting specifications.
- Indoor:Concealed ceiling and wall-mounted nodes address penetration losses through concrete, steel, and low-emissivity glass in commercial buildings. CommScope anchors large-scale deployments in Singapore's integrated resort complexes through fiber optic backbone expertise.
- In-Building:Distributed coverage systems integrated during construction or retrofit phases command premium project margins due to coordination with MEP contractors.
- Outdoor:Weather-hardened enclosures and lightning protection for campus and venue perimeter coverage.
- Rooftop:Elevated mounting positions for line-of-sight optimization and macro network backhaul integration.
Revenue concentration favors Indoor; greenfield opportunity favors In-Building.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT spectrum reallocation at 3.3-3.6 GHz and India's WPC ETA certification mandates are compressing deployment timelines across Asia-Pacific, forcing venue operators and transit authorities toward fiber-fed active architectures.
China
Jakarta-Bandung high-speed rail corridors and metro tunnel extensions demand contiguous cellular coverage that macro towers cannot penetrate. MIIT enforces GB standards compliance for radio transmission equipment, elevating technical barriers for component suppliers. ZTE Corporation and Huawei Technologies compete aggressively on 5G NR upgrade paths for rail operators expanding tunnel infrastructure.
India
Telecommunication Engineering Centre certification mandates tighten equipment standards for imported RF devices. WPC ETA validation adds 4-6 month pre-deployment cycles that compress installation windows. Demand clusters visibly in urban transit corridors where venue operators modernize connectivity infrastructure under compressed timelines.
Japan
MIC spectrum allocation frameworks for 5G millimeter wave at 28 GHz shape antenna density requirements in commercial districts. Building owners face revised technical conformance certificates requiring documented coverage uniformity metrics. Tokyo and Osaka developments respond by pre-installing fiber backbone capacity for future node augmentation.
Singapore
Integrated resort complexes anchor large-scale indoor deployments requiring guaranteed coverage uniformity. Property developers specify O-RAN compliant interfaces to avoid single-source dependency across 10-15 year infrastructure lifecycles. This interoperability mandate fragments procurement toward modular component suppliers.
Australia
ACMA electromagnetic energy exposure standards constrain transmitter power thresholds in healthcare and education environments. Hospital campuses require certified low-power configurations meeting exposure thresholds. Procurement bifurcates between capital equipment budgets and recurring managed service contracts for RF planning.
Asia-Pacific Distributed Antenna System Market Competitive Environment
Player mix skews toward vertically integrated system vendors and modular component specialists. Market structure concentrates around tier-one infrastructure providers with captive semiconductor sourcing and domestic manufacturing scale. Three archetypes dominate: fiber backbone specialists anchoring resort and commercial deployments; active component fabricators leveraging cost advantages through integrated supply chains; and neutral host integrators managing multi-operator revenue-sharing models. Competitive moves center on O-RAN compliance certification and strategic partnerships with property developers seeking interoperability guarantees.
Among Asia-Pacific-based system vendors, Huawei Technologies Co., Ltd. and ZTE Corporation occupy positions within the active DAS component tier, exemplifying vertically integrated manufacturing archetypes. CommScope Inc. anchors the fiber backbone specialist category through large-scale indoor deployment expertise. Corning Incorporated represents the materials-science-to-systems integration pathway. These three entities collectively illustrate how certification compliance and manufacturing scale separate addressable market tiers across the region's fragmented procurement landscape.
| Leading Market Players |
|---|
| CommScope Inc. |
| Corning Incorporated |
| Comba Telecom Systems Holdings Ltd. |
| AT&T |
| American Tower Corporation |
| Huawei Technologies Co., Ltd. |
| ZTE Corporation |
| Cobham Wireless |
| PT Tower Bersama Infrastructure TBK |
| Others |
Value Chain & Pricing Dynamics
Project-based contracting with multi-year service attachments locks in both semiconductor allocation priority and price visibility for active DAS deployments across Indonesia's rail corridors and Singapore's integrated resorts. China's MIIT GB standards compliance and India's WPC ETA certification create tiered qualification barriers that segment supplier access and sustain margin premiums for certified component vendors.
Pricing Analysis
Certification level (MIIT GB/WPC ETA-grade) creates the primary spread between active DAS architectures and passive legacy systems. Three-tier pricing structure separates premium active fiber-fed deployments from standard hybrid configurations and economy passive coaxial installations. Cost compression in the passive tier is intensifying as Southeast Asian stadium operators accelerate 3.5 GHz migration timelines. Hospitality and education verticals exhibit the highest price sensitivity, while rail operators and integrated resort developers prioritize coverage uniformity guarantees over unit cost.
Supply Chain Analysis
Port congestion along the Shanghai-Singapore trade lane elevates landed costs for RF front-end modules and fiber optic cabling destined for ASEAN deployment sites. RF semiconductor fabrication concentrates in Taiwan and South Korea, while passive component assembly feeds from Vietnam and Thailand. Single-source vulnerability in remote radio unit chipsets exposes project timelines to foundry allocation volatility. Distribution runs through authorized system integrators with MIIT and WPC certification credentials rather than open component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized RF engineering capabilities in 3.5 GHz propagation modeling and fiber-to-the-antenna design lag deployment demand across Southeast Asia, constraining project execution velocity and inflating labor premiums for qualified integrators.
For Market Incumbents: Consolidate certification credentials across China's MIIT GB standards and India's WPC ETA frameworks to filter out modular component competitors from premium project tiers. Deepen captive semiconductor sourcing relationships with Taiwan and South Korea foundries to secure allocation priority during supply volatility. Neutral host revenue-sharing complexity presents margin pressure; standardize contract templates to accelerate venue operator negotiations. For New Entrants and Emerging Players: Lead with O-RAN compliant interface specialization targeting Singapore's integrated resort developers seeking interoperability guarantees across 10-15 year infrastructure lifecycles. Vietnam's electronics assembly migration creates localized component sourcing hubs with reduced landed cost for ASEAN hospitality and education projects. Position as modular remote radio unit suppliers to fragment procurement away from vertically integrated system vendors. For Investors and Strategic Acquirers: Capital is best deployed toward RF engineering services firms with proven 3.5 GHz propagation modeling capabilities and existing MIIT/WPC certification relationships. Long-term viability rests on software-defined RAN convergence enabling multi-tenant neutral host monetization. Monitor Japan's MIC millimeter-wave allocation enforcement as the signal indicating antenna density upgrade cycles across commercial districts.| Strategic Initiative | Industry Significance |
|---|---|
| O-RAN Compliance Certification | Singapore property developers specify interoperable interfaces to avoid single-source dependency. |
| Certification Investment (MIIT/WPC) | China and India regulatory barriers filter uncertified suppliers from premium project tiers. |
| Software-Defined RAN Integration | Cloud-native orchestration enables multi-tenant neutral host business models for venue operators. |
| RF Engineering Talent Acquisition | Specialized 3.5 GHz propagation skills lag deployment demand across Southeast Asia. |
| Vietnam Manufacturing Localization | Electronics assembly migration reduces landed costs for ASEAN hospitality and education projects. |
Study Parameters
The analysis maps active DAS, passive DAS, hybrid configurations, and small cell architectures, each validated through primary interviews with RF engineering directors, venue operator procurement leads, rail authority project managers, and DAS system integrators. Secondary validation draws from MIIT GB standards filings, WPC ETA certification databases, Japan MIC spectrum allocation notices, and ACMA electromagnetic exposure guidelines. Bottom-up project pipeline assessment triangulates against top-down vendor revenue segmentation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models technology tier, end-use vertical, installation type, and regional regulatory cluster dimensions. CAGRs derive from deployment timeline compression analysis and 5G NR densification mandate trajectories. Fiber backbone capacity pre-installation rates and antenna node density requirements inform infrastructure expansion assumptions.
The analysis sits within stated boundaries; outcomes outside sustained MIIT spectrum enforcement, WPC certification timeline stability, or neutral host commercial model adoption would require recalibration. Forecasts reflect documented assumptions regarding semiconductor supply allocation, rail corridor construction schedules, and stadium modernization investment cycles. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
5G Wireless Ecosystem Market
Wireless Technologies
Global Mobile and Wireless Backhaul Market
Wireless Technologies
France Fixed Wireless Access (FWA) Market
Wireless Technologies
Italy Fixed Wireless Access (FWA) Market
Wireless Technologies
Wifi Kiosks Market
Wireless Technologies
Global WLAN Market
Wireless Technologies
Multefire Market
Wireless Technologies
Outdoor Wi-Fi Market
Wireless Technologies
Wireless Intercom Equipment Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
Latin America Wireless Mesh Networking Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
Wireless Connectivity Market
Wireless Technologies
5G Small Cell Market
Wireless Technologies
Global Wireless Mesh Network Market
Wireless Technologies
Global Wireless Health Market