
 Outdoor Wi-Fi Market | 2026-2036
Outdoor Wi-Fi Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Wi-Fi Market Insights
The EU Green Deal is shifting procurement criteria for public infrastructure projects across member states, mandating energy-efficient network equipment in outdoor deployments. Cisco Systems leverages its enterprise routing portfolio to anchor large-scale smart city contracts in European municipalities. Hewlett Packard Enterprise competes through its Aruba Networks subsidiary, which specializes in cloud-managed outdoor access points with integrated IoT radios. Huawei Technologies dominates supply to Asia-Pacific telecom operators building neutral-host outdoor networks.
Outdoor Wi-Fi encompasses ruggedized wireless access infrastructure engineered to withstand temperature extremes, moisture ingress, and particulate contamination while delivering sustained throughput across uncontrolled environments. Equipment typically carries IP67 or IP65 enclosure ratings and operates across extended temperature ranges to maintain link stability in direct sunlight or freezing conditions. Mesh systems are capturing expanded share in campus and recreational deployments where trenching fiber proves cost-prohibitive. Wi-Fi 6 technology leads new installations by enabling denser client associations and improved battery efficiency for connected devices in high-footfall public spaces.
The Federal Communications Commission in the United States governs spectrum allocation and transmit power limits for unlicensed outdoor radio operations, while the European Telecommunications Standards Institute harmonizes cross-border interoperability requirements. China's Ministry of Industry and Information Technology administers type-approval processes that shape product design cycles for equipment destined for East Asian deployments. Stakeholders must weigh spectrum licensing trajectories and local content rules when configuring regional manufacturing and distribution footprints.
Market Dynamics
Smart city infrastructure mandates are compressing deployment timelines for municipal outdoor networks, forcing equipment vendors to accelerate certification cycles and pre-integrate management platforms with urban IoT backbones.
Growth Catalysts
- EU Green Deal procurement mandates:Energy-efficiency requirements for public infrastructure are redirecting municipal budgets toward certified low-power outdoor access points across member states.
- Wi-Fi 6E spectrum expansion:The FCC's 6 GHz unlicensed allocation is unlocking higher-density deployments in US stadiums and transit hubs without licensed spectrum costs.
- Neutral-host network proliferation:Asia-Pacific telecom operators are consolidating indoor-outdoor coverage through shared infrastructure models that reduce per-carrier capex burdens.
Market Restraints
- Semiconductor supply concentration:RF front-end component sourcing remains concentrated among a limited set of foundry operators, creating lead-time volatility for outdoor-rated chipsets.
- IP67 enclosure cost premiums:Ruggedized housing materials and gasket engineering add 40-60% manufacturing cost overhead versus indoor equivalents, compressing margin structures at volume.
- Sub-6 GHz spectrum congestion:Unlicensed band saturation in dense urban corridors is degrading effective throughput and forcing premature refresh cycles.
Strategic Opportunities
- India Smart Cities Mission:Federal funding for 100 urban centers is creating tender pipelines for integrated Wi-Fi and surveillance infrastructure with 10-year operations contracts.
- Private 5G-Wi-Fi convergence:Enterprise manufacturing campuses are requesting unified policy engines that bridge licensed cellular and unlicensed Wi-Fi under single network management.
- Edge AI radio integration:On-device inference capabilities are opening new revenue streams through anonymized pedestrian analytics sold as subscription services to retail and venue operators.
Industry Challenges
- RF engineering talent scarcity:Specialized expertise in outdoor propagation modeling and interference mitigation remains concentrated among legacy telecom vendor alumni, constraining product development velocity.
- Multi-agency certification complexity:Equipment must sequentially satisfy FCC Part 15, EU Radio Equipment Directive, and country-specific type-approval processes before commercial shipment, extending time-to-revenue.
- Legacy controller integration:Enterprise customers with embedded Cisco or HPE management architectures face forklift upgrade costs when adopting cloud-native outdoor platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Wi-Fi Market |
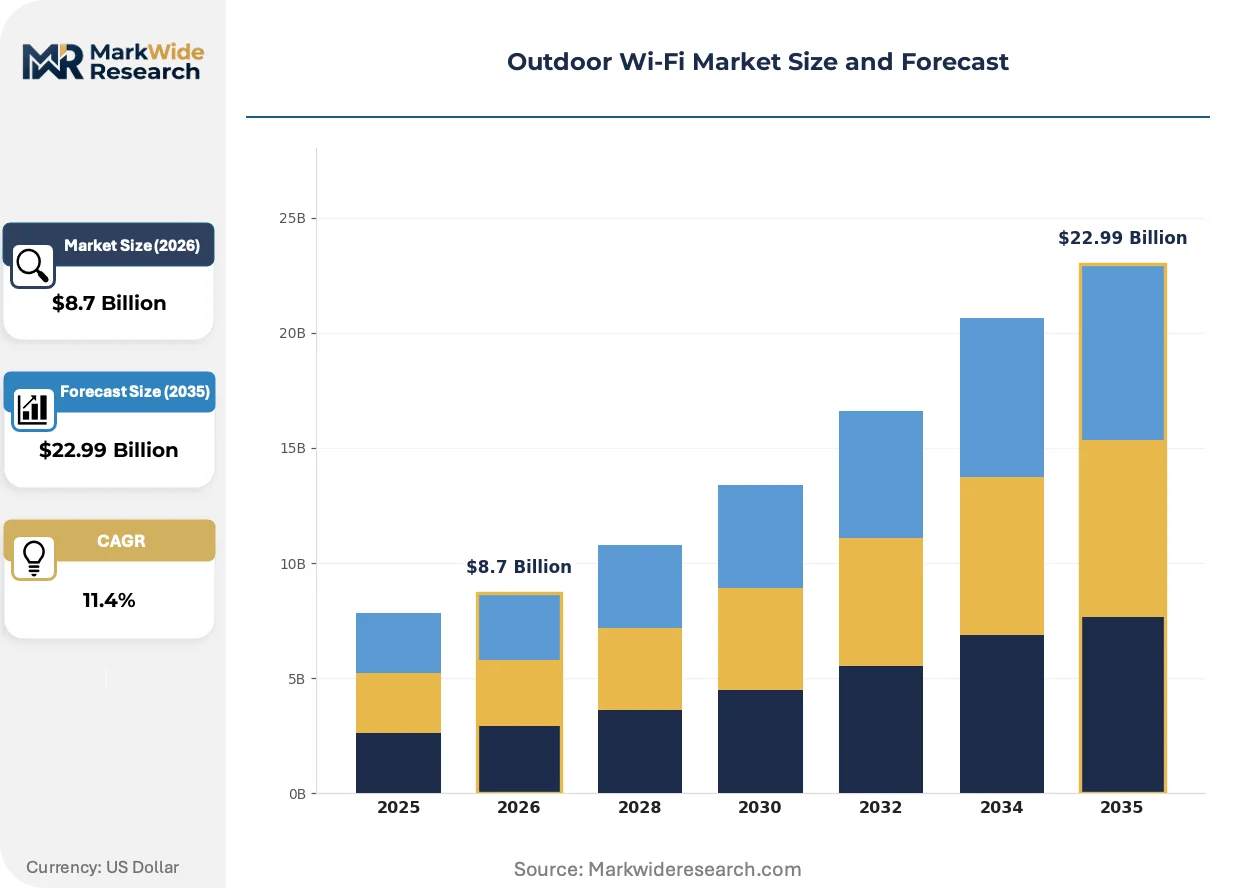
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Access Points, Extenders, Mesh Systems, Routers Deployment Type: Indoor, Outdoor, Hybrid, Cloud-Based End User: Hospitality, Retail, Education, Public Spaces Technology: Wi-Fi 5, Wi-Fi 6, Long Range, Dual Band |
| Companies Covered | Cisco Systems, Hewlett Packard Enterprise, Fortinet, Juniper Networks, Aruba Networks, Huawei Technologies, NETGEAR, Ubiquiti Networks, CommScope, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Wi-Fi Market Trends and Innovations
Network architecture is fragmenting from monolithic controller systems toward disaggregated software stacks, enabling operators to mix hardware vendors without management platform lock-in. This decomposition is accelerating procurement cycle compression and reshaping vendor competitive moats.
Open Radio Access Network specifications are modularizing outdoor Wi-Fi deployment models, allowing neutral-host operators to source radios, baseband, and orchestration layers from separate suppliers. Stadium and convention center operators in Germany and Japan are piloting these disaggregated stacks to reduce single-vendor dependency. The structural consequence is compressing incumbent pricing power while elevating systems integrators who can certify multi-vendor interoperability.
The EU Radio Equipment Directive's 2024 cybersecurity amendments are mandating firmware signing and vulnerability disclosure timelines for all network infrastructure sold in member states. Hardware vendors must now embed secure boot architectures and maintain 10-year patch commitments, increasing non-recurring engineering costs. Outdoor equipment categories with extended deployment lifecycles face the steepest compliance burden, favoring vendors with established European service organizations.
Consumption patterns are pivoting from perpetual licensing toward subscription-based network-as-a-service contracts, particularly among municipal buyers with constrained capital budgets. French and Spanish city governments are leading this shift, bundling hardware, installation, and 7-year maintenance into single operational expenditures. The model transfers technology obsolescence risk to vendors while demanding sophisticated financing capabilities that tier-2 equipment suppliers struggle to match.
Outdoor Wi-Fi Market Segmentation
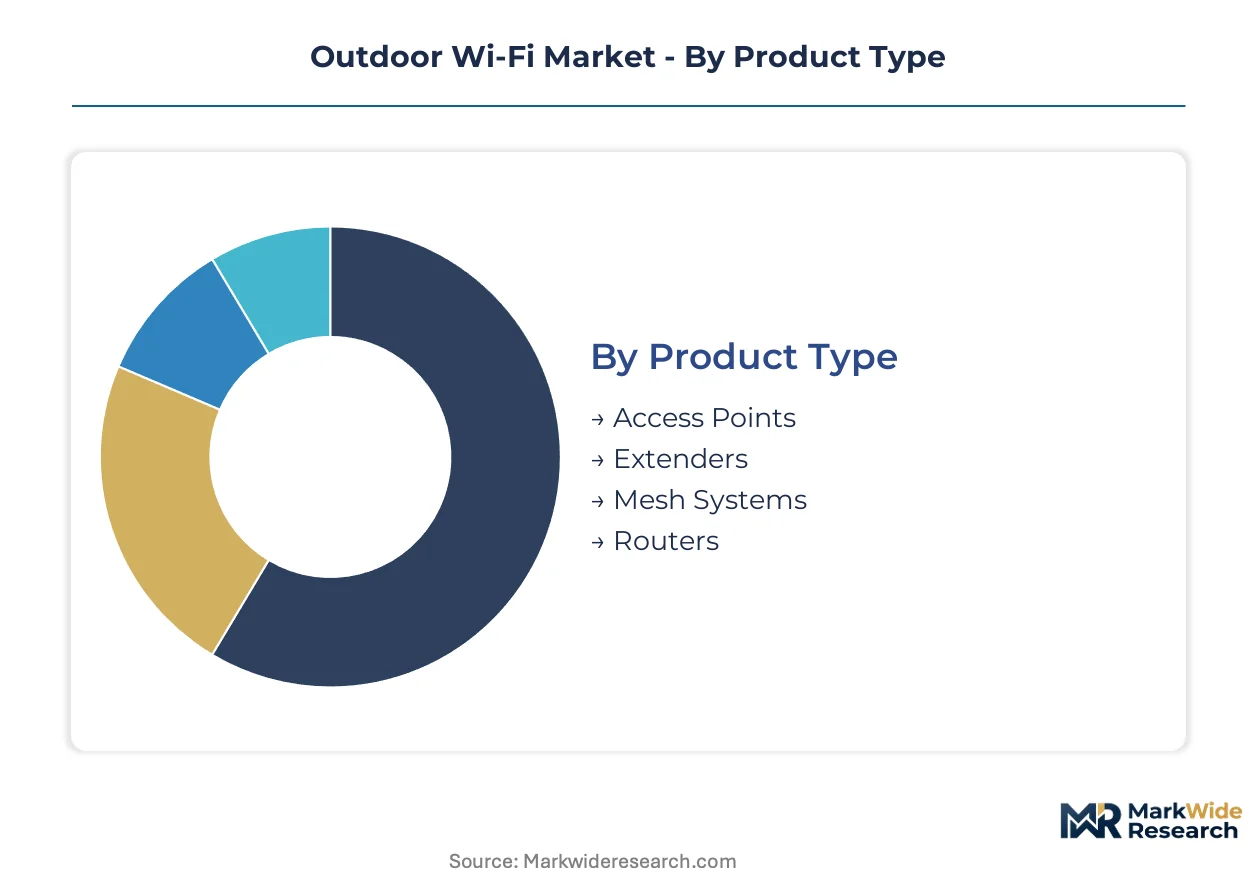
Outdoor Wi-Fi segmentation reveals how hardware specifications, deployment architectures, and spectrum capabilities map to distinct procurement patterns across municipal, enterprise, and venue operator budgets. Understanding these divides clarifies why vendor product portfolios fragment across ruggedization tiers and management complexity levels.
Product Type:
Standalone access points dominate straightforward coverage extensions, while mesh systems and extenders embed into broader campus or smart city backbones requiring seamless handoff capabilities.
- Access Points:Ruggedized enclosures with IP67 ratings and integrated directional antennas serve stadium concourses and transit platforms. Barcelona's municipal deployments favor these units for their direct compatibility with legacy Cisco controller architectures.
- Mesh Systems:Self-healing multi-hop configurations eliminate fiber trenching in parks and recreational corridors. Singapore's Gardens by the Bay installation demonstrates how battery-backed mesh nodes sustain coverage through monsoon-induced power fluctuations.
- Extenders:Bridge devices amplify signal reach across warehouse yards and marina docks where primary infrastructure stops short.
- Routers:Edge-routing units with embedded LTE failover serve remote construction sites and temporary event installations.
Volume placements concentrate in Access Points; the faster expansion belongs to Mesh Systems.
Deployment Type:
Pure outdoor specifications command manufacturing premiums, whereas hybrid and cloud-managed configurations reduce operational overhead through centralized policy orchestration.
- Outdoor:Purpose-built hardware withstands temperature swings from -40°C to 60°C and salt spray corrosion in coastal installations. FCC Part 15 transmit power limits shape antenna gain specifications for US deployments.
- Hybrid:Unified indoor-outdoor management platforms serve university campuses and hospital systems seeking consistent authentication across building perimeters. Aruba Networks and Cisco compete aggressively for these contracts in German and French higher education tenders.
- Cloud-Based:Controller-less architectures provisioned through web dashboards appeal to municipal IT departments with limited RF engineering staff. French city governments lead adoption here, bundling seven-year operational contracts.
- Indoor:Climate-controlled specifications with standard enclosures serve transitional spaces like atriums and covered walkways.
Hybrid deployments capture the largest project values; cloud-based configurations are climbing the fastest as operational expenditure models displace capital budgets.
End User:
Procurement sophistication varies sharply across sectors, with public spaces demanding decade-long service commitments while retail operators prioritize rapid deployment cycles.
- Public Spaces:Municipal RFPs mandate IPv6 support, encrypted management tunnels, and compliance with EU Radio Equipment Directive cybersecurity amendments. Barcelona and Singapore tenders exemplify this specification density.
- Hospitality:Resorts and hotel chains prioritize seamless roaming across pool decks, golf courses, and beachfronts. Marriott's Caribbean properties have standardized on Wi-Fi 6E for interference-resistant guest streaming.
- Retail:Big-box operators and shopping districts leverage Wi-Fi analytics for footfall measurement, requiring edge AI radio integration that Huawei and HPE now bundle as subscription services.
- Education:K-12 districts and universities face E-Rate funding compliance in the US, while European institutions align procurement with EU Green Deal energy-efficiency mandates.
Public Spaces absorb the highest unit volumes; Retail shows the steepest expansion trajectory as monetizable analytics justify infrastructure refresh cycles.
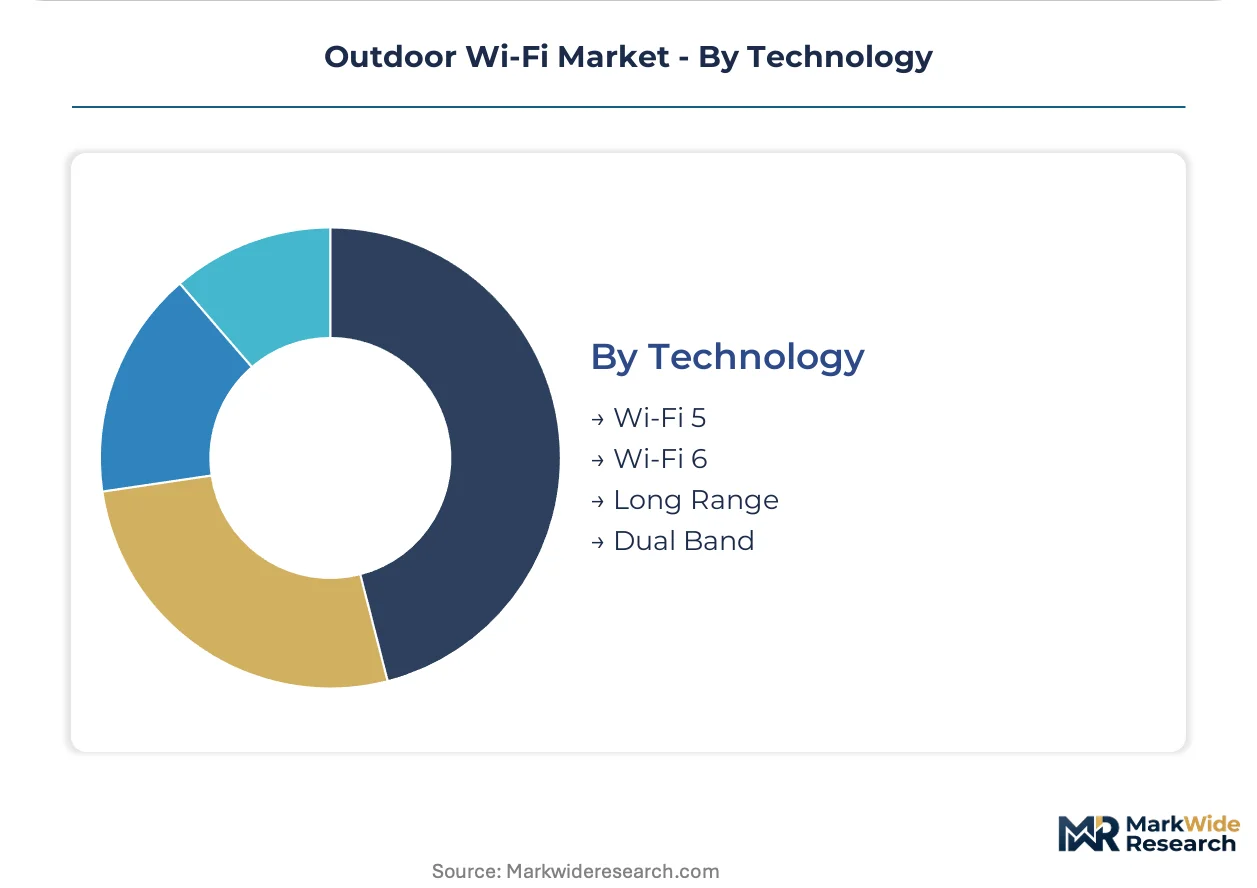
Technology:
Spectrum allocation and client device compatibility dictate technology selection, with newer standards enabling denser associations but requiring hardware refresh investments.
- Wi-Fi 6:OFDMA and target wake time protocols support thousands of simultaneous connections in stadiums and convention centers. The standard leads new installations across Asia-Pacific urban densification programs.
- Dual Band:Simultaneous 2.4 GHz and 5 GHz operation maintains backward compatibility with legacy IoT sensors while delivering throughput to modern smartphones. Industrial campuses in Japan and Germany specify this flexibility for mixed-device environments.
- Wi-Fi 5:802.11ac hardware continues in cost-sensitive deployments where client density remains moderate and refresh budgets are constrained.
- Long Range:Proprietary protocol extensions extend coverage across agricultural monitoring and remote utility infrastructure, though these sacrifice interoperability for reach.
Wi-Fi 6 commands the dominant placement share; Dual Band configurations are gaining share fastest as IoT device diversity complicates spectrum planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Smart Nation initiative anchors municipal outdoor network deployment across Southeast Asia, with the Gardens by the Bay installation demonstrating mesh resilience through monsoon conditions.
United States
The FCC's 6 GHz unlicensed allocation drives stadium and transit hub densification, while E-Rate funding shapes K-12 district procurement. Dallas-Fort Worth airport corridors host neutral-host pilots bridging cellular and Wi-Fi under unified policy engines.
Germany
Bundesnetzagentur spectrum harmonization enables cross-border interoperability for outdoor campus networks. Bavarian industrial zones pilot private 5G-Wi-Fi convergence at manufacturing campuses seeking unified management platforms.
China
MIIT type-approval processes compress product design cycles for neutral-host equipment serving telecom operators. Yangtze River Delta smart city clusters deploy high-density Wi-Fi 6 infrastructure across Shanghai's public transit corridors.
India
The Smart Cities Mission funds 100 urban centers with 10-year operations contracts for integrated Wi-Fi and surveillance. Maharashtra's Mumbai-Pune corridor leads tender pipelines for municipal IT departments with constrained capital budgets.
Spain
EU Green Deal procurement mandates redirect municipal budgets toward certified low-power access points. Barcelona's metropolitan deployments favor ruggedized units compatible with legacy controller architectures across smart city infrastructure.
Outdoor Wi-Fi Market Competitive Landscape
Premium-margin players sit above commodity-margin players across ruggedization tiers and management complexity levels. The vendor base stratifies between enterprise routing specialists, cloud-native platform providers, and telecom equipment incumbents. Three archetypes dominate: full-stack infrastructure vendors, disaggregated systems integrators, and subscription-based network-as-a-service operators. Competitive intensity concentrates on certification acceleration and multi-vendor interoperability validation.
Among US-based infrastructure vendors, Cisco Systems and Hewlett Packard Enterprise occupy positions across enterprise and municipal segments, with HPE's Aruba Networks subsidiary representing cloud-managed specialization. Huawei Technologies anchors supply relationships with Asia-Pacific telecom operators building neutral-host architectures. These three exemplify distinct strategic postures: controller-anchored incumbency, cloud-native diversification, and integrated telecom equipment supply.
| Leading Market Players |
|---|
| Cisco Systems |
| Hewlett Packard Enterprise |
| Fortinet |
| Juniper Networks |
| Aruba Networks |
| Huawei Technologies |
| NETGEAR |
| Ubiquiti Networks |
| CommScope |
| Others |
Pricing and Supply Chain Analysis
Copper and aluminum commodity indices on the London Metal Exchange cascade through outdoor Wi-Fi manufacturing costs, with enclosure-grade alloys commanding 15-20% premiums over standard grades and forcing tiered pricing stratification across ruggedization levels.
Pricing Analysis
Throughput-guarantee contracts anchor enterprise municipal procurement, with vendors pricing against sustained gigabit-per-second delivery rather than hardware unit costs. Three-tier pricing structure across premium, standard, and economy levels separates IP67-certified smart city units from hybrid campus deployments and indoor-extender bridge devices. Cost compression in standard-tier mesh systems is intensifying because Asian contract manufacturers are absorbing enclosure engineering overhead into volume production. Municipal buyers with decade-long service mandates show lowest price sensitivity; retail operators refreshing analytics-capable infrastructure every 3-4 years drive hardest bargain negotiations.
Supply Chain Analysis
Direct-to-municipality channels handle smart city tender demand, while distributor networks serve mid-market campus and hospitality deployments. RF front-end component sourcing concentrates in Taiwan, South Korea, and Japan, with gallium nitride power amplifiers and beamforming antenna arrays feeding from specialized foundry capacity. IP67-rated aluminum die-casting and fluorosilicone gasket materials constitute critical input dependencies. Single-source vulnerability in 6 GHz filter supply creates chokepoint exposure for Wi-Fi 6E product ramps. Distribution runs through value-added resellers with RF engineering certification in European and North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Radio Equipment Directive cybersecurity amendments are compressing weaker vendors out of European procurement pipelines, accelerating consolidation toward suppliers with 10-year firmware maintenance capabilities and established service organizations.
For Market Incumbents: Extend cloud-native management platform coverage to neutral-host telecom operators before Huawei solidifies Asia-Pacific anchor tenancy. Accelerate FCC Part 15 and EU RED certification pre-clearance for Wi-Fi 7 hardware to outpace mid-tier competitors lacking regulatory affairs scale. Defensive consolidation through acquisition of edge-AI analytics specialists addresses retail sector subscription revenue threats.
For New Entrants and Emerging Players: Open RAN disaggregation protocols offer entry wedge into German and Japanese stadium pilots seeking multi-vendor interoperability validation. Target India's Smart Cities Mission tender pipeline where 10-year operations contracts favor financing-capable challengers over hardware-only vendors. Lead with subscription-based network-as-a-service positioning to bypass incumbent controller-locked installed bases.
For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-native platform specialists with existing EU service footprints amid tier-2 vendor margin collapse. Five-to-ten year viability windows reward acquisitions of RF engineering talent pools concentrated among legacy telecom alumni. Monitor FCC 6 GHz spectrum allocation enforcement as inflection signal for US densification investment waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Clearance Investment | Accelerated FCC Part 15 and EU RED approvals compress time-to-revenue against competitors. |
| Edge-AI Radio Integration | On-device inference capabilities unlock footfall analytics subscriptions for retail venue operators. |
| Neutral-Host Partnership | Shared infrastructure models with Asia-Pacific telecom operators reduce per-carrier capex burdens. |
| Open RAN Stack Development | Modular disaggregation appeals to German stadium operators reducing single-vendor dependency. |
| Network-as-a-Service Financing | Operational expenditure bundling transfers technology obsolescence risk from municipal buyers. |
Research Methodology
Document review covered FCC spectrum allocation filings, EU Radio Equipment Directive amendments, and MIIT type-approval databases, complemented by interviews with municipal IT procurement directors, RF engineering leads at equipment vendors, smart city project managers, and telecom infrastructure planners. Secondary validation drew from customs trade data, SEC 10-K infrastructure disclosure segments, and hyperscaler outdoor network capex announcements. Bottom-up unit shipment estimates triangulated against top-down municipal budget allocation analysis.
Historical deployment trajectories cross-referenced against expert panel input on spectrum licensing timelines and smart city funding cycles. Segmentation modeling spanned ruggedization tier, deployment architecture, end-use sector, and technology generation across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating client density coefficients and refresh cycle compression factors. Forecast inputs included EU Green Deal procurement mandate adoption rates and FCC 6 GHz unlicensed utilization trajectories.
Several conditions sit outside the modeled scope, including unforeseen spectrum reallocation decisions, geopolitical trade restrictions on semiconductor equipment, and pandemic-scale supply chain disruptions. Forecasts reflect base-case assumptions regarding certification timeline stability and municipal budget continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Wireless Microphone Market
Wireless Technologies
Industrial Wireless Solution Market
Wireless Technologies
Asia-Pacific Wireless Microphone Market
Wireless Technologies
Wireless USB (WUSB) Devices Market
Wireless Technologies
Public Wi-Fi Market
Wireless Technologies
USA Li-Fi Market
Wireless Technologies
North America Wireless Microphone Market
Wireless Technologies
Wireless Phone Chargers Market
Wireless Technologies
Global Gi Fi Technology Market
Wireless Technologies
Europe Wireless Microphone Market
Wireless Technologies
Telecom Wireless Data Market
Wireless Technologies
Global Open Radio Access Network (Oran) Market
Wireless Technologies
Global Wireless Testing Market
Wireless Technologies
Telecom Millimeter Wave (MMW) Technology Market
Wireless Technologies
Wimax Market
Wireless Technologies
Global Wireless Health Market