
 5G Small Cell Market | 2026-2036
5G Small Cell Market Size, Share, and Industry Trends Forecast 2026-2036
5G Small Cell Market Analysis
Open RAN disaggregation is reconfiguring how baseband processing splits from radio units in small cell architectures. Ericsson leverages its massive MIMO portfolio to sustain technology leadership in integrated deployments. Nokia Corporation anchors European supply chains through its AirScale portfolio, while Samsung Electronics dominates 5G vRAN trials with Korean operators.
A 5G small cell is a low-power radio access node operating in licensed and unlicensed spectrum below 250 mW, designed to extend coverage and capacity in dense environments through sub-6 GHz and mmWave frequencies. Femtocell and picocell installations lead current volume shipments for indoor enterprise environments where wall-mounted deployment minimizes civil works. Microcell and metrocell segments capture outdoor pole-mounted applications where hybrid deployment models blending standalone and cloud-based architectures show the fastest structural expansion.
The FCC governs spectrum auctions and equipment authorization in the United States, while the EU AI Act and CE marking frameworks shape product compliance across European deployments. China's MIIT enforces GB standards and dual carbon goals that constrain base station power budgets, directly influencing radio unit design specifications. Stakeholders must monitor how open interface standardization at O-RAN Alliance intersects with national security review regimes to determine vendor eligibility and procurement timelines.
Market Dynamics
Open RAN disaggregation is fragmenting the vendor base as baseband processing decouples from radio units, forcing incumbents to defend integrated portfolios while software-native entrants capture virtualized deployment contracts.
Growth Catalysts
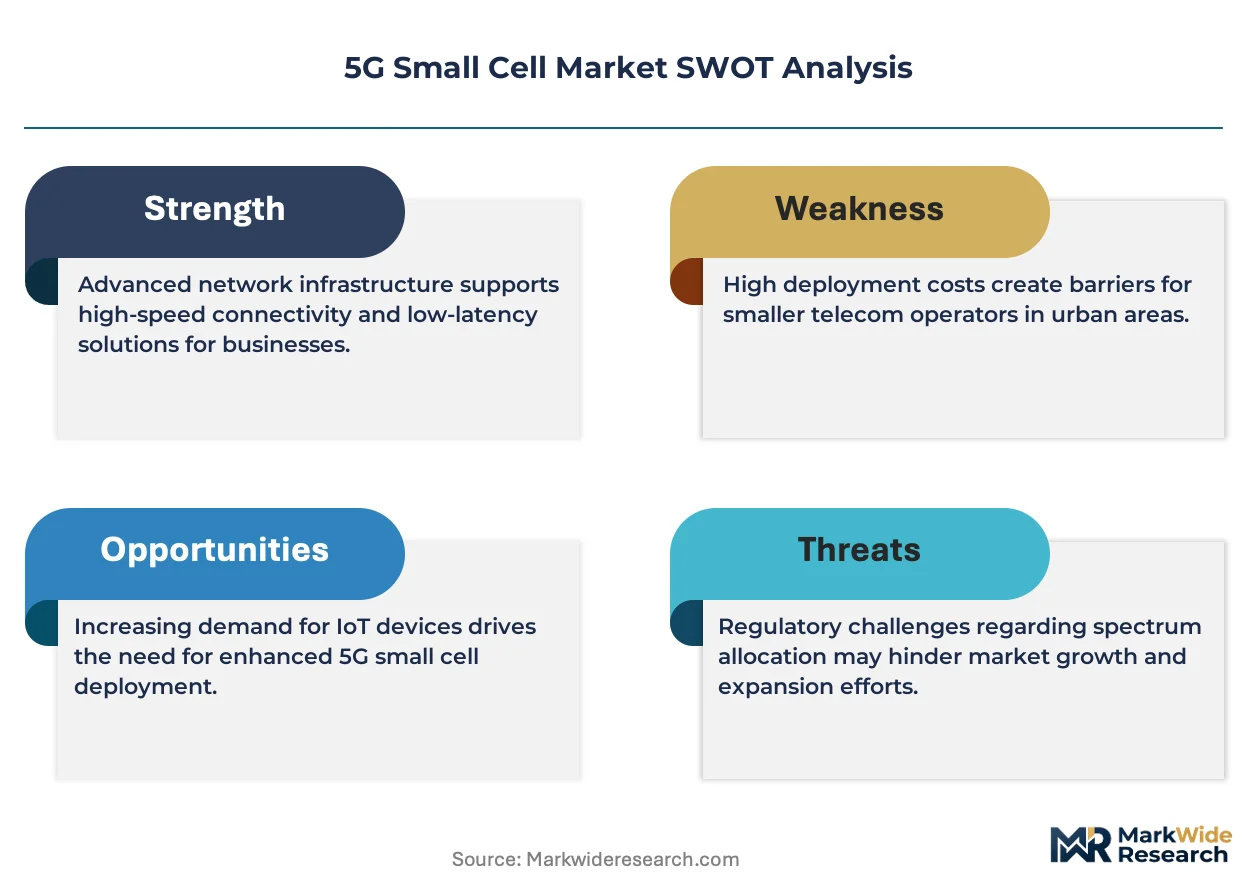
- FCC spectrum allocation rules:The United States regulator's mid-band auction releases are accelerating carrier capital deployment timelines for dense urban small cell grids.
- Enterprise private networks:Manufacturing clusters in China are deploying integrated baseband-radio units for deterministic latency in automated production lines.
- mmWave densification:Korean operators are driving volume shipments of outdoor pole-mounted microcells to sustain gigabit throughput in Seoul's commercial districts.
Market Restraints
- Radio frequency component concentration:Gallium nitride power amplifier supply concentrates among a limited set of foundry operators, creating input cost volatility for sub-6 GHz unit production.
- MIIT power budgets:China's GB standards enforce dual carbon goals that constrain base station energy consumption, limiting radio unit output specifications.
- Site acquisition friction:Municipal permitting regimes in dense European cities extend deployment timelines for street-level small cell installations.
Strategic Opportunities
- India's smart city mandates:The country's urban infrastructure programs are creating procurement channels for integrated small cell street furniture in Tier-1 metropolitan zones.
- Neutral host models:Third-party infrastructure providers are capturing multi-tenant revenue streams by deploying shared small cell assets in US commercial real estate.
- AI-driven radio resource management:Convergence of machine learning inference with edge compute is enabling dynamic spectrum allocation in Japanese industrial campuses.
Industry Challenges
- Open interface certification delays:O-RAN Alliance specification versioning lags commercial deployment timelines, forcing vendors to maintain multiple firmware branches.
- Legacy 4G interworking complexity:Dual-mode small cells require synchronized timing plane management across heterogeneous vendor generations, inflating integration engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Small Cell Market |
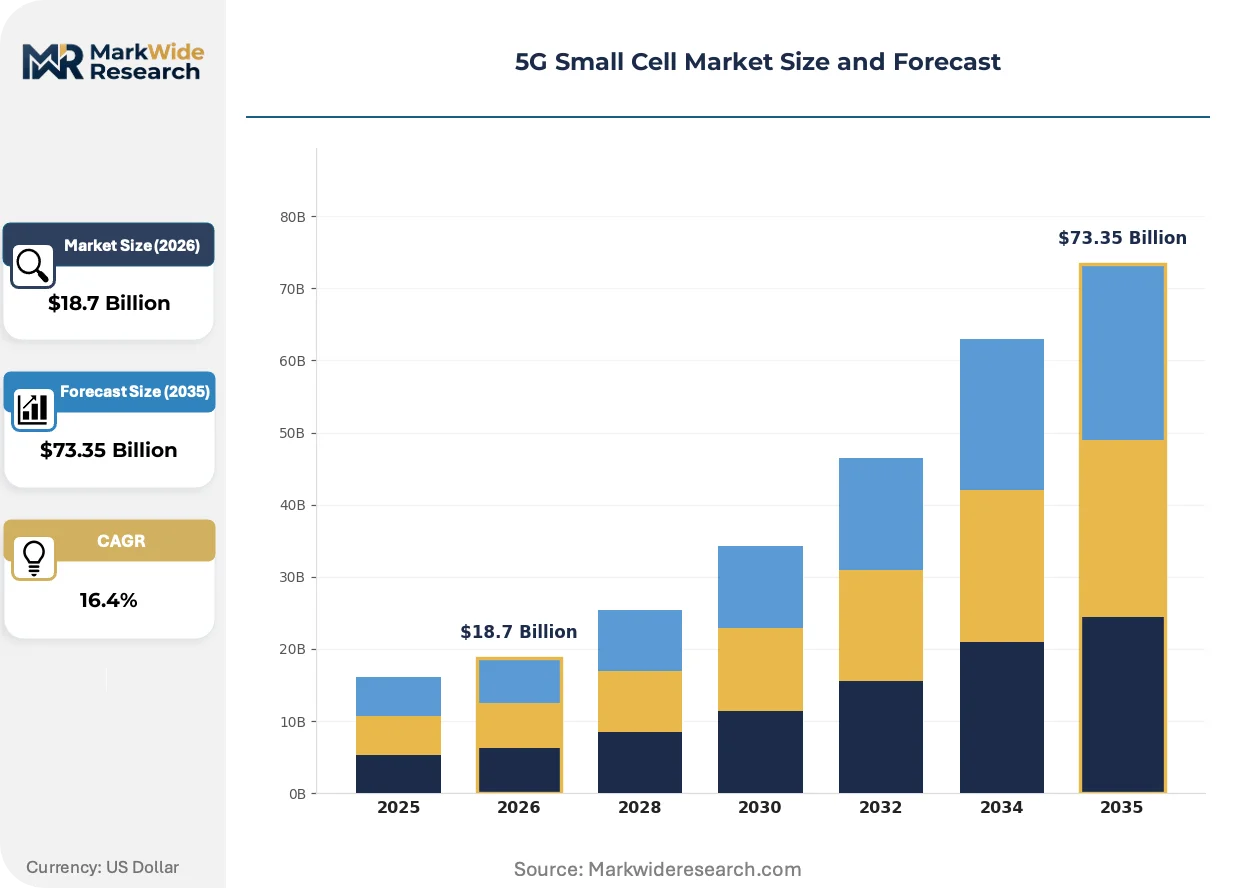
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Femtocell, Picocell, Microcell, Metrocells Installation: Outdoor, Indoor, Pole-mounted, Wall-mounted End User: Telecom Operators, Enterprises, Government, Public Safety Deployment: Standalone, Integrated, Hybrid, Cloud-based |
| Companies Covered | Ericsson, Nokia Corporation, Huawei Technologies, Cisco Systems, Samsung Electronics, ZTE Corporation, Qualcomm Technologies, NEC Corporation, Fujitsu Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Small Cell Market Emerging Trajectories
Virtualized baseband functions are compressing hardware refresh cycles as software-defined architectures permit feature deployment without physical site visits, altering how carriers contract for capacity expansion.
Cloud-native centralized units are migrating from purpose-built appliances to containerized workloads running on commodity servers. Tier-1 carriers in South Korea are adopting this architecture fastest, compressing three-year hardware replacement cycles into continuous software rollouts. The shift is migrating from vendor-locked integrated stacks toward multi-supplier disaggregated procurement models.
The EU AI Act's risk classification framework is imposing documentation burdens on small cells with embedded inference engines for traffic optimization. Equipment vendors must now maintain algorithmic transparency registers for deployments in European Union member states. This is slowing product launches for AI-enhanced radio units while creating compliance service revenue streams for certification consultancies.
Neutral host infrastructure procurement is displacing direct carrier ownership models in US commercial real estate. Property developers now contract specialized firms to deploy and operate multi-tenant small cell systems, unbundling network access from tenancy agreements. This pattern is most visible in Texas and Florida logistics hubs where warehouse operators demand guaranteed coverage without managing carrier relationships directly.
5G Small Cell Market Segmentation
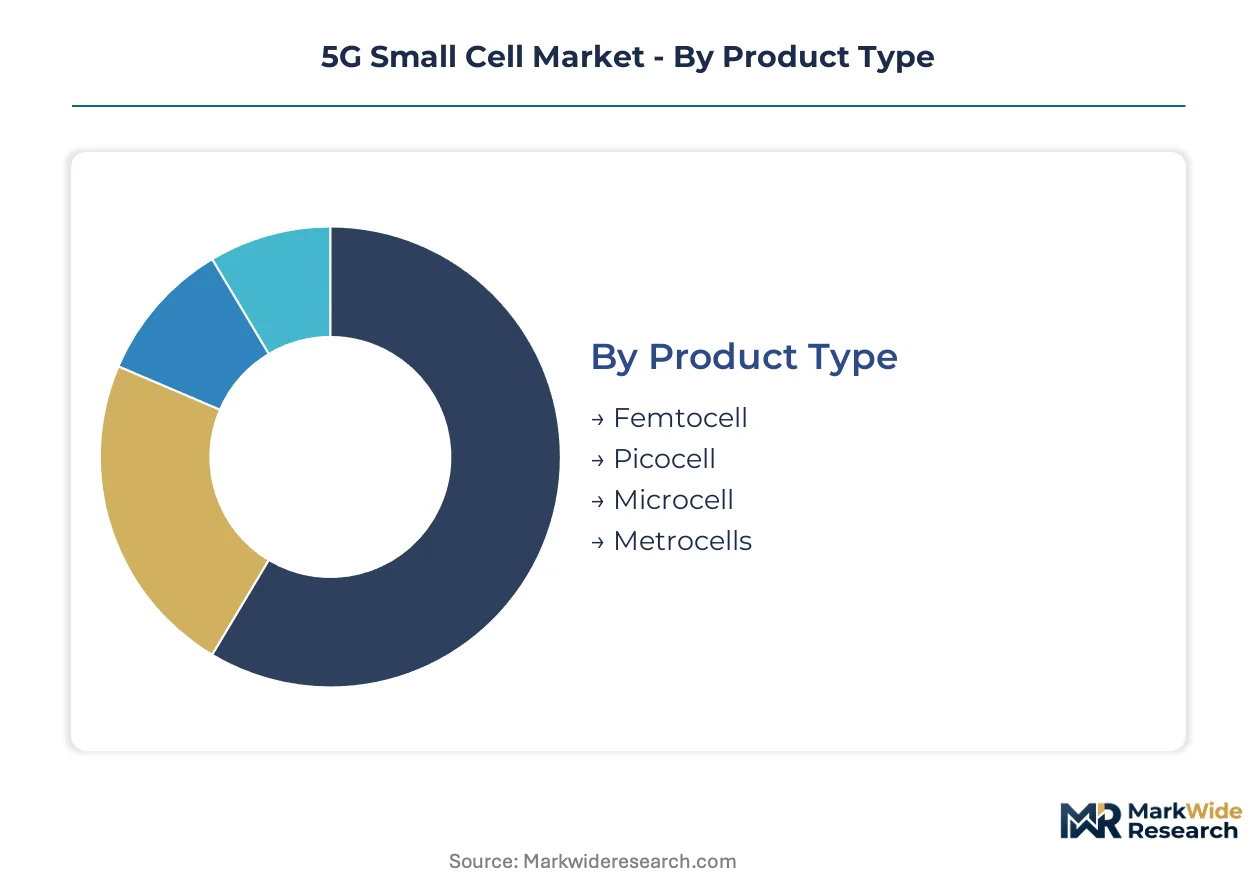
5G small cell segmentation reflects how deployment physics, site constraints, and buyer economics fragment procurement patterns. Each dimension—product scale, mounting method, customer type, and architecture—creates distinct vendor qualification requirements and margin structures.
Product Type:
Mature indoor formats dominate current shipment volumes while outdoor metro-scale units emerge as the structural growth frontier.
- Femtocell:Ultra-low-power units below 20 mW designed for residential and SOHO environments. Demand concentrates in South Korean apartment complexes where telecom operators subsidize customer-premises equipment to reduce macro network load.
- Picocell:Wall-mounted indoor units operating between 100-250 mW with integrated antennas. Enterprise deployments in China's manufacturing clusters drive adoption for deterministic coverage in automated production zones where cabling costs dominate total project economics.
- Microcell:Outdoor pole-mounted systems serving 200-500 meter radii in urban corridors. German municipal permitting regimes favor these for street-level densification where macro site acquisition fails.
- Metrocells:High-capacity outdoor nodes supporting hundreds of simultaneous users in dense commercial districts. Indian smart city mandates in Mumbai and Delhi are creating procurement channels for integrated street furniture deployments.
Picocell installations handle the majority of throughput; metrocells are expanding most quickly on share.
Installation:
Cost tier stratification separates civil-works-heavy outdoor deployments from rapid-install indoor alternatives.
- Outdoor:Ground-based cabinets and concealed street furniture requiring trenching and power distribution. FCC pole attachment rules in the United States accelerate timelines where utility infrastructure is accessible.
- Indoor:Enterprise-grade distributed antenna systems and small cell overlays. Japanese industrial campuses deploy these for private network isolation where metal structures block macro signals.
- Pole-mounted:Strand-mounted or streetlight-integrated units minimizing ground footprint. Brazilian urban renewal programs in São Paulo specify these for favela coverage extension without land acquisition.
- Wall-mounted:Rapid-install brackets for enterprise and residential environments. UK commercial real estate developers favor these for neutral host deployments where tenant turnover demands flexible infrastructure.
Outdoor installations absorb the largest capital allocation per site; wall-mounted configurations are climbing the fastest on deployment velocity.
End User:
Customer type determines procurement sophistication, with telecom operators driving standardization while enterprise and public safety buyers demand customization.
- Telecom Operators:Tier-1 carriers specifying open interfaces and multi-vendor interoperability. Korean operators lead volume procurement through consolidated national infrastructure programs.
- Enterprises:Manufacturing, logistics, and mining firms deploying private 5G for operational technology integration. German automotive plants specify these for AGV coordination with sub-10 millisecond latency requirements.
- Government:Municipal broadband and rural coverage programs. India's BharatNet initiative sources integrated baseband-radio units for village connectivity targets.
- Public Safety:First responder networks requiring hardened equipment with mission-critical reliability. UAE critical infrastructure projects specify these for port and airport emergency communications.
Telecom operators commit the largest annual procurement volumes; enterprise buyers are gaining share fastest as private network regulations mature.
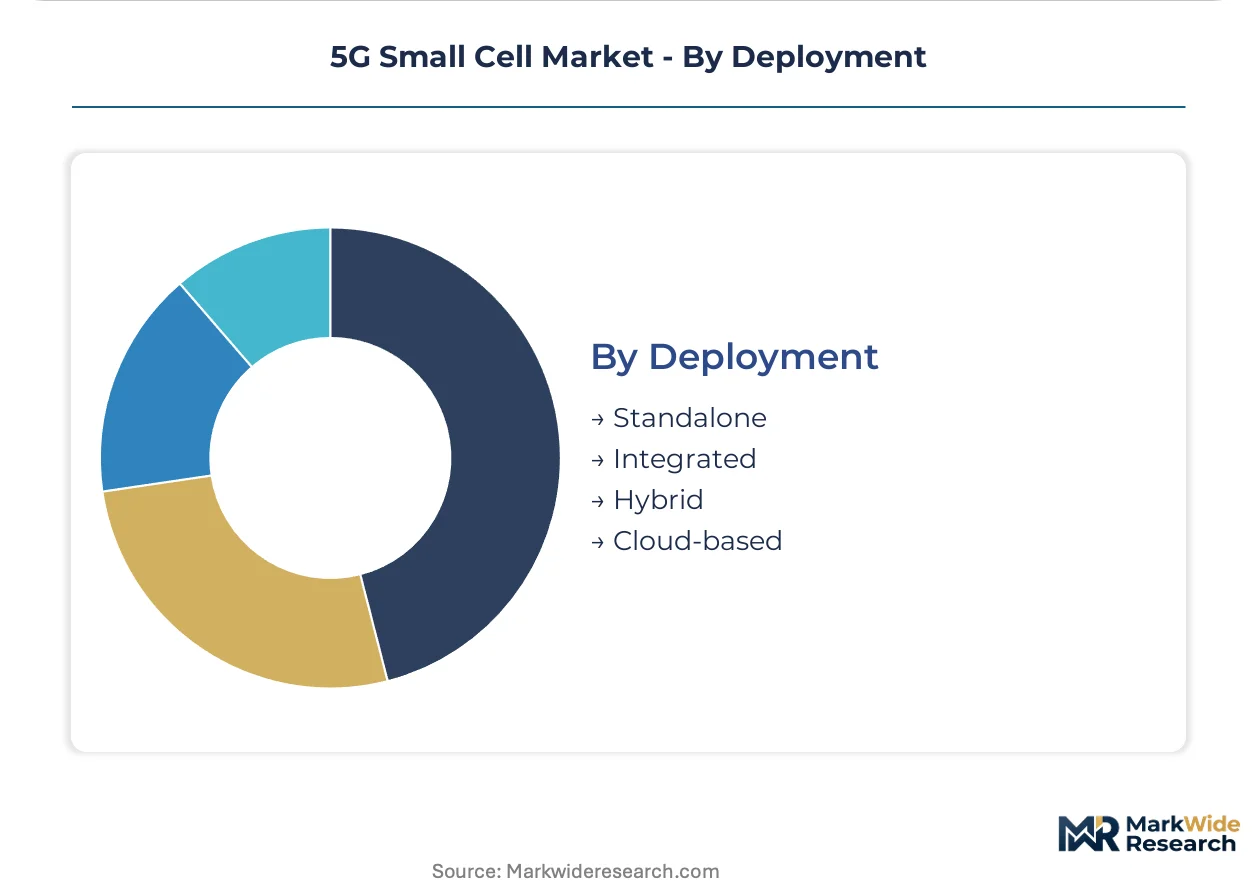
Deployment:
Architecture choice reflects the trade-off between operational control and capital efficiency, with virtualization disrupting traditional integrated procurement.
- Standalone:Self-contained baseband and radio units with no external dependencies. Rural deployments in Australia favor these where backhaul constraints prevent centralized architectures.
- Integrated:Vendor-locked baseband-radio combinations optimized for performance. Chinese MIIT power budget enforcement drives demand for these in dense urban grids where energy efficiency dominates total cost of ownership.
- Hybrid:Split architectures with centralized baseband and distributed radio units. US neutral host providers deploy these to serve multiple carriers from shared infrastructure.
- Cloud-based:Fully virtualized baseband functions running on commodity compute. South Korean carriers lead adoption, compressing hardware refresh cycles through software-defined feature deployment.
Integrated architectures still carry the majority of installed base; cloud-based deployments show the steepest expansion trajectory as open RAN specifications stabilize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean equipment manufacturers supply dense urban deployment projects across Southeast Asian markets, while Chinese radio unit producers dominate procurement channels for integrated baseband systems in manufacturing clusters.
United States
Telecom operators accelerate mid-band small cell grids following FCC spectrum auction releases. The regulator's equipment authorization framework shapes vendor qualification timelines for street-level densification. Texas and Florida logistics hubs drive neutral host infrastructure procurement where warehouse operators contract third-party providers.
China
Manufacturing clusters in coastal provinces deploy integrated baseband-radio units for automated production lines with deterministic latency requirements. MIIT enforces GB standards and dual carbon goals that constrain base station power budgets and influence radio unit design specifications. Yangtze River Delta cities concentrate procurement for energy-efficient dense urban grids.
South Korea
Korean operators lead global volume procurement through consolidated national infrastructure programs. The country's spectrum regulator accelerates mmWave densification timelines for gigabit throughput in Seoul's commercial districts. Busan-Ulsan industrial corridors drive private 5G adoption for automated manufacturing integration.
Germany
Automotive plants specify microcell deployments for AGV coordination with sub-10 millisecond latency requirements. Municipal permitting regimes favor street-level densification where macro site acquisition fails. Bavaria and Baden-Württemberg concentrate procurement for industrial campus private networks.
India
Smart city mandates in Mumbai and Delhi create procurement channels for integrated small cell street furniture. The BharatNet initiative sources baseband-radio units for village connectivity targets. Tier-1 metropolitan zones drive adoption of pole-mounted systems for urban infrastructure programs.
5G Small Cell Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around integrated portfolio vendors and software-native entrants. Incumbents defend vendor-locked baseband-radio combinations while open RAN disaggregation fragments procurement toward multi-supplier models. Strategic archetypes include integrated equipment vendors, semiconductor specialists, and cloud-native software providers. Dominant competitive moves encompass strategic partnerships for open interface certification and portfolio diversification into virtualized baseband functions.
Among Nordic integrated equipment vendors, Ericsson and Nokia Corporation exemplify archetypes defending technology leadership through massive MIMO portfolios and European supply chain anchoring respectively. Samsung Electronics occupies a position representing Korean vendor concentration in 5G vRAN trials and dense urban deployment volume.
| Leading Market Players |
|---|
| Ericsson |
| Nokia Corporation |
| Huawei Technologies |
| Cisco Systems |
| Samsung Electronics |
| ZTE Corporation |
| Qualcomm Technologies |
| NEC Corporation |
| Fujitsu Limited |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta manufacturing clusters anchor global radio unit capacity, concentrating gallium nitride power amplifier foundry output and compressing margins for sub-6 GHz baseband-radio combinations. FCC equipment authorization timelines and MIIT dual carbon enforcement create divergent compliance cost structures that fragment pricing power across export destinations.
Pricing Analysis
Sub-6 GHz integrated units command premium positioning against legacy 4G small cells and pre-commercial mmWave prototypes. Three-tier pricing structure across premium massive MIMO configurations, standard picocell deployments, and economy femtocell residential units dominates procurement contracts. Cost compression in economy tiers intensifies because Chinese foundry overcapacity floods the residential segment. Enterprise buyers in German automotive plants exhibit lowest price sensitivity due to deterministic latency requirements, while neutral host providers in US logistics hubs drive hardest bargain terms.
Supply Chain Analysis
US Commerce Department export controls on advanced semiconductor manufacturing equipment constrain gallium nitride substrate flows to Chinese radio unit producers. Taiwan and South Korea concentrate frontend wafer processing, while Malaysia and Vietnam handle final assembly and test. Supply chains draw from silicon carbide substrates, RF filter ceramics, and precision antenna substrates. Single-source vulnerability concentrates in GaN-on-SiC epitaxy services. Distribution runs through carrier-direct procurement for integrated stacks and systems integrator channels for open RAN disaggregated components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open RAN interface standardization at the O-RAN Alliance creates platform-economics inflection as interoperability protocols unbundle vendor-locked baseband-radio combinations into multi-supplier ecosystems.
For Market Incumbents: Pre-empt software-native entrants by accelerating containerized baseband function certification before open interface specifications stabilize. Defend integrated portfolio margins through captive gallium nitride foundry partnerships that constrain input cost volatility for sub-6 GHz unit production. Prioritize backward integration into RF filter ceramic supply.
For New Entrants and Emerging Players: Pursue neutral host infrastructure contracts in US commercial real estate where warehouse operators demand guaranteed coverage without managing carrier relationships directly. Target Indian smart city mandates for integrated small cell street furniture procurement. Lead with AI-driven radio resource management as differentiated value proposition.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-software convergence play because virtualized baseband migration compresses hardware replacement cycles into continuous software revenue streams. Acquisition targets cluster around cloud-native RAN software specialists with O-RAN Alliance certification progress. Watch for FCC mid-band auction release timing as carrier capital deployment inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Certification Investment | O-RAN Alliance protocol compliance unlocks multi-carrier procurement contracts previously captured by integrated vendors. |
| GaN Foundry Partnership | Captive gallium nitride power amplifier supply insulates margin structures from Taiwan and South Korean foundry pricing volatility. |
| Neutral Host Infrastructure Deployment | Third-party street furniture ownership captures multi-tenant revenue streams in Texas and Florida logistics corridors. |
| AI Radio Resource Integration | Machine learning inference at the edge enables dynamic spectrum allocation for Japanese industrial campus private networks. |
| Enterprise Private Network Verticalization | Deterministic latency specifications for German automotive AGV coordination command premium pricing above carrier-grade deployments. |
Methodological Framework
Initial hypotheses were tested against primary input from carrier network planning executives, open RAN systems integrators, RF component procurement leads, and municipal broadband program directors and refined through secondary validation against FCC equipment authorization databases, O-RAN Alliance specification releases, MIIT GB standard filings, and carrier capital expenditure disclosures. Bottom-up unit shipment estimates triangulated with top-down infrastructure spending analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product scale tier, mounting method, end-user archetype, and deployment architecture choice. CAGRs derived from carrier deployment timeline acceleration curves and open RAN adoption rate assumptions. Industry-specific forecast inputs encompassed spectrum auction release schedules and municipal permitting regime efficiency variations.
Sensitivities concentrate around O-RAN Alliance specification versioning delays, gallium nitride foundry capacity allocation shifts, and FCC equipment authorization backlog fluctuations. Forecasts reflect documented assumptions on carrier consolidation patterns and enterprise private network regulatory maturation. Material shifts in export control regime stringency or MIIT power budget enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Mesh Wifi System Market
Wireless Technologies
Europe Fixed Wireless Access (FWA) Market
Wireless Technologies
Prepaid Wireless Service Market
Wireless Technologies
Visible Light Communication (VLC) Market
Wireless Technologies
Wireless LAN Controller Market
Wireless Technologies
Wireless Antenna Market
Wireless Technologies
Wi-Fi Booster Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
Li-Fi Market
Wireless Technologies
Femtocell Market
Wireless Technologies
Global Wireless Health Market
Wireless Technologies
Fixed Wireless Access (5G/Wttx/LTE) Market
Wireless Technologies
Voice Over LTE (VOLTE) and Voice Over Wi-Fi Market
Wireless Technologies
Multefire Market
Wireless Technologies
Global Gi Fi Technology Market
Wireless Technologies
Telecom Wireless Data Market