
 Digital Onboarding Software Market | 2026-2036
Digital Onboarding Software Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Onboarding Software Market Insights
Banking and fintech verticals are expanding their share of digital onboarding software procurement as Know Your Customer mandates tighten globally. Userpilot leverages product-led growth tooling to anchor its position in self-service onboarding workflows for SaaS applications. Rocketlane specializes in project-based customer implementations, competing through structured milestone tracking that reduces time-to-value for enterprise deployments. Chameleon sustains technology leadership in embedded guidance layers, differentiating through no-code customization that lets product teams deploy contextual tutorials without engineering dependency.
Digital onboarding software encompasses platforms that automate user registration, identity verification, and feature activation through orchestrated workflows across web and mobile interfaces. These systems typically integrate document capture, biometric matching, and API connections to government or credit databases to validate identities while maintaining audit trails for compliance purposes. Cloud-based deployment models capture the dominant margin pool as enterprises prioritize elastic infrastructure and rapid provisioning over capital-intensive on-premises installations. Integrated solutions that bundle identity verification with CRM and core banking APIs represent the fastest-growing product type, while mobile apps face margin compression from commoditized app store distribution and fragmented device compatibility testing.
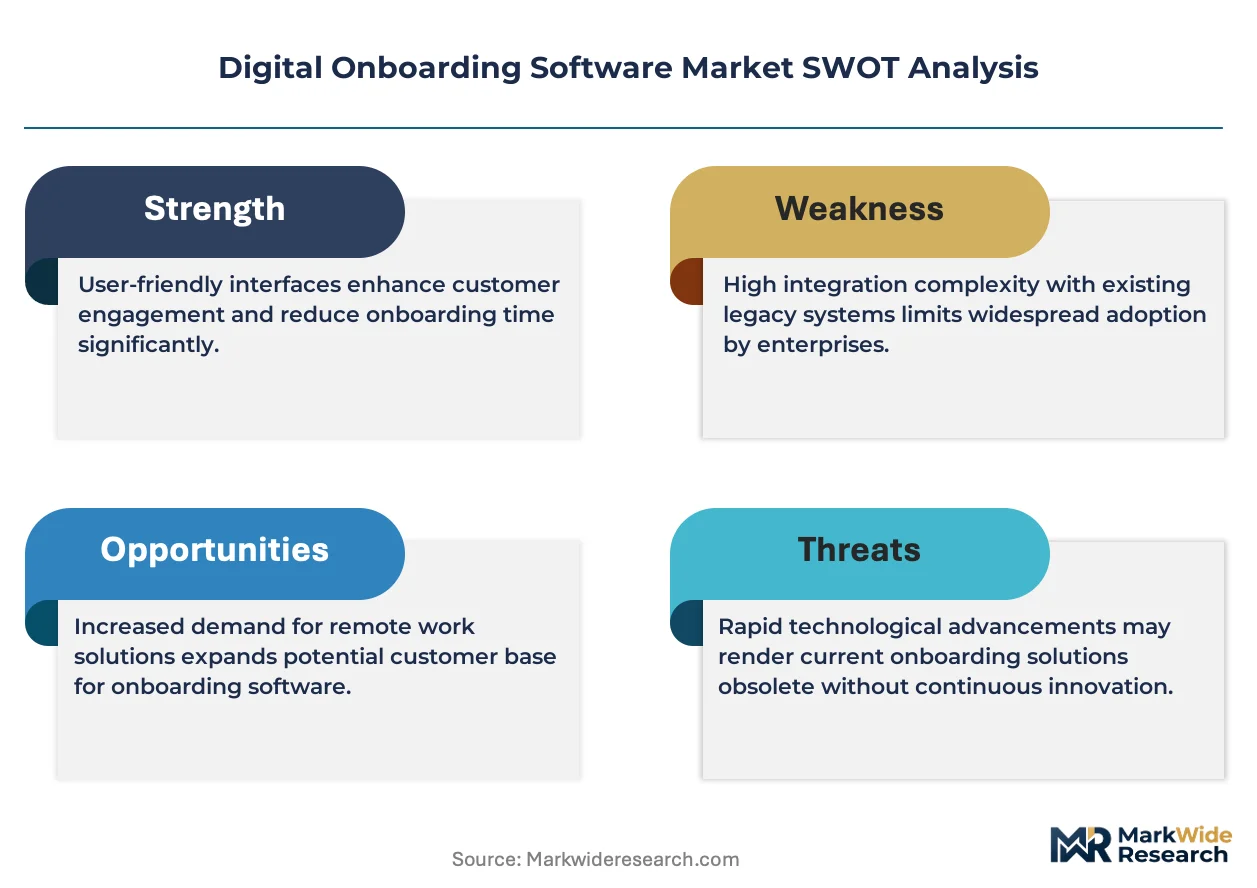
The US Federal Reserve's digital identity framework discussions and the EU's eIDAS 2.0 standards for electronic identification are reshaping product roadmaps, forcing vendors to architect cross-border interoperability into their verification stacks. GDPR and sector-specific banking regulations in Germany, France, and the United Kingdom impose strict data residency and consent management requirements that filter which platforms qualify for regulated financial services contracts. Stakeholders must monitor how decentralized identity protocols and government-issued digital wallets alter the competitive boundary between proprietary onboarding stacks and public infrastructure.
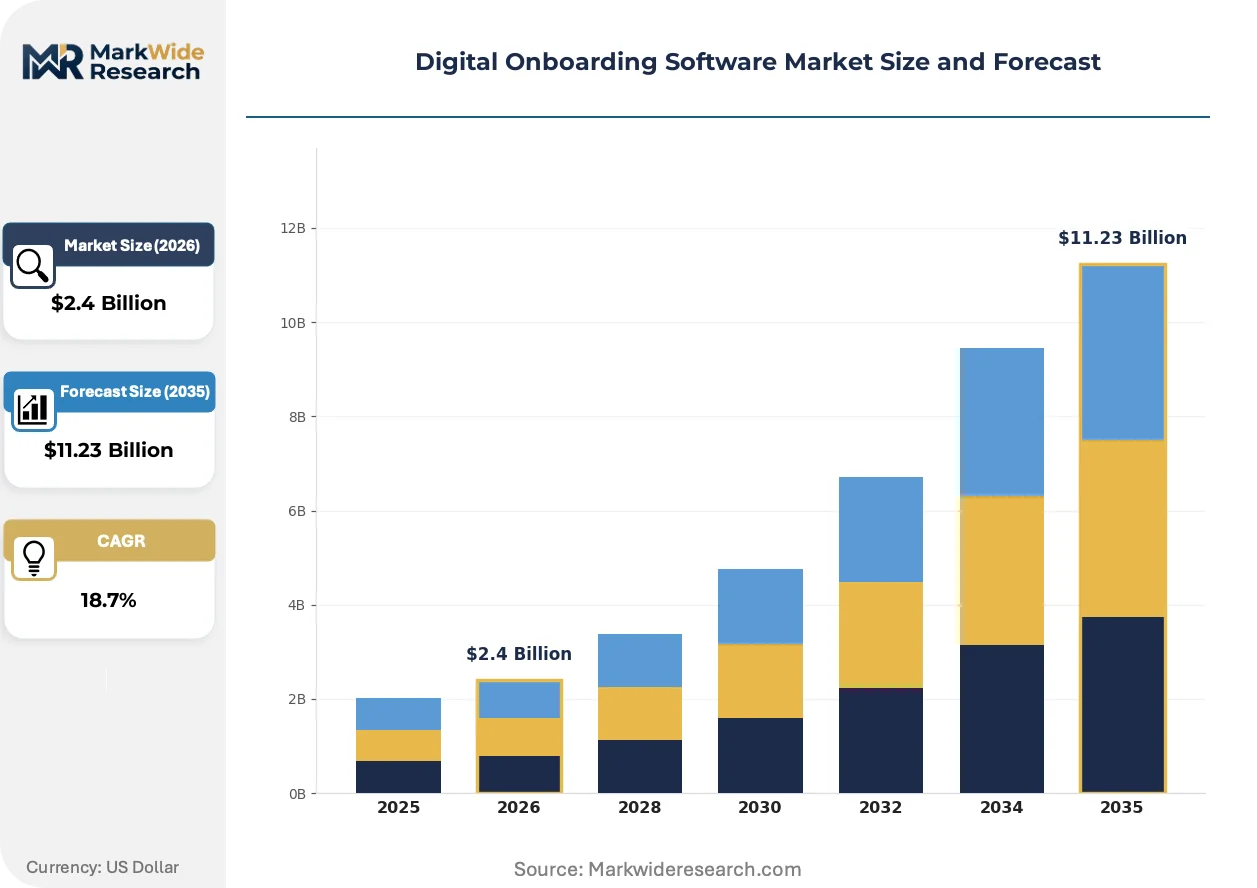
Market Dynamics
API-first architecture mandates from financial services procurement teams are compressing deployment timelines and forcing vendors to decouple monolithic platforms into interoperable microservices.
Growth Catalysts
- EU eIDAS 2.0:The European Union's electronic identification framework mandates cross-border wallet interoperability, forcing platform vendors to rebuild verification stacks for government-issued digital credentials.
- Biometric liveness detection:Deepfake-resistant facial recognition protocols are becoming standard in banking applications, reducing fraud exposure and accelerating customer approval workflows.
- Cloud infrastructure elasticity:Financial institutions in Singapore and the United Arab Emirates are prioritizing auto-scaling verification capacity during account-opening surges, eliminating on-premises provisioning delays.
Market Restraints
- Data residency compliance:Germany's Federal Financial Supervisory Authority enforces strict local processing requirements that fragment vendor operations across national boundaries.
- Document forgery sophistication:Synthetic identity fraud using AI-generated credentials is degrading confidence in automated verification pipelines, forcing manual review layer additions.
- Biometric template storage costs:Encrypted vault infrastructure for fingerprint and facial data requires specialized hardware security modules that inflate operational expenditure.
Strategic Opportunities
- Embedded finance penetration:Non-bank platforms in Brazil and Mexico require white-label onboarding modules, creating distribution partnerships with retail and telecom verticals.
- Decentralized identity convergence:Self-sovereign credential standards from the W3C are enabling passwordless verification flows that bypass traditional document upload friction.
- Small business banking:Underpenetrated merchant onboarding in India presents volume expansion as regional banks digitize sole proprietor account opening.
Industry Challenges
- Legacy core banking integration:COBOL-based transaction systems at established financial institutions resist real-time API connectivity, forcing expensive middleware development.
- Multi-jurisdiction compliance engineering:Product teams must maintain parallel code branches for GDPR, LGPD, and sector-specific banking regulations, fragmenting release velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Onboarding Software Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $11.23 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Web Platforms, APIs, Integrated Solutions End User: Financial Institutions, E-Commerce Platforms, Technology Firms, Service Providers Deployment Model: Cloud-based, On-premises, Hybrid, SaaS User Experience: Self-service, Guided Workflow, Interactive Tutorials, Multi-lingual Support |
| Companies Covered | Appcues, Guidecx, Dock, OnRamp, Rocketlane, Zite, Chameleon, Precursive, Userpilot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Onboarding Software Market Trends and Innovations
Passive behavioral biometrics are displacing active authentication steps, embedding continuous trust scoring into user sessions without explicit friction points.
Passive behavioral biometrics analyze keystroke dynamics, device tilt patterns, and navigation cadence to construct risk profiles without requiring users to perform explicit actions. Tier-one banks in the United Kingdom and Australia are deploying these invisible signals to reduce step-up authentication frequency by half. The technology is overtaking knowledge-based verification methods that rely on static security questions vulnerable to social engineering and data breaches.
The US Federal Reserve's digital identity framework discussions are pressuring vendors to architect portable credential verification that transcends institutional boundaries. This policy momentum is accelerating investment in interoperable wallet infrastructure that can validate government-issued credentials across state lines. Community banks and credit unions are most exposed, lacking internal engineering resources to rebuild compliance stacks independently.
Subscription-based pricing for verification API calls is displacing perpetual license models as fintechs prioritize variable cost structures aligned with customer acquisition volume. Mid-market SaaS platforms are negotiating consumption-tier contracts that bundle identity proofing with ongoing fraud monitoring. This shift is most visible in the United States, where venture-backed startups resist capital-intensive upfront commitments during fundraising cycles.
Digital Onboarding Software Market Segmentation
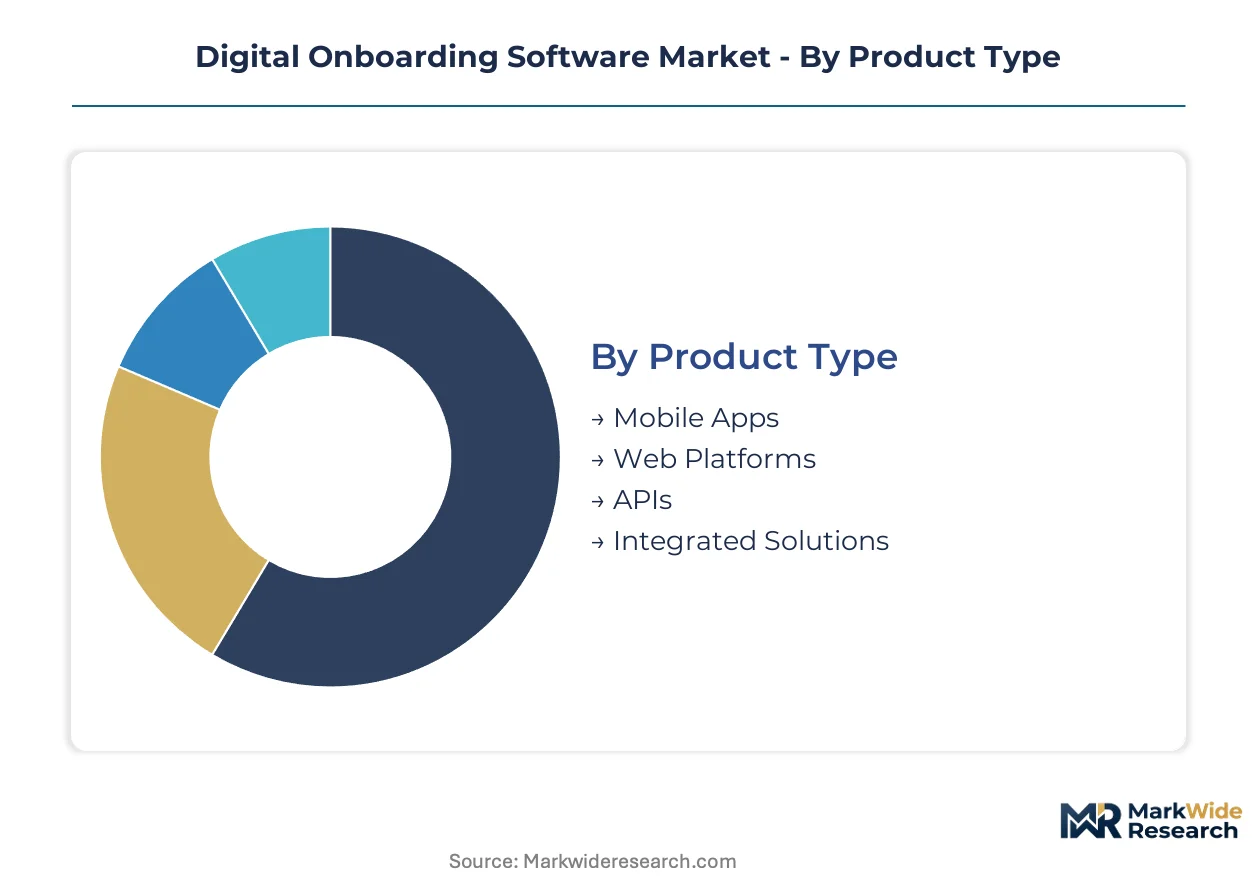
Digital onboarding software procurement varies sharply by technical architecture and operational context. Buyers prioritize deployment flexibility, identity verification depth, and integration complexity when selecting platforms. Segmentation reveals where vendor specialization creates sustainable margin pools versus commoditized competition.
Product Type:
Technical architecture determines integration burden and revenue durability for platform vendors.
- Integrated Solutions:Bundle identity verification, CRM connectivity, and core banking APIs into unified orchestration layers. Financial institutions in the United States and Singapore favor these configurations to compress deployment timelines and reduce middleware development costs.
- APIs:Deliver modular verification microservices that procurement teams compose into custom workflows. Fintechs prioritize consumption-based pricing for these interfaces to align costs with customer acquisition volume.
- Web Platforms:Browser-based onboarding portals with document capture and biometric matching capabilities.
- Mobile Apps:Native iOS and Android applications for account opening and identity validation.
Integrated Solutions lead volumes today; APIs are gaining share fastest.
End User:
Regulatory exposure and fraud loss rates shape procurement sophistication across buyer categories.
- Financial Institutions:Banks, credit unions, and insurers operating under Know Your Customer mandates. Tier-one institutions in the United Kingdom and Australia demand passive behavioral biometrics and liveness detection to reduce step-up authentication friction.
- E-Commerce Platforms:Online marketplaces requiring seller verification and payment onboarding. These buyers prioritize speed over depth, accepting higher fraud thresholds to minimize checkout abandonment.
- Technology Firms:SaaS providers embedding user registration into product-led growth funnels.
- Service Providers:Telecom and utility companies performing customer identity checks for subscription activation.
Financial Institutions dominate procurement spend; E-Commerce Platforms are expanding most quickly.
Deployment Model:
Infrastructure preferences reflect capital availability and compliance jurisdiction requirements.
- Cloud-based:Elastic verification capacity provisioned through hyperscaler infrastructure. Auto-scaling architectures eliminate provisioning delays during account-opening surges in Singapore and the United Arab Emirates.
- SaaS:Subscription access to multi-tenant platforms with shared compliance updates. Venture-backed startups in the United States negotiate consumption-tier contracts to preserve capital during fundraising cycles.
- Hybrid:Split processing between cloud orchestration and on-premises biometric template storage.
- On-premises:Dedicated hardware installations for strict data residency requirements.
Cloud-based deployments anchor current procurement; SaaS models show the steepest expansion trajectory.
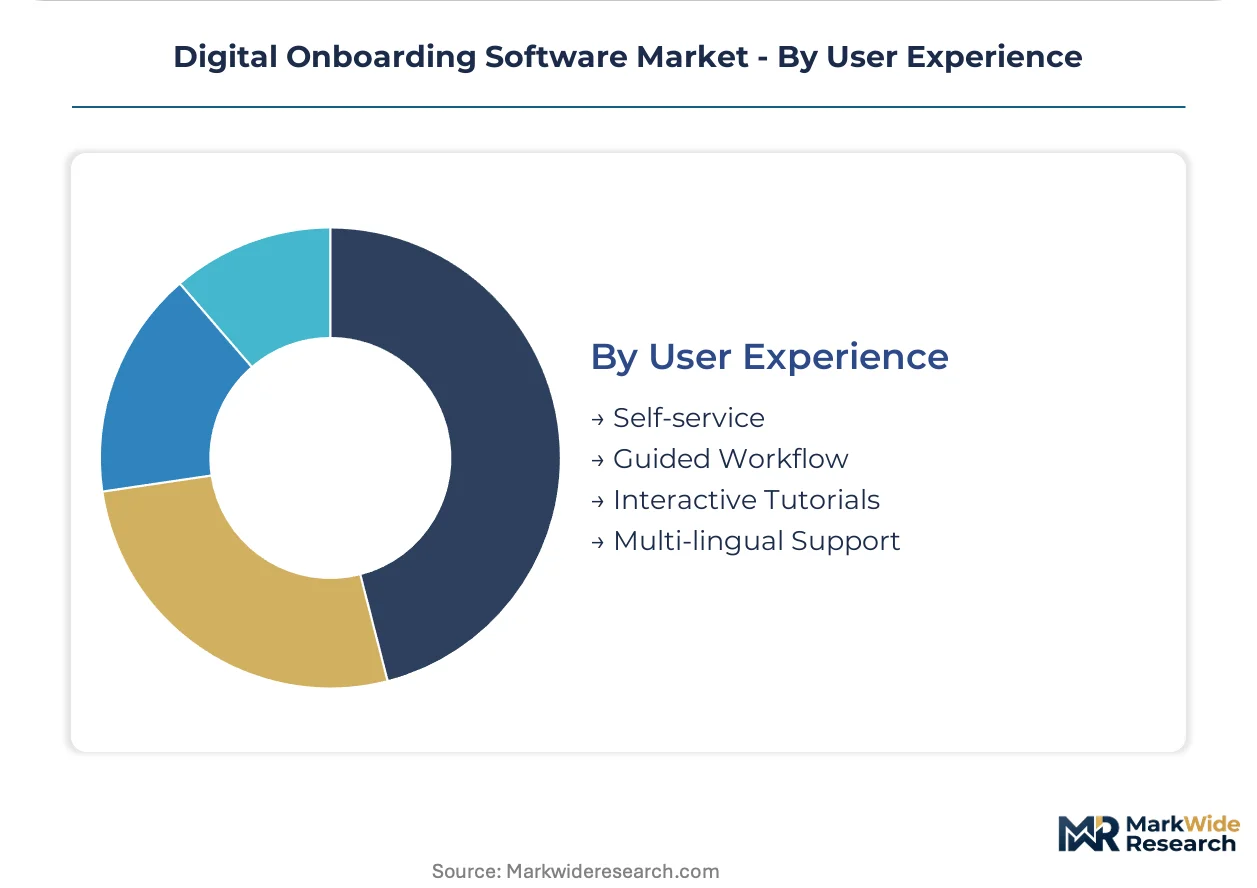
User Experience:
Friction reduction tactics separate conversion-optimized platforms from compliance-first configurations.
- Self-service:Unassisted user registration with automated document capture and real-time validation. SaaS applications deploy these flows to minimize sales touchpoints and accelerate product-led growth.
- Guided Workflow:Step-by-step interfaces with progress indicators and contextual help. These structures reduce abandonment in complex financial product onboarding where documentation requirements intimidate users.
- Interactive Tutorials:Embedded walkthroughs demonstrating feature activation during initial sessions.
- Multi-lingual Support:Localized interfaces accommodating regional language and document format variations.
Self-service interfaces command the largest installed base; Guided Workflow adoption is climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping vendor operations as compliance-cost differentials between jurisdictions drive platform architecture decisions and data center placement strategies.
United States
The Federal Reserve's digital identity framework discussions and SEC disclosure requirements are accelerating enterprise SaaS procurement cycles. Tier-one banks in New York and San Francisco demand passive behavioral biometrics and liveness detection to compress step-up authentication friction. Silicon Valley clusters anchor venture-backed fintech onboarding innovation, while Chicago's legacy banking infrastructure resists real-time API connectivity.
Germany
BaFin's strict data residency mandates fragment vendor operations across national boundaries, inflating operational expenditure for encrypted biometric template storage. The country's Federal Financial Supervisory Authority enforces local processing requirements that disqualify multi-tenant cloud architectures lacking dedicated German infrastructure. Frankfurt's financial services concentration drives demand for hybrid deployment models splitting orchestration between cloud and on-premises vaults.
United Kingdom
FCA consumer duty rules and Open Banking API mandates are reshaping procurement criteria for tier-one institutions. London's fintech density creates concentrated demand for consumption-tier verification contracts aligned with variable customer acquisition volumes. The Financial Conduct Authority's regulatory sandbox has incubated multiple onboarding platforms now expanding into Commonwealth markets.
Singapore
Monetary Authority of Singapore guidelines for digital banking licenses are compressing deployment timelines for cloud-native verification stacks. The city-state's position as ASEAN financial hub creates surge-capacity requirements during cross-border account-opening peaks. Local procurement teams prioritize auto-scaling architectures that eliminate provisioning delays during volume spikes.
Brazil
Central Bank of Brazil Pix instant payment integration and LGPD consent management requirements are creating white-label onboarding demand from retail and telecom verticals. São Paulo's embedded finance ecosystem drives partnership models for non-bank platforms requiring modular verification microservices. The country's synthetic identity fraud exposure is degrading confidence in fully automated pipelines.
Digital Onboarding Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with API-first vendors capturing fintech procurement while integrated suite providers dominate tier-one banking mandates. The vendor base organizes into three strategic tiers: product-led growth tooling specialists, project-based implementation platforms, and embedded guidance layer providers. Consolidation pressure is intensifying as procurement teams mandate microservice interoperability, forcing M&A activity around API connectivity assets and geographic expansion into underpenetrated Latin American and Indian markets.
Among product-led growth specialists, Userpilot and Chameleon exemplify contrasting archetypes within the self-service onboarding workflow segment. Userpilot anchors the product analytics-integrated tier, while Chameleon occupies the no-code customization position that reduces engineering dependency for deployment teams. Rocketlane represents the project-based implementation vector, with structured milestone tracking capabilities that compress enterprise deployment timelines. These three companies collectively illustrate how vendor specialization around friction-reduction tactics creates defensible positioning against horizontal platform competition.
| Leading Market Players |
|---|
| Appcues |
| Guidecx |
| Dock |
| OnRamp |
| Rocketlane |
| Zite |
| Chameleon |
| Precursive |
| Userpilot |
| Others |
Pricing and Supply Chain Analysis
API-first architecture migration simultaneously compresses vendor cost structures and concentrates procurement leverage among hyperscale cloud infrastructure providers in the United States and Singapore. Subscription-based consumption models for verification API calls now dominate procurement, displacing perpetual licensing and forcing vendors to align pricing with variable customer acquisition volumes rather than fixed enterprise commitments.
Pricing Analysis
Direct-to-OEM channels handle hyperscale financial institution demand with volume-tiered discounts that compress margins for standardized verification microservices. Pricing stratifies across premium, standard, and economy tiers based on biometric liveness detection sophistication and data residency certification levels. Cost compression in the standard tier is intensifying because fintech startups negotiate consumption-based contracts during fundraising cycles. SaaS platforms exhibit highest price sensitivity, while tier-one banks prioritize compliance depth over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through cloud orchestration partnerships with infrastructure providers in the United States, Ireland, and Singapore. Encrypted biometric template storage draws from specialized hardware security module manufacturers and hyperscaler compute capacity. Single-source vulnerability in liveness detection algorithm licensing creates concentration risk for vendors dependent on proprietary facial recognition IP. Distribution runs through API marketplaces and direct enterprise sales teams with embedded technical integration support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement teams prioritize deepfake-resistant biometric stacks over commodity document capture solutions. Financial institutions now mandate liveness detection and passive behavioral analytics as baseline requirements, filtering out undifferentiated vendors.
For Market Incumbents: Anticipate margin compression from open-source decentralized identity protocols by deepening vertical integration into biometric hardware security module production. Acquire API connectivity specialists in Brazil and India to defend position against regional challengers. Prioritize certification investment for EU eIDAS 2.0 wallet interoperability before compliance deadlines tighten procurement qualification. For New Entrants and Emerging Players: Enter via white-label onboarding modules for embedded finance platforms in Mexico and Southeast Asia, where regulatory arbitrage creates temporary procurement windows. Target small business banking digitization in India as the most penetrable segment, leveraging lightweight SaaS deployment to bypass legacy core banking integration costs. Pursue partnership-first go-to-market angles with telecom and retail verticals seeking non-bank financial service expansion. For Investors and Strategic Acquirers: Valuations sit cheapest among API-first verification specialists with proven hyperscaler marketplace distribution. Long-term viability hinges on cross-border interoperability architecture that transcends single-jurisdiction regulatory shifts. Target acquisition profile centers on vendors with W3C decentralized identity protocol integration and established Monetary Authority of Singapore or BaFin compliance credentials. Watch biometric template storage cost curves as the signal to monitor for operational leverage inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first orchestration layers reduce middleware development costs for tier-one banks in London and Singapore. |
| Geographic Expansion | Latin American embedded finance penetration creates white-label distribution partnerships with retail and telecom verticals. |
| Acquisition of Specialist Firm | Biometric liveness detection specialists command premium positioning as deepfake-resistant protocols become standard. |
| Strategic Partnership | Hyperscaler marketplace listings accelerate procurement cycles for consumption-based verification API contracts. |
| Product Launch | Passive behavioral biometrics deployment reduces step-up authentication friction for FCA-regulated UK institutions. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with CTOs, IT procurement officers, platform engineers, and integration specialists alongside secondary validation. Primary fieldwork draws from SEC filings, hyperscaler capex disclosures, App Annie mobile SDK data, and central bank digital licensing announcements. Bottom-up segment sizing triangulates against top-down regulatory mandate impact assessments across the analysis window.
Rate-of-change decomposition separates volume effects from value migration across deployment model, organization size, vertical specialization, integration complexity, and regional adoption pattern dimensions. CAGRs derive from elasticity modeling of verification API call volumes against customer acquisition cycle timing in venture-backed fintech segments. Industry-specific forecast inputs include EU eIDAS 2.0 implementation trajectory and biometric template storage hardware cost curves.
Inputs from central bank licensing databases and hyperscaler partnership announcements were available through the study window; gaps in private fintech customer acquisition metrics introduce uncertainty bands around consumption-based pricing adoption velocity. Forecasts reflect assumptions regarding regulatory timeline adherence and cloud infrastructure elasticity deployment rates. Periodic stress-testing of base assumptions is recommended given synthetic identity fraud sophistication and potential decentralized identity protocol disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Agent-Oriented Enterprise Architecture Market
Digital Solutions
System Integrator Market
Digital Solutions
Enterprise Search Market
Digital Solutions
Turkey ICT Market
Digital Solutions
Data Labeling Solution and Services Market
Digital Solutions
Computerized Maintenance Management System Market
Digital Solutions
Computer Aided Design (CAD) Market
Digital Solutions
Managed File Transfer (MFT) Market
Digital Solutions
Hardware Engineering and Design Services Market
Digital Solutions
North America Digital Signage Market
Digital Solutions
Data As a Service (Daas) Market
Digital Solutions
Digital Metronome Market
Digital Solutions
ICT Investment in Government Market
Digital Solutions
Enterprise Asset Management (EAM) Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Construction Design App Market