
 Europe IT Asset Disposition Market | 2026-2036
Europe IT Asset Disposition Market Size, Share, and Industry Trends Forecast 2026-2036
Europe IT Asset Disposition Market Foresight
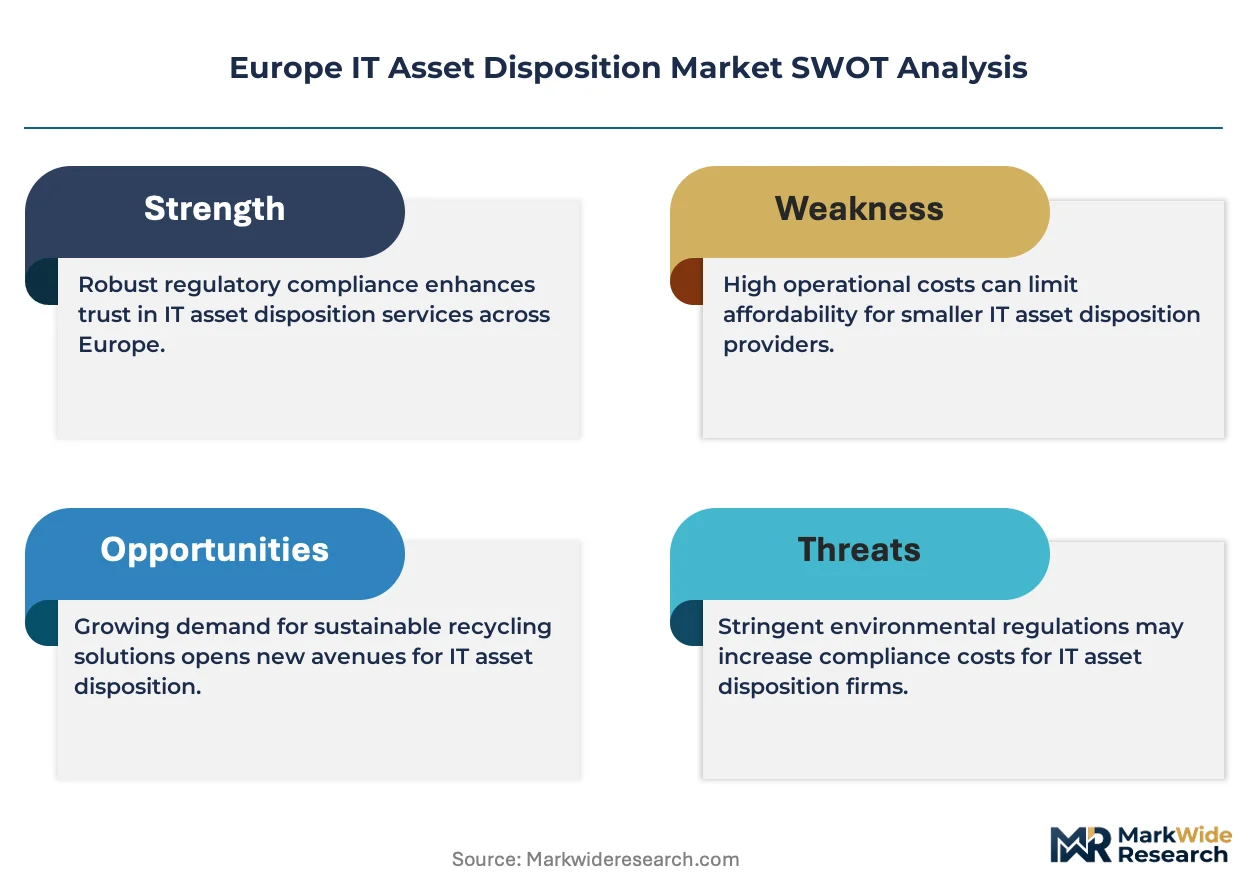
The EU Green Deal is hardening electronics recovery mandates across member states, forcing enterprises to document chain-of-custody for retired servers, laptops, and networking gear. Dell Technologies Asset Recovery leverages its OEM relationships to secure enterprise decommissioning contracts at scale. Sims Lifecycle Services anchors its European footprint through certified recycling facilities in the Netherlands and Germany. Foxway competes on hardware remarketing velocity, turning corporate refresh cycles into secondary revenue streams for clients.
Europe IT Asset Disposition encompasses the secure retirement, data sanitization, refurbishment, and material recovery of enterprise information technology equipment, with NIST 800-88 and ADISA certification protocols governing data wiping integrity and audit trail documentation. The primary commercial purpose centers on risk mitigation for data-bearing assets while extracting residual value through resale or precious metal reclamation. Data Destruction services command premium pricing due to GDPR liability exposure and the legal requirement for demonstrable evidence of irreversible data elimination. Hardware Remarketing generates margin pools by extending device lifecycles for corporate and educational buyers seeking TCO reduction. Certified Recycling absorbs volume from aging infrastructure in public sector organizations where WEEE compliance deadlines drive scheduled replacement programs.
REACH restricts hazardous substance thresholds in recovered components, while the EU AI Act introduces emerging documentation requirements for AI-enabled hardware decommissioning. The WEEE Directive sets collection and recovery targets that national regulators in Germany, France, and Italy enforce through producer responsibility organizations. ECHA substance restrictions shape downstream recycling economics by limiting certain flame retardant recovery pathways. Stakeholders must monitor evolving CSRD disclosure rules that will mandate granular reporting on IT asset circularity metrics and carbon avoidance claims.
Market Dynamics
EU Green Deal mandates are compressing enterprise refresh cycles while forcing documented chain-of-custody protocols for every decommissioned asset across member states.
Growth Catalysts
- GDPR enforcement:Financial institutions in Germany and France now mandate certified data destruction with audit trails, creating recurring revenue pools for compliant service providers.
- WEEE Directive targets:National regulators in Italy and Spain enforce producer responsibility obligations that accelerate scheduled IT replacement in public sector organizations.
- AI-enabled hardware:Server refresh cycles are shortening as enterprises deploy GPU-intensive infrastructure, generating volume for decommissioning specialists.
Market Restraints
- Logistics cost volatility:Cross-border transport of hazardous e-waste components faces fluctuating fuel surcharges and carbon border adjustment fees.
- Smelter concentration:Precious metal recovery depends on a narrow base of European refiners in Belgium and Germany, creating bottleneck risk.
- REACH substance restrictions:Flame retardant recovery pathways face narrowing economic viability as ECHA tightens hazardous substance thresholds.
Strategic Opportunities
- Poland and Czechia:Manufacturing-driven IT asset generation in these economies remains underpenetrated by certified disposition providers.
- CSRD disclosure rules:Mandatory granular reporting on IT asset circularity metrics will drive demand for verified carbon avoidance documentation.
- Blockchain-IoT convergence:Immutable chain-of-custody records are attracting enterprise buyers seeking tamper-proof audit trails for regulatory defense.
Industry Challenges
- ADISA certification timelines:Auditor capacity constraints are extending certification queues for new market entrants.
- Legacy ERP integration:Asset tracking systems must interface with decades-old procurement databases in established European banks.
- Specialized technician scarcity:NIST 800-88 certified data sanitization engineers command premium wages amid limited training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe IT Asset Disposition Market |
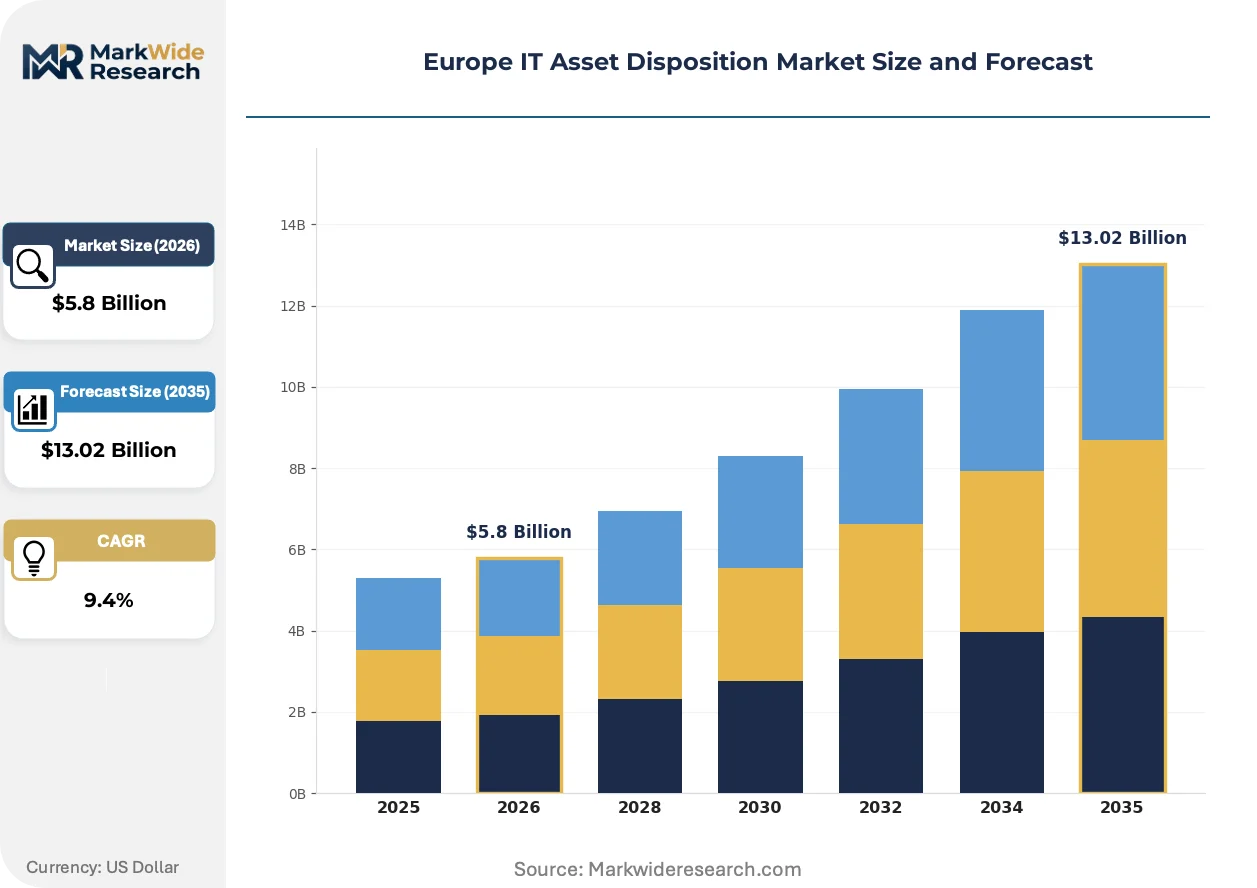
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.02 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Destruction, Hardware Remarketing, Recycling, Logistics, IT Asset Recovery Technology: Data Wiping, Physical Destruction, Degaussing, Certified Recycling, Secure Transportation End User: Corporate Enterprises, Public Sector Organizations, Financial Institutions, Educational Institutes, Non-Profit Organizations Distribution Channel: Direct Sales, Online Platforms, Third-Party Vendors, Value-Added Resellers, Managed Service Providers |
| Companies Covered | Iron Mountain, Dell Technologies Asset Recovery, Flex IT, Hewlett Packard Enterprise Asset Upcycling, IBM Global Asset Recovery Services, Liquid Technology, Foxway, Sims Lifecycle Services, TecDis, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe IT Asset Disposition Market Shifts & Advancements
Automation is penetrating data sanitization workflows while regulatory documentation requirements harden across the European regulatory perimeter.
Automated data destruction verification systems are expanding into enterprise decommissioning contracts. Large German banks and Dutch insurers now require cryptographic proof of erasure rather than manual certificate collection. This technology is compressing service delivery timelines while elevating compliance defensibility against GDPR audit scrutiny.
CSRD disclosure mandates are reshaping procurement specifications for ITAD services. Large enterprises must now report Scope 3 emissions from retired equipment, forcing vendors to provide granular carbon avoidance calculations. French and Italian public sector tenders increasingly weight circularity metrics above unit pricing.
Hardware-as-a-service adoption is altering residual value capture models. Corporate buyers in the Netherlands and Scandinavia now expect ITAD providers to manage reverse logistics within subscription contracts rather than transactional arrangements. This shift concentrates volume with vendors possessing integrated refurbishment capabilities.
Europe IT Asset Disposition Market Segmentation
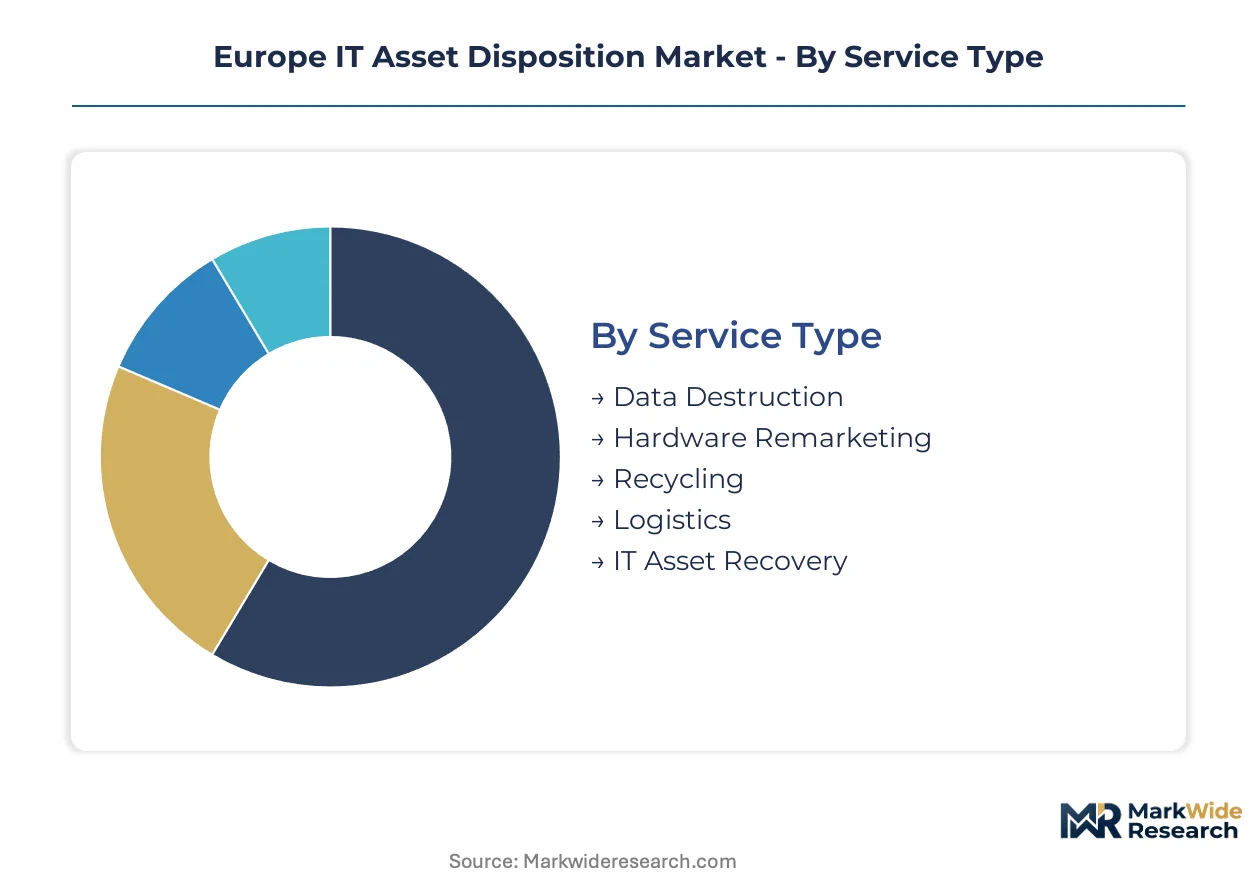
Europe IT Asset Disposition service providers structure offerings around data security liability, residual value recovery, and regulatory compliance intensity. Segment boundaries blur as integrated vendors bundle destruction, remarketing, and certified recycling under unified contracts.
Service Type:
Data Destruction commands premium pricing while Hardware Remarketing drives volume scale across enterprise portfolios.
- Data Destruction:NIST 800-88 and ADISA-certified sanitization protocols eliminate recoverable data from storage media through cryptographic erasure or physical shredding. German banks and French insurers mandate audit-trail documentation for every destroyed asset to defend against GDPR penalties.
- Hardware Remarketing:Functional refurbishment and resale of servers, laptops, and networking equipment to secondary markets. Dutch corporate buyers and Scandinavian educational institutes prioritize total cost of ownership reduction through certified pre-owned hardware procurement.
- Recycling:Material recovery from non-functional electronics under WEEE Directive compliance frameworks. Precious metal reclamation concentrates at Belgian and German smelters with REACH substance restrictions narrowing viable processing pathways.
- Logistics:Secure chain-of-custody transport of decommissioned assets from enterprise data centers to processing facilities. Cross-border e-waste movements face carbon border adjustment fees and hazardous material licensing requirements.
- IT Asset Recovery:Comprehensive programs combining inventory valuation, data sanitization, and disposition channel optimization. Large French public sector tenders increasingly specify integrated recovery services over point solutions.
Today's leader: Data Destruction. Tomorrow's challenger: Hardware Remarketing.
Technology:
Physical destruction methods dominate high-security environments while software-based wiping expands in cost-sensitive segments.
- Data Wiping:Overwrite algorithms rendering stored information irretrievable without hardware damage. Automated verification systems now generate cryptographic proof of erasure for Dutch insurers and German financial institutions defending GDPR audits.
- Physical Destruction:Shredding, crushing, or disintegration of storage media to eliminate any data recovery possibility. Central banks and defense contractors across France, Italy, and Spain mandate physical destruction for classified or sensitive infrastructure retirement.
- Degaussing:Magnetic field neutralization of hard disk drives and tape storage. Legacy media formats in established European banking infrastructure still require degaussing before final disposition.
- Certified Recycling:Downstream processing with documented material recovery rates and hazardous substance handling. ECHA restrictions on flame retardant recovery are compressing margins at Netherlands and Germany processing facilities.
- Secure Transportation:GPS-tracked, sealed-container logistics with tamper-evident protocols. Blockchain-IoT convergence is attracting enterprise buyers seeking immutable chain-of-custody records for regulatory defense.
Physical destruction anchors high-assurance contracts. Data wiping is climbing the fastest as automation compresses service delivery timelines.
End User:
Financial institutions pay compliance premiums while public sector organizations drive scheduled replacement volume.
- Corporate Enterprises:Technology, telecommunications, and manufacturing sectors with scheduled refresh cycles generating predictable decommissioning volume. CSRD disclosure mandates are forcing granular Scope 3 emissions reporting on retired equipment.
- Public Sector Organizations:Government agencies and healthcare systems with WEEE Directive-driven replacement schedules. Italian and Spanish regulators enforce producer responsibility obligations that accelerate IT asset turnover.
- Financial Institutions:Banks, insurers, and payment processors with stringent data security requirements. GDPR enforcement in Germany and France has institutionalized certified destruction with audit trails as standard procurement specifications.
- Educational Institutes:Universities and technical colleges seeking TCO reduction through refurbished hardware. Dutch and Scandinavian institutions increasingly procure through hardware-as-a-service models with embedded ITAD obligations.
- Non-Profit Organizations:Charities and NGOs with limited IT budgets and basic data protection needs. Donation pathways for functional equipment face tightening GDPR documentation requirements.
Financial Institutions dominate premium pricing. Corporate Enterprises represent the deepest volume pool.
Distribution Channel:
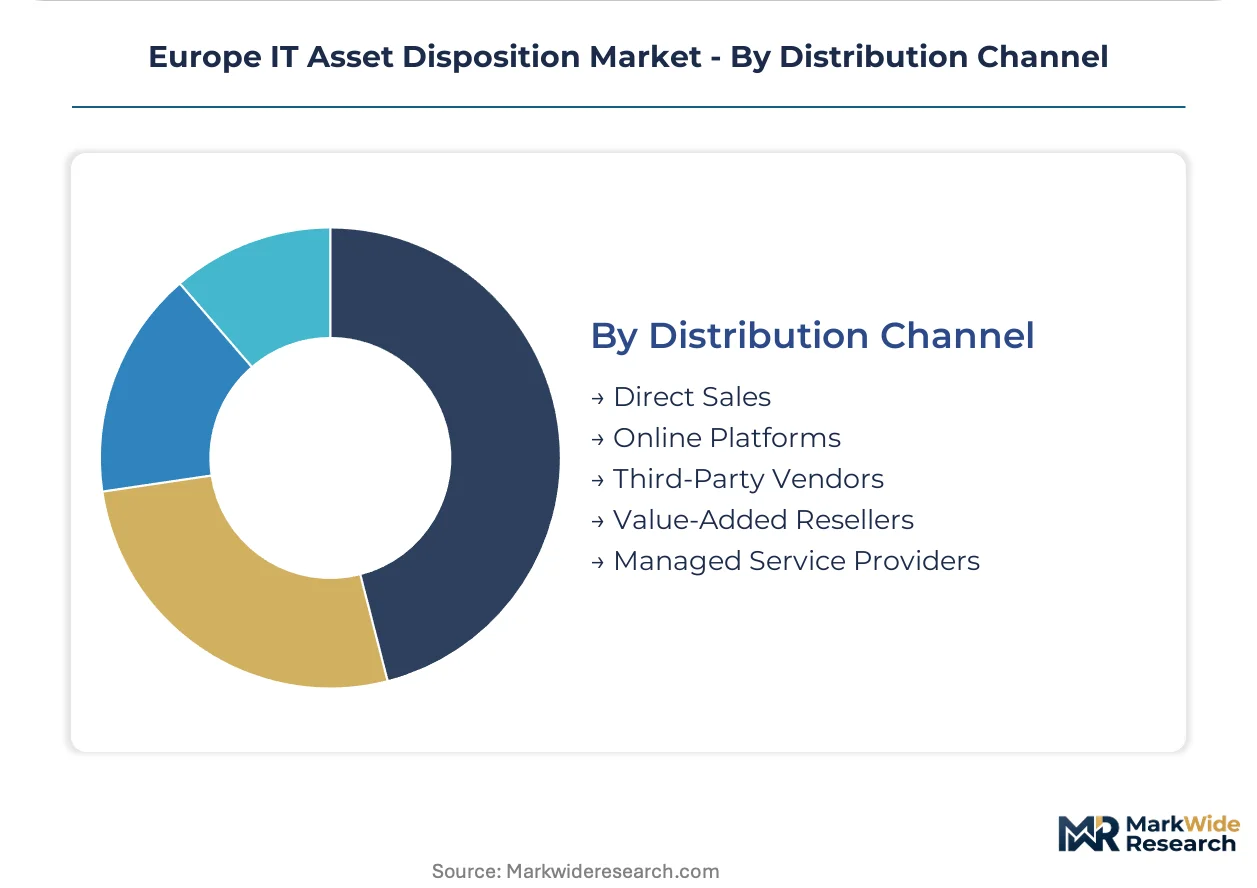
Direct sales capture enterprise accounts while managed service providers consolidate mid-market access.
- Direct Sales:Vendor relationships with large enterprises and public sector procurement frameworks. Dell Technologies and similar OEMs leverage hardware refresh cycles to secure integrated decommissioning contracts at scale.
- Online Platforms:Digital marketplaces for standardized services and transparent pricing. Small and medium enterprises in Poland and Czechia increasingly initiate ITAD procurement through platform-based discovery.
- Third-Party Vendors:Independent specialists competing on service flexibility and geographic coverage. Certification backlogs at ADISA auditors are extending market entry timelines for new entrants.
- Value-Added Resellers:IT infrastructure providers bundling disposition with hardware sales and maintenance. Hardware-as-a-service adoption in the Netherlands is concentrating volume with resellers possessing integrated refurbishment capabilities.
- Managed Service Providers:Outsourced IT operations including end-of-life asset management. French and Italian public sector tenders increasingly weight circularity metrics above unit pricing in MSP selection criteria.
Direct Sales commands the largest contract value. Managed Service Providers are gaining share fastest through subscription bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IT asset disposition services first scaled in Northern Europe through early WEEE Directive implementation and dense banking infrastructure. Germany and the Netherlands established certification protocols that spread across the continent. Today, regulatory enforcement and circular economy roadmaps drive service demand concentration.
Germany
Financial institutions in Frankfurt and Munich mandate ADISA-certified data destruction with full audit trails under BSI and KBA oversight. The national circular economy roadmap accelerates scheduled IT replacement in public sector organizations. North Rhine-Westphalia hosts the densest cluster of certified processing facilities serving cross-border enterprise contracts.
France
Paris-based banks and insurers now require cryptographic proof of erasure for GDPR defense, creating premium service tiers. ANSM and CNIL enforcement hardens documentation requirements for healthcare and financial data-bearing assets. The Île-de-France region concentrates demand through centralized procurement frameworks for public sector IT refresh cycles.
Netherlands
Hardware-as-a-service adoption in Amsterdam and Rotterdam shifts ITAD obligations into subscription contracts rather than transactional arrangements. The Dutch national circular economy program enforces WEEE recovery targets through producer responsibility organizations. Eindhoven's technology corridor generates substantial enterprise decommissioning volume from semiconductor and equipment manufacturers.
Italy
Rome and Milan regulators enforce producer responsibility obligations that accelerate scheduled replacement in government agencies. The national recovery and resilience plan channels funding toward public sector digital infrastructure renewal. Northern industrial clusters in Lombardy and Piedmont drive manufacturing-sector IT asset generation requiring certified disposition.
Poland
Manufacturing-driven IT asset generation in Warsaw and Kraków remains underpenetrated by certified disposition providers relative to Western Europe. EU cohesion funds support public sector digitalization programs with embedded end-of-life management requirements. The Silesian industrial basin generates rising volumes of enterprise equipment from automotive and machinery producers.
Europe IT Asset Disposition Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and audit-trail sophistication. The vendor base stratifies into three tiers: OEM-affiliated providers leveraging hardware refresh relationships, independent specialists competing on geographic coverage flexibility, and integrated platform operators bundling logistics with refurbishment. Consolidation pressure intensifies as ADISA certification backlogs extend market entry timelines for new entrants. Dominant competitive moves include strategic partnerships with financial institutions and backward integration into precious metal recovery.
Within the OEM-affiliated tier, Dell Technologies Asset Recovery and Hewlett Packard Enterprise Asset Upcycling exemplify players leveraging hardware relationships to secure integrated decommissioning contracts. Sims Lifecycle Services anchors the independent specialist position through Netherlands and Germany processing infrastructure. Foxway occupies a distinct position on hardware remarketing velocity, turning corporate refresh cycles into secondary revenue streams.
| Leading Market Players |
|---|
| Iron Mountain |
| Dell Technologies Asset Recovery |
| Flex IT |
| Hewlett Packard Enterprise Asset Upcycling |
| IBM Global Asset Recovery Services |
| Liquid Technology |
| Foxway |
| Sims Lifecycle Services |
| TecDis |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists now control the largest independent processing networks across the Netherlands and Germany, compressing margins for family-owned mid-caps while enforcing volume-based pricing discipline on enterprise contracts. This ownership concentration tightens supply-side coordination and amplifies pricing power at the top tier.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates enterprise procurement, with ADISA certification grade and audit-trail sophistication driving differentiation. Premium tiers command substantial uplifts from Frankfurt banks demanding cryptographic erasure proof, while economy tiers serve Polish manufacturers with basic WEEE compliance. Cost compression in standard-tier logistics is intensifying because carbon border adjustment fees and fuel volatility squeeze cross-border transport margins. Public sector organizations in Italy and Spain exhibit highest price sensitivity, whereas German financial institutions prioritize compliance defensibility over unit cost.
Supply Chain Analysis
Reverse-logistics flows for corporate refresh cycles concentrate processing capacity in the Netherlands, Germany, and Belgium, where certified facilities cluster near North Sea ports. Precious metal recovery draws from Belgian and German smelters with limited alternative refining pathways. Single-source vulnerability sits at the smelter tier, where REACH substance restrictions on flame retardant recovery narrow viable downstream processing. Distribution runs through direct enterprise contracts with OEM-affiliated providers, supplemented by managed service provider bundling in the Dutch hardware-as-a-service segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Western European certification premiums and Central European manufacturing volumes, with Poland and Czechia offering 30-40% cost advantages on logistics and labor against Dutch and German baselines.
For Market Incumbents: Deploy ADISA certification depth as a competitive moat against emerging platform-based entrants. Acquire distressed mid-cap processors in North Rhine-Westphalia to consolidate regional capacity. Deepen backward integration into precious metal recovery to capture margins currently flowing to Belgian smelters.
For New Entrants and Emerging Players: Begin with hardware remarketing velocity as the wedge into Polish manufacturing corridors, where certified disposition penetration lags Western Europe by several years. Target Warsaw and Kraków automotive clusters with rapid-turn refurbishment programs. Build initial credibility through online platform visibility before scaling to direct enterprise sales.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent specialists lacking integrated refurbishment capabilities, as hardware-as-a-service bundling concentrates volume with full-stack providers. The 5-10 year viability window favors assets with established ADISA certification and cross-border logistics permits. Monitor CSRD disclosure adoption rates as the inflection signal for carbon avoidance documentation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| ADISA Certification Investment | Unlocks premium-tier contracts with Frankfurt and Munich financial institutions under BSI oversight. |
| Blockchain-IoT Chain-of-Custody Deployment | Generates tamper-proof audit trails that Dutch insurers now mandate for GDPR defense. |
| Poland Processing Facility Establishment | Captures manufacturing-driven IT asset generation in underpenetrated Central European markets. |
| Precious Metal Recovery Integration | Reduces dependency on Belgian and German smelter bottlenecks for margin capture. |
| Hardware-as-a-Service Partnership | Locks in recurring volume from Dutch and Scandinavian corporate subscription transitions. |
Research Methodology
Coverage spans Western Europe and Central Europe, with primary inputs from each region triangulated against secondary validation. Primary interviews engaged ITAD operations directors, enterprise procurement officers at German banks, ESG compliance leads, ADISA auditors, and logistics coordinators at Netherlands processing facilities. Secondary sources included WEEE Directive implementation reports, ECHA substance restriction databases, CSRD draft standards, and producer responsibility organization filings. Bottom-up service volume estimates were cross-checked against top-down enterprise IT spend projections.
Rate-of-change decomposition anchored the analytical framework across the analysis window, with growth drivers modeled separately from replacement cycle compression and regulatory enforcement intensity. Segmentation dimensions included service type, technology method, end-user industry, and geographic regulatory cluster. CAGRs were derived from fitted trend extrapolation validated against historical WEEE collection trajectories and banking IT refresh patterns. GPU-intensive server refresh cycles and CSRD disclosure timelines served as industry-specific demand inputs.
Several conditions sit outside the modeled scope, including potential REACH amendments on additional flame retardant classes and unilateral national deviations from EU-wide e-waste targets. Forecasts reflect assumptions about continued GDPR enforcement intensity and ADISA auditor capacity expansion. Practitioners should monitor carbon border adjustment mechanism scope expansion and AI hardware decommissioning documentation requirements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Notepad Market
Digital Solutions
Digital Evidence Management System Market
Digital Solutions
Global Asset Tracking Software Market
Digital Solutions
Community Engagement Software Market
Digital Solutions
North America Digital Pen Market
Digital Solutions
Global E-Signature Platform Market
Digital Solutions
Global Handwriting Digital Pen Market
Digital Solutions
Fuel Management Software Market
Digital Solutions
US Digital Twin Market
Digital Solutions
NFT Creation Software Market
Digital Solutions
Global B2B Buyer Intent Data Tools Market
Digital Solutions
Mexico Online Gambling Market
Digital Solutions
Switzerland ICT Market
Digital Solutions
Cloud Monetization Market
Digital Solutions
Digital Marketing Software Market
Digital Solutions
Global Content Recommendation Engine Market