
 Healthcare Computerized Maintenance Management System Market | 2026-2036
Healthcare Computerized Maintenance Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Computerized Maintenance Management System Market Analytics
Aftermarket service revenue from legacy on-premises installations is narrowing as subscription-based cloud platforms capture recurring margin pools. Accruent sustains a dominant position in North American hospital networks through deep integration with existing facility management ecosystems. IBM leverages its Watson IoT infrastructure to differentiate on predictive analytics capabilities for medical asset uptime.
A Healthcare Computerized Maintenance Management System is a software platform that schedules, tracks, and analyzes maintenance activities for medical equipment and facility infrastructure, typically incorporating work order routing, spare parts inventory, and regulatory audit trails to ensure continuous clinical operations and compliance documentation. Cloud-based deployment leads among new implementations due to lower capital requirements and faster rollout cycles, while on-premises solutions retain share in institutions with strict data sovereignty requirements. IoT Integration represents the fastest-expanding technology segment as connected sensors on imaging and diagnostic equipment enable real-time condition monitoring and automated failure alerting.
FDA quality system regulations and Joint Commission accreditation standards shape product design by mandating audit trails, corrective action documentation, and preventive maintenance scheduling for critical medical devices. HIPAA security rules further constrain cloud architecture choices, requiring encrypted transmission, access logging, and business associate agreements for any vendor handling protected health information. Stakeholders must weigh interoperability commitments against the risk of vendor lock-in as health systems consolidate maintenance data across multi-site networks.
Market Dynamics
Hospital networks are consolidating maintenance operations onto unified platforms, driven by FDA cybersecurity mandates for medical device servicing and the operational imperative to reduce clinical downtime across distributed facilities.
Growth Catalysts
- FDA Quality System Regulation:Mandatory audit trails and preventive maintenance documentation for critical devices push hospitals toward integrated CMMS platforms that automate compliance workflows.
- IoT sensor proliferation:Real-time condition monitoring on imaging equipment enables predictive maintenance models that reduce unplanned outages and extend asset lifecycles.
- United States health system consolidation:Integrated delivery networks seek vendor consolidation across multi-site footprints, favoring scalable cloud-based maintenance management.
Market Restraints
- Legacy system integration costs:On-premises installations from the 2010s require expensive middleware to connect with modern cloud platforms, delaying upgrade cycles.
- Data sovereignty requirements:Institutions in Germany and Switzerland face strict national health data laws that complicate cross-border cloud hosting arrangements.
- Cybersecurity insurance premiums:Rising costs for cyber liability coverage connected to medical device networks constrain IT budgets for maintenance system expansion.
Strategic Opportunities
- India hospital modernization:CDSCO medical device regulations are tightening quality management requirements, creating demand for compliant maintenance tracking systems.
- AI-IoT convergence:Machine learning models applied to vibration and thermal sensor data from diagnostic equipment enable automated failure prediction with minimal human intervention.
- Joint Commission accreditation:New standards for equipment management documentation create pull for platforms with built-in audit-ready reporting modules.
Industry Challenges
- Biomedical engineering talent scarcity:Shortages of technicians trained in both clinical equipment repair and software platform administration limit implementation velocity.
- Multi-vendor interoperability:Proprietary data formats from Siemens, GE, and Philips imaging systems complicate unified maintenance dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Computerized Maintenance Management System Market |
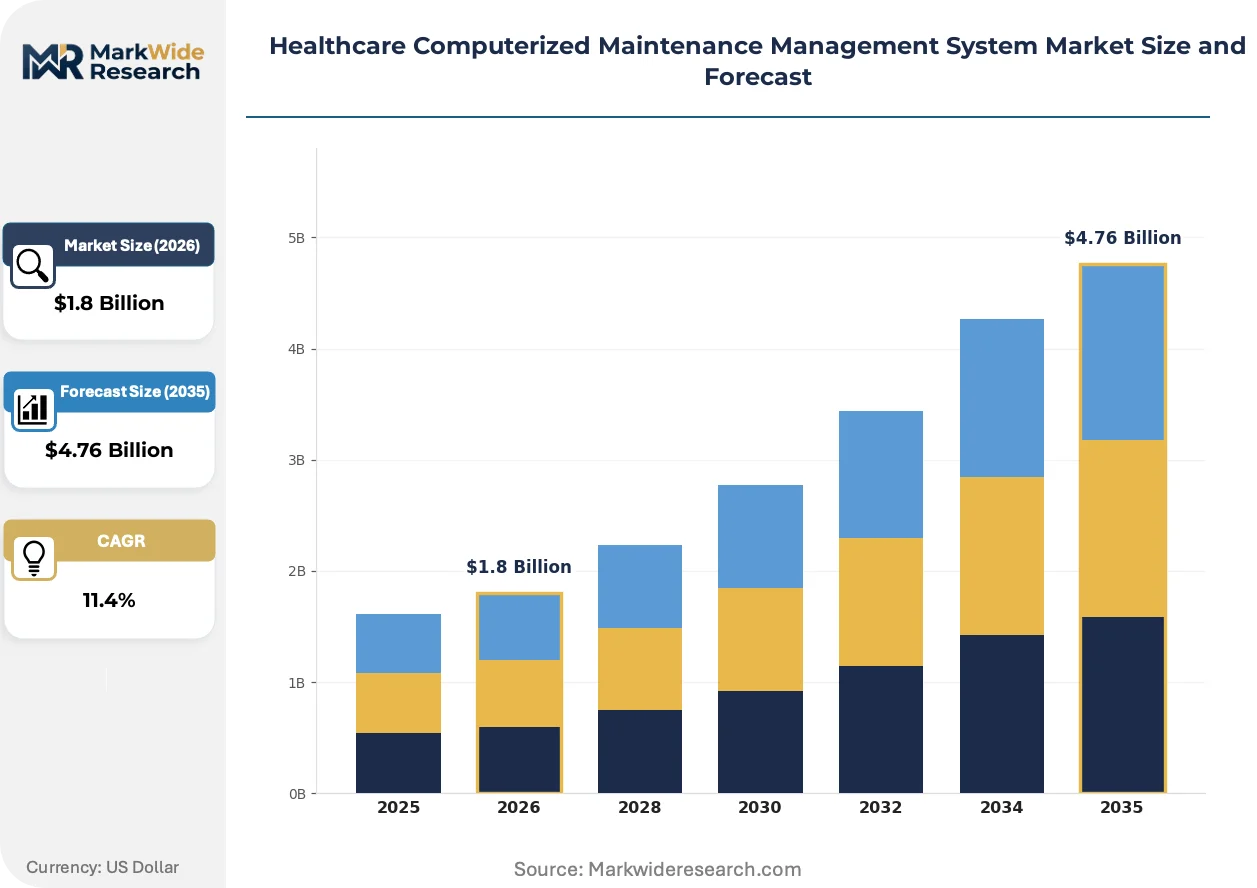
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Open Source Technology: IoT Integration, AI Analytics, Mobile Access, Automation End User: Hospitals, Clinics, Healthcare Facilities, Laboratories Application: Asset Management, Work Order Management, Inventory Control, Compliance Tracking |
| Companies Covered | Accruent, IBM, Fluke Corporation, Hippo CMMS, MPulse Software, Limble CMMS, FSI, Ultimo Software Solutions, Facilio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Computerized Maintenance Management System Market Evolving Landscape
Digital infrastructure for healthcare asset management is pivoting from reactive repair scheduling toward continuous condition monitoring, with regulatory pressure and cloud economics accelerating platform replacement cycles.
Edge computing architectures deployed directly on imaging equipment are digitizing maintenance workflows by processing sensor data locally before cloud transmission. Radiology departments in academic medical centers are piloting these systems to reduce latency in failure alerts. The shift is digitizing how clinical engineering teams prioritize daily work orders, compressing response windows from hours to minutes.
EU Medical Device Regulation (MDR) post-market surveillance requirements are mandating systematic performance tracking for implantable and diagnostic equipment across European hospital networks. Manufacturers must now provide maintenance documentation accessible to notified bodies, forcing CMMS vendors to embed MDR-compliant data export functions. German university hospitals are leading adoption of these enhanced traceability modules.
Subscription-based platform economics are displacing perpetual license models as health system CFOs prioritize operational expenditure over capital allocation. Integrated delivery networks in Texas and California are consolidating vendor relationships around multi-year SaaS agreements that bundle implementation, training, and regulatory update services. The model concentrates purchasing authority with system-level procurement teams rather than individual facility managers.
Healthcare Computerized Maintenance Management System Market Segmentation
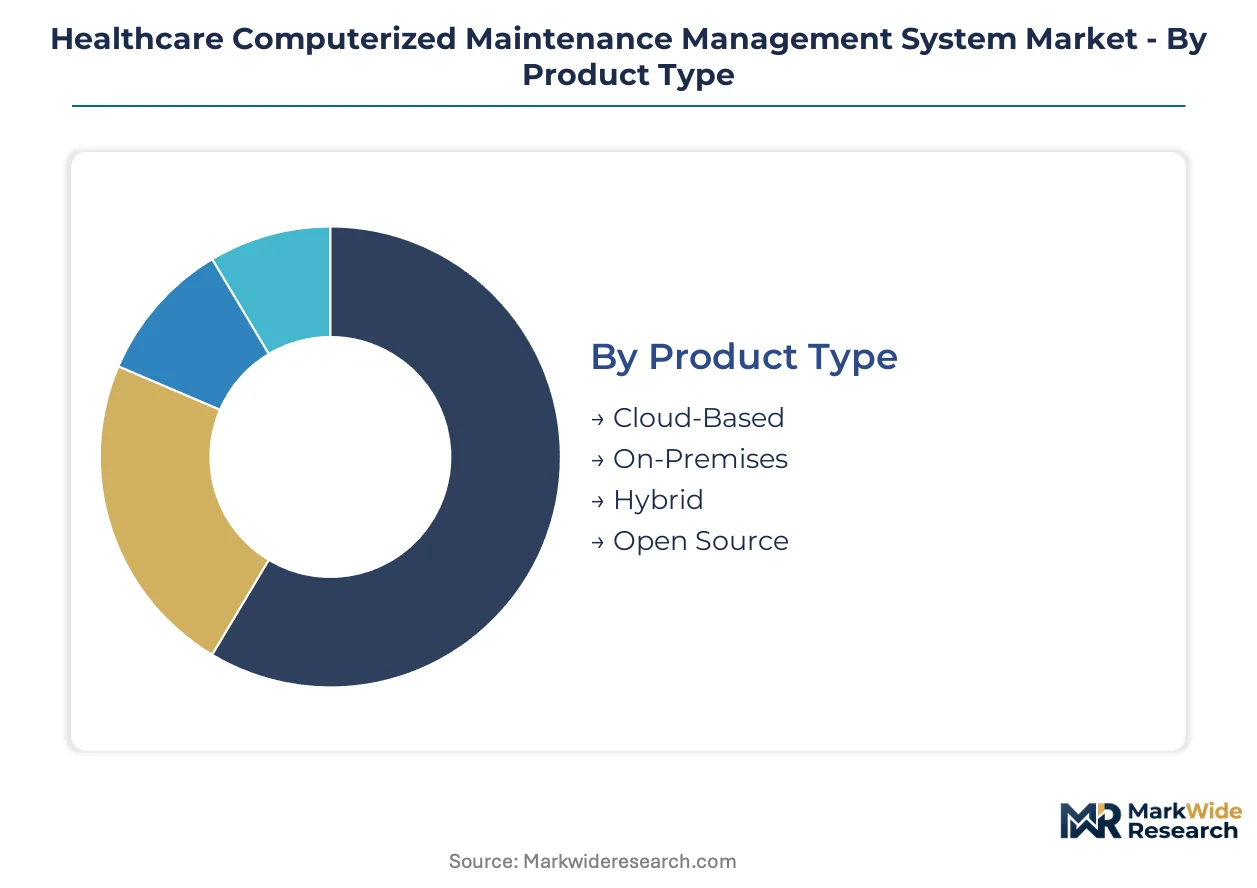
Healthcare CMMS platforms fragment across deployment architectures, analytical capabilities, and operational workflows. Each dimension carries distinct compliance implications and capital requirements that shape vendor selection criteria.
Product Type:
Cost tier structures the initial procurement decision and ongoing operational burden for health system CFOs.
- Cloud-Based:Multi-tenant SaaS platforms deliver remote accessibility, automatic security patching, and subscription pricing that shifts expenditure from capital to operational budgets. Demand concentrates in United States integrated delivery networks consolidating multi-site maintenance operations under unified dashboards.
- On-Premises:Locally installed servers retain full data custody within institutional firewalls, satisfying HIPAA business associate agreement minimization strategies. German and Swiss university hospitals favor this architecture under strict national health data sovereignty laws.
- Hybrid:Split deployments keep sensitive patient data on local infrastructure while routing non-PHI maintenance analytics to cloud processors.
- Open Source:Community-developed platforms offer customization flexibility for biomedical engineering departments with internal software development capacity.
Cloud-Based commands the established base. The steepest expansion runs through Hybrid as institutions balance agility against compliance risk.
Technology:
Application sophistication determines predictive capability depth and technician workflow efficiency.
- IoT Integration:Connected sensors on MRI and CT equipment stream vibration, thermal, and operational cycle data to central monitoring platforms. Academic medical centers in the United States deploy these systems to compress failure detection-to-response windows from hours to minutes.
- AI Analytics:Machine learning models trained on historical failure patterns forecast asset degradation trajectories and optimize preventive maintenance scheduling intervals.
- Mobile Access:Smartphone and tablet interfaces enable bedside work order initiation, barcode scanning for parts inventory, and photographic documentation of equipment conditions.
- Automation:Rules-based engines trigger maintenance requests, purchase requisitions, and regulatory report generation without human intervention.
Mobile Access dominates current implementations. AI Analytics is gaining share fastest as imaging equipment manufacturers embed predictive algorithms in service contracts.
End User:
Customer type scales feature requirements from single-site compliance to enterprise-wide standardization.
- Hospitals:Multi-departmental deployments spanning clinical engineering, facilities management, and infection control demand role-based access controls and comprehensive audit trails. United States hospital networks drive volume as FDA cybersecurity mandates force platform consolidation.
- Clinics:Outpatient settings prioritize streamlined work order routing and minimal training overhead for small technical staffs.
- Healthcare Facilities:Long-term care and rehabilitation centers emphasize durable medical equipment tracking and resident safety documentation.
- Laboratories:Research and diagnostic labs require calibration scheduling, reagent inventory integration, and GLP-compliant record retention.
Hospitals anchor revenue concentration. Laboratories show the steepest expansion trajectory as precision medicine investments multiply analytical instrument counts.
Application:
Functional modules align software expenditure with specific operational pain points and regulatory exposure.
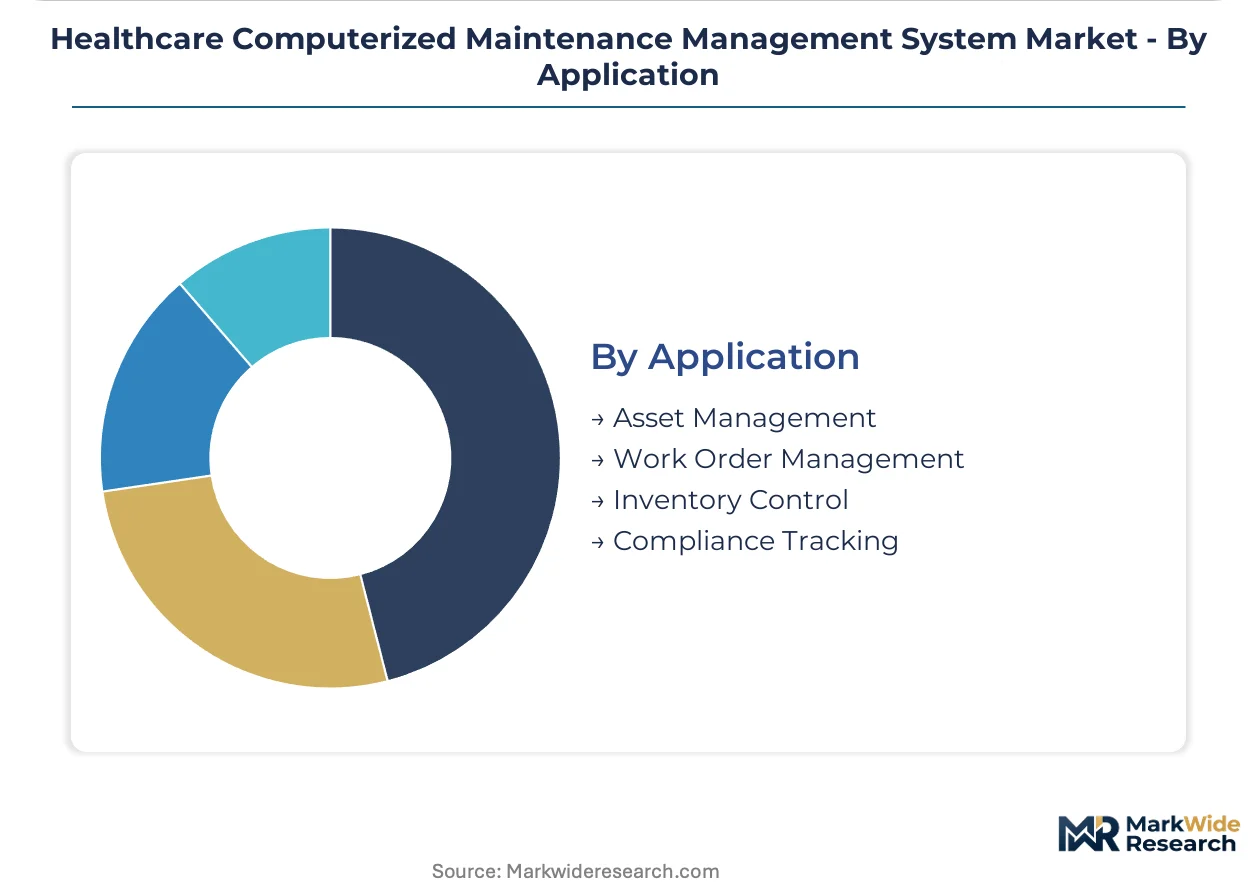
- Asset Management:Comprehensive equipment registries track purchase dates, warranty status, service histories, and replacement timelines across capital-intensive imaging fleets. United States health systems deploy these modules to satisfy Joint Commission equipment management standards.
- Work Order Management:Digital ticketing systems route repair requests, track technician assignments, and measure response time performance against internal SLAs.
- Inventory Control:Spare parts warehouses link consumption to specific equipment models and automate reorder points based on criticality classifications.
- Compliance Tracking:Automated documentation generation supports FDA quality system regulation audits, preventive maintenance log maintenance, and corrective action record retention.
Asset Management holds the installed base majority. Compliance Tracking is climbing the fastest as EU MDR post-market surveillance requirements tighten documentation burdens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: United States health systems prioritize predictive uptime platforms, while German institutions emphasize data sovereignty architectures, and Indian hospital networks focus on cost-optimized compliance modules.
United States
FDA cybersecurity mandates for medical device servicing and Joint Commission accreditation standards drive hospital network consolidation onto unified cloud platforms. Integrated delivery networks in Texas and California are bundling multi-year SaaS agreements that combine implementation, training, and regulatory update services. The Southeast corridor from Florida to Georgia shows concentrated deployment of IoT-enabled predictive maintenance for imaging fleets.
Germany
Strict national health data sovereignty laws under GDPR and the EU Medical Device Regulation push university hospitals toward on-premises and hybrid deployment architectures. The EU MDR post-market surveillance requirements mandate systematic performance tracking for diagnostic equipment, forcing CMMS vendors to embed compliant data export functions. Bavarian medical centers lead adoption of enhanced traceability modules for implantable device documentation.
Switzerland
Federal data protection ordinances and Swissmedic medical device oversight create demand for locally hosted maintenance management systems with encrypted transmission protocols. University hospitals in Zurich and Geneva favor hybrid architectures that process sensitive patient data on-site while routing non-PHI analytics to cloud processors. The Basel pharmaceutical corridor drives specialized laboratory asset management requirements for calibration scheduling and GLP-compliant record retention.
India
CDSCO medical device regulations are tightening quality management requirements for hospital networks undergoing modernization. Corporate hospital chains in Maharashtra and Karnataka are deploying cloud-based platforms to automate preventive maintenance documentation and corrective action workflows. The Delhi-NCR region shows accelerating demand for mobile-accessible work order systems among outpatient clinic networks.
United Kingdom
NHS digital transformation programs and MHRA medical device registration requirements push trusts toward integrated asset management platforms. London-based academic medical centers are piloting edge computing architectures on imaging equipment to compress failure detection-to-response windows. The Midlands corridor concentrates procurement of compliance tracking modules to satisfy evolving post-market surveillance obligations.
Healthcare Computerized Maintenance Management System Market Competitive Landscape
Capability concentration sits with specialized healthcare software vendors; scale advantage sits with diversified technology conglomerates with IoT infrastructure. The vendor base organizes into three tiers: dominant North American platform providers with deep facility management ecosystem integration, diversified industrial technology conglomerates leveraging predictive analytics infrastructure, and emerging cloud-native specialists competing on deployment velocity. Competitive moves center on strategic partnerships with imaging equipment manufacturers and geographic expansion through health system consolidation mandates.
Within the dominant platform tier, Accruent and IBM exemplify contrasting scale-versus-capability positioning. Accruent occupies a position as the archetypal healthcare facility management specialist with entrenched hospital network relationships. IBM represents the diversified technology conglomerate vector, leveraging Watson IoT infrastructure to anchor predictive analytics offerings. Hippo CMMS sits within the emerging cloud-native tier, exemplifying deployment models that prioritize rapid rollout cycles over deep legacy system integration.
| Leading Market Players |
|---|
| Accruent |
| IBM |
| Fluke Corporation |
| Hippo CMMS |
| MPulse Software |
| Limble CMMS |
| FSI |
| Ultimo Software Solutions |
| Facilio |
| Others |
Value Network & Pricing Analysis
Undercapacity in cloud infrastructure provisioning across German and Swiss university hospitals is driving extended implementation timelines and premium pricing for compliant deployment architectures. This utilization squeeze simultaneously elevates vendor bargaining power in data-sovereignty-constrained markets while compressing margins for rapid-deployment cloud-native competitors.
Pricing Analysis
Long-term SaaS subscription contracts dominate procurement patterns among United States integrated delivery networks, with three-year bundled agreements combining implementation, training, and regulatory update services displacing perpetual license models. Price differentiation rests on FDA validation tier and IoT sensor integration depth, with cybersecurity-hardened platforms commanding substantial premiums over baseline compliance modules. Cost compression in mid-tier cloud offerings is intensifying as Hippo CMMS and Limble CMMS compete on deployment velocity. Small clinic networks exhibit highest price sensitivity, while academic medical centers prioritize predictive analytics capabilities over acquisition cost.
Supply Chain Analysis
Extended payment terms from 45 to 90 days characterize vendor financing arrangements as cloud-native specialists compete for health system CFO attention against established platform providers. Software development capacity concentrates in the United States, India, and Ireland, with regulatory compliance documentation expertise clustering in Germany and Switzerland. The supply chain draws from specialized healthcare IT talent pools and hyperscaler cloud infrastructure, with single-source vulnerability resting on AWS, Azure, and Google Cloud hosting dependencies. Distribution runs through direct enterprise sales teams supplemented by GPO contracts and imaging equipment manufacturer service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment constructs formidable defensive moats in this market, as FDA quality system documentation requirements and Joint Commission accreditation standards embed incumbent platforms deeply into hospital operational workflows.
For Market Incumbents: Harden platform stickiness through deeper integration with Siemens, GE, and Philips imaging equipment APIs, reducing multi-vendor interoperability friction that currently fragments maintenance dashboards. Invest in edge computing architectures deployed directly on diagnostic equipment to compress failure detection-to-response windows below emerging cloud-native competitors. Vertical integration into biomedical engineering training programs addresses talent scarcity limiting implementation velocity. For New Entrants and Emerging Players: India's corporate hospital chains in Maharashtra and Karnataka represent substantial underpenetration opportunity as CDSCO regulations tighten quality management requirements without legacy system baggage. Target outpatient clinic networks in the Delhi-NCR region with mobile-first work order systems emphasizing minimal training overhead. Partner with regional imaging equipment distributors for co-selling access to maintenance contract decision-makers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as subscription economics displace on-premises infrastructure investments. Acquisition targets should display established FDA 21 CFR Part 11 validation documentation and existing hospital network referenceability rather than pure technology differentiation. Watch for inflection signals in health system RFP volume acceleration preceding platform consolidation mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Deep integration with Texas and California IDN procurement teams secures multi-year SaaS recurring revenue bases. |
| Platform Integration | API connectivity with Watson IoT infrastructure differentiates predictive analytics offerings for imaging fleet uptime. |
| FDA Submission | 21 CFR Part 11 validation documentation enables sales to United States hospital networks facing cybersecurity mandates. |
| Geographic Expansion | CDSCO-compliant modules position vendors for India's corporate hospital modernization wave. |
| Acquisition of Specialist Firm | Edge computing capabilities from academic medical center pilots accelerate failure detection-to-response compression. |
Research Methodology
Operator-level perspectives from biomedical engineering directors, hospital purchasing committee chairs, GPO contracts managers, and CMMS platform implementation specialists anchored the qualitative base. These primary insights combined with secondary validation from FDA 510(k) filings, Joint Commission accreditation databases, hospital procurement records, and CMS Medicare cost report data. Bottom-up equipment fleet analysis and top-down health system IT spending estimates were triangulated to constrain projection variance.
Scenario-bracketing around regulatory enforcement intensity and cloud adoption velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass deployment architecture, technology sophistication tier, end-user scale category, and application functional module. CAGRs were derived from fitted growth curves against historical platform replacement cycles and health system consolidation trajectories. Forecast inputs incorporated IoT sensor penetration rates on imaging equipment and EU MDR documentation burden escalation.
Macroeconomic conditions sit as an overlay; deviation in health system capital expenditure cycles and cybersecurity insurance premium trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding FDA enforcement continuity and cloud infrastructure cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
North America Enterprise Information Archiving (EIA) Market
Digital Solutions
Global Service Delivery Platform Market
Digital Solutions
Global Integration Platform As a Service (IPAAS) Market
Digital Solutions
Social Networking App Market
Digital Solutions
North America Managed Mobility Service Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
Distributed Performance and Availability Management Software Market
Digital Solutions
Cloud Electronic Design Automation Market
Digital Solutions
Global Data Historian Market
Digital Solutions
System Integrator Market
Digital Solutions
Data Integration Market
Digital Solutions
Application Modernization Services Market
Digital Solutions
Epedigree Software Market
Digital Solutions
Mexico Digital Twin Market
Digital Solutions
Global Mobile Workforce Management Market
Digital Solutions
Web Based E-Detailing Market