
 Europe Digital Twin Market | 2026-2036
Europe Digital Twin Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Twin Market Analytics
Automotive manufacturing is restructuring demand patterns across the Europe Digital Twin Market as virtual prototyping replaces physical test cycles. Siemens anchors its position through deep software-hardware integration in industrial automation. Dassault Systèmes dominates aerospace and automotive design suites with 3D experience platforms. Robert Bosch GmbH leverages sensor-to-cloud connectivity to sustain its factory digitalization footprint.
A digital twin constitutes a dynamic virtual replica of a physical asset, system, or process that ingests real-time sensor data and applies physics-based or data-driven models to simulate behavior, predict performance, and optimize operations without disrupting live production. The technology relies on IoT connectivity, high-fidelity simulation engines, and cloud or edge computing infrastructure to mirror operational states across their full lifecycle. Software and platform segments capture the dominant share of value as vendors bundle simulation kernels with analytics layers and industry-specific templates. Cloud-based and hybrid deployment modes are expanding fastest as manufacturers seek scalable compute for complex multiphysics simulations without capital-intensive on-premises infrastructure. Predictive maintenance and design optimization use cases concentrate margin pools where operational downtime avoidance justifies premium licensing.
The EU AI Act and GDPR establish compliance boundaries for autonomous decision-making and data governance in connected industrial environments, while CE marking under the EU Green Deal pressures manufacturers to document energy and emissions performance through validated digital models. ECHA REACH obligations further extend material traceability requirements into twin-based supply chain visibility tools. Stakeholders must monitor how evolving EU regulatory frameworks for AI transparency and product sustainability reshape platform certification requirements and customer procurement criteria.
Market Dynamics
Automotive OEMs in Germany, France, and Italy are consolidating virtual validation workflows around unified digital twin platforms, compressing physical prototyping cycles from months to weeks while satisfying CE marking documentation requirements under the EU Green Deal.
Growth Catalysts
- EU Green Deal mandates:Industrial operators must document energy and emissions performance through validated digital models to secure CE marking, forcing deployment of real-time simulation infrastructure.
- German automotive cluster concentration:BMW, Volkswagen, and Mercedes-Benz suppliers in Bavaria and Baden-Württemberg are procuring integrated twin platforms for virtual crash testing and powertrain optimization.
- Edge-to-cloud connectivity maturation:5G private networks and time-sensitive networking standards now enable sub-10 millisecond latency for high-fidelity physics simulations at production line scale.
Market Restraints
- GDPR data governance friction:Cross-border data flows for cloud-hosted twins face Article 44-49 compliance audits, delaying multi-site deployments by 6-18 months.
- Physics engine licensing concentration:High-fidelity multiphysics kernels from US and German specialized vendors command 40-60% of platform costs, squeezing mid-tier system integrators.
- Legacy OT-IT integration debt:Brownfield factories running 1990s-era SCADA architectures require costly protocol translation layers before twin connectivity becomes feasible.
Strategic Opportunities
- Poland and Czech Republic manufacturing expansion:Automotive and electronics FDI in Central Europe lacks mature digital twin infrastructure, creating first-mover platform installation opportunities.
- EU AI Act conformity assessment:Autonomous decision-making modules within twins require notified body certification, opening audit and validation service revenue streams.
- Digital thread-to-twin convergence:PLM systems from design suites are merging with operational twins, enabling closed-loop product lifecycle optimization from R&D through end-of-life.
Industry Challenges
- Multiphysics simulation expertise scarcity:European universities produce fewer than 2,000 graduates annually with combined mechanical, electrical, and software modeling competencies.
- ISO 23247 standardization lag:Incomplete asset administration shell specifications force vendors to maintain parallel interoperability protocols, fragmenting customer integration roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Twin Market |
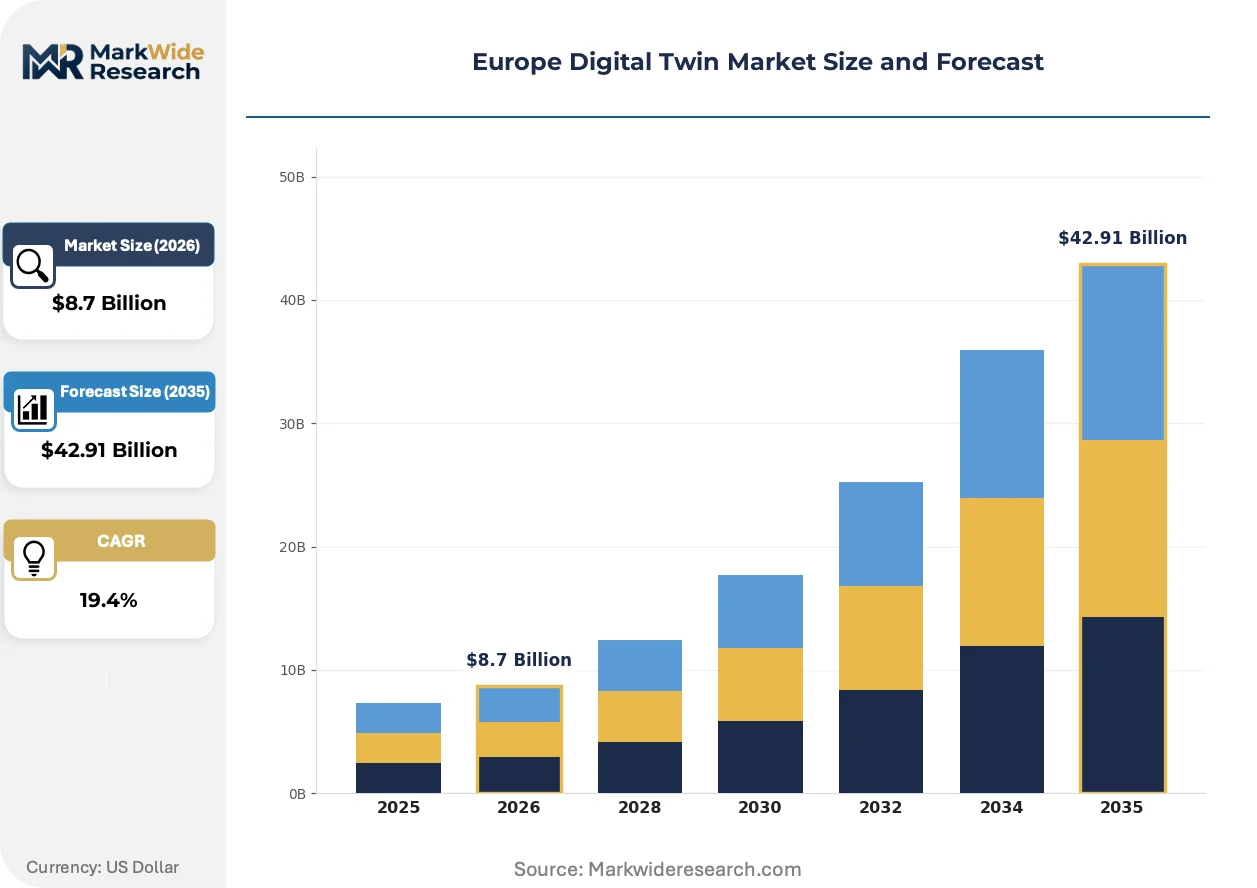
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Platform, Services, Infrastructure Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Industry Vertical: Manufacturing, Healthcare, Automotive, Aerospace Use Case: Predictive Maintenance, Simulation, Design Optimization, Asset Management |
| Companies Covered | ANSYS, Robert Bosch GmbH, Siemens, Honeywell International Inc., AVEVA Group plc, Dassault Systèmes, PTC, Rockwell Automation, GE Vernova, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Twin Market Evolving Landscape
Generative AI is embedding into twin platforms, compressing model calibration from weeks to hours while raising new EU AI Act transparency obligations for autonomous industrial decision systems.
AI-powered surrogate modeling is automating physics simulation workflows previously requiring manual finite element mesh refinement. Automotive crash safety teams at Renault and Stellantis are deploying these tools to evaluate 10x more design variants per development cycle. The technology is automating away tier-2 engineering service contracts for routine load case analysis.
CSRD sustainability reporting rules now mandate granular Scope 3 emissions disclosure, forcing manufacturers to deploy supply chain twins tracing material provenance from raw extraction through finished goods. ECHA REACH database integration has become a procurement prerequisite for chemical and automotive sectors. French industrial groups are advancing fastest, leveraging existing product environmental footprint methodologies.
Subscription pricing for platform access is displacing perpetual license models across German machinery and automotive verticals. Siemens and Dassault Systèmes now derive majority revenue from recurring cloud contracts, locking customers into continuous upgrade cycles. Equipment-as-a-service providers in Italy are bundling twin analytics into monthly machine rental fees, embedding intelligence directly into financing structures.
Europe Digital Twin Market Segmentation
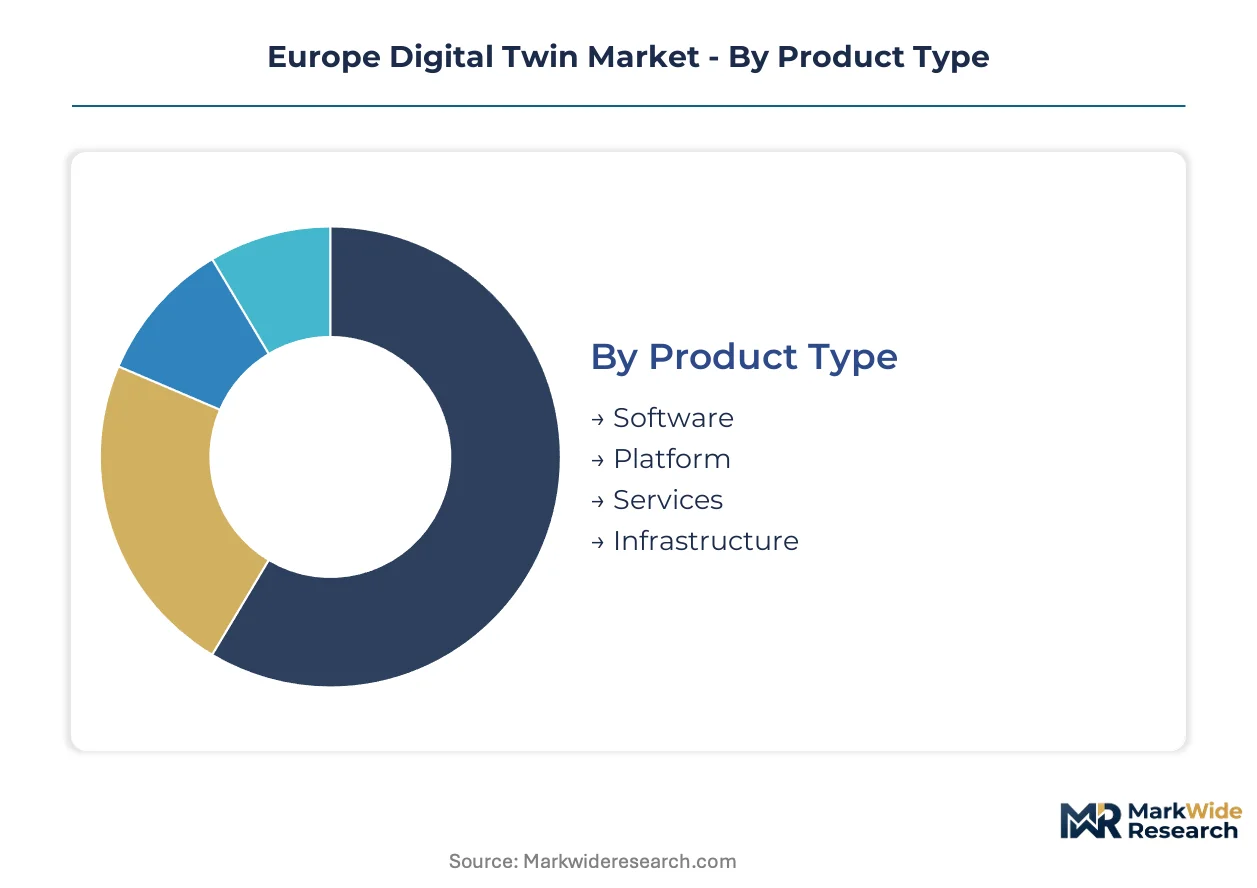
Digital twin procurement patterns diverge sharply across deployment modes and industry verticals. Software licensing models, data sovereignty requirements, and physics simulation complexity create distinct buyer archetypes with incompatible vendor evaluation criteria.
Product Type:
Cost tier separates enterprise platform commitments from modular service engagements.
- Software:Simulation kernels and analytics engines form the core IP layer, embedding physics solvers and machine learning inference modules. German automotive OEMs in Bavaria and Baden-Württemberg dominate procurement, driven by virtual crash testing and powertrain validation requirements under CE marking mandates.
- Platform:Integrated environments bundle modeling tools, data ingestion pipelines, and visualization layers with industry-specific templates. Cloud-native architectures are displacing perpetual licenses fastest among mid-tier machinery suppliers seeking scalable compute without capital intensity.
- Services:System integration, model calibration, and change management support implementation.
- Infrastructure:Edge servers, 5G private networks, and sensor hardware enable real-time data pipelines.
Volume sits with Software; growth tilts toward Platform.
Deployment:
Data gravity and latency tolerance dictate architecture selection across brownfield and greenfield sites.
- Cloud-Based:Scalable compute resources support complex multiphysics simulations without on-premises capital expenditure. GDPR Article 44-49 compliance audits delay multi-site deployments by 6-18 months, constraining cross-border data flows for centralized twin hosting.
- Hybrid:Sensitive operational data remains on-premises while compute-intensive modeling shifts to cloud resources. French industrial groups advance fastest, leveraging existing product environmental footprint methodologies for CSRD-aligned sustainability reporting.
- On-Premises:Air-gapped installations serve defense and critical infrastructure operators with sovereignty requirements.
- Edge Computing:Sub-10 millisecond latency enables real-time feedback loops for production line control.
Hybrid deployments command current procurement volume; edge-native architectures are climbing the fastest as 5G private networks mature.
Industry Vertical:
Regulatory pressure intensity and asset complexity create divergent platform requirements.
- Automotive:Virtual prototyping compresses physical test cycles from months to weeks while satisfying EU Green Deal documentation requirements. BMW, Volkswagen, and Mercedes-Benz suppliers consolidate validation workflows around unified platforms for crash safety and emissions optimization.
- Manufacturing:Brownfield factories running 1990s-era SCADA architectures require costly protocol translation layers before twin connectivity becomes feasible. Poland and Czech Republic manufacturing expansion lacks mature infrastructure, creating first-mover installation opportunities.
- Aerospace:Long asset lifecycles and certification rigor demand high-fidelity physics modeling.
- Healthcare:Patient data sensitivity restricts deployment to on-premises or sovereign cloud architectures.
Automotive anchors revenue concentration; manufacturing is gaining share fastest through Central European FDI.
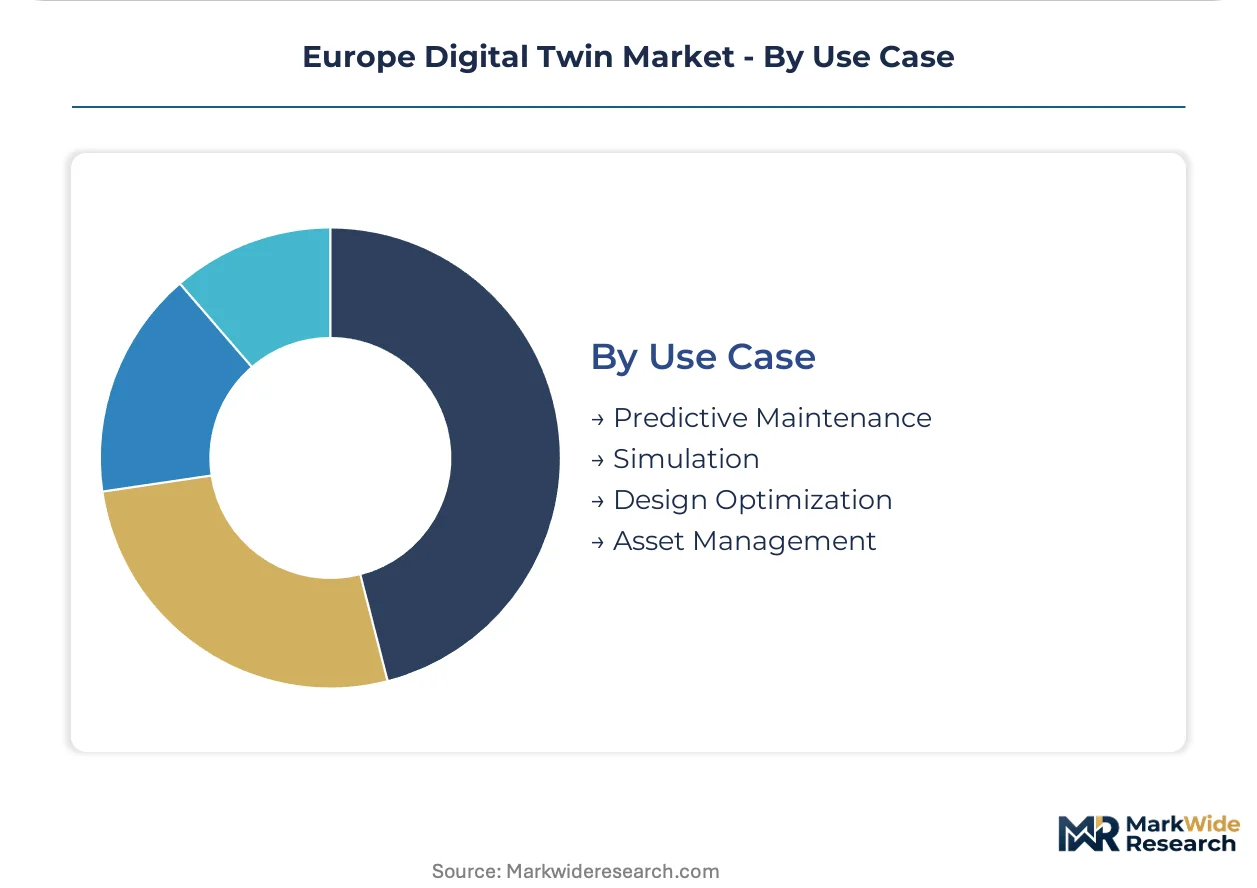
Use Case:
ROI measurability and implementation complexity determine adoption sequencing.
- Predictive Maintenance:Operational downtime avoidance justifies premium licensing through quantified failure cost prevention. Sensor-to-cloud connectivity enables condition monitoring with physics-informed remaining useful life estimation.
- Simulation:AI-powered surrogate modeling automates finite element workflows, compressing model calibration from weeks to hours while raising EU AI Act transparency obligations for autonomous decision systems.
- Design Optimization:Closed-loop PLM integration enables variant evaluation at 10x previous throughput.
- Asset Management:Lifecycle traceability supports CSRD Scope 3 emissions disclosure and ECHA REACH material provenance requirements.
Predictive Maintenance captures margin concentration; simulation is expanding most quickly through generative AI integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany produces the dominant share of digital twin platform value, yet consumption spreads across automotive and machinery clusters in France, Italy, and Central Europe. The EU Green Deal and CE marking requirements apply uniformly, but implementation intensity varies by national industrial structure.
Germany
Automotive OEMs and Tier-1 suppliers in Bavaria and Baden-Württemberg drive procurement for virtual crash testing and powertrain validation. The KBA enforces type-approval documentation that digital twins must satisfy under EU vehicle regulations. Stuttgart and Munich host the densest concentration of industrial software R&D facilities.
France
Aerospace and nuclear energy operators deploy high-fidelity physics simulations for long-asset lifecycle management. ANSM and ASN impose certification rigor that favors validated digital models for safety-critical systems. The Île-de-France region concentrates platform development talent near Paris-Saclay research clusters.
Italy
Equipment-as-a-service providers in Emilia-Romagna embed twin analytics into machine rental contracts. The country's national standardization body, UNI, participates actively in ISO 23247 asset administration shell specifications. Turin and Milan anchor automotive and machinery digitalization demand.
United Kingdom
Defense and critical infrastructure operators mandate sovereign cloud or air-gapped twin architectures. The UK Information Commissioner's Office applies GDPR-equivalent data governance through the UK GDPR framework. London and the Southeast concentrate financial services demand for operational risk simulation.
Poland
Automotive and electronics FDI from German and Asian manufacturers lacks mature digital twin infrastructure. The Polish Centre for Accreditation participates in EU conformity assessment alignment for CE marking. The Silesia and Greater Poland voivodeships attract first-mover platform installations.
Europe Digital Twin Market Competitive Landscape
Top-tier vendors anchor enterprise platform commitments, while specialized physics engine providers and regional system integrators occupy lower tiers. The market structure concentrates around software-hardware integration capability and industry-specific template depth. Two strategic archetypes dominate: industrial automation conglomerates with captive hardware ecosystems, and pure-play simulation software vendors with aerospace-automotive design heritage. Competitive moves center on cloud-native portfolio migration and strategic partnerships for edge-to-cloud connectivity.
Within the industrial automation tier, Siemens and Robert Bosch GmbH represent archetypes of deep software-hardware integration, while Dassault Systèmes exemplifies the design-centric simulation platform model. These three anchors occupy distinct competitive positions—Siemens through factory automation dominance, Bosch through sensor-to-cloud factory digitalization, and Dassault Systèmes through 3D experience platforms serving aerospace and automotive design workflows.
| Leading Market Players |
|---|
| ANSYS |
| Robert Bosch GmbH |
| Siemens |
| Honeywell International Inc. |
| AVEVA Group plc |
| Dassault Systèmes |
| PTC |
| Rockwell Automation |
| GE Vernova |
| Others |
Value Network & Pricing Analysis
CE marking requirements under the EU Green Deal gate both qualified supply and premium-tier pricing access, forcing industrial operators to document energy and emissions performance through validated digital models before platform procurement becomes viable. This environmental compliance barrier stratifies vendors into certified premium providers versus non-compliant economy alternatives.
Pricing Analysis
Margin tightening in mid-tier platform licensing reflects physics engine royalty burdens from specialized German and US kernel vendors. Subscription SaaS models now dominate German automotive and machinery verticals, displacing perpetual licenses through recurring cloud contracts. Price differentiation rests on CE marking certification depth and ISO 23247 asset administration shell compliance, with GDPR-ready hybrid deployments commanding premiums. Tier-2 system integrators face acute price sensitivity as high-fidelity multiphysics licensing consumes 40-60% of platform costs.
Supply Chain Analysis
Domestic-content mandates in French nuclear and aerospace sectors reshape sourcing toward EU-based physics simulation talent and sovereign cloud infrastructure. Supply concentrates in Germany, France, and the Netherlands for industrial automation hardware and edge computing components. Raw material dependencies span silicon photonics for sensor arrays, rare earth elements for precision actuators, and specialized alloys for harsh-environment edge servers. Single-source vulnerability runs through US-based multiphysics kernel licensing. Distribution runs through direct enterprise sales teams and certified system integrator networks serving automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Digital Twin Market operates as a cost-of-compliance story where the EU AI Act creates a barrier-to-entry moat for platform vendors with notified body certification capabilities.
For Market Incumbents: Anticipate generative AI integration disrupting traditional physics simulation licensing models by compressing model calibration timelines. Defend position through deeper ISO 23247 standard participation and captive multiphysics kernel development to reduce royalty exposure. Prioritize edge-to-cloud hybrid deployment certification under GDPR Article 44-49 to accelerate multi-site customer deployments. For New Entrants and Emerging Players: Launch via audit and validation services for EU AI Act conformity assessment, the most penetrable white-space segment. Target Poland and Czech Republic automotive FDI clusters lacking mature digital twin infrastructure. Deploy equipment-as-a-service financing models bundling twin analytics into monthly machine rental fees. For Investors and Strategic Acquirers: Notified body certification acquisition velocity is the leading indicator that platform consolidation will accelerate among mid-tier vendors lacking compliance capabilities. Long-term viability favors vendors with vertical-specific template libraries and captive physics engine IP. Monitor ECHA REACH database integration capabilities as the signal for supply chain twin readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Siemens and Dassault Systèmes merge PLM systems with operational twins for closed-loop lifecycle optimization. |
| Strategic Partnership | 5G private network operators collaborate with edge server vendors to enable sub-10 millisecond latency for production line control. |
| Acquisition of Specialist Firm | Physics engine vendors purchase surrogate modeling startups to embed generative AI into simulation workflows. |
| Geographic Expansion | Platform providers establish first-mover installations in Poland and Czech Republic automotive manufacturing corridors. |
| Green Certification Program | Vendors develop EU Green Deal-aligned documentation tools securing CE marking for industrial operator customers. |
Research Methodology
Document review covered EU regulatory filings, industrial software vendor SEC disclosures, and ECHA REACH database structures, complemented by interviews with plant engineers, OEM procurement teams, platform engineering leads, and aftermarket service heads at German automotive suppliers. Secondary validation drew from customs trade data, KBA type-approval documentation, and ANSM safety-critical system certifications. Bottom-up deployment modeling and top-down market sizing were triangulated against primary field intelligence.
Segment-level outputs across the analysis window were generated through multivariate frameworks incorporating deployment mode, industry vertical, use case complexity, and regional regulatory cluster intensity. CAGRs were derived from elasticity modeling against EU Green Deal implementation timelines and CE marking enforcement trajectories. Forecast inputs included 5G private network maturity curves and generative AI surrogate modeling adoption rates.
Regulatory enforcement delays, physics engine licensing concentration shifts, and ISO 23247 standardization fragmentation are the dominant revision risks to projection boundaries. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Sharing Economy Market
Digital Solutions
Product Life Cycle Management (PLM) Market
Digital Solutions
Global Enterprise Information Archiving Market
Digital Solutions
Global Cloud OSS BSS Market
Digital Solutions
Product Design and Development Services Market
Digital Solutions
API Management Market
Digital Solutions
Real-Time Temperature and Location Monitoring Platforms for Cold Chain Market
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Global Inventory Optimization Software Market
Digital Solutions
Data Monetization Solutions for Life Science Companies Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Harbor Management Software Market
Digital Solutions
Water Level and Storage Monitoring Software Market
Digital Solutions
Conference Room Solutions Market
Digital Solutions
Global B2B Buyer Intent Data Tools Market
Digital Solutions
Cloud Backup and Recovery Market