
 Asia-Pacific Consumer Electronics Packaging Market | 2026-2036
Asia-Pacific Consumer Electronics Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Consumer Electronics Packaging Market Insights
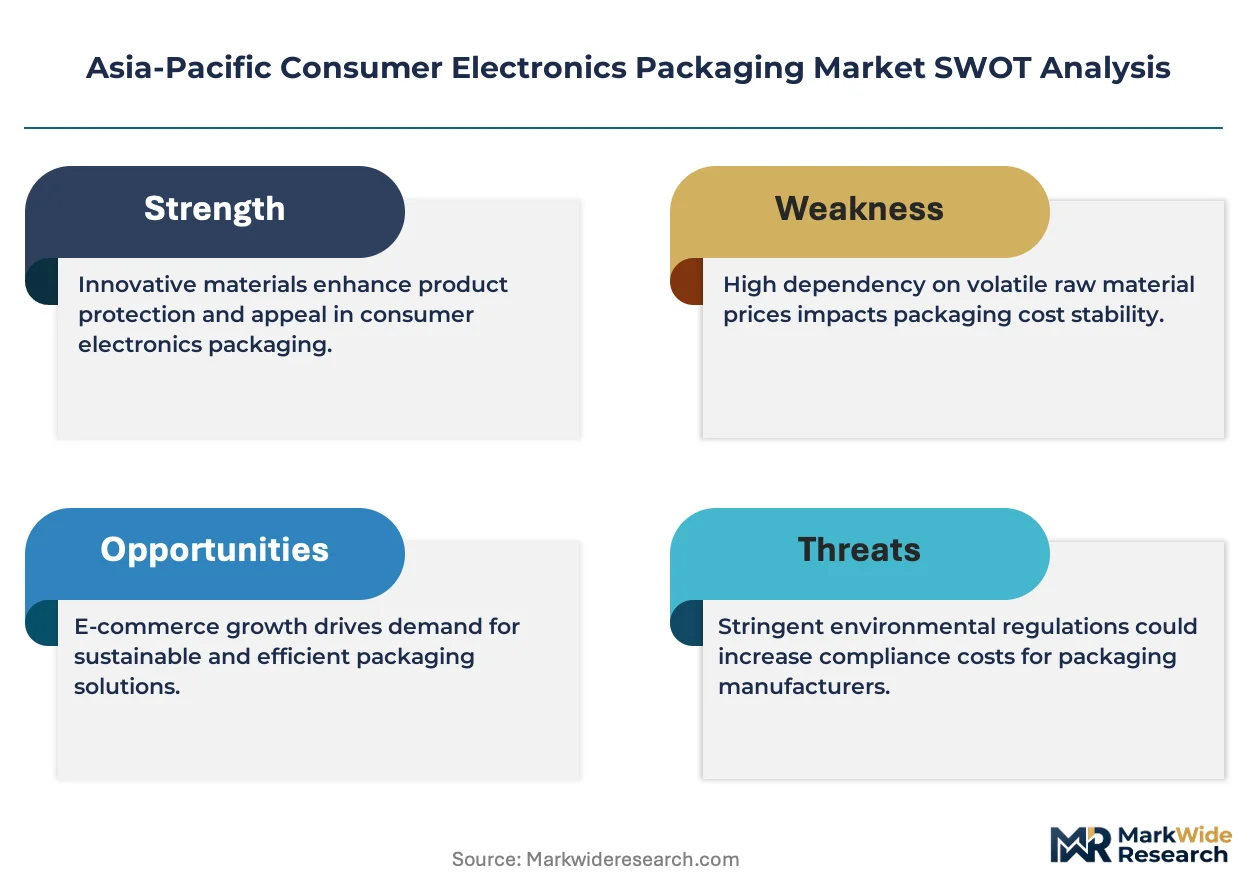
China's GB standards for packaging recyclability is pivoting material selection across the value chain. DS Smith leverages European design expertise to serve premium electronics brands in Shanghai and Shenzhen. Samsung Electronics anchors packaging demand through its vertically integrated smartphone assembly in Vietnam and India. Smurfit Kappa Group competes on corrugated innovation for laptop and tablet shippers across Southeast Asia.
Asia-Pacific consumer electronics packaging encompasses protective enclosures engineered from corrugated fiberboard, molded pulp, expanded polystyrene, or thermoformed plastics, typically incorporating anti-static coatings, cushioning geometries, and tamper-evident closures to prevent damage during multi-modal transit from assembly plants to end consumers. Bags and blister packs lead volume in smartphone accessories and wearable accessories where minimal material and retail visibility matter. Boxes and trays command margin pools in laptop and premium tablet segments where structural integrity and unboxing experience differentiate brands. Foam and molded pulp are displacing virgin plastic in Samsung and Apple supplier ecosystems as ESG procurement standards harden.
China's SAMR enforces labeling and material safety rules for electronics packaging circulating domestically, while India's BIS certification mandates dimensional and load-bearing standards for export-bound consignments. Japan's METI circular economy guidelines pressure brands to design for disassembly and fiber recovery. Stakeholders must monitor how ASEAN harmonization of packaging waste directives reshapes cross-border material compliance and supplier qualification timelines.
Market Dynamics
China's SAMR recyclability mandates and India's BIS export certification are forcing material substitutions across the Asia-Pacific consumer electronics packaging value chain, compressing supplier qualification timelines and redrawing procurement maps for corrugated fiberboard and molded pulp enclosures.
Growth Catalysts
- E-commerce fulfillment acceleration:Smartphone and laptop OEMs in Guangdong and Jiangsu provinces are expanding protective packaging volumes to serve direct-to-consumer channels. Last-mile damage reduction specifications are tightening across major logistics networks.
- India's PLI scheme for electronics:Component packaging investments are clustering near Noida and Bengaluru assembly hubs as contract manufacturers qualify local corrugated and thermoformed suppliers.
- Molded pulp substitution:Expanded polystyrene cushioning is exiting Samsung and Apple supplier ecosystems under hardening ESG procurement standards. Fiber-based alternatives are capturing premium smartphone and tablet segments.
Market Restraints
- Recycled pulp input volatility:Old corrugated container prices fluctuate with China's waste import restrictions and domestic collection rates. Cost pass-through mechanisms remain underdeveloped for mid-tier packaging converters.
- Vietnam supply concentration:Samsung Electronics anchors disproportionate packaging demand through its vertically integrated smartphone assembly in Bac Ninh and Thai Nguyen provinces. Supplier diversification is structurally constrained.
- Anti-static coating technical gaps:Domestic Chinese and Indian producers lag European counterparts in conductive polymer formulations for high-value semiconductor shipments. Import dependency persists for premium electronics brands.
Strategic Opportunities
- Indonesia underpenetration:Laptop and tablet packaging demand is accelerating around Batam and Jakarta as OEMs diversify assembly footprints beyond China and Vietnam. Local corrugated capacity expansion lags end-market growth.
- Japan METI circular economy guidelines:Design-for-disassembly mandates are creating specification premiums for fiber recovery-optimized enclosures. Brands are qualifying packaging engineered for automated material separation.
- Smart packaging convergence:NFC-enabled authentication and tamper-evident closures are merging with structural protection. Pharmaceutical-grade serialization expertise is transferring to consumer electronics premium tiers.
Industry Challenges
- Cross-border compliance timeline compression:ASEAN harmonization of packaging waste directives is accelerating supplier requalification demands. Multi-country OEM footprints require simultaneous adherence to divergent national implementation schedules.
- Legacy thermoforming asset stranding:Virgin plastic capacity in Thailand and Malaysia faces utilization pressure as ESG procurement standards harden. Capital redeployment into fiber molding lines demands technical retooling and workforce reskilling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Consumer Electronics Packaging Market |
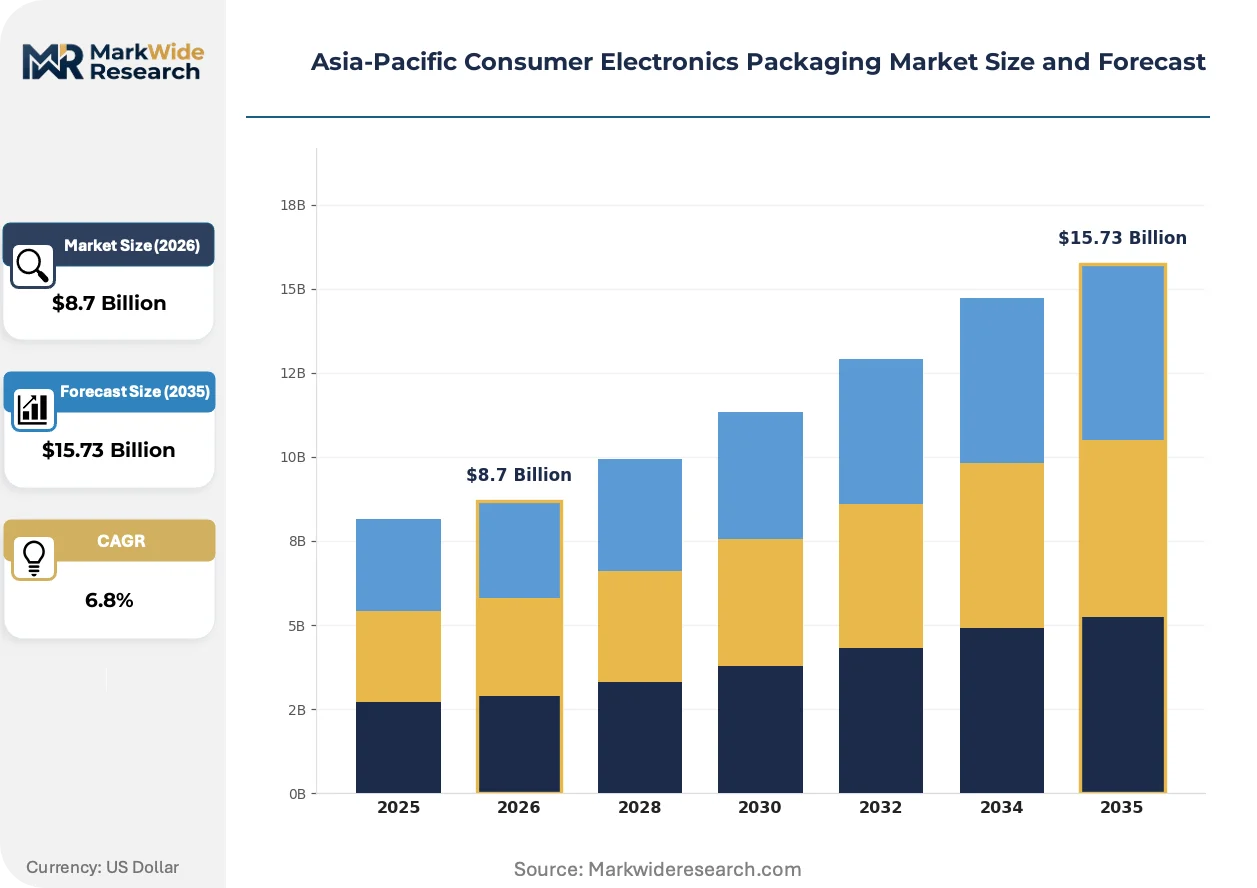
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bags, Boxes, Trays, Blister Packs Material: Cardboard, Plastic, Foam, Paper End User: Retailers, Distributors, Manufacturers, Ecommerce Product Type: Smartphones, Laptops, Tablets, Wearables |
| Companies Covered | Amkor Technology, ASE Technology Holding, Taiwan Semiconductor Manufacturing, Samsung Electronics, JCET Group, Sonoco Products Company, DS Smith, Smurfit Kappa Group, Sealed Air, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Consumer Electronics Packaging Market Trends and Innovations
Molded fiber engineering and smart authentication layers are compressing material specifications and procurement criteria across Asia-Pacific consumer electronics packaging. Three developments are restructuring competitive positioning.
Structural molded pulp is rewriting protective packaging economics for premium smartphones and tablets. Samsung and Apple supplier ecosystems are adopting fiber-based cushioning geometries that match expanded polystyrene drop-test performance. The technology is compressing virgin plastic share in high-margin segments where unboxing experience and sustainability credentials intersect.
China's GB standards for packaging recyclability are mandating material composition disclosures and fiber recovery rates for domestic circulation. SAMR enforcement is disqualifying multi-material laminates that impede automated sorting. Laptop and tablet shippers are redesigning enclosures to eliminate adhesive-dependent mixed-fiber constructions.
Unboxing experience specifications are elevating structural integrity and aesthetic finishing as procurement differentiators. Premium electronics brands are qualifying packaging converters on haptic quality and print fidelity metrics alongside protective performance. This behavior is most visible in China's tier-one cities where social media amplification of product reveals drives brand equity investments.
Asia-Pacific Consumer Electronics Packaging Market Segmentation
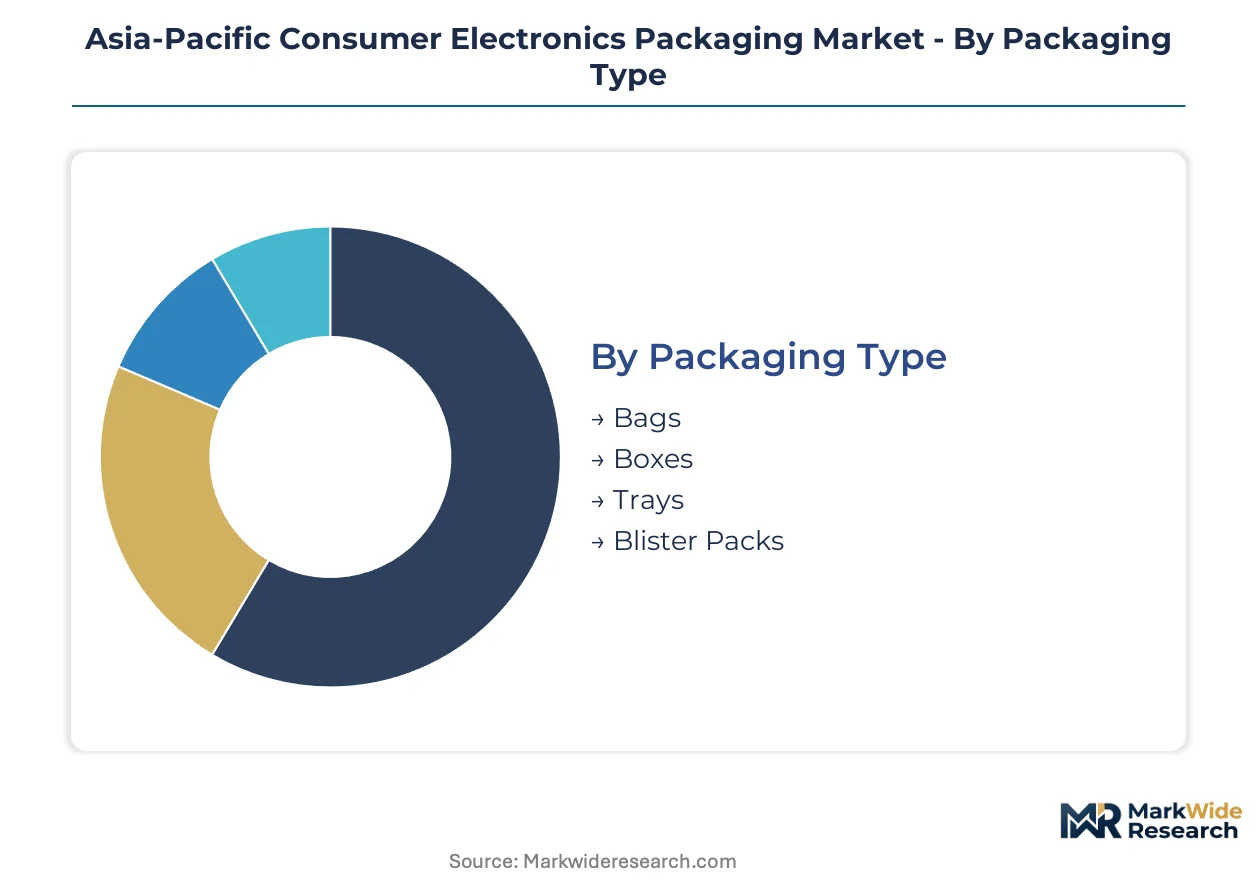
Segmentation in Asia-Pacific consumer electronics packaging reveals how protective requirements diverge across fulfillment channels and product fragility tiers. Material selection and structural design vary sharply between direct-to-consumer e-commerce flows and bulk retail distribution, while smartphone and laptop segments drive divergent specification investments.
Packaging Type:
Structural formats split between standalone protective enclosures and embedded cushioning systems integrated into master shipping containers.
- Boxes:Corrugated fiberboard enclosures with multi-layer flute configurations dominate laptop and premium tablet shipments through Guangdong and Jiangsu assembly clusters. SAMR recyclability mandates are compressing mixed-material constructions as brands redesign for automated fiber recovery.
- Trays:Thermoformed and molded pulp inserts provide structural nesting for smartphones during multi-modal transit from Vietnam and India assembly plants. Samsung's vertically integrated operations in Bac Ninh and Thai Nguyen provinces anchor specification development for drop-test performance.
- Bags:Polyethylene and kraft paper pouches serve smartphone accessories and wearable peripherals where minimal material weight reduces last-mile freight costs.
- Blister Packs:Clear thermoformed cavities with printed card backing deliver retail visibility for earbuds, charging cables, and screen protectors across Southeast Asian consumer electronics retail.
Volume placements concentrate in Boxes; the faster expansion belongs to Trays as molded pulp substitutes expand polystyrene displacement.
Material:
Cost tiers stratify procurement between commodity fiber inputs and engineered polymer formulations for high-value semiconductor protection.
- Cardboard:Recycled corrugated containerboard forms the structural backbone for laptop and tablet outer enclosures, with Old Corrugated Container price volatility in China creating margin pressure for mid-tier converters.
- Foam:Expanded polystyrene cushioning retains foothold in cost-sensitive smartphone segments despite ESG-driven exit pressures from Apple and Samsung supplier ecosystems. Molded pulp alternatives are gaining specification share fastest.
- Plastic:PET and PP thermoforms deliver retail visibility and moisture barriers for wearable accessories and charging peripherals across Indonesian and Philippine distribution networks.
- Paper:Molded fiber and kraft wrapping papers are displacing virgin plastic in premium unboxing experiences, with Japan METI circular economy guidelines accelerating design-for-disassembly adoption.
Cardboard captures the largest procurement volumes; molded fiber formulations within Paper are climbing the fastest as ESG procurement standards harden across OEM ecosystems.
End User:
Customer type determines structural complexity, with direct-to-consumer channels demanding damage-rate guarantees that bulk retail flows rarely match.
- Ecommerce:Direct-to-consumer smartphone and laptop shipments require enhanced drop-test specifications and tamper-evident closures as last-mile damage claims pressure logistics networks across China and India.
- Manufacturers:Component packaging for contract electronics assembly in Noida and Bengaluru clusters emphasizes anti-static coatings and cleanroom-compatible materials for semiconductor handling.
- Distributors:Bulk palletization and master carton efficiency drive specification for wholesale flows through Singapore and Hong Kong logistics hubs.
- Retailers:Shelf-ready packaging with print fidelity and hang-tab compatibility serves consumer electronics retail across tier-one Chinese cities and Japanese electronics chains.
Ecommerce channels are driving the steepest specification upgrades; Manufacturer-directed procurement maintains the tightest qualification timelines for anti-static technical compliance.
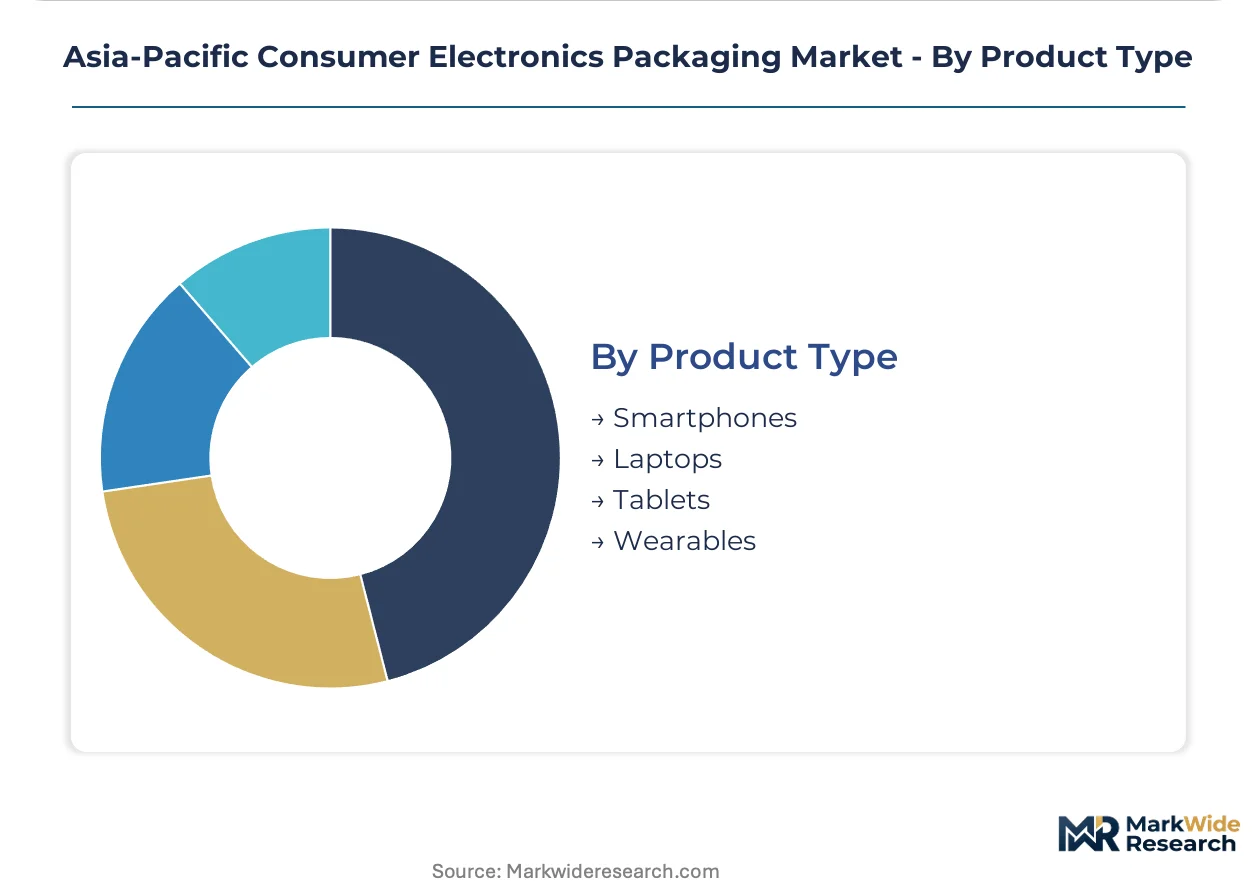
Product Type:
Fragility and unit value determine protective packaging investment intensity, with premium tiers separating from mass-market through unboxing experience engineering.
- Smartphones:High-velocity SKUs with slim form factors require precision-fit molded pulp or foam cushioning, with social media unboxing amplification in Chinese tier-one cities driving haptic quality investments.
- Laptops:Larger dimensional footprints and higher unit values command multi-layer corrugated enclosures with corner protection and premium print finishing for brand differentiation.
- Tablets:Intermediate fragility and growing direct-to-consumer volumes are accelerating molded pulp tray adoption as brands balance protection weight against sustainability credentials.
- Wearables:Small form factors and accessory bundling favor minimal-material blister and bag configurations with retail visibility prioritization over structural cushioning.
Smartphones absorb the deepest packaging engineering investment per unit; Wearables are expanding volume fastest as earbud and smartwatch shipments multiply across Asia-Pacific consumer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's bonded zones in Guangdong and Jiangsu provinces concentrate electronics assembly and packaging procurement. India's PLI scheme for electronics manufacturing is redirecting component packaging investments toward Noida and Bengaluru clusters. Vietnam's Bac Ninh and Thai Nguyen provinces anchor Samsung's vertically integrated smartphone assembly and captive packaging demand.
China
Guangdong and Jiangsu provinces host the densest OEM assembly clusters for smartphones and laptops. SAMR enforces GB standards for packaging recyclability that disqualify multi-material laminates. Dongguan and Suzhou converters are retooling lines to eliminate adhesive-dependent mixed-fiber constructions.
India
Noida and Bengaluru assembly hubs are scaling protective packaging volumes under the PLI scheme for electronics manufacturing. BIS certification mandates dimensional and load-bearing standards for export-bound consignments. Local corrugated and thermoformed suppliers near these clusters are qualifying for contract manufacturer procurement.
Vietnam
Bac Ninh and Thai Nguyen provinces concentrate Samsung Electronics' vertically integrated smartphone assembly. This concentration anchors disproportionate packaging demand for molded pulp trays and corrugated master cartons. Supplier diversification remains structurally constrained by the scale of single-anchor demand.
Japan
Kanto region electronics brands face METI circular economy guidelines pressuring design-for-disassembly specifications. Fiber recovery-optimized enclosures command specification premiums as automated material separation requirements harden. Tokyo-based packaging engineers are qualifying converters on automated sorting compatibility.
Indonesia
Batam and Jakarta are accelerating laptop and tablet packaging demand as OEMs diversify assembly footprints beyond China and Vietnam. Local corrugated capacity expansion lags end-market growth. Import-dependent converters are capturing premium segments while domestic mid-tier supply struggles to scale.
Asia-Pacific Consumer Electronics Packaging Market Competitive Landscape
European producers anchor one tier through design expertise and sustainability credentials; Asia-Pacific specialists hold volume positions through proximity to OEM assembly clusters. The market structures around three tiers: multinational fiberboard converters with regional design centers, domestic Chinese and Indian corrugated specialists serving mid-tier electronics brands, and captive packaging operations integrated into Samsung and Apple supplier ecosystems. Capacity expansion and molded pulp technology licensing represent the dominant competitive moves as ESG procurement standards harden.
Within the multinational converter tier, DS Smith and Smurfit Kappa Group exemplify European-origin players leveraging sustainability credentials and corrugated innovation to serve premium electronics brands in Shanghai, Shenzhen, and across Southeast Asia. Samsung Electronics occupies a distinctive position as both anchor customer and vertically integrated producer through its captive packaging demand in Vietnam and India. These three entities represent the spectrum from independent converter to integrated OEM, illustrating how procurement power and geographic proximity interact in supplier qualification.
| Leading Market Players |
|---|
| Amkor Technology |
| ASE Technology Holding |
| Taiwan Semiconductor Manufacturing |
| Samsung Electronics |
| JCET Group |
| Sonoco Products Company |
| DS Smith |
| Smurfit Kappa Group |
| Sealed Air |
| Others |
Pricing and Supply Chain Analysis
Old Corrugated Container price indices in China cascade through Asia-Pacific consumer electronics packaging tiers, compressing margins for mid-tier converters while premium molded pulp specifications command stability through Samsung and Apple supplier ecosystems.
Pricing Analysis
Short lead-time premiums separate contract pricing from spot procurement across Guangdong and Jiangsu converter networks. Three-tier pricing structure across premium, standard, and economy levels stratifies by fiber recovery certification under SAMR GB standards and anti-static coating technical grade. Pricing pressure stems from recycled pulp input volatility as China's waste import restrictions tighten collection economics. Contract manufacturers in Noida and Bengaluru exhibit highest price sensitivity; premium electronics brands in Chinese tier-one cities prioritize specification compliance over unit cost.
Supply Chain Analysis
Workforce availability constraints in Vietnam's Bac Ninh and Thai Nguyen provinces limit supplier diversification around Samsung's vertically integrated operations. Raw material flows draw from Chinese OCC collection networks, Thai petrochemical feedstocks for thermoformed plastics, and Indonesian pulp plantations for molded fiber expansion. Single-source vulnerability concentrates in Vietnam's Samsung-anchored demand cluster. Distribution runs through Singapore and Hong Kong logistics hubs for regional wholesale flows, with direct-to-consumer e-commerce channels bypassing traditional tiering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific consumer electronics packaging is becoming a vertical-integration race as OEMs pursue captive molded pulp capacity to harden ESG procurement compliance and compress supplier qualification timelines.
For Market Incumbents: Anchor specification control through backward integration into molded fiber engineering capabilities near Vietnam and India assembly clusters. Defend against European converter design expertise by accelerating SAMR GB-compliant fiber recovery certifications. Prioritize anti-static coating R&D partnerships to reduce import dependency for semiconductor-grade protection.
For New Entrants and Emerging Players: Smart packaging authentication layers offer technology-first wedge into premium smartphone and tablet tiers where NFC-enabled tamper evidence commands specification premiums. Target Indonesia's underpenetrated laptop packaging demand around Batam assembly diversification. Lead with pharmaceutical-grade serialization expertise transfer to electronics unboxing experience engineering.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier corrugated specialists with SAMR certification infrastructure in Jiangsu and Guangdong provinces facing OCC price volatility compression. Long-term viability rests on converter positioning for Japan METI circular economy compliance and automated fiber recovery compatibility. Monitor ASEAN packaging waste directive harmonization schedules as inflection triggers for cross-border supplier requalification waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Molded Pulp Capacity Expansion | Captures ESG-driven polystyrene substitution demand from Samsung and Apple ecosystems. |
| Anti-Static Coating Technology Licensing | Reduces import dependency for semiconductor-grade protection in Noida and Bengaluru hubs. |
| Smart Packaging Authentication Integration | Merges NFC serialization with structural protection for premium unboxing experiences. |
| Backward Integration into Fiber Recovery | Secures OCC supply chain stability amid China's waste import restriction volatility. |
| Regional Design Center Establishment | Positions European sustainability credentials proximate to Shanghai and Shenzhen OEM procurement. |
Research Methodology
Multi-period observation of Old Corrugated Container price movements, SAMR enforcement patterns, and OEM supplier qualification timelines anchored the trend analysis, supplemented by interviews with packaging converters, contract manufacturer procurement leads, logistics network operators, and sustainability compliance officers. Secondary validation drew from Chinese customs trade data, BIS certification registries, METI circular economy guideline releases, and ASEAN harmonization draft directives. Bottom-up volume modeling across material types and top-down demand triangulation from assembly cluster outputs were cross-referenced for convergence.
Segment-weighting approaches distributed value across packaging type, material composition, end-user channel, and product fragility tier throughout the projection horizon. CAGRs were derived from fitted growth curves against historical e-commerce penetration rates and PLI scheme investment trajectories. Forecast inputs incorporated molded pulp substitution elasticities and anti-static coating technical adoption thresholds specific to semiconductor handling requirements.
Several conditions sit outside the modeled scope, including abrupt SAMR enforcement escalations, Samsung vertical integration scope expansion, and ASEAN directive implementation delays. Forecasts reflect documented assumptions on ESG procurement standard hardening velocity and fiber recovery technology cost curves. Material deviation in OCC price volatility, PLI scheme renewal terms, or METI disassembly mandate enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronics Packaging
Fan-Out Wafer Level Packaging Market
Electronics Packaging
Consumer Electronics Packaging Market
Electronics Packaging
Electronic Goods Packaging Market
Electronics Packaging
MEMS Packaging Solder Market
Electronics Packaging
Multi-Chip Module Packaging Market
Electronics Packaging
Electronic Wrapper Market
Electronics Packaging
Anti-Counterfeit Electrical and Electronics Packaging Market
Electronics Packaging
Power Module Packaging Market
Electronics Packaging
Europe Consumer Electronics Packaging Market
Electronics Packaging
Industrial Electronics Packaging Market
Electronics Packaging
Global Display Packaging Market
Electronics Packaging
North America Consumer Electronics Packaging Market
Electronics Packaging
Global Mobile Phones Packaging Market
Electronics Packaging
Mobile Phone Accessories Packaging Market
Electronics Packaging
Asia-Pacific Battery Packaging Market
Electronics Packaging
Electronic Packaging Market