
 MEMS Packaging Solder Market | 2026-2036
MEMS Packaging Solder Market Size, Share, and Industry Trends Forecast 2026-2036
MEMS Packaging Solder Market Insights
EU REACH compliance deadlines for hazardous substance restrictions is pivoting solder alloy development priorities across the MEMS packaging supply chain. Indium Corporation specializes in indium-bearing and lead-free formulations for thermal cycling endurance in hermetic packages. Henkel AG & Co. KGaA dominates adhesive and solder material portfolios for flip-chip MEMS assemblies. Senju Metal Industry Co., Ltd. anchors Asian supply chains with refined bar and paste products for precision die-attach operations.
MEMS packaging solder denotes fusible metal alloys—typically tin-silver-copper, tin-bismuth, or indium-based compositions with melting points between 139°C and 221°C—applied to create permanent mechanical and electrical joints between MEMS dies, substrates, and protective caps during hermetic or near-hermetic sealing. These alloys must withstand thermal cycling, outgassing constraints, and coefficient-of-thermal-expansion mismatches unique to micromachined silicon structures. Lead-free solder formulations now lead product type demand as OEMs eliminate exemptions under RoHS-derived frameworks, while paste form factors capture the fastest growth trajectory due to stencil-printing compatibility with shrinking pad geometries in consumer electronics and medical device end user segments. Reflow technology maintains the largest installed base but selective soldering is gaining share for temperature-sensitive MEMS gyroscopes and pressure sensors.
FDA device-quality regulations, EPA toxic substance reporting under TSCA, and ISO 10993 biocompatibility standards collectively elevate qualification burdens for solder materials entering medical device and implantable MEMS channels. Japan's METI enforces JIS standards for electronic-grade solder purity that directly shape import acceptance criteria for foreign alloy suppliers. Stakeholders must monitor evolving alloy composition restrictions and thermal performance benchmarks as automotive safety-critical MEMS deployment expands.
Market Dynamics
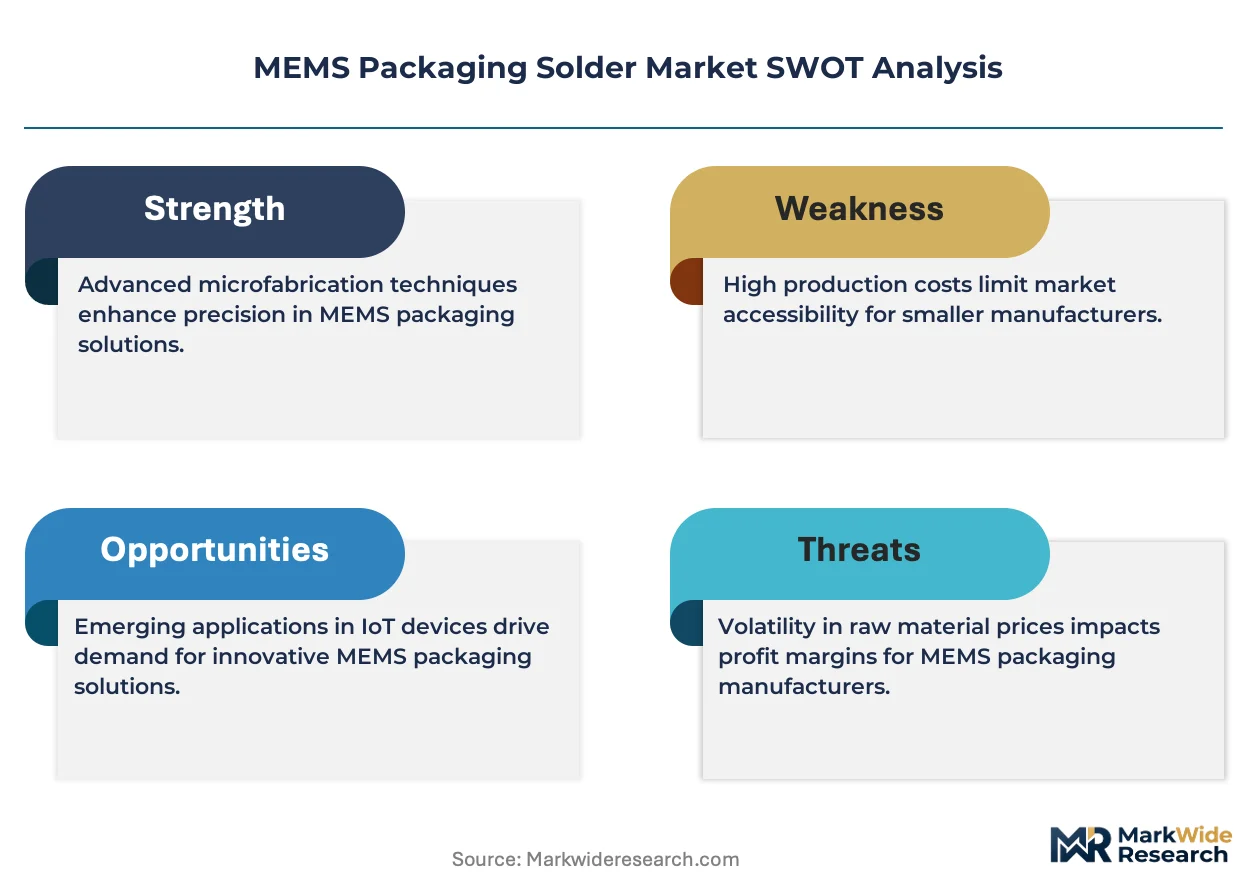
EU REACH substance restrictions are forcing alloy reformulation across MEMS packaging supply chains, redirecting R&D investment from legacy tin-lead systems toward silver-copper and bismuth-tin alternatives while compressing qualification timelines for automotive lidar and aerospace inertial sensor platforms.
Growth Catalysts
- Automotive lidar deployment:Tier-one OEMs in Germany and Japan are scaling hermetic sensor module production, consuming high-reliability solder interconnects for thermal cycling endurance.
- RoHS exemption phase-outs:The European directive's tightening timelines are eliminating lead-content waivers, mandating lead-free paste adoption across consumer electronics MEMS packaging lines.
- Medical device biocompatibility mandates:ISO 10993 compliance requirements for implantable MEMS are creating premium solder specification tiers with enhanced purity thresholds.
Market Restraints
- Indium supply concentration:Over 80 percent of refined indium originates from Chinese smelters, exposing alloy formulators to export restriction risk and price volatility.
- Silver cost inflation:Precious metal price swings in SAC305 and SAC387 alloys are compressing margins for high-volume consumer electronics assemblers.
- Coefficient-of-thermal-expansion mismatch:Silicon MEMS dies and ceramic substrates require engineered solder compositions that extend qualification cycles by 12-18 months.
Strategic Opportunities
- Flip-chip MEMS penetration in wearables:Apple and Samsung supply chains are adopting wafer-level solder bumping for miniaturized biometric sensors, opening paste formulation contracts.
- India PLI scheme for electronics:Domestic MEMS foundry incentives under the Production-Linked Incentive program are attracting solder material localization investments from Japanese suppliers.
- Selective soldering retrofit:Temperature-sensitive pressure sensor manufacturers are replacing reflow ovens with laser-assisted bonding systems, creating equipment-alloy bundled service models.
Industry Challenges
- Hermeticity test technician scarcity:Fine leak detection and helium mass spectrometry expertise is concentrated among aging workforces in German and Japanese packaging houses.
- Dual certification burden:Suppliers must simultaneously satisfy AEC-Q100 automotive stress test qualifications and FDA 21 CFR Part 820 quality system regulations for multi-sector customers.
- Alloy intellectual property thickets:Indium Corporation and Senju Metal Industry patent estates around low-alpha solder compositions are complicating new entrant formulation freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MEMS Packaging Solder Market |
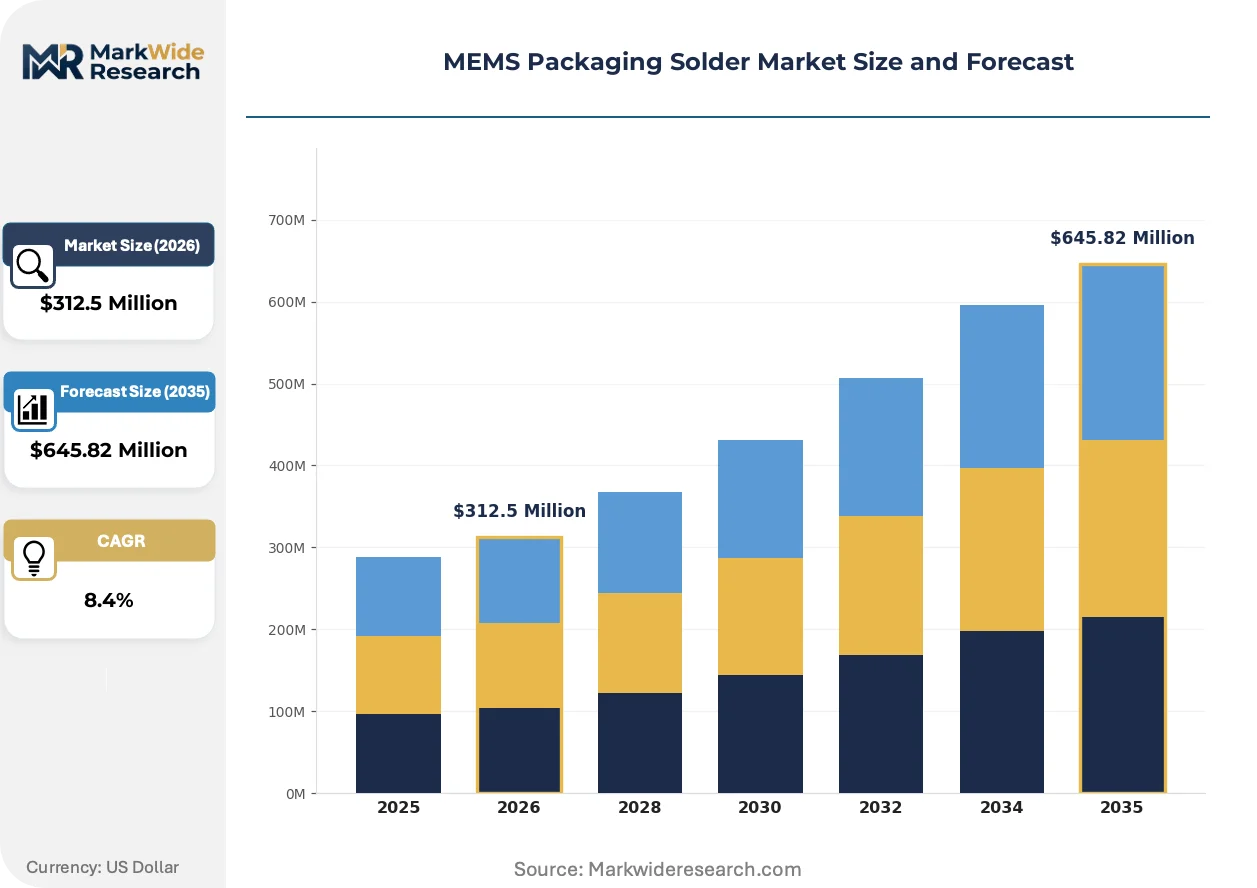
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-based Solder, Lead-free Solder, Silver-based Solder, Specialty Alloys End User: Consumer Electronics, Automotive Applications, Telecommunications, Medical Devices Form: Wire, Paste, Bar, Preform Technology: Reflow, Wave, Selective Soldering, Manual Soldering |
| Companies Covered | Indium Corporation, Henkel AG & Co. KGaA, Senju Metal Industry Co., Ltd., Amkor Technology, Inc., ASE Group, STATS ChipPAC Ltd., Alpha Assembly Solutions, AIM Solder, Kester, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MEMS Packaging Solder Market Trends and Innovations
Alloy development is pivoting toward thermal fatigue resistance as automotive safety-critical MEMS deployment accelerates, while stencil-printing process control and reflow atmosphere management are emerging as differentiable technical capabilities among material suppliers.
SAC305 (tin-silver-copper) is consolidating as the default lead-free alloy for consumer electronics MEMS packaging despite its higher melting point versus tin-lead predecessors. Smartphone and TWS earbud manufacturers are accepting the 217°C liquidus temperature to secure RoHS compliance without sacrificing joint reliability. This consolidation is compressing demand for experimental bismuth-tin formulations that previously targeted low-temperature applications.
Japan's METI is enforcing revised JIS Z 3282 standards for electronic-grade solder purity that now include stricter limits on cadmium and bismuth contaminants. Foreign alloy suppliers must demonstrate batch-level traceability to gain import acceptance at precision MEMS foundries in Kyoto and Nagoya. Medical device assemblers are absorbing the compliance cost premium to maintain access to Japanese substrate bonding markets.
Consolidated procurement contracts are displacing spot purchasing for high-volume MEMS assemblers in Taiwan and South Korea. Foxconn and Luxshare-ICT are negotiating multi-year solder paste supply agreements with fixed price collars and dedicated technical service teams. This shift is most visible in camera module and microphone packaging lines where annual solder consumption exceeds 50 metric tons per facility.
MEMS Packaging Solder Market Segmentation
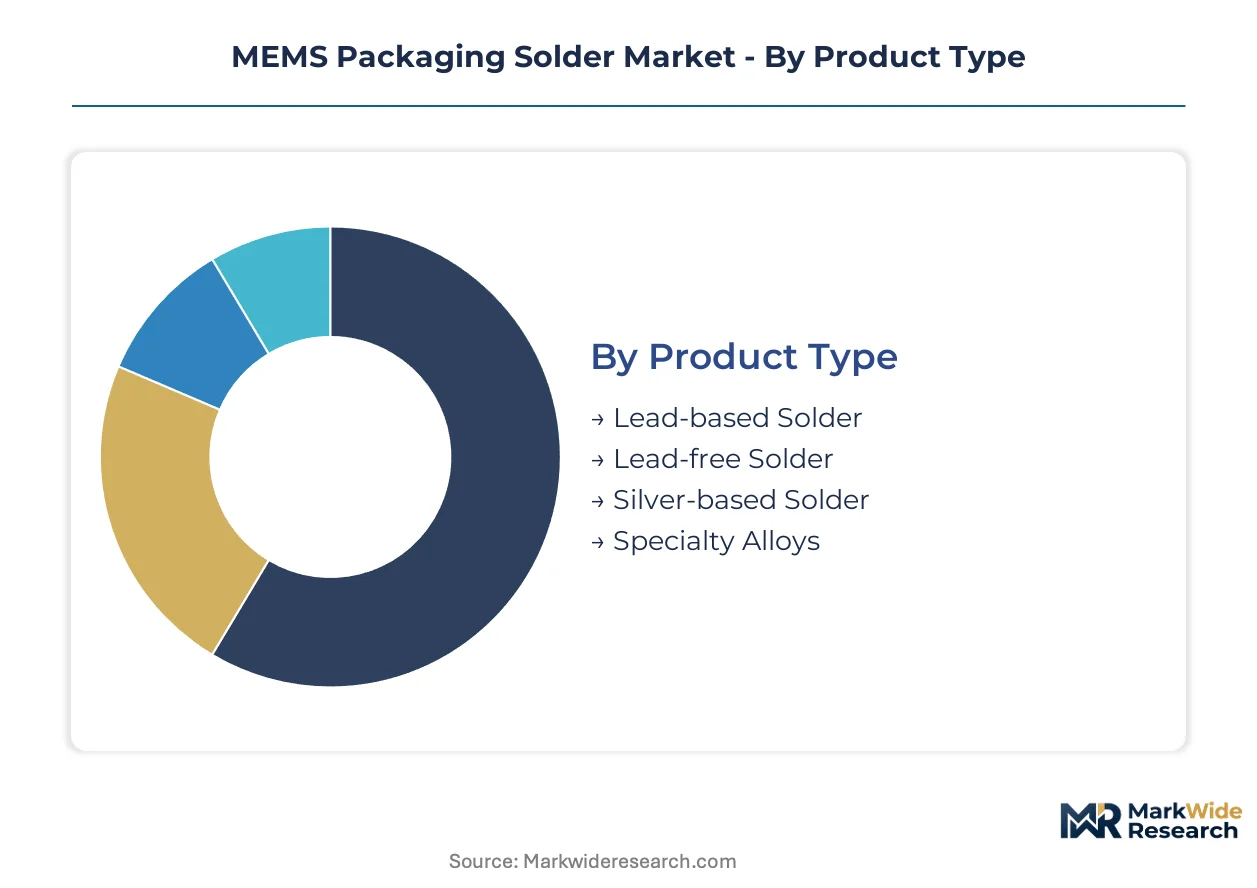
MEMS packaging solder segments diverge sharply in capital requirements and technical qualification burdens. Alloy purity thresholds and bonding equipment specifications create tiered entry barriers that reshape competitive positioning across formulation types and application methods.
Product Type:
Lead-free solder formulations demand the heaviest upfront investment in vacuum induction melting infrastructure and contamination-controlled casting environments. Capital intensity drops progressively through silver-based alloys, specialty compositions, and legacy lead-bearing systems.
- Lead-free Solder:SAC305 and SAC387 tin-silver-copper compositions dominate automotive lidar and consumer electronics packaging lines. RoHS exemption phase-outs in Germany and Japan are mandating wholesale line conversions at tier-one EMS providers. Hermetic sealing qualification cycles extend 14-18 months for these alloys.
- Silver-based Solder:High-purity SAC compositions with elevated silver content target medical implantable MEMS requiring ISO 10993 biocompatibility certification. Precious metal price volatility compresses margins for high-volume assemblers in South Korea.
- Lead-based Solder:Legacy tin-lead eutectic persists in aerospace and defense MEMS exempted from RoHS directives.
- Specialty Alloys:Indium-bearing and bismuth-tin compositions address coefficient-of-thermal-expansion mismatches in pressure sensor die-attach.
Most installed capacity flows through Lead-free Solder. Expansion is steepest in Silver-based Solder.
End User:
Automotive Applications concentrate the highest value-per-kilogram demand, while Consumer Electronics generates volume scale that amortizes formulation R&D across massive unit throughput.
- Automotive Applications:Hermetic sensor modules for lidar and inertial measurement units require thermal cycling endurance across -40°C to 150°C operating ranges. German OEMs in Stuttgart and Munich are qualifying second-source solder suppliers for safety-critical platforms.
- Consumer Electronics:Smartphone camera modules and TWS microphone assemblies consume paste formulations in 50-metric-ton annual quantities at single Foxconn facilities. Stencil-printing process control separates qualified from marginal suppliers.
- Medical Devices:Implantable MEMS for glucose monitoring and cardiac pacing demand batch-level traceability and low-alpha emission specifications.
- Telecommunications:5G base station timing oscillators and filter packages prioritize reflow compatibility with ceramic substrates.
Automotive Applications command premium pricing tiers. Consumer Electronics is gaining share fastest.
Form:
Paste formulations require the most sophisticated downstream technical service investment, including stencil design support and reflow profile optimization.
- Paste:Type 4 and Type 5 powder particle distributions enable stencil-printing of 200-micron pad geometries in miniaturized biometric sensors. Apple and Samsung supply chains are consolidating procurement around qualified paste suppliers with dedicated technical teams.
- Wire:Flux-cored and solid wire forms serve manual rework and selective soldering operations for temperature-sensitive gyroscope packages.
- Bar:Cast bar products feed wave soldering systems for through-hole MEMS microphone assemblies.
- Preform:Precision-cut preforms target high-reliability die-attach in aerospace inertial sensors.
Paste carries the largest revenue base. Preform applications are climbing the fastest.
Technology:
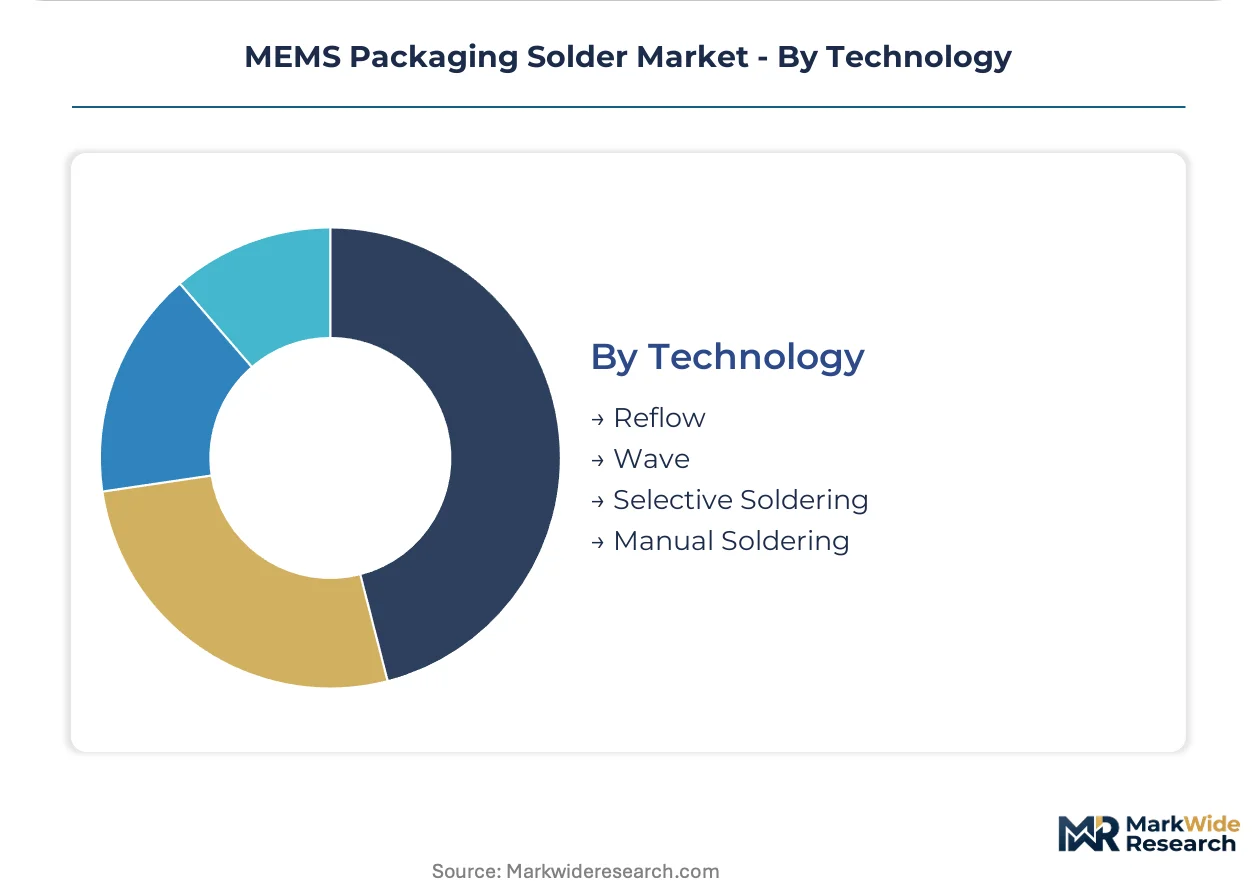
Reflow soldering demands the most capital-intensive thermal processing infrastructure, while selective soldering systems offer retrofit pathways for temperature-constrained MEMS designs.
- Reflow:Convection and vapor phase reflow ovens maintain the dominant installed base across consumer electronics packaging lines. Atmosphere control with nitrogen inerting prevents oxidation of lead-free alloy joints during peak temperature exposure.
- Selective Soldering:Laser-assisted and mini-wave systems are displacing batch reflow for pressure sensor modules where silicon die temperatures must stay below 200°C. Equipment-alloy bundled service models are emerging from Japanese suppliers.
- Wave Soldering:Legacy through-hole MEMS microphone packaging persists at high-volume EMS facilities in Taiwan.
- Manual Soldering:Rework and prototype operations retain skilled technician dependency.
Reflow dominates current capacity. Selective Soldering shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision MEMS packaging technicians cluster around automotive and aerospace manufacturing corridors in Germany, Japan, and the United States. These three countries anchor the industry's talent base and concentrate hermetic sealing expertise for safety-critical sensor modules.
Germany
Stuttgart and Munich host tier-one automotive OEMs scaling lidar sensor production for autonomous driving platforms. REACH substance restrictions under ECHA enforcement are accelerating lead-free solder line conversions at EMS facilities. The Baden-Württemberg precision cluster around Stuttgart qualifies second-source solder suppliers for thermal cycling endurance specifications.
Japan
Kyoto and Nagoya foundries supply high-reliability die-attach materials for inertial measurement units in aerospace applications. METI enforces revised JIS Z 3282 purity standards that restrict cadmium and bismuth contaminants in electronic-grade solder. The Chubu region around Nagoya maintains specialized helium mass spectrometry capacity for hermeticity validation.
United States
FDA-regulated medical device assemblers in Minnesota and Massachusetts demand ISO 10993-certified solder for implantable glucose monitors and cardiac pacing systems. EPA toxic substance reporting under TSCA elevates batch-level traceability requirements for alloy suppliers. The Twin Cities corridor concentrates hermetic packaging expertise for defense-aerospace MEMS exempted from RoHS directives.
South Korea
Foxconn and Luxshare-ICT suppliers in Gyeonggi Province consume 50-metric-ton annual solder paste quantities for smartphone camera modules. The national semiconductor regulator aligns import inspection protocols with JIS purity benchmarks. Seoul Capital Area packaging houses are consolidating procurement around multi-year supply agreements with fixed price collars.
India
Domestic MEMS foundry incentives under the PLI scheme are attracting Japanese solder material localization investments. BIS certification requirements for electronic-grade alloys are tightening import substitution timelines. Karnataka's electronics manufacturing cluster near Bangalore is qualifying stencil-printing process control for miniaturized biometric sensor assemblies.
MEMS Packaging Solder Market Competitive Landscape
The competitive structure tilts toward formulation specialists with vacuum induction melting infrastructure and contamination-controlled casting environments. Three archetypes dominate: precious metal alloy refiners serving medical implantable channels, high-volume paste formulators integrated with consumer electronics EMS supply chains, and equipment-alloy bundled service providers targeting selective soldering retrofits. Capacity expansion and strategic technical service partnerships constitute the dominant competitive moves.
Within the formulation specialist tier, Indium Corporation and Senju Metal Industry Co., Ltd. exemplify precious metal and indium-bearing alloy expertise, while Henkel AG & Co. KGaA occupies a position bridging adhesive and solder material portfolios for flip-chip assemblies. These three entities anchor the premium specification segment where hermetic sealing qualification cycles extend 14-18 months.
| Leading Market Players |
|---|
| Indium Corporation |
| Henkel AG & Co. KGaA |
| Senju Metal Industry Co., Ltd. |
| Amkor Technology, Inc. |
| ASE Group |
| STATS ChipPAC Ltd. |
| Alpha Assembly Solutions |
| AIM Solder |
| Kester |
| Others |
Pricing and Supply Chain Analysis
Multi-year procurement contracts with fixed price collars from Foxconn and Luxshare-ICT are forcing solder paste suppliers to absorb silver price volatility while maintaining dedicated technical service teams, compressing margins for high-volume consumer electronics formulators and accelerating consolidation around integrated equipment-alloy service models.
Pricing Analysis
Bundled equipment-alloy service contracts from Japanese suppliers are displacing spot purchasing for selective soldering retrofits in temperature-sensitive pressure sensor lines. Price differentiation hinges on ISO 10993 biocompatibility certification tier and stencil-printing technical support depth. Cost compression in SAC305 alloys is intensifying because precious metal price swings outpace pass-through clauses. Consumer electronics assemblers in South Korea exhibit the highest price sensitivity, while medical device OEMs in Minnesota accept premium tiers for batch traceability.
Supply Chain Analysis
Indium supply rests on Chinese smelters controlling over 80 percent of refined output, exposing alloy formulators to export restriction risk. The supply chain draws from Japanese vacuum induction melting capacity for high-purity electronic-grade alloys and German precision casting infrastructure for hermetic sealing applications. Raw material dependencies span silver bullion, tin concentrate, and rare earth refining byproducts. Single-source vulnerability concentrates in indium feedstock. Distribution runs through qualified distributor networks serving tier-one EMS facilities in Taiwan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MEMS packaging solder market functions as a stable compounder anchored by automotive safety-critical sensor deployment, where hermetic sealing qualification cycles extending 14-18 months create durable supplier-customer lock-in and recurring formulation refresh revenue.
For Market Incumbents: Acquire helium mass spectrometry testing capacity and certified technician teams to address the aging workforce concentration in German and Japanese packaging houses. Consolidate formulation IP around low-alpha solder compositions to complicate new entrant freedom-to-operate. Add vacuum induction melting capacity in the Czech Republic or Poland to hedge REACH compliance cost escalation and serve Stuttgart OEM clusters with regional technical service. For New Entrants and Emerging Players: Enter via stencil-printing process control specialization for miniaturized biometric sensors in India PLI-subsidized foundries, where domestic qualification timelines remain shorter than import substitution hurdles. Target Karnataka electronics manufacturing clusters near Bangalore with localized paste formulation and dedicated reflow profile optimization teams. Pursue equipment-alloy bundled service contracts for laser-assisted selective soldering retrofits displacing batch reflow in pressure sensor packaging. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap alloy formulators holding JIS Z 3282-certified purity infrastructure and established relationships with Kyoto and Nagoya precision MEMS foundries. The 5-10 year viability window favors targets with medical device channel access and automotive AEC-Q100 qualification track records. Watch for indium export restriction announcements from Chinese authorities as the critical inflection signal for supply chain restructuring and price spike realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indium Refining | Captive supply of critical feedstock insulates margins from Chinese export volatility. |
| Medical Device Certification Investment | ISO 10993 compliance opens premium pricing tiers for implantable MEMS channels. |
| Selective Soldering Equipment Partnership | Laser-assisted bonding bundling creates switching costs for temperature-sensitive gyroscope manufacturers. |
| Regional Technical Service Expansion | Dedicated reflow optimization teams in India PLI clusters accelerate localization timelines. |
| Hermeticity Testing Capacity Acquisition | Helium mass spectrometry expertise scarcity in aging German workforces commands scarcity rents. |
Research Methodology
Direct dialogue with solder alloy formulators, MEMS packaging engineers at tier-one automotive OEMs, EMS procurement directors, and hermeticity test technicians grounded the qualitative foundation. Secondary validation drew from ECHA REACH substance restriction filings, METI JIS standard revision notices, FDA 510(k) implantable device submissions, and SEC 10-K disclosures from listed materials suppliers. Bottom-up segment sizing triangulated against top-down end-use consumption models across automotive lidar, consumer electronics, and medical device channels.
Bottom-up volume modeling by alloy composition, form factor, and bonding technology combined with top-down OEM procurement spend analysis across the projection horizon. Segmentation dimensions spanned product type, end user, form, and technology, with regional regulatory cluster overlays for REACH, RoHS, and JIS compliance tiers. CAGRs derived from fitted growth curves incorporating automotive sensor unit forecasts and medical device implantable MEMS adoption trajectories.
Inputs from hermetic packaging technicians and alloy supplier technical directors were available through the study window; gaps in real-time indium spot price volatility and Chinese export policy timing introduce uncertainty bands around cost pass-through assumptions. Forecasts reflect documented assumptions on RoHS exemption phase-out adherence and PLI scheme disbursement pacing. Regulatory acceleration in EU substance restrictions, indium supply disruption, or automotive lidar deployment delays represent the small set of named triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronics Packaging
Electronic Goods Packaging Market
Electronics Packaging
Mobile Phone Accessories Packaging Market
Electronics Packaging
Global Mobile Phones Packaging Market
Electronics Packaging
Asia-Pacific Consumer Electronics Packaging Market
Electronics Packaging
Multi-Chip Module Packaging Market
Electronics Packaging
Anti-Counterfeit Electrical and Electronics Packaging Market
Electronics Packaging
Europe and USA Consumer Electronics Packaging Market
Electronics Packaging
Fan-Out Wafer Level Packaging Market
Electronics Packaging
North America Consumer Electronics Packaging Market
Electronics Packaging
Electronic Wrapper Market
Electronics Packaging
Power Module Packaging Market
Electronics Packaging
Industrial Electronics Packaging Market
Electronics Packaging
Europe Consumer Electronics Packaging Market
Electronics Packaging
Global Display Packaging Market
Electronics Packaging
Asia-Pacific Battery Packaging Market
Electronics Packaging
Consumer Electronics Packaging Market