
 North America Consumer Electronics Packaging Market | 2026-2036
North America Consumer Electronics Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Consumer Electronics Packaging Market Insights
E-commerce fulfillment channels is fragmenting across North America as direct-to-consumer electronics shipments multiply. Sealed Air leverages automated packaging systems to capture volume in high-velocity distribution centers. WestRock anchors corrugated substrate supply through integrated mill networks serving Mexico, the US, and Canada. JOHNSBYRNE differentiates through specialty finishing and graphic capabilities targeting premium unboxing experiences.
Consumer electronics packaging encompasses protective enclosures engineered from corrugated fiberboard, molded pulp, expanded polystyrene, and thermoformed plastics, typically specified to ECT ratings between 32 and 44 pounds per inch for stacking performance during palletized distribution. The primary purpose centers on damage prevention, brand presentation, and reverse logistics facilitation for devices ranging from smartphones to large-format displays. Folding cartons dominate unit volume for accessories and smaller devices due to flat-pack efficiency and printability, while rigid boxes concentrate margin pools in flagship smartphone and wearable launches where unboxing rituals drive consumer engagement. Flexible pouches represent the fastest-expanding format for cable and peripheral categories as brands reduce cube and freight cost.
The US EPA oversees sustainable materials management guidelines that push OEMs toward recycled content verification, while Health Canada and PMRA coordinate extended producer responsibility frameworks affecting post-consumer packaging recovery rates. The US FTC Green Guides constrain environmental marketing claims on electronics packaging, forcing substantiation of biodegradable and recyclable assertions. Stakeholders must monitor pending state-level packaging EPR legislation across California, New York, and Washington to anticipate compliance cost redistribution between brands and converters.
Market Dynamics
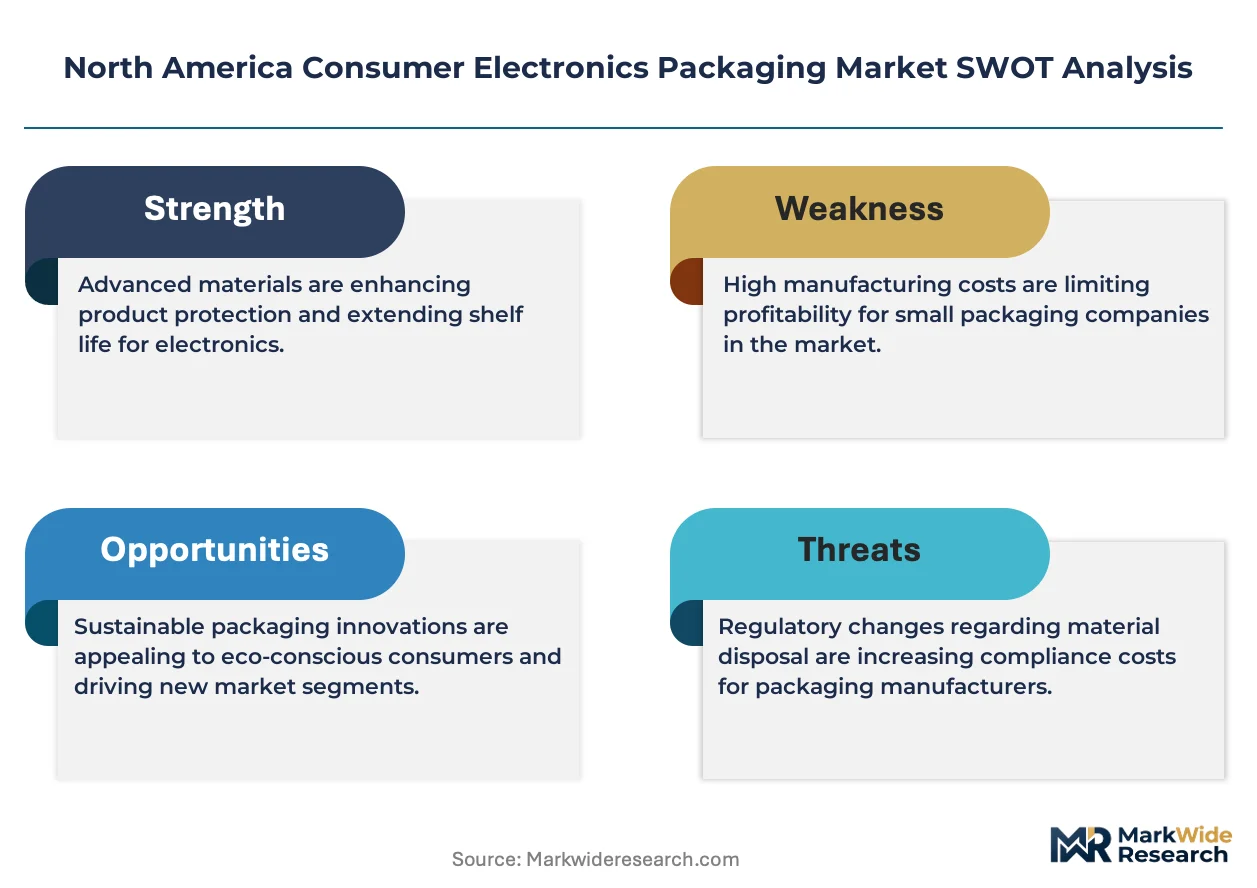
Smartphone OEM procurement of molded fiber trays is expanding across North America as the US EPA sustainable materials management initiative and Canada's single-use plastic regulations accelerate material transitions away from petroleum-based protective packaging.
Growth Catalysts
- California's Silicon Valley logistics corridor:Concentrated electronics assembly and fulfillment operations generate sustained demand for high-velocity packaging formats optimized for automated handling systems.
- Canada's single-use plastic regulations:Federal restrictions on expanded polystyrene foodware and packaging create regulatory pull toward molded pulp and fiber-based alternatives in Ontario's electronics assembly belt.
- Molded fiber thermoforming:Advances in precision molding technology enable protective geometries previously achievable only with petroleum-based foams, opening substitution pathways for fragile device categories.
Market Restraints
- Old corrugated container price volatility:OCC feedstock costs fluctuate with residential recycling collection rates and Chinese import policy shifts, compressing converter margins on recycled-content specifications.
- Resin supply concentration:Thermoformed PET and rPET substrate availability depends on Gulf Coast petrochemical complex output, exposing electronics brands to hurricane-related production interruptions.
- Moisture sensitivity thresholds:Molded pulp protective structures exhibit performance degradation above relative humidity levels that corrugated fiberboard tolerates, limiting deployment in unconditioned distribution legs.
Strategic Opportunities
- Mexico electronics manufacturing expansion:Nearshoring of smartphone and wearable assembly from Asia creates demand for localized packaging supply chains serving Baja California and Guanajuato industrial corridors.
- Extended producer responsibility frameworks:Health Canada and provincial regulators are designing post-consumer packaging recovery mandates that favor converters with established recycling infrastructure partnerships.
- Digital printing on fiber substrates:Direct-to-shape inkjet systems enable late-stage customization for limited-edition device launches, collapsing SKU proliferation costs versus traditional flexographic plate changes.
Industry Challenges
- Structural packaging engineering talent:The intersection of finite element analysis, sustainable materials science, and automated fulfillment system integration requires skill profiles scarce in traditional corrugated and folding carton workforces.
- FTC Green Guides substantiation:Environmental marketing claims on biodegradable and recyclable assertions demand third-party verification documentation that extends new product introduction timelines.
- Legacy ERP integration:Packaging specification management systems at major electronics OEMs require custom API development to synchronize with emerging carbon accounting platforms tracking scope 3 emissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Consumer Electronics Packaging Market |
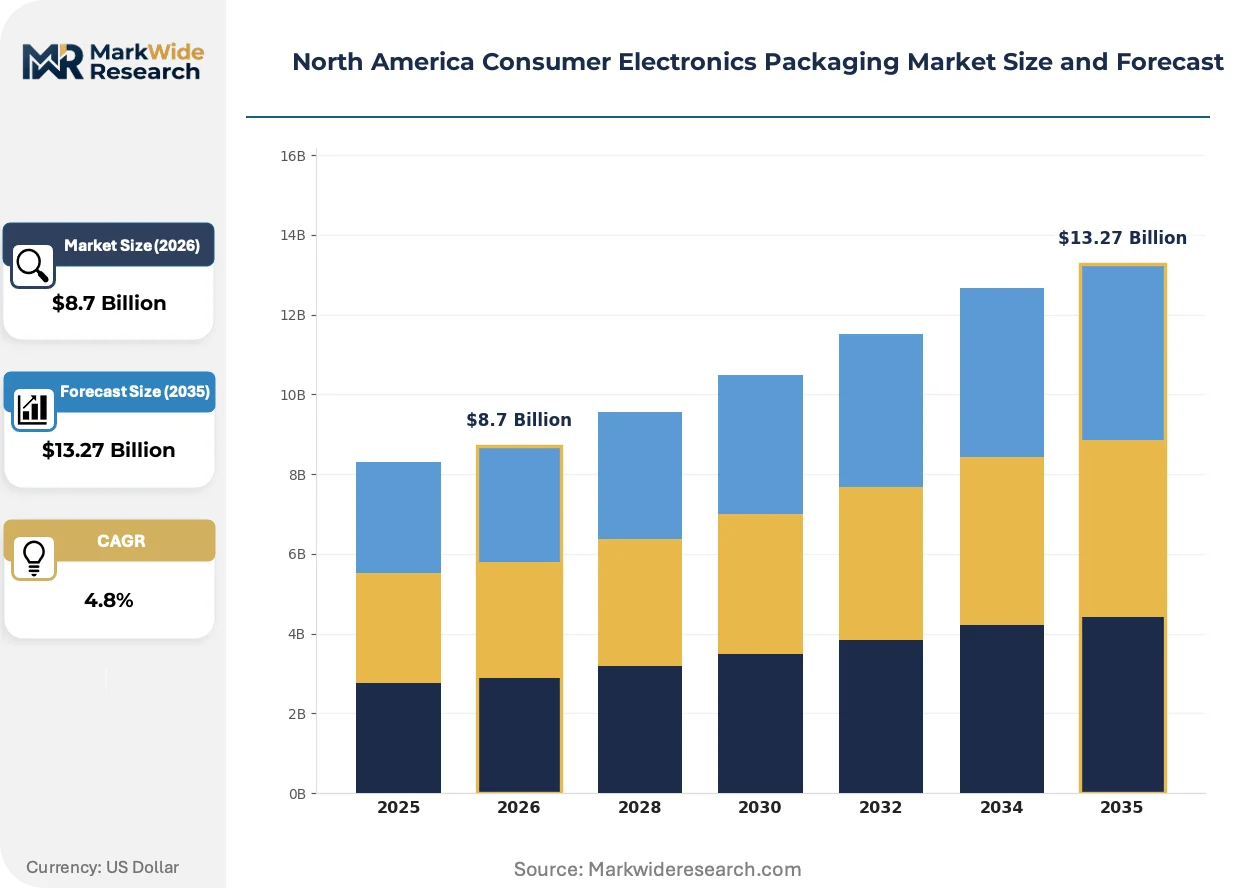
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Blister Packs, Folding Cartons, Rigid Boxes, Flexible Pouches Material: Cardboard, Plastic, Styrofoam, Biodegradable Materials End User: Retail, E-commerce, Wholesale, OEMs Design Complexity: Simple, Interactive, Custom, Standardized |
| Companies Covered | DuPont, AMETEK, JOHNSBYRNE, Pregis LLC, Sealed Air, WestRock, Sonoco Products Company, Smurfit Kappa, UFP Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Consumer Electronics Packaging Market Trends and Innovations
Active transformation across North American consumer electronics packaging centers on three vectors: virtualized protective design, regulatory material mandates, and fulfillment channel fragmentation reshaping volume allocation between direct-to-consumer and retail-bound formats.
Digital twin simulation for drop-testing and compression analysis is virtualizing physical prototyping cycles for protective packaging development. Sealed Air and specialized engineering firms deploy finite element modeling to predict damage propagation through molded fiber structures without mold fabrication. Smartphone OEMs adopting this workflow compress development timelines from twelve weeks to four, enabling late-stage design changes tied to component shifts.
The US EPA sustainable materials management guidelines push OEMs toward recycled content verification thresholds that reshape substrate specifications. California's pending packaging EPR legislation and Washington state's extended producer responsibility frameworks create compliance cost redistribution pressures between brands and converters. Electronics assemblers in Ontario and Quebec face parallel provincial recovery rate mandates that favor local converters with established post-consumer fiber collection partnerships.
Unboxing ritual monetization is redirecting premium packaging investment toward influencer-optimized formats. Flagship smartphone and wearable launches now specify rigid box constructions with magnetic closures and sequential reveal mechanics designed for social media documentation. JOHNSBYRNE and specialty converters capture this margin pool through integrated finishing capabilities serving Los Angeles and New York creative agency specifications, while mass-market accessories migrate toward flexible pouches reducing dimensional weight charges in parcel networks.
North America Consumer Electronics Packaging Market Segmentation
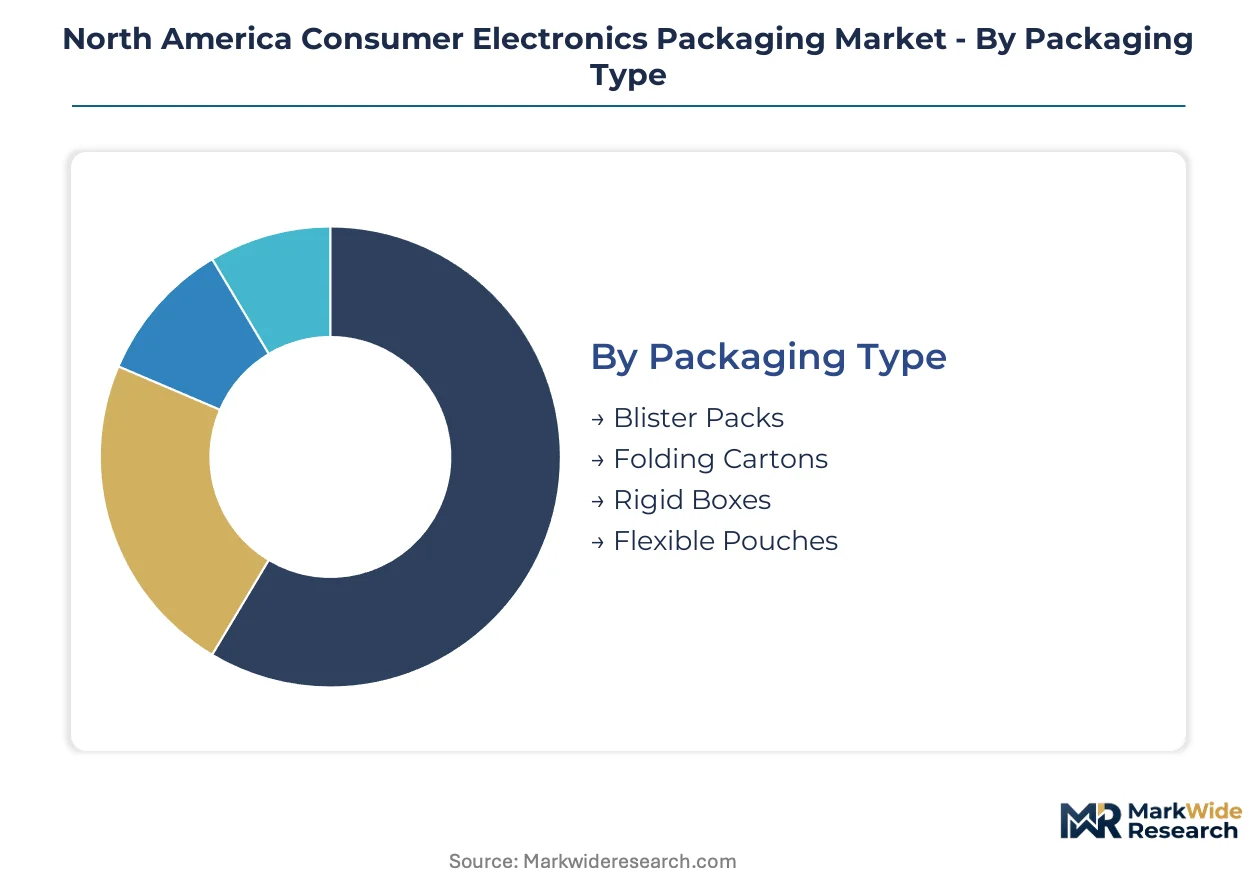
Consumer electronics packaging selection hinges on the tension between protection requirements, unboxing experience expectations, and fulfillment channel economics. Each segmentation dimension reveals distinct procurement patterns across smartphone, wearable, and display categories.
Packaging Type:
End-use applications span from mass-market accessories to flagship device launches, with format selection driven by automation compatibility and dimensional weight optimization.
- Folding Cartons:Corrugated fiberboard constructions rated ECT 32-44 dominate accessory and mid-tier device volume. California's Silicon Valley logistics corridor generates concentrated demand for flat-pack efficiency in high-velocity distribution centers.
- Rigid Boxes:Premium board constructions with magnetic closures and sequential reveal mechanics serve flagship smartphone and wearable launches. Unboxing ritual monetization drives procurement specifications from Los Angeles and New York creative agencies.
- Blister Packs:Thermoformed PET clamshells with printed backing cards persist in retail-bound peripheral categories despite sustainability pressures.
- Flexible Pouches:Multi-layer barrier films reduce cube and freight cost for cable and peripheral direct-to-consumer shipments.
The dominant share belongs to Folding Cartons, while Flexible Pouches are gaining share fastest through e-commerce channel expansion.
Material:
Cost tiers stratify from commodity recycled fiber to certified biodegradable substrates, with regulatory mandates accelerating transitions away from petroleum-based protective structures.
- Cardboard:Recycled-content corrugated and folding carton grades anchor volume across all device categories. Old corrugated container price volatility compresses converter margins when Chinese import policy shifts disrupt OCC feedstock flows.
- Biodegradable Materials:Molded fiber thermoforming achieves precision geometries previously requiring expanded polystyrene. Canada's single-use plastic regulations and US EPA sustainable materials management guidelines accelerate substitution in Ontario's electronics assembly belt.
- Plastic:Thermoformed PET and rPET substrates depend on Gulf Coast petrochemical complex output, exposing brands to hurricane-related production interruptions.
- Styrofoam:Expanded polystyrene protective structures face phased elimination under federal and provincial restrictions across the United States and Canada.
Cardboard retains the dominant position, though Biodegradable Materials show the steepest expansion trajectory as regulatory deadlines approach.
End User:
Customer type determines order cadence, customization depth, and reverse logistics infrastructure requirements.
- E-commerce:Direct-to-consumer shipments demand damage-resistant designs optimized for parcel network handling. Sealed Air's automated packaging systems capture volume in high-velocity distribution centers serving this channel.
- OEMs:Original equipment manufacturers specify protective structures synchronized with assembly line throughput and component change cycles. Late-stage customization via digital printing enables limited-edition launches without SKU proliferation penalties.
- Retail:Brick-and-mortar display requirements drive shelf-ready packaging with theft-deterrent features and vertical stacking stability.
- Wholesale:Bulk shipment formats prioritize pallet cube efficiency over individual unboxing experience.
E-commerce commands the dominant share, while OEM procurement is climbing the fastest through Mexico nearshoring expansion.
Design Complexity:
Margin pools concentrate at the intersection of engineering sophistication and brand storytelling, with tiered offerings spanning commodity protection to experiential reveal mechanics.
- Custom:Bespoke structural engineering with integrated finishing and graphic capabilities targets premium unboxing experiences. JOHNSBYRNE serves this specification tier through specialty production assets.
- Standardized:Pre-engineered protective structures with validated drop-test performance reduce new product introduction timelines for mass-market device categories.
- Interactive:Sequential opening mechanisms and embedded NFC or AR activation elements bridge physical packaging with digital engagement.
- Simple:Minimal material constructions satisfy cost-constrained accessory categories where protection requirements are modest.
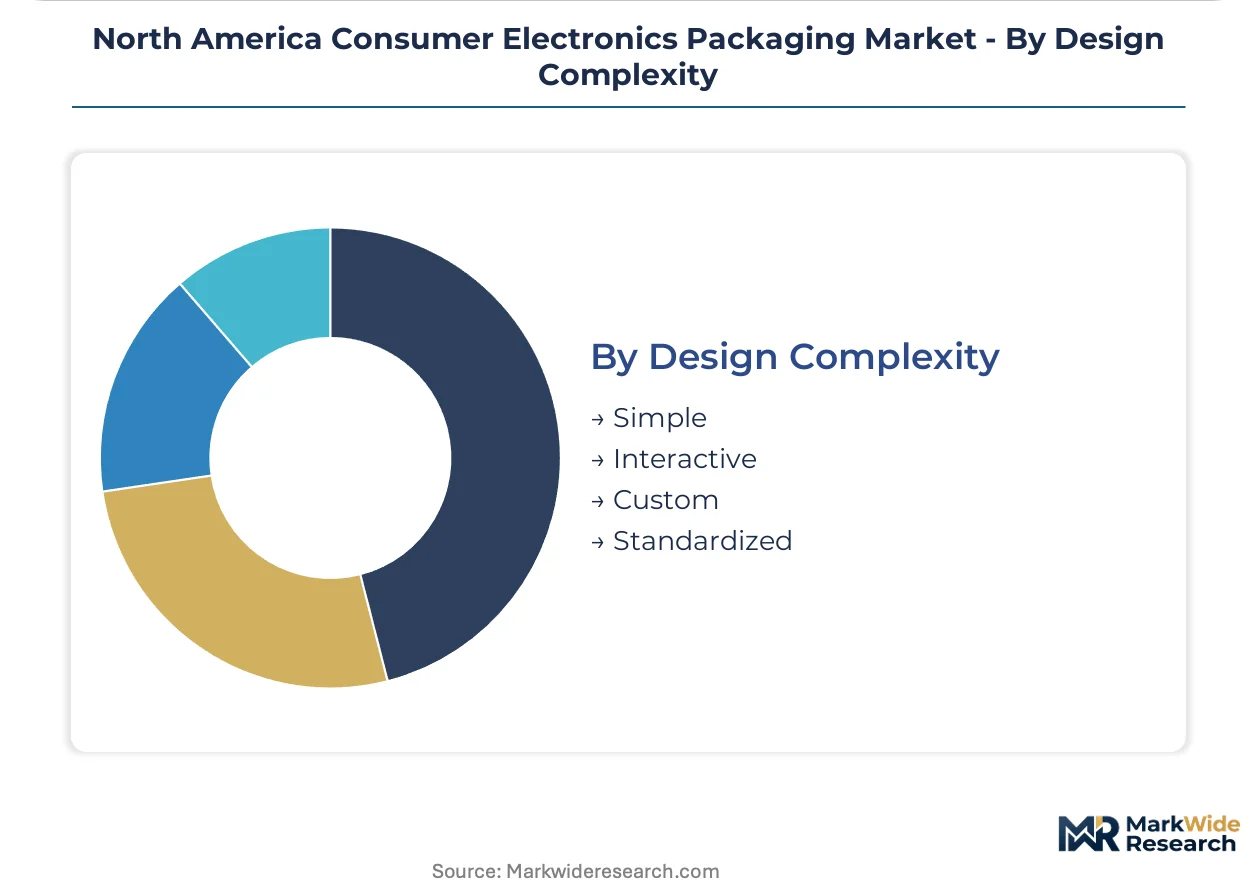
Standardized designs hold the dominant share, yet Custom specifications are expanding most quickly through influencer-optimized flagship launches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Silicon Valley corridor commands pricing premiums for high-velocity automated formats, while Mexico's Baja California assembly belt extracts cost advantages through proximity logistics. This asymmetry reshapes procurement geography across the continent.
United States
California's Silicon Valley logistics corridor and the Pacific Northwest electronics cluster drive concentrated demand for ECT 32-44 rated corrugated and automated packaging systems. The EPA's sustainable materials management guidelines push OEMs toward recycled content verification thresholds. Texas and Arizona distribution centers are expanding capacity to serve nearshored assembly operations from Mexico.
Canada
Ontario's electronics assembly belt generates sustained procurement of molded fiber trays as brands transition from petroleum-based protective structures. Health Canada and PMRA coordinate extended producer responsibility frameworks affecting post-consumer packaging recovery rates. Quebec's provincial recovery rate mandates favor converters with established post-consumer fiber collection partnerships in the Montreal-Toronto corridor.
Mexico
Baja California and Guanajuato industrial corridors attract smartphone and wearable assembly migration from Asia, creating localized packaging supply chain demand. Federal economic development programs support industrial park infrastructure for electronics manufacturing. Tijuana and Querétaro logistics hubs are expanding corrugated substrate inventory positions to serve just-in-time assembly requirements.
North America Consumer Electronics Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate and protective structure supply. The vendor base stratifies across three functional layers: integrated paperboard mills with captive corrugated networks, automated packaging system providers, and specialty converters with finishing capabilities. Consolidation pressures concentrate in the mill tier where scale determines OCC feedstock access. Competitive moves center on Mexico capacity expansion and digital printing technology partnerships.
Among integrated paperboard suppliers, WestRock anchors North American corrugated substrate supply through mill networks spanning Mexico, the US, and Canada. Sealed Air occupies the automated systems tier with packaging machinery deployed in high-velocity distribution centers. JOHNSBYRNE represents the specialty converter archetype, differentiated through finishing and graphic capabilities targeting premium unboxing specifications from Los Angeles and New York creative agencies.
| Leading Market Players |
|---|
| DuPont |
| AMETEK |
| JOHNSBYRNE |
| Pregis LLC |
| Sealed Air |
| WestRock |
| Sonoco Products Company |
| Smurfit Kappa |
| UFP Technologies |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Mexico's Baja California corrugated substrate mills is compressing converter margins while simultaneously enabling aggressive pricing postures for smartphone OEM procurement. This utilization imbalance feeds back into supplier consolidation pressures across North American paperboard networks.
Pricing Analysis
The customization-premium spread separates rigid box specifications for flagship smartphone launches from standardized folding carton volumes for accessory categories. Three-tier pricing structure across premium, standard, and economy levels differentiates by finishing complexity and unboxing ritual investment. Pricing pressure stems from OCC feedstock volatility triggered by Chinese import policy shifts. Mass-market accessory brands exhibit highest price sensitivity, while flagship device OEMs prioritize unboxing experience over unit cost.
Supply Chain Analysis
Export-control regime restrictions on advanced packaging machinery from Germany and Japan constrain thermoforming precision equipment flows into North American converter facilities. Geographic supply concentration centers on US Gulf Coast petrochemical complexes for rPET substrates, Canadian boreal forests for virgin fiber, and Mexican industrial corridors for nearshored assembly integration. Raw material dependencies include OCC collections from residential recycling streams, coated paperboard from integrated mills, and barrier coatings from specialty chemical suppliers. Single-source vulnerability runs through Sealed Air's automated systems tier. Distribution runs through high-velocity fulfillment centers in California's Silicon Valley logistics corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where automated packaging system interoperability determines converter competitive position. Ecosystem lock-in effects favor suppliers whose machinery specifications synchronize with major electronics OEM ERP platforms.
For Market Incumbents: Entrench position through backward integration into molded fiber thermoforming technology and captive OCC collection networks in Ontario and Quebec. Digital printing capability investments defend against SKU proliferation penalties from limited-edition device launches. Threat of Mexico nearshoring acceleration demands Baja California capacity expansion.
For New Entrants and Emerging Players: Guanajuato's underpenetrated industrial corridor offers white-space access for corrugated substrate suppliers serving wearable assembly migration. Specialty finishing for influencer-optimized unboxing experiences represents the most penetrable premium tier. Go-to-market through Los Angeles and New York creative agency specifications bypasses incumbent OEM procurement lock-in.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automated packaging system providers with installed base service contracts. Long-term viability favors converters with established Health Canada EPR framework compliance infrastructure. Acquisition targets include regional molded fiber specialists with Ontario electronics belt relationships. Signal to watch: California packaging EPR legislation implementation timeline.
| Strategic Initiative | Industry Significance |
|---|---|
| Mexico Capacity Expansion | Captures smartphone assembly nearshoring volume in Baja California and Guanajuato corridors. |
| Digital Printing Technology Partnership | Enables late-stage customization for limited-edition launches without traditional plate costs. |
| Molded Fiber Thermoforming Investment | Substitutes petroleum-based protective structures under EPA sustainable materials guidelines. |
| EPR Framework Compliance Infrastructure | Positions converters for Health Canada and provincial recovery rate mandate advantages. |
| Automated Packaging System Integration | Synchronizes with OEM ERP platforms for high-velocity distribution center capture. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EPA sustainable materials management documentation, Canadian federal register entries, and trade customs data. Packaging procurement directors at smartphone OEMs, corrugated mill operations managers, and creative agency production leads provided structured input. Bottom-up volume modeling triangulates against top-down value estimates derived from substrate pricing indices.
Forecast inputs include smartphone shipment trajectories, e-commerce channel penetration rates, and regulatory deadline schedules across the analysis window. Segmentation dimensions span packaging type, material substrate, end-user channel, and design complexity tier. CAGRs derive from regression analysis against historical substrate consumption patterns and OEM procurement cycle data. Mexico nearshoring velocity and California EPR implementation pace serve as scenario sensitivity variables.
Practitioners should monitor Chinese OCC import policy shifts, hurricane frequency in Gulf Coast petrochemical corridors, and state-level EPR legislative advancement for early signals. Forecasts embed assumptions about sustained regulatory pressure toward fiber-based alternatives. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronics Packaging
Asia-Pacific Consumer Electronics Packaging Market
Electronics Packaging
Consumer Electronics Packaging Market
Electronics Packaging
Electronic Packaging Market
Electronics Packaging
Europe and USA Consumer Electronics Packaging Market
Electronics Packaging
Electronic Goods Packaging Market
Electronics Packaging
Europe Consumer Electronics Packaging Market
Electronics Packaging
Industrial Electronics Packaging Market
Electronics Packaging
MEMS Packaging Solder Market
Electronics Packaging
Global Display Packaging Market
Electronics Packaging
Mobile Phone Accessories Packaging Market
Electronics Packaging
Fan-Out Wafer Level Packaging Market
Electronics Packaging
Electronic Wrapper Market
Electronics Packaging
Power Module Packaging Market
Electronics Packaging
Multi-Chip Module Packaging Market
Electronics Packaging
Global Mobile Phones Packaging Market
Electronics Packaging
Asia-Pacific Battery Packaging Market