
 Electronic Packaging Market | 2026-2036
Electronic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Packaging Market Analysis
Advanced substrate engineering talent is reorganizing supply chains as foundries compete for finite pools of interposer designers and thermal management specialists. DuPont de Nemours anchors North American material supply through fluoropolymer and high-performance resin portfolios for laminates and dielectrics. SCHOTT AG specializes in hermetic glass-to-metal sealing for aerospace and medical device packaging where reliability thresholds exclude polymer alternatives. Mondi Group extends paper-based protective packaging into semiconductor logistics, competing with molded foam incumbents on sustainability credentials.
Electronic packaging encompasses the enclosure, interconnection, thermal management, and environmental protection of integrated circuits and discrete components, typically operating across temperature ranges from minus 55°C to 150°C depending on application grade. Its primary purpose is to preserve electrical functionality while dissipating heat and shielding sensitive die from moisture, mechanical stress, and electromagnetic interference. Plastic substrates and laminates still occupy the highest volume share across consumer electronics and automotive modules, though ceramic packages lead in radio-frequency and power applications where thermal conductivity and hermeticity command premium positioning. Flip Chip interconnect technology is displacing wire bonding in high-performance computing and telecommunications baseband processors as I/O density requirements exceed peripheral pad limitations.
The EPA regulates per- and polyfluoroalkyl substance discharge from etching and plating operations, pushing U.S. fabricators toward aqueous cleaning chemistries and closed-loop wastewater systems. REACH restrictions on halogenated flame retardants and EU F-Gas Regulation phase-down schedules compel European substrate producers to qualify phosphorus-nitrogen intumescent systems and low-global-warming-potential cleaning agents. China's MEE enforces dual carbon goals through energy intensity benchmarks that favor domestic manufacturers investing in renewable-powered lamination and metallization lines. Stakeholders must monitor how divergent chemical compliance timelines reshape qualification costs and regional sourcing decisions for multi-site OEMs.
Market Dynamics
Semiconductor foundries in Taiwan and South Korea are expanding advanced substrate capacity to serve AI accelerator demand, creating a talent war for interposer designers and thermal management specialists that is reorganizing global supply chains.
Growth Catalysts
- AI Accelerator Substrate Demand:Heterogeneous integration requirements for high-performance computing chips are pulling Ball Grid Array and Flip Chip technologies into mainstream adoption.
- EU F-Gas Regulation Phase-Down:Mandates on low-global-warming-potential materials are accelerating qualification of phosphorus-nitrogen intumescent flame retardant systems in European substrate production.
- China Dual Carbon Goals:Energy intensity benchmarks enforced by MEE favor domestic manufacturers investing in renewable-powered lamination and metallization lines.
Market Restraints
- Fluoropolymer Input Cost Volatility:Per- and polyfluoroalkyl substance discharge restrictions under EPA regulations are compressing margins for U.S. fabricators forced into aqueous cleaning chemistries.
- Advanced Substrate Talent Concentration:Finite pools of interposer designers cluster around Taiwan and South Korea foundries, creating chokepoints for capacity expansion elsewhere.
- Hermetic Glass Substitution Limits:Aerospace and medical device packaging where reliability thresholds exclude polymer alternatives face material availability constraints from specialty glass-to-metal sealing suppliers.
Strategic Opportunities
- Paper-Based Protective Packaging:Mondi Group's semiconductor logistics solutions compete with molded foam incumbents on sustainability credentials, opening share in eco-conscious OEM supply chains.
- Low-Emission Dielectric Materials:Substrate manufacturers qualifying low-emission formulations gain preferential positioning with OEMs facing Scope 3 disclosure requirements under CSRD.
- Automotive Module Grade Expansion:Temperature range requirements from minus 55°C to 150°C in automotive applications create specification premiums for ceramic package suppliers.
Industry Challenges
- Closed-Loop Wastewater System Capex:EPA compliance for etching and plating operations demands capital-intensive infrastructure that mid-tier fabricators struggle to finance.
- REACH Qualification Timeline Compression:Halogenated flame retardant restrictions force simultaneous reformulation and requalification, stretching R&D bandwidth across product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Packaging Market |
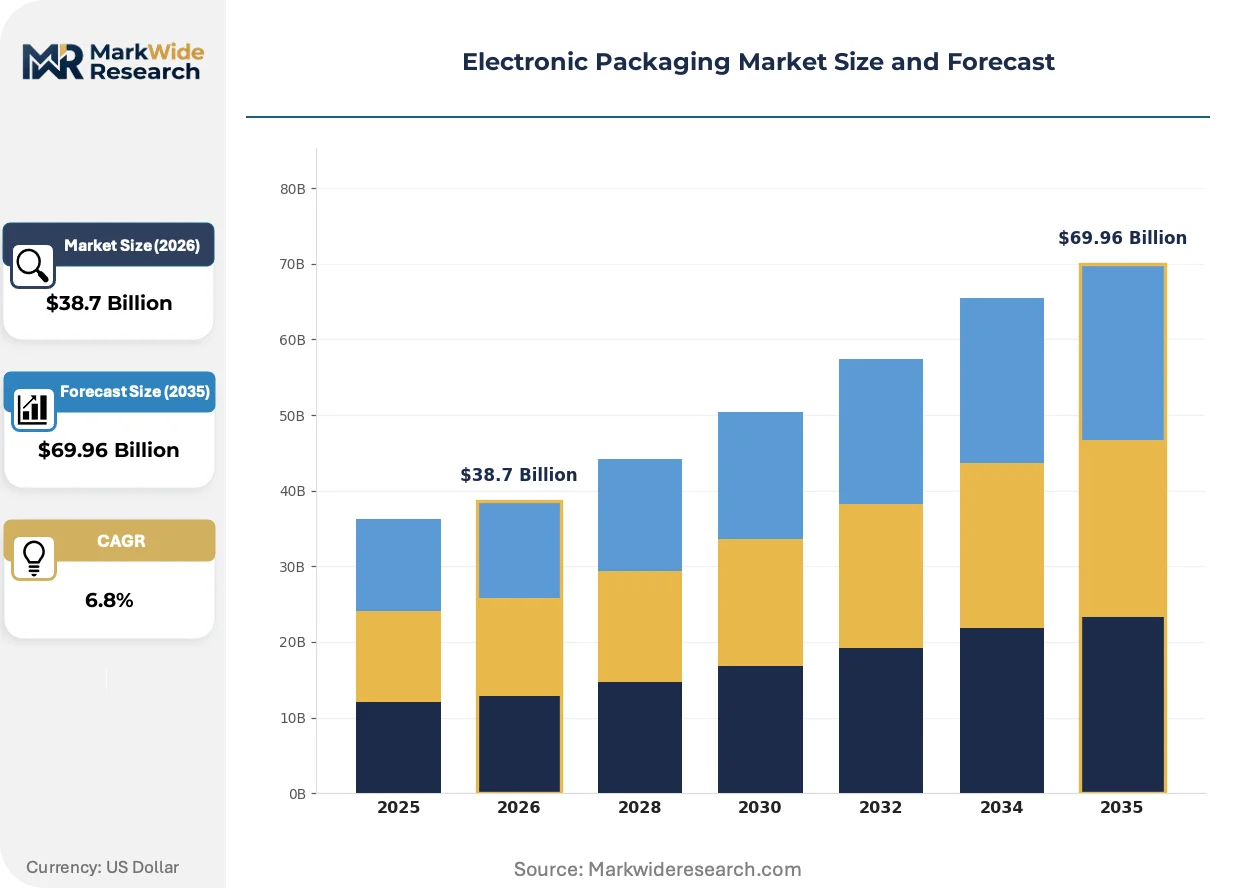
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hill-Top, Ball Grid Array, Quad Flat Package, Chip-on-Board Material: Plastic, Glass, Metal, Ceramic End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Technology: 3D Packaging, System-in-Package, Flip Chip, Advanced Substrate |
| Companies Covered | SCHOTT AG, WestRock Company, UFP Technologies, Inc., Mondi Group, Smurfit Kappa Group PLC, Sealed Air Corporation, Sonoco Products Company, Dunapack Packaging Group, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Packaging Market Emerging Trajectories
Electronic packaging is experiencing simultaneous pressure from thermal density requirements and chemical compliance mandates, forcing convergence between material science and process engineering.
Flip Chip interconnect technology is miniaturizing I/O density beyond wire bonding limitations. High-performance computing and telecommunications baseband processor manufacturers are adopting this technology aggressively. The structural consequence is compressing peripheral pad architectures and enabling heterogeneous integration at previously unattainable pitch densities.
REACH restrictions on halogenated flame retardants are forcing substrate producers toward phosphorus-nitrogen intumescent systems. European manufacturers face compressed qualification windows as F-Gas Regulation phase-down schedules synchronize with material transitions. Laminate suppliers serving automotive and consumer electronics modules are responding with parallel formulation tracks to maintain multi-regional certification.
After-sales service unbundling is fragmenting traditional distributor relationships in semiconductor logistics. Protective packaging buyers are separating material supply from technical support, favoring specialists like Mondi Group over integrated distributors. This pattern is most visible in European and North American OEM supply chains where sustainability scorecards drive direct sourcing decisions.
Electronic Packaging Market Segmentation
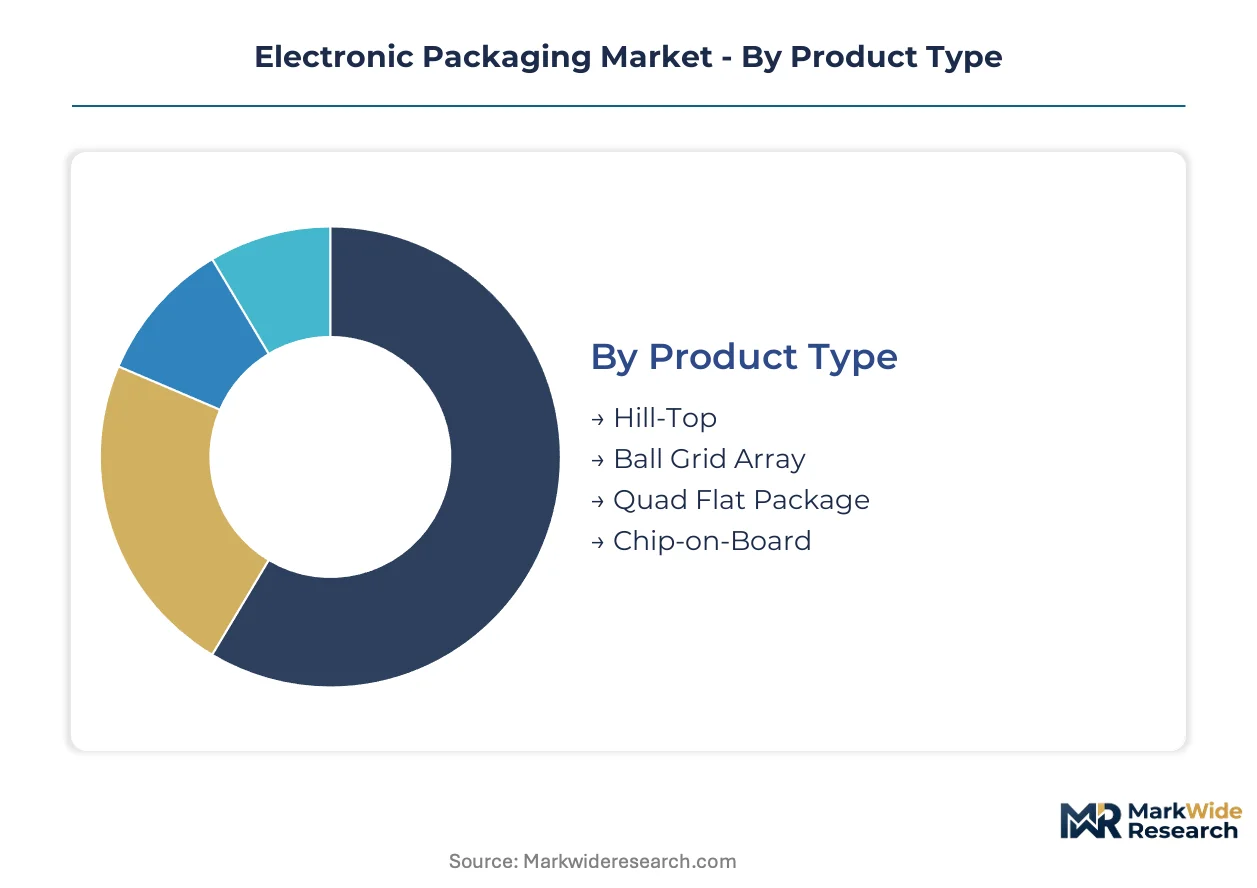
Electronic packaging segmentation reveals divergent margin structures across interconnect architectures and material systems. Product type and technology categories concentrate premium returns where heterogeneous integration complexity escalates.
Product Type:
Margin pools concentrate in high-I/O density formats serving AI accelerator and baseband processor applications.
- Ball Grid Array:Area-array interconnect architecture enables superior electrical performance and thermal dissipation compared to peripheral-lead alternatives. Taiwan and South Korea foundries are expanding Ball Grid Array substrate capacity to capture AI accelerator demand from NVIDIA and AMD. Heterogeneous integration requirements for high-performance computing chips are pulling this technology into mainstream adoption.
- Flip Chip:Direct die-to-substrate attachment eliminates wire bond loops, reducing inductance and enabling finer pitch densities. Telecommunications baseband processor manufacturers are adopting this technology aggressively as I/O density requirements exceed peripheral pad limitations. The structural consequence compresses peripheral pad architectures and enables previously unattainable integration densities.
- Hill-Top:Leadframe-based package format maintains cost positioning in consumer electronics volume applications where I/O counts remain moderate.
- Quad Flat Package:Peripheral-lead gull-wing configuration persists in automotive modules and industrial equipment where established reliability databases outweigh density advantages.
- Chip-on-Board:Direct die attach to printed circuit board minimizes package overhead for cost-sensitive applications with relaxed environmental requirements.
Ball Grid Array holds installed capacity. Flip Chip is rotating up the share rankings.
Material:
Cost tier stratification separates commodity laminates from ceramic and metal systems commanding specification premiums.
- Plastic:Epoxy-molded compound and organic laminate substrates occupy the highest volume share across consumer electronics and automotive modules. REACH restrictions on halogenated flame retardants are forcing European substrate producers toward phosphorus-nitrogen intumescent systems.
- Ceramic:Alumina and aluminum nitride packages lead in radio-frequency and power applications where thermal conductivity and hermeticity command premium positioning. Temperature range requirements from minus 55°C to 150°C in automotive applications create specification premiums for ceramic package suppliers.
- Metal:Copper and aluminum base packages address power semiconductor thermal management where heat spreading dominates design constraints.
- Glass:Specialty glass-to-metal sealing from SCHOTT AG serves aerospace and medical device packaging where reliability thresholds exclude polymer alternatives.
Ceramic maintains specification premiums in aerospace and medical segments. Plastic is expanding most quickly through automotive electrification.
End User:
Application maturity varies sharply across temperature grade requirements and qualification timeline pressures.
- Automotive:Module-grade packaging must survive minus 55°C to 150°C operating ranges with zero-defect reliability expectations over 15-year service lives. EPA per- and polyfluoroalkyl substance discharge restrictions are compressing margins for U.S. fabricators serving this segment.
- Consumer Electronics:Smartphone and wearable device packaging prioritizes miniaturization and cost optimization over extended temperature performance. China's MEE energy intensity benchmarks favor domestic manufacturers investing in renewable-powered lamination lines for this high-volume segment.
- Telecommunications:Base station and optical networking equipment demands thermal management performance at intermediate price points between consumer and automotive grades.
- Industrial Equipment:Factory automation and process control applications require extended temperature ranges with longer product life cycles than consumer electronics.
Automotive holds the most demanding qualification protocols. Consumer Electronics is gaining share fastest through foldable device proliferation.
Technology:
Supply concentration clusters around advanced substrate and 3D packaging capability in Taiwan and South Korea foundry ecosystems.
- Advanced Substrate:High-density interconnect and embedded die technologies enable heterogeneous integration of chiplets from multiple process nodes. Finite pools of interposer designers cluster around Taiwan and South Korea foundries, creating chokepoints for capacity expansion elsewhere.
- Flip Chip:Controlled collapse chip connection technology dominates high-performance computing where electrical performance requirements exclude wire bonding alternatives.
- 3D Packaging:Through-silicon via stacking achieves memory-on-logic integration for bandwidth-constrained AI workloads.
- System-in-Package:Multi-die integration in single molded units addresses RF front-end and sensor fusion applications in smartphones and automotive radar.
Advanced Substrate holds the critical talent concentration. System-in-Package is climbing the fastest through 5G RF module proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA regulations on per- and polyfluoroalkyl substance discharge are compressing margins for U.S. fabricators forced into aqueous cleaning chemistries and closed-loop wastewater systems. Taiwan and South Korea foundries anchor advanced substrate capacity expansion for AI accelerator demand.
United States
AI accelerator substrate demand from NVIDIA and AMD pulls Ball Grid Array capacity toward domestic packaging facilities. EPA discharge restrictions on fluoropolymer inputs force mid-tier fabricators toward capital-intensive closed-loop wastewater infrastructure. Greater Phoenix and Austin semiconductor corridors concentrate heterogeneous integration talent pools.
Taiwan
Foundry ecosystems in Hsinchu and Tainan Science Parks drive interposer designer concentration for high-performance computing chips. The region lacks explicit chemical phase-down mandates but faces indirect pressure through CSRD-aligned OEM supply chain audits. Taiwan Semiconductor Manufacturing Company anchors advanced substrate capacity serving global AI accelerator demand.
South Korea
Samsung Electronics and SK Hynix accelerate Flip Chip adoption for memory-on-logic integration in bandwidth-constrained AI workloads. The country's national chemical regulator enforces halogenated flame retardant restrictions parallel to REACH timelines. Seoul Capital Area and Busan-Ulsan corridor concentrate 3D packaging and System-in-Package capability.
China
MEE energy intensity benchmarks favor domestic manufacturers investing in renewable-powered lamination and metallization lines for consumer electronics volume. Dual carbon goals compress qualification timelines for low-emission dielectric materials in substrate production. Yangtze River Delta clusters in Shanghai and Suzhou dominate ceramic package supply for automotive and telecommunications grades.
Germany
Automotive module packaging for minus 55°C to 150°C temperature grades concentrates specification premiums in Bavaria and Baden-Württemberg supplier networks. ECHA REACH restrictions on halogenated flame retardants force simultaneous reformulation across laminate portfolios. Stuttgart and Munich industrial corridors anchor ceramic-to-metal sealing specialists serving aerospace reliability thresholds.
Electronic Packaging Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the electronic packaging value chain. Advanced substrate engineering concentrates around foundry-integrated specialists with captive interposer design capability, while commodity laminate suppliers compete on scale and qualification breadth. Three archetypes dominate: materials science multinationals with fluoropolymer and resin portfolios, hermetic sealing specialists serving exclusionary reliability segments, and paper-based protective packaging innovators attacking sustainability-driven procurement shifts. Competitive moves center on M&A for thermal management talent and strategic partnerships to secure renewable-powered metallization capacity.
Among materials science multinationals, DuPont de Nemours anchors North American laminate and dielectric supply through fluoropolymer portfolios. SCHOTT AG occupies a specialist position in hermetic glass-to-metal sealing for aerospace and medical device applications where polymer alternatives fail reliability thresholds. Mondi Group exemplifies the sustainability-driven archetype, extending paper-based protective packaging into semiconductor logistics against molded foam incumbents.
| Leading Market Players |
|---|
| SCHOTT AG |
| WestRock Company |
| UFP Technologies, Inc. |
| Mondi Group |
| Smurfit Kappa Group PLC |
| Sealed Air Corporation |
| Sonoco Products Company |
| Dunapack Packaging Group |
| DuPont de Nemours, Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with Taiwan and South Korea foundries lock in substrate allocation and price visibility for AI accelerator buyers, insulating advanced packaging purchasers from spot-market fluoropolymer volatility while compressing margins for mid-tier fabricators lacking comparable supply security.
Pricing Analysis
Taiwan commands premium positioning over Chinese domestic supply for advanced substrates, with price spreads widening for interposer-equipped formats. Three-tier pricing structure across automotive-grade ceramic, high-performance computing laminate, and consumer electronics plastic separates qualification-burdened tiers from commodity volumes. Cost compression in U.S. wire-bonding segments intensifies as EPA discharge restrictions force aqueous chemistry conversions. Consumer electronics OEMs exhibit highest price sensitivity, while aerospace and medical device buyers absorb premiums for hermetic glass-to-metal sealing.
Supply Chain Analysis
Interposer designer concentration in Hsinchu and Tainan Science Parks creates talent chokepoints that throttle substrate capacity expansion outside Taiwan and South Korea. Raw material flows draw from Japanese fluoropolymer resin suppliers, German specialty glass manufacturers, and Chinese copper-clad laminate producers. Single-source vulnerability runs through Taiwan Strait logistics exposure for high-density interconnect substrates. Distribution runs through foundry-integrated packaging houses and independent substrate vendors serving fabless semiconductor designers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electronic packaging market functions as a defensive-moat industry where switching costs for substrate requalification and foundry ecosystem lock-in protect incumbent positioning against new entrant disruption.
For Market Incumbents: Consolidate interposer design talent pools through targeted acquisition in Greater Phoenix and Austin corridors before emerging substrate specialists can scale. Deepen backward integration into fluoropolymer resin supply to offset EPA-driven input cost volatility. Prioritize certification investment for phosphorus-nitrogen intumescent systems ahead of REACH timeline compression. For New Entrants and Emerging Players: After-sales service unbundling in European semiconductor logistics exposes share opportunities against integrated distributors. Target paper-based protective packaging for eco-conscious OEM supply chains where sustainability scorecards override incumbent relationships. Pursue direct sourcing partnerships with automotive module manufacturers seeking lower-emission dielectric alternatives. For Investors and Strategic Acquirers: Capital is best deployed toward hermetic sealing specialists serving exclusionary reliability segments where polymer substitution limits create durable margin structures. Long-term viability favors ceramic package suppliers with automotive grade certification and aerospace qualification databases. Watch CSRD-aligned Scope 3 disclosure acceleration as inflection indicator for low-emission material preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Management Talent Acquisition | Captures scarce interposer designers from Taiwan foundry ecosystems for AI substrate capacity. |
| Low-Emission Dielectric Qualification | Positions substrate manufacturers for CSRD Scope 3 disclosure requirements in European OEM supply chains. |
| Renewable-Powered Metallization Investment | Aligns lamination capacity with China's MEE energy intensity benchmarks for dual carbon compliance. |
| Hermetic Glass-to-Metal Sealing Expansion | Serves aerospace and medical device packaging where reliability thresholds exclude polymer alternatives. |
| Paper-Based Protective Packaging Scale-Up | Competes with molded foam incumbents on sustainability credentials in semiconductor logistics. |
Methodological Framework
A standing panel of substrate fabrication engineers, foundry packaging strategists, thermal management specialists, and semiconductor procurement directors provided ongoing calibration against secondary validation from SEC 10-K filings, Taiwan Stock Exchange disclosures, EPA enforcement databases, and ECHA REACH registration data. Bottom-up build-ups of substrate capacity and top-down cross-checks against foundry capex announcements were reconciled through iterative triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated interconnect architecture, material system, temperature grade, and end-use application dimensions. CAGRs were derived from slope-logic analysis of capacity expansion trajectories and input cost curves, with explicit treatment of fluoropolymer price volatility and talent scarcity constraints.
Forecasts assume regulatory continuity in EPA discharge regimes, ECHA REACH phase-down schedules, and China's MEE dual carbon enforcement; material policy shifts would require re-modeling of qualification timelines and regional sourcing economics. Practitioners should keep alternative scenarios live as F-Gas Regulation acceleration and CSRD disclosure mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronics Packaging
Anti-Counterfeit Electrical and Electronics Packaging Market
Electronics Packaging
Electronic Wrapper Market
Electronics Packaging
Electronic Goods Packaging Market
Electronics Packaging
Mobile Phone Accessories Packaging Market
Electronics Packaging
MEMS Packaging Solder Market
Electronics Packaging
Multi-Chip Module Packaging Market
Electronics Packaging
Global Display Packaging Market
Electronics Packaging
Europe and USA Consumer Electronics Packaging Market
Electronics Packaging
Industrial Electronics Packaging Market
Electronics Packaging
Fan-Out Wafer Level Packaging Market
Electronics Packaging
North America Consumer Electronics Packaging Market
Electronics Packaging
Europe Consumer Electronics Packaging Market
Electronics Packaging
Global Mobile Phones Packaging Market
Electronics Packaging
Power Module Packaging Market
Electronics Packaging
Consumer Electronics Packaging Market
Electronics Packaging
Asia-Pacific Consumer Electronics Packaging Market