
 Multi-Chip Module Packaging Market | 2026-2036
Multi-Chip Module Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Chip Module Packaging Market Foresight
Advanced packaging engineering talent is rotating from traditional wire-bond disciplines toward heterogeneous integration and chiplets design. Intel Corporation leverages its IDM 2.0 strategy to sustain captive advanced packaging capacity in Arizona and New Mexico. Samsung Electronics anchors its multi-chip module roadmap with X-Cube 3D stacking technology, competing directly with TSMC's CoWoS and InFO platforms for high-bandwidth memory integration.
Multi-chip module packaging integrates multiple semiconductor dies into a single functional unit through substrate-based or wafer-level interconnects, typically achieving interconnect pitches below 55 micrometers for high-performance applications. Flip chip technology dominates current volume production due to its established infrastructure and cost structure, while 3D packaging captures the fastest expansion as memory-logic stacking becomes essential for AI training accelerators. Wafer-level packaging commands premium margins in RF communication modules for 5G millimeter-wave handsets, whereas chemically-enhanced processes remain niche but critical for hermetic aerospace and defense applications.
The US Department of Commerce export controls on advanced semiconductor manufacturing equipment constrain certain multi-chip module technologies destined for specific end markets, while China's MIIT and SAMR enforce GB standards for reliability testing and environmental compliance in domestic supply chains. ISO 9001 and IATF 16949 certifications function as baseline market access requirements for automotive electronics applications. Stakeholders must monitor how substrate material shortages and co-packaging optics integration reshape supplier qualification timelines and capital allocation priorities.
Market Dynamics
Artificial intelligence accelerators are compressing interconnect pitch requirements below 55 micrometers, forcing substrate suppliers to retool for organic laminate alternatives and reconfiguring capital allocation across the packaging value chain.
Growth Catalysts
- High-bandwidth memory integration:AI training workloads demand memory-logic stacking through 3D architectures, pulling advanced packaging capacity expansion in Taiwan's Hsinchu cluster.
- China's dual carbon goals:GB standards for substrate material selection are accelerating adoption of low-emission underfill compounds in domestic supply chains.
- 5G millimeter-wave handset RF modules:Wafer-level packaging captures premium positioning as smartphone OEMs prioritize antenna integration density.
Market Restraints
- Substrate material concentration:Ajinomoto Build-up Film and similar dielectric suppliers in Japan control critical input volumes, creating single-source vulnerability.
- US Department of Commerce export controls:Equipment licensing restrictions constrain multi-chip module technology transfers for specific high-performance computing end markets.
- Flip chip infrastructure lock-in:Established wire-bond facilities resist write-downs, slowing heterogeneous integration adoption despite performance advantages.
Strategic Opportunities
- Co-packaged optics integration:Silicon photonics convergence with electrical interconnects opens new qualification pathways for datacenter switch architectures.
- India's PLI scheme for electronics manufacturing:Subsidy structures attract substrate and OSAT investment away from traditional East Asian concentration.
- Chemically-enhanced hermetic packaging:Aerospace and defense applications sustain niche premium positioning as commercial volumes commoditize.
Industry Challenges
- Chiplets design methodology gap:Semiconductor packaging engineers lack standardized training in die-to-die interface protocols, delaying customer qualification cycles.
- IATF 16949 automotive certification timelines:Multi-chip modules for EV power electronics face 18-24 month validation periods that compress product windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Chip Module Packaging Market |
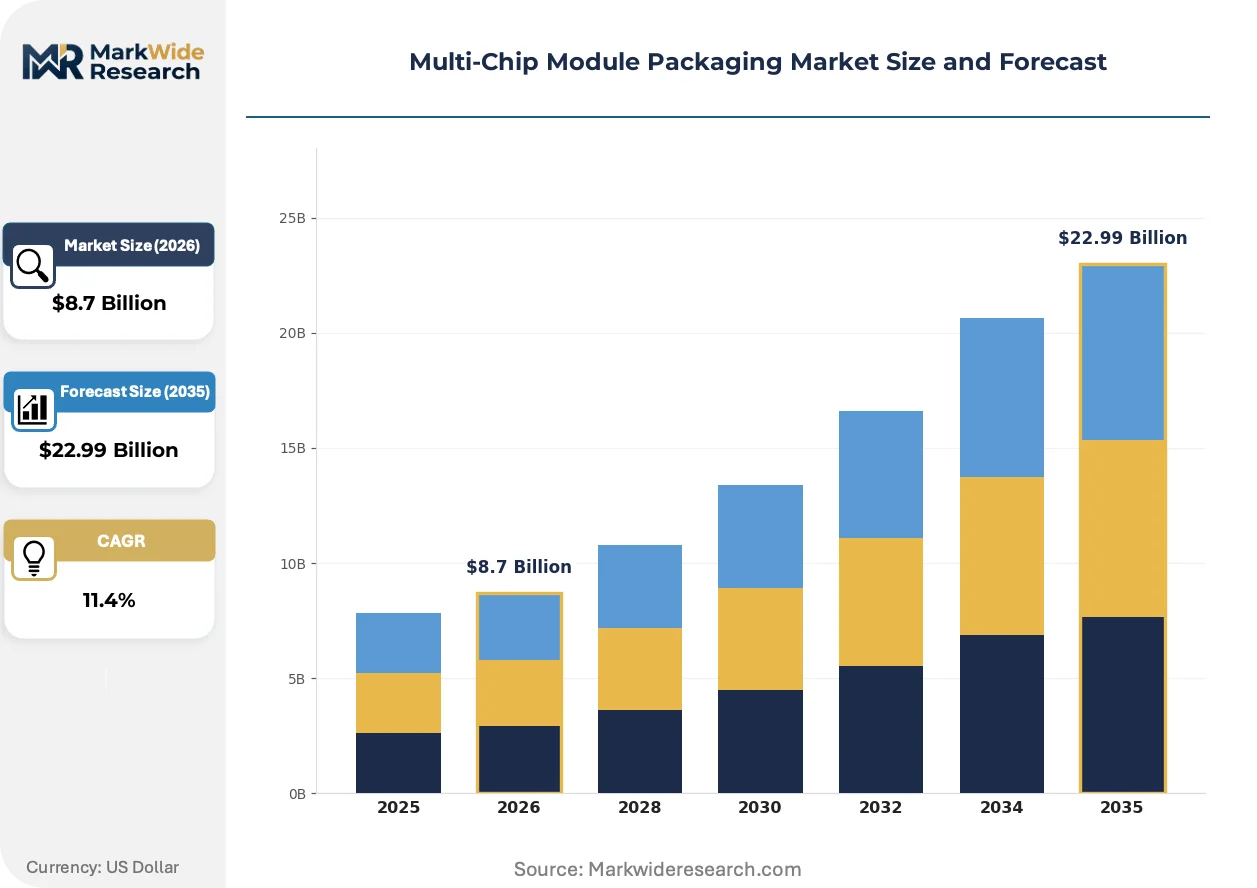
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Ceramic, Hybrid, Metal Technology: 3D Packaging, Flip Chip, Wafer-Level, Chemically-Enhanced End User: Telecommunications, Consumer Electronics, Industrial Automation, Automotive Electronics Application: High-Performance Computing, Internet of Things, Smart Devices, RF Communication |
| Companies Covered | Intel Corporation, Infineon Technologies, Samsung Electronics, Micron Technology, SK Hynix Inc., Texas Instruments, STMicroelectronics, Amkor Technology, Taiwan Semiconductor Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Chip Module Packaging Market Shifts & Advancements
Interconnect architecture evolution is fragmenting process technology roadmaps, with substrate-based and wafer-level approaches diverging in equipment requirements and talent specialization.
Hybrid bonding technology is miniaturizing die-to-die connections below 10 micrometer pitch without solder intermediates. AI accelerator designers at hyperscale datacenter operators are adopting this approach for logic-to-memory stacks. The technology is miniaturizing form factors while eliminating thermal interface resistance that constrains traditional microbump approaches.
China's MIIT and SAMR enforcement of updated GB standards for reliability testing is reshaping material qualification protocols. Domestic substrate suppliers must now document thermal cycling performance under stricter environmental compliance criteria. Automotive electronics applications face the steepest documentation burdens as they bridge consumer and industrial reliability tiers.
Buyer consolidation among hyperscale cloud operators is compressing supplier negotiation cycles and unbundling traditional OSAT service packages. Direct substrate procurement by system designers is displacing turnkey packaging contracts in North American and European supply chains. This pattern concentrates most visibly in AI training infrastructure deployments where performance specifications override incumbent relationships.
Multi-Chip Module Packaging Market Segmentation
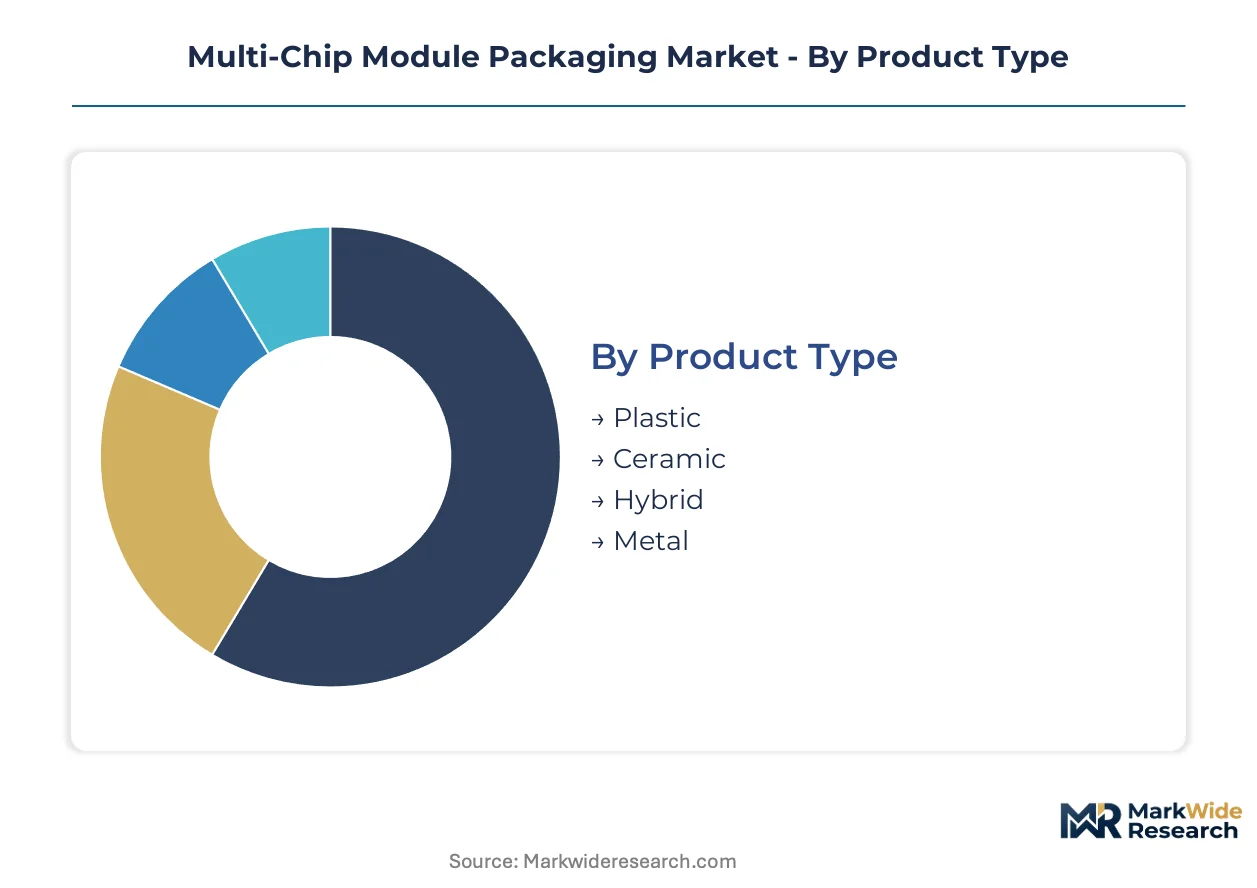
Segmentation in multi-chip module packaging reveals how substrate material choices and interconnect architectures channel demand toward distinct customer qualification pathways. Each dimension—product type, technology, end user, and application—carries unique margin structures and capital intensity requirements that reshape supplier positioning.
Product Type:
Plastic substrates flow through high-volume consumer channels, while ceramic and metal variants concentrate in defense and aerospace procurement pipelines with extended validation cycles.
- Plastic:Organic laminate substrates dominate smartphone and consumer electronics volumes due to established flip chip infrastructure and cost-efficient mass production. Taiwan's OSAT cluster processes the majority of plastic-based modules for 5G handset RF components.
- Ceramic:Alumina and aluminum nitride substrates deliver thermal stability for power electronics and satellite communications. Demand concentrates in Japan's aerospace supply chain and European space agency procurement programs where hermetic sealing requirements override cost sensitivity.
- Hybrid:Combines organic and inorganic layers for automotive power module applications requiring balanced thermal and mechanical performance.
- Metal:Copper-molybdenum and copper-tungsten composites anchor defense radar and high-power laser systems with extreme thermal dissipation needs.
By volume, Plastic leads. By growth pace, Hybrid is ahead.
Technology:
Cost tiers separate mature interconnect methods from emerging architectures demanding fresh capital deployment and specialized engineering talent.
- 3D Packaging:Through-silicon vias and hybrid bonding stack memory atop logic dies for AI training accelerators. Hyperscale datacenter operators in the United States and Taiwan are pulling capacity expansion for high-bandwidth memory integration.
- Flip Chip:Solder bump interconnects below 150 micrometer pitch remain the workhorse for consumer electronics and automotive control modules. Established infrastructure across Malaysia and Vietnam sustains cost-competitive volume production despite performance limitations versus 3D alternatives.
- Wafer-Level:Fan-out and fan-in approaches serve millimeter-wave 5G handsets and IoT sensors where form factor minimization commands premium positioning.
- Chemically-Enhanced:Specialized coatings and hermetic sealing protect aerospace and medical implants from moisture and radiation exposure.
Flip Chip generates the largest revenue base. 3D Packaging is climbing the fastest as memory-logic stacking becomes essential for AI infrastructure.
End User:
Customer type determines reliability tier requirements, with automotive and industrial applications imposing stricter certification burdens than consumer segments.
- Telecommunications:Base station and optical transport equipment demand high-reliability ceramic and metal packages with extended temperature range specifications. China's 5G deployment and India's network expansion are pulling substrate volumes through specialized RF module channels.
- Consumer Electronics:Smartphones, tablets, and wearables drive plastic-based flip chip and wafer-level packaging at extreme cost compression. South Korean and Chinese OEMs dominate procurement with consolidated supplier negotiation power.
- Industrial Automation:Robotics and process control systems require extended temperature cycling performance.
- Automotive Electronics:EV power modules and ADAS processors face IATF 16949 validation timelines that stretch supplier qualification cycles.
Consumer Electronics ships the highest unit volumes. Automotive Electronics is gaining share fastest as electrification multiplies semiconductor content per vehicle.
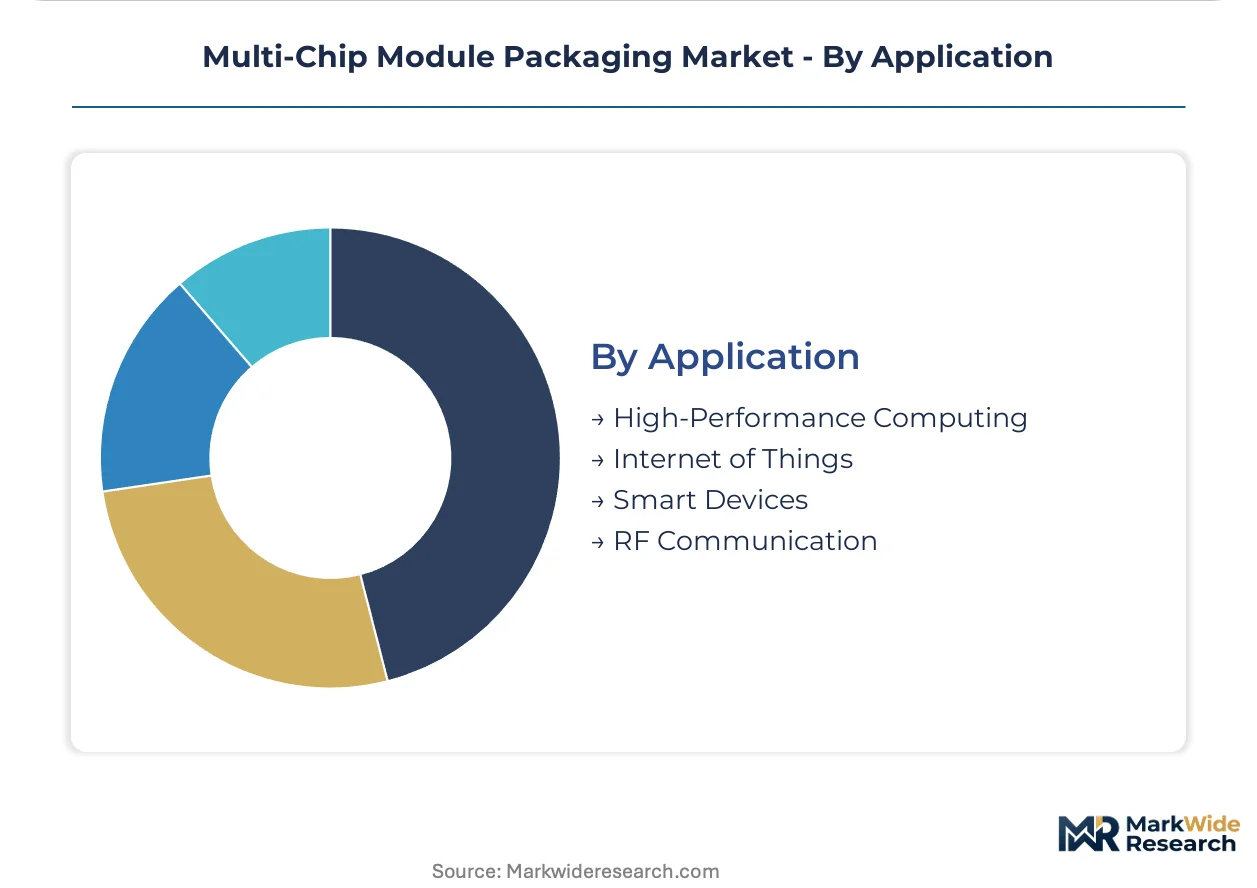
Application:
Application focus dictates interconnect pitch requirements and thermal management intensity, with high-performance computing demanding the most advanced packaging architectures.
- High-Performance Computing:AI training and inference accelerators compress interconnect pitches below 55 micrometers through 3D stacking and advanced substrate materials. United States-based hyperscale operators are qualifying Taiwan-sourced CoWoS and InFO variants for datacenter deployment.
- RF Communication:5G millimeter-wave and satellite terminals integrate antenna-in-package solutions through wafer-level fan-out. South Korean smartphone OEMs and Chinese infrastructure vendors are the primary demand anchors.
- Internet of Things:Low-power sensor nodes favor cost-optimized flip chip and wire-bond alternatives.
- Smart Devices:Wearables and hearables prioritize miniaturized wafer-level form factors.
RF Communication leads in revenue concentration. High-Performance Computing shows the steepest expansion trajectory as AI infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Taiwan's Hsinchu Science Park exceeds that of Malaysia's Penang cluster by a factor reflecting technology node differentiation. United States-based hyperscale operators pay premiums for CoWoS capacity that Malaysian flip-chip facilities cannot command. This asymmetry shapes capital allocation across the packaging value chain.
United States
Hyperscale datacenter operators in Arizona and New Mexico are pulling captive advanced packaging capacity through Intel's IDM 2.0 investments. The Department of Commerce export controls constrain certain high-performance computing technology transfers under licensing restrictions. Arizona's Phoenix metro anchors the densest domestic cluster for heterogeneous integration engineering talent.
China
Domestic AI accelerator designers are accelerating substrate material qualification under MIIT and SAMR enforcement of updated GB standards. The dual carbon goals reshape underfill compound selection criteria for environmental compliance. Yangtze River Delta packaging facilities in Jiangsu province are retooling for organic laminate alternatives to reduce emission intensity.
Taiwan
TSMC and ASE anchor the world's densest advanced packaging ecosystem in Hsinchu Science Park, pulling memory-logic stacking capacity expansion. The cluster processes the majority of high-bandwidth memory integration for AI training accelerators. Kaohsiung's emerging packaging corridor is absorbing overflow demand as CoWoS and InFO platforms reach capacity constraints.
South Korea
Samsung Electronics anchors multi-chip module roadmaps with X-Cube 3D stacking technology competing directly with Taiwanese platforms. SK Hynix is expanding high-bandwidth memory packaging capacity for hyperscale datacenter qualification. The Seoul Capital Area concentration of OSAT investment reflects government-backed semiconductor infrastructure programs.
Japan
Ajinomoto Build-up Film and similar dielectric suppliers control critical substrate input volumes for advanced interconnect architectures. METI industrial policy supports domestic material science capabilities for sub-55 micrometer pitch applications. Kyushu's packaging material cluster is deepening specialization in low-loss dielectrics for 5G millimeter-wave modules.
Multi-Chip Module Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the multi-chip module packaging value chain. Taiwan-based foundry-OSAT hybrids command premium positioning in 3D stacking and wafer-level platforms, while Malaysian and Vietnamese facilities dominate flip-chip volume production through established infrastructure. The market structure separates into captive IDM packaging divisions, independent OSATs, and substrate material specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as AI infrastructure demand compresses qualification timelines.
Among integrated device manufacturers, Intel Corporation exemplifies the captive packaging archetype through Arizona and New Mexico facility investments. Samsung Electronics and SK Hynix Inc. occupy positions within the memory-centric packaging tier, anchoring high-bandwidth memory integration roadmaps. Taiwan Semiconductor Manufacturing Company sits within the foundry-OSAT hybrid category, representing the technology leadership position in CoWoS and InFO platforms that hyperscale operators prioritize for AI accelerator deployment.
| Leading Market Players |
|---|
| Intel Corporation |
| Infineon Technologies |
| Samsung Electronics |
| Micron Technology |
| SK Hynix Inc. |
| Texas Instruments |
| STMicroelectronics |
| Amkor Technology |
| Taiwan Semiconductor Manufacturing Company |
| Others |
Supply & Pricing Matrix
Capacity reservation contracts with Taiwan-based foundry-OSAT hybrids lock in multi-year substrate allocations and price visibility for hyperscale datacenter operators, insulating qualified buyers from spot-market volatility while concentrating margin capture among Hsinchu cluster incumbents. This contract structure reinforces the bifurcation between captive supply arrangements for AI accelerator designers and transactional procurement for consumer electronics OEMs.
Pricing Analysis
Customization-premium spreads separate configured-to-order CoWoS and InFO platforms from standard flip-chip catalog offerings. Three-tier pricing structure across premium, standard, and economy levels reflects interconnect pitch requirements, with sub-55 micrometer architectures commanding substantial premiums over established wire-bond alternatives. Cost compression in consumer-grade plastic substrate modules is intensifying because South Korean and Chinese smartphone OEMs consolidate procurement volumes. Automotive electronics buyers exhibit the lowest price sensitivity due to IATF 16949 certification barriers that disqualify cost-optimized suppliers.
Supply Chain Analysis
Ajinomoto Build-up Film production in Japan's Kyushu cluster represents a chokepoint that constrains substrate material flows for advanced interconnect architectures below 55 micrometers. Manufacturing gravity centers on Taiwan, South Korea, and Japan for high-performance modules, while Malaysia and Vietnam handle flip-chip volume production. Critical inputs include organic laminate substrates, low-loss dielectrics, and high-purity copper interconnect materials. Single-source vulnerability in Japanese dielectric supply creates structural risk for capacity expansion timelines. Distribution runs through direct substrate procurement by system designers in North America and turnkey OSAT channels in East Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where switching costs between substrate-qualified suppliers and AI accelerator designers exceed eighteen months, entrenching incumbent positioning regardless of marginal price competition.
For Market Incumbents: Consolidate substrate material supply through backward integration into Ajinomoto Build-up Film alternatives or captive organic laminate production in Taiwan's Kaohsiung corridor. Add heterogeneous integration capacity in Arizona to capture Intel IDM 2.0 spillover demand. Threat substitution from hybrid bonding technology demands accelerated CoWoS-L roadmap investment to maintain pitch leadership. For New Entrants and Emerging Players: Differentiate on chemically-enhanced hermetic packaging for aerospace and defense applications where commercial volumes commoditize and certification timelines protect margin structures. India's PLI scheme for electronics manufacturing offers the most penetrable geography for substrate and OSAT investment away from East Asian concentration. Pursue qualification partnerships with European space agency procurement programs as the go-to-market anchor. For Investors and Strategic Acquirers: Substrate material specialists with documented thermal cycling performance under China's updated GB standards represent the acquisition target archetype most exposed to AI infrastructure demand inflections. Long-term viability hinges on qualification velocity rather than capacity scale, favoring targets with existing hyperscale datacenter operator relationships. Watch Co-packaged optics integration timelines as the signal indicating silicon photonics convergence maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Technology Deployment | Eliminates thermal interface resistance in logic-to-memory stacks for AI training accelerators. |
| Co-Packaged Optics Integration | Opens qualification pathways for datacenter switch architectures converging silicon photonics with electrical interconnects. |
| Substrate Material Backward Integration | Reduces single-source vulnerability to Japanese dielectric suppliers for sub-55 micrometer pitch applications. |
| India PLI Scheme Manufacturing Footprint | Diversifies OSAT capacity away from Taiwan's Hsinchu cluster concentration risks. |
| IATF 16949 Automotive Certification Investment | Captures EV power module demand as electrification multiplies semiconductor content per vehicle. |
Research Methodology
Operator-level perspectives from semiconductor packaging engineers, substrate procurement leads at hyperscale datacenter operators, OSAT operations directors, and automotive electronics qualification managers anchored the qualitative base for this analysis. Primary interview findings combined with secondary validation from SEC filings, Taiwan Stock Exchange disclosures, customs and trade data for substrate material flows, and MIIT/SAMR regulatory documentation. Bottom-up capacity modeling across Taiwan's Hsinchu and Kaohsiung clusters triangulated with top-down AI accelerator shipment forecasts.
Sensitivity analysis across interconnect pitch migration scenarios, substrate material substitution elasticities, and export control restriction intensities shaped the forecast framework. Segmentation dimensions modeled include product type, packaging technology, end-user industry, and application focus across the projection horizon. CAGRs derived from capacity expansion announcements, equipment utilization rates, and customer qualification pipeline visibility. Industry-specific inputs encompassed high-bandwidth memory integration roadmaps and China's dual carbon goal compliance timelines for underfill compound selection.
The analysis sits within stated boundaries; outcomes outside sustained AI infrastructure investment, stable Taiwan Strait logistics, and gradual hybrid bonding cost reduction would require recalibration. Forecasts reflect documented assumptions regarding substrate supplier concentration and equipment licensing restrictions. Practitioners should keep alternative scenarios live as US Department of Commerce export control enforcement and China's GB standards evolution reshape qualification pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronics Packaging
Consumer Electronics Packaging Market
Electronics Packaging
Asia-Pacific Consumer Electronics Packaging Market
Electronics Packaging
Power Module Packaging Market
Electronics Packaging
Europe and USA Consumer Electronics Packaging Market
Electronics Packaging
Electronic Wrapper Market
Electronics Packaging
Europe Consumer Electronics Packaging Market
Electronics Packaging
Fan-Out Wafer Level Packaging Market
Electronics Packaging
North America Consumer Electronics Packaging Market
Electronics Packaging
Electronic Goods Packaging Market
Electronics Packaging
Mobile Phone Accessories Packaging Market
Electronics Packaging
Anti-Counterfeit Electrical and Electronics Packaging Market
Electronics Packaging
Asia-Pacific Battery Packaging Market
Electronics Packaging
Global Display Packaging Market
Electronics Packaging
MEMS Packaging Solder Market
Electronics Packaging
Industrial Electronics Packaging Market
Electronics Packaging
Global Mobile Phones Packaging Market