
 Anti-Counterfeit Electrical and Electronics Packaging Market | 2026-2036
Anti-Counterfeit Electrical and Electronics Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Counterfeit Electrical and Electronics Packaging Market Outlook
Polyethylene terephthalate with embedded holographic threads is recalibrating cost structures across tamper-evident layers. Avery Dennison Corporation leverages its film-coating infrastructure to dominate substrate supply for premium electronics. 3M Company anchors its position through adhesive formulations that survive reflow soldering temperatures. CCL Industries Inc. specializes in multi-layer labels that integrate both visible and covert authentication features.
Anti-counterfeit electrical and electronics packaging encompasses engineered substrates, printed security elements, and digital verification interfaces designed to prevent unauthorized duplication of semiconductor, component, and finished-device packaging. Holographic diffraction gratings operating at 600-1200 lines per millimeter provide optical verification without power requirements, while RFID inlays at 13.56 MHz enable automated supply-chain authentication. Among packaging types, shrink sleeves capture expanding share in consumer electronics due to their 360-degree surface coverage and resistance to removal without destruction. RFID technology leads value contribution as automotive component suppliers mandate item-level tracking from Tier 2 vendors through final assembly.
The US FDA and FCC jointly shape demand through medical-device packaging rules and electromagnetic emission standards for embedded authentication electronics. The EU's REACH regulation restricts certain pigment chemistries in holographic foils, pushing converters toward compliant alternatives. China's SAMR enforces GB standards for traceability markings on domestically sold electronics. Stakeholders must weigh regulatory compliance costs against the channel-protection value of multi-layer authentication architectures as counterfeit penetration deepens in secondary markets.
Market Dynamics
The EU's Digital Product Passport mandate is forcing electronics brands to rebuild packaging architectures around traceable substrates, compressing converter lead times while expanding authentication layer complexity.
Growth Catalysts
- NFC-enabled factory gate verification:Smartphone manufacturers across Vietnam and Thailand now embed near-field communication tags at origin to track component provenance through assembly.
- REACH-compliant holographic chemistry:ECHA restrictions on legacy pigment formulations are accelerating adoption of compliant diffraction gratings in premium electronics packaging.
- Automotive Tier 2 mandates:Item-level RFID tracking requirements from German and Japanese vehicle assemblers are pulling authentication demand through semiconductor supply chains.
Market Restraints
- Silver and rare-earth input volatility:Conductive ink formulations depend on spot-priced precious metals, squeezing converter margins during commodity spikes.
- Substrate supply concentration:PET film with embedded security threads sources primarily from three Southeast Asian petrochemical complexes, creating single-point vulnerability.
- Reflow soldering thermal limits:Adhesive authentication layers face degradation above 260°C, excluding their use from high-temperature ceramic component packaging.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for domestic mobile device assembly are creating first-mover advantage for authentication substrate providers establishing local coating capacity.
- Blockchain-physical convergence:Immutable ledger integration with tamper-evident seals enables end-to-end provenance verification for medical-grade semiconductors.
- Direct-to-retailer authentication portals:Bypassing traditional distributor channels, packaging converters now sell serialized verification systems straight to consumer electronics brands.
Industry Challenges
- Multi-standard electromagnetic compliance:FCC emission limits for embedded RFID differ from EU RED directives, forcing dual-certification engineering for global substrate designs.
- Legacy serialization system integration:Pharmaceutical-track-and-trace infrastructure from the 2010s requires expensive middleware to interface with modern electronics authentication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Counterfeit Electrical and Electronics Packaging Market |
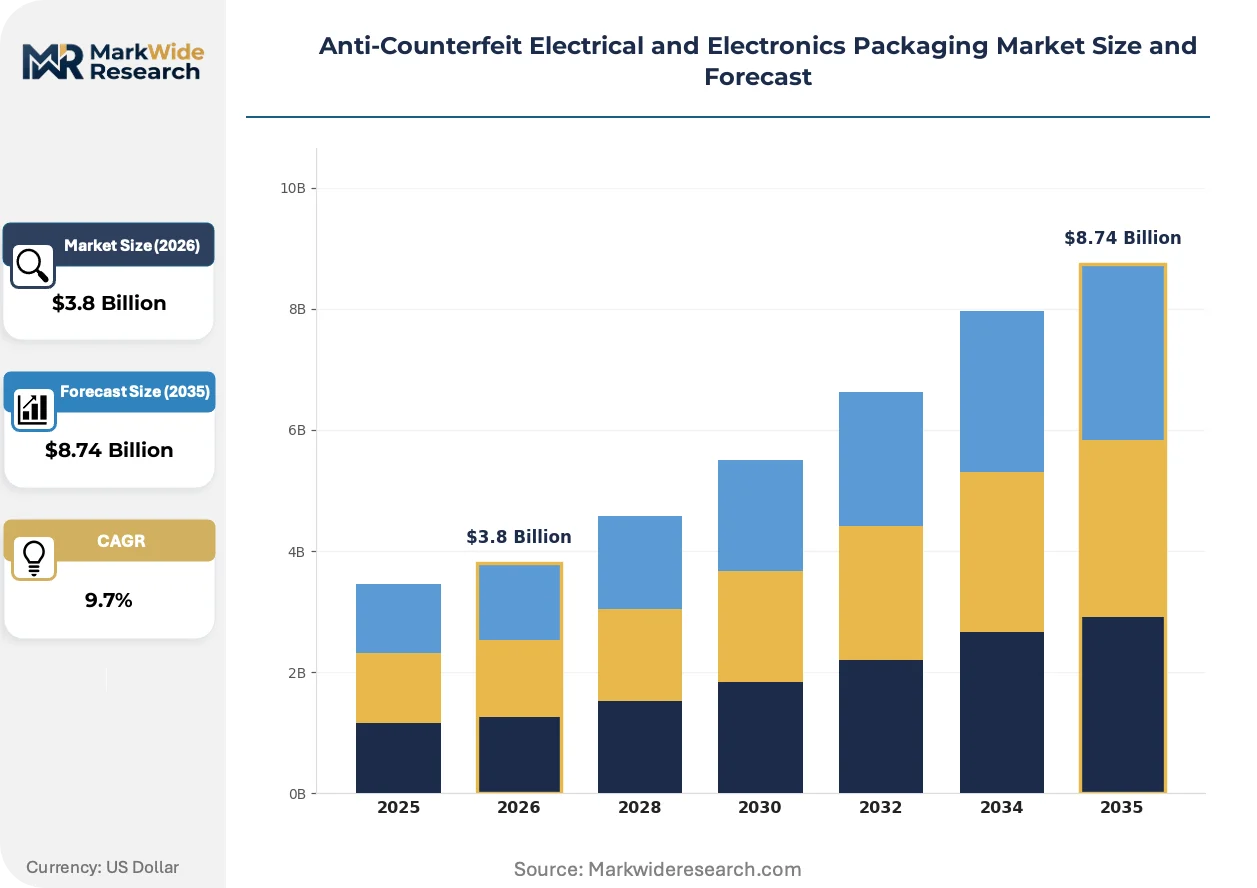
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Labels, Tags, Holograms, Barcodes Technology: RFID, NFC, QR Codes, Digital Watermarking End User: Consumer Electronics, Automotive Components, Industrial Equipment, Pharmaceuticals Packaging Type: Boxes, Pouches, Blister Packs, Shrink Sleeves |
| Companies Covered | Avery Dennison Corporation, 3M Company, CCL Industries Inc., Zebra Technologies Corporation, SICPA Holding SA, SATO Holdings Corporation, AlpVision SA, Authentix Inc., DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Counterfeit Electrical and Electronics Packaging Market Strategic Shifts
Authentication packaging is absorbing digital identity layers at the substrate level, blurring the boundary between physical tamper evidence and automated supply-chain verification. Three developments are compressing technology adoption cycles.
Polyethylene terephthalate films with embedded holographic threads are absorbing optical verification functions previously handled by separate overlay applications. Consumer electronics brands in South Korea and Taiwan specify these substrates for smartphone box packaging, eliminating secondary hot-stamping operations. The convergence is compressing converter equipment footprints while raising minimum order thresholds for security-thread integration.
REACH regulation amendments from ECHA are restricting chromate-based pigments in holographic foil manufacturing. Electronics packaging converters serving EU markets now source compliant diffraction coatings from specialized chemical suppliers in Switzerland and Germany. Medical device manufacturers face the steepest reformulation timelines, as their packaging must simultaneously satisfy EMA traceability rules and ECHA substance restrictions.
Certification-driven procurement now dominates supplier selection for automotive electronics authentication. German Tier 1 suppliers mandate ISO 27001-aligned data handling for any RFID inlay provider, while Japanese assemblers require JIS-standard tamper-evidence testing. This behavioral shift is visible most acutely in Vietnam's northern industrial corridor, where Samsung and Apple suppliers now pre-qualify packaging vendors against dual certification regimes before contract negotiation.
Anti-Counterfeit Electrical and Electronics Packaging Market Segmentation
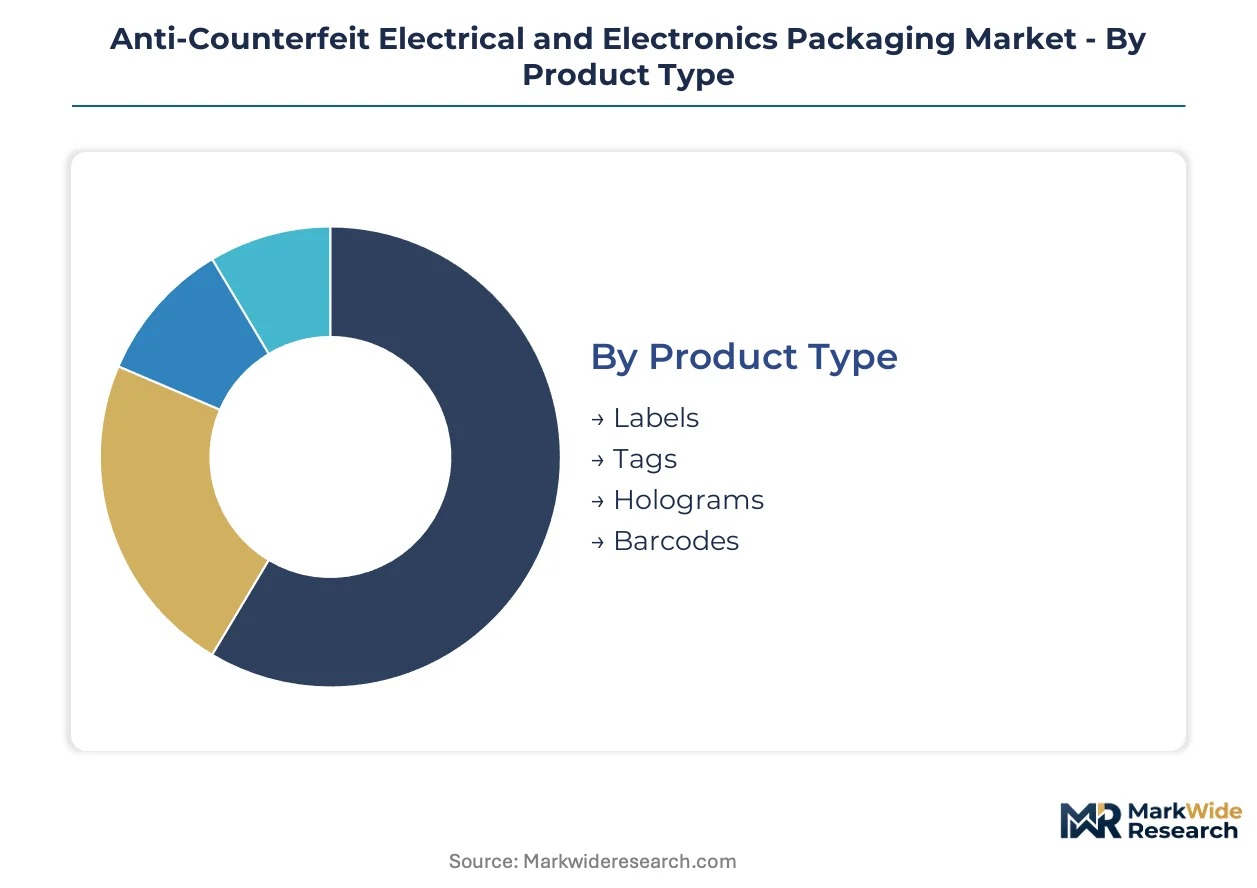
Authentication packaging segments diverge sharply between high-volume commodity substrates and precision-engineered premium tiers. Electronics brands configure multi-layer security architectures by mixing physical tamper evidence with digital verification interfaces across these four dimensions.
Product Type:
Volume applications favor printable substrates while premium electronics specify multi-feature authentication elements.
- Labels:Pressure-sensitive adhesive constructions with embedded microtext and color-shifting inks dominate smartphone accessory packaging. Vietnamese contract manufacturers specify PET-based labels with destructible facestocks for charger and cable verification.
- Tags:Hangtag formats with integrated NFC inlays enable consumer-facing authenticity checks without app downloads. Demand clusters in South Korean consumer electronics retail, where Samsung and LG mandate tag-based verification for warranty activation.
- Holograms:Diffractive optical elements with custom origination patterns.
- Barcodes:Serialized 2D matrix codes for supply-chain track-and-trace.
Mature deployment sits with Labels. Newer deployment is concentrated in Tags.
Technology:
Automotive and medical applications pull high-reliability identification systems while consumer goods favor cost-optimized verification.
- RFID:UHF and HF inlays operating at 860-960 MHz and 13.56 MHz enable automated gate-to-gate tracking without line-of-sight. German and Japanese automotive assemblers mandate item-level RFID for powertrain components, forcing Tier 2 semiconductor suppliers into compliance.
- NFC:ISO 14443-compliant tags bridge physical packaging with mobile authentication experiences. Thailand and Vietnam smartphone factories embed NFC at origin for component provenance tracking through final assembly.
- QR Codes:Static and dynamic matrix symbologies for consumer verification.
- Digital Watermarking:Imperceptible signal embedding for forensic authentication.
Established infrastructure supports QR Codes. Investment flows fastest into NFC.
End User:
Regulatory intensity varies dramatically across verticals, with medical and automotive facing mandatory traceability while consumer electronics follows brand-protection logic.
- Consumer Electronics:Smartphone, laptop, and peripheral packaging with multi-layer overt and covert features. Samsung and Apple supplier clusters in Vietnam's northern industrial corridor drive specification intensity for shrink sleeve and box authentication.
- Automotive Components:ECU, sensor, and power semiconductor packaging with ISO 27001-aligned data handling. German Tier 1 suppliers pre-qualify vendors against dual certification regimes before contract award.
- Industrial Equipment:Heavy electrical and automation component authentication.
- Pharmaceuticals:Medical-device packaging with FDA and EMA traceability compliance.
Procurement sophistication peaks in Automotive Components. Volume expansion runs through Consumer Electronics.
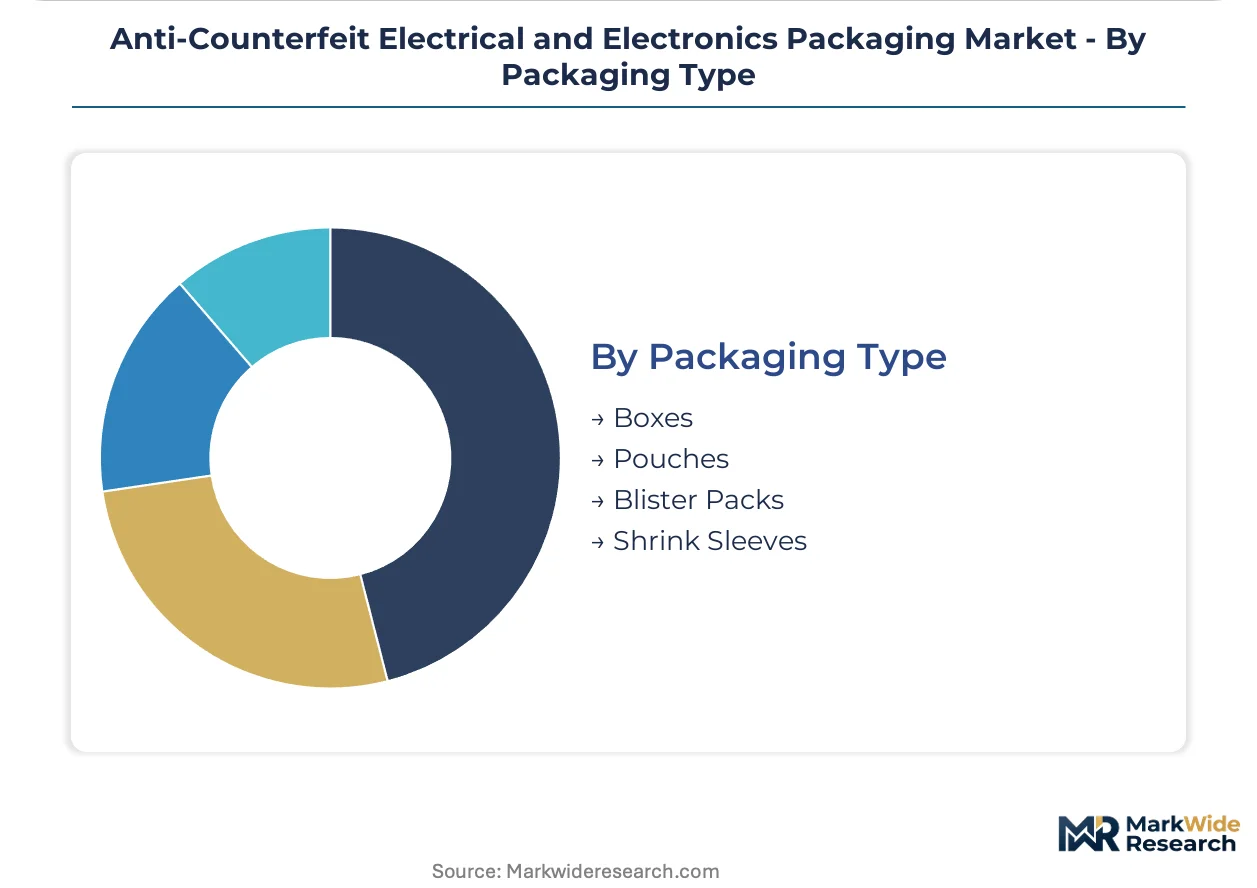
Packaging Type:
Surface coverage requirements and removal resistance dictate format selection across electronics sub-categories.
- Shrink Sleeves:360-degree PET or PVC sleeves with integrated holographic bands and tear strips. Taiwan and South Korean brands specify these for premium smartphone boxes, eliminating secondary hot-stamping while ensuring destruction upon removal.
- Boxes:Folding carton and rigid box constructions with embedded security threads and tamper-evident closures. REACH-compliant substrate sourcing from Swiss and German chemical suppliers serves EU-market medical electronics.
- Pouches:Flexible film formats for component and accessory packaging.
- Blister Packs:Thermoformed cavities with printed lidding foil for small electronics.
Format standardization centers on Boxes. Specification innovation concentrates in Shrink Sleeves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for anti-counterfeit electrical and electronics packaging concentrates in manufacturing corridors where smartphone assembly, automotive electronics, and semiconductor packaging intersect with stringent traceability mandates.
Vietnam
Samsung and Apple supplier clusters in the northern industrial corridor drive specification intensity for NFC-enabled tags and shrink sleeve authentication. SAMR-aligned GB standards for traceability markings on re-exported electronics create dual-compliance pressure for contract manufacturers. Bac Ninh and Thai Nguyen provinces host the densest concentration of smartphone component packaging converters.
Germany
Automotive Tier 1 suppliers mandate ISO 27001-aligned data handling for RFID inlay providers serving ECU and power semiconductor packaging. REACH restrictions on chromate-based pigments force converters toward compliant diffraction coatings from Swiss chemical suppliers. Bavaria and Baden-Württemberg anchor demand through Volkswagen, BMW, and Bosch supplier networks.
China
Domestic electronics brands and export-oriented contract manufacturers absorb PET films with embedded holographic threads for smartphone box authentication. SAMR enforces GB standards for traceability markings on domestically sold devices, compressing converter lead times. The Yangtze River Delta and Pearl River Delta concentrate substrate coating capacity and security thread integration.
South Korea
Samsung and LG mandate NFC tag-based verification for warranty activation in consumer electronics retail, pulling authentication demand through component supply chains. MFDS traceability rules for medical-grade semiconductors add regulatory layering. The Seoul Capital Area and Busan-Ulsan corridor host premium electronics packaging specification centers.
United States
FDA and FCC jointly shape demand through medical-device packaging rules and electromagnetic emission standards for embedded authentication electronics. Reflow soldering thermal limits exclude adhesive authentication layers from high-temperature ceramic component packaging in defense and aerospace applications. Texas and California concentrate semiconductor packaging authentication procurement.
Anti-Counterfeit Electrical and Electronics Packaging Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with adhesive and substrate specialists commanding premium tiers while regional converters serve volume applications. The vendor base organizes around three strategic archetypes: integrated material-science conglomerates with film-coating infrastructure, specialized authentication technology developers with digital verification platforms, and regional packaging converters with security-thread integration capabilities. Competitive moves concentrate on REACH-compliant chemistry reformulation and dual-certification engineering for FCC and EU RED electromagnetic compliance.
Within the integrated material-science tier, Avery Dennison Corporation and 3M Company occupy positions that exemplify substrate and adhesive specialization respectively. Avery Dennison leverages film-coating infrastructure to anchor supply for premium electronics authentication substrates. 3M represents the thermal-resistance archetype through adhesive formulations that survive reflow soldering temperatures. CCL Industries Inc. sits within the multi-layer label specialist category, integrating visible and covert authentication features for semiconductor and component packaging applications.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| 3M Company |
| CCL Industries Inc. |
| Zebra Technologies Corporation |
| SICPA Holding SA |
| SATO Holdings Corporation |
| AlpVision SA |
| Authentix Inc. |
| DuPont |
| Others |
Value Chain & Pricing Dynamics
Silver spot prices and rare-earth oxide benchmarks cascade through conductive ink formulations into three distinct authentication packaging tiers. PET film with embedded holographic threads anchors premium pricing, while commodity label substrates compete on volume scale in Southeast Asian converter markets.
Pricing Analysis
High-volume label converters in Vietnam and Thailand operate on thin per-unit margins, while multi-layer substrate specialists in South Korea and Germany capture premium pricing through REACH-compliant chemistry and dual-certification engineering. Price differentiation hinges on ISO 27001-aligned data handling for automotive RFID inlays and thermal resistance ratings for reflow soldering applications. Cost compression in standard-grade NFC tags is intensifying because Samsung and Apple suppliers are consolidating procurement around pre-qualified vendor pools. Contract manufacturers in Vietnam's northern corridor exhibit the highest price sensitivity, whereas German Tier 1 automotive suppliers prioritize certification-grade reliability over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Samsung and Apple supplier clusters, while specialized distributors serve mid-tier consumer electronics brands. Raw material dependencies draw from silver for conductive inks, rare-earth elements for holographic pigments, and PET resin from Southeast Asian petrochemical complexes. Geographic concentration centers on Vietnam for smartphone packaging authentication, Germany for automotive component verification, and China for substrate coating capacity. Single-source vulnerability in PET film with embedded security threads creates structural risk. Distribution runs through converter-direct relationships with electronics brands, bypassing traditional wholesale channels for serialized verification systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Authentication substrate supply is tightening around REACH-compliant holographic chemistry capacity, propping pricing power for converters with certified coating infrastructure. The EU's Digital Product Passport mandate compresses lead times while expanding layer complexity, favoring incumbent material-science specialists.
For Market Incumbents: Deploy backward integration into PET film coating to secure holographic thread supply against Southeast Asian petrochemical concentration. Acquire Swiss and German chemical suppliers with ECHA-compliant diffraction coating expertise before reformulation deadlines tighten. Lock in long-term offtake agreements with rare-earth oxide processors to hedge against commodity volatility in holographic pigment inputs.
For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing opens a window for domestic authentication substrate capacity, targeting smartphone assembly clusters in Tamil Nadu and Karnataka. Focus on NFC-enabled factory gate verification systems for Vietnam's northern industrial corridor, where Samsung and Apple suppliers are pre-qualifying new vendors. Lead with blockchain-physical convergence offerings for medical-grade semiconductor provenance, a segment where incumbent footprint remains shallow.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier label converters with security-thread integration capabilities in Vietnam and Thailand, where pricing pressure is squeezing independent operators. Monitor silver price volatility as an inflection indicator for conductive ink formulation margins. Long-term viability rests on regulatory compliance infrastructure rather than commodity substrate scale.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Chemistry Reformulation | ECHA pigment restrictions force substrate converters toward Swiss and German specialty coating suppliers. |
| Dual-Certification Engineering Investment | Simultaneous FCC and EU RED compliance enables single-SKU global supply to automotive Tier 1 vendors. |
| Blockchain-Physical Convergence Development | Immutable ledger integration with tamper-evident seals satisfies medical-device traceability mandates from FDA and EMA. |
| Direct-to-Brand Channel Bypass | Serialized verification portals eliminate distributor margins for packaging converters serving consumer electronics OEMs. |
| Rare-Earth Supply Security Hedging | Long-term offtake agreements with oxide processors insulate holographic foil margins against spot price spikes. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with packaging converters, electronics OEM procurement directors, and authentication technology R&D heads combined with secondary validation from ECHA substance restriction databases, SAMR GB standard filings, and FCC equipment authorization records. Bottom-up triangulation across substrate shipment volumes and top-down reconciliation against electronics assembly output estimates ensured cross-verified demand sizing.
Granularity-level modeling deployed country-specific regulatory cluster analysis alongside technology adoption curves for RFID, NFC, and holographic authentication formats. Segmentation dimensions included packaging type, end-use vertical, and certification tier across the projection horizon. CAGRs derived from fitted growth curves applied to base-year volume estimates, with electronics assembly output and traceability mandate implementation timelines as key forecast inputs.
Caveats apply where ECHA REACH amendment timelines or FCC emission standard revisions could materially shift the outlook. Forecasts rest on assumptions regarding smartphone assembly growth in Vietnam and automotive electronics traceability mandate expansion in Germany. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronics Packaging
Industrial Electronics Packaging Market
Electronics Packaging
Global Mobile Phones Packaging Market
Electronics Packaging
Fan-Out Wafer Level Packaging Market
Electronics Packaging
Asia-Pacific Battery Packaging Market
Electronics Packaging
MEMS Packaging Solder Market
Electronics Packaging
Europe and USA Consumer Electronics Packaging Market
Electronics Packaging
Power Module Packaging Market
Electronics Packaging
Multi-Chip Module Packaging Market
Electronics Packaging
North America Consumer Electronics Packaging Market
Electronics Packaging
Electronic Goods Packaging Market
Electronics Packaging
Mobile Phone Accessories Packaging Market
Electronics Packaging
Europe Consumer Electronics Packaging Market
Electronics Packaging
Electronic Wrapper Market
Electronics Packaging
Global Display Packaging Market
Electronics Packaging
Consumer Electronics Packaging Market
Electronics Packaging
Asia-Pacific Consumer Electronics Packaging Market