
 Europe Consumer Electronics Packaging Market | 2026-2036
Europe Consumer Electronics Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Consumer Electronics Packaging Market Insights
Subscription-based packaging recovery services is expanding the value proposition beyond one-time material supply. DS Smith Plc leverages closed-loop recycling infrastructure across its continental network. Smurfit Kappa Group plc anchors premium rigid box production for smartphone launches in the Nordics. Mondi Group specializes in lightweight paperboard solutions that reduce logistics emissions for cross-border e-commerce.
Europe consumer electronics packaging encompasses protective enclosures engineered from paperboard, molded fiber, corrugated board, and selective polymer films, designed to shield devices from mechanical shock, electrostatic discharge, and moisture ingress during transit and retail display. The primary commercial purpose centers on brand differentiation at point-of-sale while satisfying EU-mandated Extended Producer Responsibility obligations for end-of-life recovery. Rigid box formats command margin pools in premium smartphone and gaming console segments where unboxing experience drives consumer retention. Carton and molded fiber categories are capturing volume growth from home appliance producers responding to Plastic Packaging Tax pressures in the United Kingdom and Italy. Blister pack demand faces structural compression as accessories suppliers abandon PVC clamshells under REACH substance restrictions.
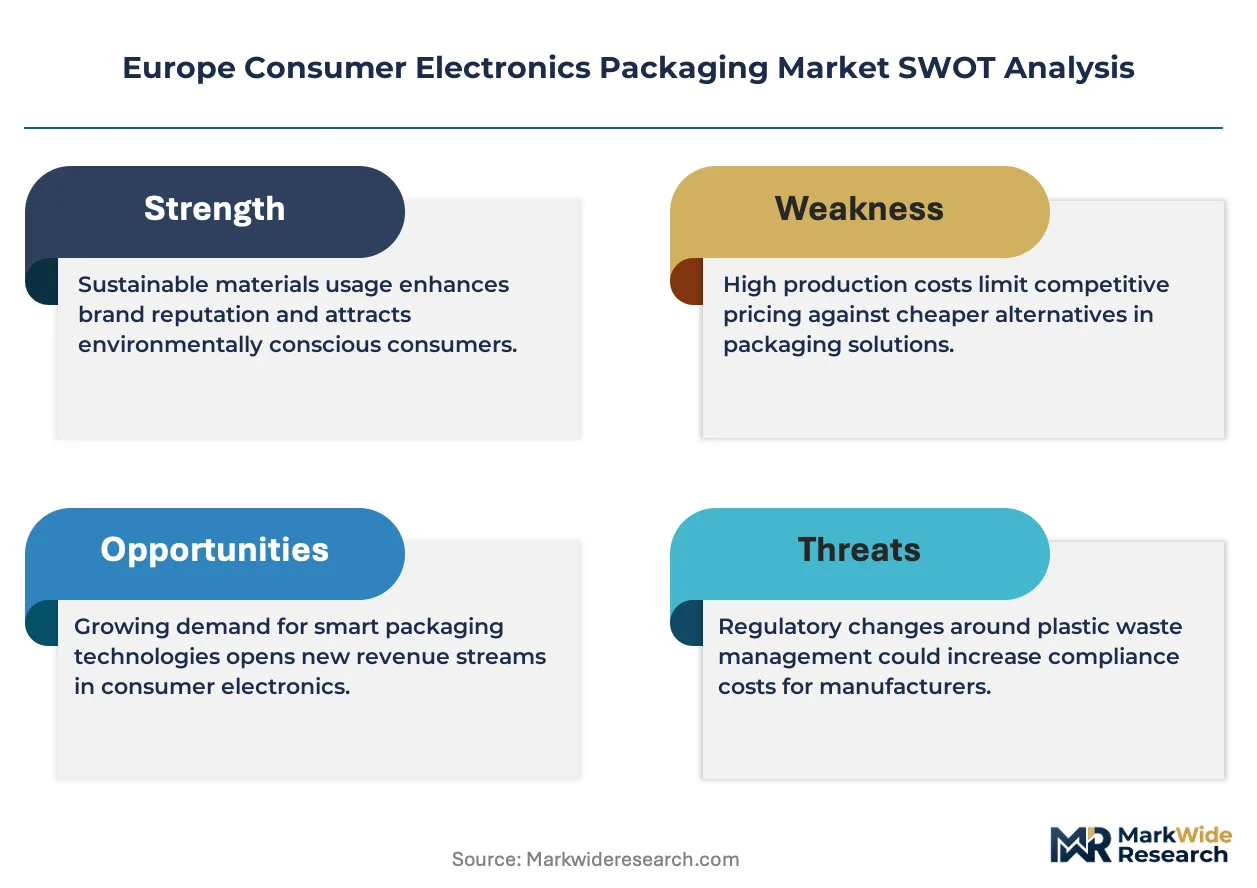
The EU Green Deal, REACH, and F-Gas Regulation collectively mandate reduced plastic content, traceable recycled feedstocks, and lower-carbon manufacturing processes across member states. ECHA substance evaluations have restricted specific phthalates and heavy metals common in legacy electronics films, forcing reformulation of flexible pouch laminates. National transpositions in Germany and France impose additional sorting and labeling requirements that reshape distributor procurement specifications. Stakeholders must monitor pending Packaging and Packaging Waste Regulation revisions to calibrate material roadmaps before compliance deadlines crystallize.
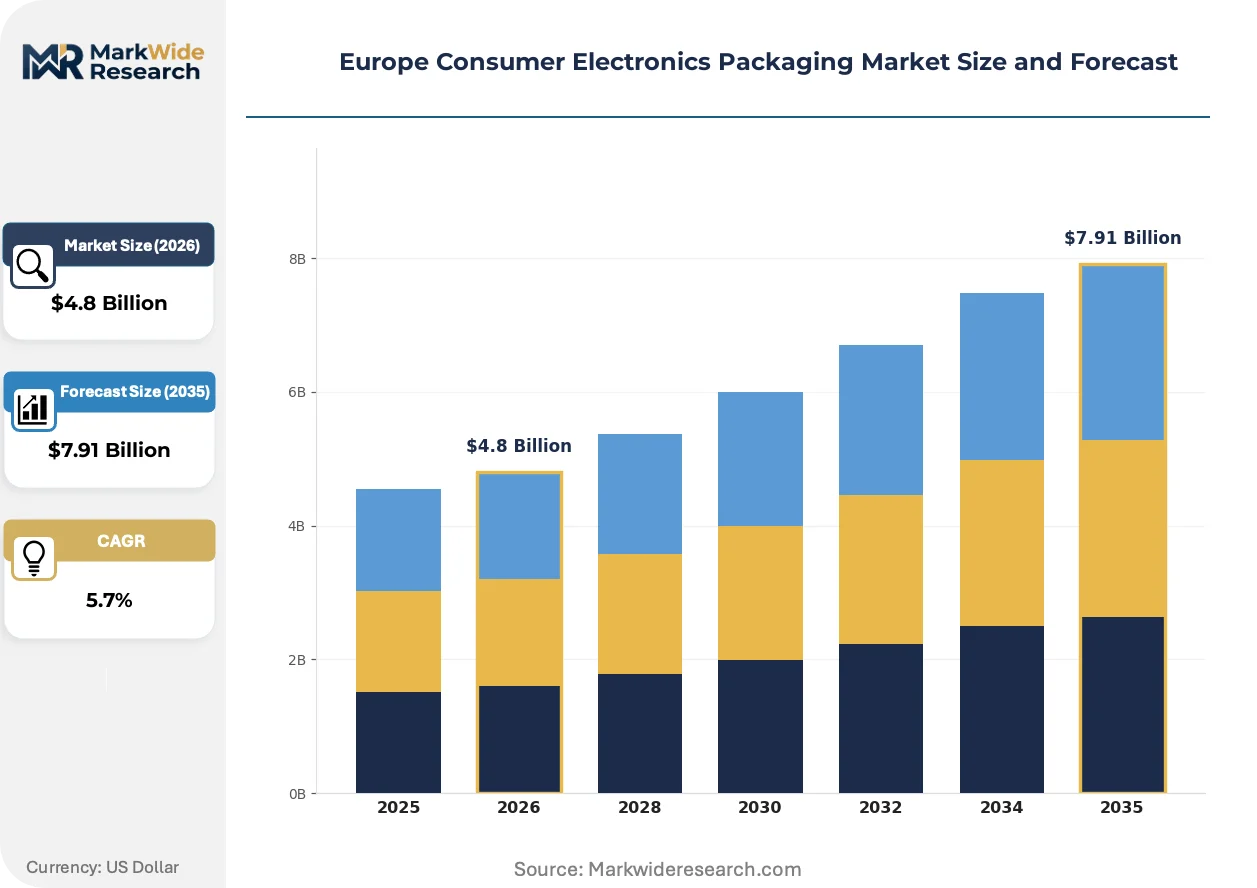
Market Dynamics
EU Green Deal mandates and REACH substance restrictions are forcing material transitions across European electronics supply chains, compressing demand for legacy plastic formats while expanding fiber-based alternatives. Packaging converters must reconfigure production lines to maintain compliance with evolving Extended Producer Responsibility frameworks.
Growth Catalysts
- REACH phthalate restrictions:Legacy PVC blister packs face mandatory phase-out, redirecting accessory manufacturers toward paperboard and molded fiber substitutes.
- German smartphone manufacturing corridors:Berlin and Munich production clusters generate concentrated demand for premium rigid box formats with unboxing-optimized designs.
- Fiber molding advances:Precision thermoforming of agricultural waste fibers now achieves tolerances matching expanded polystyrene for shock absorption.
Market Restraints
- Recycled pulp cost volatility:OCC (old corrugated containers) feedstock prices fluctuate with municipal collection efficiency, squeezing converter margins.
- Barrier coating supply concentration:Water-based oxygen barrier chemistries for molded fiber remain concentrated among three specialty chemical suppliers in the Netherlands and Belgium.
- Heat-seal adhesive technical limitations:Bio-based hot-melt formulations lack the tack strength of synthetic alternatives for high-speed carton closing lines.
Strategic Opportunities
- Polish e-commerce fulfillment expansion:Central European logistics hubs near Warsaw and Łódź create demand for lightweight paperboard designs optimized for parcel network sorting.
- EU Packaging and Packaging Waste Regulation revisions:Pending mandatory recycled content thresholds will favor early movers with secured fiber supply contracts.
- Smart packaging convergence:Integration of printed NFC antennas with folding carton substrates enables authentication and re-ordering functionality.
Industry Challenges
- Color-matching skill scarcity:Lithographic press operators capable of maintaining brand-specified Pantone consistency across recycled fiber substrates remain scarce in Eastern European converting plants.
- ESG certification timeline compression:FSC Chain of Custody audits and Carbon Trust footprint verifications create six-month qualification delays for new supplier onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Consumer Electronics Packaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Rigid Box, Carton, Blister Pack, Flexible Pouch Material: Plastic, Paperboard, Glass, Metal End User: Smartphone Manufacturers, Home Appliance Producers, Gaming Companies, Accessories Suppliers Distribution Channel: Online Retail, Brick-and-Mortar Stores, Wholesale, Distributors |
| Companies Covered | DS Smith Plc, Smurfit Kappa Group plc, Sonoco Products Company, Billerud AB, Stora Enso Oyj, Mondi Group, WestRock Company, International Paper Company, Huhtamäki Oyj, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Consumer Electronics Packaging Market Trends and Innovations
Material science breakthroughs and regulatory tightening are converging to reshape European electronics packaging, with automation and circularity emerging as dominant design principles. Converters are racing to deploy formats that satisfy both performance specifications and emerging compliance thresholds.
Robotic pick-and-place systems integrated with vision-guided quality inspection are automating the assembly of complex rigid box formats previously dependent on manual folding and insertion. German premium audio equipment manufacturers have adopted these lines for limited-edition product launches, reducing labor content per unit by half while tightening dimensional tolerances for magnetic closure alignment. This automation is compressing the viable scale threshold for domestic production, enabling shorter-run customization without offshore cost penalties.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances (PFAS) in food-contact materials are extending to electronics packaging through precautionary supply chain policies. ECHA's 2023 restriction proposal triggered immediate reformulation of grease-resistant coatings for gaming console outer wraps, with converters accelerating migration to silicone-based barrier alternatives. Nordic retailers have imposed PFAS-free procurement specifications ahead of formal mandates, creating a two-tier supplier qualification landscape across the region.
Direct-to-consumer subscription models for refurbished smartphones are fragmenting traditional OEM-controlled packaging specifications. French and Dutch circular economy platforms now specify standardized carton dimensions across multiple device brands to optimize reverse logistics density, displacing brand-unique box formats. This specification consolidation concentrates purchasing power with platform operators, compressing converter margins while rewarding suppliers with pan-European distribution networks.
Europe Consumer Electronics Packaging Market Segmentation
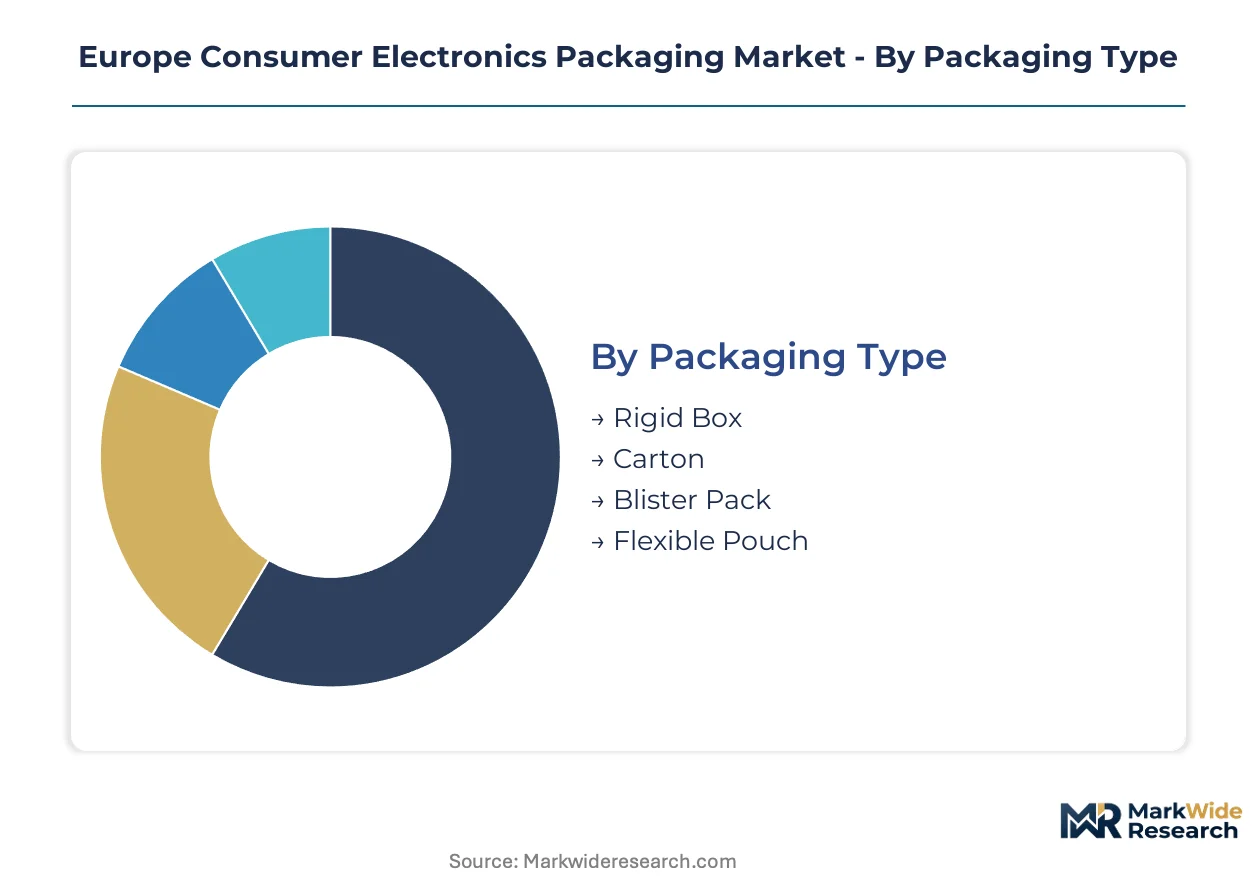
Segmentation in European electronics packaging reveals divergent margin structures between premium unboxing experiences and cost-optimized transit protection. Material compliance timelines and channel-specific logistics requirements further stratify procurement specifications across the value chain.
Packaging Type:
Volume shipments concentrate in lightweight formats for e-commerce fulfillment, while premium tiers command rigid constructions for flagship product launches.
- Rigid Box:Constructed from laminated paperboard with magnetic closures and velvet-flocked inserts. German and French smartphone OEMs specify these formats for flagship launches where unboxing videos drive social media engagement. REACH-compliant adhesives and FSC-certified substrates add qualification complexity for converters.
- Carton:Folding carton designs using recycled fiber grades with water-based barrier coatings. Polish and Dutch e-commerce fulfillment hubs specify these for home appliance shipments to minimize dimensional weight charges in parcel networks. Carton formats are gaining share fastest as Plastic Packaging Tax pressures mount.
- Blister Pack:Thermoformed PVC and PET clamshells with printed card backing, now declining as REACH phthalate restrictions and retailer sustainability mandates force transition.
- Flexible Pouch:Multi-layer laminates with aluminum foil barriers for cable and accessory protection, facing reformulation pressure as PFAS coatings face ECHA evaluation.
Mature deployment sits with Blister Pack formats in legacy retail fixtures. Newer deployment is concentrated in Carton designs optimized for automated sortation in Central European logistics hubs.
Material:
Regulatory pressure on carbon intensity and end-of-life recovery is reordering material hierarchies across converter supply chains.
- Paperboard:Bleached and unbleached kraft grades with customized caliper for crush resistance. Nordic retailers and German electronics OEMs have mandated minimum recycled content thresholds that favor established pulp suppliers with integrated recycling infrastructure. Paperboard specifications now dominate premium smartphone and audio equipment segments.
- Plastic:rPET, rPP, and bio-based PE films with controlled crystallinity for thermoforming. Italian and UK appliance manufacturers retain plastic formats for moisture-sensitive components, though volumes compress under Extended Producer Responsibility fee escalations. Recycled feedstock certification delays create supply bottlenecks.
- Metal:Aluminum tins and steel cases for limited-edition collectibles and high-value accessories, occupying niche positioning in gaming merchandise.
- Glass:Tempered glass containers for premium audio vacuum tubes and specialty components, negligible volume but irreplaceable for specific technical requirements.
Material qualification timelines stretch longest for Plastic formats requiring ECHA substance documentation. Paperboard specifications achieve faster supplier onboarding through established FSC Chain of Custody pathways.
End User:
Procurement sophistication varies sharply between vertically integrated OEMs and fragmented accessories suppliers.
- Smartphone Manufacturers:Berlin and Munich production clusters specify rigid box formats with embedded NFC authentication tags and magnetic closure systems. German OEMs impose quarterly sustainability audits that disqualify converters lacking carbon footprint verification.
- Gaming Companies:Nordic and UK publishers commission collectible packaging with holographic finishes and thermochromic inks for limited-edition console releases. These specifications prioritize unboxing spectacle over unit cost minimization.
- Home Appliance Producers:Polish and Italian manufacturers of small domestic appliances specify carton formats optimized for pallet density in cross-border distribution.
- Accessories Suppliers:Fragmented cable and charger vendors in Shenzhen-to-Rotterdam supply chains face margin compression from REACH compliance costs and retailer sustainability scorecards.
Contract duration extends longest with Smartphone Manufacturers seeking supply security for flagship launch windows. Accessories Suppliers rotate suppliers most frequently on price.
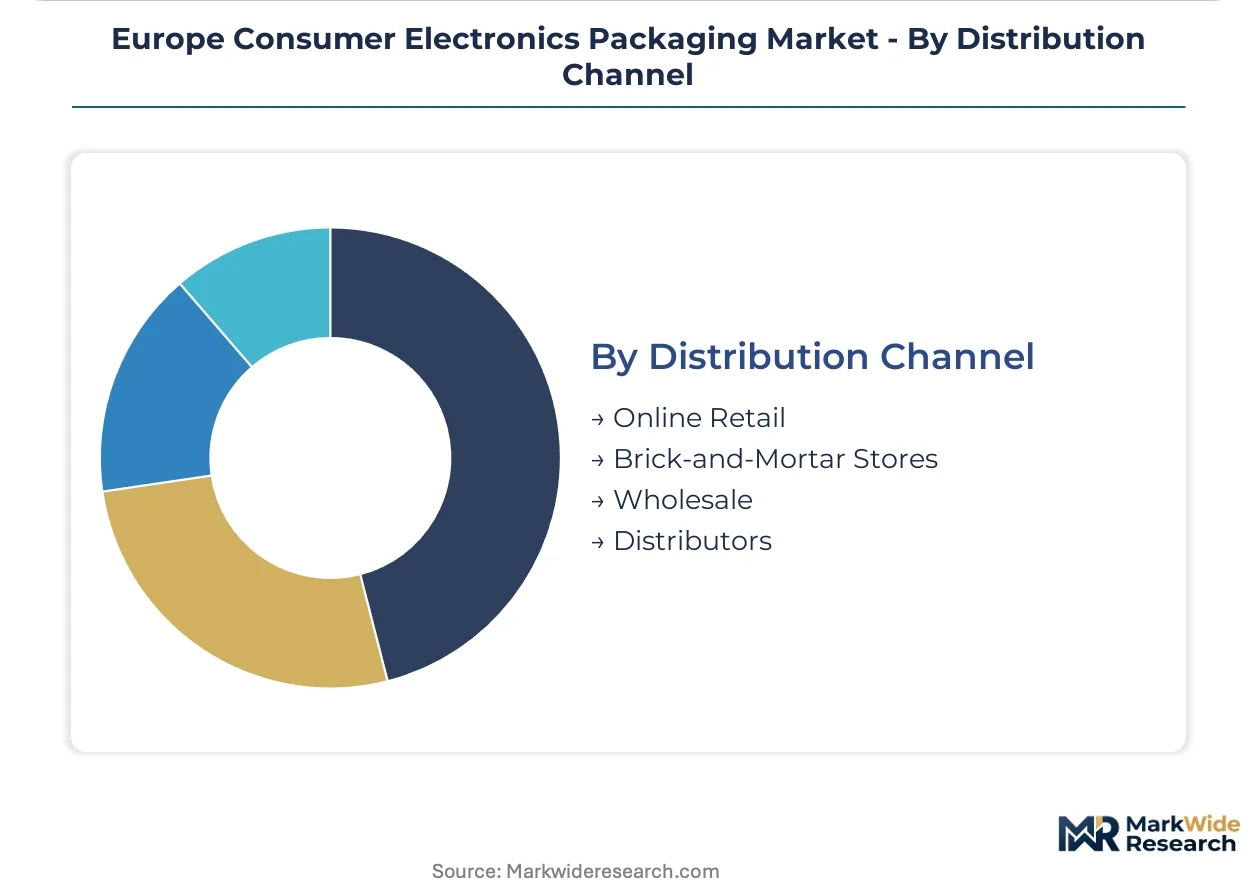
Distribution Channel:
Channel-specific damage rates and return logistics economics drive divergent packaging specifications.
- Online Retail:Direct-to-consumer shipments through Amazon and regional platforms require drop-test-certified designs with minimized void fill. Dutch and German fulfillment centers specify carton formats compatible with automated pack stations and returns processing.
- Brick-and-Mortar Stores:Electronics retailers in France and Italy demand shelf-ready packaging with tear-away hang tabs and anti-theft tag integration. These formats prioritize retail presentation over transit compression resistance.
- Distributors:Pan-European electronics wholesalers in the Netherlands specify neutral outer cartons enabling brand-agnostic inventory pooling across multiple OEMs.
- Wholesale:Volume procurement by enterprise resellers emphasizes pallet optimization and mixed-SKU container loading efficiency over individual unboxing experience.
Specification standardization has advanced furthest in Online Retail channels converging on parcel-network-optimized dimensions. Brick-and-Mortar Stores retain the most brand-customized format diversity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in Germany and Poland generate the bulk of protective packaging supply, while consumption concentrates in Western European retail corridors where premium unboxing specifications originate. This geographic split shapes logistics costs and compliance calibration across converter networks.
Germany
Berlin and Munich smartphone manufacturing corridors drive rigid box demand for flagship launches with magnetic closure systems. ECHA substance evaluations under REACH have restricted specific phthalates in flexible pouch laminates, forcing local converters to reformulate adhesive chemistries. Bavarian production clusters now host automated rigid box assembly lines serving premium audio equipment manufacturers.
France
Paris-based electronics retailers specify shelf-ready packaging with tear-away hang tabs and anti-theft integration for brick-and-mortar distribution. The EU Green Deal national transpositions impose additional sorting and labeling requirements that reshape procurement specifications. Auvergne-Rhône-Alpes hosts molded fiber thermoforming facilities supplying agricultural waste-based shock absorption components.
Poland
Warsaw and Łódź logistics hubs create concentrated demand for lightweight paperboard designs optimized for automated parcel network sorting. Extended Producer Responsibility frameworks mandate end-of-life recovery documentation that compresses supplier onboarding timelines. Silesian converting plants are expanding capacity to serve cross-border e-commerce fulfillment into Germany and the Netherlands.
Netherlands
Rotterdam distribution corridors specify neutral outer cartons enabling brand-agnostic inventory pooling across multiple OEMs. PFAS restriction proposals from ECHA have triggered immediate migration to silicone-based barrier coatings for gaming console outer wraps. Eindhoven-region chemical suppliers concentrate water-based oxygen barrier chemistries for molded fiber applications.
United Kingdom
London and Southeast England electronics retailers face Plastic Packaging Tax pressures that accelerate carton format adoption for home appliance shipments. FSC Chain of Custody audits and Carbon Trust footprint verifications create qualification delays for new supplier onboarding. Midlands-based converters specialize in drop-test-certified designs for Amazon and regional platform fulfillment centers.
Europe Consumer Electronics Packaging Market Competitive Landscape
Top-tier vendors anchor premium rigid box production for flagship smartphone launches, while mid-tier converters compete on carton volume for e-commerce fulfillment channels. The vendor base stratifies across integrated pulp-to-box operators, specialty coating developers, and regional folding carton specialists. Three archetypes dominate: fiber-based sustainability specialists, automation-enabled custom rigid box producers, and scale-driven corrugated volume suppliers. Competitive moves concentrate on M&A to secure recycled pulp supply contracts and strategic partnerships with chemical developers for barrier coating innovation.
Among integrated paperboard producers, DS Smith Plc and Smurfit Kappa Group plc exemplify the sustainability-specialist archetype with closed-loop recycling infrastructure across continental networks. Mondi Group occupies a position within the lightweight substrate tier, representing converters focused on logistics emission reduction for cross-border e-commerce. These three entities anchor the competitive landscape through distinct geographic and technical positioning rather than overlapping capability claims.
| Leading Market Players |
|---|
| DS Smith Plc |
| Smurfit Kappa Group plc |
| Sonoco Products Company |
| Billerud AB |
| Stora Enso Oyj |
| Mondi Group |
| WestRock Company |
| International Paper Company |
| Huhtamäki Oyj |
| Others |
Pricing and Supply Chain Analysis
German and French smartphone OEM procurement concentration anchors contract-based long-term offtake pricing for premium rigid box formats, while Polish e-commerce fulfillment hubs drive spot-market volatility in lightweight carton categories. REACH compliance costs and FSC certification premiums stratify converter margins across the value chain.
Pricing Analysis
Margin tightening in standard-grade carton production reflects OCC feedstock price volatility and Plastic Packaging Tax escalations in the United Kingdom and Italy. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified rigid boxes with magnetic closures from recycled-content cartons and uncoated molded fiber substitutes. Cost-down pressure on economy-tier blister pack alternatives accelerates as accessory manufacturers abandon PVC formats under REACH phthalate restrictions. Accessories suppliers in Shenzhen-to-Rotterdam supply chains exhibit highest price sensitivity, while German flagship smartphone OEMs prioritize unboxing performance over unit cost.
Supply Chain Analysis
Skilled lithographic press operators capable of Pantone consistency on recycled fiber substrates remain scarce in Eastern European converting plants, constraining capacity expansion in Poland and the Czech Republic. Pulp supply concentrates in Nordic integrated producers and German recycled fiber processors, with barrier coating chemistries for molded fiber anchored in Netherlands and Belgium specialty chemical suppliers. Single-source vulnerability sits with water-based oxygen barrier formulations from three Eindhoven-region developers. Distribution runs through Rotterdam distribution corridors for pan-European inventory pooling and Warsaw-Łódź logistics hubs for Central European e-commerce fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe consumer electronics packaging market functions as a cost-of-compliance story where REACH substance restrictions and Extended Producer Responsibility frameworks erect barrier-to-entry moats favoring converters with pre-qualified supply chains and carbon footprint verification.
For Market Incumbents: To counter margin compression from recycled pulp cost volatility, DS Smith Plc and Smurfit Kappa Group plc should deepen backward integration into municipal collection infrastructure across Germany and the Netherlands. Securing captive supply of OCC feedstock through long-term municipal contracts insulates converter margins from collection efficiency fluctuations. For New Entrants and Emerging Players: Accessories suppliers facing REACH compliance cost burdens represent an underserved buyer archetype seeking standardized carton formats across multiple device brands. Polish and Romanian converters can capture this volume by offering FSC-certified folding cartons with water-based barrier coatings at price points below German and French rigid box specialists. Direct-to-consumer circular economy platforms in France and the Netherlands provide a channel entry point through specification consolidation for refurbished smartphone packaging. For Investors and Strategic Acquirers: The window for entry favors mid-tier converters with established Eindhoven-region chemical partnerships and automated rigid box assembly lines serving Berlin and Munich production clusters. Acquisition targets should demonstrate secured fiber supply contracts ahead of EU Packaging and Packaging Waste Regulation recycled content mandates. Pending ECHA PFAS restriction finalization serves as the critical signal to watch for barrier coating reformulation winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Infrastructure | DS Smith Plc's closed-loop network across continental Europe secures captive OCC feedstock supply against municipal collection volatility. |
| Barrier Coating Reformulation Partnership | Converters accelerating silicone-based PFAS alternatives with Eindhoven-region chemical suppliers gain qualification advantage under ECHA timelines. |
| Automated Rigid Box Assembly Deployment | German premium audio equipment manufacturers reduce labor content by half while tightening magnetic closure tolerances for limited-edition launches. |
| FSC Chain of Custody Certification Investment | Nordic retailers and German electronics OEMs mandate minimum recycled content thresholds that disqualify uncertified competitors. |
| Central European Logistics Hub Proximity | Polish converting plants near Warsaw and Łódź optimize lightweight paperboard designs for automated parcel network sorting density. |
Research Methodology
Document review covered EU regulatory filings including ECHA substance restriction proposals and Packaging and Packaging Waste Regulation drafts, complemented by interviews with packaging procurement managers at German smartphone OEMs, sustainability directors at Nordic retailers, plant managers at Polish converting facilities, and barrier coating R&D leads at Netherlands specialty chemical suppliers. Secondary validation drew from trade customs data, FSC Chain of Custody audit records, and SEC filings of publicly traded paperboard producers. Bottom-up volume modeling across packaging type, material, end user, and distribution channel segments was cross-referenced against top-down macroeconomic indicators for consumer electronics shipments.
Historical shipment patterns were cross-referenced against panel input from converter executives and retail category buyers to establish baseline demand curves across the projection horizon. Segmentation dimensions modeled include packaging format rigidity tiers, recycled content certification levels, OEM vertical integration status, and channel-specific damage rate requirements. CAGRs were derived through regression analysis of material substitution elasticities under regulatory compliance cost scenarios, with inputs from pulp futures pricing and Extended Producer Responsibility fee schedules across member states.
Revisions become necessary when ECHA accelerates PFAS restriction timelines, when EU Packaging and Packaging Waste Regulation recycled content thresholds exceed converter readiness, or when municipal collection efficiency disruptions alter OCC feedstock availability. Material deviation in named triggers warrants pause and re-evaluation of capacity expansion assumptions and barrier coating migration schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronics Packaging
MEMS Packaging Solder Market
Electronics Packaging
Global Display Packaging Market
Electronics Packaging
Europe and USA Consumer Electronics Packaging Market
Electronics Packaging
Mobile Phone Accessories Packaging Market
Electronics Packaging
Asia-Pacific Consumer Electronics Packaging Market
Electronics Packaging
Electronic Wrapper Market
Electronics Packaging
Fan-Out Wafer Level Packaging Market
Electronics Packaging
Consumer Electronics Packaging Market
Electronics Packaging
Industrial Electronics Packaging Market
Electronics Packaging
Multi-Chip Module Packaging Market
Electronics Packaging
North America Consumer Electronics Packaging Market
Electronics Packaging
Electronic Packaging Market
Electronics Packaging
Electronic Goods Packaging Market
Electronics Packaging
Global Mobile Phones Packaging Market
Electronics Packaging
Power Module Packaging Market
Electronics Packaging
Asia-Pacific Battery Packaging Market