
 Power Module Packaging Market | 2026-2036
Power Module Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Power Module Packaging Market Analysis
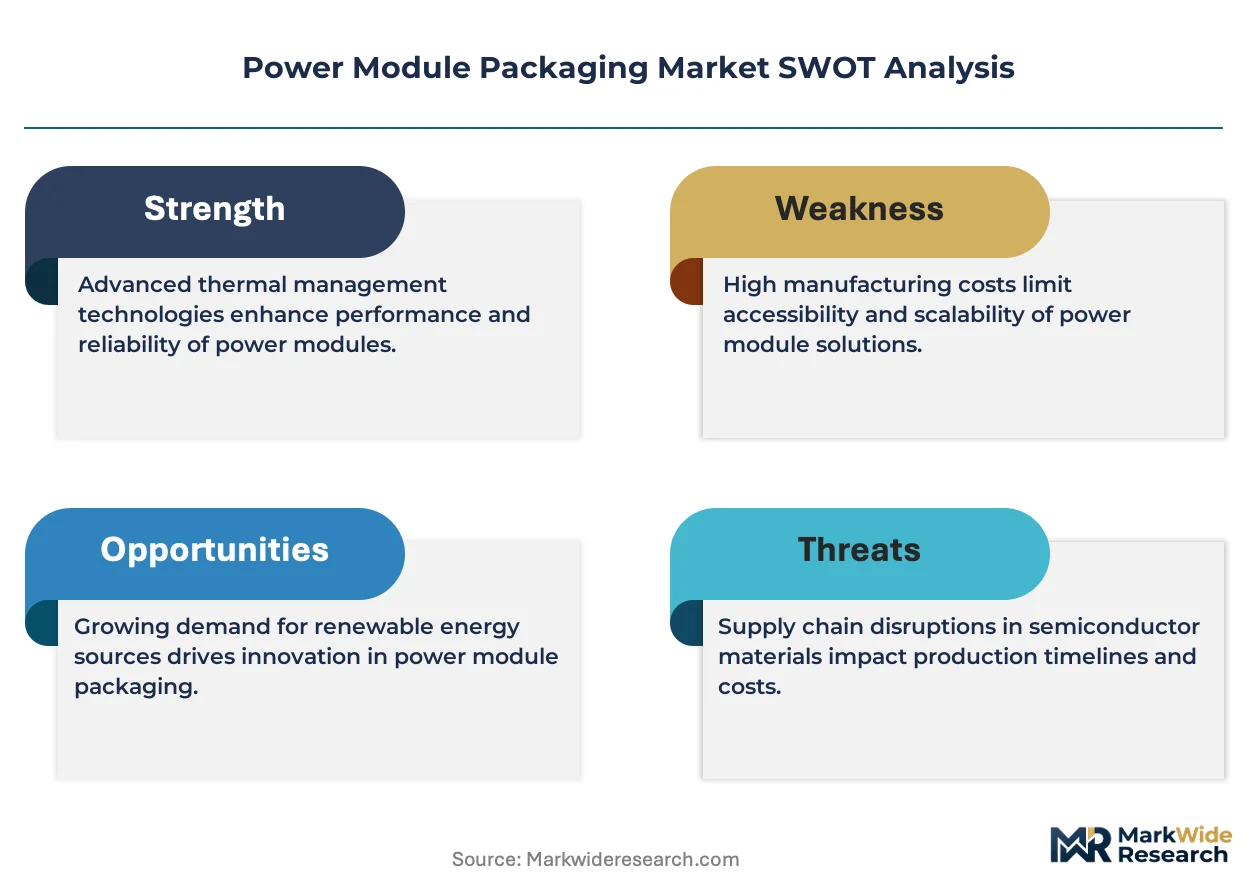
Software-defined thermal management is rebalancing what power module suppliers actually monetize. Infineon Technologies leverages its captive silicon carbide wafer capacity to anchor premium module lines. STMicroelectronics competes through integrated gallium nitride solutions that extend its addressable power range. Semikron Danfoss specializes in standardized platform architectures that simplify customer integration cycles.
Power module packaging encloses and interconnects semiconductor dies within thermally conductive, electrically isolated housings to enable reliable power conversion at voltages from 600V to 1.7kV and currents exceeding 300A. Ceramic substrates, typically aluminum oxide or aluminum nitride, provide the critical thermal path while maintaining dielectric strength above 15kV/mm for traction inverter applications. Ceramic-based packages command the highest margin pools due to thermal performance requirements in automotive and aerospace end uses. Wire bond interconnection remains the dominant assembly method, though flip chip configurations are gaining share in high-frequency consumer electronics applications where parasitic inductance must stay below 5nH.
The EU Green Deal and F-Gas Regulation are tightening thermal management efficiency mandates that directly shape module substrate selection and cooling system design. China's MIIT enforces GB standards for electric vehicle power electronics that dictate minimum conversion efficiency thresholds. Japan's METI coordinates domestic semiconductor packaging consortia to secure supply chain resilience for automotive and industrial customers. Stakeholders must monitor how regional efficiency mandates diverge on substrate material specifications and whether ceramic supply concentration in specific manufacturing clusters creates procurement vulnerability.
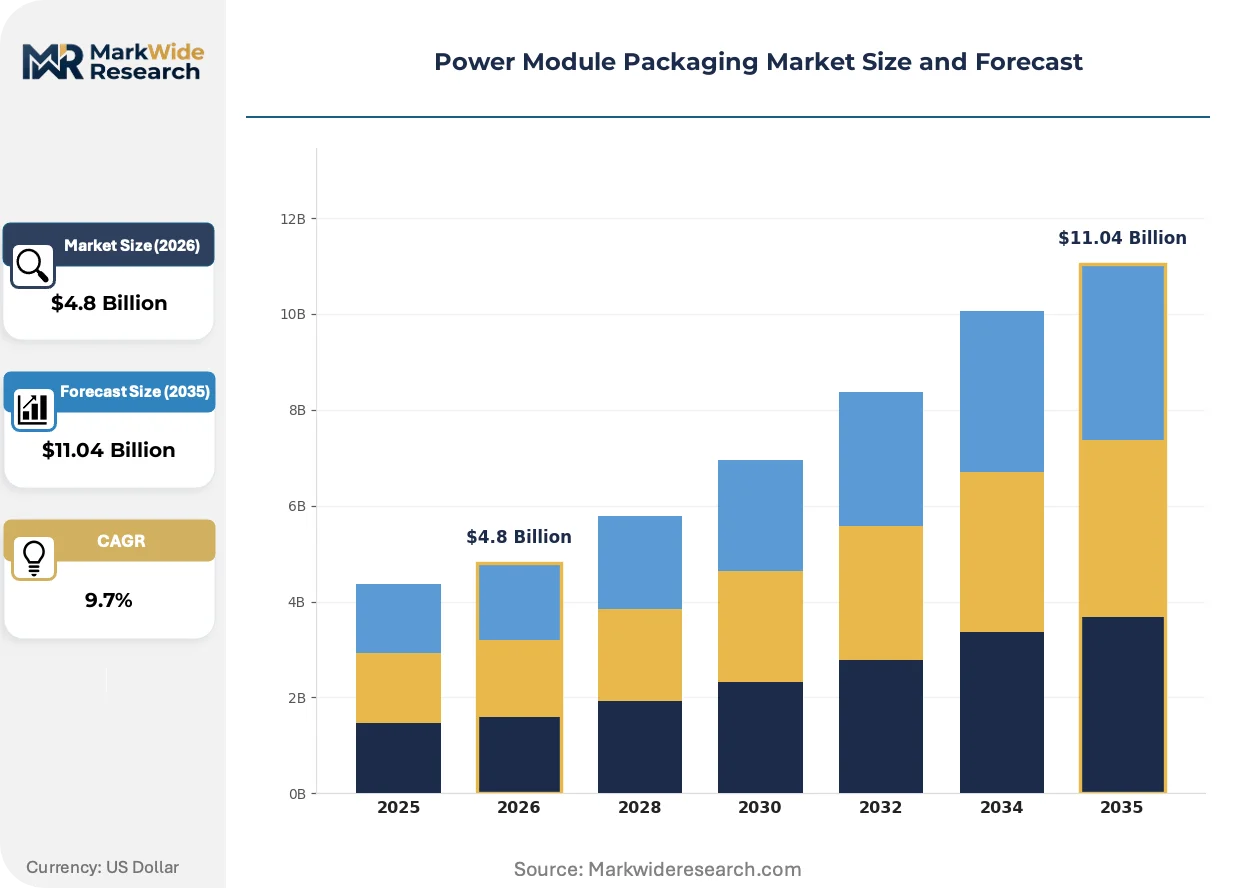
Market Dynamics
Silicon carbide die penetration in automotive traction inverters is compressing module packaging thermal budgets and forcing substrate material upgrades across supplier portfolios.
Growth Catalysts
- EU F-Gas Regulation:The regulation mandates lower-global-warming-potential cooling systems in power electronics, accelerating demand for advanced ceramic substrates that reduce thermal management complexity.
- China MIIT dual carbon goals:China's efficiency mandates for electric vehicle power electronics are pulling silicon carbide module adoption through minimum conversion efficiency thresholds.
- Automotive electrification supply chains:German, Japanese, and South Korean vehicle manufacturers are scaling procurement of wide-bandgap modules, concentrating demand in East Asian packaging centers.
Market Restraints
- Aluminum nitride substrate concentration:Ceramic substrate manufacturing clusters in specific East Asian regions create procurement vulnerability for European and North American module assemblers.
- Wire bond reliability limits:Traditional aluminum wire interconnection faces thermal cycling fatigue constraints above 175°C junction temperatures, restricting high-temperature silicon carbide deployment.
- Flip chip capital intensity:Migration to flip chip configurations requires substantial cleanroom and precision placement equipment investment, favoring large-scale captive producers.
Strategic Opportunities
- India automotive power electronics:India's PLI scheme for electric vehicle manufacturing creates white space for module packaging localization serving domestic two-wheeler and three-wheeler electrification.
- GaN-SiC hybrid integration:Convergence of gallium nitride control electronics with silicon carbide power stages enables multi-chip module architectures that extend addressable voltage-current envelopes.
- Software-defined thermal management:Embedded sensor integration and real-time thermal modeling create service revenue streams beyond hardware shipment.
Industry Challenges
- Power electronics packaging engineering scarcity:The specialized skill set combining thermal, electrical, and mechanical design for wide-bandgap devices concentrates in automotive semiconductor hubs.
- AEC-Q101 qualification timelines:Automotive-grade module certification cycles extend 18-24 months, compressing product development windows against rapidly evolving inverter specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Module Packaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Discrete, Integrated, Hybrid, Module Connection Type: Wire Bond, Flip Chip, Press Fit, Solder Material: Ceramic, Metal, Plastic, Silicon End User: Automotive, Industrial, Aerospace, Consumer Electronics |
| Companies Covered | STMicroelectronics, Semikron Danfoss, Infineon Technologies, Texas Instruments, Toshiba, Mitsubishi Electric, ON Semiconductor, ROHM Semiconductor, Fuji Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Module Packaging Market Emerging Trajectories
Power module packaging is bifurcating between standardized platform architectures for volume automotive applications and customized high-reliability solutions for aerospace and defense end uses.
Silver sintering die attach is overtaking traditional solder-based thermal interfaces in silicon carbide modules. The technology enables junction temperatures exceeding 200°C while reducing thermal resistance by half. Automotive inverter manufacturers in Germany and South Korea are adopting silver sintering at scale for 800V platform launches. This thermal interface transition is overtaking conventional packaging cost structures and favoring suppliers with captive materials processing capabilities.
The EU Green Deal's cascading efficiency mandates are tightening thermal management specifications across industrial power conversion equipment. The F-Gas Regulation specifically targets refrigerant-based cooling systems, pushing module designers toward passive and liquid-cooled ceramic substrates. Packaging suppliers serving European industrial drive manufacturers are responding with aluminum nitride substrate portfolios and integrated pin-fin baseplates.
Automotive OEMs are consolidating power module supplier panels and demanding direct engineering collaboration on inverter thermal stack design. Tier-1 inverter manufacturers are losing procurement autonomy as vehicle makers specify substrate materials, cooling interfaces, and sensor integration requirements. This vertical coordination is most pronounced in Japanese and South Korean automotive supply chains, where keiretsu-style relationships are deepening around silicon carbide module development programs.
Power Module Packaging Market Segmentation
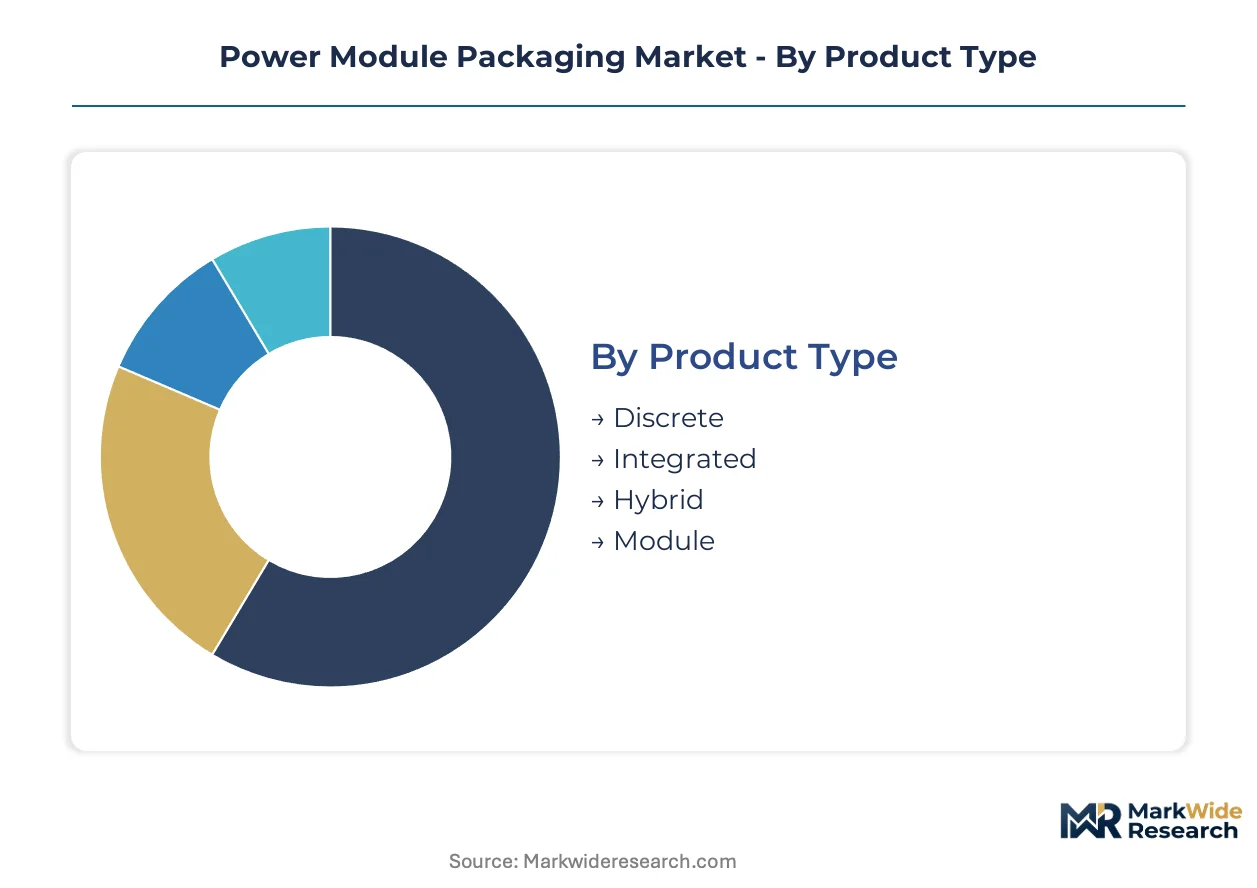
Power module packaging segmentation reveals distinct certification burdens across product architectures. AEC-Q101 automotive qualification, MIL-STD-883 defense screening, and JEDEC industrial standards each map to specific segment combinations, creating divergent margin structures and supplier capability requirements.
Product Type:
Discrete packages carry lighter certification loads than integrated or hybrid architectures, though automotive traction applications impose uniform AEC-Q101 demands across all product categories.
- Discrete:Single-die packages with standardized footprints dominate consumer power supplies and low-voltage industrial drives. Demand concentrates in Shenzhen and Dongguan manufacturing clusters serving white-goods and LED lighting OEMs.
- Integrated:Multi-die configurations combining gate drivers with power stages require more complex thermal modeling and extended qualification cycles. German inverter manufacturers specify integrated modules for 800V EV platforms, pulling silicon carbide adoption through minimum efficiency thresholds.
- Hybrid:Silicon-silicon carbide combinations optimize cost-performance tradeoffs in mid-voltage industrial motor drives. Japanese industrial equipment makers favor hybrid architectures for 400V servo systems.
- Module:Fully integrated power stages with embedded cooling interfaces face the heaviest certification burdens. Aerospace applications in Toulouse and Hamburg require DO-160 environmental screening atop standard industrial qualifications.
Leading the category by volume: Discrete. Growing fastest: Module.
Connection Type:
Interconnection method determines thermal cycling reliability and parasitic inductance, with flip chip commanding premium positioning in high-frequency segments.
- Wire Bond:Aluminum wire interconnection remains the dominant assembly method for modules below 175°C junction temperatures. South Korean automotive suppliers maintain wire bond dominance for cost-sensitive hybrid vehicle inverters.
- Flip Chip:Copper pillar configurations reduce parasitic inductance below 5nH for GaN-based consumer chargers. Taiwan-based OSATs specialize in flip chip power packaging for smartphone fast-charging adapters.
- Press Fit:Pin-based mechanical interconnection simplifies field replacement in railway traction systems. European rolling stock manufacturers specify press fit modules for maintainability in harsh vibration environments.
- Solder:Traditional solder attach faces displacement by silver sintering in automotive silicon carbide modules above 150kW power ratings.
Highest margin capture: Flip Chip. Steepest expansion trajectory: Press Fit.
Material:
Substrate material selection directly determines thermal performance ceilings and dielectric withstand capabilities, with ceramic substrates carrying the steepest cost premiums.
- Ceramic:Aluminum oxide and aluminum nitride substrates enable junction temperatures exceeding 175°C with thermal conductivity above 170 W/mK. Japanese material suppliers dominate high-purity aluminum nitride supply for automotive traction inverters.
- Metal:Copper and aluminum baseplates with insulating layers balance thermal performance against cost in industrial motor drives. Chinese domestic suppliers have scaled metal substrate production for photovoltaic inverter applications.
- Plastic:Thermally conductive polymer housings serve sub-100W consumer applications where cost minimization dominates. Thai manufacturing clusters specialize in high-volume plastic power module assembly for appliance motors.
- Silicon:Silicon interposers and embedded die configurations enable highest-density integration in data center power delivery. US hyperscalers specify silicon-based power integration for AI accelerator voltage regulation modules.
Margin concentration: Ceramic. Volume leadership: Metal.
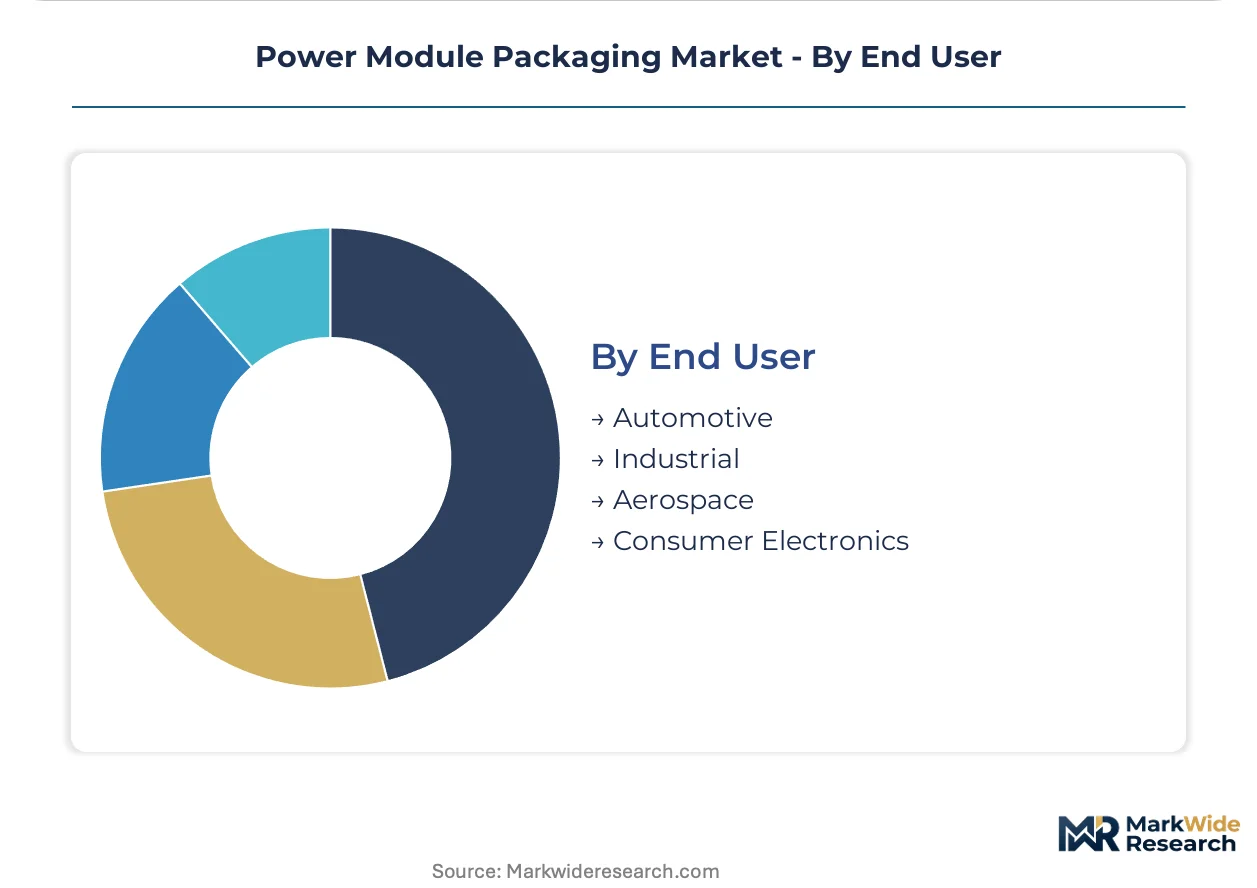
End User:
End-use segmentation separates qualification-intensive automotive and aerospace applications from industrial and consumer segments with faster product cycles.
- Automotive:Traction inverter and onboard charger applications impose AEC-Q101 screening plus OEM-specific production part approval processes. German, Japanese, and South Korean vehicle manufacturers consolidate supplier panels around silicon carbide module development programs.
- Industrial:Motor drives, renewable energy inverters, and uninterruptible power supplies span voltage classes from 400V to 3.3kV. EU F-Gas Regulation efficiency mandates are pushing industrial module designers toward liquid-cooled ceramic substrates.
- Aerospace:Satellite power conditioning and aircraft actuator systems require hermetic packaging and extended temperature range operation. Toulouse-based airframers specify custom ceramic packages with integrated EMI shielding.
- Consumer Electronics:Smartphone chargers and laptop adapters prioritize miniaturization and cost above thermal margins. Dongguan-based assemblers dominate high-volume consumer power module production.
Revenue concentration: Automotive. Fastest qualification cycles: Consumer Electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dongguan and Shenzhen manufacturing clusters dominate consumer-grade power module assembly, while automotive-grade ceramic substrate demand concentrates in Nagoya, Seoul, and Stuttgart industrial corridors.
China
MIIT dual carbon goals and GB standards for electric vehicle power electronics are pulling silicon carbide module adoption through mandatory conversion efficiency thresholds. The Yangtze River Delta and Pearl River Delta host the densest concentrations of metal substrate production for photovoltaic inverters, with domestic suppliers scaling aluminum nitride capacity to reduce import dependency.
Germany
KBA vehicle certification requirements and EU F-Gas Regulation mandates are accelerating demand for liquid-cooled ceramic substrates in industrial drive systems. Stuttgart and Munich anchor the automotive traction inverter supply chain, where OEMs specify substrate materials and cooling interfaces directly to module suppliers.
Japan
METI coordinates domestic semiconductor packaging consortia to secure supply chain resilience for automotive and industrial customers. Nagoya and Osaka industrial zones concentrate high-purity aluminum nitride substrate manufacturing, with keiretsu relationships deepening around silicon carbide module development programs.
South Korea
MFDS and MOTIE efficiency frameworks support domestic EV platform launches requiring 800V silicon carbide traction inverters. Seoul and Busan manufacturing centers scale wire bond and silver sintering assembly capacity, with Hyundai and Kia consolidating supplier panels around captive module development.
United States
EPA efficiency standards and NHTSA electrification targets shape power module procurement for domestic EV manufacturing. Texas and Arizona semiconductor fabrication corridors attract packaging investment for data center power delivery, with hyperscalers specifying silicon interposer integration for AI accelerator voltage regulation.
Power Module Packaging Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent technology roadmaps. The market structure consolidates around captive silicon carbide wafer capacity, integrated gallium nitride solutions, and standardized platform architectures. Three archetypes dominate: vertically integrated semiconductor conglomerates, specialized power packaging foundries, and automotive-tier module assemblers. Competitive moves center on silver sintering process licensing and ceramic substrate supply agreements.
Among European vertically integrated conglomerates, Infineon Technologies and STMicroelectronics exemplify the captive materials processing tier. Semikron Danfoss occupies a position within the standardized platform specialist archetype. These three anchors represent divergent strategic postures: silicon carbide wafer ownership, gallium nitride integration breadth, and customer integration cycle compression.
| Leading Market Players |
|---|
| STMicroelectronics |
| Semikron Danfoss |
| Infineon Technologies |
| Texas Instruments |
| Toshiba |
| Mitsubishi Electric |
| ON Semiconductor |
| ROHM Semiconductor |
| Fuji Electric |
| Others |
Supply Flow & Price Mechanics
Ceramic substrate certification ladders bifurcate pricing power between automotive-grade aluminum nitride suppliers and commodity metal substrate producers. AEC-Q101 qualification timelines extend 18-24 months for traction inverter modules, concentrating premium pricing with Japanese and German substrate manufacturers while Chinese metal substrate producers compete on spot pricing for photovoltaic inverters.
Pricing Analysis
Margin tightening in standard-grade metal substrates reflects Chinese domestic capacity expansion for photovoltaic applications. Three-tier pricing structure across automotive-certified ceramic, industrial-grade metal, and consumer plastic substrates segments buyers by thermal performance requirements. Price differentiation tracks conversion efficiency thresholds mandated by China's MIIT and the EU F-Gas Regulation. Automotive OEMs exhibit lowest price sensitivity due to thermal reliability requirements, while consumer electronics assemblers in Dongguan drive aggressive cost-down negotiations.
Supply Chain Analysis
Single-source vulnerability sits with high-purity aluminum nitride substrate manufacturing concentrated in Nagoya and Osaka industrial zones. Raw material dependencies include ceramic powder feedstocks from Japanese chemical suppliers, copper baseplates from Chinese smelters, and silver sintering paste from German specialty chemical producers. Supply chain risk centers on tariff exposure for European module assemblers importing Japanese ceramic substrates. Distribution runs through Tier 1 inverter manufacturers in Stuttgart, Seoul, and Nagoya who specify materials directly to captive packaging operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power module packaging operates under aluminum nitride substrate supply constraints that prop pricing for qualified automotive grades. Foundry capacity for silver sintering die attach remains concentrated among large-scale captive producers.
For Market Incumbents: Deploy silver sintering process licensing to capture technology transfer revenues as automotive OEMs consolidate supplier panels. Infineon Technologies and STMicroelectronics should anchor backward integration into ceramic substrate supply agreements to defend against Japanese material supplier concentration. Threat of emerging GaN-SiC hybrid architectures demands accelerated R&D in multi-chip module thermal modeling capabilities. For New Entrants and Emerging Players: Tier 2 automotive inverter manufacturers in India represent the most penetrable channel partner type for module packaging localization under the PLI scheme. White space exists in two-wheeler and three-wheeler electrification supply chains where AEC-Q101 qualification burdens remain lighter. Target software-defined thermal management service contracts as a go-to-market angle that extends revenue beyond hardware shipment. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated semiconductor conglomerates seeking captive packaging capacity. Long-term viability favors targets with silver sintering process expertise and established automotive qualification records. Watch for inflection in Chinese domestic aluminum nitride capacity expansion as a signal for ceramic substrate pricing compression.| Strategic Initiative | Industry Significance |
|---|---|
| Silver Sintering Process Licensing | Technology transfer agreements with South Korean automotive suppliers accelerate 800V platform deployment. |
| Ceramic Substrate Supply Agreement | Long-term offtake contracts with Japanese material producers secure AEC-Q101 qualification continuity. |
| Software-Defined Thermal Management | Embedded sensor integration creates recurring service revenue from German OEM inverter fleets. |
| India Manufacturing Localization | Domestic assembly capacity captures PLI scheme incentives for two-wheeler electrification demand. |
| GaN-SiC Hybrid Module Development | Multi-chip architectures extend addressable voltage envelopes for next-generation traction inverters. |
Methodological Framework
Independent corroboration across power module packaging executives, automotive Tier 1 procurement directors, and ceramic substrate material suppliers underwrites the qualitative findings. Primary interviews with thermal management engineers, inverter platform architects, and semiconductor foundry operations managers combined with secondary validation from SEC 10-K filings, MIIT GB standard documentation, and EU F-Gas Regulation impact assessments. Bottom-up capacity estimates and top-down demand projections triangulate market sizing.
Rate-of-change decomposition across silicon carbide die penetration curves, substrate material substitution elasticities, and automotive platform electrification timelines structures the analytical framework. Segmentation dimensions modeled include package architecture, interconnection technology, substrate material, and end-use application across the projection horizon. CAGRs derive from vehicle production forecasts, inverter power density roadmaps, and efficiency mandate compliance trajectories.
Caveats apply where aluminum nitride supply expansion, silver sintering yield improvements, or automotive OEM supplier panel consolidation could materially shift the outlook. Deviation in Chinese domestic ceramic substrate capacity buildout would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronics Packaging
Consumer Electronics Packaging Market
Electronics Packaging
North America Consumer Electronics Packaging Market
Electronics Packaging
Multi-Chip Module Packaging Market
Electronics Packaging
MEMS Packaging Solder Market
Electronics Packaging
Fan-Out Wafer Level Packaging Market
Electronics Packaging
Asia-Pacific Battery Packaging Market
Electronics Packaging
Industrial Electronics Packaging Market
Electronics Packaging
Europe Consumer Electronics Packaging Market
Electronics Packaging
Anti-Counterfeit Electrical and Electronics Packaging Market
Electronics Packaging
Global Display Packaging Market
Electronics Packaging
Asia-Pacific Consumer Electronics Packaging Market
Electronics Packaging
Electronic Packaging Market
Electronics Packaging
Global Mobile Phones Packaging Market
Electronics Packaging
Europe and USA Consumer Electronics Packaging Market
Electronics Packaging
Electronic Goods Packaging Market
Electronics Packaging
Electronic Wrapper Market