
 Fan-Out Wafer Level Packaging Market | 2026-2036
Fan-Out Wafer Level Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Fan-Out Wafer Level Packaging Market Analysis
Panel-level fan-out packaging is expanding as a modular alternative to traditional wafer-level formats, letting buyers scale production without committing to full 300mm wafer infrastructure. TSMC leverages its CoWoS and InFO platforms to dominate high-performance computing packaging. ASE Technology Holding anchors its position through diversified OSAT capacity across Taiwan and China. Samsung Electronics competes by integrating memory and logic packaging within its captive foundry-to-assembly pipeline.
Fan-Out Wafer Level Packaging (FOWLP) reconstitutes singulated dies onto a carrier, embeds them in epoxy mold compound, and builds redistribution layers to create high-density interconnects with line/space geometries below 2μm. The primary purpose is enabling thinner packages with superior electrical performance for mobile and compute devices. Double-sided configurations lead in I/O-intensive applications like AI accelerators and networking silicon. Consumer Electronics remains the largest application segment, though Automotive is gaining traction as ADAS modules require higher reliability under thermal cycling. Organic materials still occupy the bulk of substrate choices, yet glass interposers are emerging for RF and millimeter-wave applications where dielectric stability matters.
The EPA regulates hazardous substance reporting for semiconductor manufacturing facilities under TSCA, while REACH governs chemical restrictions for products entering Europe. China's GB standards and MIIT directives shape local material qualifications and import substitution timelines. Taiwan's Industrial Development Bureau coordinates packaging R&D subsidies that reinforce the island's cluster density. Stakeholders must monitor how divergent chemical compliance regimes between the US, Europe, and China reshape mold compound supply chains and qualification timelines.
Market Dynamics
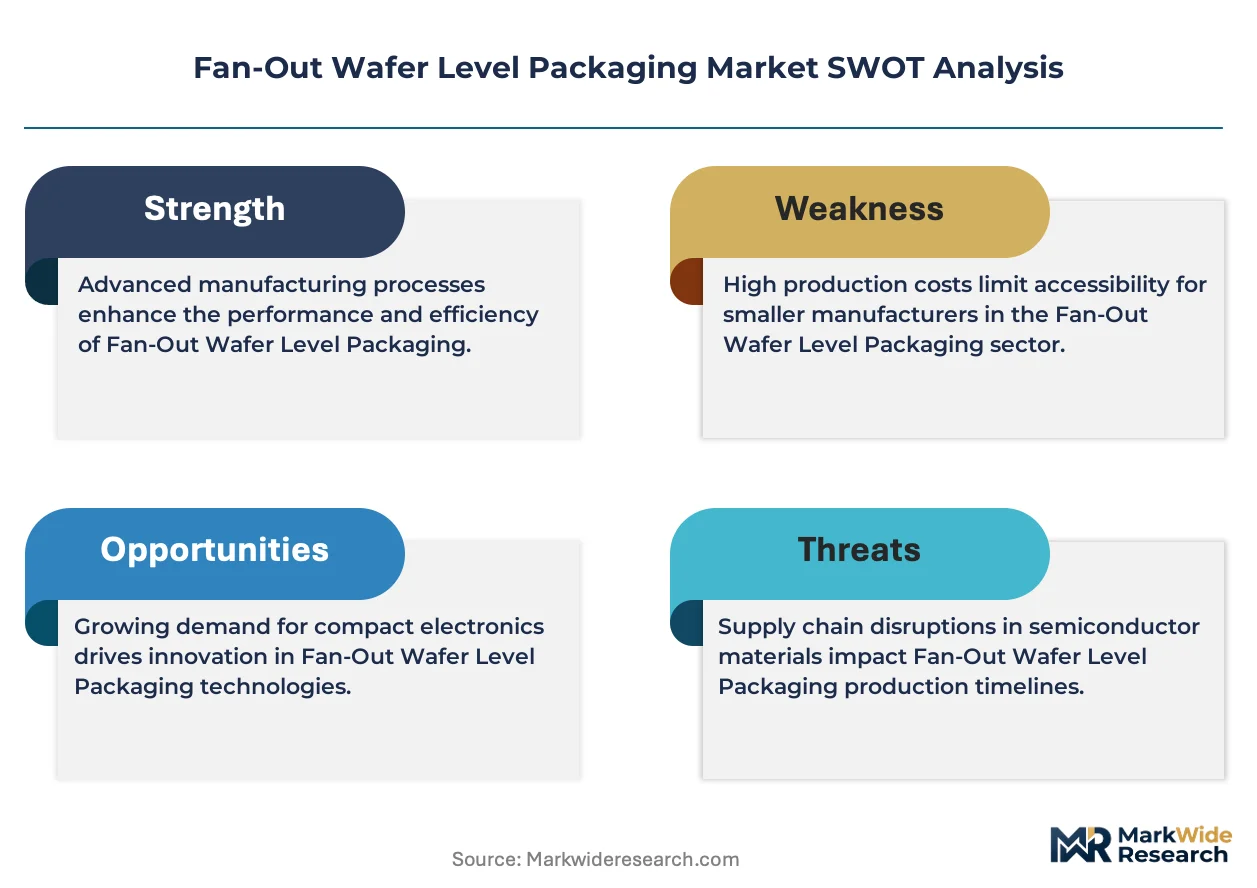
The Fan-Out Wafer Level Packaging market is undergoing structural compression as panel-level formats challenge wafer-level dominance, forcing equipment suppliers and OSATs to place divergent bets on carrier size and throughput economics.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is accelerating transitions to lower-impact epoxy mold compounds, creating qualification pull-through for European automotive and consumer electronics buyers.
- AI Accelerator Demand:High-performance computing chiplet architectures require double-sided FOWLP configurations with sub-2μm line/space geometries, expanding addressable substrate area per die.
- Taiwan's IDB Subsidies:The Industrial Development Bureau coordinates packaging R&D funding that reinforces Kaohsiung-Taichung cluster density and anchors advanced foundry-to-OSAT pipelines.
Market Restraints
- Epoxy Resin Price Volatility:Bisphenol-A and phenolic hardener feedstock costs swing with crude oil and benzene derivatives, compressing mold compound margins unpredictably.
- Equipment Supplier Concentration:Die bonder and laser debonding tool capacity concentrates among Japanese and German capital equipment vendors, creating 12-18 month lead time bottlenecks.
- Warpage Control Limits:Coefficient of thermal expansion mismatches between silicon dies, mold compound, and organic substrates constrain maximum panel sizes below 600mm.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for semiconductor assembly and testing are attracting OSAT greenfield investments in Gujarat and Karnataka, opening captive demand for packaging materials.
- Glass Interposer RF Applications:Millimeter-wave antenna-in-package modules for 5G infrastructure and automotive radar favor glass substrates with stable dielectric constants across temperature.
- Chiplet Interconnect Convergence:Hybrid bonding integration with FOWLP redistribution layers enables 3D stacking without through-silicon vias, reducing thermal resistance in networking silicon.
Industry Challenges
- Process Engineer Scarcity:Redistribution layer lithography and laser via drilling expertise concentrates among senior technicians in Taiwan and South Korea, constraining expansion timelines elsewhere.
- Multi-Site Qualification Burden:Automotive ADAS modules require AEC-Q100 and ISO 26262 certifications that add 18-24 months to new mold compound approvals.
- Legacy Equipment Compatibility:Panel-level tooling footprints conflict with existing 300mm wafer infrastructure, forcing OSATs to choose between greenfield investment and stranded asset risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fan-Out Wafer Level Packaging Market |
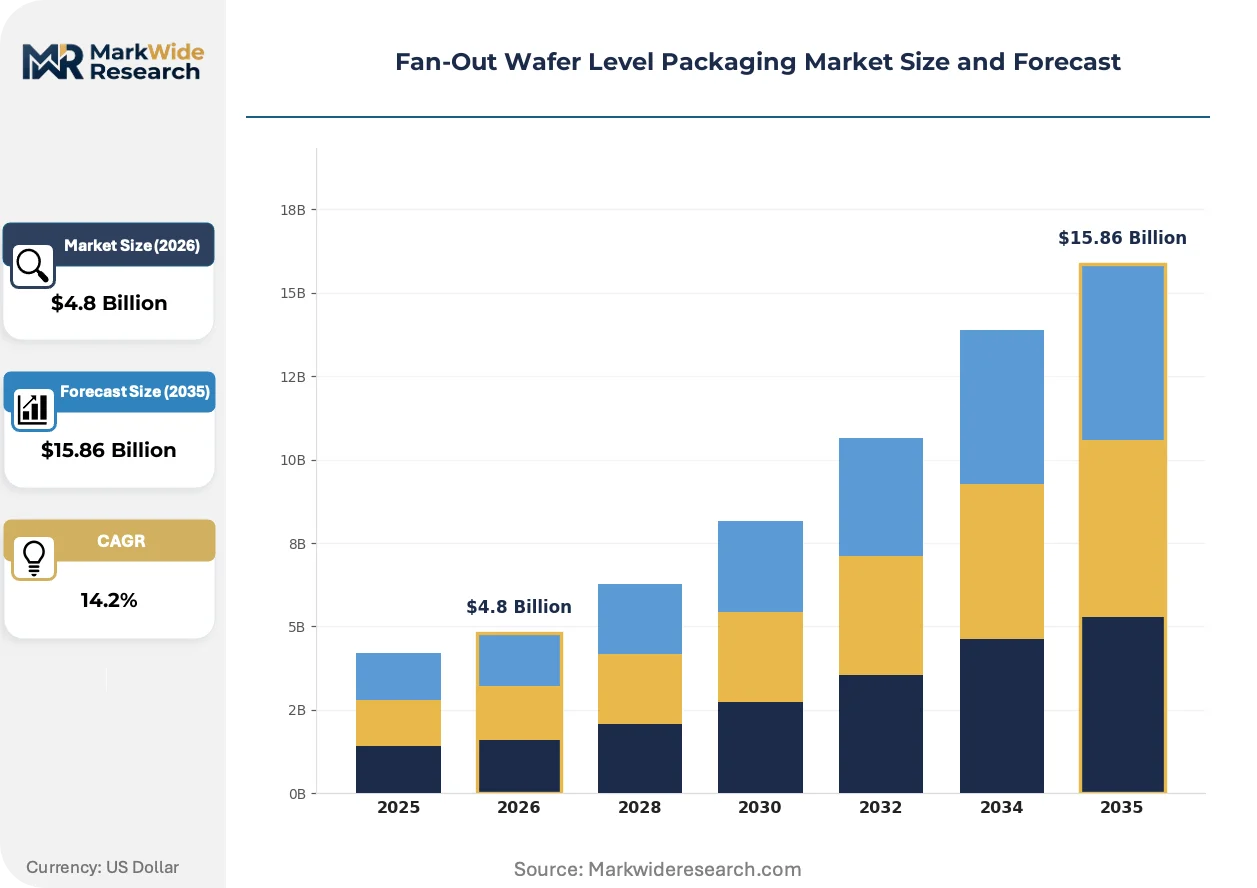
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, SOI, 3D-IC Application: Consumer Electronics, Automotive, Telecommunications, Industrial Devices Material: Silicon, Glass, Organic, Epoxy End User: OEMs, Tier-1 Suppliers, Contract Manufacturers, Design Houses |
| Companies Covered | Taiwan Semiconductor Manufacturing Company Limited (TSMC), ASE Technology Holding Co., Ltd., Amkor Technology, Samsung Electronics Co. Ltd., JCET Group Co., Ltd., Powertech Technology Inc., Nepes Corporation, Intel Corporation, GlobalFoundries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fan-Out Wafer Level Packaging Market Emerging Trajectories
Process architectures are fragmenting as panel-level fan-out formats mature alongside wafer-level platforms, creating parallel qualification tracks that reshape equipment procurement and material specification workflows.
Glass core substrate technology is decentralizing high-frequency packaging away from organic laminate dominance. Glass carriers offer dimensional stability below 3 ppm/°C and surface roughness control for fine-pitch redistribution layers. RF module designers in South Korea and Japan are qualifying glass-based fan-out for 77GHz automotive radar and 28GHz 5G millimeter-wave applications. The shift is compressing traditional BT resin substrate share in antenna-in-package segments.
REACH chemical restrictions are tightening substance disclosure requirements for semiconductor materials entering European assembly facilities. ECHA's SCIP database mandates notification for substances of very high concern in packaging materials, forcing mold compound suppliers to requalify formulations and extend supply chain documentation. Automotive Tier-1 suppliers with European final assembly exposure are consolidating qualified material lists and extending vendor audit cycles.
Buyers are consolidating packaging procurement around captive foundry-OSAT partnerships rather than arm's-length merchant assembly contracts. Apple and NVIDIA have locked multi-year capacity allocations with TSMC's InFO and CoWoS platforms. This channel compression is marginalizing second-tier OSATs and shifting price negotiation leverage toward wafer-level packaging specialists with proven high-volume yield records.
Fan-Out Wafer Level Packaging Market Segmentation
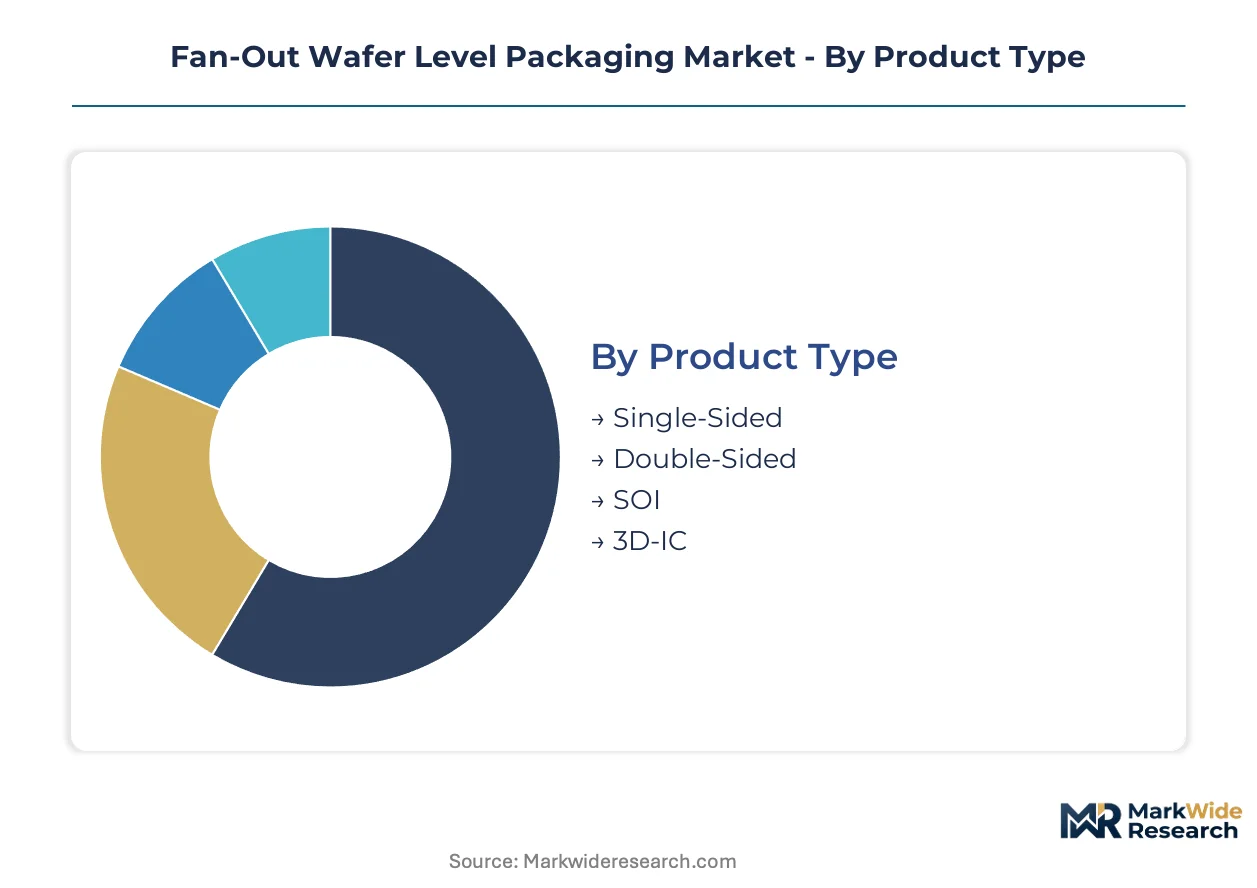
Segmentation in fan-out wafer level packaging reveals how capital allocation, thermal requirements, and supply chain positioning diverge across substrate formats and end-use verticals. Buyers configure procurement strategies around die density, panel size scalability, and qualification burden rather than unit cost alone.
Product Type:
Capital intensity varies sharply across substrate configurations, with double-sided architectures requiring dual lithography passes and precision alignment systems that multiply upfront equipment outlays.
- Double-Sided:Embeds active dies on both faces of the reconstituted wafer, enabling I/O densities exceeding 10,000 connections per package. AI accelerator demand from NVIDIA and AMD concentrates in TSMC's CoWoS-S variants, where thermal cycling reliability under 150W TDP drives qualification timelines. Warpage control across 600mm panels remains the binding constraint on yield.
- Single-Sided:Routes all interconnects through one redistribution layer stack, reducing mold compound stress and simplifying laser debonding. Smartphone APs and baseband modems dominate volume, with Apple and Qualcomm locking multi-year InFO allocations. Capital requirements run 40-50% below double-sided equivalents.
- SOI:Integrates silicon-on-insulator wafers for RF switch and LNA applications where substrate isolation suppresses crosstalk.
- 3D-IC:Stacks multiple fan-out layers with hybrid bonding, enabling logic-memory integration without through-silicon via penalties.
Most installed capacity flows through Single-Sided. Expansion is steepest in Double-Sided.
Application:
End-use differentiation tracks thermal envelope and qualification rigor, with automotive modules imposing AEC-Q100 stress testing that extends mold compound approval cycles by 18-24 months.
- Consumer Electronics:Smartphones, tablets, and wearables drive the largest substrate volume, prioritizing z-height reduction below 0.8mm and electromagnetic interference shielding. TSMC's InFO_PoP captures flagship AP business from Apple and MediaTek, where package thickness directly enables battery capacity expansion.
- Automotive:ADAS processors and radar modules require -40°C to 150°C operational windows with zero field failure tolerance. Bosch and Continental are qualifying panel-level fan-out for 77GHz imaging radar, where glass interposer stability outperforms organic substrates across temperature swings.
- Telecommunications:Baseband and millimeter-wave infrastructure demand low-loss dielectrics for 28GHz and 39GHz bands.
- Industrial Devices:Factory automation and medical imaging prioritize long-term supply continuity over leading-edge density.
Consumer Electronics absorbs the highest wafer starts. Automotive climbs the fastest as electrification multiplies sensor count per vehicle.
Material:
Substrate selection fractures along frequency, thermal, and cost axes, with glass carriers commanding 3-4x organic laminate pricing but enabling sub-3 ppm/°C dimensional stability.
- Organic:BT resin and ABF laminate dominate cost-sensitive applications, offering proven supply chains and established laser drilling parameters. ASE and Amkor run high-volume smartphone lines on organic RDL stacks, though moisture absorption limits millimeter-wave performance.
- Glass:Borosilicate and alkali-free glass substrates enable fine-pitch redistribution below 2μm line/space with near-zero coefficient of thermal expansion mismatch to silicon. Samsung Electro-Mechanics and Shinko Electric are qualifying glass core fan-out for 5G antenna-in-package modules in South Korea and Japan.
- Silicon:Remains the die material itself, with interposer applications requiring polished wafers for hybrid bonding.
- Epoxy:Mold compound formulations determine warpage, filler loading, and thermal conductivity in the reconstituted wafer.
Organic materials command the largest installed base. Glass is gaining share fastest in RF and high-frequency compute.
End User:
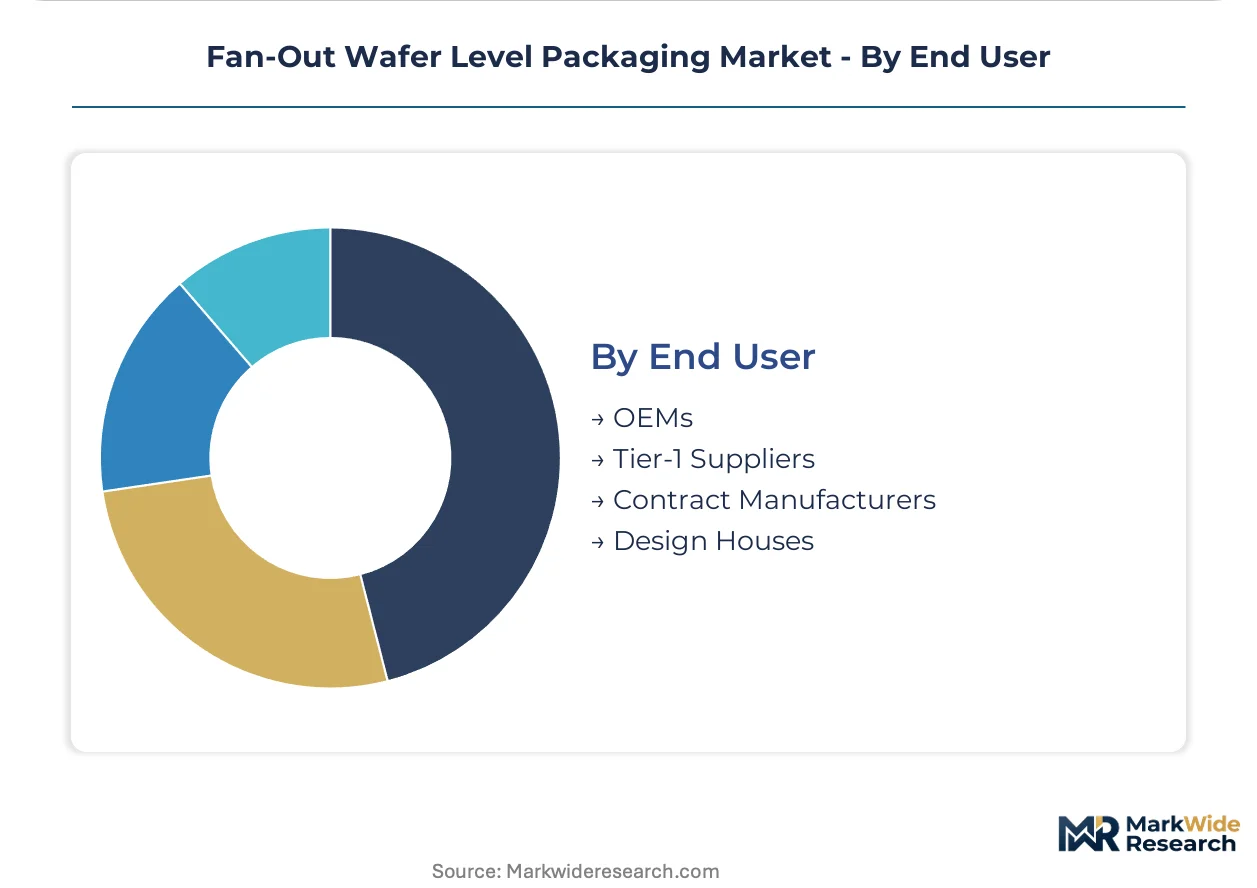
Procurement authority concentrates differently across the value chain, with OEMs capturing packaging specification power in consumer electronics while Tier-1 suppliers control automotive module design.
- OEMs:Apple, Samsung Mobile, and NVIDIA dictate packaging architecture directly, locking multi-year capacity at TSMC and bypassing merchant OSATs for strategic silicon. Their technical teams specify RDL layer count, die-to-die spacing, and thermal interface material requirements.
- Tier-1 Suppliers:Bosch, Denso, and Continental design ADAS modules that integrate fan-out packaged radar transceivers, though foundry selection often rests with semiconductor partners. Their qualification gates determine which mold compounds achieve production release.
- Contract Manufacturers:Foxconn, Jabil, and Flex execute system-level assembly, inheriting packaging specifications from upstream design owners.
- Design Houses:Fabless semiconductor companies without captive packaging engineering rely on foundry-OSAT partnerships for process development.
OEMs direct the highest-value packaging allocations. Tier-1 Suppliers are expanding their specification authority fastest as automotive electronics complexity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer-level packaging scaled first in Taiwan during the 2010s, when foundries pioneered die reconstitution to escape wire-bond constraints. This lineage now diffuses across three continents as governments subsidize domestic packaging capacity.
United States
AI accelerator demand from NVIDIA and AMD concentrates advanced packaging procurement through TSMC Arizona and Intel's domestic foundry investments. The EPA regulates TSCA chemical reporting for mold compound imports. Greater Phoenix anchors federal CHIPS Act packaging subsidies.
Germany
Automotive radar modules for Bosch and Continental drive glass interposer qualifications for 77GHz applications. The EU F-Gas Regulation phases down fluorinated greenhouse gases in epoxy formulations. Dresden's silicon cluster extends into advanced substrate R&D.
Japan
Die bonder and laser debonding equipment from Tokyo Electron and Disco anchors capital goods supply. METI coordinates semiconductor packaging subsidies under the Semiconductor Digital Industry Strategy. Kyushu's Kumamoto prefecture hosts TSMC's JASM foundry with captive OSAT pipelines.
South Korea
Samsung Electronics integrates memory and logic packaging through captive foundry-to-assembly pipelines. MFDS monitors chemical safety in semiconductor materials alongside environmental regulators. Seoul's Pangyo cluster concentrates fabless design houses specifying fan-out architectures.
India
Production-linked incentives under the PLI scheme attract OSAT greenfield investments in Gujarat and Karnataka. BIS qualifications govern mold compound imports for local assembly. Dholera and Sanand emerging as packaging substrate manufacturing zones.
Fan-Out Wafer Level Packaging Market Vendor Landscape
Premium-margin players sit above commodity-margin players across yield consistency and thermal cycling reliability. The market compresses into two tiers: foundry-integrated packaging divisions commanding multi-year capacity locks, and merchant OSATs competing on turnaround speed. Three archetypes dominate—captive foundry packagers, diversified assembly subcontractors, and memory-integrated conglomerates. Capacity expansion and strategic foundry-OSAT partnerships constitute the dominant competitive moves.
Within the foundry-integrated tier, Taiwan Semiconductor Manufacturing Company Limited exemplifies premium-margin positioning through captive InFO and CoWoS platforms. ASE Technology Holding Co., Ltd. and Amkor Technology occupy merchant OSAT archetypes with diversified geographic capacity. Samsung Electronics Co. Ltd. represents the memory-integrated conglomerate model, binding logic and DRAM packaging within a single pipeline.
| Leading Market Players |
|---|
| Taiwan Semiconductor Manufacturing Company Limited (TSMC) |
| ASE Technology Holding Co., Ltd. |
| Amkor Technology |
| Samsung Electronics Co. Ltd. |
| JCET Group Co., Ltd. |
| Powertech Technology Inc. |
| Nepes Corporation |
| Intel Corporation |
| GlobalFoundries Inc. |
| Others |
Supply Flow & Price Mechanics
Panel-level fan-out migration from 300mm wafer formats compresses capital efficiency curves while redistributing pricing power toward equipment vendors with carrier-size flexibility. Taiwan's foundry-OSAT nexus and Japan's die bonder concentration create asymmetric margin capture across the value chain.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CoWoS-class double-sided configurations from InFO smartphone lines and commodity panel-level alternatives. Premium tiers command yield-guaranteed allocations from NVIDIA and Apple, while standard tiers face cost compression from epoxy resin volatility and benzene derivative feedstock swings. Automotive ADAS buyers exhibit lowest price sensitivity due to AEC-Q100 qualification barriers, whereas consumer electronics procurement teams negotiate aggressively on mold compound unit costs.
Supply Chain Analysis
AEC-Q100 and ISO 26262 certification gating extends mold compound qualification timelines, concentrating qualified supplier lists among Japanese and German chemical specialists with automotive track records. Taiwan, South Korea, and Japan anchor supply concentration for die bonders, laser debonding tools, and epoxy formulations. Bisphenol-A and phenolic hardener inputs draw from petrochemical feedstocks vulnerable to crude oil volatility. Single-source vulnerability concentrates in 12-18 month lead time bottlenecks for Japanese die bonder capacity. Distribution runs through captive foundry-OSAT partnerships rather than merchant assembly channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI accelerator demand for sub-2μm line/space geometries has shifted procurement toward premium double-sided configurations, making yield consistency the decisive competitive filter.
For Market Incumbents: Deploy hybrid bonding integration as a process lever to defend CoWoS-class margins against panel-level cost challengers. Consolidate redistribution layer lithography expertise through targeted retention programs in Kaohsiung-Taichung corridors. Lock multi-year capacity allocations with NVIDIA and AMD before Intel's domestic foundry packaging scales. For New Entrants and Emerging Players: Mid-size fabless semiconductor companies without captive packaging engineering represent the most penetrable buyer archetype. Target India's PLI-subsidized OSAT greenfields in Gujarat for equipment supply partnerships rather than direct packaging competition. Qualify glass interposer formulations for 77GHz automotive radar as a differentiated entry wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among merchant OSATs with stranded 300mm wafer infrastructure and delayed panel-level transitions. Five-to-ten year viability hinges on securing foundry partnership status rather than arm's-length contract wins. Watch TSMC's Arizona CoWoS ramp as the signal for North American packaging margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Integration | Enables 3D stacking without TSV penalties for AI accelerators at TSMC and Samsung. |
| Glass Interposer Qualification | Captures 77GHz radar and 28GHz 5G antenna-in-package share from organic substrates. |
| India PLI Greenfield Investment | Secures production-linked subsidies for OSAT capacity in Gujarat and Karnataka zones. |
| Epoxy Mold Compound Requalification | Meets EU F-Gas phasedown timelines for European automotive module supply. |
| Process Engineer Retention Programs | Defends redistribution layer lithography expertise against expansion timelines elsewhere. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OSAT procurement directors, foundry packaging engineers, epoxy mold compound formulators, and die bonder equipment specialists with secondary validation against SEMI equipment forecasts, EPA TSCA chemical filings, EU ECHA SCIP database disclosures, and Taiwan IDB subsidy announcements. Bottom-up wafer start projections and top-down packaging value chain estimates were triangulated for segment consistency.
Segment-weighting across product type, application, material, and end user dimensions drove analytical framework construction over the projection horizon. Double-sided, single-sided, SOI, and 3D-IC configurations were modeled separately with CAGRs derived from foundry capacity expansion schedules and AI accelerator tape-out volumes. Consumer electronics, automotive, telecommunications, and industrial device demand curves were cross-referenced against thermal cycling reliability requirements.
Inputs from foundry earnings disclosures and OSAT utilization reports were available through the study window; gaps in panel-level yield data and automotive qualification timelines introduce uncertainty bands around expansion timing assumptions. Forecasts reflect documented assumptions on epoxy resin price trajectories and equipment lead time normalization. A model refresh is warranted upon material change in EU F-Gas enforcement intensity or TSMC Arizona CoWoS yield ramp schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronics Packaging
Global Mobile Phones Packaging Market
Electronics Packaging
Anti-Counterfeit Electrical and Electronics Packaging Market
Electronics Packaging
Global Display Packaging Market
Electronics Packaging
Electronic Goods Packaging Market
Electronics Packaging
Power Module Packaging Market
Electronics Packaging
Consumer Electronics Packaging Market
Electronics Packaging
Electronic Wrapper Market
Electronics Packaging
North America Consumer Electronics Packaging Market
Electronics Packaging
Europe and USA Consumer Electronics Packaging Market
Electronics Packaging
MEMS Packaging Solder Market
Electronics Packaging
Multi-Chip Module Packaging Market
Electronics Packaging
Asia-Pacific Consumer Electronics Packaging Market
Electronics Packaging
Electronic Packaging Market
Electronics Packaging
Europe Consumer Electronics Packaging Market
Electronics Packaging
Mobile Phone Accessories Packaging Market
Electronics Packaging
Industrial Electronics Packaging Market