
 Asia-Pacific Battery Packaging Market | 2026-2036
Asia-Pacific Battery Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Battery Packaging Market Analytics
Chinese pouch-cell producers is recalibrating laminate supply chains to match Korean cathode output. Nefab Group dominates temperature-controlled logistics formats for cylindrical cells shipped from Tianjin to Rotterdam. Toppan Inc. leverages aluminum-laminated film R&D to sustain barrier-performance leadership in prismatic designs. Samsung SDI anchors Korean domestic demand through proprietary pouch-film specifications that exclude third-party converters.
Asia-Pacific battery packaging encompasses cell-level enclosures, module housings, and pack assemblies engineered to contain electrolytes, manage thermal runaway, and withstand UN 38.3 transportation stress tests. Barrier layers in aluminum-laminated pouches achieve oxygen transmission rates below 0.01 cc/m²/day to preserve lithium-ion chemistry stability across maritime transit. Metal packaging for automotive modules captures the dominant margin pool as OEMs mandate crash-resistant steel enclosures, while flexible formats for consumer electronics compete on thickness reduction below 80 micrometers. Composite solutions blending mica sheets with polymer frames represent the fastest-growing structural category as Chinese producers seek weight reduction without sacrificing fire resistance.
China's SAMR enforces GB/T standards for lithium-ion battery transport packaging that mandate multi-layer thermal insulation in rail and road shipments. Japan's METI circular-economy guidelines require recycled-content thresholds in consumer-electronics battery sleeves, pressuring converters to certify post-industrial polymer streams. South Korea's KATS aligns with UN Recommendations on the Transport of Dangerous Goods, creating harmonized testing protocols that reduce cross-border compliance duplication. Stakeholders must monitor how India's forthcoming battery-swapping regulations redefine pack-level interchangeability standards and packaging dimensional tolerances.
Market Dynamics
Electric vehicle OEMs across China, Japan, and South Korea are consolidating procurement authority at the pack-assembly tier, compressing margins for standalone cell-enclosure suppliers and forcing converters to integrate thermal-management functions.
Growth Catalysts
- UN 38.3 Transport Mandates:Maritime lithium-ion shipping rules from the UN Recommendations on the Transport of Dangerous Goods are tightening barrier-performance specifications, pulling advanced aluminum-laminated film capacity into certification-heavy production lines.
- China's Dual Carbon Goals:National carbon-neutrality targets are accelerating module-to-pack structural simplification, reducing enclosure part counts while preserving crashworthiness through composite mica-polymer hybrids.
- Jiangsu-Guangdong Gigafactory Corridors:Concentrated battery production in these two provinces is generating localized demand for just-in-time packaging logistics, pulling regional converters into co-location strategies with cell manufacturers.
Market Restraints
- Aluminum Price Volatility:Fluctuations in primary aluminum input costs are compressing margins for metal-canister producers serving automotive module housings, forcing pass-through clauses that OEMs resist.
- Korean Cathode Supply Concentration:Pouch-cell laminate converters depend on POSCO and LG Chem for coated aluminum foil, creating single-source vulnerability when Korean producers prioritize captive demand.
- Thickness-Fire Resistance Trade-off:Flexible consumer-electronics pouches below 80 micrometers struggle to meet China's GB/T thermal-runaway containment standards without sacrificing energy density.
Strategic Opportunities
- India BIS Certification Pipeline:India's Bureau of Indian Standards is finalizing lithium-ion transport packaging rules that will require certified local production, creating first-mover advantage for converters establishing domestic laminate capacity.
- Battery-Swapping Infrastructure:India's forthcoming interoperability standards for two-wheeler pack exchange are opening standard-format enclosure design contracts with dimensional tolerances that favor modular, replaceable housing architectures.
- Recycled-Content Mandates:Japan's METI circular-economy guidelines for consumer-electronics sleeves are pressuring brands to certify post-industrial polymer streams, rewarding converters with verified closed-loop material systems.
Industry Challenges
- Multiphysics Simulation Talent Gap:Pack-level thermal-runaway modeling requires coupled mechanical-electrochemical expertise that Asian engineering programs have not scaled, delaying OEM qualification timelines.
- Cross-Border Certification Duplication:South Korea's KATS alignment with UN transport protocols reduces testing redundancy, but Chinese SAMR rail-specific insulation rules and Indian BIS road-shipment mandates still force parallel validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Battery Packaging Market |
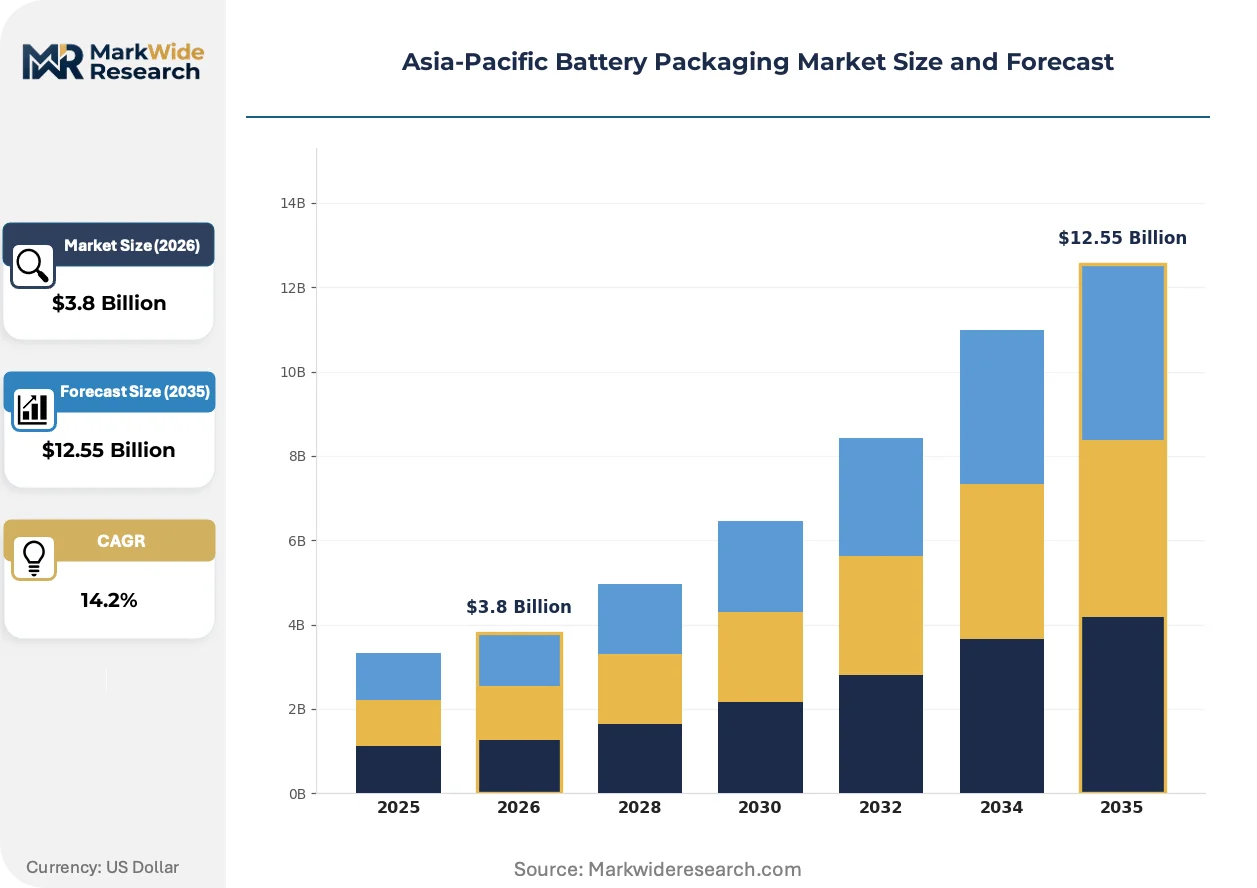
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Paper, Composite End User: Consumer Electronics, Automotive, Industrial, Renewable Energy Packaging Type: Flexible, Rigid, Semi-Rigid, Sustainable Distribution Channel: Online, Offline, Direct Sales, Wholesalers |
| Companies Covered | Nefab Group, Toppan Inc., Wellplast AB, Samsung SDI, LG Chem, Panasonic Corporation, CATL, BYD, Manika Plastech Pvt. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Battery Packaging Market Evolving Landscape
Packaging formats across the Asia-Pacific are converging on multifunctional designs that merge structural integrity with active thermal management, eliminating discrete component layers that added weight and assembly complexity.
Composite mica-polymer laminates are consolidating the traditional separation between fire-barrier films and structural housings. Chinese automotive pack assemblers are adopting these hybrids at volume scale for electric SUV platforms. This consolidation is compressing the supplier base by disqualifying pure-play film converters lacking compounding capabilities.
China's SAMR enforcement of GB/T lithium-ion rail-transport standards is mandating multi-layer thermal insulation in domestic shipments. Cell manufacturers are redesigning module enclosures to incorporate aerogel-interlayer stacks that previously sat outside the packaging perimeter. Cylindrical cell producers in Tianjin are absorbing the highest compliance costs, shifting road freight for shorter routes to bypass rail certification requirements.
Automotive OEMs are centralizing pouch-cell procurement through dedicated pack-assembly joint ventures, bypassing legacy distributor networks that handled spot purchases for prototype builds. Korean chaebol battery divisions are internalizing this channel, locking converter relationships through multi-year film-supply agreements. This concentration is most visible in South Korea's domestic electric bus segment, where Seoul's municipal fleet operators now source complete pack systems rather than discrete cells.
Asia-Pacific Battery Packaging Market Segmentation
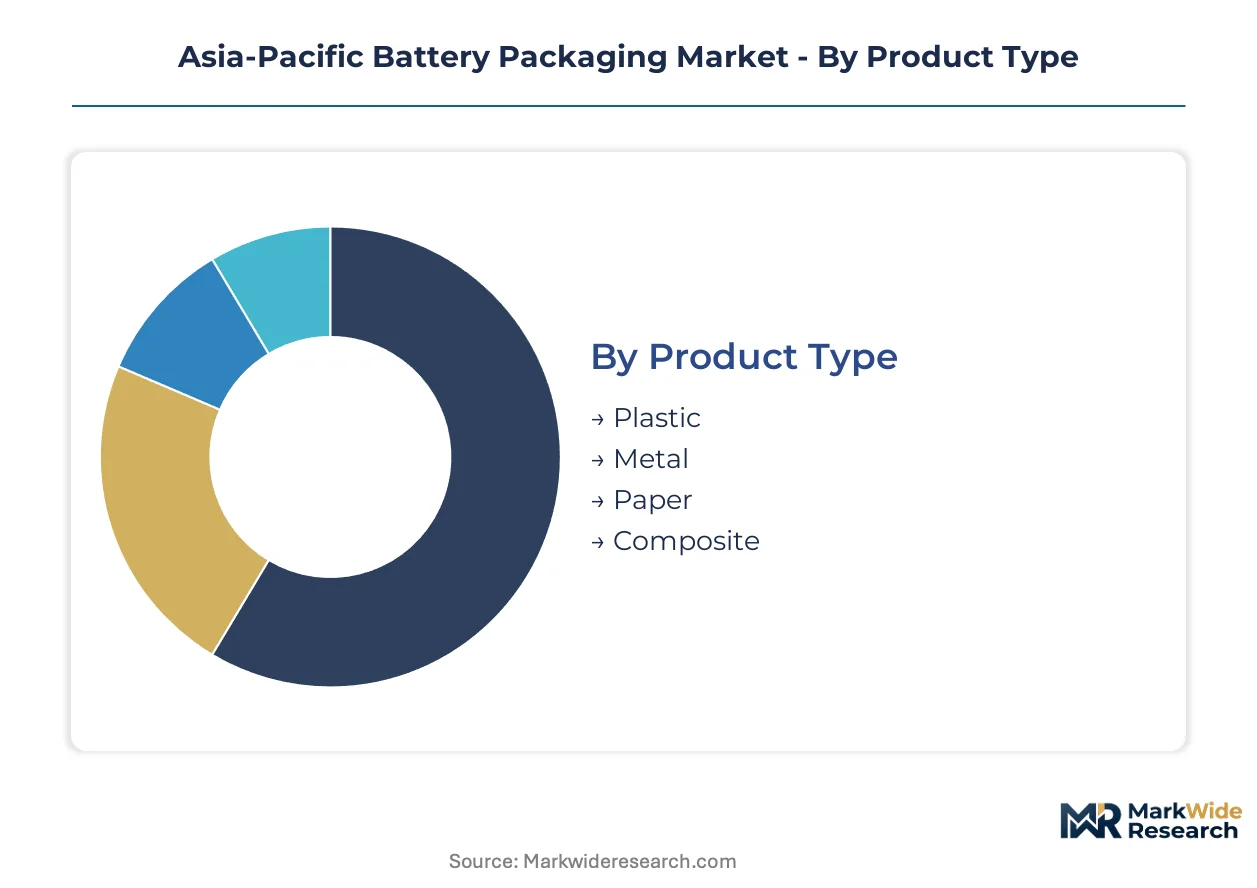
Packaging format selection in the Asia-Pacific battery sector tracks directly to cell chemistry stability requirements and transportation regulatory load. Material choices cascade through thermal management design, UN 38.3 certification pathways, and end-use durability specifications.
Product Type:
Upgrade cycles in battery packaging materials are compressing as automotive OEMs consolidate enclosure specifications and composite solutions displace legacy formats.
- Plastic:Polymer enclosures dominate consumer electronics pouches where thickness reduction below 80 micrometers preserves energy density. Jiangsu province converters are scaling polypropylene module housings for two-wheeler battery swaps under India's forthcoming BIS standards.
- Metal:Crash-resistant steel enclosures capture automotive module margins as Chinese OEMs mandate GB/T-compliant rail shipment protection. Aluminum-laminated films in cylindrical cell cans face margin pressure from primary aluminum price volatility.
- Paper:Corrugated fiberboard formats serve secondary packaging for UN 38.3 maritime compliance, absorbing moisture-buffer functions in Southeast Asian humidity corridors.
- Composite:Mica-polymer hybrids are displacing discrete fire-barrier layers in Chinese electric SUV platforms.
Volume placements concentrate in Metal; the faster expansion belongs to Composite.
End User:
Application-driven specification divergence is widening as automotive pack assemblers internalize procurement authority and consumer electronics brands chase micrometer-scale thickness reduction.
- Consumer Electronics:Pouch-cell laminates for smartphones and laptops compete on barrier-performance below 0.01 cc/m²/day oxygen transmission. Japanese METI recycled-content mandates are pressuring sleeve converters to certify post-industrial polymer streams.
- Automotive:Module-to-pack structural simplification under China's dual carbon goals is reducing enclosure part counts while preserving crashworthiness through composite hybrids. CATL and BYD anchor demand in Guangdong and Jiangsu corridors.
- Industrial:Stationary storage systems require extended thermal-runaway containment durations that favor thicker rigid enclosures over flexible formats.
- Renewable Energy:Grid-scale battery installations in South Korea prioritize KATS-aligned UN transport protocols for cross-border project logistics.
Automotive commands the revenue pool; Renewable Energy is climbing the fastest as grid storage deployments accelerate.
Packaging Type:
Format flexibility requirements are hardening around transportation-mode-specific certification burdens rather than end-use convenience alone.
- Flexible:Aluminum-laminated pouches from Toppan Inc. sustain barrier-performance leadership in prismatic designs. Korean cathode supply concentration through POSCO and LG Chem creates single-source vulnerability for coated foil inputs.
- Rigid:Steel module housings for electric buses in Seoul's municipal fleet now ship as complete pack systems rather than discrete cells. Samsung SDI proprietary specifications exclude third-party converters.
- Semi-Rigid:Polymer-frame composites with mica inserts balance weight reduction against China's GB/T thermal insulation mandates.
- Sustainable:Recycled-content certification is becoming a qualifier for Japanese consumer electronics contracts.
Flexible formats dominate shipment volume; Sustainable packaging is gaining share fastest on regulatory pressure.
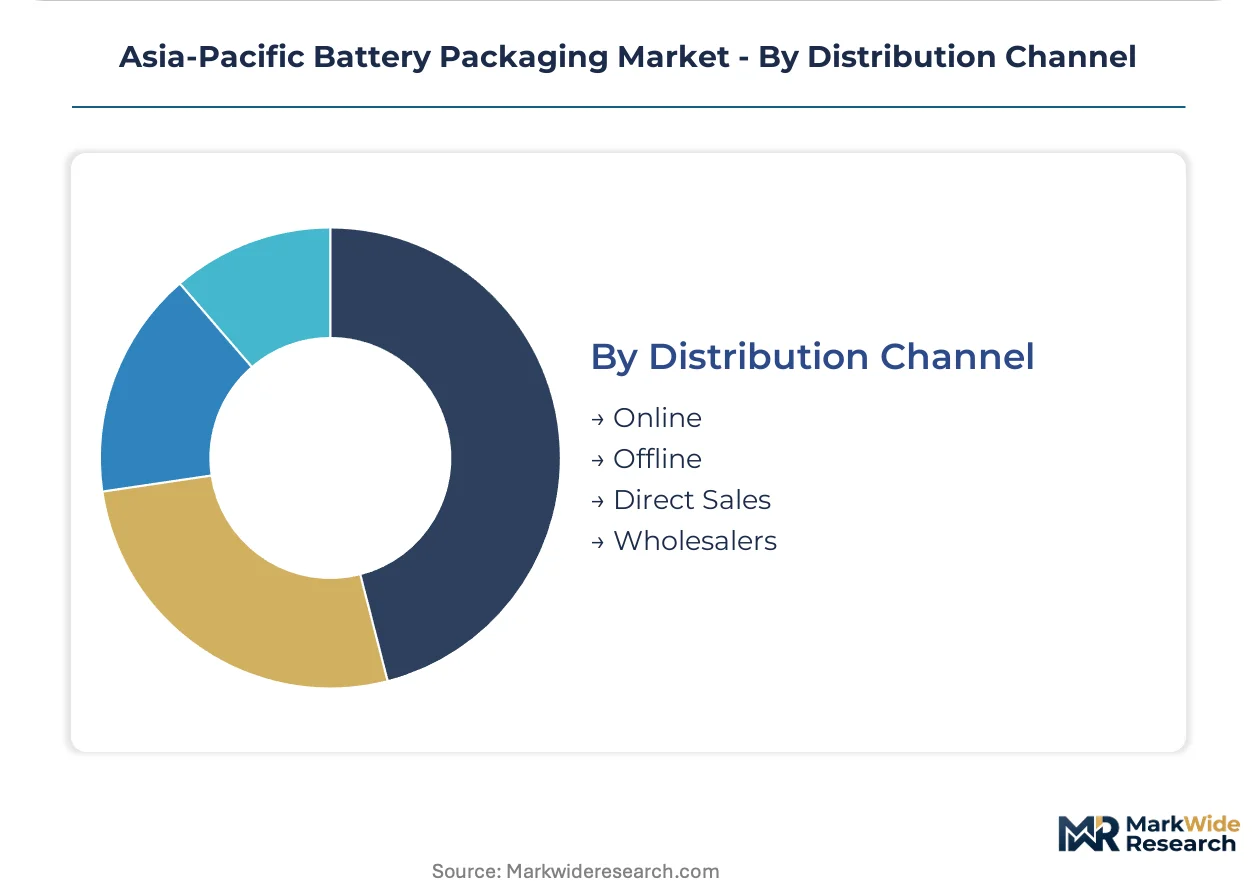
Distribution Channel:
Channel structure is compressing as pack-assembly joint ventures absorb procurement authority and bypass legacy distributor networks.
- Online:Digital procurement platforms serve spot purchases for prototype builds and aftermarket replacement cells in fragmented Southeast Asian markets.
- Offline:Regional converter co-location with gigafactories in Jiangsu and Guangdong is pulling just-in-time logistics away from traditional wholesale channels.
- Direct Sales:Korean chaebol battery divisions are locking multi-year film-supply agreements that eliminate intermediary margins.
- Wholesalers:Distributor networks retain relevance for smaller industrial and renewable energy projects lacking scale for direct converter relationships.
Direct Sales captures the margin expansion; Online channels are expanding most quickly in underpenetrated Southeast Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary aluminum smelters in China's Shandong province supply feedstock for laminated film converters serving Jiangsu and Guangdong battery corridors. Japanese petrochemical complexes in Chiba and Kanagawa prefectures produce specialty polymers for high-barrier pouches. Korean steelmakers in Pohang and Gwangyang anchor metal enclosure supply for domestic automotive module assemblers.
China
CATL and BYD drive cell enclosure demand through gigafactory clusters in Jiangsu and Guangdong provinces. SAMR enforces GB/T standards mandating multi-layer thermal insulation for rail shipments of lithium-ion batteries. Tianjin cylindrical cell producers absorb elevated compliance costs by shifting shorter routes to road freight.
Japan
Consumer electronics brands source sub-80 micrometer pouch laminates for smartphones and laptops. METI circular-economy guidelines require recycled-content thresholds in battery sleeves, pressuring converters to certify post-industrial polymer streams. Toppan Inc. maintains barrier-performance leadership from Kanagawa-based R&D facilities.
South Korea
Seoul's municipal electric bus fleet operators now procure complete pack systems rather than discrete cells. KATS aligns domestic testing with UN Recommendations on the Transport of Dangerous Goods, reducing cross-border certification duplication. Samsung SDI proprietary pouch-film specifications exclude third-party converters from Korean domestic demand.
India
Two-wheeler battery-swapping infrastructure is opening standard-format enclosure design contracts under forthcoming interoperability standards. BIS certification mandates for lithium-ion battery transport are tightening material specifications and requiring certified local production. Manika Plastech occupies position among converters establishing domestic laminate capacity for first-mover advantage.
Australia
Grid-scale battery installations for renewable energy integration prioritize UN 38.3 maritime compliance for cell imports from Asian suppliers. Domestic packaging demand concentrates in secondary corrugated formats for humidity-buffer functions. Limited local cell manufacturing redirects procurement toward module assembly and pack integration services.
Asia-Pacific Battery Packaging Market Competitive Landscape
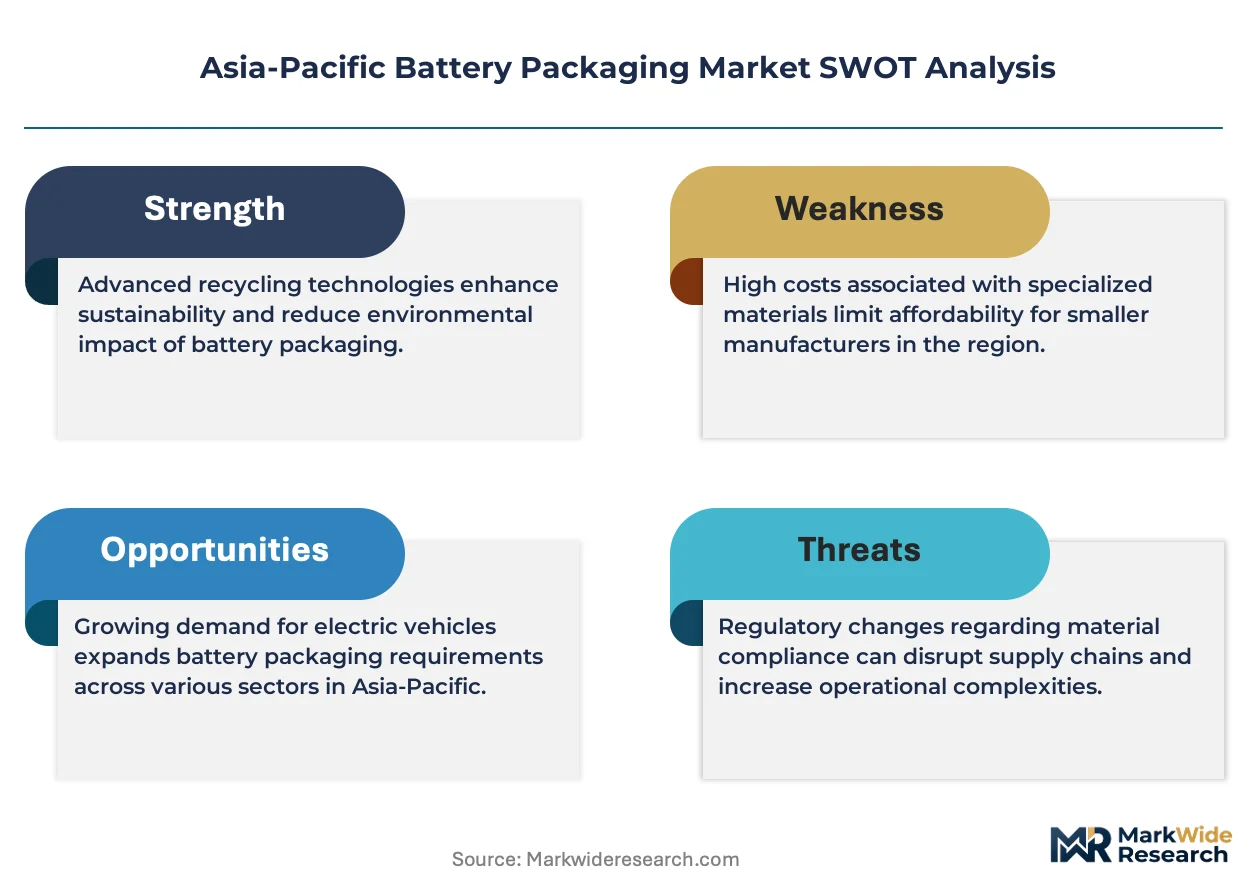
Global majors compete with regional champions across barrier-film technology and thermal-management integration. The vendor base separates into three tiers: integrated battery manufacturers with captive packaging divisions, specialized laminate converters with materials science capabilities, and logistics-focused providers of temperature-controlled shipping formats. Consolidation pressure is accelerating as automotive OEMs centralize procurement at the pack-assembly tier, compressing margins for standalone cell-enclosure suppliers. Two dominant competitive moves are reshaping positioning: converters are integrating thermal-management functions into structural housings, and regional players are establishing co-location strategies with gigafactory corridors.
Within the integrated-manufacturer tier, CATL and BYD exemplify the shift toward captive supply of module-to-pack enclosures. Among specialized converters, Toppan Inc. and Nefab Group occupy positions representing distinct strategic archetypes—materials-led barrier innovation versus logistics-anchored temperature control. Samsung SDI sits within the closed-ecosystem category where proprietary specifications lock out third-party competition. These three groupings—captive-integrated, independent-specialist, and ecosystem-proprietary—capture the competitive structure across the Asia-Pacific battery packaging sector.
| Leading Market Players |
|---|
| Nefab Group |
| Toppan Inc. |
| Wellplast AB |
| Samsung SDI |
| LG Chem |
| Panasonic Corporation |
| CATL |
| BYD |
| Manika Plastech Pvt. Ltd. |
| Others |
Value Network & Pricing Analysis
Composite mica-polymer hybrid adoption is compressing enclosure part counts while simultaneously concentrating procurement authority at automotive pack-assembly tiers, reshaping cost economics toward thermal-management integration and away from discrete component sourcing.
Pricing Analysis
Warranty and thermal-runaway containment service bundling now separates premium converter offerings from unbundled commodity film supply. Three-tier pricing structure across premium, standard, and economy levels reflects GB/T certification grade and volume scale, with automotive OEMs least price-sensitive due to crashworthiness mandates. Pricing pressure stems from primary aluminum volatility forcing pass-through resistance. Consumer electronics brands exhibit highest price sensitivity as they chase sub-80 micrometer thickness targets.
Supply Chain Analysis
Workforce availability for multiphysics simulation talent in Jiangsu and Guangdong provinces is constraining OEM qualification timelines and pulling regional converters into co-location strategies. Supply concentrates in China, South Korea, and Japan, with Korean cathode supply through POSCO and LG Chem creating single-source vulnerability for coated aluminum foil. Distribution runs through direct multi-year film-supply agreements that Korean chaebol battery divisions are locking to eliminate intermediary margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where China's SAMR enforcement of GB/T rail-transport standards creates a certification-heavy moat favoring converters with established thermal-insulation validation.
For Market Incumbents: Anchor defensive positioning through captive supply of module-to-pack enclosures and backward integration into mica-polymer compounding capabilities. Samsung SDI's proprietary pouch-film specifications demonstrate how ecosystem lockout preserves margin pools against standalone converter commoditization. Prioritize R&D investment in aerogel-interlayer integration to absorb SAMR compliance costs that Tianjin cylindrical producers currently shoulder. For New Entrants and Emerging Players: Launch via certified local production under India's forthcoming BIS standards to capture first-mover advantage in two-wheeler battery-swapping enclosure contracts. Target Southeast Asian online procurement channels for spot aftermarket purchases where fragmented demand lacks scale for direct converter relationships. Pursue post-industrial polymer stream certification to qualify for Japanese METI recycled-content mandates pressuring consumer electronics sleeve contracts. For Investors and Strategic Acquirers: Re-rating potential sits with specialized laminate converters possessing materials science capabilities given the consolidation pressure forcing thermal-management integration into structural housings. Long-term viability favors players with verified closed-loop material systems and compounding capabilities that pure-play film converters lack. Watch for India's BIS certification pipeline completion as inflection indicator for domestic capacity establishment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mica-Polymer Compounding | Captures margin pools as composite hybrids displace discrete fire-barrier layers in CATL and BYD supply chains. |
| GB/T Certification Investment | Unlocks automotive module-to-pack procurement authority concentrated at Chinese OEM pack-assembly tiers. |
| Co-location with Gigafactory Corridors | Enables just-in-time logistics for Jiangsu and Guangdong cell manufacturers compressing distributor channels. |
| Post-Industrial Polymer Stream Certification | Qualifies converters for Japanese METI recycled-content mandates in consumer electronics battery sleeves. |
| BIS-Certified Local Production | Secures first-mover positioning in India's two-wheeler battery-swapping standard-format enclosure contracts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with pack-assembly procurement leads, thermal-management R&D directors, laminate converter operations heads, and logistics coordinators at temperature-controlled shipping providers. Bottom-up cell shipment volumes from Jiangsu and Guangdong corridors were triangulated against top-down automotive production data and UN 38.3 certification registry analysis.
Data-stream reconciliation across the analysis window applied product-type, end-user, and packaging-format segmentation with regional regulatory cluster differentiation. CAGRs were derived from multivariate regression against gigafactory capacity expansion timelines and cathode output trajectories. Forecast inputs incorporated SAMR enforcement intensity for GB/T standards and BIS rule finalization progress.
The model assumes a particular technology adoption path; alternative pathways for solid-state cell architectures would alter the outlook by eliminating liquid electrolyte containment requirements. Forecasts reflect assumptions regarding aluminum price stabilization and Korean cathode supply allocation priorities. Material deviation in India's interoperability standard implementation or SAMR rail-insulation enforcement scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronics Packaging
Anti-Counterfeit Electrical and Electronics Packaging Market
Electronics Packaging
Europe and USA Consumer Electronics Packaging Market
Electronics Packaging
Industrial Electronics Packaging Market
Electronics Packaging
Mobile Phone Accessories Packaging Market
Electronics Packaging
Global Display Packaging Market
Electronics Packaging
MEMS Packaging Solder Market
Electronics Packaging
North America Consumer Electronics Packaging Market
Electronics Packaging
Electronic Goods Packaging Market
Electronics Packaging
Global Mobile Phones Packaging Market
Electronics Packaging
Multi-Chip Module Packaging Market
Electronics Packaging
Fan-Out Wafer Level Packaging Market
Electronics Packaging
Europe Consumer Electronics Packaging Market
Electronics Packaging
Power Module Packaging Market
Electronics Packaging
Electronic Wrapper Market
Electronics Packaging
Asia-Pacific Consumer Electronics Packaging Market
Electronics Packaging
Consumer Electronics Packaging Market