
 Electronic Goods Packaging Market | 2026-2036
Electronic Goods Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Goods Packaging Market Analysis
Aftermarket service revenue is narrowing as a distinct margin pool as original equipment manufacturers internalize protective packaging design and logistics coordination. DuPont de Nemours leverages advanced polymer science to anchor its position in high-performance antistatic films. Smurfit Kappa Group competes through integrated corrugated and paperboard solutions tailored to electronics fulfillment channels. Sealed Air Corporation specializes in automated inflatable packaging systems that reduce dimensional weight shipping penalties.
Electronic goods packaging encompasses engineered enclosures, cushioning assemblies, and barrier systems designed to protect semiconductors, displays, and finished devices from electrostatic discharge, mechanical shock, and atmospheric moisture during transit and storage, typically incorporating multilayer coextruded films, molded expanded polyethylene, or precision-die-cut fiberboard with specified compression strength and surface resistivity below 10^11 ohms per square. Flexible packaging leads in volume across consumer electronics accessories and cable assemblies where low unit weight and customization offset premium film costs. Rigid boxes concentrate margin pools in premium smartphone and laptop unboxing experiences where brand presentation commands pricing power. Antistatic bags represent the fastest-growing material category as chip shortages elevate sensitivity to electrostatic damage in semiconductor logistics.
The EPA regulates hazardous substance labeling and disposal pathways for electronics packaging containing flame retardants or metallized films, while REACH restricts phthalate plasticizers and persistent organic pollutants in polymer films entering European supply chains. California's Department of Resources Recycling and Recovery enforces extended producer responsibility frameworks that obligate brands to fund collection infrastructure for post-consumer packaging waste. Stakeholders must monitor evolving state-level packaging EPR legislation and semiconductor export control classifications that reshape regional manufacturing footprints and associated protective packaging demand.
Market Dynamics
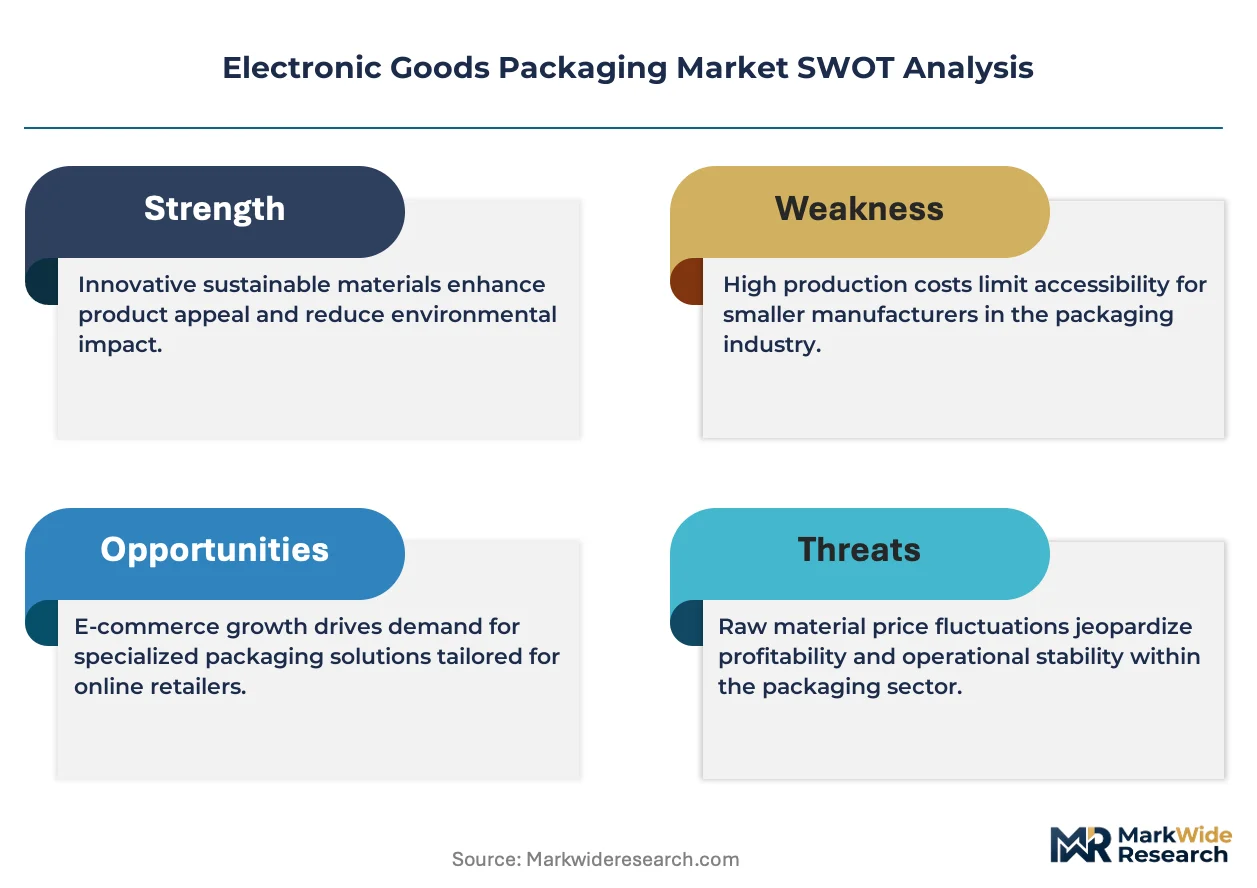
Extended producer responsibility mandates are forcing electronics brands to internalize end-of-life packaging costs, collapsing the traditional separation between product design and waste management planning.
Growth Catalysts
- California SB 54:The state's extended producer responsibility framework obligates electronics brands to fund recycling infrastructure, accelerating demand for mono-material packaging that simplifies post-consumer processing.
- Semiconductor logistics sensitivity:Chip shortages have elevated electrostatic discharge protection to a supply chain priority, expanding specification requirements for surface resistivity below 10^11 ohms per square in transit packaging.
- Molded fiber engineering:Advances in precision-forming technology enable protective geometries previously achievable only in expanded polystyrene, opening substitution pathways for banned single-use plastics in European electronics fulfillment.
Market Restraints
- Petrochemical input volatility:Polypropylene and polyethylene resin prices fluctuate with crude oil benchmarks, compressing margins for multilayer film converters serving consumer electronics accessories.
- Antistatic additive supply concentration:Carbon black and surfactant chemistries for conductive packaging concentrate among specialty chemical producers in Germany and Japan, creating single-source vulnerability.
- REACH compliance friction:ECHA restrictions on phthalate plasticizers and persistent organic pollutants force reformulation cycles that extend qualification timelines for polymer films entering European supply chains.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and mobile device production are creating demand for localized protective packaging capacity near Chennai and Noida clusters.
- Automated inflatable systems:E-commerce fulfillment density favors on-demand void-fill technologies that reduce dimensional weight shipping penalties in last-mile distribution.
- Closed-loop material recovery:EU Green Deal circular economy action plan funding supports pilot programs for post-industrial polyethylene recovery in electronics manufacturing corridors.
Industry Challenges
- Electrostatic simulation expertise:Finite element modeling of charge dissipation in complex geometries requires specialized talent scarce among traditional packaging engineering teams.
- Multi-jurisdiction labeling alignment:Reconciling EPA hazardous substance requirements, California CalRecycle EPR mandates, and EU waste framework directives creates compliance overhead for multinational electronics brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Goods Packaging Market |
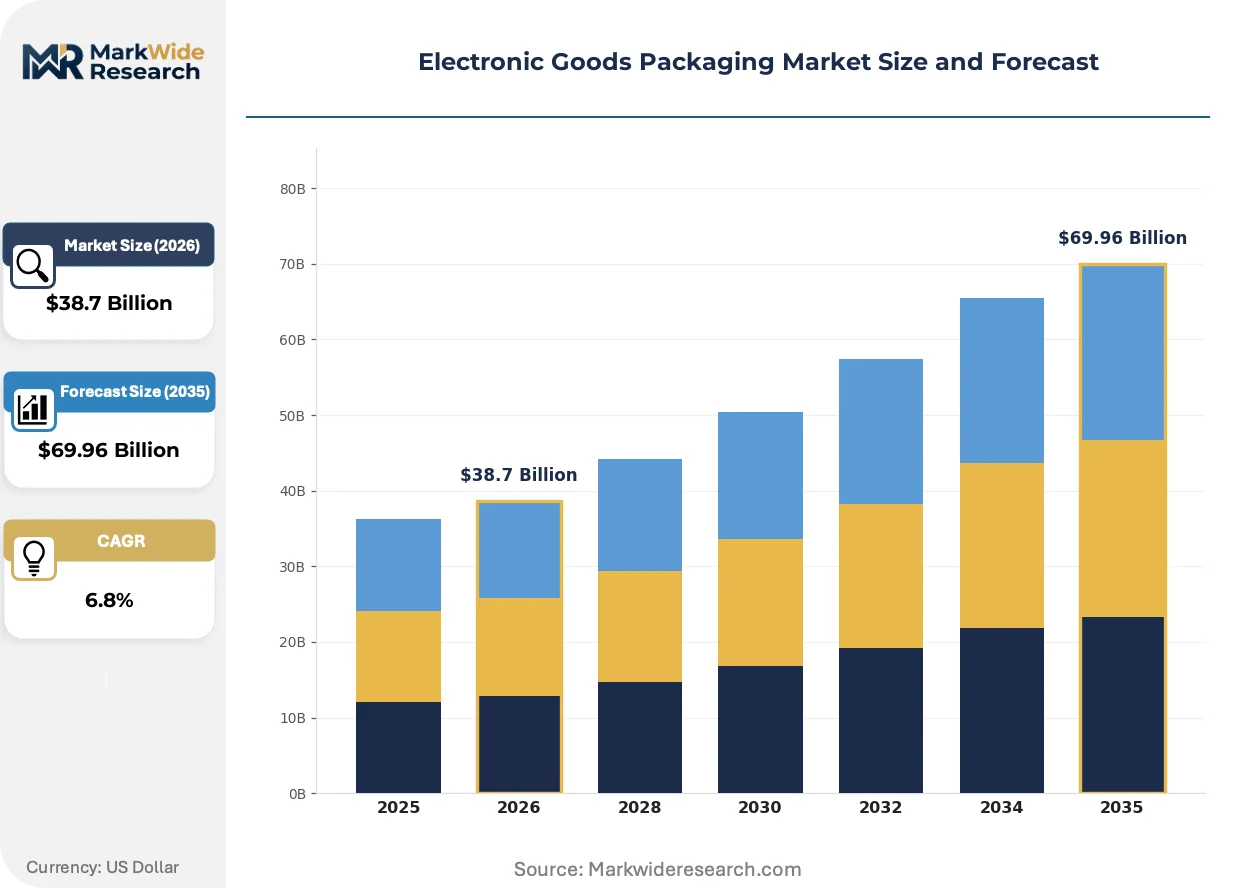
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Packaging, Rigid Boxes, Bubble Wrap, Antistatic Bags Material: Plastic, Cardboard, EPE Foam, Paperboard End User: Manufacturers, Retailers, Distributors, OEMs Functionality: Shock Resistance, Moisture Protection, Anti-static, Insulation |
| Companies Covered | DuPont de Nemours, Inc., Smurfit Kappa Group, Sealed Air Corporation, Mondi Group, WestRock Company, Sonoco Products Company, SCHOTT AG, DS Smith, UFP Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Goods Packaging Market Emerging Trajectories
Digital thread technologies are collapsing the information gap between packaging specification and field performance, enabling real-time design iteration based on damage telemetry from distribution networks.
Smart sensor integration into antistatic bags and cushioning assemblies is digitizing supply chain visibility. Semiconductor manufacturers in Taiwan and South Korea now specify RFID-enabled humidity and shock logging for high-value wafer shipments. This capability is compressing insurance premiums and accelerating root-cause analysis for transit damage claims.
REACH authorization requirements for flame retardants are restructuring polymer formulation practices across European electronics packaging. ECHA sunset dates for halogenated compounds force substitution with phosphorus-based alternatives that require requalification of compression strength and thermal stability. German automotive electronics suppliers face the most compressed compliance timelines.
Unboxing experience design has migrated from marketing collateral to procurement specification. Premium smartphone brands now mandate tear-path engineering and acoustic feedback in rigid box structures, displacing generic clamshell designs. This specification intensity concentrates among contract manufacturers serving Apple and Samsung assembly partners in Zhengzhou and Ho Chi Minh City.
Electronic Goods Packaging Market Segmentation
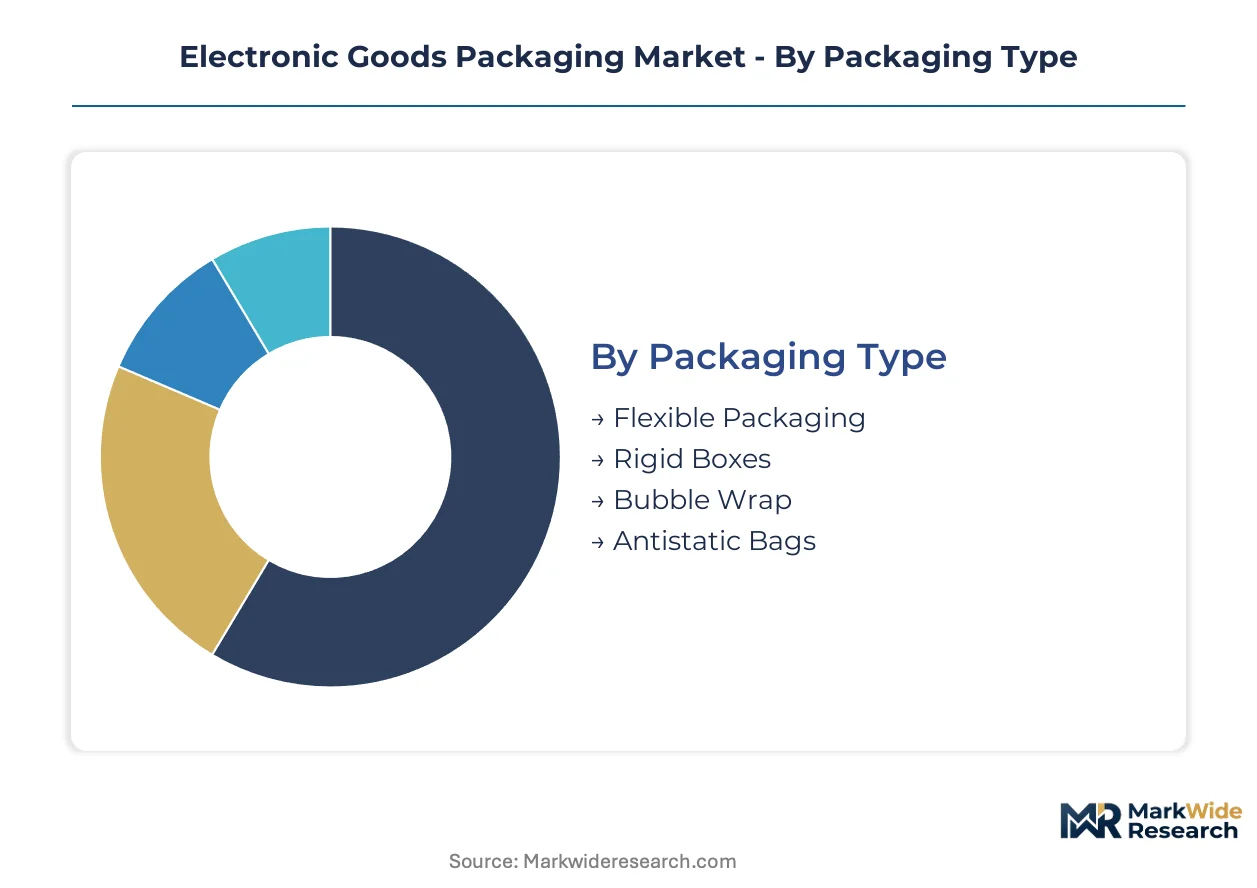
Segmentation in electronic goods packaging reveals how protection requirements fragment across device value tiers and logistics touchpoints. After-sales service intensity varies dramatically by segment, with semiconductor logistics demanding precision antistatic solutions while consumer accessories prioritize cost-efficient void-fill.
Packaging Type:
After-sales service intensity peaks in packaging types where field failure rates directly impact brand warranty costs and customer retention metrics.
- Flexible Packaging:Multilayer coextruded films and laminated pouches dominate cable assemblies, chargers, and low-value accessories where unit economics prohibit rigid enclosure costs. Demand concentrates in Shenzhen and Dongguan contract manufacturing corridors serving e-commerce fulfillment channels. E-commerce volume growth is compressing per-unit film specifications toward minimum viable protection.
- Antistatic Bags:Metallized polymer films and carbon-loaded polyethylene maintain surface resistivity below 10^11 ohms per square for semiconductor wafer and component transit. Taiwan Semiconductor Manufacturing and Samsung Foundry specifications now mandate lot-traceable bag serialization for high-value wafer shipments. REACH restrictions on halogenated flame retardants are forcing reformulation cycles among German film converters.
- Rigid Boxes:Premium smartphone and laptop unboxing experiences command structural specifications including tear-path engineering and acoustic feedback. Apple and Samsung procurement teams in Zhengzhou and Ho Chi Minh City now mandate rigid box suppliers to maintain dedicated quality engineering cells.
- Bubble Wrap:Air-entrapment films in standardized roll and pouch formats serve secondary cushioning for mixed-product fulfillment. Amazon and Alibaba logistics networks in the United States and China specify recycled-content minimums for bubble wrap procurement.
By volume, Flexible Packaging leads. By growth pace, Antistatic Bags is ahead.
Material:
Cost tier differentiation separates commodity materials serving high-volume consumer electronics from engineered substrates protecting semiconductor and medical device shipments.
- Plastic:Polypropylene and polyethylene resins form the substrate for multilayer barrier films, with blown film extrusion capacity concentrated in Zhejiang province and the US Gulf Coast. Crude oil price volatility directly compresses converter margins.
- EPE Foam:Expanded polyethylene molding delivers precision cushioning geometries for display panel and hard drive protection. Japanese chemical producers in Osaka and Nagoya maintain formulation leadership for antistatic EPE grades.
- Cardboard:Corrugated fiberboard in double-wall and triple-wall configurations protects large appliances and server equipment through distribution networks. Smurfit Kappa and WestRock operate integrated mill-to-box plants near major electronics manufacturing clusters.
- Paperboard:Solid bleached sulfate and coated unbleached kraft grades enable premium print surfaces for smartphone and laptop rigid boxes. European Union single-use plastic directives are accelerating paperboard substitution in electronics fulfillment.
EPE Foam commands the highest specification intensity. Plastic maintains the widest application footprint.
End User:
Procurement authority patterns distinguish end users by their integration depth into packaging design and supplier qualification processes.
- OEMs:Original equipment manufacturers including Apple, Dell, and HP maintain captive packaging engineering teams that specify down to resin grade and compression test protocols. Direct supplier relationships bypass traditional distribution channels.
- Manufacturers:Contract electronics manufacturers in Foxconn, Pegatron, and Jabil facilities execute packaging specifications developed by brand owners, with limited authority to substitute materials without formal engineering change approval.
- Distributors:Arrow Electronics and Avnet maintain packaging requirements for semiconductor and component shipments to contract manufacturers, with antistatic and moisture barrier specifications tied to manufacturer qualification programs.
- Retailers:Amazon, Best Buy, and B&H Photo specify secondary packaging for marketplace and direct-ship electronics, with dimensional weight optimization and frustration-free packaging programs driving material selection.
OEMs retain the tightest specification control. Retailers are expanding procurement influence fastest.
Functionality:
Margin pools concentrate in functionality segments where certification testing and failure liability create barriers to commodity competition.
- Anti-static:Surface resistivity control prevents electrostatic discharge damage to semiconductors, with specification thresholds tightening below 10^9 ohms per square for advanced node wafer shipments. Taiwan and South Korean foundries now require RFID-enabled charge monitoring.
- Moisture Protection:Desiccant-integrated barrier bags and aluminum-laminated enclosures maintain <40% relative humidity for moisture-sensitive devices, with IPC/JEDEC J-STD-033 standards governing floor life and bake requirements.
- Shock Resistance:Drop-test certification to ISTA 3A and ASTM D5276 protocols protects displays and storage devices through distribution networks, with acceleration data loggers increasingly specified for high-value shipments.
- Insulation:Thermal barrier materials protect temperature-sensitive components during extreme climate transit, with phase-change materials and vacuum insulation panels specified for lithium battery and pharmaceutical electronics shipments.
Anti-static functionality carries the highest failure cost exposure. Moisture Protection is gaining specification intensity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in consumer electronics accessories show acute price sensitivity, while semiconductor logistics operators absorb premium costs for electrostatic protection without volume elasticity.
United States
California's SB 54 extended producer responsibility framework obligates electronics brands to fund recycling infrastructure, accelerating demand for mono-material packaging. The EPA regulates hazardous substance labeling for flame retardants in polymer films. Contract manufacturing clusters in Austin and Silicon Valley specify antistatic surface resistivity below 10^11 ohms per square for semiconductor shipments.
Germany
Automotive electronics suppliers in Stuttgart and Munich face compressed compliance timelines for REACH authorization of halogenated flame retardants. ECHA restrictions on phthalate plasticizers force reformulation cycles for polymer films entering European supply chains. German specialty chemical producers in Ludwigshafen maintain formulation leadership for carbon black conductive additives.
China
Shenzhen and Dongguan contract manufacturing corridors drive volume demand for multilayer coextruded films serving e-commerce fulfillment channels. MIIT standards govern electronics packaging material specifications for domestic shipment. Zhengzhou assembly partners for premium smartphone brands now mandate rigid box suppliers to maintain dedicated quality engineering cells.
South Korea
Samsung Foundry specifications mandate lot-traceable bag serialization for high-value wafer shipments, expanding RFID-enabled humidity and shock logging requirements. The country's national industrial regulator enforces semiconductor export control classifications that reshape protective packaging demand. Foundry clusters in Pyeongtaek and Hwaseong specify surface resistivity below 10^9 ohms per square for advanced node shipments.
India
PLI scheme incentives for semiconductor and mobile device production create demand for localized protective packaging capacity near Chennai and Noida clusters. BIS certification requirements govern material specifications for electronics packaging entering domestic distribution. Tamil Nadu electronics manufacturing zones attract corrugated and molded fiber converters from multinational packaging groups.
Electronic Goods Packaging Market Vendor Landscape
Capability concentration sits with specialty chemical and precision-forming tiers; scale advantage sits with integrated paperboard and film extrusion players. The vendor base organizes around three strategic archetypes: polymer science specialists commanding antistatic formulation premiums, integrated fiberboard operators leveraging mill-to-box economics, and automated systems providers reducing dimensional weight penalties. Dominant competitive moves include backward integration into resin compounding and geographic expansion toward electronics manufacturing clusters in Vietnam and India.
Within the polymer science tier, DuPont de Nemours, Inc. exemplifies advanced material positioning, while Smurfit Kappa Group anchors integrated corrugated solutions. Sealed Air Corporation occupies a position in automated inflatable systems that reduce shipping penalties.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Smurfit Kappa Group |
| Sealed Air Corporation |
| Mondi Group |
| WestRock Company |
| Sonoco Products Company |
| SCHOTT AG |
| DS Smith |
| UFP Technologies, Inc. |
| Others |
Supply Flow & Price Mechanics
Zhejiang province's blown film extrusion capacity concentration directly shapes downstream pricing power for multilayer barrier converters serving consumer electronics accessories. Petrochemical input volatility from crude oil benchmarks compresses margins unevenly across converter tiers, with integrated resin compounders capturing spread advantages over standalone processors.
Pricing Analysis
Long-term offtake contracts dominate semiconductor-grade antistatic film procurement, while spot market transactions prevail in consumer accessory flexible packaging. Price differentiation separates premium EPE foam grades with sub-10^9 ohm surface resistivity from commodity void-fill alternatives, with certification to IPC/JEDEC standards commanding substantial premiums. Pricing pressure stems from Amazon and Alibaba logistics networks mandating recycled-content minimums that raise input costs without corresponding price recovery. Contract manufacturers in Shenzhen exhibit acute price sensitivity, whereas Samsung Foundry procurement absorbs premium costs for lot-traceable bag serialization without volume elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for electronics packaging serving North American fulfillment channels. Raw material dependencies center on polypropylene and polyethylene resins from Zhejiang province and the US Gulf Coast, carbon black conductive additives from German and Japanese specialty chemical producers, and metallized films from South Korean converters. Single-source vulnerability concentrates in antistatic additive supply chains, where formulation expertise anchors in Ludwigshafen and Osaka. Distribution runs through direct supplier relationships with Foxconn and Pegatron assembly partners, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finite element modeling expertise for electrostatic simulation represents the critical capability gap separating commodity converters from precision-tier suppliers. Packaging engineering teams with specialized charge dissipation talent command premium positioning as semiconductor logistics sensitivity intensifies.
For Market Incumbents: Build formulation IP moats around halogen-free flame retardant alternatives ahead of ECHA sunset dates. DuPont de Nemours and Smurfit Kappa Group should accelerate backward integration into resin compounding to secure margin capture against petrochemical volatility. Antistatic additive supply concentration in Germany and Japan presents acquisition vulnerability that captive formulation capacity would neutralize. For New Entrants and Emerging Players: Establish a beachhead in molded fiber precision-forming for European electronics fulfillment, where single-use plastic bans create substitution demand without incumbent lock-in. India's PLI scheme corridors near Chennai and Noida offer greenfield capacity deployment with localized procurement relationships. Target contract manufacturers serving premium smartphone brands with rigid box engineering capabilities, where tear-path and acoustic feedback specifications concentrate margin pools. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because extended producer responsibility mandates are collapsing waste management planning into packaging design. Acquisition targets should prioritize converters with post-industrial polyethylene recovery capabilities and mono-material engineering expertise. The signal to watch is state-level EPR legislation adoption velocity in the United States, which would replicate California SB 54 economics across additional manufacturing corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures margin spread and secures supply continuity against petrochemical volatility for multilayer film converters. |
| RFID-Enabled Smart Packaging Systems | Samsung Foundry and TSMC specifications now mandate lot-traceable serialization for high-value wafer shipments. |
| Halogen-Free Flame Retardant Reformulation | ECHA authorization timelines force substitution ahead of sunset dates for electronics packaging entering European supply chains. |
| Geographic Expansion toward India PLI Corridors | Tamil Nadu and Uttar Pradesh electronics manufacturing zones attract protective packaging capacity from multinational groups. |
| Closed-Loop Post-Industrial Recovery Programs | EU Green Deal circular economy funding supports pilot programs for polyethylene recovery in manufacturing corridors. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted to calibrate market sizing and growth trajectory assumptions. Primary interviews captured perspectives from packaging engineering directors at Apple and Samsung assembly partners, procurement leads at Foxconn and Pegatron facilities, antistatic film converters in Zhejiang and Ludwigshafen, and logistics specification managers at Amazon and Alibaba networks. Secondary validation drew from EPA hazardous substance filings, ECHA REACH authorization databases, MIIT electronics packaging standards, and SEC disclosures from DuPont de Nemours and Sealed Air Corporation. Bottom-up volume modeling across packaging type, material, and functionality segments was triangulated against top-down macroeconomic drivers.
Calibration against historical growth patterns and regulatory implementation timelines anchored projection assumptions across the analysis window. Segmentation dimensions modeled include packaging type, material substrate, end-user procurement authority, and functionality certification tier. CAGRs were derived from elasticity-adjusted volume forecasts incorporating semiconductor manufacturing capacity expansion, e-commerce fulfillment density growth, and extended producer responsibility mandate adoption curves. Industry-specific inputs encompassed surface resistivity specification tightening trends, molded fiber substitution rates for expanded polystyrene, and RFID sensor integration adoption in wafer logistics.
Sensitivities concentrate around crude oil price volatility impacts on resin economics, REACH authorization timeline acceleration or delay, and semiconductor export control reclassifications affecting regional manufacturing footprints. Forecasts reflect assumptions about regulatory implementation velocity and substitution technology maturation that operating reality may revise. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronics Packaging
Europe and USA Consumer Electronics Packaging Market
Electronics Packaging
Global Display Packaging Market
Electronics Packaging
Global Mobile Phones Packaging Market
Electronics Packaging
Industrial Electronics Packaging Market
Electronics Packaging
North America Consumer Electronics Packaging Market
Electronics Packaging
Electronic Wrapper Market
Electronics Packaging
Multi-Chip Module Packaging Market
Electronics Packaging
Mobile Phone Accessories Packaging Market
Electronics Packaging
MEMS Packaging Solder Market
Electronics Packaging
Consumer Electronics Packaging Market
Electronics Packaging
Anti-Counterfeit Electrical and Electronics Packaging Market
Electronics Packaging
Power Module Packaging Market
Electronics Packaging
Asia-Pacific Consumer Electronics Packaging Market
Electronics Packaging
Asia-Pacific Battery Packaging Market
Electronics Packaging
Electronic Packaging Market
Electronics Packaging
Europe Consumer Electronics Packaging Market