
 Global Mobile Phones Packaging Market | 2026-2036
Global Mobile Phones Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Phones Packaging Market Intelligence
The shift towards asset-light contract manufacturing models is tilting the competitive landscape away from capital-intensive incumbents, allowing nimble design-focused firms to challenge established players. Amcor PLC leverages its global manufacturing footprint to serve multinational OEMs with consistent quality and supply chain reliability. In contrast, Sonoco Products Company specializes in protective solutions and custom inserts engineered for high-value electronic devices, differentiating on performance rather than just volume.
Mobile phones packaging is the integrated system of materials designed for the secure containment and presentation of a device and its accessories, often using high-density foam inserts for shock absorption. Its primary commercial purpose is ensuring device integrity from factory to consumer while reinforcing brand identity. Eco-friendly boxes made from molded pulp and kraft paper are gaining share, driven by OEM sustainability goals. E-commerce platforms represent the fastest-growing end-user segment, demanding robust shipment-ready solutions.
Regulations such as the EU's Corporate Sustainability Reporting Directive (CSRD) and China's GB standards for packaging materials are mandating greater transparency and use of recycled content. These frameworks directly influence material selection and design choices for manufacturers selling into these key markets. Suppliers must now navigate the strategic trade-off between premium aesthetics, material circularity, and cost pressures from high-volume device launches.
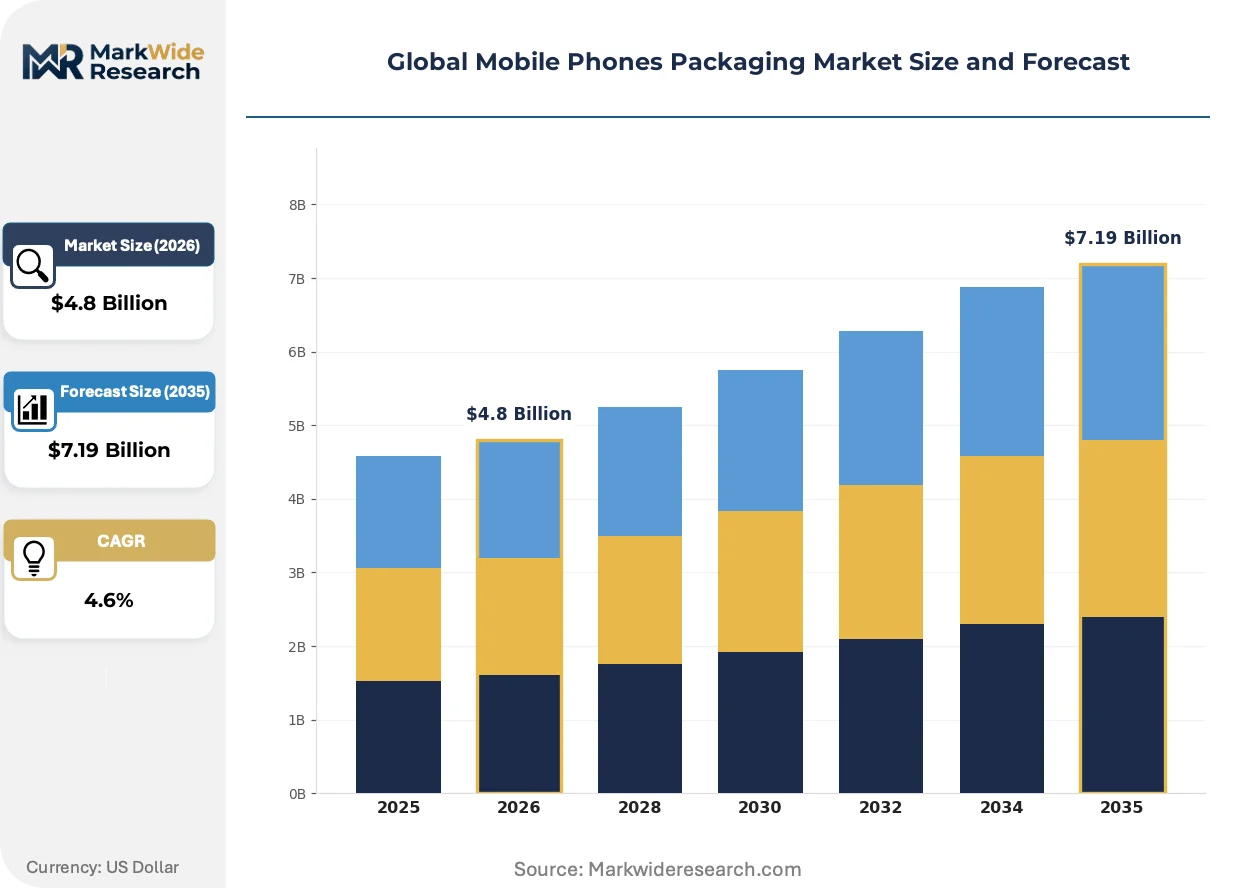
Market Dynamics
The central dynamic shaping the mobile phone packaging market is the structural tension between sustainability regulations demanding material circularity and e-commerce logistics requiring enhanced durability, forcing a fundamental redesign of packaging form and function away from single-use plastics.
Growth Catalysts
- E-commerce Channel Shift:The expansion of online sales necessitates packaging designed for individual shipment, increasing demand for durable, compact, and tamper-evident solutions that protect devices through complex postal and courier networks.
- Sustainability Mandates:Regulatory frameworks, including the EU's Corporate Sustainability Reporting Directive (CSRD), compel OEMs to increase recycled content and adopt compostable materials like molded pulp, driving material innovation.
- Manufacturing Diversification:The establishment of smartphone assembly plants in India and Vietnam creates concentrated, localized demand for packaging converters capable of supporting high-volume, just-in-time production schedules.
Market Restraints
- Input Cost Volatility:Fluctuating prices for key raw materials, particularly recycled kraft paper and molded fiber pulp, directly impact the cost structure and margin stability for packaging manufacturers.
- Accessory Unbundling:The trend of removing chargers and earphones from the primary box reduces the overall size and complexity of packaging required per device, constraining volume growth for insert specialists. *Aesthetic Demands: Premium smartphone brands require high-end finishes and color consistency that can be difficult and costly to achieve with recycled materials, creating a conflict with sustainability goals.
Strategic Opportunities
- Refurbished Device Market:The fast-growing secondary market for refurbished and pre-owned phones presents an opportunity for cost-effective, secure, and brand-agnostic packaging solutions tailored to this distinct channel.
- Smart Packaging Features:Integrating anti-counterfeiting technologies like QR codes or NFC tags into packaging can provide brand protection and enhanced post-sale consumer engagement, creating a new value proposition.
- Circular Economy Services:Developing take-back and closed-loop recycling programs in partnership with mobile operators and retailers offers a service-based model beyond simple component supply.
Industry Challenges
- Design and Testing Cycles:Aligning packaging design with confidential, rapidly changing device dimensions under tight launch deadlines requires significant operational agility and creates immense pressure on prototyping and testing.
- Global Compliance Burden:Navigating and certifying products against a patchwork of national regulations, such as China's GB standards and EU packaging waste rules, increases administrative overhead and supply chain complexity.
- Material Performance Trade-offs:Balancing the desire for premium aesthetics and a positive unboxing experience with the physical requirements of shock absorption and moisture resistance using eco-friendly materials remains a core technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Phones Packaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Blister Packs, Paperboard Boxes, Plastic Cases, Eco-Friendly Boxes, Foam Inserts Material: Corrugated Fiberboard, PET Plastic, Polypropylene, Molded Pulp, Kraft Paper Application: Retail Display, Protection, Branding, Shipment, Gift Packaging End User: OEMs, Distributors, Retail Chains, E-commerce Platforms, Service Centers |
| Companies Covered | International Paper, DS Smith Plc, Amcor PLC, Sonoco Products Company, Mondi Group, WestRock Company, Smurfit Kappa Group, AptarGroup, Packaging Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Phones Packaging Market Strategic Shifts & Innovations
Innovation in mobile phone packaging is driven by the dual objectives of minimizing environmental impact and maximizing logistical efficiency. This forces a re-evaluation of materials, structural design, and the very purpose of the physical box in a digitally integrated consumer experience.
Molded fiber pulp, derived from recycled paper or other plant-based sources, provides a custom-fit, protective cushion for devices and accessories. Smartphone OEMs are rapidly adopting this material to meet corporate sustainability goals and appeal to environmentally conscious consumers. The transition to molded pulp is rendering obsolete traditional expanded polystyrene and plastic-based foam inserts within the supply chain.
China's GB standards for packaging materials impose strict limits on hazardous substances and mandate specific criteria for recyclability. This regulatory framework forces non-compliant materials out of the supply chain for any product sold in the country. Device manufacturers and their suppliers must now source or develop certified materials and redesign packaging to maintain market access in this critical geography.
A significant shift in consumer electronics is the unbundling of accessories, such as power adapters and headphones, from the primary device packaging. This change, driven by cost-saving and environmental considerations, directly reduces the required footprint and internal complexity of the phone box. This trend is most visible in the flagship product tiers of North American and European markets.
Global Mobile Phones Packaging Market Segmentation
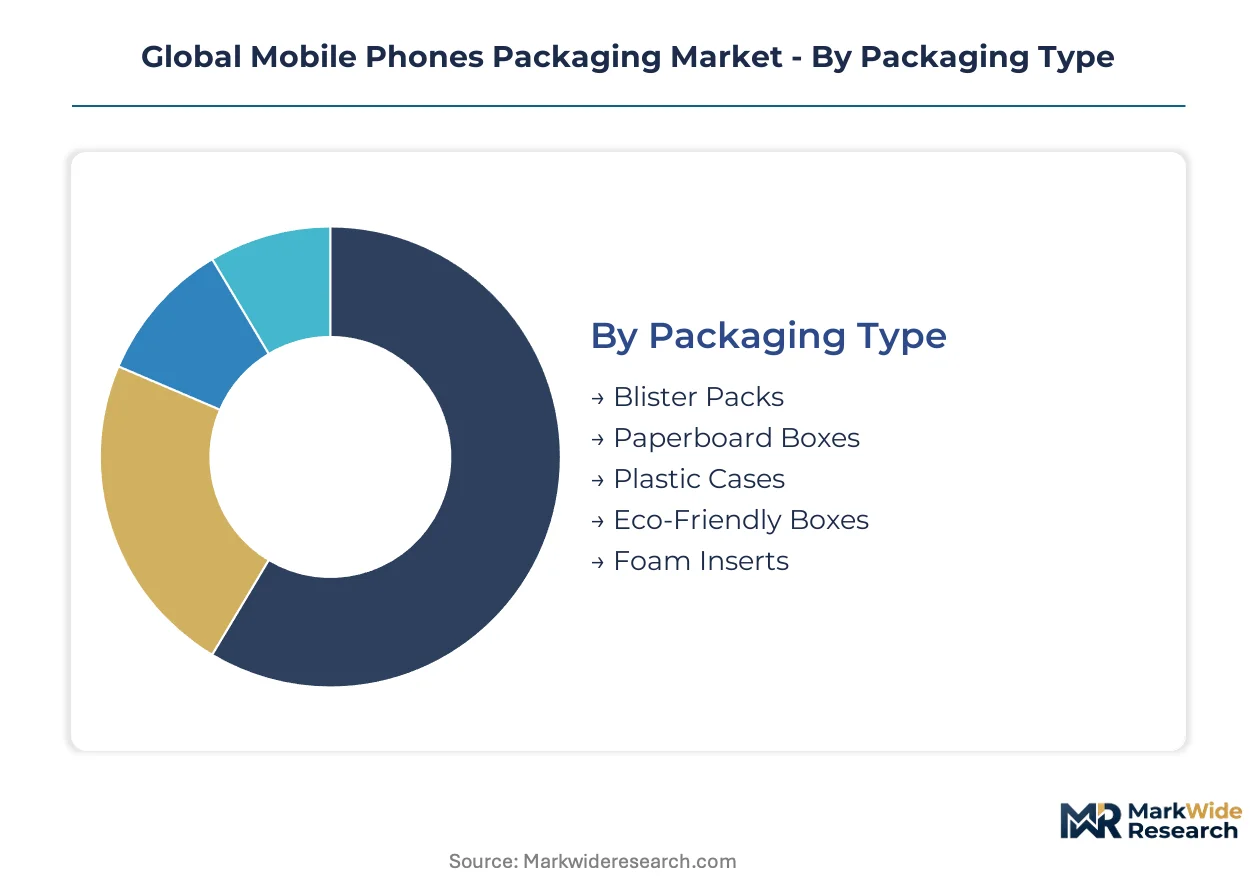
Understanding the mobile phones packaging market requires a detailed examination of its constituent segments. These classifications reveal distinct demand patterns, material preferences, and end-user requirements that shape the competitive landscape. Analyzing these segments helps identify pockets of innovation and areas of concentrated growth across the value chain.
Packaging Type:
The use-case spectrum for mobile phone packaging ranges from basic protective functions to elaborate brand presentation.
- Eco-Friendly Boxes:These solutions utilize materials such as molded pulp, kraft paper, or recycled content, designed to minimize environmental impact and meet sustainability mandates. Demand concentrates in European markets, driven by regulations like the EU Green Deal and consumer preference for sustainable products.
- Paperboard Boxes:Constructed from various paper-based materials, these boxes offer a balance of aesthetic appeal, structural integrity, and customizability for branding. Their demand is high among smartphone OEMs globally, especially for premium device launches, due to print quality and protective capabilities.
- Blister Packs:Transparent plastic packaging often used for accessories or entry-level devices, providing visibility and tamper-evidence.
- Plastic Cases:Durable plastic enclosures offering robust protection, primarily for rugged phones or as secondary protective layers during transit.
- Foam Inserts:High-density foam components engineered for shock absorption, safeguarding devices and accessories within outer packaging.
Established volume favors Paperboard Boxes; emerging adoption favors Eco-Friendly Boxes.
Material:
Material choices reflect a strategic trade-off between cost tier, protective performance, and environmental compliance.
- Molded Pulp:Formed from recycled paper fibers, this material provides custom-fit cushioning and is rapidly displacing traditional plastics in device packaging. Its demand is accelerating in markets like China, influenced by GB standards for packaging materials and OEM sustainability goals.
- Kraft Paper:A strong, durable paper made from wood pulp, often used for outer cartons or internal dividers due to its high tear resistance and recyclability. This material sees high demand in e-commerce applications for its robustness and cost-effectiveness in India.
- Corrugated Fiberboard:Multi-layered paper-based material known for its strength and cushioning properties, widely used for shipping containers and bulk packaging.
- PET Plastic:Transparent, lightweight plastic frequently employed for blister packs and protective films, offering good barrier properties.
- Polypropylene:A versatile plastic used for various packaging components, including trays and cases, valued for its chemical resistance and flexibility.
The market is shifting towards Molded Pulp, while Corrugated Fiberboard remains a foundational material.
Application:
Customer type dictates the specific functional requirements for mobile phone packaging, from factory to consumer.
- Shipment:Packaging designed to withstand the rigors of transit, ensuring device integrity through postal and courier networks. This application is critical for e-commerce platforms, which require compact and durable solutions to minimize damage during individual deliveries.
- Protection:The primary function of packaging involves safeguarding devices from physical damage, moisture, and static electricity during storage and transport. OEMs prioritize this for high-value smartphones, often utilizing high-density foam inserts for shock absorption.
- Branding:Packaging serves as a crucial touchpoint for brand identity, conveying premium aesthetics and product value through design, print quality, and unboxing experience.
- Retail Display:Packaging optimized for shelf appeal and product visibility in brick-and-mortar stores, often incorporating clear windows or attractive graphics.
- Gift Packaging:Specialized packaging designed for aesthetic appeal and enhanced presentation, often featuring premium finishes and unique opening mechanisms.
Shipment applications are gaining share fastest, driven by online sales, while Protection remains a constant requirement.
End User:
Volume requirements and supply chain structures vary significantly across different end-user segments for mobile phone packaging.
- E-commerce Platforms:These entities require packaging optimized for individual shipment, durability, and cost-efficiency to handle high volumes of direct-to-consumer deliveries. This segment presents the steepest expansion trajectory for packaging demand due to continued online retail growth.
- OEMs:Original Equipment Manufacturers demand packaging that aligns with brand identity, protects high-value devices, and supports global supply chain logistics. OEMs drive innovation in sustainable materials, influenced by regulations such as the EU's Corporate Sustainability Reporting Directive (CSRD).
- Distributors:These intermediaries require bulk packaging solutions for efficient warehousing and onward distribution to retailers or smaller vendors.
- Retail Chains:Physical stores need packaging that attracts consumers, facilitates product display, and offers anti-theft features.
- Service Centers:These facilities require packaging for returning or repairing devices, prioritizing secure containment and efficient handling.
Demand from E-commerce Platforms is experiencing the steepest expansion trajectory, while OEMs continue to set industry standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global mobile phone packaging dynamics reflect a complex interplay between manufacturing hubs and high-consumption markets. Regions with significant smartphone assembly operations often drive demand for localized packaging supply, while major consumer markets influence design trends and regulatory compliance for imported devices.
India
India's demand for mobile phone packaging stems from its expanding smartphone assembly sector and a rapidly growing domestic consumer base. The Production Linked Incentive (PLI) scheme encourages local manufacturing, boosting demand for just-in-time packaging solutions. Major electronics manufacturing clusters in Noida, Sri City, and Chennai are concentrating packaging converter activity.
China
China remains a dominant force in mobile phone manufacturing and a significant consumer market, driving immense packaging volume. GB standards for packaging materials mandate strict compliance, influencing material selection and design for both domestic and export products. The Yangtze River Delta and Pearl River Delta regions represent key manufacturing and packaging innovation hubs.
United States
The United States market is characterized by high consumer demand for premium devices and a strong e-commerce presence, requiring robust shipment-ready packaging. FCC regulations influence electronic device packaging, particularly for safe transit and consumer information. Silicon Valley and other tech centers drive demand for innovative, protective packaging solutions for new product launches.
Germany
Germany's market emphasizes sustainability and premium aesthetics for mobile phone packaging, driven by discerning consumers and stringent environmental regulations. The EU Green Deal and Corporate Sustainability Reporting Directive (CSRD) compel manufacturers to adopt eco-friendly materials and transparent reporting. Industrial regions like Bavaria and North Rhine-Westphalia are key points for packaging design and material innovation.
Vietnam
Vietnam has emerged as a critical mobile phone manufacturing hub, attracting significant foreign direct investment from major OEMs. This manufacturing concentration creates localized demand for high-volume, cost-effective packaging solutions. Industrial zones around Hanoi and Ho Chi Minh City are expanding their capabilities to support the electronics export sector.
Global Mobile Phones Packaging Market Key Industry Players
On the supply side, the industry is moderately consolidated among large, diversified packaging conglomerates, with specialized firms occupying niche segments. Two strategic archetypes dominate: global material suppliers leveraging extensive manufacturing networks, and design-focused specialists providing high-performance protective solutions. Dominant competitive moves include strategic partnerships with OEMs and continuous material innovation to meet sustainability goals.
International Paper exemplifies a global scale player, offering a broad portfolio of paper-based packaging solutions across diverse industries. Sonoco Products Company sits within the specialization archetype, known for its engineered protective solutions and custom inserts tailored for high-value electronic devices. Amcor PLC represents another large-scale participant, leveraging its global manufacturing footprint to serve multinational OEMs with consistent quality and supply chain reliability.
| Leading Market Players |
|---|
| International Paper |
| DS Smith Plc |
| Amcor PLC |
| Sonoco Products Company |
| Mondi Group |
| WestRock Company |
| Smurfit Kappa Group |
| AptarGroup |
| Packaging Corporation of America |
| Others |
Cost & Logistics Intelligence
The Asia-Europe shipping lanes' fluctuating freight costs directly impact mobile phone packaging supply concentration and downstream price differentiation for OEMs. These cost dynamics influence material sourcing decisions and final product pricing strategies.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for mobile phone packaging. Price differentiation stems from customization levels for device dimensions and certification compliance with GB standards or EU CSRD. Cost compression intensifies within the e-commerce segment, driven by high volume and efficiency demands. E-commerce platforms demonstrate the highest price sensitivity, while premium smartphone brands remain less sensitive.
Supply Chain Analysis
China's GB standards for packaging materials limit the flow of non-compliant inputs into its manufacturing hubs. Mobile phone packaging supply concentrates in China, India, and Vietnam, where smartphone assembly operations are expanding. The supply chain draws heavily from molded pulp and kraft paper, exposing manufacturers to commodity price volatility. Distribution primarily involves direct-to-assembly plant delivery for just-in-time production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile phone packaging market is navigating a cyclical recovery, primarily driven by renewed consumer electronics spending in key markets. This rebound is fostering opportunities across the value chain as device shipments stabilize.
For Market Incumbents: Pre-empt emerging niche players by investing in advanced material science for eco-friendly solutions like molded pulp. Consolidate market share through strategic acquisitions of smaller, design-focused firms to counter the threat of nimble competitors. Capacity expansion in India and Vietnam also strengthens supply chain reliability against regional manufacturing diversification and fluctuating input costs.
For New Entrants and Emerging Players: The refurbished device market represents a highly penetrable entry point for cost-effective, brand-agnostic packaging solutions. Focus on developing secure, durable designs tailored for individual e-commerce shipments, emphasizing tamper-evidence. A go-to-market strategy emphasizing rapid prototyping and material circularity appeals to sustainability-conscious resellers and repair networks.
For Investors and Strategic Acquirers: The EU's Corporate Sustainability Reporting Directive reshapes the acquisition landscape, favoring companies with robust ESG credentials and circular economy services. Long-term viability hinges on investments in firms specializing in molded pulp and smart packaging features, particularly those offering anti-counterfeiting technologies. A key signal to watch is the adoption rate of closed-loop recycling programs by major OEMs and mobile operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Material Innovation | Develops advanced eco-friendly materials like molded pulp to meet sustainability mandates. |
| Geographic Expansion | Establishes production facilities in India and Vietnam to serve growing assembly hubs. |
| Circular Economy Services | Offers take-back and recycling programs, creating new service-based revenue streams. |
| Digital Integration | Incorporates smart packaging features such as NFC tags for brand protection. |
| Supply Chain Optimization | Enhances just-in-time delivery capabilities for high-volume OEM partners. |
Research Approach
A standing panel of packaging engineers, procurement leads, logistics managers, and sustainability officers provided ongoing calibration for market trends. This approach combined primary interviews with industry stakeholders and secondary validation from trade associations and regulatory filings. Bottom-up and top-down triangulation ensured data accuracy and comprehensive market understanding.
Scenario-bracketing established the outer bounds for market projection across the analysis window, accounting for varying economic conditions. The analytical framework modeled segmentation dimensions including packaging type, material, application, and end-user. Compound annual growth rates were derived from historical data and projected shifts in material adoption. Smartphone shipment volumes and e-commerce penetration served as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in global consumer spending or raw material prices would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement and technological advancements in eco-friendly materials. Material shifts in major OEM sustainability policies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronics Packaging
Mobile Phone Accessories Packaging Market
Electronics Packaging
MEMS Packaging Solder Market
Electronics Packaging
Europe and USA Consumer Electronics Packaging Market
Electronics Packaging
Consumer Electronics Packaging Market
Electronics Packaging
Power Module Packaging Market
Electronics Packaging
Global Display Packaging Market
Electronics Packaging
Anti-Counterfeit Electrical and Electronics Packaging Market
Electronics Packaging
Electronic Packaging Market
Electronics Packaging
North America Consumer Electronics Packaging Market
Electronics Packaging
Industrial Electronics Packaging Market
Electronics Packaging
Electronic Goods Packaging Market
Electronics Packaging
Asia-Pacific Battery Packaging Market
Electronics Packaging
Asia-Pacific Consumer Electronics Packaging Market
Electronics Packaging
Electronic Wrapper Market
Electronics Packaging
Europe Consumer Electronics Packaging Market
Electronics Packaging
Multi-Chip Module Packaging Market